
 Audio CODEC Market | 2026-2036
Audio CODEC Market Size, Share, and Industry Trends Forecast 2026-2036
Audio CODEC Market Intelligence
Taiwanese foundry capacity is restructuring the supply base for audio CODEC silicon. Qualcomm Technologies leverages its Snapdragon platform integration to dominate premium mobile CODEC placement. Cirrus Logic sustains design wins in Apple supply chains through analog-to-digital converter specialization. Texas Instruments Incorporated anchors industrial and automotive CODEC demand with broad temperature-grade portfolios.
An audio CODEC (coder-decoder) converts analog audio signals to digital bitstreams and vice versa, typically operating at sampling rates from 8 kHz to 192 kHz with bit depths of 16 to 32 bits for voice and high-fidelity reproduction. The device serves as the critical interface between microphones, speakers, and digital processing systems across consumer, automotive, and professional equipment. Lossless CODEC formats command margin pools in professional audio and archival applications where fidelity preservation outweighs bandwidth constraints. Conversational CODEC variants are gaining fastest in voice-over-IP and teleconferencing endpoints as enterprise hybrid work persists. Stream-based CODEC architectures dominate multimedia and gaming pipelines where adaptive bitrate delivery reduces buffering.
FCC Part 15 rules govern unlicensed wireless audio transmission in the United States, while the EU Green Deal and RoHS directives constrain hazardous material content in European-sold CODEC hardware. ETSI and ITU-T standards shape interoperability mandates for VoIP and streaming codecs deployed across telecom infrastructure. Stakeholders must monitor evolving energy-efficiency benchmarks and royalty-free codec proliferation as determinants of product cost structures and platform licensing strategies.
Market Dynamics
Wireless audio transmission protocols are fragmenting platform architectures as manufacturers balance proprietary ecosystems against interoperability mandates from telecom regulators.
Growth Catalysts
- EU AI Act compliance:Voice biometric authentication requirements in European consumer electronics are accelerating demand for low-latency encoder-decoder pairs with embedded neural processing.
- Smart speaker penetration:Far-field microphone arrays in connected home devices require multi-channel CODEC silicon with beamforming preprocessing capabilities.
- Taiwanese foundry expansion:Advanced node capacity additions at TSMC and UMC are reducing lead times for 22nm audio SoC production.
Market Restraints
- Silicon wafer cost volatility:300mm substrate pricing fluctuations directly compress gross margins on discrete CODEC components.
- RoHS substance restrictions:European ECHA directives on lead-free solder alloys complicate high-reliability automotive qualification timelines.
- Bluetooth protocol saturation:Royalty stacking across AAC, aptX, and LDAC licensing pools erodes profitability in mid-tier wireless earbuds.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting CODEC module assembly to Gujarat and Tamil Nadu corridors.
- Auracast broadcast audio:Bluetooth LE Audio public address applications in airports and transit systems create greenfield demand for broadcast-enabled encoder chips.
- Automotive cabin zoning:Individualized audio bubbles in electric vehicles require spatial audio CODECs with head-tracking integration.
Industry Challenges
- Acoustic engineer scarcity:Tuning expertise for active noise cancellation algorithms remains concentrated among a small pool of specialists in Shenzhen and Seoul.
- Multi-standard certification:Simultaneous FCC Part 15, CE marking, and TELEC approvals extend product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio CODEC Market |
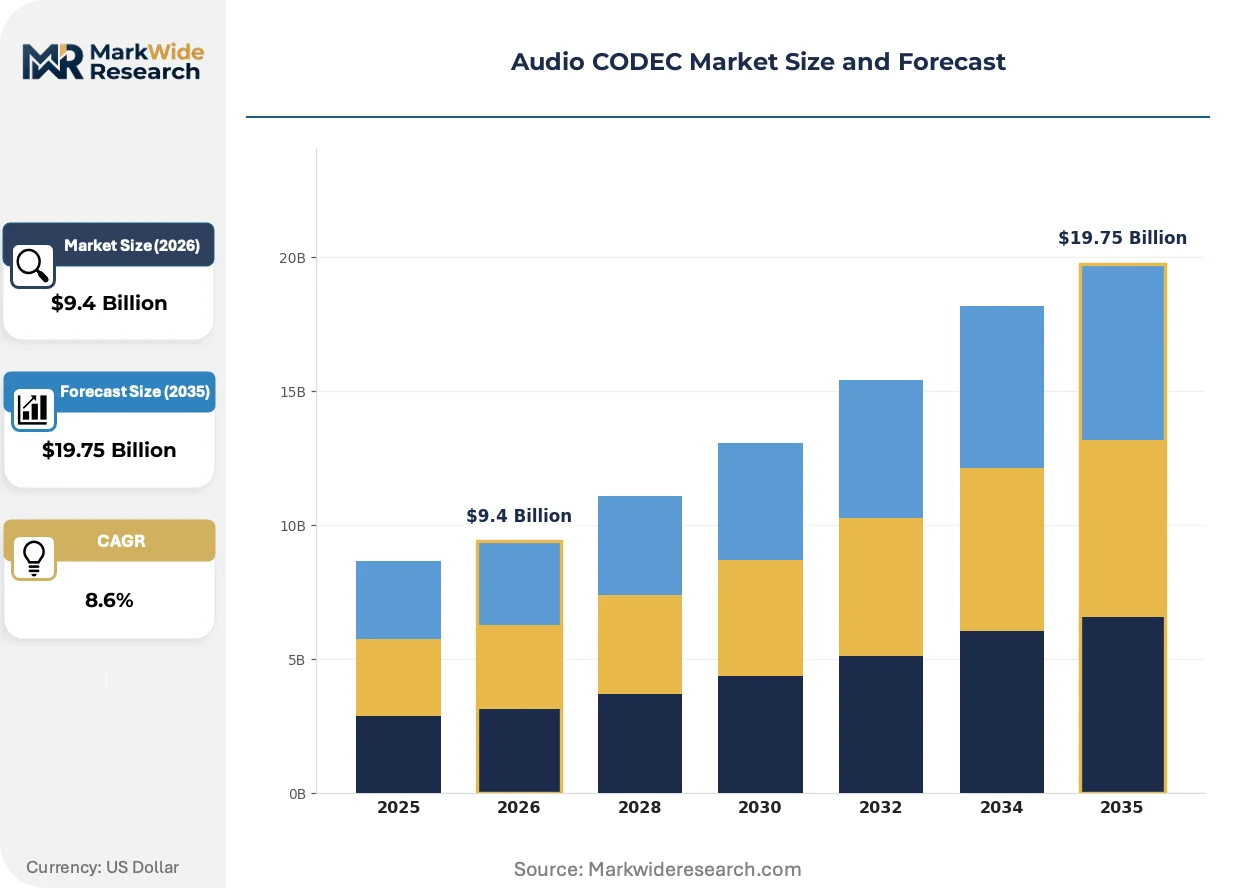
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.75 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lossy CODEC, Lossless CODEC, Conversational CODEC, Stream-based CODEC Application: Streaming Services, Voice-over-IP, Multimedia Applications, Gaming Technology: PCM, AAC, Opus, Vorbis End User: Consumer Electronics, Telecommunication, Automotive Audio, Professional Audio |
| Companies Covered | Realtek Semiconductor Corp., Texas Instruments Incorporated, Analog Devices, Inc., ROHM Co., Ltd., Sony Corporation, Qualcomm Technologies, Inc., STMicroelectronics, Dolby Laboratories Inc., Cirrus Logic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio CODEC Market Strategic Shifts & Innovations
Audio CODEC architectures are splitting between highly integrated application processors and discrete high-fidelity components as use cases diverge across mobility, stationary, and embedded contexts.
Software-defined audio pipelines are modularizing hardware-software boundaries in professional recording interfaces. Studio equipment manufacturers now deploy field-upgradable DSP firmware rather than fixed-function silicon. This shift is modularizing supply chain relationships as CODEC vendors compete to host third-party algorithm marketplaces.
ETSI's upcoming immersive audio standards for 5G voice services are mandating object-based spatial encoding in European telecom infrastructure. Network equipment vendors must retrofit existing VoIP gateways with next-generation encoder support. German and French carriers are piloting these codecs in enterprise conferencing deployments ahead of 2026 compliance deadlines.
Enterprise procurement teams are consolidating audio peripheral vendors to reduce support overhead in hybrid work environments. IT departments now specify unified communication certifications as primary selection criteria over raw acoustic specifications. This concentration is most pronounced in North American financial services and legal sectors where Microsoft Teams and Zoom compatibility gates purchasing decisions.
Audio CODEC Market Segmentation
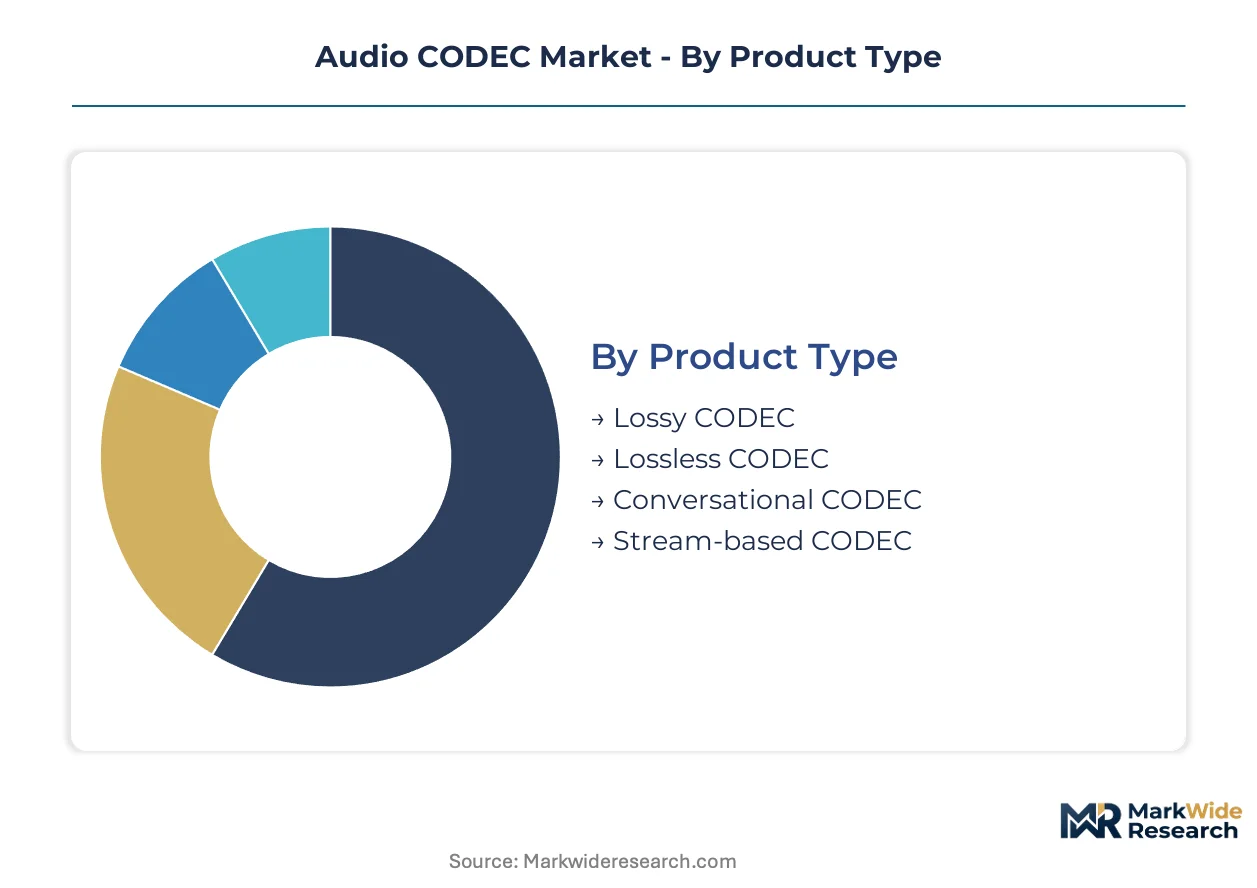
Audio CODEC segmentation reveals how compression philosophy, transmission context, and fidelity requirements split demand across incompatible technical specifications. Each axis—product architecture, use case, encoding standard, and buyer type—carries distinct margin profiles and qualification barriers.
Product Type:
Compression fidelity versus bandwidth efficiency defines the core technology axis, with implementations ranging from perceptually optimized discard algorithms to bit-perfect archival preservation.
- Lossy CODEC:Perceptual coding discards masked audio data to achieve compression ratios of 10:1 or greater. Streaming platforms in the United States and India drive volume demand for AAC and MP3 variants where bandwidth costs dominate fidelity concerns.
- Lossless CODEC:Bit-perfect reconstruction preserves original PCM waveforms through FLAC or ALAC compression. Archival institutions in Germany and Japan specify lossless formats for master recording preservation, with professional studios in London and Nashville adopting these standards for intermediate production workflows.
- Conversational CODEC:Ultra-low latency encoding prioritizes intelligibility over musical fidelity for real-time voice transmission. Enterprise VoIP deployments across European financial services and North American healthcare systems require sub-150ms end-to-end latency with packet-loss concealment.
- Stream-based CODEC:Adaptive bitrate architectures adjust compression dynamically to network conditions. Gaming pipelines and live broadcast infrastructure in South Korea and Brazil deploy these variants to minimize buffering during variable connectivity.
Lossy CODEC leads on scale; conversational CODEC leads on momentum.
Application:
End-use context determines whether latency, fidelity, or computational efficiency takes priority in CODEC selection.
- Streaming Services:On-demand music and video platforms require efficient delivery to heterogeneous device ecosystems. Catalog depth and concurrent user scale in the United States and Brazil favor aggressive compression with broad decoder compatibility.
- Voice-over-IP:Real-time telephony demands robust packet-loss recovery and echo cancellation integration. Corporate unified communications procurement in Germany and France mandates ITU-T G.722 and Opus support for interoperability.
- Multimedia Applications:Video editing and content creation tools require scrubbing-responsive decode performance. Post-production houses in Los Angeles and Mumbai specify low-CPU-overhead formats for timeline playback efficiency.
- Gaming:Spatial audio and positional voice chat impose simultaneous low-latency and 3D rendering requirements. Esports tournament infrastructure in Shanghai and Stockholm drives demand for hardware-accelerated encode paths.
Streaming services anchor volume; gaming applications climb fastest.
Technology:
Encoding standard selection locks ecosystems into royalty obligations, patent pools, and decoder availability across target hardware.
- PCM:Uncompressed pulse-code modulation serves as the reference implementation for professional audio interfaces. Studio equipment manufacturers in Vienna and Tokyo maintain PCM-native signal chains for mastering workflows.
- AAC:Advanced Audio Coding dominates mobile and broadcast licensing through MPEG patent pools. Smartphone OEMs in China and Taiwan pay per-unit royalties for AAC decode capabilities in baseband processors.
- Opus:Royalty-free IETF standard converges speech and music optimization in a single algorithm. WebRTC implementations and open-source telephony stacks in European public sector deployments favor Opus for cost predictability.
- Vorbis:Open-source alternative maintains niche presence in legacy gaming and streaming infrastructure. Indie game developers and non-commercial broadcasters leverage Vorbis to avoid licensing overhead.
AAC commands installed base; Opus gains share fastest.
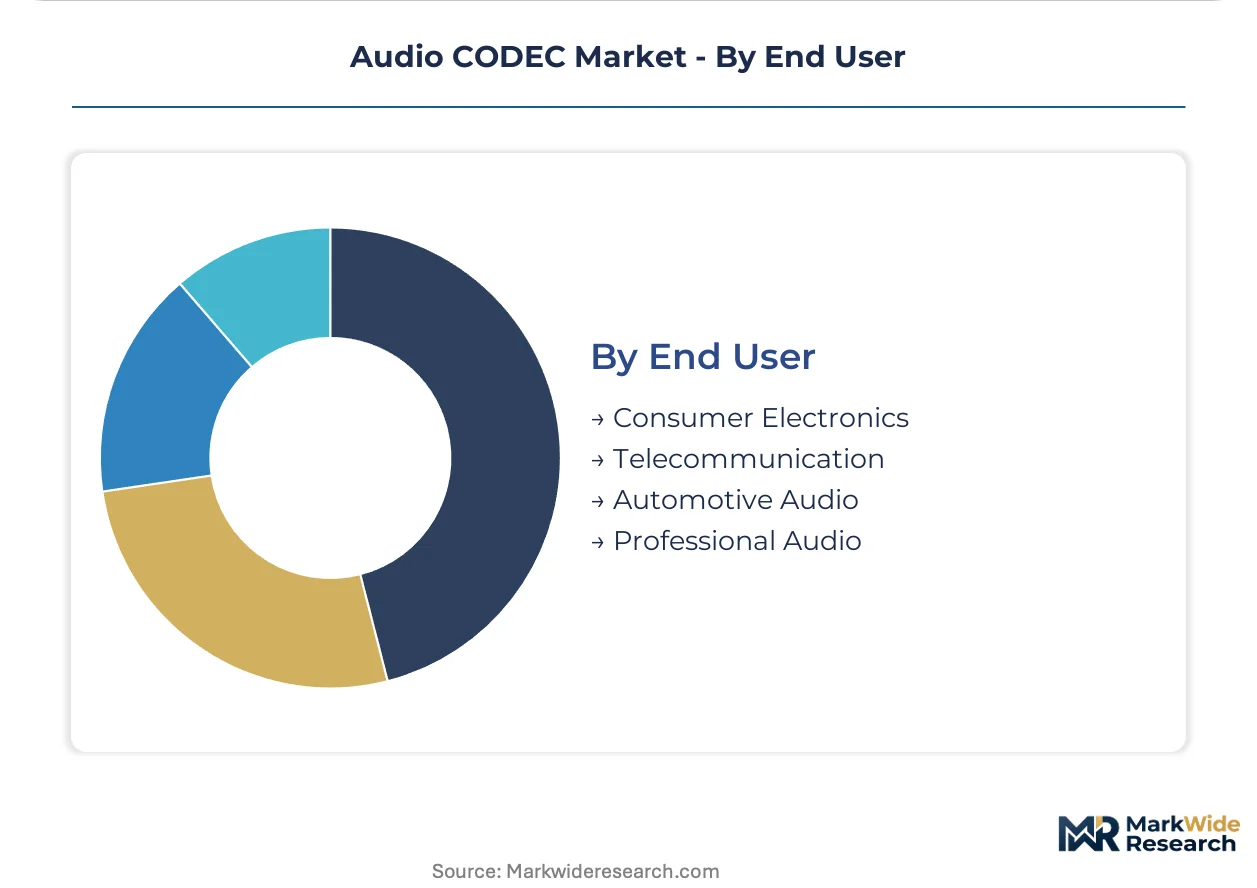
End User:
Buyer sophistication and qualification requirements separate consumer commodity demand from automotive and professional segments with extended certification cycles.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs prioritize silicon integration and power efficiency. Design wins at major handset manufacturers in China and Vietnam hinge on CODEC-PMIC combination packages.
- Telecommunication:Carrier-grade equipment vendors require NEBS compliance and decades-long supply continuity. Base station and central office deployments in India and Indonesia specify industrial-temperature-grade components with formal change control.
- Automotive Audio:Cabin acoustics and safety-critical voice recognition impose AEC-Q100 qualification. Electric vehicle programs in Germany and the United States integrate spatial audio CODECs with head-tracking sensors for individualized sound zones.
- Professional Audio:Recording studios and live sound reinforcement demand 192kHz/32-bit specifications with deterministic latency. Console manufacturers in the United Kingdom and Japan source discrete converter chips from specialized analog semiconductor foundries.
Consumer electronics leads on scale; automotive audio leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting audio CODEC assembly toward jurisdictions with streamlined compliance frameworks and targeted production incentives. Foundry capacity expansions in Taiwan and contract manufacturing growth in India illustrate how cost-of-compliance gaps reshape semiconductor supply geography.
United States
FCC Part 15 rules govern unlicensed wireless audio transmission, creating certification requirements that favor established CODEC vendors with dedicated compliance teams. The IRA's domestic semiconductor manufacturing incentives are attracting packaging and test facilities to Arizona and Texas. Austin and Dallas-Fort Worth clusters concentrate fabless design houses serving automotive and consumer audio segments.
China
MIIT's GB standards for audio equipment mandate specific electromagnetic compatibility thresholds for devices sold domestically. Dual carbon goals are pressuring Shenzhen and Dongguan manufacturers to adopt energy-efficient CODEC architectures in wireless earbuds and smart speakers. The Yangtze River Delta hosts the densest concentration of microphone-array integrators supplying global OEMs.
Germany
EU Green Deal constraints on hazardous materials intersect with ECHA RoHS directives to qualify lead-free solder processes for automotive CODEC modules. KBA type-approval requirements for in-vehicle electronics extend development cycles for cabin audio systems. Bavaria's Munich-Stuttgart corridor anchors premium automotive acoustic engineering for electric vehicle programs.
India
PLI scheme production-linked incentives for electronics manufacturing are attracting CODEC module assembly to Gujarat and Tamil Nadu corridors. BIS certification requirements for telecom equipment create localization mandates for voice-processing silicon deployed in carrier infrastructure. Chennai and Sriperumbudur industrial zones concentrate contract manufacturers serving smartphone export markets.
South Korea
MFDS medical device regulations indirectly shape CODEC specifications for hearing-aid and diagnostic audio equipment. METI-aligned energy efficiency benchmarks for consumer electronics drive demand for low-power encoder-decoder pairs. Seoul's Gangnam-Seongnam corridor hosts specialized acoustic engineering consultancies tuning active noise cancellation algorithms for global brands.
Audio CODEC Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue software-defined audio pipelines and AI-integrated voice processing. The vendor base stratifies between integrated platform providers, discrete converter specialists, and licensing-royalty aggregators. Three archetypes dominate: fabless semiconductor designers with foundry partnerships, analog-focused mixed-signal houses, and standards-essential patent holders monetizing codec formats. Competitive moves center on strategic partnerships for IP bundling and geographic expansion into India PLI-eligible manufacturing zones.
Among Taiwan-based fabricators, Realtek Semiconductor Corp. exemplifies the high-volume consumer electronics archetype with broad decoder compatibility portfolios. Texas Instruments Incorporated anchors the industrial-temperature-grade segment through analog-to-digital converter specialization and automotive qualification depth. Qualcomm Technologies, Inc. occupies a platform-integration position where Snapdragon ecosystem bundling secures premium mobile CODEC placement. Cirrus Logic Inc. represents the Apple-centric discrete converter specialist model with focused analog signal chain expertise.
| Leading Market Players |
|---|
| Realtek Semiconductor Corp. |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| ROHM Co., Ltd. |
| Sony Corporation |
| Qualcomm Technologies, Inc. |
| STMicroelectronics |
| Dolby Laboratories Inc. |
| Cirrus Logic Inc. |
| Others |
Cost & Logistics Intelligence
Advanced node migration to 22nm processes at Taiwanese foundries is compressing die costs for integrated audio SoCs while simultaneously concentrating wafer supply among TSMC and UMC. This technological shift tightens OEM bargaining power against discrete CODEC vendors who lack captive fabrication.
Pricing Analysis
Distributor margins in the audio CODEC channel typically capture 15-25 points between fabless designers and contract manufacturers, though direct-to-OEM volume arrangements bypass this layer entirely. Pricing stratifies across premium, standard, and economy tiers based on sampling rate specifications and automotive qualification grade. Cost compression in mid-tier wireless earbuds is intensifying because royalty stacking across AAC, aptX, and LDAC patent pools erodes vendor margins. Consumer electronics OEMs in China and Vietnam exhibit the highest price sensitivity, while German automotive audio programs tolerate premium pricing for AEC-Q100 certified components.
Supply Chain Analysis
Dual-sourcing mandates from Apple and Samsung force CODEC vendors to qualify second-source foundry relationships, typically splitting volume between TSMC and GlobalFoundries. Silicon supply concentrates in Taiwan, South Korea, and the United States, with 300mm wafer fabrication drawing from polysilicon feedstock anchored in Germany and the United States. Single-source vulnerability persists at the advanced node level where EUV lithography equipment depends on ASML's Dutch manufacturing. Distribution runs through specialized semiconductor distributors like Arrow and Avnet serving EMS providers in Vietnam and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The audio CODEC market functions as a stable compounder where wireless audio protocol proliferation and automotive cabin digitization generate persistent silicon demand across consumer and industrial cycles.
For Market Incumbents: Cement platform integration advantages by deepening Snapdragon ecosystem bundling at Qualcomm and defending Apple supply chain exclusivity at Cirrus Logic. Threats from royalty-free Opus adoption in European public sector deployments erode licensing revenue pools. Priority levers include backward integration into MEMS microphone manufacturing and capacity reservation at TSMC N6 nodes for automotive qualification pipelines. For New Entrants and Emerging Players: Regional contract manufacturers in India's PLI-eligible Gujarat and Tamil Nadu corridors represent the most penetrable buyer archetype, underserved by established CODEC vendors focused on premium smartphone sockets. White-space targets include Auracast-enabled broadcast audio chips for airport infrastructure and software-defined audio pipelines for professional recording interfaces. Go-to-market should leverage design partnerships with Shenzhen-based acoustic engineering consultancies for rapid ANC algorithm tuning. For Investors and Strategic Acquirers: Valuations sit cheapest among analog-focused mixed-signal houses with automotive qualification depth but limited consumer platform exposure. Long-term viability framing favors vendors with dual exposure to electric vehicle cabin audio and enterprise VoIP infrastructure. The signal to watch is ETSI immersive audio standard adoption velocity in German and French carrier pilot programs, which would retrofit demand for next-generation encoder silicon.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Partnership | Qualcomm's Snapdragon bundling locks premium mobile CODEC placement against discrete competitors. |
| Automotive Qualification Investment | AEC-Q100 certification opens electric vehicle cabin zoning opportunities with German OEMs. |
| Royalty-Free Codec Adoption | Opus integration reduces licensing exposure for European public sector VoIP deployments. |
| Foundry Capacity Reservation | TSMC N22 node commitments secure supply continuity for smart speaker SoC demand. |
| Acoustic Engineering Acquisition | Shenzhen and Seoul tuning specialist purchases address active noise cancellation talent scarcity. |
Research Approach
Direct dialogue with fabless semiconductor executives, foundry account managers, automotive audio system architects, and acoustic engineering consultants grounded qualitative assessments in operational reality. Secondary validation drew from FCC Part 15 filings, ETSI standardization documents, MIIT GB compliance certificates, and SEC 10-K disclosures from identified market participants. Bottom-up unit shipment estimates across smartphone, automotive, and professional audio channels triangulated against top-down semiconductor consumption data from Taiwan and South Korea trade statistics.
Segment-level revenue outputs across the projection horizon reflect modeled assumptions for wireless audio attach rates, electric vehicle production ramp, and enterprise VoIP infrastructure refresh cycles. The analytical framework incorporated compression format adoption curves, royalty pool evolution, and regional regulatory compliance timelines as endogenous variables. CAGRs derived from logistic diffusion models of technology substitution rather than linear extrapolation, with foundry capacity utilization and silicon wafer pricing treated as supply-side constraints.
Underlying measurement precision varies by segment; consumer electronics volume estimates carry tighter precision than professional audio given consolidated OEM reporting, while automotive audio projections depend on electric vehicle platform timing assumptions. Deviation in ETSI immersive audio standard enforcement timelines or Bluetooth LE Audio penetration rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Fuse Bases Market
Electronic Components
Braking Resistors Market
Electronic Components
Chip Shield Market
Electronic Components
2D Electronics Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Electric Capacitor Market
Electronic Components
Amplifier Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Intel Motherboards Market