
 China Data Center Server Market | 2026-2036
China Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Server Market Insights
Arm-based processor architectures and liquid cooling integration is tilting server design away from legacy x86 thermal envelopes. Huawei Technologies Co Ltd anchors domestic chip-to-system verticality through its Kunpeng and Ascend lines. Inspur Group dominates volume manufacturing for state-backed cloud infrastructure tenders. New H3C Technologies Co Ltd competes aggressively in telecommunications edge deployments with converged rack platforms.
China data center servers are computing appliances engineered to GB 50174 reliability tiers with power densities now routinely exceeding 30 kW per rack for AI training nodes, purpose-built for sovereign cloud and enterprise virtualization workloads. Rack servers occupy the largest revenue pool given hyperscaler standardization, while hyper-converged systems represent the fastest structural expansion as provincial governments consolidate legacy IT estates. Blade servers retain share in financial services where space constraints dominate, though tower configurations fade outside remote enterprise edge use.
MIIT enforces GB standards for server energy efficiency and carbon intensity disclosure, while SAMR monitors anti-competitive conduct in state procurement channels. The country's national data bureau coordinates east-west computing resource transfer mandates that reshape facility location logic. Stakeholders must track how dual carbon enforcement timelines alter power supply agreements for new server deployments.
Market Dynamics
Dual carbon enforcement timelines are compressing power supply agreements for new server deployments across China's eastern corridor, forcing hyperscalers to relocate training clusters westward where renewable baseload is abundant and land costs are lower.
Growth Catalysts
- East-West Computing Resource Transfer:The national data bureau's mandate redistributes AI training workloads from Beijing and Shanghai to Inner Mongolia and Guizhou, unlocking stranded renewable capacity for 30 kW-plus rack densities.
- GB 50174 Tier III Reliability Standards:Provincial governments are consolidating legacy IT estates into hyper-converged systems that meet sovereign cloud uptime requirements, accelerating replacement cycles for aging blade infrastructure.
- Liquid Cooling Integration:Immersion and cold-plate architectures enable sustained operation above traditional air-cooled thermal envelopes, allowing telcos to deploy GPU-heavy edge nodes in space-constrained central offices.
Market Restraints
- Domestic Processor Yield Volatility:Advanced node fabrication constraints limit Kunpeng and Ascend die availability, creating allocation bottlenecks for state-backed tenders.
- Power Purchase Agreement Rigor:MIIT carbon intensity disclosure rules now require verified renewable matching for new facility approvals, extending commissioning timelines by 8-14 months in grid-constrained provinces.
- Legacy x86 Software Inertia:Enterprise virtualization stacks retain tight optimization for Intel and AMD instruction sets, complicating Arm migration for financial services core banking systems.
Strategic Opportunities
- Telecommunications Edge Convergence:5G standalone rollouts create demand for converged rack platforms in prefecture-level cities, with New H3C Technologies capturing share through integrated routing-compute appliances.
- Carbon-Neutral Facility Certification:SAMR's pending green procurement scoring system will prioritize servers with verified embodied carbon audits, rewarding early adopters of circular material flows.
- AI Inference at Manufacturing Plants:Industrial edge deployments in Guangdong and Jiangsu require low-latency vision processing, opening volume channels for compact liquid-cooled nodes outside traditional data center footprints.
Industry Challenges
- Immersion Cooling Technician Scarcity:Dielectric fluid handling and leak detection protocols demand specialized field skills that vocational pipelines have not yet scaled to match deployment velocity.
- Inter-Provincial Data Sovereignty Friction:Cross-border workload migration within state cloud frameworks triggers compliance reviews under evolving cybersecurity classifications, complicating load balancing architectures.
- Legacy Facility Retrofit Economics:Existing raised-floor installations in Tier I cities face demolition-rebuild thresholds when liquid cooling penetration exceeds 40 percent of rack count, stranding capital in suboptimal real estate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Server Market |
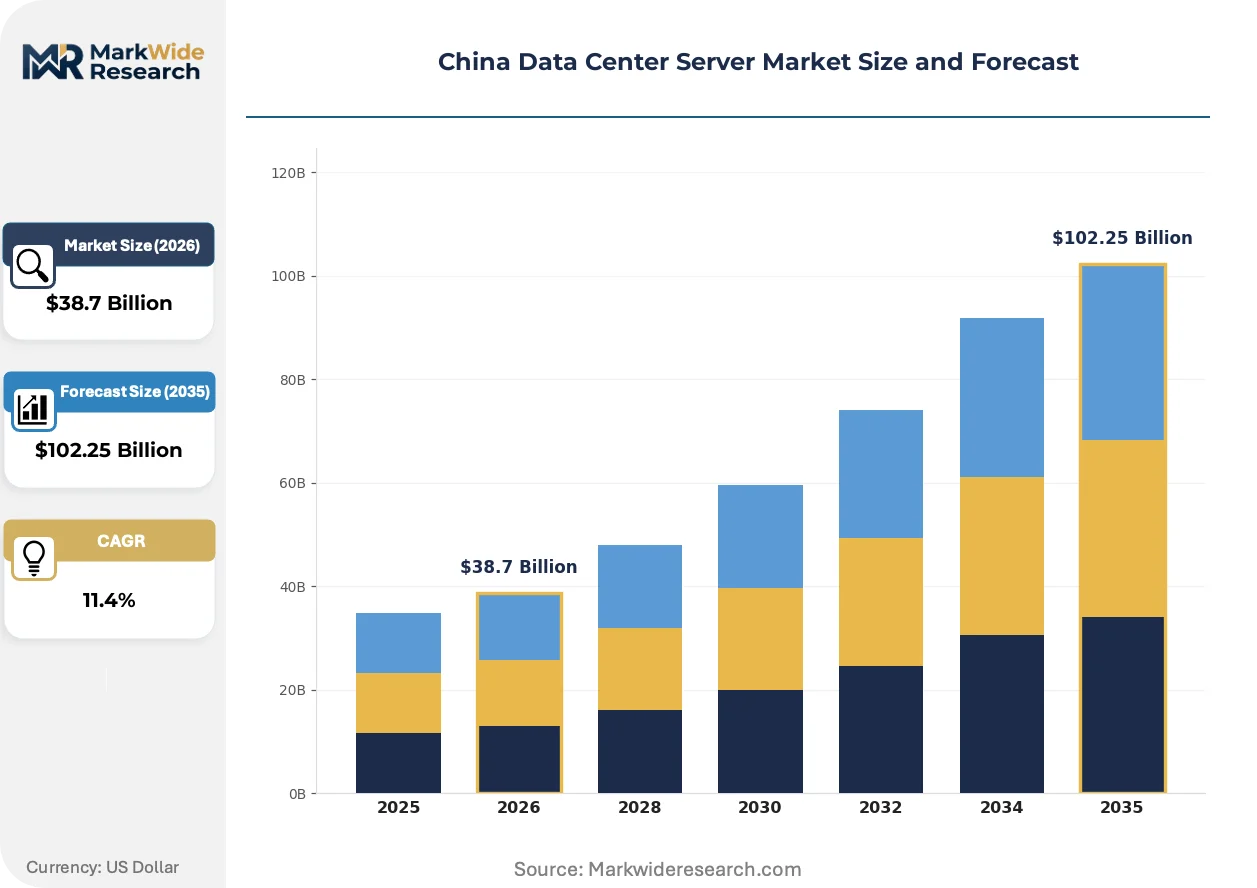
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Hyper-Converged Systems End User: Cloud Service Providers, Telecommunications, Enterprises, Government Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Colocation Service Type: Managed Services, Maintenance, Professional Services, Technical Support |
| Companies Covered | New H3C Technologies Co Ltd, Dawning Information Industry Company Limited, Huawei Technologies Co Ltd, Nanjing ZTE Software Co Ltd, Shenzhen Innovision Technology Co Ltd, Inspur Group, Dell Inc, Hyllsi Technology Co Ltd, Lenovo Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Server Market Trends and Innovations
Server design orthodoxy is fracturing along thermal and architectural axes as sovereign compute requirements and energy physics collide, producing divergent optimization paths for training versus inference workloads.
Direct liquid cooling is rendering obsolete air-cooled thermal envelopes for AI training nodes. Hyperscalers in Beijing and Shanghai now specify immersion-ready chassis for all GPU-heavy procurements above 25 kW per rack. Legacy CRAC-based designs face accelerated depreciation as power density requirements outstrip mechanical cooling capacity.
MIIT's GB standards for server energy efficiency are tightening disclosure granularity from facility-level to server-level metrics. Manufacturers must now submit idle and peak power curves for certification, with non-compliant systems excluded from state procurement catalogs. Domestic OEMs are redesigning power delivery subsystems to optimize for the new weighted efficiency formula.
Hyperscaler procurement panels are consolidating vendor lists to three approved suppliers per server category, reversing the fragmented sourcing of the 2015-2020 period. This concentration forces mid-tier manufacturers to specialize in edge or legacy support niches. Provincial SOEs face extended qualification timelines as they adapt to the new consolidated bidding frameworks.
China Data Center Server Market Segmentation
Server procurement patterns diverge sharply across deployment contexts in China, with hyperscaler standardization clashing against sovereign cloud customization and edge latency requirements. Understanding these fault lines reveals where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
Form factor selection tracks power density requirements and facility constraints across Beijing, Shanghai, and Shenzhen hyperscale clusters versus provincial edge deployments.
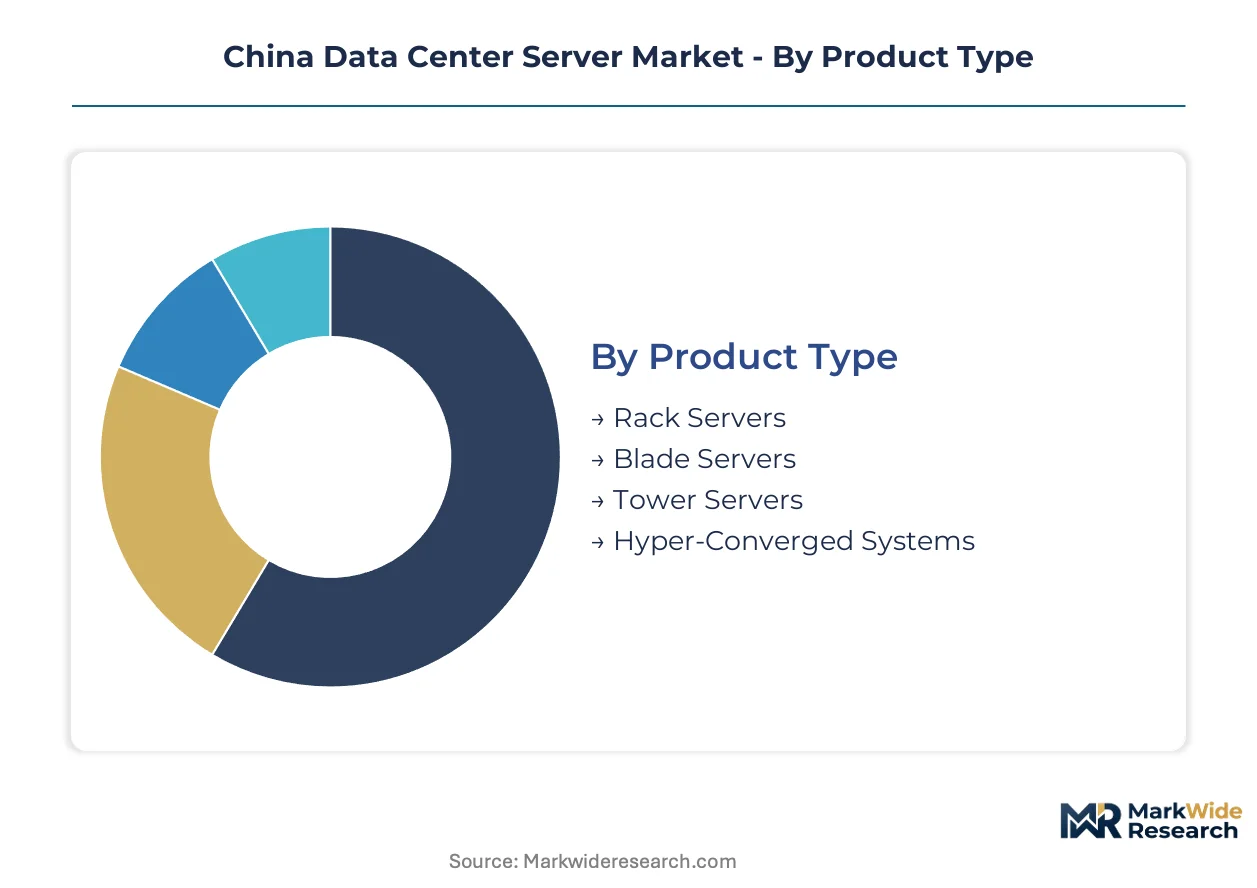
- Rack Servers:Standardized 19-inch chassis dominate hyperscale procurement with configurations exceeding 30 kW per rack for AI training nodes. Beijing and Shanghai cloud campuses specify immersion-ready variants under GB 50174 Tier III reliability mandates, compressing vendor qualification timelines.
- Hyper-Converged Systems:Integrated compute-storage-network appliances are displacing legacy three-tier infrastructure in provincial government consolidation projects. Guizhou and Inner Mongolia facilities favor these for rapid east-west computing resource transfer deployment without specialized integration labor.
- Blade Servers:High-density shared infrastructure persists in financial services core banking systems where space constraints dominate and x86 software inertia slows Arm migration.
- Tower Servers:Standalone vertical enclosures retain limited utility for remote enterprise edge use outside traditional data center footprints, fading from mainstream procurement.
The dominant share belongs to Rack Servers, while Hyper-Converged Systems is closing the gap fastest.
End User:
Buyer sophistication and procurement scale create tiered supply relationships, with state-backed tenders imposing domestic processor requirements that private cloud operators navigate differently.
- Cloud Service Providers:Hyperscalers drive volume procurement with consolidated vendor panels restricting three approved suppliers per server category. Their 25 kW-plus rack specifications are accelerating liquid cooling adoption across Beijing and Shanghai facilities.
- Government:Provincial SOEs face extended qualification timelines under new consolidated bidding frameworks while consolidating legacy IT estates. MIIT carbon intensity disclosure rules require verified renewable matching for facility approvals.
- Telecommunications:5G standalone rollouts create demand for converged rack platforms in prefecture-level cities with space-constrained central offices requiring compact liquid-cooled nodes.
- Enterprises:Industrial edge deployments in Guangdong and Jiangsu manufacturing plants require low-latency vision processing outside traditional data center footprints.
Cloud Service Providers command the largest procurement volumes, though Government tenders are expanding most quickly under sovereign computing mandates.
Deployment Model:
Infrastructure control preferences map directly to data sovereignty requirements and workload sensitivity, with cross-provincial migration triggering compliance friction under evolving cybersecurity classifications.
- Public Cloud:Third-party operated shared infrastructure concentrates in Beijing, Shanghai, and Shenzhen where hyperscale facilities cluster. East-west computing resource transfer mandates are redistributing training workloads to Inner Mongolia and Guizhou.
- Private Cloud:Single-tenant dedicated environments serve financial services core banking systems with tight x86 optimization requirements and stringent uptime obligations.
- Hybrid Cloud:Orchestrated public-private combinations address manufacturing edge deployments requiring low-latency local processing with centralized training coordination.
- Colocation:Multi-tenant facility leasing faces commissioning timeline extensions of 8-14 months in grid-constrained provinces under MIIT renewable verification requirements.
Public Cloud retains the dominant infrastructure share, while Private Cloud is gaining ground fastest among compliance-sensitive verticals.
Service Type:
Lifecycle support models reflect technician scarcity and immersion cooling complexity, with specialized skills commanding premium pricing in dielectric fluid handling protocols.
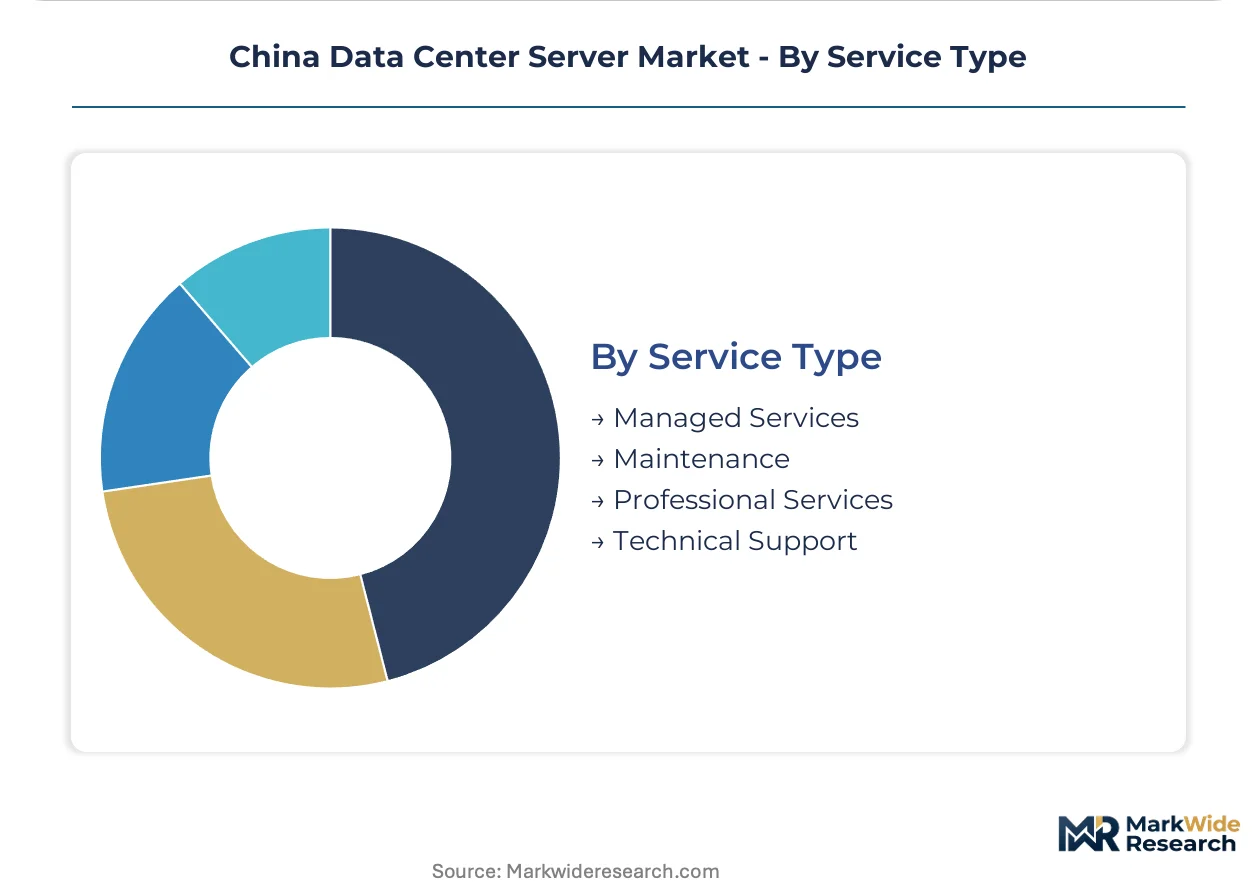
- Managed Services:Comprehensive operational outsourcing addresses provincial government capability gaps in liquid cooling maintenance and GPU cluster optimization.
- Maintenance:Break-fix and preventive support contracts face technician pipeline constraints for immersion cooling leak detection and cold-plate servicing.
- Professional Services:Design and implementation consulting accelerates for legacy facility retrofits facing demolition-rebuild thresholds when liquid cooling exceeds 40 percent of rack count.
- Technical Support:Remote and on-site assistance tiers differentiate by response time commitments, with premium tiers covering dielectric fluid emergency protocols.
Managed Services holds the largest revenue pool, while Professional Services is climbing the fastest on legacy modernization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports data center servers through the Yangtze River Delta corridor to Southeast Asian cloud operators expanding Jakarta and Singapore facilities. Domestic procurement absorbs over 80% of production volume.
Beijing-Tianjin-Hebei
Hyperscaler AI training clusters and sovereign cloud mandates concentrate procurement here. MIIT enforces GB 50174 Tier III reliability standards for all new facility approvals. Zhangjiakou hosts relocated workloads under east-west computing transfer protocols with direct renewable grid connections.
Yangtze River Delta
Shanghai cloud campuses drive liquid-cooled rack specifications exceeding 30 kW density. SAMR monitors consolidated vendor panels restricting three approved suppliers per server category. Kunshan manufacturing bases supply immersion-ready chassis for GPU-heavy deployments.
Pearl River Delta
Shenzhen edge computing nodes serve 5G standalone rollouts in prefecture-level cities. The national data bureau coordinates workload redistribution to western provinces. Guangdong industrial plants deploy compact liquid-cooled vision processing systems outside traditional data center footprints.
Western China
Inner Mongolia and Guizhou absorb east-west computing transfer workloads with stranded renewable baseload. Dual carbon enforcement compresses power supply timelines for eastern corridor deployments. Guiyang facilities leverage lower land costs and verified renewable matching for 30 kW-plus rack densities.
Sichuan-Chongqing
Provincial government IT estate consolidation accelerates hyper-converged system procurement. Carbon intensity disclosure rules extend commissioning timelines by 8-14 months in grid-constrained zones. Chengdu serves as a secondary training cluster destination with hydroelectric grid advantages.
China Data Center Server Market Competitive Landscape
Channel-controlling players compete with product-specialist players across state-backed tender frameworks and private cloud procurement channels. The vendor base consolidates around three approved suppliers per server category under hyperscaler qualification panels. Strategic archetypes include domestic chip-to-system vertical integrators, volume manufacturing specialists, and telecommunications edge converged platform providers. Competitive moves center on vendor list consolidation and liquid cooling subsystem partnerships.
Within the domestic vertical integration tier, Huawei Technologies Co Ltd and Inspur Group occupy anchor positions through sovereign computing mandates. New H3C Technologies Co Ltd exemplifies the telecommunications edge specialization archetype. These three entities represent the consolidated supplier base now dominating state procurement catalogs.
| Leading Market Players |
|---|
| New H3C Technologies Co Ltd |
| Dawning Information Industry Company Limited |
| Huawei Technologies Co Ltd |
| Nanjing ZTE Software Co Ltd |
| Shenzhen Innovision Technology Co Ltd |
| Inspur Group |
| Dell Inc |
| Hyllsi Technology Co Ltd |
| Lenovo Group Limited |
| Others |
Pricing and Supply Chain Analysis
Kunshan manufacturing bases anchor server chassis production capacity, concentrating component sourcing power in the Yangtze River Delta corridor. This geographic clustering enables tier-one OEMs to negotiate favorable terms while compressing lead times for hyperscaler procurement panels.
Pricing Analysis
Current-generation liquid-cooled rack configurations command substantial premiums over prior-generation air-cooled chassis, while next-generation immersion-ready designs are pre-quoting at elevated tiers. The dominant pricing structure runs on contract-based long-term offtake agreements with hyperscalers, with price differentiation driven by GB 50174 certification grade and volume scale commitments. Pricing pressure stems from domestic processor yield volatility constraining Kunpeng and Ascend die availability. Cloud service providers exhibit the least price sensitivity given consolidated vendor panels, while provincial government tenders face acute budget constraints.
Supply Chain Analysis
Extended payment terms from hyperscaler procurement panels are forcing mid-tier manufacturers to seek supply-chain finance facilities from state-backed lenders. Component sourcing draws from Taiwan for advanced node semiconductors, South Korea for memory modules, and domestic foundries for mature-node power management ICs. Raw material dependencies center on copper busbars for power delivery, dielectric fluids for immersion cooling, and specialized aluminum alloys for chassis thermal management. Single-source vulnerability concentrates in advanced node fabrication capacity. Distribution runs through direct OEM relationships with hyperscalers and state procurement catalogs for government tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as liquid cooling penetration accelerates from niche AI training deployments toward mainstream rack specifications, with sovereign cloud mandates creating sustained procurement tailwinds.
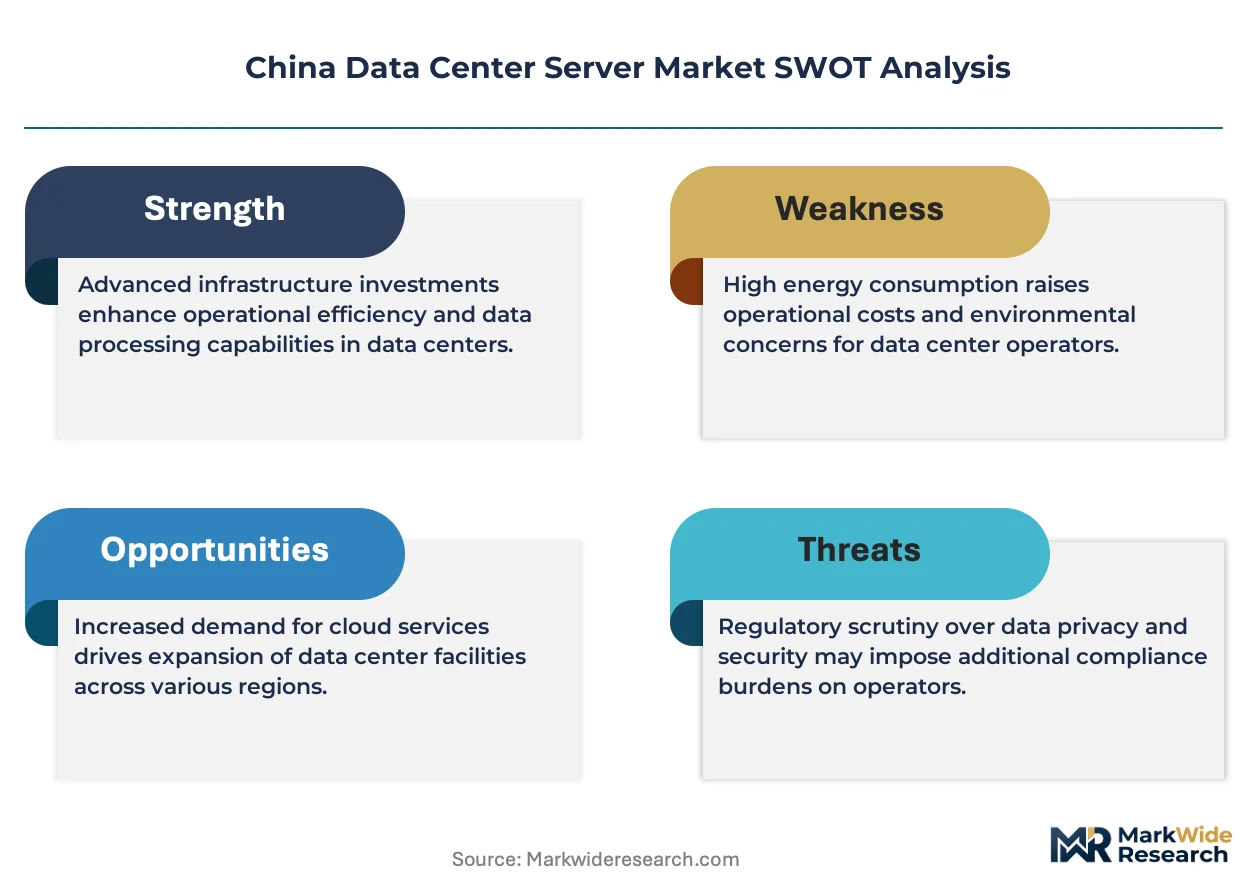
For Market Incumbents: Entrench dominance through backward integration into liquid cooling subsystem production and captive supply of immersion-ready chassis platforms. Huawei Technologies and Inspur Group should accelerate Kunpeng processor yield improvement to counter allocation bottlenecks threatening state tender participation. Channel control through consolidated vendor panels offers defensive moats against emerging telecommunications edge specialists. For New Entrants and Emerging Players: Build out specialized capabilities in dielectric fluid handling protocols and compact edge node design for prefecture-level 5G deployments. The telecommunications edge segment remains most penetrable given space-constrained central office requirements that favor converged rack platforms. A direct go-to-market angle through provincial SOE qualification timelines can bypass hyperscaler vendor consolidation. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign compute infrastructure play because national data bureau mandates for east-west computing resource transfer will sustain facility buildouts regardless of cyclical cloud capex fluctuations. Target acquisition candidates include liquid cooling subsystem specialists and Arm-based server design houses with MIIT certification pathways. Monitor MIIT carbon intensity disclosure enforcement timelines as the critical inflection signal for commissioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liquid Cooling Subsystems | Captive production of cold-plate and immersion components secures margin pools as GB standards tighten thermal requirements. |
| Arm-Based Processor Certification Investment | MIIT server-level energy efficiency disclosure rules favor architectures optimized for the new weighted efficiency formula. |
| Provincial Edge Deployment Partnership | Prefecture-level 5G standalone rollouts create volume channels outside hyperscaler vendor consolidation. |
| Renewable-Verified Facility Qualification | SAMR pending green procurement scoring will prioritize servers with verified embodied carbon audits. |
| Dielectric Fluid Technician Pipeline Development | Vocational training partnerships address scarcity constraining immersion cooling deployment velocity. |
Research Methodology
Desk research of MIIT policy filings, hyperscaler procurement disclosures, and GB standards documentation preceded structured interviews with data center facility planners, server OEM product managers, and provincial SOE procurement officers. Secondary validation incorporated customs trade data, SAMR tender announcement databases, and foundry capacity reports. Bottom-up unit economics for rack configurations were triangulated against top-down market sizing from facility commissioning pipelines.
Forecast assumptions held fixed the east-west computing resource transfer mandate timelines and GB 50174 Tier III reliability enforcement intensity, while varying domestic processor yield trajectories and renewable grid interconnection velocities. The analytical framework modeled segmentation across product type, end user, deployment model, and cooling architecture across the analysis window. CAGRs were derived from facility pipeline tracking and hyperscaler capex commitment patterns, with inputs from liquid cooling penetration curves and sovereign cloud budget allocation disclosures.
Practitioners should monitor MIIT carbon intensity disclosure enforcement rigor and domestic advanced node fabrication yield reports for early signals of commissioning timeline compression or extension. Forecasts reflect these documented assumptions; deviation in dual carbon policy implementation pace, inter-provincial data sovereignty friction resolution, or Arm-based software ecosystem maturity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
North America Green Data Center Market