
 Data Center Transformation Market | 2026-2036
Data Center Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Transformation Market Intelligence
The substitution of on-premise physical servers with virtualized cloud infrastructure is realigning the capital expenditure models for global enterprises. Microsoft leverages its Azure platform to dominate the cloud workload migration space, offering scalable solutions. IBM specializes in complex hybrid cloud integration services for large financial institutions and government agencies. Schneider Electric provides critical data center infrastructure management solutions, focusing on power and cooling efficiency.
Data center transformation encompasses the comprehensive modernization of IT infrastructure, facilities, and operational models to enhance business agility and performance. A key objective is improving energy efficiency, which is benchmarked using metrics like Power Usage Effectiveness (PUE) to track non-IT energy use. Among solution types, cloud workload migration and network optimization are experiencing significant investment. The hybrid cloud deployment model remains the prevailing strategy for enterprises seeking to balance the security of on-premises systems with public cloud scalability.
The EU's General Data Protection Regulation (GDPR) influences data residency choices, shaping where new data centers are built to comply with sovereignty rules. In the United States, the EPA's ENERGY STAR program for data centers provides a key framework for voluntary energy efficiency certification and benchmarking. Stakeholders must navigate the complex trade-offs between these data sovereignty regulations, cybersecurity imperatives, and the pursuit of sustainable operations.
Market Dynamics
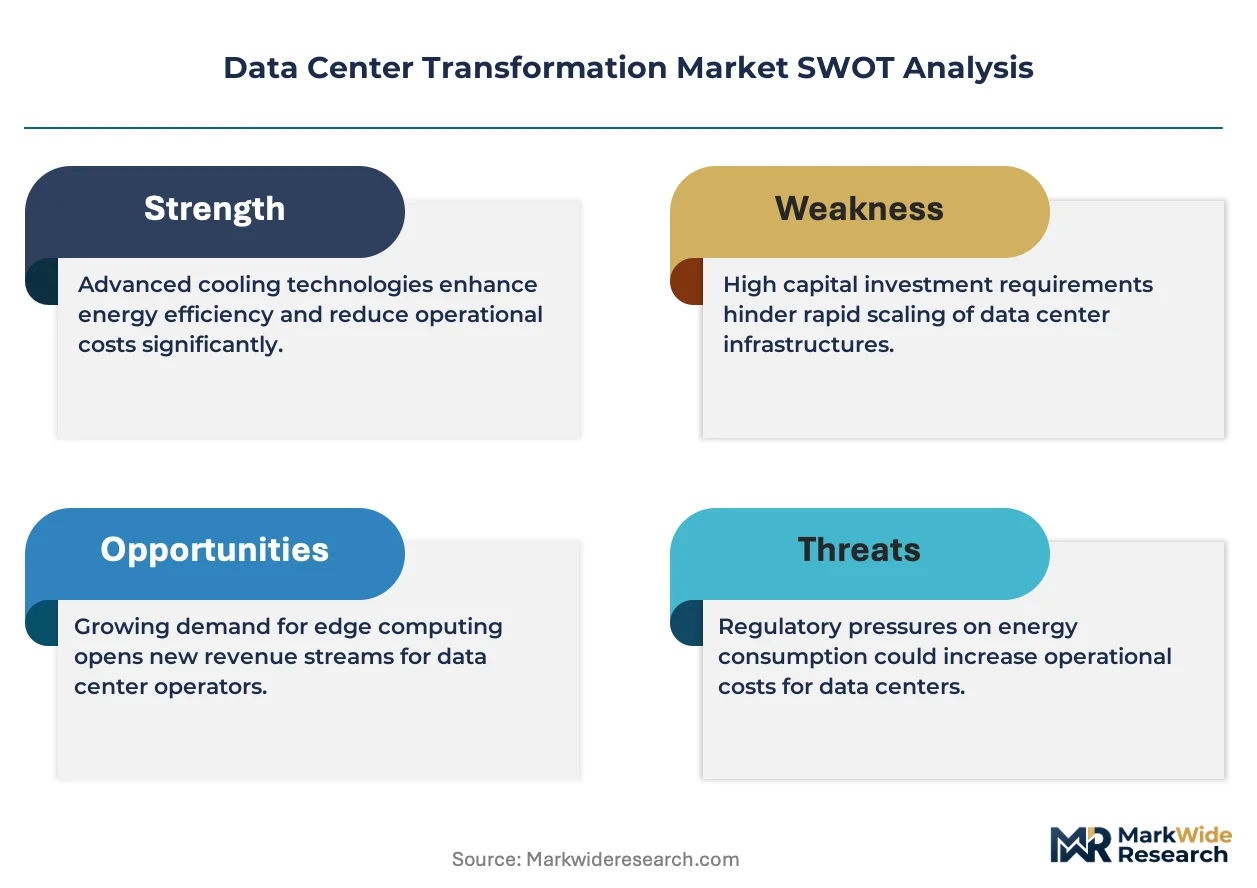
The central dynamic in data center transformation is the tension between escalating demand for computational power and the urgent need for sustainable operations. This is driven by both regulatory pressures for energy efficiency and the economic imperative to optimize cloud infrastructure costs.
Growth Catalysts
- BFSI Sector Modernization:Financial institutions are heavily investing in IT infrastructure upgrades to improve disaster recovery capabilities, secure transaction processing, and comply with stringent financial regulations, driving demand for both cloud migration and on-premise modernization.
- Sustainability Mandates:European regulations like the Corporate Sustainability Reporting Directive (CSRD) compel enterprises to measure and disclose data center energy consumption, directly stimulating investment in energy-efficient infrastructure and performance monitoring solutions like PUE.
- Hybrid Cloud Adoption:The hybrid cloud model remains the dominant enterprise strategy, creating persistent demand for integration services, network optimization tools, and management platforms that bridge private data centers with public cloud resources.
Market Restraints
- Legacy System Complexity:The deep integration of mission-critical legacy systems, particularly mainframes in banking and government, presents a significant technical barrier and cost impediment to modernization and full cloud migration.
- Data Sovereignty Regulations:Strict data residency laws, including the EU's GDPR, impose geographic constraints on data storage and processing, complicating architectural design for multinational corporations and limiting the choice of cloud providers.
- High Capital Expenditure:Modernizing or building new data center facilities requires immense upfront capital investment in power, cooling, and physical security infrastructure, representing a substantial hurdle for many organizations without access to hyperscale resources.
Strategic Opportunities
- Edge Computing Expansion:The growth of IoT and 5G applications creates a significant opportunity for smaller, distributed edge data centers located closer to end-users, opening new markets beyond established technology hubs.
- AI-Driven Operations (AIOps):Converging artificial intelligence and machine learning with data center management tools offers a pathway to create autonomous infrastructure that can predict failures, optimize energy usage, and self-heal without human intervention.
- Emerging Market Penetration:Developing technology ecosystems in regions like Southeast Asia and Latin America present white-space opportunities for colocation and cloud service providers to build infrastructure that serves growing local and regional demand.
Industry Challenges
- Specialized Skills Scarcity:A persistent talent gap exists for professionals who possess a combination of skills in modern cloud-native technologies, cybersecurity, and the management of aging on-premise infrastructure, hindering transformation projects.
- Cybersecurity in Hybrid Environments:Protecting a distributed IT footprint that spans on-premise systems, multiple public clouds, and edge locations creates a vastly expanded attack surface, challenging security teams to maintain visibility and consistent policy enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Transformation Market |
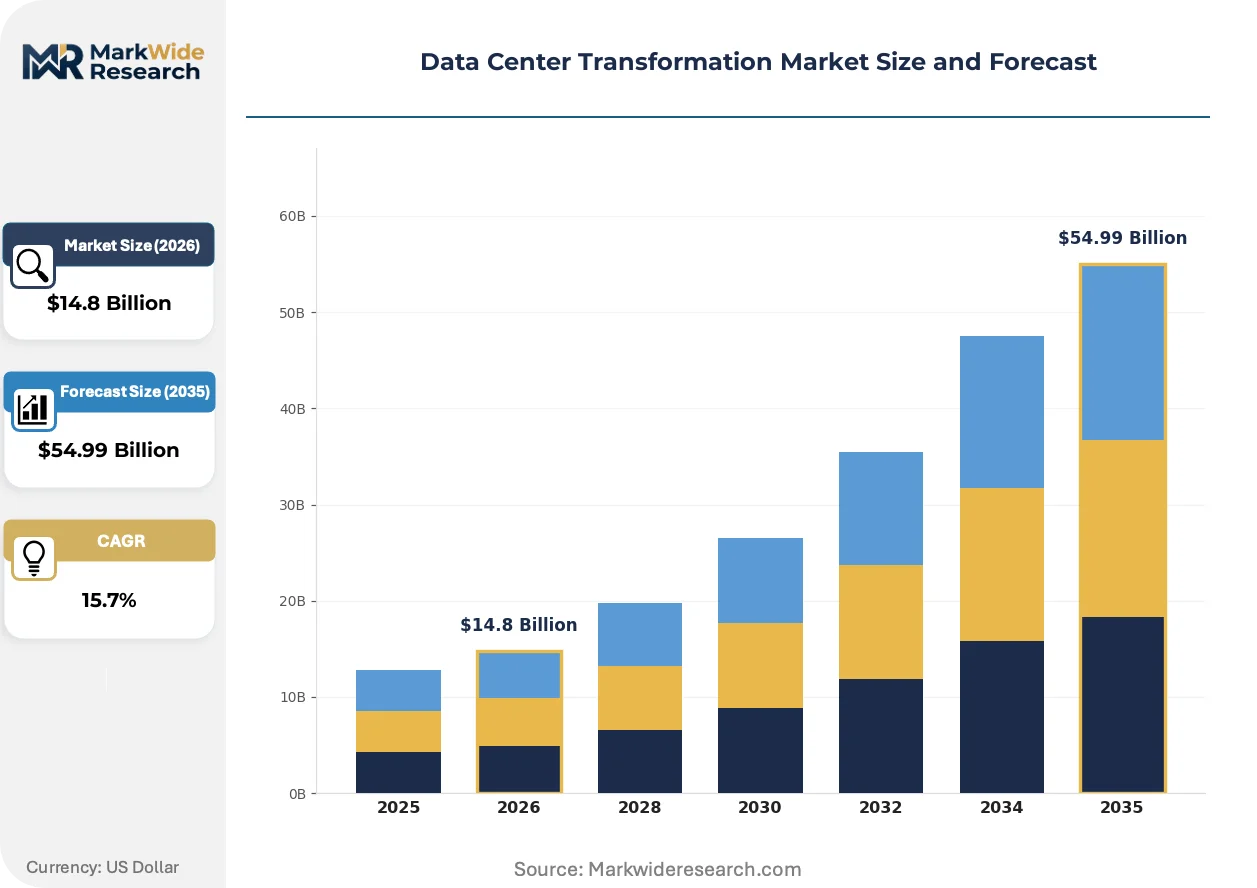
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $54.99 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Colocation, Multi-Cloud, Hybrid Cloud, Edge Data Centers Solution Type: Data Center Infrastructure Management, Virtualization, Network Optimization, Security Solutions, Cloud Workload Migration Application: IT Infrastructure Modernization, Disaster Recovery, Capacity Expansion, Cloud Integration, Compliance Management End User Industry: BFSI, Telecommunications, Government Agencies, Media & Entertainment, Education |
| Companies Covered | IBM, Microsoft, Cisco Systems, Inc., Dell Inc., Schneider Electric SE, Accenture, Atos, HCL Technologies, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Transformation Market Strategic Shifts & Innovations
Sustainability and intelligence are defining the next wave of data center evolution. Innovations focus on radically improving energy efficiency at the hardware level while abstracting operational complexity through software, enabling more autonomous and resilient infrastructure management across distributed environments.
Liquid cooling technologies are a direct response to the thermal challenges of high-density computing. These systems, including direct-to-chip and immersion cooling, are being adopted by hyperscalers and high-performance computing operators to manage intense heat from AI accelerators and advanced CPUs. This fundamental shift from traditional air cooling is electrifying the approach to facility design, enabling server densities previously considered unfeasible.
The US Environmental Protection Agency's ENERGY STAR for Data Centers program is a key policy influencer. It establishes a voluntary but highly regarded benchmark for certifying energy performance, creating a clear market signal for sustainable operations. Colocation providers in competitive markets like Northern Virginia actively pursue this certification to attract enterprise customers who have their own corporate sustainability mandates to fulfill.
A notable behavioral shift is the move from fixed-capacity contracts to flexible, consumption-based models for infrastructure. This pattern disrupts the traditional long-term colocation lease, as enterprises now demand the ability to scale resources on-demand via hybrid cloud management platforms. This trend is most pronounced in agile-dependent sectors like digital media and software development, where compute needs are highly variable.
Data Center Transformation Market Segmentation
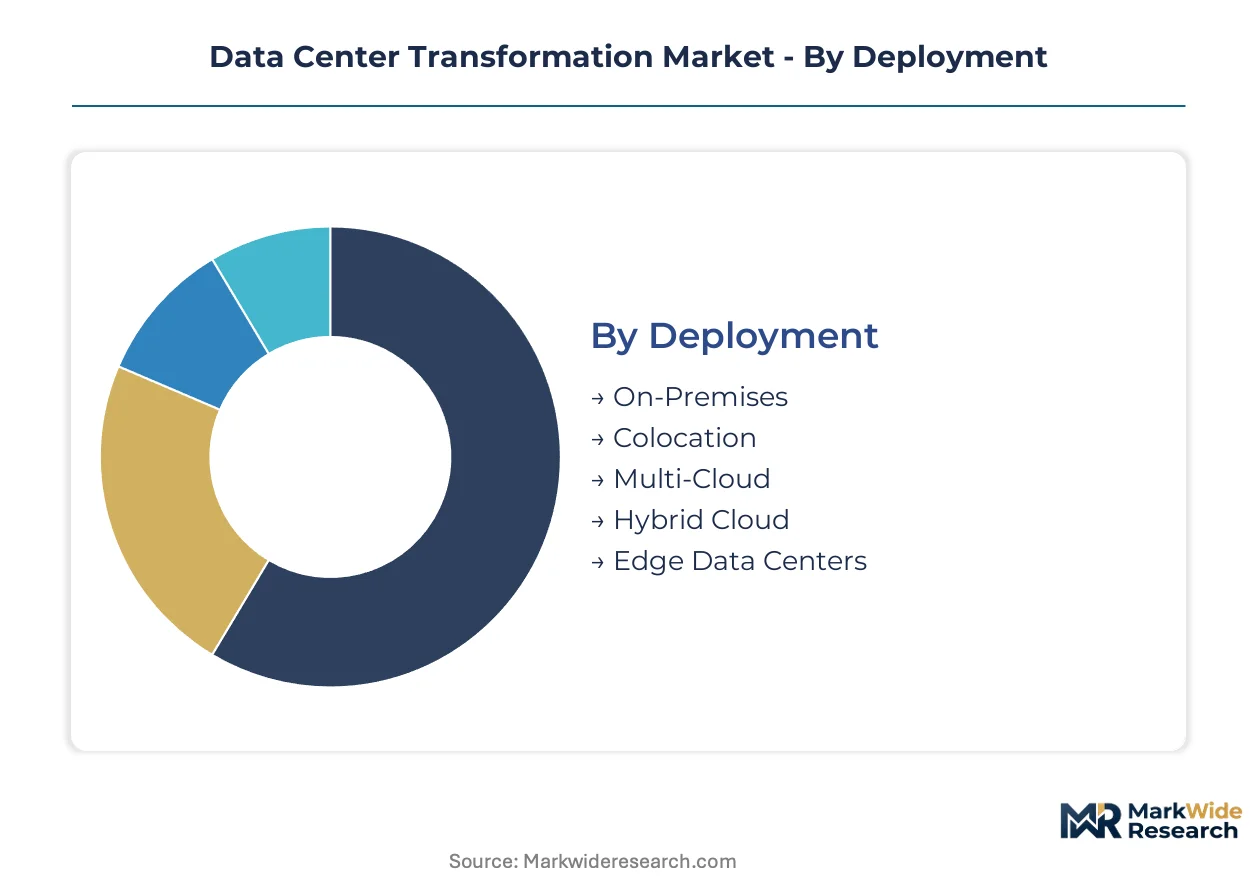
Understanding the segmentation within the data center transformation market reveals how enterprises prioritize investments and adopt new technologies based on their operational needs and strategic objectives. This granular analysis highlights the diverse approaches organizations take to modernize their IT infrastructure, facilities, and operational models.
Deployment:
The deployment models for data center transformation vary significantly in their upfront capital requirements and operational expenditure profiles.
- On-Premises:This model involves maintaining privately owned and operated data centers within an organization's own facilities, offering maximum control over data and infrastructure. It demands substantial capital for hardware, software, and physical security.
- Colocation:Enterprises lease space for their servers and networking hardware in a third-party data center facility, benefiting from shared power, cooling, and physical security infrastructure. Demand for colocation services is concentrating in established technology hubs like Northern Virginia.
- Multi-Cloud:This strategy involves using cloud services from multiple public cloud providers, distributing workloads across different environments to avoid vendor lock-in and enhance resilience. It requires sophisticated management tools for seamless operation.
- Hybrid Cloud:This deployment integrates public cloud services with private on-premises infrastructure, allowing data and applications to move between environments. This model balances the security of on-premises systems with public cloud scalability, a prevailing enterprise strategy.
- Edge Data Centers:These are smaller, distributed data centers located closer to end-users and data sources, enabling lower latency and faster processing for IoT and 5G applications. Their expansion is driven by the need for localized computational power.
Colocation absorbs the bulk of installed capacity; Edge Data Centers are expanding most quickly.
Solution Type:
Solutions are often chosen based on the specific operational challenges enterprises aim to address in their IT environments.
- Data Center Infrastructure Management:These solutions provide centralized monitoring and management of a data center's physical infrastructure, including power, cooling, and environmental controls. Schneider Electric provides critical infrastructure management solutions focusing on power and cooling efficiency.
- Virtualization:This technology creates virtual versions of computing resources, such as servers, storage, and networks, abstracting hardware from software to improve resource utilization and flexibility. Virtualization is fundamental to cloud infrastructure.
- Network Optimization:Solutions in this category enhance network performance, reliability, and security across distributed data center and cloud environments. Network optimization is critical for efficient hybrid cloud operations.
- Security Solutions:These encompass a range of technologies and practices designed to protect data centers and their data from cyber threats, unauthorized access, and compliance breaches. Cybersecurity in hybrid environments presents an expanded attack surface.
- Cloud Workload Migration:This involves moving applications, data, and IT processes from on-premises infrastructure to cloud environments, leveraging platforms like Microsoft Azure for scalable solutions. Cloud workload migration is experiencing significant investment.
Cloud Workload Migration solutions dominate investment; Security Solutions are gaining traction rapidly.
Application:
Enterprises adopt data center transformation for diverse strategic objectives, often influenced by their industry's regulatory landscape and competitive pressures.
- IT Infrastructure Modernization:This application focuses on upgrading outdated hardware, software, and network components to improve performance, efficiency, and scalability. The BFSI sector is heavily investing in IT infrastructure upgrades.
- Disaster Recovery:Data center transformation enhances an organization's ability to recover critical data and systems following a disruptive event, ensuring business continuity. Financial institutions are improving disaster recovery capabilities.
- Capacity Expansion:Organizations undertake transformation to increase their computing, storage, or network capacity to meet growing demand or support new initiatives. This often involves adopting scalable cloud resources.
- Cloud Integration:This involves connecting and managing disparate cloud services and on-premises systems to create a unified and efficient IT environment. IBM specializes in complex hybrid cloud integration services.
- Compliance Management:Transformation initiatives address regulatory requirements, such as data residency rules under the EU's GDPR or energy reporting mandates like the CSRD. Compliance management influences data center location choices.
IT Infrastructure Modernization represents the primary driver for transformation initiatives; Compliance Management is exhibiting the steepest expansion trajectory.
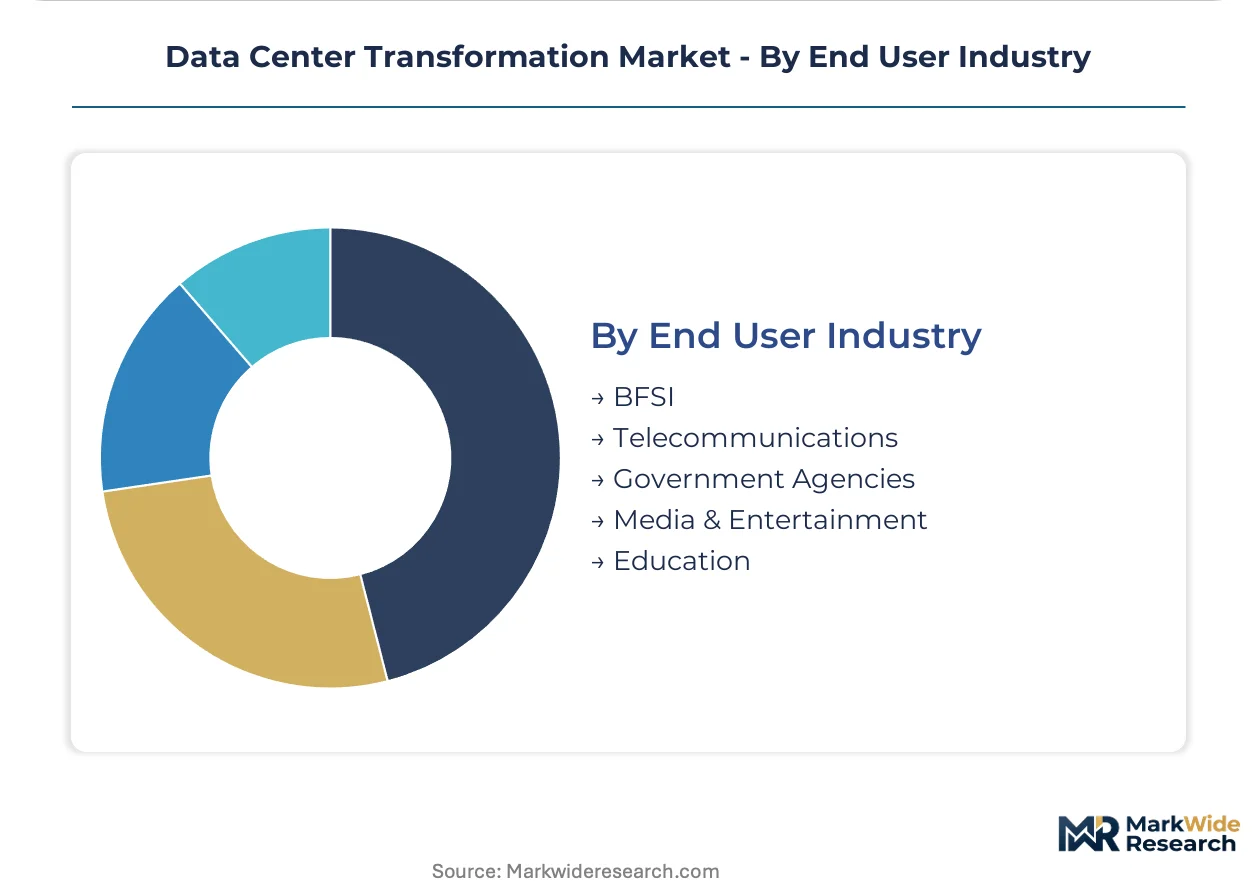
End User Industry:
Each end-user industry approaches data center transformation with distinct priorities, reflecting varying levels of digital maturity and regulatory compliance burdens.
- BFSI:The Banking, Financial Services, and Insurance sector is a major adopter, driven by the need for secure transaction processing, enhanced disaster recovery, and compliance with stringent financial regulations. Adoption within the BFSI sector is accelerating.
- Telecommunications:This sector leverages data center transformation to support 5G rollout, network function virtualization, and the management of vast amounts of subscriber data. Telecommunications companies are crucial for edge computing infrastructure.
- Government Agencies:Public sector entities modernize their data centers to improve service delivery, enhance data security, and comply with national data sovereignty laws. IBM provides complex hybrid cloud integration for government agencies.
- Media & Entertainment:This industry requires scalable and agile data center solutions to handle large volumes of content, support streaming services, and manage fluctuating computational demands for rendering and processing. Agile-dependent sectors show flexible consumption models.
- Education:Educational institutions adopt transformation to support e-learning platforms, research computing, and administrative systems, often balancing cost-efficiency with performance requirements. This sector frequently leverages cloud resources for scalability.
The BFSI sector leads in transformation expenditure; Media & Entertainment is climbing the fastest in adoption rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for data center transformation solutions shows significant concentration in established technology hubs globally. This strategic focus drives investment in colocation and hybrid cloud services in key regions. Enterprises prioritize locations offering robust infrastructure, regulatory compliance, and connectivity for their evolving IT needs.
United States
Demand for IT infrastructure modernization and cloud workload migration is high among BFSI and government agencies. The EPA's ENERGY STAR program influences voluntary energy efficiency certification for data centers. Northern Virginia remains a primary hub for colocation services, attracting major hyperscalers and enterprise customers.
Germany
European enterprises seek advanced data center solutions for cloud integration and compliance management. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates energy consumption disclosure, stimulating green infrastructure investment. Frankfurt leads as a major European data center hub, serving as a critical internet exchange point for the continent.
British
Financial institutions and media companies in the UK require robust disaster recovery and scalable cloud capacity. Compliance with GDPR and other data residency regulations heavily influences data center architectural choices. London's Docklands area continues to host a dense concentration of financial and media data centers, supporting high-speed transactions.
Japan
Advanced manufacturing and telecommunications sectors drive demand for network optimization and edge computing. METI regulations promote energy efficiency in IT facilities, encouraging investment in sustainable data center technologies. Tokyo serves as a significant regional data center market, supporting a wide range of digital services and cloud deployments.
Singapore
Southeast Asia's digital economy fuels strong demand for multi-cloud and hybrid cloud integration services. Singapore's national policies emphasize digital infrastructure development and data sovereignty within the region. Jurong and Tai Seng areas are key data center clusters, attracting international cloud providers and colocation operators.
Data Center Transformation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the data center transformation market. The market exhibits a tiered structure, ranging from hyperscale cloud providers offering broad platforms to specialized firms focusing on niche infrastructure solutions. Key archetypes include global cloud platform giants, complex hybrid IT integration service providers, and physical data center infrastructure management solution vendors. Strategic partnerships, portfolio diversification, and geographic expansion are common competitive moves among market participants.
Global cloud platform giants like Microsoft exemplify leadership in scalable cloud workload migration solutions, leveraging extensive platform capabilities for enterprises worldwide. IBM occupies a distinct position, specializing in complex hybrid cloud integration services, particularly for large financial institutions and government agencies that require bespoke solutions. Schneider Electric, an established infrastructure solution provider, anchors the market for critical data center infrastructure management, focusing on power and cooling efficiency across various facility types. These companies collectively represent the diverse expertise and service offerings required for comprehensive data center modernization initiatives.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Cisco Systems, Inc. |
| Dell Inc. |
| Schneider Electric SE |
| Accenture |
| Atos |
| HCL Technologies |
| Wipro |
Cost & Logistics Intelligence
Specialized cloud engineering talent concentrated in established technology hubs, such as Northern Virginia and Frankfurt, directly influences service pricing. Labor-cost differentials across these regions contribute to varying pricing-tier spreads for data center transformation services.
Pricing Analysis
Volume-based contracts for colocation services typically operate on long-term agreements, while cloud workload migration often uses a consumption-based model. Price differentiation stems from the level of customization required for complex hybrid cloud integrations and the specific service level agreements for uptime. Pricing pressure stems from the commoditization of basic public cloud resources by hyperscalers. Small and medium enterprises exhibit higher price sensitivity for standardized solutions, whereas large financial institutions prioritize value-based, secure offerings for their mission-critical operations.
Supply Chain Analysis
Logistics and freight costs for heavy IT infrastructure components, such as servers and cooling systems, significantly impact the final cost of data center deployment. Hardware components often source from manufacturing hubs in China, Taiwan, and Southeast Asia. The supply chain relies on a steady flow of semiconductors, specialized cooling liquids, and rare earth elements for advanced hardware. Geopolitical tensions and trade policies create tariff exposure for critical IT hardware components. Downstream distribution runs through a network of value-added resellers, system integrators, and direct sales channels to enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center transformation represents a critical technology-transition phase, with virtualized cloud infrastructure displacing traditional on-premise physical servers. This shift reshapes enterprise IT strategies and operational models.
For Market Incumbents: Deploy advanced AIOps platforms to optimize energy efficiency and predict infrastructure failures. This counters margin pressure from hyperscale providers in commodity services. Invest in specialized cybersecurity certifications to address expanded attack surfaces in hybrid environments. Expand offerings in sovereign cloud solutions to comply with GDPR and other data residency regulations.
For New Entrants and Emerging Players: Regional enterprises in developing technology ecosystems often struggle with complex hybrid cloud integrations. These players require localized, cost-effective solutions for disaster recovery and compliance management. Offer specialized consulting and managed services for edge computing deployments in underserved urban areas. Focus on industry-specific vertical solutions, such as secure data processing for regional financial institutions.
For Investors and Strategic Acquirers: Re-rating potential sits with infrastructure management software providers given the urgent need for operational efficiency and sustainability. Target specialized firms developing liquid cooling technologies or AI-driven optimization tools for acquisition. These companies offer long-term value in a market driven by energy efficiency mandates. Watch for increased enterprise adoption of consumption-based infrastructure models as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven DCIM Solutions | Enhances operational efficiency and energy optimization for data centers. |
| Expand Edge Computing Infrastructure | Supports low-latency applications for IoT and 5G in new markets. |
| Offer Sovereign Cloud Services | Ensures compliance with strict data residency regulations like GDPR. |
| Acquire Hybrid Cloud Integration Specialists | Strengthens capabilities for complex enterprise IT modernization projects. |
| Invest in Liquid Cooling Technologies | Addresses thermal challenges of high-density AI and HPC workloads. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and technology whitepapers underwrites the qualitative findings. This study combines primary interviews with IT infrastructure architects, data center operations managers, and cloud solution vendors. Secondary validation draws from hyperscaler financial disclosures, EPA ENERGY STAR program data, and EU CSRD guidelines. A rigorous bottom-up and top-down triangulation process ensured data consistency.
Forecasts were anchored to a robust historical reference period, extending growth trajectories across the analysis window. The analytical framework modeled segmentation dimensions including deployment type, solution type, application, and end-user industry. CAGRs were derived by projecting technology adoption curves and infrastructure investment cycles. Key forecast inputs included projected enterprise IT spending and regulatory compliance timelines.
Revisions become necessary when significant geopolitical shifts or unexpected technological breakthroughs materialize. Forecasts reflect assumptions regarding regulatory stability and sustained enterprise digital transformation initiatives. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market