
 South Africa Data Center Market | 2026-2036
South Africa Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Market Insights
POPIA is decoupling data center investment from generic IT infrastructure budgets by mandating local storage for personal information. Teraco leverages its carrier-neutral campus in Isando to sustain cross-border interconnection demand. Africa Data Centres anchors expansion in Cape Town with direct seawater cooling access. NTT DATA competes through managed hosting specialization for enterprise compliance workloads.
A data center constitutes a purpose-built facility housing servers, storage systems, and networking equipment with redundant power, cooling, and connectivity infrastructure maintaining 99.999% uptime for digital service delivery. Colocation dominates revenue as enterprises abandon owned facilities, while cloud services represent the fastest-growing product type as Microsoft and Amazon Web Services localize regions. Hybrid deployment models concentrate margin pools where enterprises blend on-premise control with off-premise elasticity.
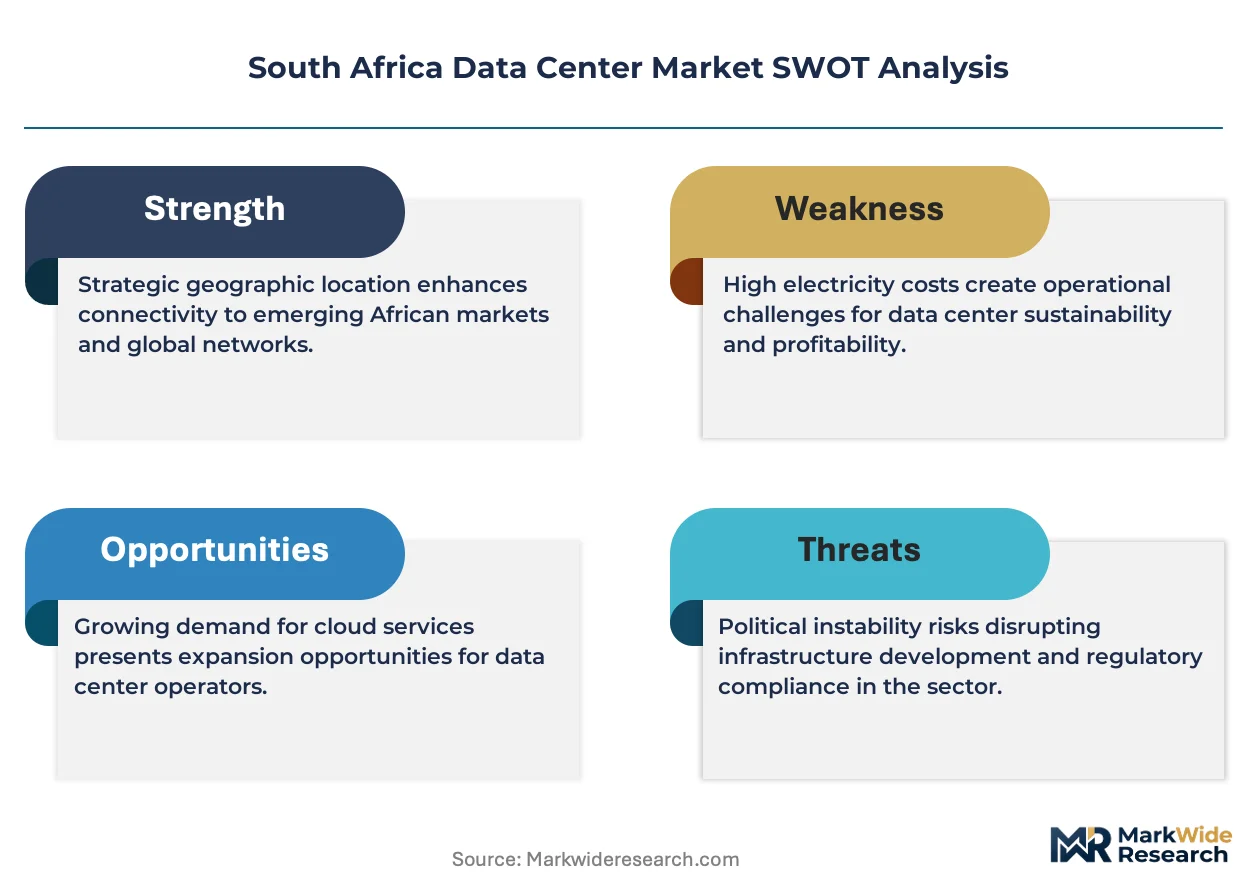
The Independent Communications Authority of South Africa governs spectrum and licensing for data center connectivity, while the National Energy Regulator of South Africa shapes power cost structures through tariff approvals. BIS standards and local fire safety codes further constrain facility design. Stakeholders must monitor grid stability commitments and renewable power purchase agreement availability before committing to long-term capacity expansion.
Market Dynamics
Data sovereignty mandates under POPIA are forcing financial services and healthcare enterprises to repatriate workloads from offshore cloud regions, redirecting capital toward locally certified facilities with certified compliance architectures.
Growth Catalysts
- POPIA Data Localization:The Protection of Personal Information Act mandates domestic storage for personal data, compelling enterprises to expand colocation footprints in Johannesburg and Cape Town.
- Financial Services:Banks and insurers are consolidating disaster recovery sites into carrier-neutral campuses to satisfy dual-redundancy requirements under prudential standards.
- Submarine Cable Landings:New fiber systems connecting Melkbosstrand and Mtunzini are reducing latency to European and Asian financial centers, attracting latency-sensitive trading workloads.
Market Restraints
- Eskom Grid Instability:Rolling blackouts and tariff volatility are inflating diesel generator run costs and complicating power purchase agreement negotiations for hyperscale builds.
- Liquid Cooling Supply Concentration:Specialized heat exchanger and coolant distribution unit manufacturing concentrates in German and Chinese supplier bases, extending procurement lead times.
- Water Scarcity in Northern Cape:Drought conditions are constraining evaporative cooling deployment outside coastal zones, limiting greenfield site selection.
Strategic Opportunities
- Renewable Energy Wheeling:Regulatory reforms enabling private power trading are allowing operators to secure wind and solar supply independent of municipal distributors.
- Edge Micro-Data Centers:Mining and logistics operations in Limpopo and Mpumalanga require sub-10ms latency for autonomous vehicle coordination and predictive maintenance analytics.
- Carbon Border Adjustment Preparedness:EU-facing exporters are pre-certifying facilities against ISO 14064 to future-proof data hosting against emerging Scope 3 disclosure requirements.
Industry Challenges
- Critical Facilities Engineering Talent:South Africa produces fewer than 200 certified data center design engineers annually, creating bidding wars for Uptime Institute-accredited professionals.
- Legacy Mainframe Migration Complexity:Government and parastatal entities operate COBOL-dependent systems that resist containerization, forcing hybrid architectures with elevated integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Market |
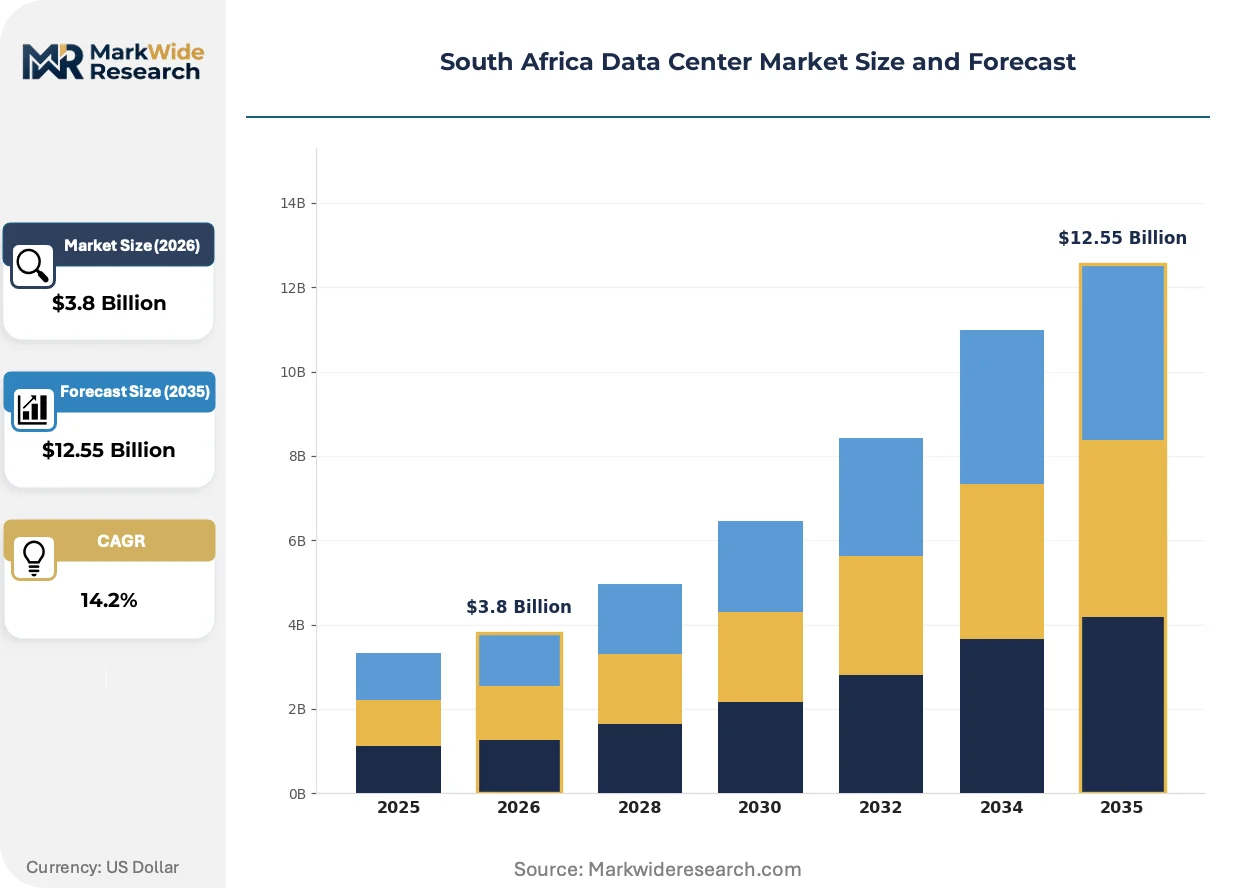
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Dedicated Servers, Cloud Services Deployment Model: On-Premise, Off-Premise, Hybrid, Multi-Cloud End User: SMEs, Large Enterprises, Government, Telecom Providers Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery |
| Companies Covered | Teraco (Digital Realty), Africa Data Centres, NTT DATA, Vantage Data Centers, Equinix, Open Access Data Centres (OADC), Digital Parks Africa, Microsoft, BCX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Market Trends and Innovations
Facility architecture is pivoting from air-cooled designs to liquid-cooled and direct-to-chip systems as power densities exceed 30kW per rack in AI training clusters.
Direct liquid cooling is absorbing heat loads from NVIDIA H100 and AMD MI300 deployments that air handlers cannot address. Hyperscale tenants in Isando and Century City are specifying DLC-ready white space in new leases. This technology is absorbing capital that previously flowed into chiller plant expansion, compressing mechanical infrastructure spend per megawatt.
The National Energy Regulator of South Africa's unbundling roadmap is enabling bilateral power contracting between generators and large consumers. Data center operators are negotiating 15-year renewable power purchase agreements with independent wind farms in the Eastern Cape. Facilities with certified green supply are capturing premium pricing from European-headquartered enterprises facing CSRD Scope 3 disclosure deadlines.
Enterprise procurement teams are consolidating vendor relationships from multi-provider sprawl toward single-campus partnerships with integrated network, compute, and compliance services. Mid-market buyers in Gauteng are abandoning managed hosting contracts for reserved capacity in hyperscale-localized regions. This concentration is most visible among fintech startups in Sandton seeking Microsoft Azure and AWS regions with POPIA-aligned data residency controls.
South Africa Data Center Market Segmentation
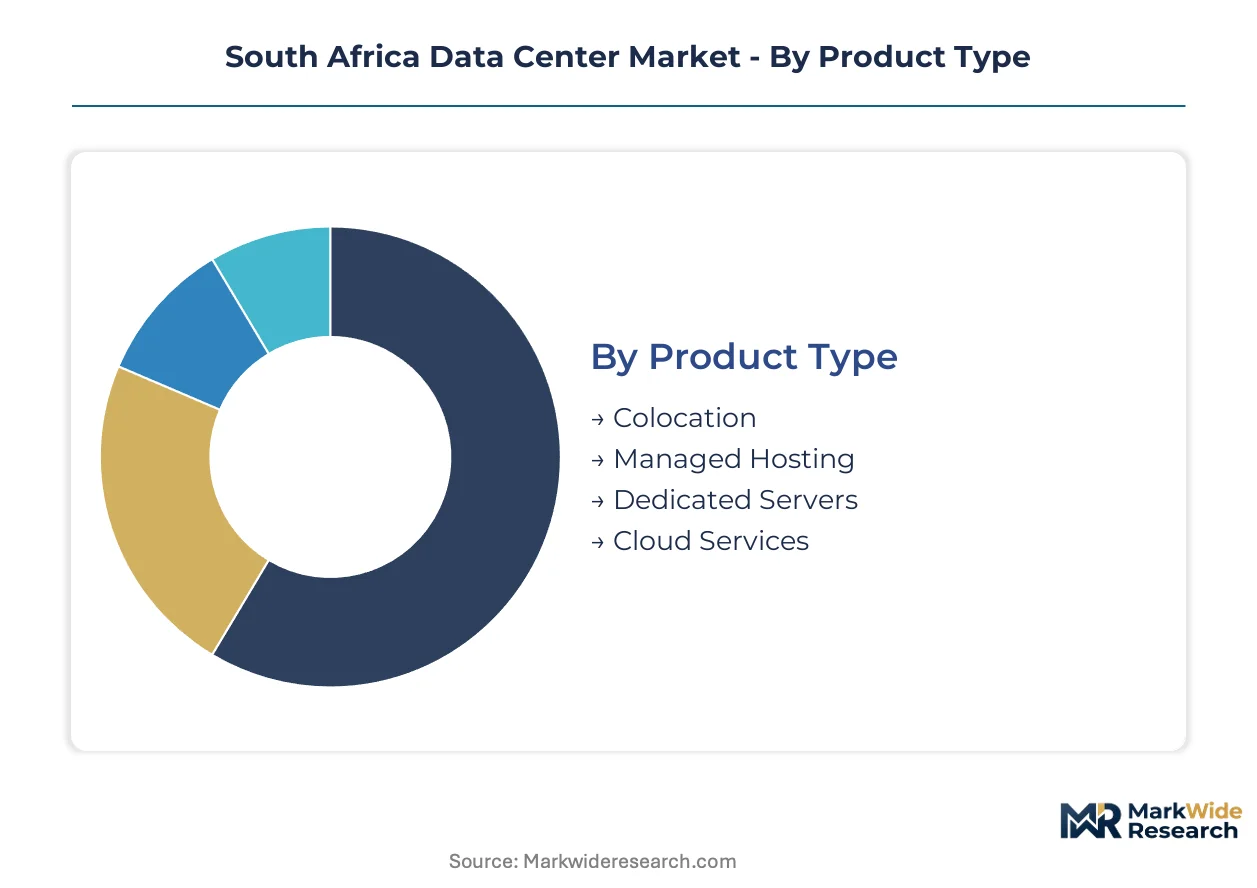
Segmentation in the South Africa data center market reveals how POPIA compliance requirements and Eskom grid constraints are reshaping procurement patterns across customer tiers and deployment architectures. Understanding these divides exposes where margin pools concentrate and which infrastructure configurations command pricing premiums.
Product Type:
Standalone facilities dominate enterprise procurement, while embedded compute services integrate into broader IT outsourcing contracts.
- Colocation:Carrier-neutral facilities provide power, cooling, and physical security for tenant-owned equipment. Financial services firms in Sandton are consolidating disaster recovery sites into Isando and Century City campuses to satisfy prudential dual-redundancy mandates.
- Cloud Services:Hyperscale regions from Microsoft Azure and AWS deliver elastic compute with POPIA-aligned data residency controls. Fintech startups in Gauteng are abandoning managed hosting for reserved capacity in these localized regions.
- Managed Hosting:Operators maintain dedicated infrastructure for single-tenant compliance workloads.
- Dedicated Servers:Bare-metal deployments serve latency-sensitive applications requiring predictable performance.
Colocation leads volumes today; cloud services is gaining share fastest.
Deployment Model:
Cost tiers separate capex-intensive ownership from opex-flexible consumption models.
- Hybrid:Blends on-premise control with off-premise elasticity through orchestrated workload placement. Enterprises in Johannesburg are deploying this architecture to keep sensitive transactional data local while bursting analytics to cloud regions.
- Multi-Cloud:Distributes workloads across AWS, Azure, and Google Cloud to mitigate vendor lock-in. Large enterprises are adopting this model to negotiate competitive pricing and ensure failover redundancy.
- On-Premise:Owned facilities retain full operational control for classified government workloads.
- Off-Premise:Third-party facilities eliminate capital burden for mid-market buyers.
Hybrid deployments anchor current infrastructure spend; multi-cloud configurations are expanding most quickly.
End User:
Customer type determines compliance burden and contract structure complexity.
- Large Enterprises:Multinationals with EU headquarters require ISO 14064 certification and Scope 3 disclosure alignment. These buyers are consolidating vendor relationships from multi-provider sprawl toward single-campus partnerships with integrated network and compliance services.
- Government:Parastatal entities operate COBOL-dependent legacy systems resisting containerization. The Department of Home Affairs and SARS maintain hybrid architectures with elevated integration costs.
- SMEs:Mid-market buyers prioritize cost predictability over customization.
- Telecom Providers:Vodacom and MTN deploy edge infrastructure for 5G core network functions.
Large enterprises dominate contract value today; government verticals are climbing the fastest amid digital transformation mandates.
Service Type:
Maturity curves separate commoditized infrastructure from value-added platform layers.
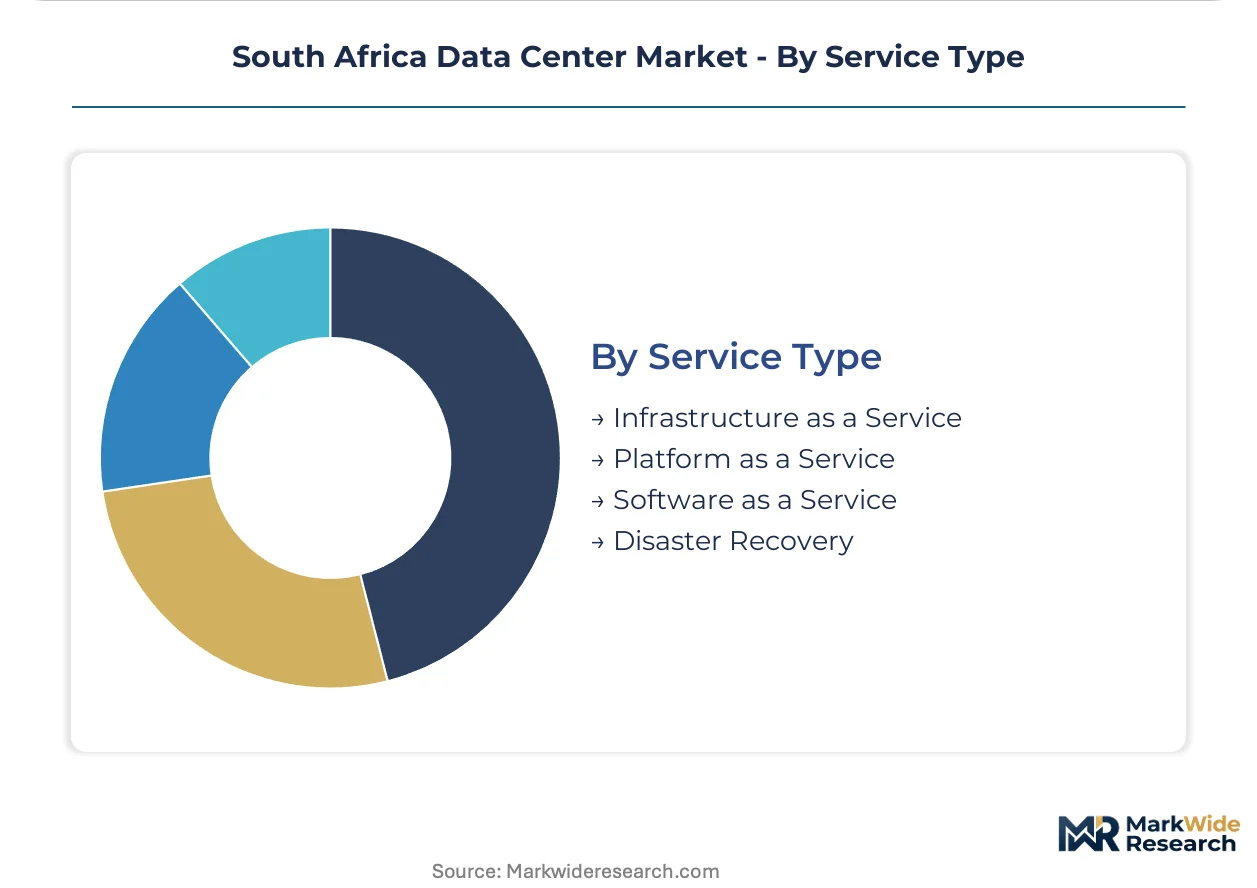
- Infrastructure as a Service:Virtualized compute, storage, and networking resources delivered on demand. Mining operations in Limpopo are consuming IaaS for predictive maintenance analytics requiring sub-10ms latency.
- Disaster Recovery:Replication and failover services ensuring business continuity under POPIA availability requirements. Banks are consolidating DR sites into certified facilities with Uptime Institute Tier III ratings.
- Platform as a Service:Managed middleware and development environments accelerating application deployment.
- Software as a Service:Application delivery models shifting operational responsibility to vendors.
Infrastructure as a Service leads current consumption; disaster recovery services show steepest expansion trajectory amid regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified data center engineers concentrate in Gauteng and Western Cape provinces, anchoring facility design capacity where fiber density and grid access intersect. This talent distribution shapes where hyperscale operators commit to multi-year buildouts.
Gauteng
Financial services clustering in Sandton and Rosebank drives demand for Tier III certified facilities with POPIA-aligned data residency controls. The National Energy Regulator of South Africa's tariff approvals shape power cost structures for Isando and Centurion campuses. Teraco's carrier-neutral facility in Isando sustains cross-border interconnection demand from banking clients.
Western Cape
Submarine cable landings at Melkbosstrand attract latency-sensitive trading workloads requiring sub-50ms European connectivity. BIS standards and local fire safety codes constrain facility design in Cape Town's constrained industrial zones. Africa Data Centres anchors expansion with direct seawater cooling access along the Atlantic seaboard.
KwaZulu-Natal
Logistics and manufacturing enterprises in Durban and Richards Bay require disaster recovery sites with dual-redundancy under prudential standards. The Independent Communications Authority of South Africa governs spectrum licensing for Mtunzini cable landing connectivity. Emerging fiber routes are reducing latency to Asian financial centers from this eastern corridor.
Eastern Cape
Wind farm developments in the Amathole district enable 15-year renewable power purchase agreements for carbon-conscious operators. Regulatory reforms permitting private power trading allow data center operators to bypass municipal distributors. Port Elizabeth's industrial zones are emerging as secondary sites for enterprises seeking green-certified hosting.
Northern Cape
Solar irradiance advantages attract renewable-powered facility concepts despite water scarcity constraining evaporative cooling deployment. Drought conditions limit greenfield site selection outside coastal-adjacent zones. Kimberley and Upington remain speculative markets pending pipeline infrastructure commitments.
South Africa Data Center Market Competitive Landscape
The competitive structure tilts toward carrier-neutral colocation specialists with established interconnection ecosystems. Facility operators differentiate through compliance certification depth rather than raw megawatt scale. Two strategic archetypes dominate: hyperscale-localized cloud regions and enterprise-focused managed hosting platforms. Competitive moves concentrate on renewable power contracting and liquid cooling infrastructure deployment.
Among South Africa-based operators, Teraco and Africa Data Centres exemplify the carrier-neutral archetype with established campus ecosystems, while NTT DATA occupies a position representing managed hosting specialization for enterprise compliance workloads. These three anchors illustrate how market positioning stratifies between interconnection density, geographic cooling advantages, and service layer integration.
| Leading Market Players |
|---|
| Teraco (Digital Realty) |
| Africa Data Centres |
| NTT DATA |
| Vantage Data Centers |
| Equinix |
| Open Access Data Centres (OADC) |
| Digital Parks Africa |
| Microsoft |
| BCX |
| Others |
Pricing and Supply Chain Analysis
Financial services firms consolidating disaster recovery sites into carrier-neutral campuses anchor pricing power with hyperscale operators. These buyers negotiate long-term reserved capacity contracts that compress margins for mid-tier colocation providers lacking Tier III certification or renewable power purchase agreements.
Pricing Analysis
Bundled infrastructure-as-a-service offerings with integrated compliance certification command 20-40% premiums over unbundled rack-and-power arrangements. Price differentiation rests on Uptime Institute tier rating and POPIA audit certification status. Cost compression in standard colocation is intensifying because diesel generator run costs from Eskom grid instability are eroding operator margins. SMEs exhibit highest price sensitivity, while EU-headquartered multinationals absorb green-certified hosting premiums to satisfy CSRD disclosure requirements.
Supply Chain Analysis
Domestic-content mandates under South Africa's local procurement frameworks are reshaping sourcing for electrical switchgear and cooling infrastructure. Manufacturing concentrates in Germany, China, and the United States for specialized heat exchangers and coolant distribution units. Data center construction draws from imported precision cooling equipment, domestic cement and steel, and regional fiber cable supplies. Single-source vulnerability in liquid cooling componentry extends procurement lead times. Distribution runs through engineering-procurement-construction contractors with direct operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Africa data center market functions as a regulatory compounder where POPIA data localization mandates continuously expand addressable demand for certified domestic facilities.
For Market Incumbents: Deploy renewable power purchase agreement contracting as a defensive moat. Operators should secure 15-year wind and solar supply from Eastern Cape independent generators before bilateral trading reforms saturate premium offtake. Carrier-neutral campuses must expand liquid-cooling-ready white space to capture NVIDIA H100 and AMD MI300 deployment demand from AI training clusters. Certification investment in ISO 14064 carbon accounting protects margin pools against EU-facing exporter procurement criteria. For New Entrants and Emerging Players: Liquid-cooled edge micro-data centers present a technology-first wedge into underpenetrated mining and logistics corridors. Limpopo and Mpumalanga autonomous vehicle coordination workloads require sub-10ms latency that centralized campuses cannot deliver. The most penetrable segment comprises mid-market mining operators abandoning on-premise server rooms for managed infrastructure-as-a-service. A channel partnership model with industrial automation distributors accelerates customer acquisition without direct enterprise sales overhead. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking localized region capacity to satisfy data residency requirements. Long-term viability hinges on facilities with secured grid alternatives and coastal cooling access. Acquisition targets should display certified compliance architectures, established interconnection ecosystems, and contracted renewable supply. The signal to watch is NERSA unbundling roadmap implementation pace, which determines bilateral power trading availability for new capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | 15-year wind contracts from Eastern Cape generators bypass Eskom tariff volatility and attract EU-headquartered enterprise demand. |
| Liquid Cooling Infrastructure Deployment | Direct-to-chip systems absorb NVIDIA H100 heat loads that air handlers cannot address in AI training clusters. |
| POPIA Compliance Certification Investment | ISO 27001 and POPIA audit status unlocks financial services procurement mandates in Sandton and Rosebank. |
| Carrier-Neutral Interconnection Expansion | Cross-border fiber access at Isando sustains banking client demand for dual-redundancy architectures. |
| Edge Micro-Data Center Buildout | Sub-10ms latency infrastructure in Limpopo serves mining predictive maintenance and autonomous vehicle coordination workloads. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged data center operators, financial services IT infrastructure directors, NERSA regulatory affairs specialists, and renewable energy project developers. Secondary validation drew from ICASA spectrum licensing records, Eskom tariff filing documents, submarine cable landing registry data, and Uptime Institute certification databases. Bottom-up facility capacity tracking and top-down sectoral IT spend analysis were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across deployment models and end-user verticals. The analytical framework modeled colocation, cloud services, managed hosting, and dedicated server product types alongside hybrid, multi-cloud, on-premise, and off-premise deployment architectures. Large enterprise, government, SME, and telecom provider end-user categories were separately projected. CAGRs were derived from capacity expansion announcements, power purchase agreement disclosures, and POPIA compliance audit trajectories. Eskom grid stability commitments and renewable PPA availability shaped facility-level buildout assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NERSA unbundling implementation, ICASA spectrum allocation timing, and Eastern Cape wind farm commissioning schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Long Term Data Retention Solutions Market