
 Africa Crop Protection Chemicals Market | 2026-2036
Africa Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Crop Protection Chemicals Market Outlook
The EU Green Deal's Farm to Fork pesticide reduction targets is restructuring import standards for African agricultural exports, forcing supply chain upgrades across the continent. Bayer AG leverages its herbicide seed treatment portfolio to sustain contract grower loyalty in South Africa's maize belt. Syngenta Group anchors its position through distributor networks spanning Kenya and Tanzania, while ADAMA Agricultural Solutions Ltd competes on price in Nigeria's fragmented cotton and soybean sectors.
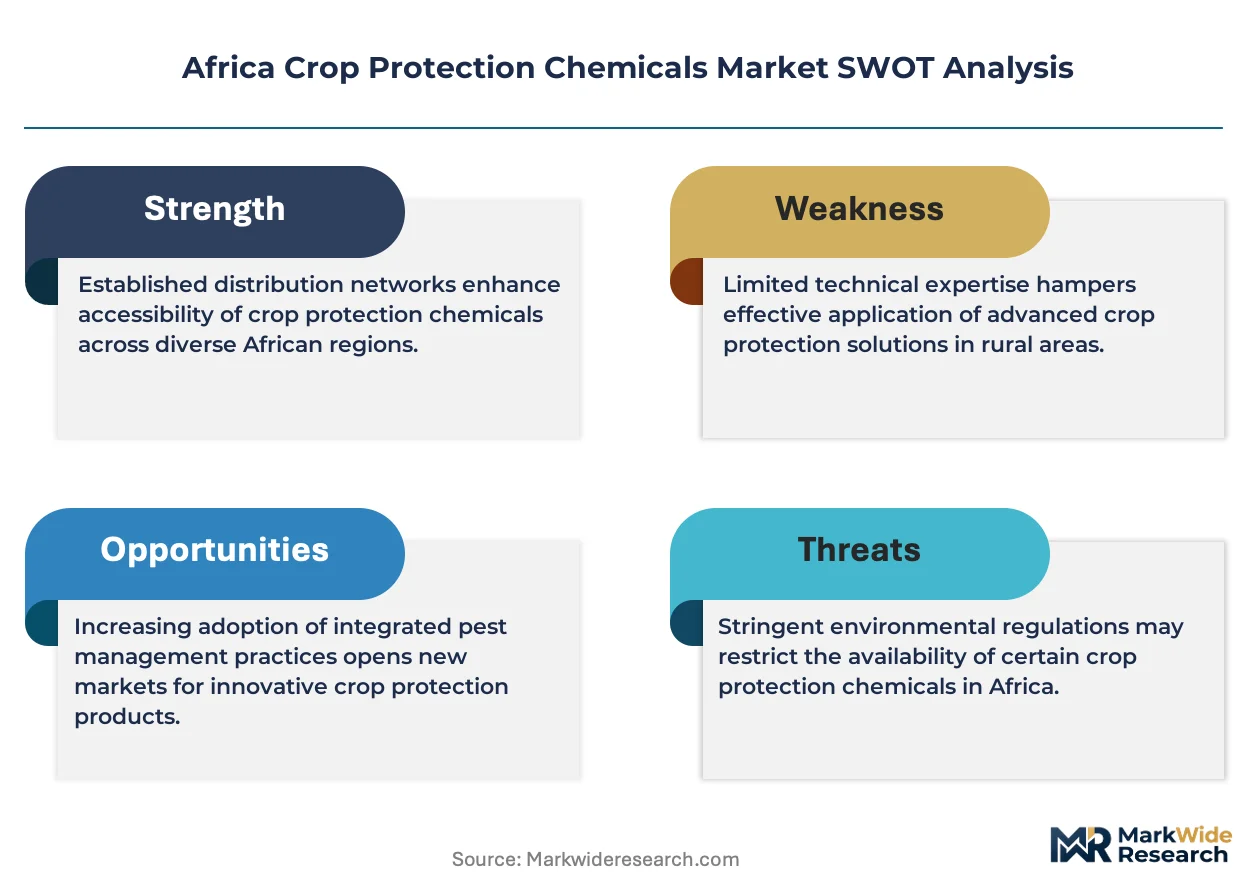
Africa crop protection chemicals encompass synthetic and biological formulations designed to control weeds, insects, fungi, and rodents in agricultural systems, typically containing active ingredients such as glyphosate, pyrethroids, or azoles formulated into emulsifiable concentrates or wettable powders for foliar or soil application. These agents serve to preserve yield potential and quality in commercial and subsistence farming operations where pest pressure causes substantial pre-harvest losses. Herbicides capture the largest value share across the product type dimension due to labor cost escalation and mechanization trends displacing manual weeding. The fruits and vegetables application segment generates premium pricing as export-oriented growers in Kenya, Ethiopia, and Morocco require residue-compliant fungicide and insecticide programs to access European retail channels.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces registration under the Fertilizers, Farm Feeds, Seeds and Remedies Act, while Kenya's Pest Control Products Board governs import licensing and residue monitoring for horticultural exports. Nigeria's National Agency for Food and Drug Administration and Control intersects with agricultural chemical oversight through counterfeit product seizures and quality certification requirements. Stakeholders must monitor evolving maximum residue limits in destination markets and pre-position biological alternatives ahead of anticipated regulatory phase-outs of key synthetic actives.
Market Dynamics
EU Green Deal pesticide reduction mandates are restructuring residue compliance requirements across African export supply chains, forcing formulation upgrades and biological alternative pre-positioning ahead of synthetic active phase-outs.
Growth Catalysts
- Herbicide mechanization:Labor cost escalation across Nigeria's cereal belt and Kenya's highland zones is displacing manual weeding with glyphosate-based programs, accelerating product turnover in smallholder channels.
- EU MRL alignment pressure:Export-oriented vegetable growers in Ethiopia and Morocco face tightening maximum residue limits under Farm to Fork targets, requiring upgraded fungicide and insecticide rotations for European retail access.
- Climate-intensified weed pressure:Erratic rainfall patterns across East African highlands are extending weed germination windows, expanding treatment frequency and volume demand among contract farming operations.
Market Restraints
- Active ingredient registration friction:South Africa's revised Fertilizers, Farm Feeds, Seeds and Remedies Act is extending approval timelines for novel chemistries, delaying commercialization of lower-toxicity replacements.
- Input cost volatility:Petrochemical feedstock price swings directly impact pyrethroid and azole production economics, compressing margin stability for formulators serving price-sensitive Nigerian cotton growers.
- Counterfeit product infiltration:Nigeria's National Agency for Food and Drug Administration and Control seizure data reveals substantial adulterated glyphosate volumes, eroding trust in distributor channels and triggering premature resistance development.
Strategic Opportunities
- Biological formulation white space:Anticipated regulatory phase-outs of key synthetic actives under EU Green Deal timelines create first-mover advantage for microbial biopesticide developers targeting Kenya's horticultural export belt.
- Seed treatment bundling:Maize belt growers in South Africa demonstrate willingness to pay premium for herbicide-treated seed packages, opening integrated product-service models that lock in seasonal chemical volumes.
- Digital extension networks:Mobile-based agronomic advisory platforms are penetrating Tanzania's fragmented cotton sector, creating direct-to-farmer channels that bypass traditional distributor markups.
Industry Challenges
- Residue monitoring infrastructure gaps:Kenya's Pest Control Products Board lacks sufficient field testing capacity to enforce MRL compliance across dispersed smallholder plots, exposing exporters to border rejection risk.
- Resistance management expertise scarcity:Integrated pest management training remains underdeveloped among extension officers serving Nigeria's soybean belt, accelerating herbicide rotation failures and yield loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Crop Protection Chemicals Market |
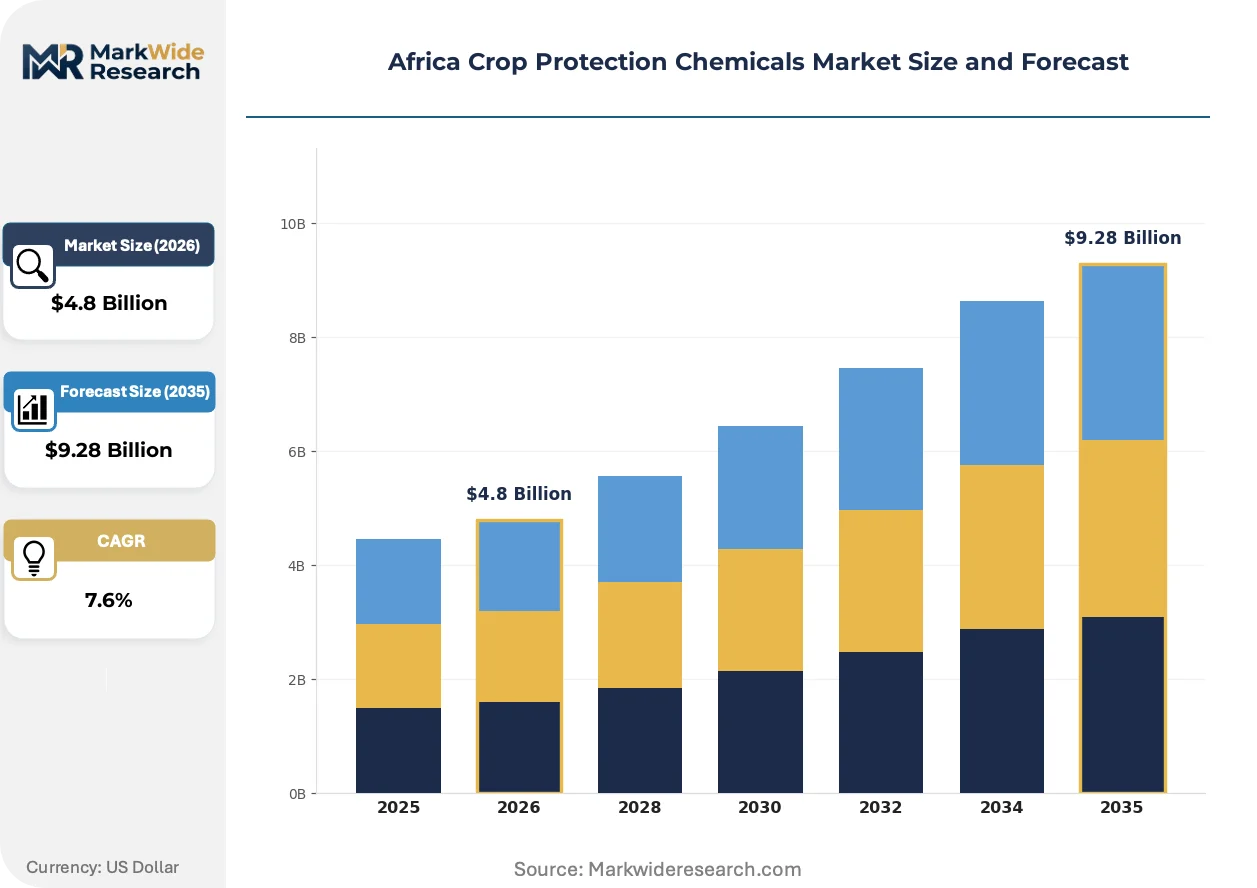
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Cereals, Fruits, Vegetables, Oilseeds End User: Agricultural Producers, Cooperatives, Distributors, Retailers Formulation: Emulsifiable Concentrates, Wettable Powders, Granules, Soluble Powders |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, FMC Corporation, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical Co., Ltd., UPL Limited, Nufarm Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Crop Protection Chemicals Market Strategic Shifts
Biological-synthetic formulation hybrids and precision application technologies are converging to reduce chemical load per hectare while maintaining export-compliant residue profiles across African high-value cropping systems.
RNA interference-based biopesticides are integrating into integrated pest management protocols for fall armyworm control in East African maize systems. South African contract growers are piloting these formulations at limited commercial scale. The technology is integrating with existing spray service provider networks, compressing adoption timelines for novel modes of action.
Kenya's Pest Control Products Board is accelerating residue monitoring protocol updates to align with EU Green Deal maximum residue limit reductions. This regulatory tightening is forcing fungicide program redesigns among Ethiopian flower exporters. High-value vegetable operations in Morocco are responding by pre-certifying biological alternatives under organic equivalency standards.
Aggregated procurement through farmer cooperatives is consolidating chemical purchasing power across Tanzania's cotton belt. Traditional village-level stockists are losing volume to warehouse receipt system-linked input suppliers. This channel restructuring is most visible in Kenya's highland vegetable clusters where export contract requirements drive quality-assured product specification.
Africa Crop Protection Chemicals Market Segmentation
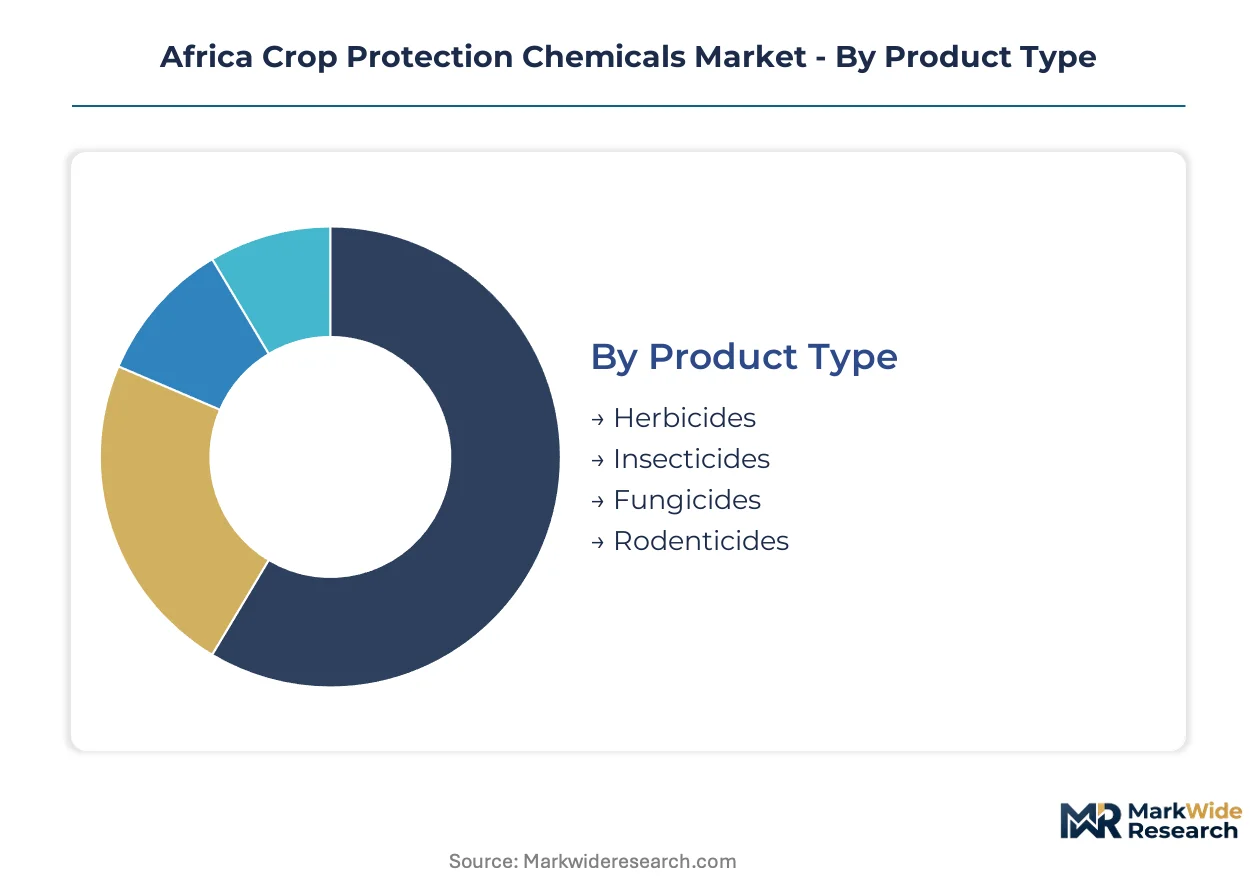
Crop protection chemical suppliers structure portfolios around four intersecting dimensions that determine pricing power, regulatory exposure, and channel access across African agricultural markets. Understanding these segment boundaries reveals where formulation investments concentrate and which customer relationships command premium positioning.
Product Type:
Active ingredient chemistry defines efficacy profiles, resistance risk, and regulatory scrutiny trajectories across African farming systems.
- Herbicides:Glyphosate-based formulations dominate volume through broad-spectrum weed control in mechanized cereal operations. Nigeria's smallholder maize belt and Kenya's highland wheat zones are expanding adoption as labor costs displace manual weeding. Resistance management protocols remain underdeveloped among extension networks.
- Insecticides:Pyrethroid and neonicotinoid chemistries target fall armyworm and aphid pressure in vegetable export corridors. Ethiopian flower growers and Moroccan tomato operations require residue-compliant rotations under EU MRL tightening. RNA interference biopesticides are entering limited commercial pilots.
- Fungicides:Azole and strobilurin formulations protect high-value horticulture from downy mildew and botrytis in humid highland climates.
- Rodenticides:Anticoagulant baits secure stored grain in East African warehouse receipt systems.
Herbicides lead on scale; insecticides lead on momentum as biopesticide alternatives accelerate.
Application:
Crop-specific pest pressure and export certification requirements create divergent formulation specifications and service intensity levels.
- Cereals:Maize and wheat operations in South Africa's commercial belt and Nigeria's northern zones drive herbicide volume through pre-emergence and post-emergence programs. Climate-intensified weed germination windows are extending treatment frequency.
- Fruits:Citrus and grape operations in Western Cape and Northern Cape provinces require integrated disease management with strict residue monitoring for European retail access. Fungicide rotations face EFSA MRL alignment pressure.
- Vegetables:French bean and snow pea exporters in Kenya's highlands and Ethiopia's Rift Valley face the steepest compliance burden under EU Green Deal residue reductions.
- Oilseeds:Soybean and cotton growers in Nigeria's Kaduna belt and Tanzania's lake zone compete on input cost minimization.
Cereals dominate volume throughput; vegetables command the steepest price premiums.
End User:
Purchasing scale and technical sophistication determine service model economics and credit risk profiles across distribution tiers.
- Agricultural Producers:Commercial farming operations in South Africa's maize belt and Zambia's copperbelt coordinate direct procurement with technical advisory bundling. These relationships anchor seasonal volume commitments and resistance management protocol adoption.
- Cooperatives:Aggregated buying groups in Kenya's highland vegetable clusters and Tanzania's cotton cooperatives are consolidating purchasing power through warehouse receipt system linkages. Quality-assured specifications are displacing village stockists.
- Distributors:National and regional wholesalers manage import licensing, inventory financing, and extension service networks across fragmented last-mile channels.
- Retailers:Agro-dealer shops serve cash-constrained smallholders with split-pack sizing and informal credit terms.
Producers concentrate value capture; cooperatives are gaining procurement leverage fastest.
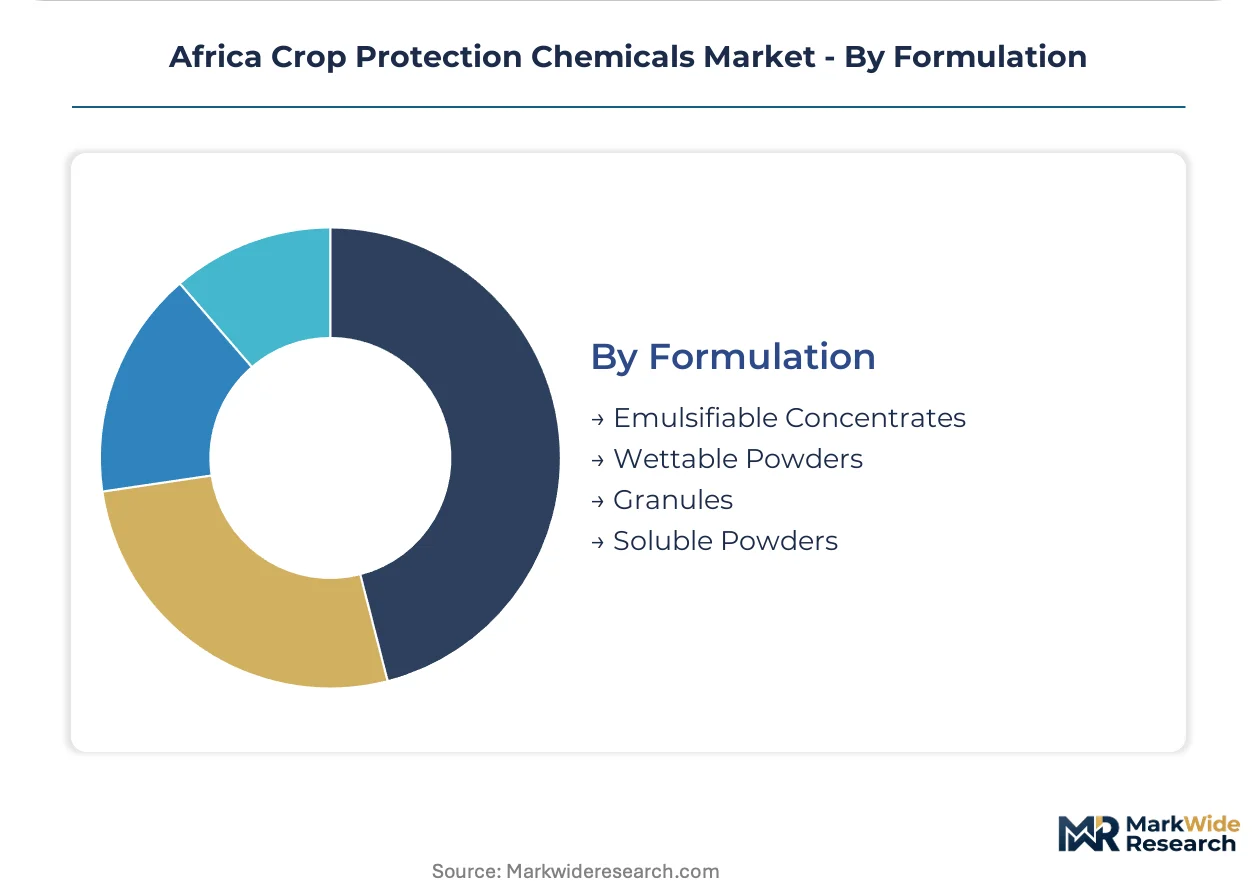
Formulation:
Physical delivery systems determine application equipment compatibility, shelf stability, and active ingredient bioavailability under African storage conditions.
- Emulsifiable Concentrates:Oil-based liquid formulations dissolve lipophilic actives for foliar penetration in high-value horticulture. Kenyan flower exporters and Moroccan tomato growers specify these for uniform coverage and residue control precision.
- Wettable Powders:Solid concentrates reconstitute into spray suspensions for broad-acre cereal applications. South African contract maize growers favor these for tank-mix flexibility and transport efficiency.
- Granules:Controlled-release matrices enable soil-incorporated application in pre-planting windows with reduced drift exposure.
- Soluble Powders:Water-dissolvable formulations suit smallholder backpack sprayer operations with limited mixing equipment.
Emulsifiable concentrates command premium positioning; wettable powders dominate volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa pioneered commercial-scale crop protection distribution across sub-Saharan Africa, establishing formulation plants and regulatory frameworks that neighboring markets later adopted. This historical foundation shapes current competitive dynamics as multinational suppliers anchor regional operations in Johannesburg and Cape Town corridors.
South Africa
Mechanized maize operations in the Free State and Mpumalanga drive herbicide volume through precision application programs. The Department of Agriculture, Land Reform and Rural Development enforces registration under the revised Fertilizers, Farm Feeds, Seeds and Remedies Act, extending approval timelines for novel chemistries. Cape Town's warehousing clusters concentrate import logistics for re-export into SADC markets.
Nigeria
Smallholder cereal farmers in Kaduna and Kano states are expanding glyphosate adoption as labor costs displace manual weeding. The National Agency for Food and Drug Administration and Control intersects with oversight through counterfeit product seizures and quality certification requirements. Lagos port complexes handle bulk formulation imports for northern distribution networks.
Kenya
Highland vegetable exporters in Kiambu and Nakuru counties face tightening EU MRL compliance pressure under Farm to Fork timelines. The Pest Control Products Board governs import licensing and residue monitoring for horticultural shipments. Nairobi's agrochemical trading hubs coordinate quality-assured procurement for cooperative buying groups.
Ethiopia
Flower and vegetable operations in the Rift Valley require upgraded fungicide rotations for European retail access. The country's national agricultural regulator maintains equivalence protocols with EU standards. Addis Ababa's cargo terminals link cold-chain logistics to Middle Eastern and European destinations.
Morocco
Tomato and citrus growers in the Souss-Massa region pre-certify biological alternatives under organic equivalency standards. The country's national food safety authority aligns residue monitoring with EFSA requirements. Agadir's port infrastructure supports year-round export scheduling to continental European markets.
Africa Crop Protection Chemicals Market Competitive Environment
Capital-heavy integrated manufacturers compete with asset-light formulation specialists across African agricultural input channels. The supplier base concentrates around multinational agrochemical conglomerates with established registration portfolios and distributor financing capabilities. Three archetypes dominate: integrated innovators with seed-chemical bundling platforms, generic-focused formulators competing on price in fragmented cotton and soybean sectors, and biological specialists pre-positioning microbial alternatives ahead of synthetic phase-outs. Competitive moves center on distributor network consolidation and biological portfolio expansion.
Among integrated innovators, Bayer AG and Syngenta Group exemplify the seed-treatment bundling archetype that locks in seasonal chemical volumes with commercial growers. ADAMA Agricultural Solutions Ltd occupies a position within the generic-focused tier, competing on price in Nigeria's fragmented cotton and soybean channels. These three anchors represent distinct strategic postures without exhausting the competitive map.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical Co., Ltd. |
| UPL Limited |
| Nufarm Limited |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap formulators across Kenya and Tanzania anchor regional supply networks while exercising disciplined margin management against multinational pricing benchmarks. Their localized blending operations compress working capital cycles and enable responsive pricing to smallholder cash-flow patterns.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. Premium tiers capture EU MRL-compliant formulations for Kenyan vegetable exporters, while economy tiers serve Nigerian cotton growers with generic glyphosate. Cost compression in the economy tier is intensifying because petrochemical feedstock volatility erodes formulator margins. Agricultural cooperatives demonstrate the highest price sensitivity, whereas South African commercial maize operations accept premium positioning for bundled seed-treatment programs.
Supply Chain Analysis
Active ingredient supply rests on Chinese and Indian specialty chemical producers for pyrethroid and azole intermediates, with formulation finishing concentrated in South Africa and Nigeria. Glyphosate technical grade and neonicotinoid precursors constitute critical input dependencies. Single-source vulnerability from concentrated Chinese intermediate production exposes African formulators to tariff and logistics disruption. Distribution runs through national wholesalers managing import licensing and inventory financing, with last-mile penetration via agro-dealer networks and emerging mobile-enabled direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa crop protection chemicals market functions as a stable compounder, underpinned by irreversible labor cost escalation that permanently displaces manual weeding across Nigeria's cereal belt.
For Market Incumbents: Deepen backward integration into active ingredient sourcing to buffer petrochemical volatility and secure registration continuity under South Africa's revised Fertilizers Act. Lock in cooperative procurement relationships through warehouse receipt system linkages before generic competitors consolidate Tanzania's cotton belt. Prioritize biological formulation pipelines to pre-position alternatives ahead of EU Green Deal synthetic phase-outs. For New Entrants and Emerging Players: The gap between premium residue-compliant formulations and economy generic pricing opens white-space targeting of mid-tier Kenyan horticultural cooperatives seeking MRL alignment without full organic certification. Nigeria's fragmented soybean sector offers penetrable volume through mobile-enabled direct-to-farmer advisory bundling. Enter via digital extension partnerships that bypass traditional distributor markups and capture farmer transaction data. For Investors and Strategic Acquirers: Valuations sit cheapest among generic-focused formulators with established Nigerian distribution footprints but underdeveloped biological portfolios. Five-to-ten-year viability hinges on regulatory navigation capability and channel control depth. Monitor EU MRL reduction announcements as the critical inflection signal for biological alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Portfolio Expansion | Microbial biopesticide development secures positioning ahead of EU Green Deal synthetic active phase-outs in Kenyan export corridors. |
| Seed Treatment Bundling | Integrated herbicide-treated seed packages lock in seasonal chemical volumes with South African commercial maize growers. |
| Digital Extension Network Deployment | Mobile-based agronomic advisory platforms create direct-to-farmer channels that disintermediate traditional distributor markups in Tanzania. |
| Cooperative Procurement Consolidation | Warehouse receipt system linkages aggregate smallholder buying power and displace village-level stockists across Kenya's highland clusters. |
| Regulatory Pre-Positioning | Early registration of lower-toxicity formulations under South Africa's revised Act accelerates commercialization timelines versus delayed entrants. |
Study Parameters
Bottom-up smallholder and commercial farm modeling reconciled against top-down import and formulation tracking forms the analytical core of this study. Primary interviews with agrochemical distribution managers, cooperative procurement officers, regulatory affairs leads at formulators, and extension service coordinators combined with secondary validation from customs trade records, national regulator seizure data, and SEC filings of listed suppliers. Triangulation across these sources ensures demand-side estimates align with supply-side shipment volumes.
Historical trendline analysis of active ingredient import volumes and treatment frequency patterns anchors the projection framework across the analysis window. Segmentation dimensions span product chemistry, crop application, end-user scale, and formulation type, with regional regulatory clusters modeled separately. CAGRs derive from fitted growth curves adjusted for policy inflection points and climate variability impacts on pest pressure cycles.
Caveats apply where EU MRL acceleration, active ingredient registration delays, or counterfeit product infiltration could materially shift the outlook. Forecasts reflect assumptions about regulatory continuity and cooperative consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Fungicide Market
Crop Protection
US Pest Control Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Crop Bactericides Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
North America Insecticide Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Dicamba Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Tembotrione Market
Crop Protection
Captan Fungicide Market
Crop Protection
Specialty Pesticides Market