
 Self-Driving Shuttle Market | 2026-2036
Self-Driving Shuttle Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Shuttle Market Insights
ISO 26262 functional safety certification is collapsing the supplier base to a handful of qualified platform builders. Waymo LLC leverages its layered sensor fusion architecture to sustain deployment velocity across Arizona and California test corridors. Navya SAS anchors European demand through manufacturing scale at its French facility, while EasyMile SAS differentiates via dedicated campus and airport transit specialization.
A self-driving shuttle is a battery-electric, low-speed automated vehicle typically operating at 15-25 mph, integrating LIDAR arrays, redundant braking systems, and V2X communication modules to transport passengers along predetermined or dynamically optimized routes without human intervention. Compact shuttles dominate current deployment counts due to lower unit costs and simpler regulatory pathways, though cargo shuttles represent the fastest-expanding segment as last-mile logistics operators seek to eliminate driver costs. Fixed-route service models command the majority of operational revenue today, while on-demand configurations capture disproportionate R&D investment because they promise higher utilization rates and fare-box recovery.
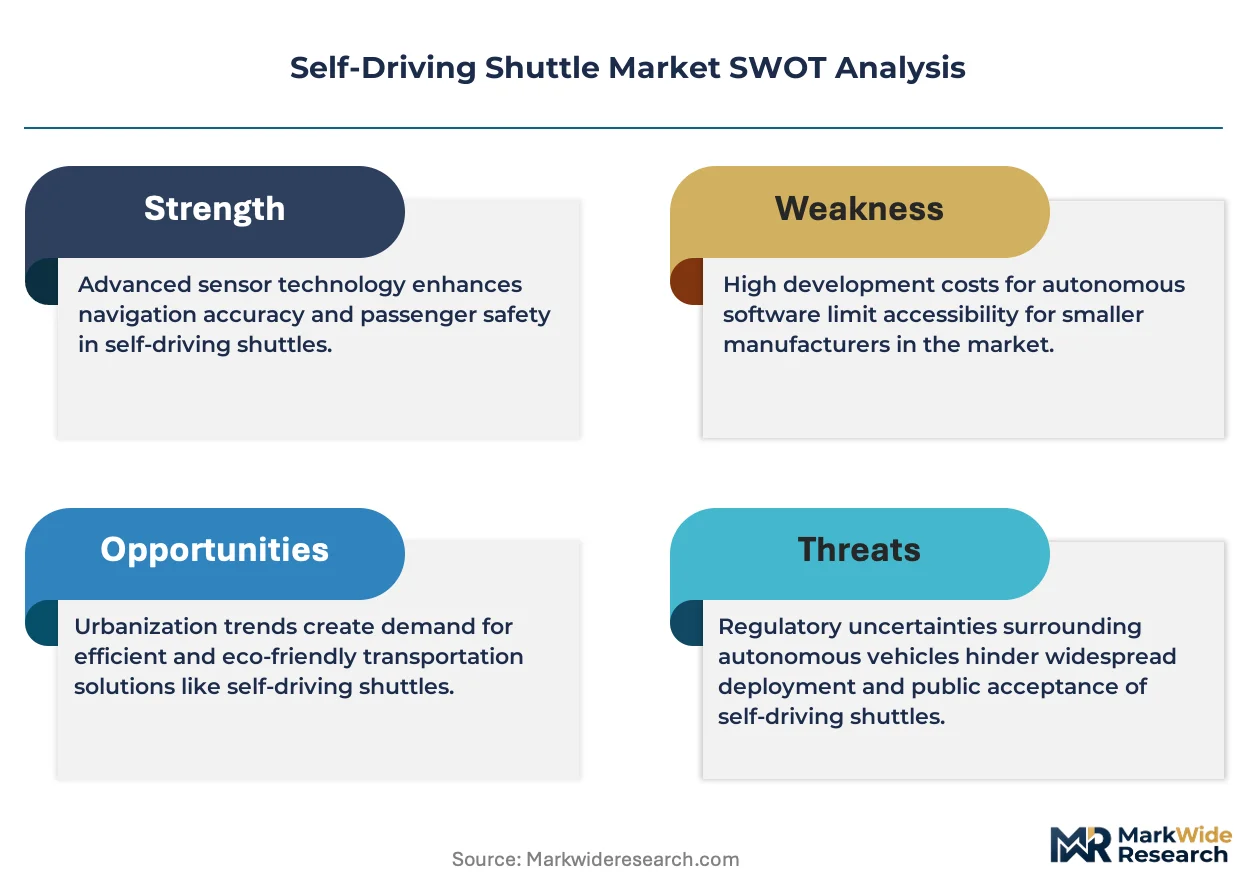
NHTSA in the United States, Germany's KBA, and Japan's METI each enforce divergent testing disclosure and operator liability frameworks that fragment platform certification costs across jurisdictions. The EU AI Act adds algorithmic transparency requirements that directly shape supplier selection for European public transport tenders. Stakeholders must track which regulatory body moves first on unified cross-border type approval, as that decision will concentrate procurement budgets and manufacturing investment in the corresponding geography.
Market Dynamics
ISO 26262 functional safety certification is collapsing the supplier base to a handful of qualified platform builders, concentrating procurement power among fleet operators who can enforce multi-year service agreements.
Growth Catalysts
- Campus fleet expansion:North American universities are scaling pilot programs under revised NHTSA automated vehicle guidance, creating repeatable deployment templates for controlled environments.
- Dedicated infrastructure deployment:Munich and Hamburg have opened autonomous shuttle lanes on public roads, demonstrating regulatory willingness to allocate street-level priority to automated services.
- Last-mile logistics substitution:Cargo shuttle demand from parcel operators is accelerating as driver cost elimination becomes a procurement mandate rather than an efficiency target.
Market Restraints
- LIDAR sensor cost concentration:Solid-state and mechanical LIDAR arrays constitute 35-45% of unit manufacturing costs, with supply constrained by semiconductor foundry allocation.
- Cross-border certification fragmentation:NHTSA, Germany's KBA, and Japan's METI enforce divergent testing disclosure frameworks that multiply platform validation expenses.
- Fixed-route revenue ceiling:Predetermined route service models limit utilization rates compared to dynamic on-demand alternatives, compressing fare-box recovery potential.
Strategic Opportunities
- EU AI Act algorithmic transparency:European public transport tenders now require explainable decision-making systems, favoring suppliers with documented sensor fusion architectures.
- Airport ground transportation integration:EasyMile SAS has demonstrated campus-to-terminal connectivity, opening procurement channels at hub airports seeking to reduce bus fleet labor costs.
- V2X communication module convergence:Integration of vehicle-to-infrastructure protocols with 5G network slicing is enabling real-time traffic priority negotiation in urban cores.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification expertise resides with fewer than two dozen engineering consultancies worldwide, extending development timelines.
- Legacy transit system integration:Municipal operators require API compatibility with existing payment and dispatch platforms, forcing redundant middleware development.
- Operator liability ambiguity:Cross-jurisdictional gaps in accident responsibility allocation between platform builders and fleet operators delay insurance product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Shuttle Market |
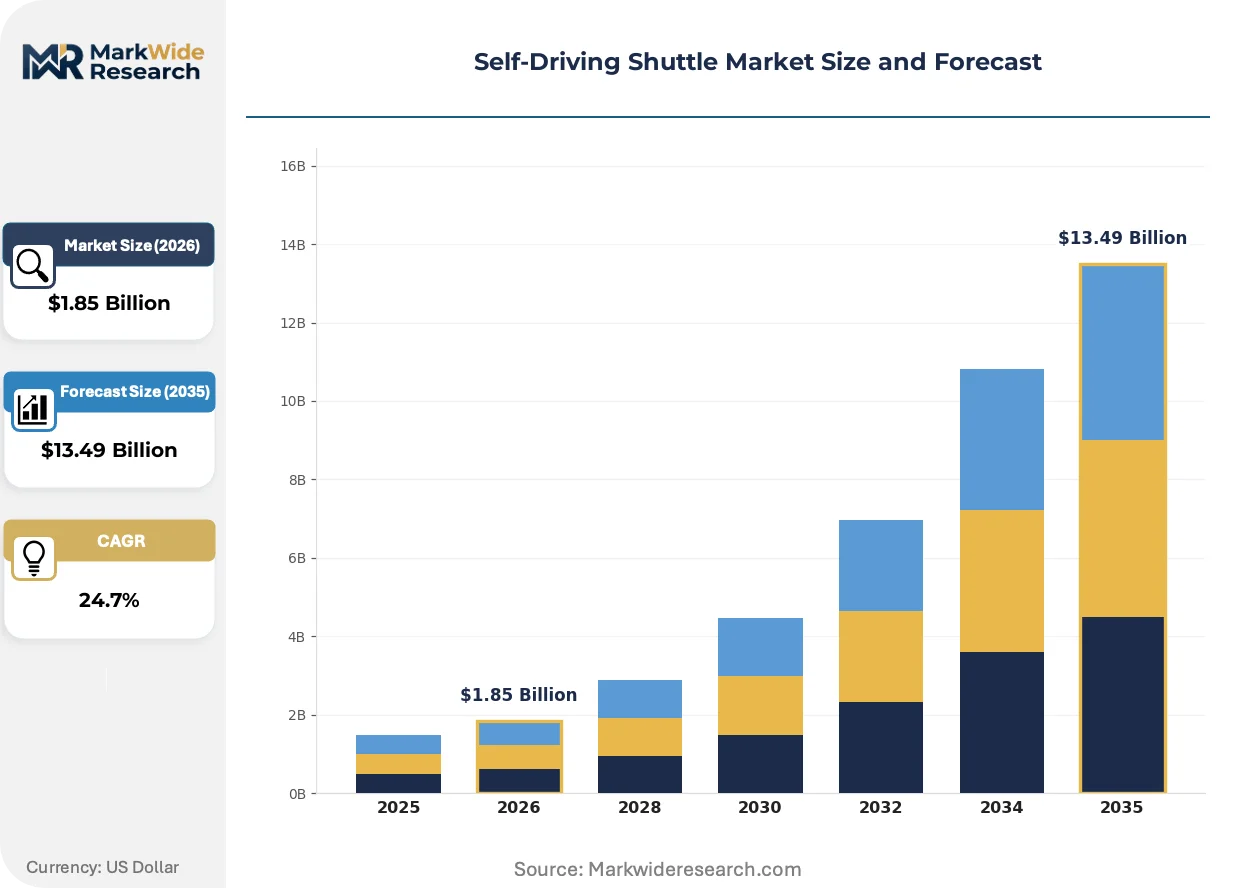
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $13.49 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Compact Shuttle, Mini Shuttle, Full-Size Shuttle, Cargo Shuttle End User: Public Transport, Campus Services, Airport Transit, Corporate Shuttle Technology: LIDAR, Computer Vision, GPS Navigation, AI Systems Service Model: On-Demand, Fixed Route, Subscription-Based, Hybrid Model |
| Companies Covered | EasyMile SAS, Navya SAS, May Mobility Inc., Zoox Inc., Waymo LLC, Nuro Inc., Beep Inc., WeRide Inc., Pony.AI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Shuttle Market Trends and Innovations
Sensor fusion architectures are actively reshaping competitive differentiation, with layered perception systems replacing single-modality approaches as the baseline for urban deployment.
LIDAR-camera-radar sensor fusion is fragmenting procurement patterns across fleet operators. Tier-1 automotive suppliers are integrating these stacks into modular shuttle platforms, while specialized autonomy vendors defend position through software-only licensing. The resulting bifurcation is compressing margins for hardware-agnostic middleware providers who lack captive sensor supply.
Germany's KBA has mandated standardized incident data recorders for all public-road automated shuttle tests, forcing platform builders to re-engineer black-box architectures for European type approval. This regulatory pressure is accelerating adoption of deterministic logging systems that satisfy both KBA disclosure requirements and EU AI Act audit trails. Suppliers without pre-certified data governance frameworks are exiting German municipal tenders.
Universities and corporate campuses are consolidating shuttle procurement under centralized mobility-as-a-service contracts, displacing discrete vehicle purchases. Facility managers now demand utilization guarantees and uptime penalties rather than capital expenditure approvals. This purchasing transformation is most advanced in Arizona and California, where test corridor operators have normalized performance-based service agreements with shuttle platform vendors.
Self-Driving Shuttle Market Segmentation
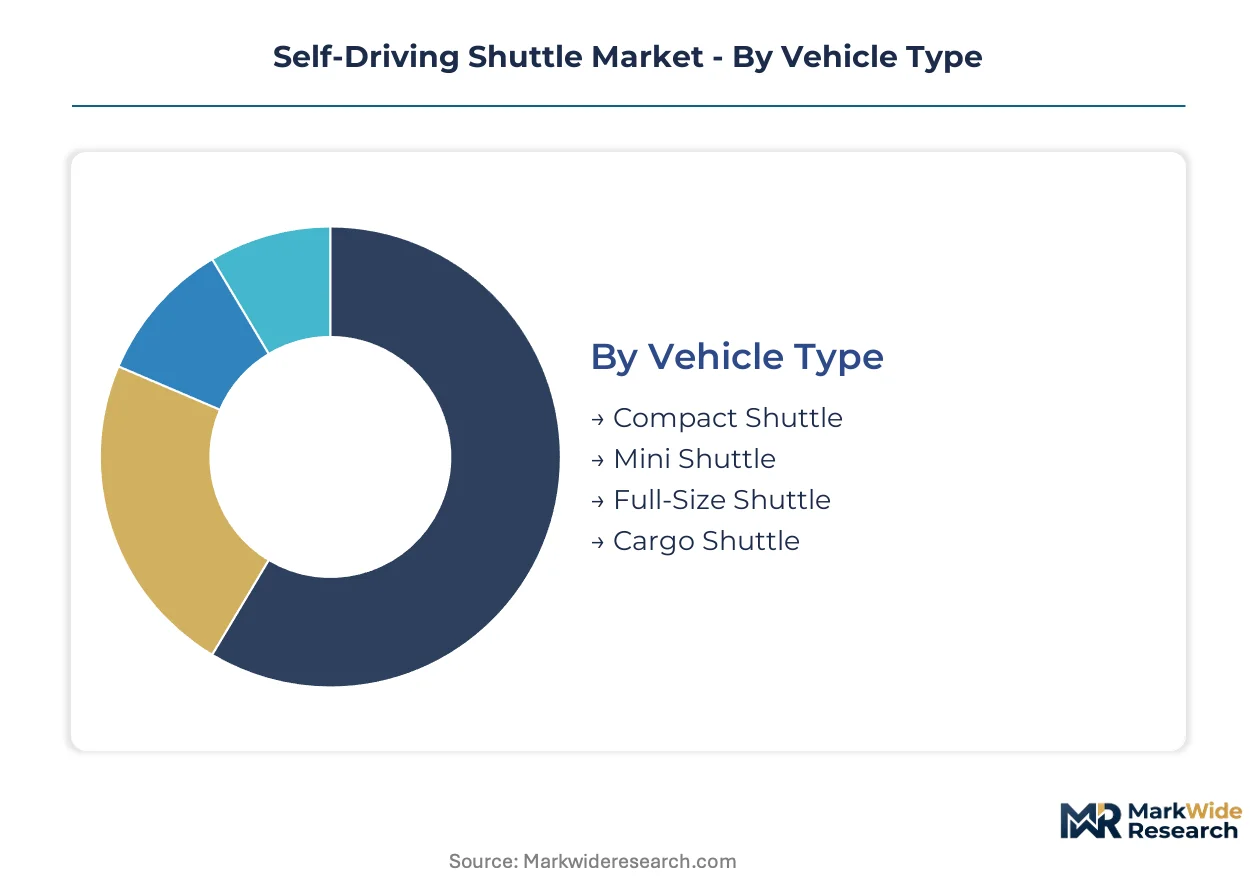
Self-driving shuttle procurement patterns diverge sharply across vehicle configurations, operational contexts, and technology stacks. Fleet operators select segments based on regulatory pathway complexity, infrastructure readiness, and labor cost elimination potential rather than unit economics alone.
Vehicle Type:
Compact shuttles flow predominantly through campus services and airport transit channels where speed restrictions and controlled access simplify deployment. Full-size variants concentrate in public transport tenders requiring higher passenger throughput.
- Compact Shuttle:Battery-electric platforms operating at 15-25 mph with simplified sensor arrays. Campus services operators across Arizona and California favor these units for controlled-environment deployment under revised NHTSA guidance.
- Cargo Shuttle:Automated parcel carriers eliminating driver costs in last-mile logistics networks. Parcel operators in Germany and Japan are accelerating procurement as labor reduction becomes a procurement mandate rather than efficiency target.
- Mini Shuttle:Mid-capacity platforms bridging passenger and utility applications. Corporate shuttle programs in Munich and Hamburg leverage these for dedicated autonomous lane operations.
- Full-Size Shuttle:Higher-capacity units requiring extended sensor fusion ranges and redundant braking architectures. Municipal operators in France and Germany specify these for trunk-route replacement.
By volume, Compact Shuttle leads. By growth pace, Cargo Shuttle is ahead.
End User:
Cost tiers separate these segments, with public transport representing capital-intensive municipal procurement and campus services enabling faster pilot-to-scale transitions.
- Campus Services:University and corporate facility managers consolidating procurement under mobility-as-a-service contracts with uptime penalties. North American universities are scaling pilot fleets as deployment templates for controlled environments.
- Public Transport:Municipal operators requiring API compatibility with legacy payment and dispatch platforms. German cities opening dedicated autonomous shuttle lanes are concentrating procurement in this segment.
- Airport Transit:Hub airports seeking to reduce bus fleet labor costs through terminal-to-parking connectivity. European tenders now require EU AI Act algorithmic transparency compliance.
- Corporate Shuttle:Private campus operators prioritizing brand visibility and employee retention over fare-box recovery. Technology campuses in California and Arizona lead adoption.
Public Transport commands the largest procurement budgets. Campus Services delivers the shortest sales cycles.
Technology:
Application requirements dictate technology selection, with urban deployment demanding multi-modal fusion and controlled environments permitting single-sensor approaches.
- LIDAR:Solid-state and mechanical arrays constituting 35-45% of unit manufacturing costs, with supply constrained by semiconductor foundry allocation. Tier-1 automotive suppliers are integrating these into modular shuttle platforms for urban deployment.
- AI Systems:Deterministic decision-making architectures satisfying EU AI Act audit trail requirements. Suppliers without pre-certified data governance frameworks are exiting German municipal tenders.
- Computer Vision:Camera-based perception stacks sufficient for low-speed, geofenced operations. Campus operators favor these for cost reduction in controlled environments.
- GPS Navigation:Satellite-based positioning augmented by V2X communication modules for real-time traffic priority negotiation in urban cores.
LIDAR dominates manufacturing cost structure. AI Systems are climbing the fastest as regulatory compliance hardens.
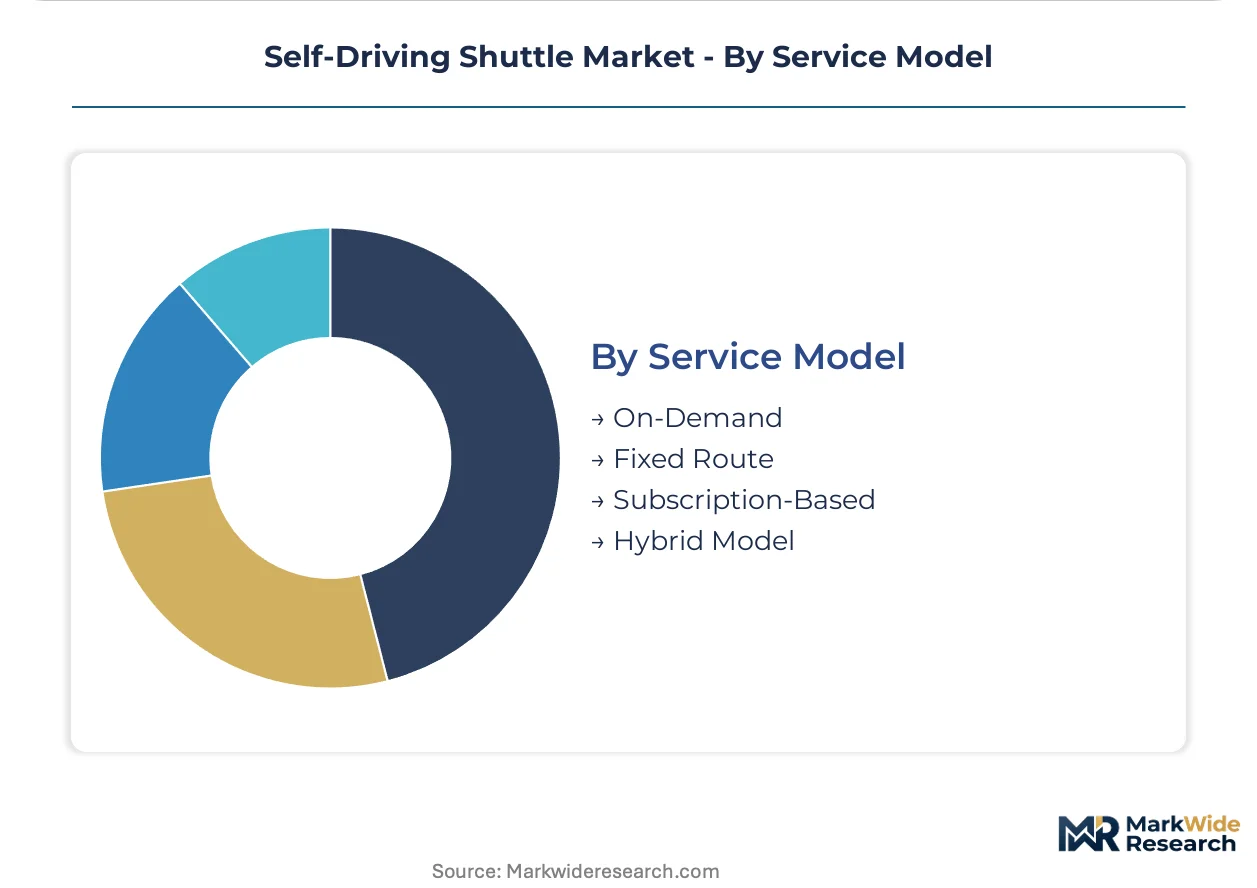
Service Model:
Customer type separates these segments, with municipal agencies favoring predictable fixed-route commitments and corporate clients demanding flexibility.
- Fixed Route:Predetermined service patterns limiting utilization rates compared to dynamic alternatives. This model commands the majority of operational revenue today through municipal procurement channels.
- On-Demand:Dynamically optimized routing promising higher utilization and fare-box recovery. This configuration captures disproportionate R&D investment from autonomy vendors seeking software differentiation.
- Hybrid Model:Scheduled trunk routes with on-demand first/last-mile feeders. Airport operators in Germany and France are piloting these for terminal-ground transportation integration.
- Subscription-Based:Corporate and campus contracts bundling vehicle access with maintenance and insurance. Facility managers in Arizona and California have normalized performance-based service agreements under this structure.
Fixed Route generates current revenue concentration. On-Demand holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Revised NHTSA automated vehicle guidance and Germany's KBA lane allocation policies are accelerating deployment permits across university campuses and municipal corridors. These regulatory shifts concentrate procurement investment in jurisdictions with clarified liability frameworks and dedicated infrastructure allocation.
United States
Campus services operators at Arizona State University and Stanford University are expanding pilot fleets under revised NHTSA guidance that streamlines testing disclosure requirements. The Federal Transit Administration coordinates with municipal transit agencies on automated shuttle integration standards. California's test corridor operators have normalized performance-based service agreements with platform vendors across the San Francisco Bay Area and greater Phoenix metropolitan region.
Germany
Munich and Hamburg have opened dedicated autonomous shuttle lanes on public roads, demonstrating regulatory willingness to allocate street-level priority to automated services. The KBA mandates standardized incident data recorders for all public-road automated shuttle tests, forcing platform builders to re-engineer black-box architectures for European type approval. Bavaria's manufacturing base anchors Navya SAS production scale at its French facility serving German municipal tenders.
France
Municipal operators in Paris and Lyon specify full-size shuttles for trunk-route replacement requiring extended sensor fusion ranges. The EU AI Act adds algorithmic transparency requirements that directly shape supplier selection for European public transport tenders. The Île-de-France region concentrates deployment trials for campus-to-terminal airport connectivity.
Japan
METI enforces divergent testing disclosure frameworks that multiply platform validation expenses for foreign suppliers seeking market entry. Parcel operators in Tokyo and Osaka are accelerating cargo shuttle procurement as labor reduction becomes a procurement mandate. The Kansai region hosts demonstration corridors for V2X communication module convergence with 5G network slicing.
China
WeRide Inc. and Pony.AI Inc. anchor domestic deployment velocity across Shenzhen and Beijing test corridors with layered sensor fusion architectures. The Ministry of Industry and Information Technology coordinates GB standards development for automated vehicle type approval. The Yangtze River Delta concentrates manufacturing investment for solid-state LIDAR arrays constrained by semiconductor foundry allocation.
Self-Driving Shuttle Market Competitive Landscape
Player mix skews toward autonomy specialists with captive sensor integration capabilities and Tier-1 automotive suppliers with modular platform architectures. The supplier base collapses under ISO 26262 functional safety certification requirements, concentrating procurement power among fleet operators who enforce multi-year service agreements. Three archetypes dominate: full-stack autonomy vendors, automotive Tier-1 platform builders, and campus-specialized service operators. Competitive moves center on strategic partnerships for regulatory pre-certification and geographic expansion through municipal tender participation.
Within the full-stack autonomy tier, Waymo LLC and Zoox Inc. exemplify layered perception system development for urban deployment velocity. Navya SAS anchors European demand through manufacturing scale, while EasyMile SAS occupies a position exemplifying campus and airport transit specialization. May Mobility Inc. represents the campus-to-municipal expansion archetype among North American operators. These companies sit within a competitive structure where pre-certified data governance frameworks determine German municipal tender eligibility and EU AI Act compliance shapes European procurement selection criteria.
| Leading Market Players |
|---|
| EasyMile SAS |
| Navya SAS |
| May Mobility Inc. |
| Zoox Inc. |
| Waymo LLC |
| Nuro Inc. |
| Beep Inc. |
| WeRide Inc. |
| Pony.AI Inc. |
| Others |
Pricing and Supply Chain Analysis
ISO 26262 functional safety certification gates both supplier qualification and price differentiation across the self-driving shuttle market, concentrating procurement leverage with fleet operators who can enforce multi-year service agreements while squeezing hardware-agnostic middleware providers lacking captive sensor supply.
Pricing Analysis
Certification level creates the primary spread between platform tiers, with ASIL-D validated units commanding substantial premiums over lower-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects sensor fusion complexity, with LIDAR-camera-radar stacks separating top-tier offerings from camera-only campus configurations. Cost compression in the compact shuttle segment is intensifying because semiconductor foundry constraints limit LIDAR array availability. Campus services operators exhibit highest price sensitivity due to mobility-as-a-service contract structures, while municipal public transport buyers prioritize compliance over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes directly impact solid-state LIDAR delivery schedules to French and German assembly facilities. Manufacturing concentrates in China, France, and the United States, with Yangtze River Delta fabs producing semiconductor substrates that feed sensor array production. The supply chain rests on germanium substrates, indium phosphide wafers, and precision optical components as critical inputs. Single-source vulnerability in semiconductor foundry allocation poses structural risk. Distribution runs through Tier-1 automotive supplier networks and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-driving shuttle market is approaching a platform-economics inflection as V2X communication module convergence with 5G network slicing creates interoperability standards that will determine which autonomy stacks achieve deployment scale.
For Market Incumbents: Secure pre-certified data governance frameworks for EU AI Act compliance before German municipal tender windows close, insulating against emerging software-only licensing competitors. Deepen backward integration into solid-state LIDAR production to reduce semiconductor foundry allocation exposure. Prioritize campus-to-municipal expansion pathways that leverage existing performance-based service agreement templates. For New Entrants and Emerging Players: Differentiate on deterministic logging architectures that satisfy both KBA incident disclosure mandates and algorithmic transparency requirements. Target airport ground transportation integration as the most penetrable segment, where labor cost elimination mandates outweigh procurement cycle complexity. Pursue hub airport connectivity pilots as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across full-size shuttle platforms requiring extended sensor fusion ranges and redundant braking architectures. Long-term viability favors suppliers with captive manufacturing footprints and regulatory pre-certification in multiple jurisdictions. Watch for the first unified cross-border type approval decision as the signal indicating which geography will concentrate procurement budgets and manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Standardization | Layered perception systems from Waymo LLC and Zoox Inc. are establishing the baseline for urban deployment velocity. |
| EU AI Act Compliance Certification | Deterministic logging systems satisfy both KBA disclosure requirements and algorithmic transparency mandates for European tenders. |
| Campus-to-Airport Connectivity Expansion | EasyMile SAS demonstrations at hub airports open procurement channels seeking bus fleet labor cost reduction. |
| V2X-5G Network Slicing Integration | Real-time traffic priority negotiation in Munich and Hamburg dedicated lanes validates infrastructure allocation willingness. |
| Cargo Shuttle Platform Development | Last-mile logistics substitution in Germany and Japan accelerates as driver cost elimination hardens into procurement mandate. |
Research Methodology
A spread of perspectives from fleet operations directors, municipal procurement officers, autonomy platform engineers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with campus services operators at Arizona State University and Stanford University, KBA certification auditors, and Tier-1 automotive supplier program managers. Secondary validation drew from NHTSA automated vehicle guidance filings, KBA incident data recorder mandates, EU AI Act regulatory texts, and municipal tender documentation from Munich, Hamburg, Paris, and Lyon. Bottom-up unit economics modeling triangulated against top-down market sizing across vehicle type, end user, technology, and service model dimensions.
Segmentation dimensions modeled include vehicle configuration, operational context, technology stack, and service model structure across the projection horizon. Deployment velocity assumptions incorporated regulatory pathway complexity, infrastructure readiness, and labor cost elimination potential rather than unit economics alone. CAGRs were derived from install base expansion rates normalized against fleet operator procurement cycle data. Industry-specific forecast inputs encompassed LIDAR sensor cost trajectories tied to semiconductor foundry allocation and V2X communication module adoption curves.
Material uncertainties — regulatory harmonization timing, semiconductor supply normalization, and cross-jurisdictional liability framework convergence — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding NHTSA guidance stability, KBA lane allocation policy continuity, and EU AI Act implementation sequencing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Asia-Pacific Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market