
 Automotive Infotainment SOC Market | 2026-2036
Automotive Infotainment SOC Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Infotainment SOC Market Insights
The EU AI Act is hardening the cost-of-entry calculus for automotive infotainment SOC vendors by mandating conformity assessments for machine-learning components embedded in driver-information systems. Qualcomm Technologies leverages its Snapdragon Digital Chassis platform to sustain design wins across tier-one automotive suppliers. NVIDIA Corporation anchors its position through high-performance GPU architectures purpose-built for multi-display cockpit consolidation.
An automotive infotainment system-on-chip integrates CPU clusters, GPU cores, neural processing units, and multimedia accelerators onto a single die, typically fabricated at 5nm or 7nm process nodes to deliver sub-10-watt thermal envelopes while rendering multiple 4K displays simultaneously. Connectivity Modules command premium silicon allocation as over-the-air update requirements expand memory bandwidth specifications across OEM programs. Electric Vehicles represent the fastest-growing end-user category, with dedicated high-voltage isolation requirements and zonal E/E architectures forcing SOC redesigns away from shared ICE-derived platforms.
The European Union's CE marking and ECHA REACH frameworks govern substance restrictions and electromagnetic compatibility for cockpit electronics sold across member states. In the United States, FCC Part 15 and NHTSA distraction guidelines shape radio-frequency certification and human-machine interface constraints for integrated displays. Stakeholders must monitor how emerging cybersecurity standards from ISO and IEC rewrite validation protocols for connected infotainment stacks before committing to long-term silicon roadmaps.
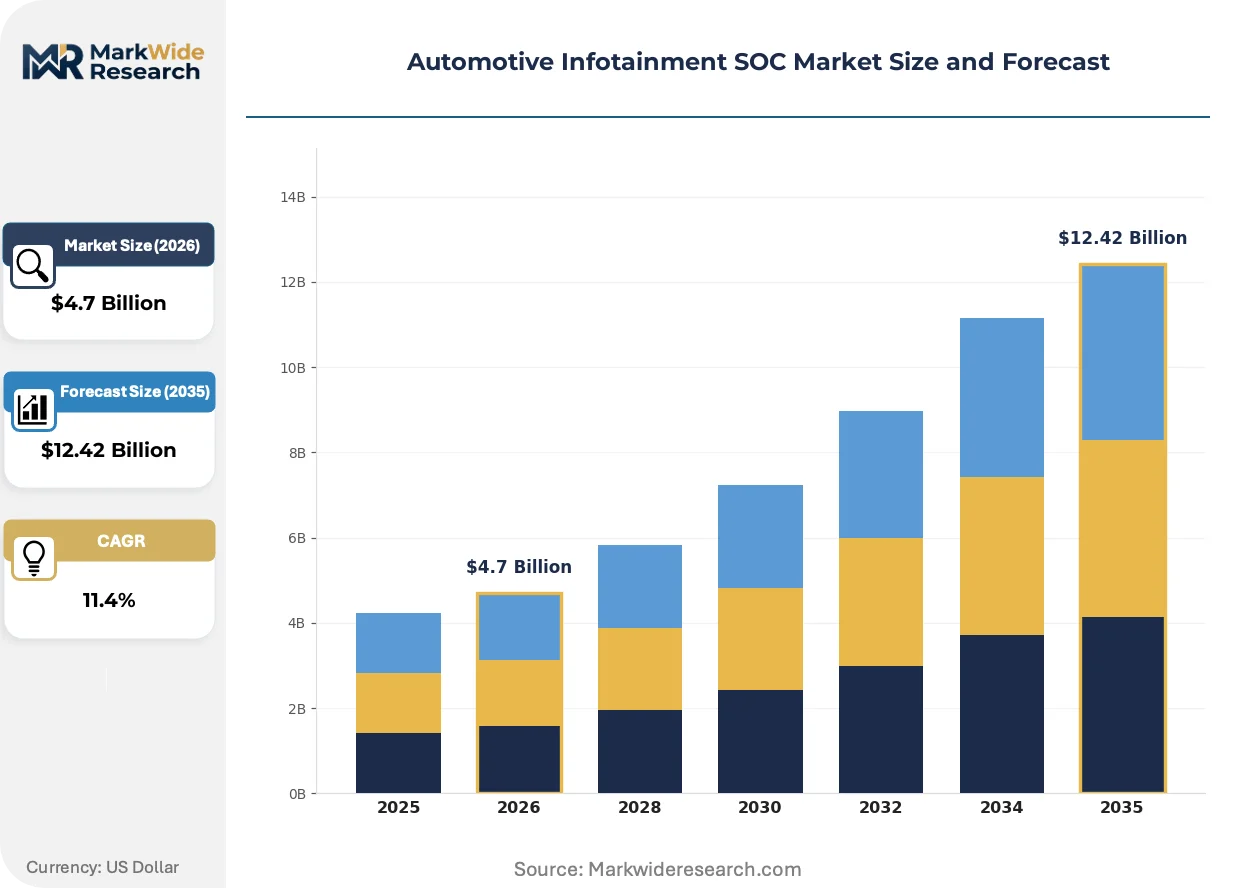
Market Dynamics
Zonal E/E architectures in electric vehicles are collapsing discrete ECU functions into centralized compute domains, forcing SOC vendors to consolidate infotainment, cluster, and ADAS workloads onto unified silicon. This architectural convergence is rewriting thermal budgets, memory hierarchies, and safety certification pathways across OEM roadmaps.
Growth Catalysts
- EU AI Act Conformity Mandates:Algorithmic transparency requirements for driver-facing ML systems are accelerating procurement of pre-certified SOCs with documented neural network interpretability.
- Zonal Gateway Integration:Ethernet-based vehicle networks are expanding SOC addressable silicon by co-locating infotainment with body domain controllers on shared compute substrates.
- German OEM Specification Leadership:Volkswagen Group and BMW AG are demanding multi-domain architectures that combine 4K rendering with ASIL-B safety isolation, pulling advanced node capacity toward automotive qualification.
Market Restraints
- Advanced Node Allocation Bottlenecks:TSMC and Samsung Foundry prioritize mobile and AI accelerator wafers, constraining 5nm automotive tape-out slots to 12-18 month queues.
- ISO 26262 Functional Safety Costs:ASIL-D certification for cluster-integrated SOCs adds $8-12 million per design generation, freezing mid-tier suppliers out of consolidated cockpit bids.
- Silicon Carbide Powertrain Competition:EV manufacturers are diverting R&D capex toward traction inverter efficiency, compressing infotainment SOC upgrade cycles.
Strategic Opportunities
- Indian Domestic Manufacturing:PLI scheme incentives for semiconductor assembly and test are drawing packaging investment for entry-level cockpit SOCs serving Maruti Suzuki and Tata Motors programs.
- Over-the-Air Update Infrastructure:Secure OTA pipelines are creating attach-rate expansion for hardware security modules co-integrated with infotainment processors.
- V2X Edge Compute Convergence:C-V2X protocol stacks are expanding SOC content per vehicle by fusing roadside unit communication with predictive navigation rendering.
Industry Challenges
- Functional Safety Talent Scarcity:ISO 26262 systems architects command 40-60% salary premiums over consumer semiconductor equivalents, constraining vendor hiring velocity.
- Legacy ICE Platform Carryover:Shared 12V electrical architectures force SOCs to support dual voltage domains, adding die area and validation complexity without performance benefit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Infotainment SOC Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Systems, Audio Systems, Connectivity Modules, Display Interfaces End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Technology: Bluetooth, Wi-Fi, Android Auto, Apple CarPlay Integration Level: Embedded Systems, Aftermarket Systems, OEM Solutions, Hybrid Systems |
| Companies Covered | Qualcomm Technologies, NVIDIA Corporation, Texas Instruments, Renesas Electronics Corporation, NXP Semiconductors, Infineon Technologies AG, STMicroelectronics, Intel Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Infotainment SOC Market Trends and Innovations
Chiplet-based disaggregation is breaking monolithic SOC designs into specialized tiles, enabling mix-and-match IP reuse across premium and volume vehicle programs. This modular approach is compressing development timelines while fragmenting supplier power across the value chain.
Neural processing units with sparse computation engines are expanding into real-time driver monitoring and occupant classification workloads. Tier-one suppliers in Germany and Japan are integrating these accelerators into 2026 platform designs. The shift is expanding silicon area allocation toward AI inference and away from fixed-function multimedia blocks.
The EU AI Act's risk-classification framework is mandating conformity assessments for emotion recognition and biometric categorization systems embedded in cabin sensing. OEMs are responding by pre-integrating explainable AI toolchains into SOC software stacks before 2025 model year launches. This regulatory pressure is most acute in German and French premium vehicle programs targeting domestic fleet sales.
Subscription-based feature activation is altering how OEMs value SOC headroom at point of manufacture. Buyers in North America and China are increasingly accepting hardware-enabled software unlocks for navigation, audio, and gaming functions. This consumption-pattern shift is inflating minimum viable compute specifications while deferring revenue recognition to post-sale digital storefronts.
Automotive Infotainment SOC Market Segmentation
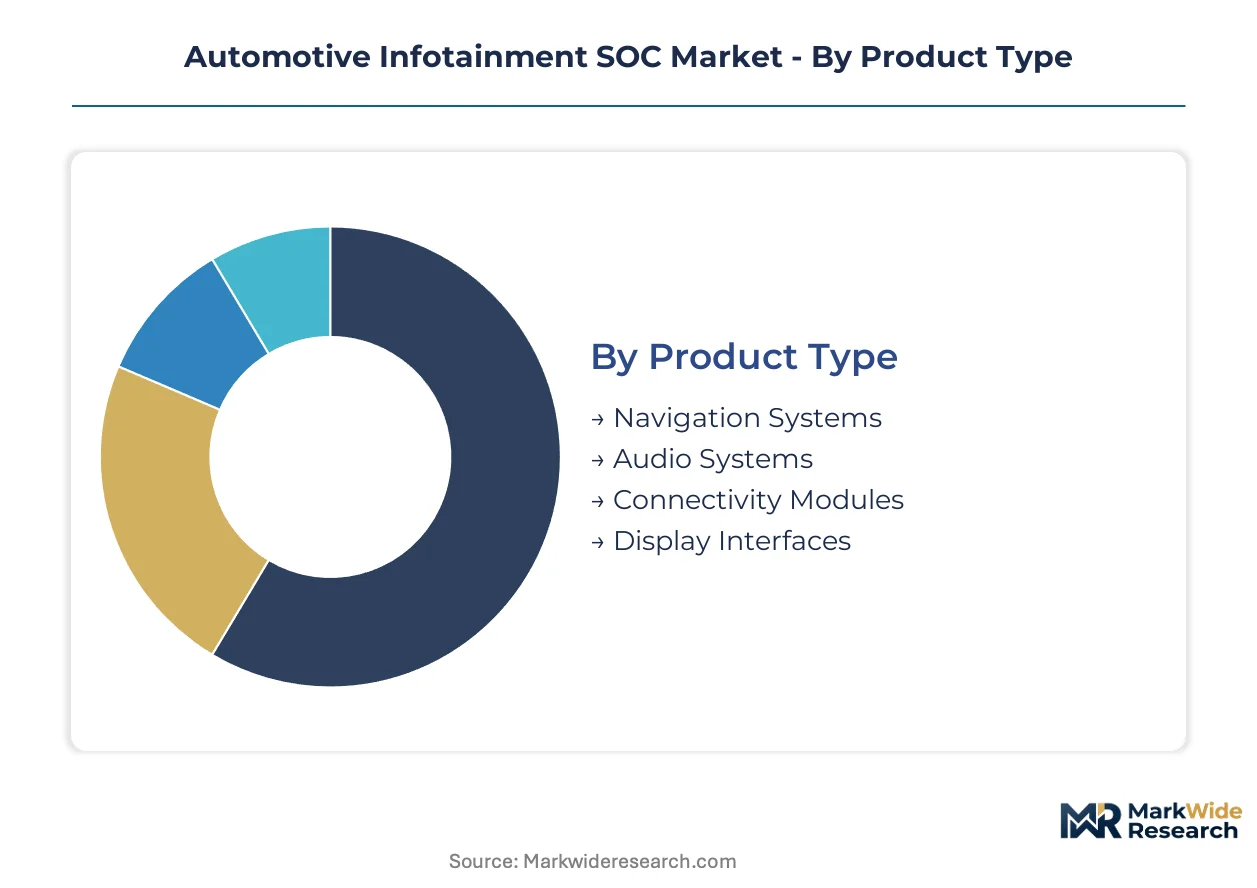
Automotive infotainment SOC procurement patterns diverge sharply across vehicle electrification tiers, cockpit consolidation architectures, and regulatory compliance thresholds. Understanding these segment boundaries clarifies where silicon vendors must allocate advanced node capacity versus mature process derivatives.
Product Type:
Connectivity Modules anchor the specification ladder, commanding the highest memory bandwidth and security co-processor density per die.
- Connectivity Modules:These SOCs integrate cellular basebands, Wi-Fi 6/6E transceivers, and hardware security modules for over-the-air update pipelines. German OEM programs specify these for zonal gateway co-location, pulling TSMC 5nm automotive capacity toward telematics-heavy configurations.
- Display Interfaces:Multi-4K rendering engines with MIPI DSI and eDP outputs dominate premium cockpit consolidation. Volkswagen Group and BMW AG demand these for cluster-infotainment fusion, accelerating ASIL-B certification timelines across silicon roadmaps.
- Navigation Systems:GPS/GNSS-accelerated SOCs with real-time kinematic correction for lane-level positioning.
- Audio Systems:DSP-optimized dies with acoustic echo cancellation and active noise reduction blocks.
Connectivity Modules lead on scale; Display Interfaces lead on momentum.
End User:
Vehicle electrification status now overrides traditional class-based segmentation in SOC procurement specifications.
- Electric Vehicles:Dedicated high-voltage isolation domains and zonal E/E architectures force clean-sheet SOC designs. These platforms omit legacy 12V support circuits, reclaiming die area for neural processing units and Ethernet switch integration. EU AI Act compliance costs concentrate here.
- Luxury Vehicles:Multi-display cockpit consolidation with rear-seat entertainment and augmented reality HUD interfaces. German and Japanese OEMs specify 7nm-class silicon with 100+ TOPS AI acceleration for occupant monitoring and predictive navigation.
- Passenger Vehicles:Volume ICE and mild-hybrid platforms with shared electrical architectures.
- Commercial Vehicles:Fleet-optimized SOCs with driver fatigue monitoring and hours-of-service logging.
Electric Vehicles expand most quickly; Luxury Vehicles sustain premium pricing power.
Technology:
Smartphone projection protocols have commoditized entry-level infotainment while forcing SOC vendors to maintain dual-certification overhead.
- Apple CarPlay:MFi-certified implementations require dedicated authentication co-processors and H.264 decode pipelines. North American OEMs mandate wireless variants, expanding Bluetooth 5.3 and ultra-wideband silicon content per vehicle.
- Android Auto:Google Mobile Services integration with modular certification tiers. Indian and Southeast Asian OEMs prioritize these for cost-optimized programs, constraining SOC margins through volume pricing pressure.
- Bluetooth:Classic and Low Energy stacks for hands-free and sensor hub aggregation.
- Wi-Fi:802.11ax/ay for hotspot and screen mirroring workloads.
Apple CarPlay dominates attach rates; Android Auto climbs fastest in emerging volume markets.
Integration Level:
Supply chain control points split between captive OEM silicon strategies and tier-one supplier consolidation plays.
- OEM Solutions:Vertically integrated designs from Volkswagen Group, Tesla, and Mercedes-Benz specify proprietary software stacks atop licensed IP blocks. These programs capture 60-70% of advanced node automotive tape-outs, freezing tier-one suppliers out of specification authority.
- Embedded Systems:Fixed-function SOCs with pre-integrated middleware and long-term supply guarantees. Japanese tier-one suppliers favor these for keiretsu relationships, prioritizing qualification stability over node advancement.
- Aftermarket Systems:Retrofit head units with reduced thermal envelopes and simplified vehicle bus interfaces.
- Hybrid Systems:Partitioned architectures separating safety-critical cluster functions from open infotainment domains.
OEM Solutions concentrate value capture; Embedded Systems anchor supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional safety engineers cluster in southern Germany and Bavaria, anchoring the highest concentration of automotive SOC design talent outside Taiwan. This workforce density shapes procurement patterns and certification timelines across the industry.
Germany
Volkswagen Group and BMW AG specifications for multi-domain cockpit architectures pull TSMC 5nm automotive capacity toward German qualification programs. The EU AI Act mandates conformity assessments for driver-facing ML systems, hardening entry barriers for non-certified silicon. Munich and Stuttgart host tier-one supplier engineering centers where ASIL-B safety isolation designs converge with 4K rendering pipelines.
United States
Detroit Three electrification roadmaps and Tesla's vertical silicon strategy consume advanced node tape-outs for zonal gateway integration. FCC Part 15 governs radio-frequency certification for connected infotainment stacks. Austin and San Diego anchor fabless design operations where neural processing unit architectures target predictive navigation and occupant monitoring workloads.
China
Domestic EV manufacturers BYD and NIO specify clean-sheet SOC designs omitting legacy 12V support circuits. MIIT GB standards govern electromagnetic compatibility for cockpit electronics sold domestically. Shanghai and Shenzhen foundries qualify 7nm-class silicon for multi-display consolidation serving premium local brands.
Japan
Toyota and Honda keiretsu relationships prioritize long-term supply guarantees over node advancement in procurement decisions. METI JIS standards shape quality assurance protocols for fixed-function embedded SOCs. Nagoya and Tokyo host tier-one supplier consolidation plays where qualification stability anchors multi-year platform commitments.
India
Maruti Suzuki and Tata Motors programs drive entry-level cockpit SOC demand through cost-optimized Android Auto implementations. The PLI scheme incentivizes semiconductor assembly and test investment for domestic packaging capacity. Karnataka and Tamil Nadu clusters attract back-end infrastructure serving emerging volume markets.
Automotive Infotainment SOC Market Competitive Landscape
The competitive structure tilts toward diversified semiconductor conglomerates with automotive-qualified advanced node access. Qualcomm Technologies and NVIDIA Corporation anchor premium tier positions through multi-domain platform strategies. Three archetypes dominate: fabless designers with captive ecosystem control, IDM suppliers with foundry partnerships, and captive OEM silicon operations. Consolidation pressures manifest through ASIL-D certification cost barriers and 12-18 month foundry queue bottlenecks.
Among fabless platform vendors, Qualcomm Technologies exemplifies ecosystem lock-in through Snapdragon Digital Chassis integration, while NVIDIA Corporation occupies a position defined by GPU-centric cockpit consolidation architectures. Texas Instruments anchors a third position through embedded processing heritage and long-horizon automotive supply relationships. These three represent divergent strategic bets on neural processing unit density versus software stack control versus qualification velocity.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| NVIDIA Corporation |
| Texas Instruments |
| Renesas Electronics Corporation |
| NXP Semiconductors |
| Infineon Technologies AG |
| STMicroelectronics |
| Intel Corporation |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
The EU AI Act's conformity assessment mandates for driver-facing machine-learning systems gate both qualified foundry supply and premium-tier pricing access for automotive infotainment SOC vendors. OEM procurement teams now pay certification premiums for pre-validated silicon while foundry queues stretch toward 18-month horizons.
Pricing Analysis
Bundled hardware-software service splits now dominate automotive SOC commercial structures. Three-tier pricing stratifies across ASIL-D certified cluster-integrated dies, ASIL-B multi-domain fusion chips, and entry-level Android Auto projection systems. Cost compression in volume ICE carryover programs intensifies as Indian and Southeast Asian OEMs squeeze tier-one suppliers. Electric vehicle manufacturers show least price sensitivity, absorbing neural processing unit premiums for zonal E/E architectures.
Supply Chain Analysis
Reverse-logistics flows for failed cockpit SOCs remain underdeveloped, with most end-of-life units shredded rather than remanufactured for secondary automotive applications. Wafer fabrication concentrates in Taiwan, South Korea, and the United States, drawing from silicon carbide substrates, advanced packaging materials, and EUV photoresist chemicals. Single-source vulnerability at TSMC's 5nm automotive nodes threatens OEM roadmaps. Distribution runs through tier-one supplier consolidation plays anchored in southern Germany and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act functions as a regulatory compounder, hardening certification barriers that accelerate procurement of pre-validated multi-domain SOCs. This dynamic concentrates value capture among vendors with documented neural network interpretability toolchains.
For Market Incumbents: Acquire ISO 26262 functional safety engineering teams to compress ASIL-D certification timelines. Qualcomm Technologies and NVIDIA Corporation should backward integrate into advanced packaging capacity to bypass foundry queue bottlenecks. Defensive positioning requires pre-integrating explainable AI software stacks before German OEM model year launches.
For New Entrants and Emerging Players: Begin with entry-level Android Auto implementations for Indian domestic manufacturing programs under the PLI scheme. White-space concentrates in cost-optimized cockpit SOCs serving Maruti Suzuki and Tata Motors. Go-to-market leverage rests on semiconductor assembly and test partnerships in Karnataka and Tamil Nadu clusters.
For Investors and Strategic Acquirers: Roll-up economics work for tier-one automotive suppliers with captive OEM relationships because zonal E/E architectures are collapsing discrete ECU procurement into consolidated cockpit compute contracts. Target acquisition archetypes include ASIL-B certified fabless designers with Volkswagen Group or BMW AG design wins. Watch for TSMC automotive capacity allocation announcements as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Unlocks cluster-infotainment fusion bids from German OEMs specifying multi-domain architectures. |
| Foundry Partnership Expansion | Secures 5nm automotive tape-out slots ahead of 12-18 month queue bottlenecks at TSMC. |
| Neural Processing Unit Integration | Captures EU AI Act-mandated driver monitoring workloads for 2026 platform designs. |
| Indian Packaging Infrastructure | Accesses PLI scheme incentives for entry-level cockpit SOC assembly serving domestic OEMs. |
| OTA Security Module Co-integration | Expands attach rates for hardware security modules alongside infotainment processors. |
Research Methodology
Multiple input streams — OEM platform engineering interviews, tier-one supplier procurement disclosures, and foundry capacity announcements — were reconciled against secondary validation. Primary fieldwork engaged SOC product managers, automotive functional safety architects, and semiconductor distribution channel heads. Secondary sources included vehicle production databases, IHS Markit registration data, SEC semiconductor filings, and EU regulatory conformity assessment documentation. Bottom-up unit economics and top-down market sizing were triangulated for coherence.
Historical shipment trajectories were cross-referenced against expert panel inputs on electrification roadmaps and zonal E/E adoption curves. Segmentation modeling spanned vehicle propulsion architecture, cockpit consolidation level, ASIL certification tier, and regional OEM specification authority. CAGRs were derived from installed base projections and content-per-vehicle expansion across the analysis window. Forecast inputs incorporated neural processing unit density roadmaps and EU AI Act implementation timelines.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Taiwan semiconductor access, raw material price spikes in silicon carbide substrates, and unanticipated regulatory delays in EU AI Act enforcement. Forecasts reflect assumptions on foundry capacity allocation and OEM electrification commitment durability. Practitioners should monitor TSMC automotive node expansion announcements and German OEM multi-domain architecture specification freezes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Audio Processor Market