
 Cloud AI Chipsets Market | 2026-2036
Cloud AI Chipsets Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud AI Chipsets Market Outlook
Modular accelerator cards sold separately from server chassis is decoupling hardware procurement from system vendor lock-in. NVIDIA Corporation leverages its CUDA software ecosystem to sustain developer loyalty across cloud instances. Advanced Micro Devices, Inc. (AMD) competes on raw compute density per watt in hyperscale deployments. Intel Corporation anchors x86-compatible AI acceleration for enterprises migrating existing workloads.
Cloud AI chipsets comprise silicon processors optimized for parallel matrix operations at scale, typically manufactured on sub-5nm process nodes with high-bandwidth memory stacks and interconnect fabrics exceeding terabyte-per-second throughput. These devices power neural network training and inference in centralized data centers. Graphics Processing Units currently dominate training workloads due to mature software stacks, while Application-Specific Integrated Circuits capture margin pools in inference-optimized deployments where power efficiency governs total cost of ownership. Field-Programmable Gate Arrays occupy niche positions in low-latency financial and defense applications requiring reconfigurable logic.
The US Commerce Department's Bureau of Industry and Security administers export controls on advanced AI accelerators to specified destinations, directly constraining shipment volumes for certain foundry customers. The EU AI Act imposes risk-tiered obligations on high-capability general-purpose AI models, shaping product certification requirements for cloud providers operating in European jurisdictions. China MIIT enforces domestic procurement preferences for government and state-owned enterprise cloud deployments, redirecting demand toward locally designed silicon. Stakeholders must monitor evolving multilateral alignment on semiconductor equipment restrictions and model capability thresholds to anticipate supply chain reconfigurations.
Market Dynamics
Hyperscale data center operators are decoupling accelerator procurement from server chassis vendors, fragmenting traditional system vendor lock-in and forcing silicon suppliers to build direct cloud relationships.
Growth Catalysts
- Generative AI Training Clusters:Cloud providers are expanding procurement of specialized accelerators for large language model training, creating sustained demand pull from the United States, China, and Germany.
- EU Chips Act Incentives:Domestic fabrication subsidies are reshaping foundry location decisions and redirecting supply chain investments toward European sovereign capacity.
- High-Bandwidth Memory Stacks:Sub-5nm process nodes with terabyte-per-second interconnect fabrics are enabling neural network training at previously unattainable scale.
Market Restraints
- Export Control Friction:The US Commerce Department's Bureau of Industry and Security administers shipment restrictions on advanced AI accelerators to specified destinations, constraining foundry customer volumes.
- Foundry Concentration Risk:Leading-edge manufacturing capacity concentrates among Taiwan and South Korea-based suppliers, creating geographic chokepoints for sub-5nm production.
- Power Density Limitations:Thermal constraints in hyperscale facilities cap rack-level deployment density, limiting total cost of ownership gains from raw compute advances.
Strategic Opportunities
- Sovereign Cloud Buildouts:Germany's Gaia-X initiative and similar national infrastructure programs are creating dedicated procurement channels for domestic-compliant silicon.
- Inference-Optimized ASICs:Application-specific integrated circuits are capturing margin pools in power-constrained edge deployments where efficiency governs operating economics.
- Modular Accelerator Cards:Disaggregated hardware procurement is integrating with open accelerator module standards, enabling multi-vendor rack configurations.
Industry Challenges
- Compiler and Software Stack Talent:Shortage of engineers proficient in parallel programming models and kernel optimization is constraining customer deployment velocity.
- EU AI Act Certification Timelines:Risk-tiered obligations on high-capability models are extending product validation cycles for cloud providers operating in European jurisdictions.
- Legacy x86 Workload Migration:Enterprises migrating existing analytics pipelines face integration complexity with parallel accelerator architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud AI Chipsets Market |
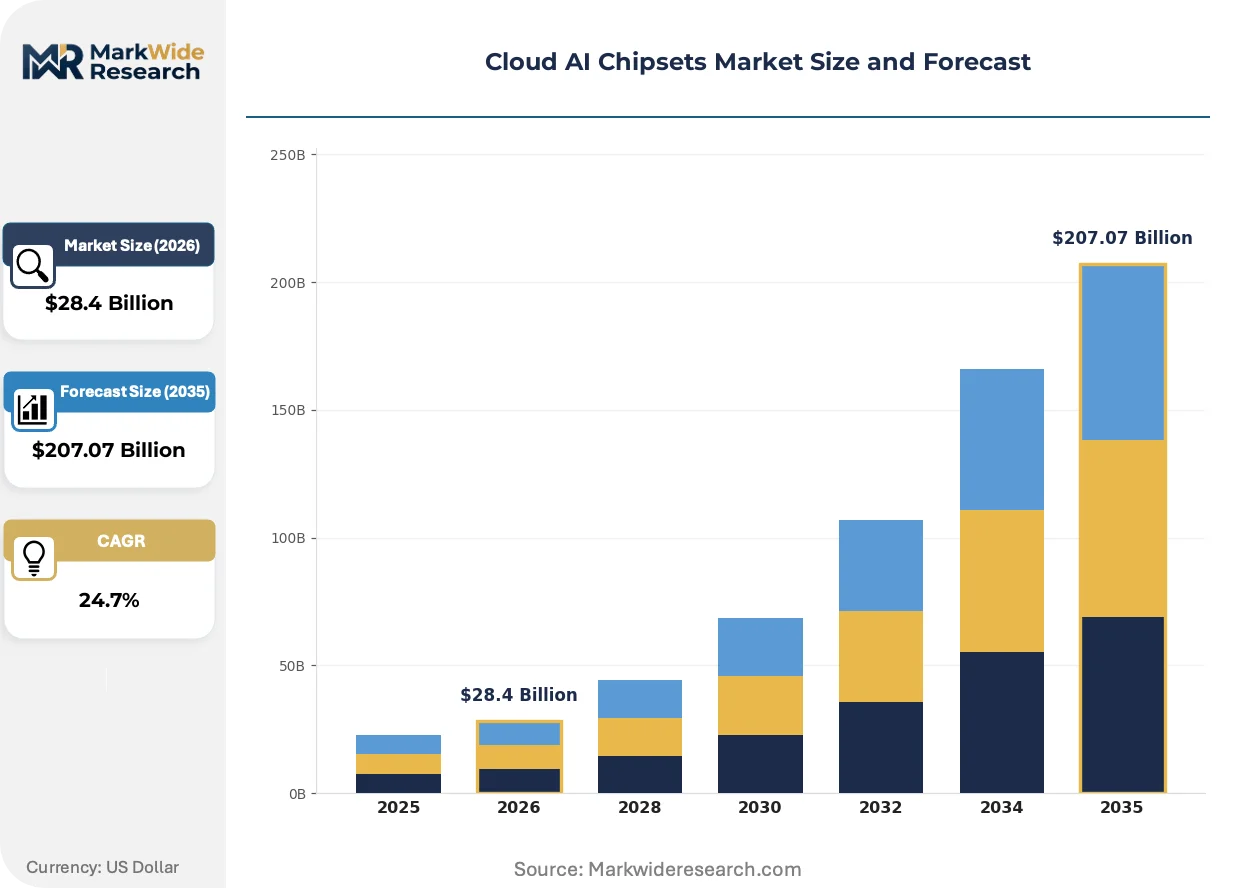
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $207.07 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensor Processors, Graphics Processing Units, Application-Specific Integrated Circuits, Field-Programmable Gate Arrays End User: Cloud Service Providers, Enterprises, Research Institutions, Government Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices, Inc. (AMD), Intel Corporation, Google, Amazon Web Services (AWS), Graphcore, Cerebras Systems, Qualcomm Technologies, Inc., Marvell Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud AI Chipsets Market Strategic Shifts
Silicon architecture is bifurcating between training-optimized and inference-optimized designs, with software ecosystems becoming the primary switching cost rather than hardware performance alone.
Chiplet-based designs with 2.5D and 3D stacking are integrating high-bandwidth memory and logic dies into unified packages. Hyperscale operators are adopting these configurations at scale for generative AI training clusters. This integration is compressing memory bandwidth bottlenecks that previously limited model parameter scaling.
The EU AI Act imposes risk-tiered obligations on high-capability general-purpose AI models, shaping product certification requirements. Cloud providers operating in European jurisdictions must document systemic risk mitigation measures. Deployment of training clusters above specified compute thresholds faces heightened scrutiny in France, Germany, and the Netherlands.
Cloud buyers are consolidating procurement decisions into centralized infrastructure teams with direct silicon supplier relationships. Traditional system vendors are losing gatekeeper status as modular accelerator cards enable multi-source rack configurations. This pattern is most visible in United States hyperscale deployments, where annual procurement volumes justify dedicated supplier engineering support.
Cloud AI Chipsets Market Segmentation
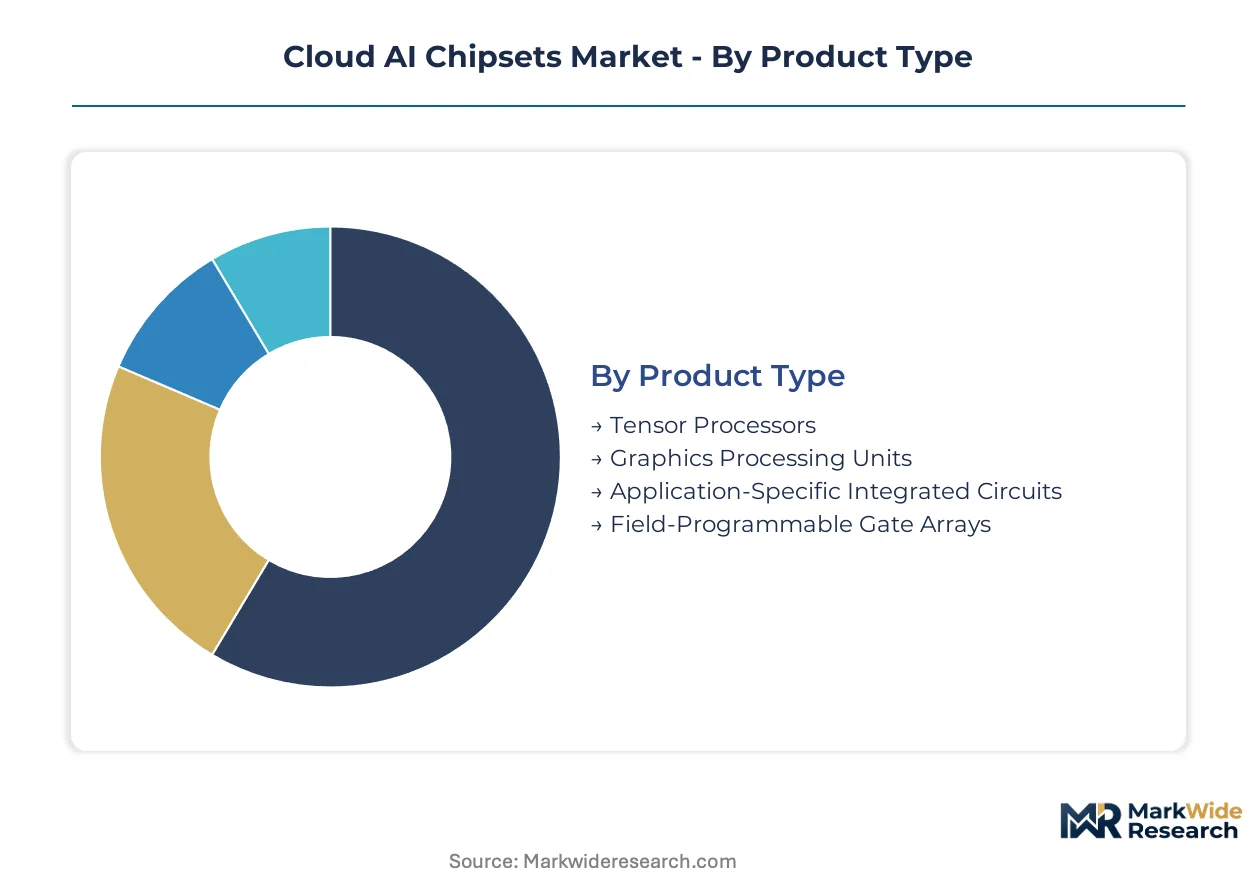
Cloud AI chipsets segment across hardware architectures, customer procurement patterns, and workload optimization requirements. Each dimension carries distinct regulatory obligations, cost structures, and software ecosystem dependencies that reshape supplier strategies.
Product Type:
EU AI Act risk-tiered obligations apply differentially: training-optimized accelerators face heightened systemic risk documentation, while inference-optimized variants encounter lighter certification burdens.
- Graphics Processing Units:Parallel processing architectures with mature CUDA and ROCm software stacks dominate large language model training clusters. NVIDIA Corporation and Advanced Micro Devices, Inc. supply hyperscale operators in the United States and Germany where generative AI buildouts concentrate demand.
- Application-Specific Integrated Circuits:Custom silicon designs optimize power efficiency for inference workloads at scale. Google Cloud TPU and Amazon Web Services Trainium deployments in power-constrained European facilities illustrate where total cost of ownership governs procurement decisions.
- Tensor Processors:Google-designed matrix multiplication units accelerate specific neural network operations.
- Field-Programmable Gate Arrays:Reconfigurable logic suits low-latency financial and defense applications requiring hardware flexibility.
Leading the category by volume: Graphics Processing Units. Growing fastest: Application-Specific Integrated Circuits.
End User:
Procurement scale and compliance requirements diverge sharply across customer types, with sovereign AI initiatives redirecting vendor engagement models.
- Cloud Service Providers:Hyperscale operators including Amazon Web Services, Microsoft Azure, and Google Cloud Platform purchase accelerators at volumes justifying direct silicon supplier relationships and custom chiplet configurations. Annual procurement cycles in the United States and China reshape foundry capacity allocation.
- Enterprises:Fortune 500 companies migrating analytics workloads face x86-to-accelerator integration complexity and compiler talent shortages that constrain deployment velocity.
- Research Institutions:Universities and national laboratories access accelerators through cloud credits and dedicated cluster allocations.
- Government:State-owned enterprises in China and defense agencies across NATO jurisdictions enforce domestic procurement preferences and export control compliance.
Cloud Service Providers command the largest procurement volumes. Government segments are expanding most quickly under sovereign AI mandates.
Technology:
Workload characteristics determine memory bandwidth requirements and precision formats, with natural language processing imposing distinct architectural demands versus computer vision pipelines.
- Deep Learning:Multi-layer neural network training requires terabyte-per-second interconnect fabrics and high-bandwidth memory stacks. Transformer-based model scaling in the United States and China drives accelerator procurement for parameter counts exceeding one trillion.
- Natural Language Processing:Large language model inference demands batch processing efficiency and context window memory management. European cloud providers under EU AI Act documentation requirements prioritize certified deployment pathways.
- Machine Learning:Traditional statistical methods and gradient-boosted frameworks run on lower-precision accelerator configurations.
- Computer Vision:Convolutional neural networks for image classification and object detection optimize for different memory access patterns than language models.
Deep Learning absorbs the majority of training-focused silicon. Natural Language Processing shows the steepest expansion trajectory as generative AI commercializes.
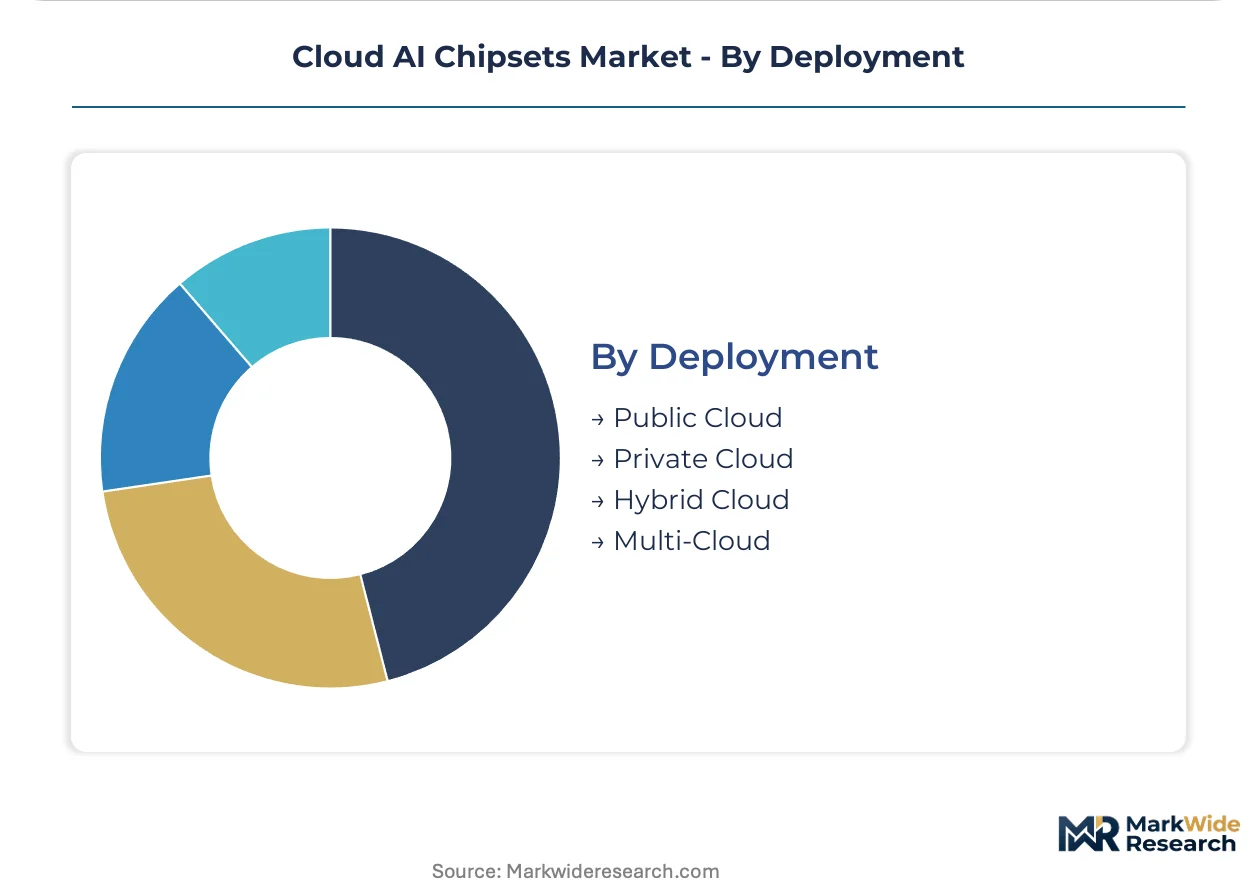
Deployment:
Data residency regulations and latency requirements fragment infrastructure topology decisions across jurisdictions.
- Public Cloud:Shared multi-tenant infrastructure delivers elastic accelerator access without capital expenditure. Amazon Web Services, Microsoft Azure, and Google Cloud Platform operate United States, German, and Singapore regions with differential EU AI Act compliance obligations.
- Private Cloud:Single-tenant dedicated clusters serve financial services and healthcare organizations with HIPAA or GDPR data localization mandates.
- Hybrid Cloud:Split workloads across on-premises and public cloud resources.
- Multi-Cloud:Diversified supplier strategies reduce concentration risk.
Public Cloud retains dominant deployment share. Private Cloud is gaining share fastest among regulated industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity concentrates in Taiwan and South Korea while consumption clusters in the United States, China, and Germany where hyperscale operators deploy training infrastructure. This geographic asymmetry creates supply chain chokepoints and regulatory friction points that reshape procurement patterns.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center corridors drive accelerator procurement volumes exceeding other national markets combined. The US Commerce Department's Bureau of Industry and Security administers export controls on advanced AI accelerators to specified destinations, constraining shipment volumes for certain foundry customers. Austin, Texas and Phoenix, Arizona host expanding packaging and test facilities as domestic fabrication incentives under the CHIPS and Science Act redirect capital flows.
China
State-owned enterprises and government cloud deployments enforce domestic procurement preferences under MIIT directives, redirecting demand toward locally designed silicon. Beijing and Shanghai municipal authorities fund sovereign AI initiatives requiring compliant accelerator supply chains. Yangtze River Delta manufacturing clusters advance sub-7nm domestic production despite equipment access restrictions.
Germany
Gaia-X federated data infrastructure and sovereign cloud mandates create dedicated procurement channels for EU-compliant silicon designs. The EU AI Act imposes risk-tiered documentation obligations on high-capability models deployed in Frankfurt and Berlin metropolitan data center zones. Bavaria's semiconductor ecosystem anchors advanced packaging investments serving European cloud providers.
South Korea
Samsung Electronics and SK Hynix dominate high-bandwidth memory supply critical to advanced accelerator packaging. Seoul government programs subsidize foundry capacity expansion for AI-optimized process nodes. Pyeongtaek and Hwaseong industrial complexes concentrate leading-edge DRAM and logic fabrication serving global accelerator demand.
Taiwan
TSMC fabricates the majority of sub-5nm AI accelerators for NVIDIA Corporation and Advanced Micro Devices, Inc. Hsinchu Science Park anchors the world's most advanced semiconductor manufacturing cluster. Geographic concentration risk intensifies as earthquake and geopolitical contingencies threaten uninterrupted supply to cloud operators in the United States and Germany.
Cloud AI Chipsets Market Competitive Environment
The competitive structure tilts toward integrated hardware-software ecosystems rather than pure silicon performance metrics. Three to five vertically integrated hyperscale operators dominate procurement volumes, compressing margins for second-tier fabricators. Strategic archetypes include CUDA-anchored ecosystem players, x86-compatible incumbents, and cloud-native silicon designers. Competitive moves center on compiler talent acquisition and direct cloud provider engineering partnerships.
Within the ecosystem-anchored tier, NVIDIA Corporation exemplifies software stack lock-in through developer tooling dominance. Advanced Micro Devices, Inc. occupies a position challenging raw compute density benchmarks in hyperscale deployments. Intel Corporation represents the x86-compatible migration pathway for enterprises with legacy analytics infrastructure. These three anchors illustrate how competitive positioning depends on switching cost engineering rather than transistor density alone.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices, Inc. (AMD) |
| Intel Corporation |
| Amazon Web Services (AWS) |
| Graphcore |
| Cerebras Systems |
| Qualcomm Technologies, Inc. |
| Marvell Technology |
| Others |
Value Chain & Pricing Dynamics
Training-optimized accelerator premiums versus inference-commodity silicon bifurcation manifests in divergent procurement contracts and foundry allocation queues. Cloud hyperscalers in the United States negotiate direct multi-year supply agreements for sub-5nm training clusters, while European edge deployers face spot-market volatility for mature-node inference chips. This tier divergence concentrates pricing power with Taiwan-based foundries serving the premium segment, while Chinese domestic suppliers absorb commodity-tier margin compression.
Pricing Analysis
Cost-down pressure on inference-optimized ASICs accelerates because hyperscale operators are internalizing silicon design and disintermediating merchant vendors. Three-tier pricing structure across premium training accelerators, standard inference cards, and economy edge devices reflects foundry node maturity and software ecosystem lock-in. NVIDIA Corporation commands the highest tier through CUDA dependency, while AMD and Intel compete on raw compute-per-watt benchmarks. Government cloud buyers in China and Germany exhibit highest price sensitivity due to sovereign compliance mandates, whereas United States hyperscalers prioritize performance over unit economics.
Supply Chain Analysis
Engineering talent shortages in Hsinchu and Pyeongtaek constrain foundry capacity expansion timelines for advanced packaging. Sub-5nm fabrication concentrates in Taiwan and South Korea, with high-bandwidth memory supply anchored in SK Hynix and Samsung Electronics facilities. Raw material dependencies span EUV photoresist from Japan, neon gas from Ukraine, and advanced substrates from Southeast Asian suppliers. Single-source vulnerability around TSMC's leading-edge nodes threatens uninterrupted supply to cloud operators in the United States and Germany. Distribution runs through direct foundry-to-cloud-provider contracts, bypassing traditional system vendor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from export control compliance costs and foundry minimum order quantities will force sub-scale accelerator vendors into strategic exits or acquisition. Surviving players must secure direct hyperscaler engineering partnerships and software stack differentiation.
For Market Incumbents: Extend compiler ecosystem lock-in through kernel optimization tooling for emerging transformer architectures. Invest in captive advanced packaging capacity in Arizona or Bavaria to mitigate Taiwan concentration risk. Defensive consolidation moves should prioritize acquiring inference-optimized ASIC teams with existing cloud deployment credentials, as hyperscale self-designed silicon threatens merchant vendor relevance. For New Entrants and Emerging Players: Begin with sovereign cloud compliance as the wedge—Gaia-X certification pathways and MIIT domestic procurement lists represent penetrable regulatory moats. Target European edge inference deployments where EU AI Act documentation requirements disadvantage incumbent software stacks. Go-to-market through systems integrators serving regulated industries offers faster validation than direct hyperscaler engagement. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated packaging-test specialists given foundry capacity expansion bottlenecks. Long-term viability in this market hinges on software ecosystem switching costs rather than transistor density metrics. Acquisition target archetype: chiplet design houses with 2.5D/3D stacking expertise and existing cloud provider engineering relationships. Watch hyperscaler capital expenditure guidance revisions as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CUDA Ecosystem Extension | Kernel optimization tooling for next-generation transformer architectures locks developer loyalty. |
| Advanced Packaging Capacity Buildout | Arizona and Bavaria facilities reduce Taiwan geographic concentration risk for cloud operators. |
| Sovereign Cloud Certification | Gaia-X and MIIT compliance pathways open procurement channels excluded from incumbent competition. |
| Inference-Optimized ASIC Development | Power efficiency gains in edge deployments capture margin pools from GPU commoditization. |
| Direct Hyperscaler Engineering Partnership | Annual procurement volumes justify dedicated silicon supplier support teams and custom configurations. |
Study Parameters
Independent corroboration across hyperscaler capital expenditure disclosures, foundry earnings call commentary, and EU regulatory filings underwrites the qualitative findings. Primary interviews with cloud infrastructure procurement directors, semiconductor packaging engineers, and regulatory compliance officers combined with secondary validation from SEC filings, TSMC technology symposium materials, and MIIT policy circulars. Bottom-up triangulation against top-down foundry capacity allocation models ensures segmentation integrity across hardware architectures and deployment modes.
Historical reference periods anchored the forecast window to pre-export-control baseline volumes and post-CHIPS-Act incentive announcement trajectories. The analytical framework models demand across product type, end user, technology workload, and deployment topology dimensions throughout the projection horizon. CAGRs derive from foundry capacity expansion schedules, hyperscaler training cluster buildout announcements, and sovereign AI initiative funding commitments. Industry-specific forecast inputs include EU AI Act certification timeline assumptions and Bureau of Industry and Security license approval rate scenarios.
Export control expansion, foundry yield recovery delays, and sovereign AI funding reallocation are the dominant revision risks. Forecasts reflect assumptions on multilateral equipment restriction alignment and cloud provider vertical integration propensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Machine Learning Chip Market