
 Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market | 2026-2036
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market Insights
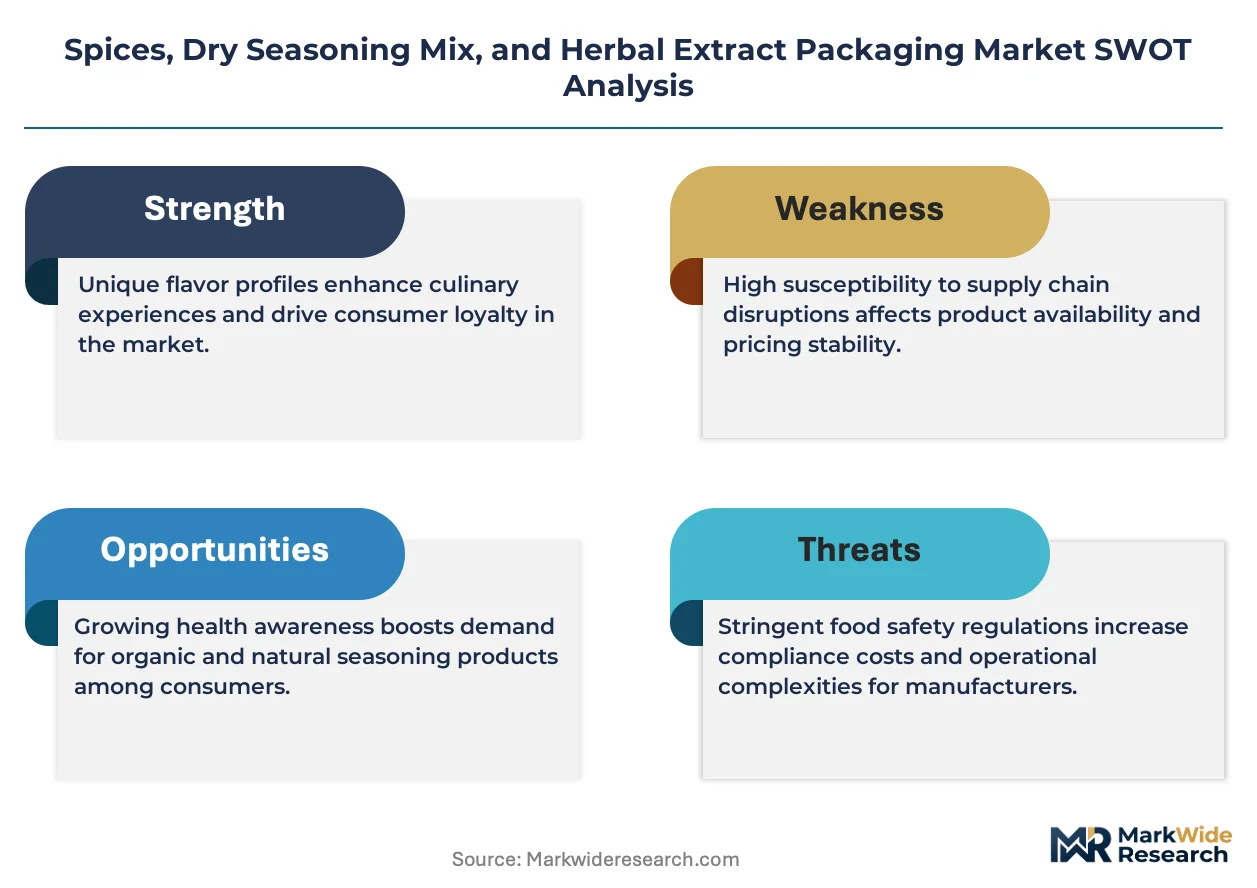
The gap between premium artisanal spice packaging and commodity dry seasoning formats is restructuring how converters allocate film assets and barrier investments. Amcor Group GmbH leverages multi-layer coextrusion technology to serve high-oxygen-barrier applications for volatile essential oils. Mondi Plc anchors European demand through paperboard-based sustainable formats that target private-label herbal extract brands. Sonoco Products Company competes in North American bulk seasoning with rigid composite canisters designed for foodservice distribution.
Spices, dry seasoning mixes, and herbal extracts require packaging engineered to block moisture ingress, prevent volatile oil loss, and resist UV degradation across shelf lives exceeding eighteen months. Laminated structures incorporating aluminum oxide or ethylene vinyl alcohol dominate applications where oleoresin potency must be preserved from factory to reconstitution. Pouches claim the fastest expansion as single-serve ethnic meal kits and direct-to-consumer spice subscriptions reshape order profiles, while glass bottles retain margin concentration in premium retail channels where transparency and reusability command price premiums. Paperboard formats are accelerating as dry rub and seasoning blend brands face retailer mandates to eliminate non-recyclable multi-material constructions.
FDA food contact substance notifications govern barrier additive approvals for spice packaging sold into United States commerce, while EU REACH and F-Gas Regulation constrain solvent-based adhesive chemistries and fluorinated barrier treatments across European supply chains. India's FSSAI packaging safety standards now require explicit migration testing for printed plastic films contacting ground spice surfaces, tightening compliance costs for export-oriented converters. Stakeholders must monitor how evolving extended producer responsibility frameworks in Germany and France redistribute recycling cost liability upstream to brand owners and their packaging suppliers.
Market Dynamics
Clean-label mandates from FDA and EU REACH are forcing packaged food manufacturers to abandon solvent-based laminates, triggering a wholesale restructuring of barrier film specifications across spice and seasoning supply chains. This regulatory compression is accelerating converter consolidation as smaller players lack capital to certify new material stacks.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is compelling converters to develop aluminum oxide barrier coatings for oleoresin preservation, creating first-mover advantages for certified suppliers.
- Ethnic meal kit proliferation:Direct-to-consumer spice subscriptions in the United States are normalizing single-serve pouch formats that demand high-speed form-fill-seal compatibility and eighteen-month shelf stability.
- Kerala-Gujarat processing clusters:India's export-grade turmeric and cardamom concentration is generating specialized packaging requirements for FSSAI-compliant migration-tested films serving European and North American buyers.
Market Restraints
- Aluminum oxide coating cost volatility:Sputtering equipment and vacuum deposition raw materials require capital commitments that exclude mid-tier converters from high-barrier spice segments.
- Ethylene vinyl alcohol supply concentration:EVOH resin production centers on Japanese and Korean petrochemical complexes, exposing seasoning packaging margins to freight and currency shocks.
- Multi-material recyclability dead-end:Laminated structures combining PET, aluminum, and polyethylene face mandatory extended producer responsibility fees in Germany and France with no near-term mechanical recycling pathway.
Strategic Opportunities
- Paperboard dry rub formats:Retailer mandates eliminating non-recyclable constructions are opening share for fiber-based seasoning packaging with heat-seal barrier coatings.
- Herbal extract pharmaceutical crossover:Standardized extract brands serving nutraceutical end-uses are adopting pharmaceutical-grade blister and bottle formats that command price premiums over food-grade alternatives.
- Foodservice bulk canister innovation:Rigid composite containers with tamper-evident closures and moisture scavenger inserts are capturing institutional procurement contracts for seasoning blend distributors.
Industry Challenges
- Migration testing certification backlog:FSSAI's explicit testing requirements for printed plastic films contacting ground spices have created six-to-nine-month approval queues at accredited Indian laboratories.
- Legacy form-fill-seal retrofit requirements:Transition from standard polyethylene to high-barrier coextrusions demands line speed recalibration and seal jaw temperature reprogramming that interrupts contract packaging operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market |
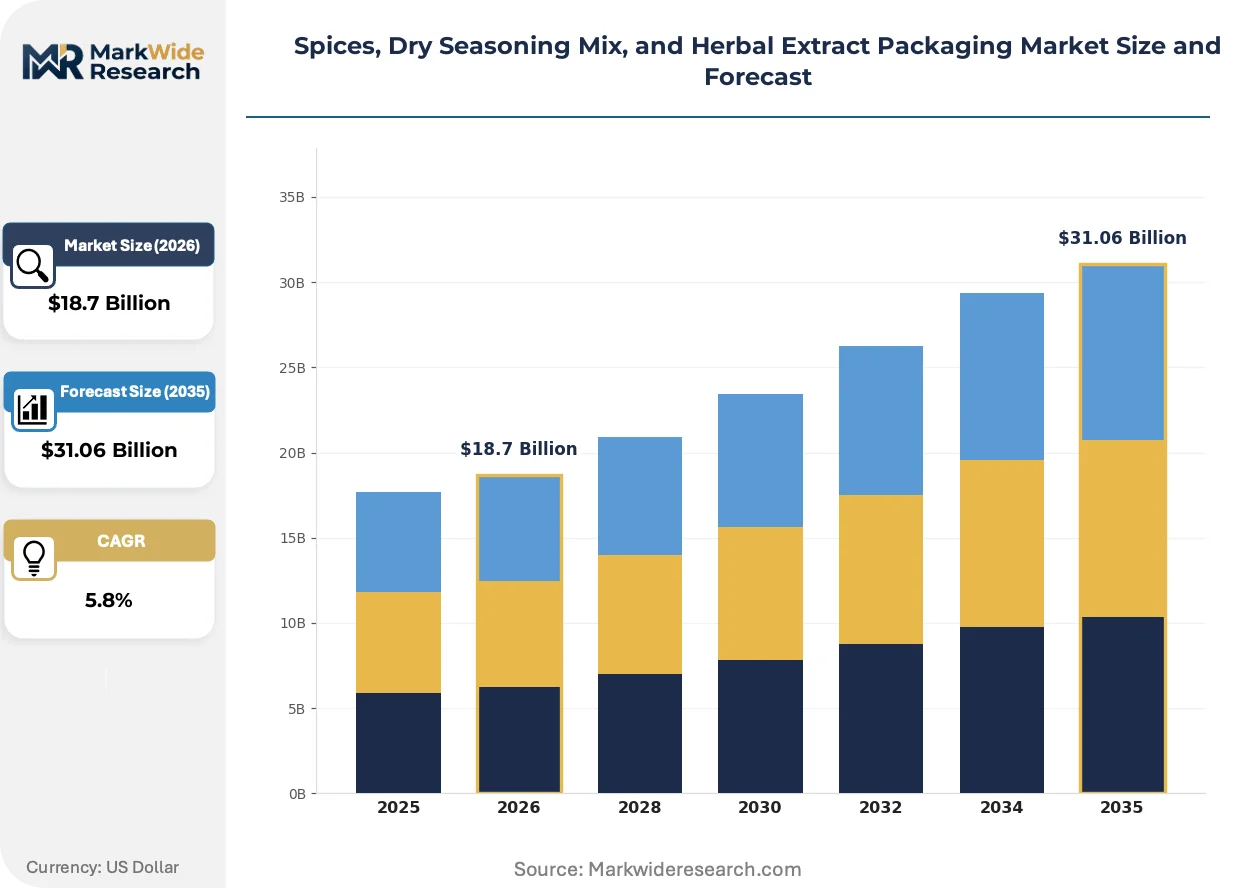
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Pouches, Jars, Sachets Material: Glass, Plastic, Metal, Paperboard Size: Small, Medium, Large, Bulk Closure Type: Screw Cap, Flip Top, Lid, Sealed |
| Companies Covered | Amcor Group GmbH, Berry Global Group, Winpak Ltd, ALPLA Group, Mondi Plc, Sealed Air Corporation, Sonoco Products Company, Constantia Flexibles, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market Trends and Innovations
Active barrier technologies and substrate substitution are compressing traditional laminate architectures while regulatory chemistry bans force material science reinvention across volatile oil packaging applications.
High-oxygen-barrier coextrusion incorporating discrete ethylene vinyl alcohol layers is consolidating the premium spice and herbal extract segment as clean-label brands abandon solvent-based adhesive laminates. North American and European seasoning manufacturers are adopting these structures at accelerated pace to preempt FDA food contact substance notification rejections and EU REACH compliance penalties. The technology is consolidating converter market share toward capital-intensive specialists with in-house multilayer blown film capabilities.
EU F-Gas Regulation constraints on fluorinated barrier treatments are eliminating perfluorinated chemistry options for moisture and grease resistance in paperboard seasoning formats. Industrial consequence includes forced migration to bio-based waxes and polysaccharide coatings that trade some barrier performance for regulatory compliance. Private-label herbal extract brands in Germany and France are most affected, responding with supplier diversification toward Scandinavian converters pioneering cellulose nanofiber alternatives.
Direct procurement of certified packaging by spice processing clusters is disintermediating traditional distributor channels as Kerala and Gujarat exporters seek FSSAI-validated film supplies with pre-cleared migration documentation. The disruption compresses margins for regional trading houses that historically sourced commodity polyethylene. This pattern is most visible in turmeric and cardamom export corridors where European buyers now mandate supplier-specific compliance files rather than generic material certificates.
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market Segmentation
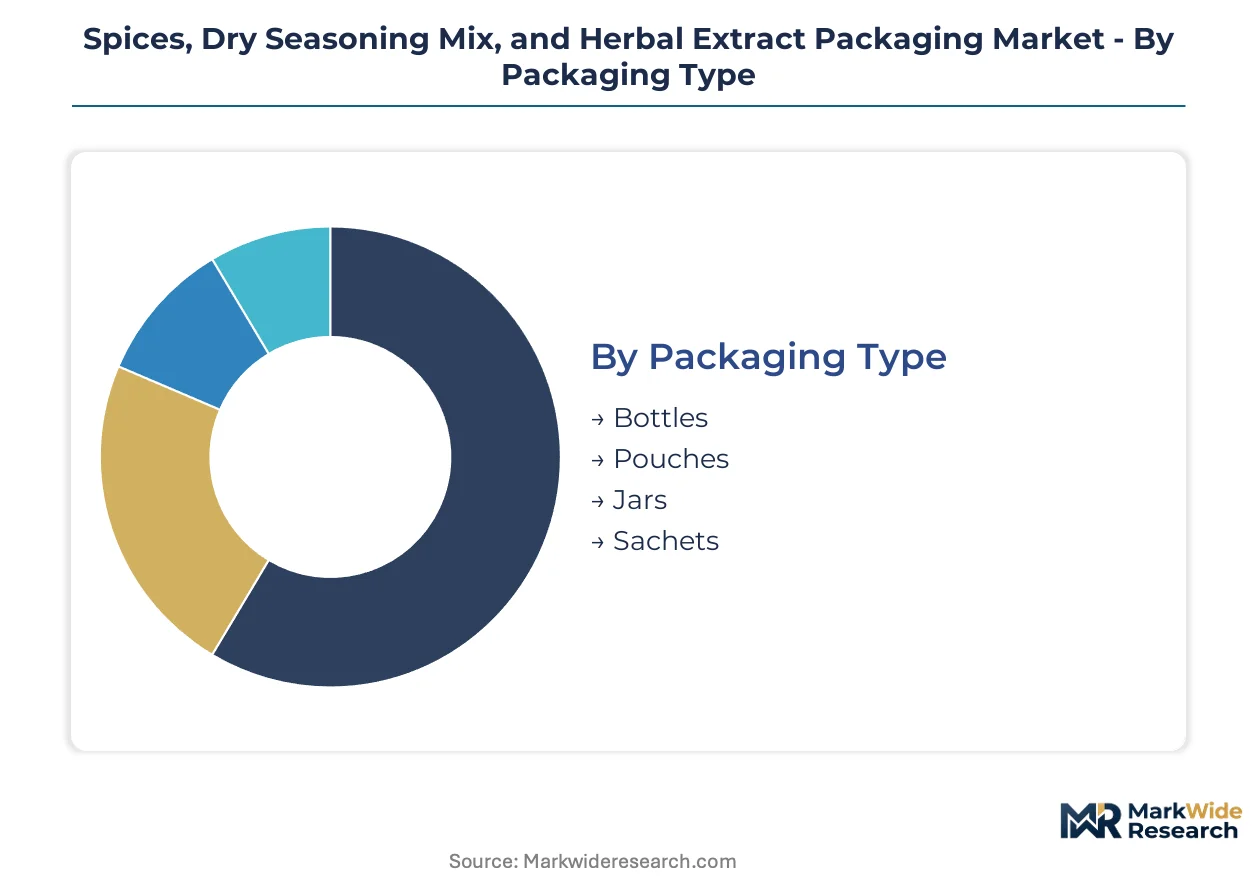
Packaging specifications for spices, dry seasoning mixes, and herbal extracts diverge sharply across end-use applications, with regulatory compliance requirements and barrier performance needs driving segment selection. Material and format choices directly determine shelf stability, migration safety certification, and recyclability positioning in target markets.
Packaging Type:
Each format carries distinct certification burdens: bottles require FDA food contact substance notifications for closure sealants, while pouches face EU REACH scrutiny on adhesive laminates and sachets trigger FSSAI migration testing for printed films contacting ground spices.
- Pouches:Laminated flexible structures with aluminum oxide or EVOH barriers dominate single-serve ethnic meal kits and direct-to-consumer spice subscriptions. Demand concentrates in the United States where eighteen-month shelf stability specifications and high-speed form-fill-seal compatibility reshape procurement patterns for seasoning blend distributors.
- Bottles:Glass and rigid plastic formats with tamper-evident closures preserve volatile essential oils in premium retail channels. European private-label herbal extract brands favor these structures for transparency and reusability positioning that commands price premiums over commodity alternatives.
- Jars:Wide-mouth rigid containers accommodate scoop access for dry rubs and seasoning blends in foodservice applications. These formats face retailer mandates eliminating non-recyclable multi-material constructions across German and French markets.
- Sachets:Single-portion foil or metallized film packets serve institutional food manufacturers and airline catering. Kerala and Gujarat export processors specify FSSAI-validated films with pre-cleared migration documentation for turmeric and cardamom shipments to European buyers.
Leading the category by volume: Pouches. Growing fastest: Sachets.
Material:
Cost tier stratification separates pharmaceutical-grade specifications from commodity food-grade alternatives, with barrier coating investments determining margin capture.
- Plastic:Multi-layer coextrusions incorporating discrete EVOH layers consolidate premium spice segments as clean-label brands abandon solvent-based adhesive laminates. Japanese and Korean petrochemical supply concentration exposes margins to freight and currency volatility.
- Glass:Pharmaceutical-grade bottles and vials command price premiums in standardized herbal extract applications crossing into nutraceutical end-uses. These formats anchor premium retail positioning where transparency and chemical inertness justify higher unit economics.
- Paperboard:Fiber-based formats with heat-seal barrier coatings capture share as dry rub brands respond to retailer mandates eliminating non-recyclable constructions. EU F-Gas Regulation constraints force migration to bio-based waxes and polysaccharide coatings that trade some barrier performance for compliance.
- Metal:Rigid composite canisters with moisture scavenger inserts serve institutional procurement contracts for bulk seasoning blend distributors. These structures require capital-intensive sputtering equipment that excludes mid-tier converters from high-barrier segments.
Highest margin capture: Glass. Fastest volume expansion: Paperboard.
Size:
Customer type segmentation separates direct-to-consumer subscription models from foodservice institutional procurement with diverging order profile economics.
- Small:Single-serve and trial-size formats align with ethnic meal kit proliferation and spice subscription services. These specifications demand precise form-fill-seal line calibration for high-speed pouch production.
- Medium:Standard retail sizes for household seasoning blends balance shelf presence with handling convenience across supermarket and specialty store channels.
- Large:Club store and family-size formats concentrate in North American retail where volume pricing and extended use cycles dominate purchasing behavior.
- Bulk:Foodservice and industrial quantities require rigid composite canisters with tamper-evident closures and moisture management systems for institutional seasoning blend distributors.
Volume concentration: Medium. Steepest expansion trajectory: Small.
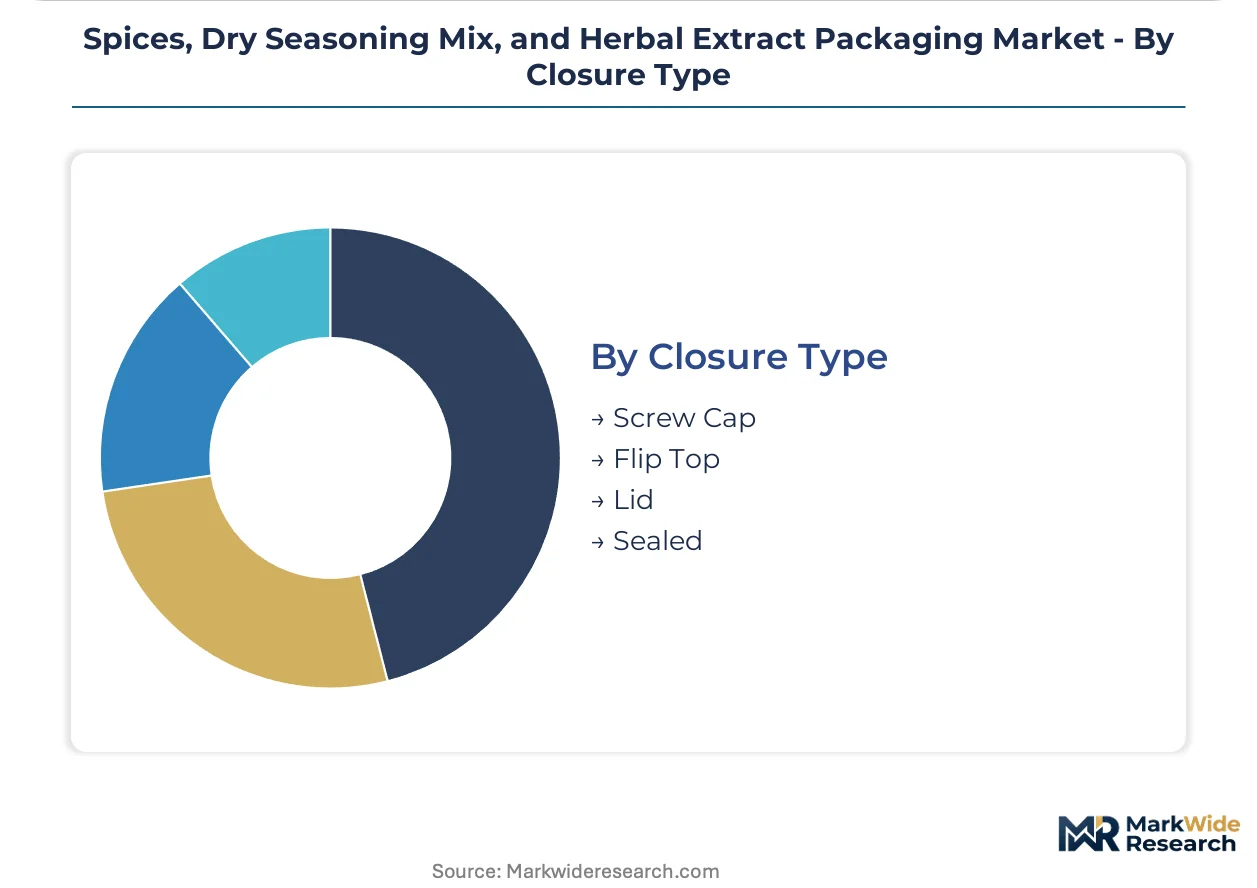
Closure Type:
Application-specific sealing performance determines volatile oil retention and moisture ingress resistance across eighteen-month shelf life requirements.
- Screw Cap:Precision-threaded closures with induction seals dominate glass bottle applications for premium herbal extracts where resealability and tamper evidence support repeat purchase positioning.
- Flip Top:One-handed dispensing convenience drives adoption in kitchen-counter seasoning blends where frequent access patterns prioritize ergonomic design over maximum barrier performance.
- Lid:Snap-fit and threaded lids for jars accommodate scoop access in foodservice dry rub applications with less stringent oxygen barrier requirements than volatile oil formats.
- Sealed:Heat-sealed and induction-sealed closures for pouches and sachets provide hermetic integrity for single-serve portions where package opening coincides with complete product consumption.
Widest application coverage: Screw Cap. Gaining share fastest: Sealed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kerala and Gujarat anchor spice processing activity, driving specialized packaging demand across export corridors to North America and Europe while regulatory divergence shapes converter strategies in each destination market.
United States
Ethnic meal kit subscriptions and direct-to-consumer spice brands normalize single-serve pouch formats. FDA food contact substance notifications govern barrier additive approvals for laminated structures. Seasoning blend distributors in the Midwest and California demand eighteen-month shelf stability specifications with high-speed form-fill-seal compatibility.
Germany
Private-label herbal extract brands favor paperboard-based sustainable formats for premium retail positioning. EU F-Gas Regulation constraints eliminate fluorinated barrier treatments, forcing migration to bio-based waxes and polysaccharide coatings. Extended producer responsibility frameworks in Germany redistribute recycling cost liability upstream to brand owners.
India
Export-grade turmeric and cardamom concentration in Kerala and Gujarat generates FSSAI-compliant packaging requirements. India's FSSAI packaging safety standards mandate explicit migration testing for printed plastic films contacting ground spice surfaces. Processing clusters now procure certified packaging directly, disintermediating traditional distributor channels.
France
Retailer mandates eliminating non-recyclable multi-material constructions accelerate paperboard format adoption for dry rub brands. EU REACH constraints on solvent-based adhesive chemistries tighten compliance costs for seasoning packaging converters. French herbal extract brands diversify suppliers toward Scandinavian converters pioneering cellulose nanofiber barrier alternatives.
United Kingdom
Premium retail channels sustain glass bottle demand where transparency and reusability command price premiums. Post-Brexit regulatory divergence creates parallel compliance tracks for spice packaging sold into UK versus EU markets. London-based seasoning distributors face dual certification burdens for barrier film specifications.
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology certification and clean-label compliance capabilities. Converter consolidation accelerates as smaller participants lack capital to certify new material stacks under tightening FDA and EU REACH mandates. Three archetypes dominate: capital-intensive multi-layer coextrusion specialists, paperboard-based sustainable format innovators, and rigid composite canister manufacturers serving foodservice bulk distribution. Dominant competitive moves include strategic partnerships with spice processing clusters for pre-cleared migration documentation and capacity expansion in aluminum oxide barrier coating capabilities.
Among European-based packaging groups, Mondi Plc and Constantia Flexibles occupy positions within the sustainable format tier, while Sonoco Products Company anchors North American bulk canister supply. Amcor Group GmbH exemplifies the capital-intensive specialist archetype with multi-layer coextrusion capabilities. These three entities represent divergent strategic responses to regulatory compression across solvent-based laminate prohibitions and fluorinated barrier treatment phaseouts.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Group |
| Winpak Ltd |
| ALPLA Group |
| Mondi Plc |
| Sealed Air Corporation |
| Sonoco Products Company |
| Constantia Flexibles |
| Amcor Plc |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up converter specialists have consolidated barrier film capacity across North America and Europe, tightening pricing discipline as capital-intensive aluminum oxide coating assets concentrate in fewer hands. This ownership pattern feeds directly into supply behavior, with rolled-up entities leveraging scale to extract preferential EVOH resin allocations while passing through coating cost volatility to seasoning blend distributors locked into eighteen-month shelf stability contracts.
Pricing Analysis
Value-based pricing anchored to oleoresin potency preservation commands premiums across pharmaceutical-grade herbal extract applications. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-validated migration-tested films from commodity polyethylene and uncoated paperboard alternatives. Price differentiation rests on certification tier and barrier performance grade. Pricing pressure stems from EVOH resin supply concentration in Japanese and Korean petrochemical complexes exposing margins to freight cost shocks. Foodservice bulk buyers exhibit highest price sensitivity, while premium retail herbal extract brands absorb premiums for pharmaceutical-grade glass and validated coextrusion structures.
Supply Chain Analysis
Direct procurement channels from Kerala and Gujarat processing clusters to certified converters are displacing traditional distributor networks for turmeric and cardamom export corridors. Raw material dependencies center on EVOH resin, aluminum oxide sputtering targets, and bio-based wax coatings for paperboard formats. Supply chain risk concentrates in single-source vulnerability for vacuum deposition equipment servicing high-barrier spice segments. Distribution runs through institutional foodservice procurement, direct-to-consumer subscription fulfillment, and European private-label retail channels with diverging compliance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converter consolidation is accelerating as capital requirements for FSSAI migration testing certification and aluminum oxide barrier coating equipment exclude sub-scale participants. EU F-Gas Regulation phaseout of fluorinated treatments is compressing margins for solvent-dependent laminators unable to fund material stack reinvention.
For Market Incumbents: Cement barrier technology leadership through captive aluminum oxide sputtering capacity additions in South India proximate to Kerala-Gujarat processing clusters. Acquire FSSAI-pre-certified film suppliers to compress six-to-nine-month migration testing queues that threaten customer retention. Prioritize pharmaceutical-grade certification investments as herbal extract brands cross into nutraceutical end-uses demanding pharmaceutical-format packaging.
For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for Scandinavian converters pioneering cellulose nanofiber barrier alternatives to capture paperboard dry rub share. Target foodservice bulk canister innovation with moisture scavenger inserts, a segment where rigid composite expertise requirements have slowed incumbent adaptation. Lead with sustainability positioning backed by pre-cleared extended producer responsibility compliance documentation.
For Investors and Strategic Acquirers: Direct procurement patterns by Indian spice processing clusters is the leading indicator that distributor-disintermediated converter models will capture margin expansion across export corridors. Five-to-ten-year viability favors capital-intensive specialists with in-house multi-layer blown film capabilities and pre-cleared FSSAI migration documentation libraries. Monitor Kerala-Gujarat exporter supplier diversification announcements as inflection signal for certification-backlog resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin Sourcing | Japanese and Korean petrochemical supply concentration exposes seasoning packaging margins to freight and currency volatility. |
| Aluminum Oxide Barrier Coating Capacity Expansion | F-Gas Regulation phaseout eliminates fluorinated treatments, creating first-mover advantages for certified sputtering equipment operators. |
| FSSAI Pre-Certified Film Acquisition | Migration testing backlogs at accredited Indian laboratories threaten customer retention for export-grade turmeric and cardamom processors. |
| Pharmaceutical-Grade Format Certification | Standardized herbal extract brands crossing into nutraceutical end-uses command price premiums over food-grade alternatives. |
| Paperboard Heat-Seal Barrier Coating Innovation | Retailer mandates eliminating non-recyclable multi-material constructions open share for fiber-based seasoning packaging. |
Research Methodology
Document review covered FDA food contact substance notification filings, EU REACH substance restriction updates, FSSAI packaging safety standard amendments, and customs trade data for spice packaging film imports, complemented by interviews with converter operations directors, spice processor procurement heads, and retail category buyers. Secondary validation drew from SEC filings of publicly traded packaging groups, ECHA regulatory guidance documents, and Indian export promotion council trade statistics. Bottom-up demand modeling from end-use application specifications was triangulated against top-down market size reconciliation.
Segment-level value and volume trajectories across the analysis window were derived from material format adoption curves, regulatory compliance cost pass-through assumptions, and processing cluster capacity expansion announcements. The analytical framework modeled packaging type, material substrate, size tier, and closure configuration dimensions alongside regional regulatory cluster differentiation. CAGRs were computed from year-over-year growth rate convergence across demand-side and supply-side estimation approaches, with specific inputs including EVOH resin price indices and aluminum oxide coating equipment utilization rates.
The model assumes a particular technology adoption path for bio-based wax and polysaccharide barrier coatings; alternative pathways for cellulose nanofiber commercialization would alter the outlook for paperboard format penetration. Forecasts reflect assumptions regarding FSSAI migration testing queue resolution and EU extended producer responsibility fee implementation timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Global Disposable Plates Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Disposable Food Containers Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Food Green Packaging Market