
 Vietnam Data Center Cooling Market | 2026-2036
Vietnam Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Cooling Market Insights
Cloud service providers is expanding their footprint across northern and southern Vietnam, reshaping the buyer landscape for precision cooling systems. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale deployments near Hanoi. STULZ GmbH specializes in high-density cooling architectures suited to tropical humidity conditions. Huawei Technologies Co Ltd competes on modular delivery speed, compressing deployment timelines for domestic operators.
Vietnam data center cooling encompasses thermal management systems engineered to maintain server inlet temperatures between 18°C and 27°C under ambient conditions exceeding 35°C and relative humidity above 80%. These systems employ compressor-based refrigeration, evaporative cooling, and liquid heat rejection circuits to protect IT equipment from thermal-induced failure. Liquid-cooled configurations are capturing margin pools as rack densities exceed 30 kW in hyperscale facilities, while air-cooled systems still dominate enterprise and colocation tiers where legacy infrastructure constrains retrofit economics. Direct liquid cooling is accelerating fastest among cloud service providers seeking to optimize power usage effectiveness below 1.2.
Vietnam's Ministry of Information and Communications and the Ministry of Industry and Trade jointly govern data center licensing and energy consumption thresholds, pushing operators toward efficiency certifications and renewable power purchase agreements. The national technical regulation QCVN on energy efficiency for buildings shapes cooling equipment procurement specifications for new construction. Stakeholders must monitor how proposed amendments to power sector regulations treat direct renewable supply contracts for data center loads, as this will determine whether northern hydropower or southern solar assets become the preferred anchor for capacity expansion.
Market Dynamics
Liquid cooling architectures are compressing deployment timelines across Vietnam's hyperscale corridor, while the Ministry of Industry and Trade's renewable energy directives force operators to co-locate with hydropower assets in Bac Ninh and Thai Nguyen provinces.
Growth Catalysts
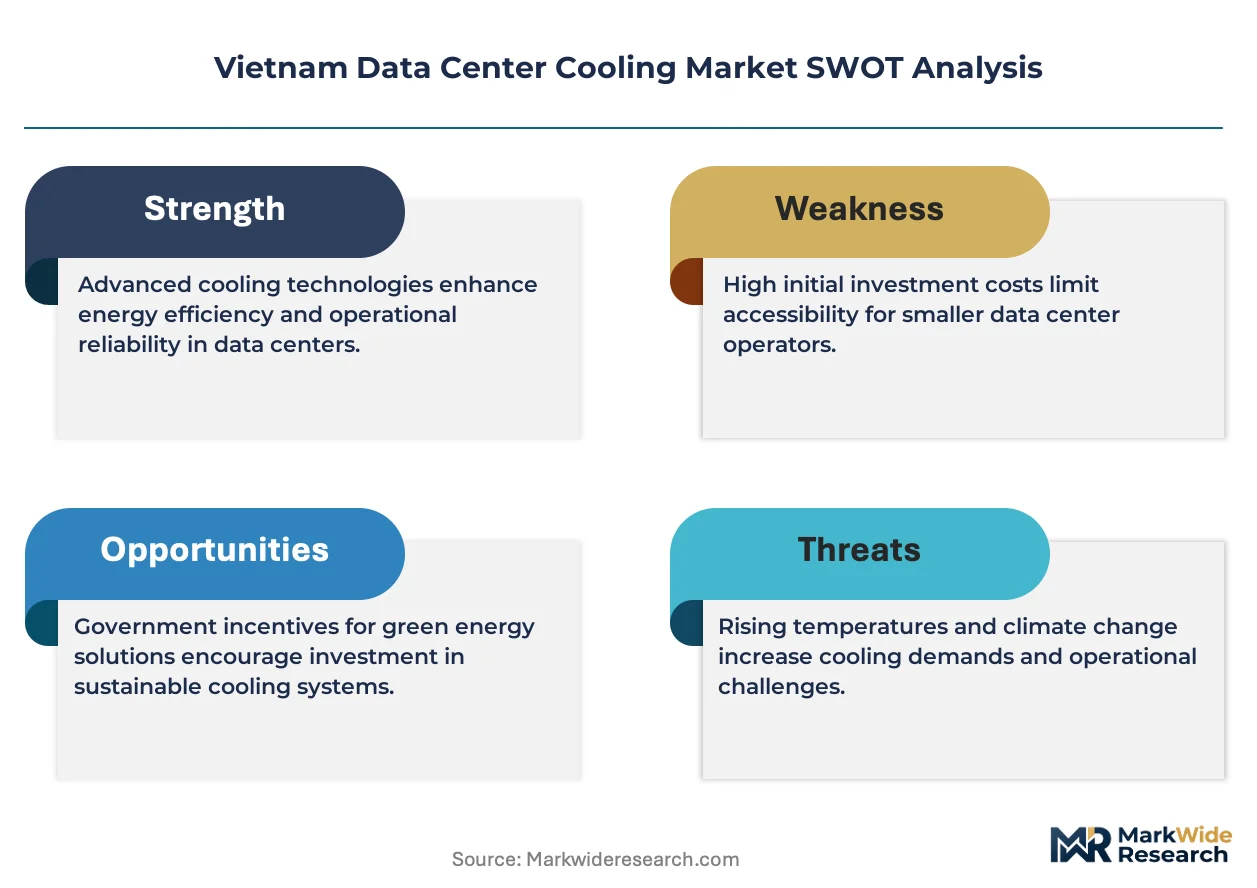
- QCVN Energy Efficiency Mandate:Vietnam's national technical regulation on building energy efficiency mandates efficiency certifications for new data center construction, accelerating precision cooling procurement specifications.
- Hyperscale Rack Density Thresholds:Cloud service providers deploying racks exceeding 30 kW are driving demand for direct liquid cooling systems that optimize power usage effectiveness below 1.2.
- Hydropower Proximity Clustering:Northern Vietnam's Bac Ninh-Thai Nguyen corridor concentrates liquid-cooled deployments near renewable assets, reducing carbon compliance costs for energy-intensive infrastructure.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger fabrication depends on copper tubing and aluminum fin stock, exposing cooling system margins to base metal price swings on the London Metal Exchange.
- Legacy Air-Cooled Infrastructure Lock-In:Enterprise and colocation facilities face prohibitive retrofit economics when upgrading from compressor-based refrigeration to liquid heat rejection circuits.
- Refrigerant Regulatory Friction:Vietnam's alignment with Kigali Amendment phase-down schedules restricts hydrofluorocarbon availability for expansion of existing air-cooled chiller fleets.
Strategic Opportunities
- Ho Chi Minh City Solar Integration:Southern Vietnam's solar irradiance profile offers underexploited potential for absorption chiller and evaporative cooling hybrids that reduce grid dependency.
- Modular Prefabrication Convergence:Factory-integrated power and cooling skids compress on-site construction timelines, enabling faster revenue recognition for domestic operators competing with international cloud entrants.
- Direct Power Purchase Agreement Liberalization:Proposed amendments to power sector regulations may permit data centers to contract directly with renewable generators, anchoring capacity expansion to northern hydropower or southern solar assets.
Industry Challenges
- Thermal-Fluid Engineering Talent Scarcity:Vietnam's technical education pipeline produces insufficient specialists in two-phase cooling, dielectric fluid management, and high-density heat rejection design.
- ISO 50001 Energy Management Certification Burden:Operators seeking efficiency credentials face 12-18 month compliance timelines that delay project financing and customer acquisition.
- Legacy Building Management System Integration Complexity:New liquid cooling loops must interface with existing SCADA and environmental monitoring infrastructure without triggering downtime during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Cooling Market |
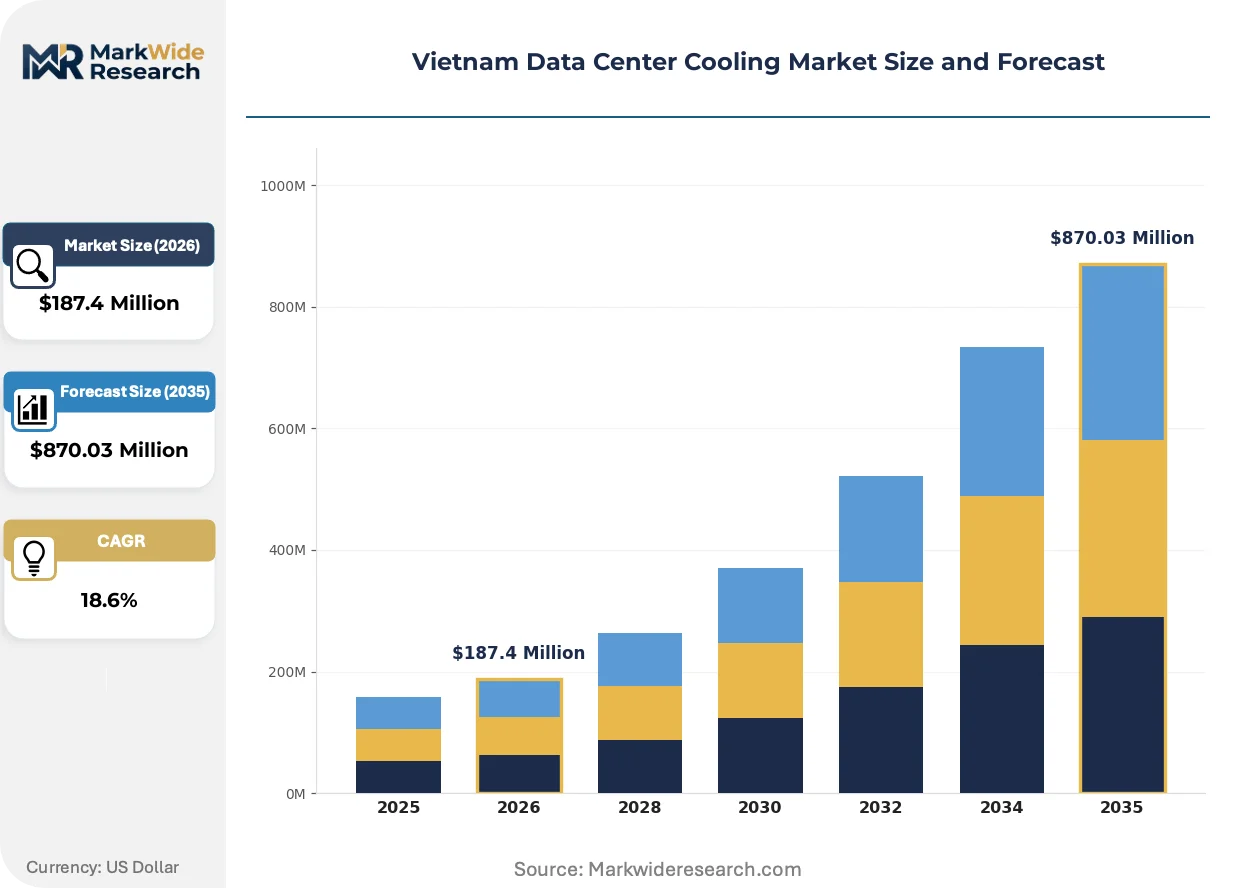
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Air-Cooled, Liquid-Cooled, Chilled Water, Direct Liquid Cooling Component Type: CRAC Units, Cooling Towers, Pumps, Heat Exchangers End User: Telecommunications, Cloud Service Providers, Colocation Facilities, Enterprises Deployment Model: On-Premises, Off-Premises, Hybrid Systems, Modular Data Centers |
| Companies Covered | Schneider Electric SE, Mitsubishi Electric Corporation, Rittal GmbH & Co. KG, Johnson Controls Inc., Daikin Industries Ltd, STULZ GmbH, Vertiv Group Corp., Huawei Technologies Co Ltd, Legrand SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Cooling Market Trends and Innovations
Cooling infrastructure in Vietnam is pivoting from site-built mechanical plants toward factory-integrated thermal systems that compress deployment risk and align with renewable energy co-location mandates.
Direct liquid cooling is modularizing across Vietnam's hyperscale facilities, replacing centralized chiller plants with rack-level heat capture loops that eliminate air-handling intermediaries. Cloud service providers in the Bac Ninh corridor are adopting these configurations fastest, compressing mechanical infrastructure deployment from 18 months to 8 weeks. This modularity is enabling rapid capacity scaling adjacent to hydropower substations without awaiting permanent building construction.
Vietnam's Ministry of Information and Communications is tightening licensing thresholds for data center energy consumption, requiring efficiency disclosures that favor liquid-cooled architectures in permit approvals. The regulation forces operators to document power usage effectiveness projections before construction begins, disadvantaging legacy air-cooled designs in competitive tenders. Northern provinces are responding with streamlined permitting for facilities demonstrating sub-1.3 PUE commitments tied to renewable power purchase agreements.
Domestic colocation buyers are consolidating vendor relationships around integrated power and cooling portfolios, displacing fragmented mechanical-electrical procurement. This concentration favors suppliers offering single-source responsibility for thermal performance guarantees, particularly among Vietnamese banks and manufacturers establishing captive data infrastructure. The shift is most visible in Hanoi, where financial institutions prioritize operational simplicity over lowest-first-cost equipment selection.
Vietnam Data Center Cooling Market Segmentation
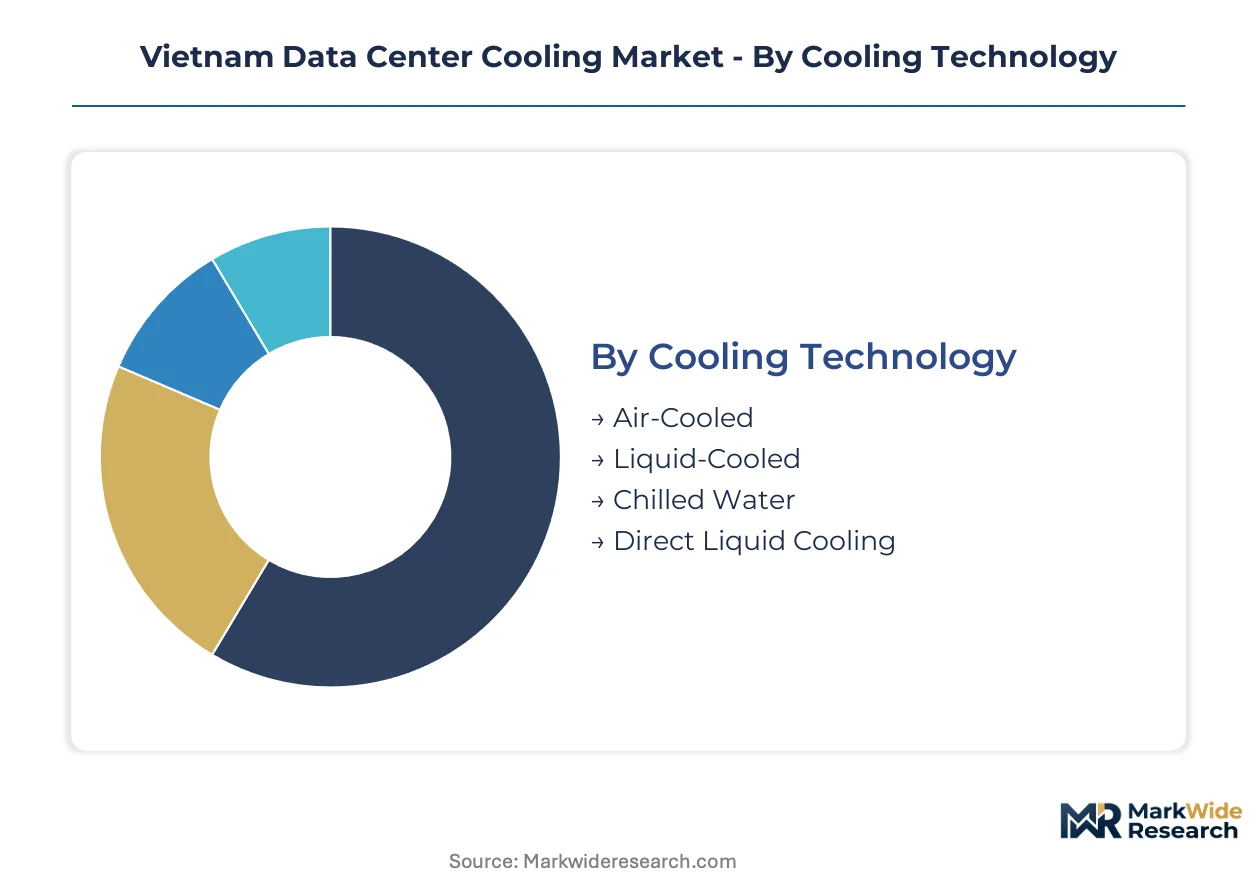
Segmentation of Vietnam's data center cooling market reveals how procurement decisions split between legacy air-cooled retrofits and next-generation liquid architectures. Understanding these divides exposes where margin pools concentrate and which technology transitions will reshape competitive positioning over the forecast window.
Cooling Technology:
Volume deployments still favor conventional refrigeration, but premium growth concentrates in direct liquid systems that compress power usage effectiveness below 1.2.
- Air-Cooled:Compressor-based refrigeration systems with outdoor condensing units dominate enterprise and colocation tiers where legacy infrastructure constrains retrofit economics. Demand concentrates in Ho Chi Minh City's established facilities, constrained by QCVN energy efficiency mandates that disadvantage air-cooled designs in new permit approvals.
- Liquid-Cooled:Direct-to-chip and immersion configurations capture heat at the server level using dielectric fluids or water-glycol mixtures. Bac Ninh-Thai Nguyen hyperscale corridors drive procurement, anchored by hydropower proximity that reduces carbon compliance costs for energy-intensive infrastructure.
- Chilled Water:Centralized chiller plants with air-handling units serve mid-density facilities requiring 15-30 kW per rack.
- Direct Liquid Cooling:Rack-level heat capture loops eliminate air-handling intermediaries entirely, compressing mechanical infrastructure deployment from 18 months to 8 weeks.
Today's leader: Air-Cooled. Tomorrow's challenger: Direct Liquid Cooling.
Component Type:
Procurement patterns reveal integrated portfolio consolidation, with buyers favoring single-source thermal performance guarantees over fragmented mechanical-electrical sourcing.
- CRAC Units:Computer room air conditioners with precision humidity control remain the workhorse for legacy facility upgrades. Hanoi financial institutions prioritize operational simplicity in captive data infrastructure, sustaining demand despite efficiency disadvantages.
- Cooling Towers:Evaporative heat rejection systems leverage Vietnam's tropical humidity for free cooling during monsoon months. Southern solar integration projects favor hybrid absorption chiller configurations that reduce grid dependency.
- Pumps:Circulation systems for liquid cooling loops require specialized engineering for two-phase cooling and dielectric fluid management.
- Heat Exchangers:Copper tubing and aluminum fin stock fabrication exposes margins to London Metal Exchange volatility.
CRAC Units anchor current procurement volumes. Cooling Towers present the steepest expansion trajectory as renewable-hybrid architectures proliferate.
End User:
Customer type determines density thresholds and retrofit willingness, splitting the market between greenfield hyperscalers and constrained legacy operators.
- Telecommunications:Carrier-grade facilities prioritize uptime over efficiency, sustaining air-cooled deployments despite higher operational expenditure. Regulatory pressure from the Ministry of Information and Communications tightens licensing thresholds, forcing efficiency disclosures.
- Cloud Service Providers:Hyperscale operators deploying racks exceeding 30 kW drive direct liquid cooling demand fastest. Bac Ninh corridor clustering near hydropower assets enables sub-1.3 PUE commitments that streamline permitting.
- Colocation Facilities:Multi-tenant economics constrain capital expenditure flexibility, locking in air-cooled infrastructure.
- Enterprises:Vietnamese banks and manufacturers establishing captive data infrastructure consolidate vendor relationships around integrated power and cooling portfolios.
Cloud Service Providers command technology leadership. Enterprises represent the largest untapped conversion opportunity as ISO 50001 certification burdens ease.
Deployment Model:
Construction modality separates time-to-revenue priorities, with factory integration compressing timelines for domestic operators competing against international cloud entrants.
- On-Premises:Site-built mechanical plants with permanent construction timelines suit established enterprises with predictable capacity requirements. Ho Chi Minh City and Hanoi anchor this segment.
- Off-Premises:Third-party colocation shifts capital burden to specialized operators, fragmenting cooling procurement across tenant specifications.
- Hybrid Systems:Mixed air-liquid configurations bridge legacy and next-generation infrastructure during phased facility upgrades.
- Modular Data Centers:Factory-integrated power and cooling skids enable rapid capacity scaling adjacent to hydropower substations without awaiting permanent building construction. Domestic operators leverage this modality to compress deployment timelines against international cloud entrants.
On-Premises retains installed base dominance. Modular Data Centers are gaining share fastest as renewable co-location mandates accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating data center cooling procurement in Vietnamese provinces where renewable energy access lowers compliance costs against efficiency mandates. The Bac Ninh-Thai Nguyen corridor attracts hyperscale deployments through hydropower proximity, while southern provinces compete on solar integration potential.
Bac Ninh Province
Hyperscale cloud operators anchor liquid-cooled deployments near hydropower substations in this northern manufacturing hub. The Ministry of Industry and Trade's renewable energy directives reward facilities demonstrating sub-1.3 PUE commitments with streamlined permitting. Samsung Electronics and Foxconn supplier ecosystems generate co-location demand for precision cooling infrastructure.
Thai Nguyen Province
Industrial park developers in this northern province target data center operators with dedicated renewable power purchase agreements. Vietnam's revised National Power Development Plan designates this corridor for energy-intensive infrastructure clustering. Liquid-cooled rack densities exceeding 30 kW concentrate near Tien Phong and Song Cong industrial zones.
Hanoi Capital Region
Financial institutions and telecommunications carriers sustain air-cooled demand in established facilities constrained by retrofit economics. The Ministry of Information and Communications tightens licensing thresholds requiring efficiency disclosures before construction permits. Cau Giay and Nam Tu Liem districts host captive data infrastructure for Vietnamese banks consolidating vendor relationships.
Ho Chi Minh City
Enterprise colocation and legacy telecommunications facilities dominate cooling procurement in Vietnam's southern commercial center. QCVN energy efficiency regulations disadvantage air-cooled designs in new permit approvals, accelerating hybrid system adoption. Thu Duc City and District 7 industrial parks explore solar-absorption chiller hybrids to reduce grid dependency.
Da Nang
Central Vietnam's emerging digital infrastructure hub attracts modular data center deployments seeking geographic diversification. The city's renewable energy mix combines hydropower from Quang Nam province with coastal wind development. Hoa Xuan and Hoa Khanh industrial zones target domestic operators compressing deployment timelines against international cloud entrants.
Vietnam Data Center Cooling Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated portfolio vendors capturing hyperscale tenders while component fabricators serve retrofit demand. The supplier base organizes around three archetypes: European industrial conglomerates with power-cooling integration capabilities, Asian electronics manufacturers competing on modular delivery speed, and specialized thermal engineering firms targeting high-density architectures. Consolidation pressure is intensifying through strategic partnerships between cooling vendors and renewable energy developers, alongside geographic expansion into provincial industrial zones.
Among European-based industrial groups, Schneider Electric SE and Rittal GmbH & Co. KG exemplify the integrated portfolio archetype, anchoring large-scale deployments through single-source thermal performance guarantees. STULZ GmbH occupies a specialist position in high-density cooling architectures, while Huawei Technologies Co Ltd represents the Asian modular delivery model compressing deployment timelines for domestic operators. These three companies illustrate how competitive positioning splits between comprehensive system integration and targeted technical specialization across Vietnam's cooling procurement landscape.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Rittal GmbH & Co. KG |
| Johnson Controls Inc. |
| Daikin Industries Ltd |
| STULZ GmbH |
| Vertiv Group Corp. |
| Huawei Technologies Co Ltd |
| Legrand SA |
| Others |
Pricing and Supply Chain Analysis
Thermal-fluid engineering talent scarcity in Vietnam's Bac Ninh-Thai Nguyen corridor compresses labor-cost differentials between liquid-cooled premium deployments and air-cooled economy retrofits, widening pricing-tier spreads as hyperscale operators absorb specialist premiums while enterprise buyers face retrofit economics constraints.
Pricing Analysis
Distributor margins for precision cooling equipment in Vietnam typically range from 15-25 percent for international brands, with direct-to-OEM contracts compressing channel layers for hyperscale cloud providers securing volume commitments. Three-tier pricing structure across premium liquid-cooled, standard chilled-water, and economy air-cooled levels reflects certification grade differentiation under QCVN energy efficiency mandates and after-sales service bundling. Pricing pressure stems from copper and aluminum input volatility on the London Metal Exchange, squeezing heat exchanger fabrication margins. Enterprise colocation facilities exhibit highest price sensitivity due to multi-tenant capital expenditure constraints, while cloud service providers prioritize performance guarantees over first-cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with China's dominance in dielectric fluid production and precision pump manufacturing for liquid cooling loops. Vietnam's data center cooling supply chain draws from China, South Korea, and Germany for compressors, heat exchangers, and control systems respectively. Copper tubing and aluminum fin stock dependencies expose margins to base metal price swings, while refrigerant availability faces regulatory restriction under Kigali Amendment phase-down schedules. Distribution runs through integrated power and cooling portfolio vendors capturing hyperscale tenders, with component fabricators serving fragmented retrofit demand via regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's data center cooling market offers margin expansion through modular prefabrication convergence compressing deployment timelines, while direct liquid cooling architectures command premium positioning as rack densities exceed 30 kW thresholds.
For Market Incumbents: Anchor integrated power and cooling portfolios through single-source thermal performance guarantees that displace fragmented mechanical-electrical procurement among Vietnamese banks and manufacturers establishing captive data infrastructure. Defend against Asian modular delivery competitors by compressing factory-integrated skid deployment timelines from 18 months to 8 weeks, leveraging certification investment under ISO 50001 energy management standards to lock in financial institution relationships in Hanoi's Cau Giay and Nam Tu Liem districts. For New Entrants and Emerging Players: Launch via factory-integrated modular data center deployments targeting Da Nang's Hoa Xuan and Hoa Khanh industrial zones, where geographic diversification demand meets underexploited renewable energy mixes combining Quang Nam hydropower with coastal wind development. Penetrate the Ho Chi Minh City solar integration opportunity through absorption chiller and evaporative cooling hybrids, offering colocation operators reduced grid dependency as QCVN regulations disadvantage air-cooled designs in new permit approvals. For Investors and Strategic Acquirers: European industrial conglomerates with power-cooling integration capabilities are the most active acquirer in this space, seeking Vietnamese distribution footprint and renewable energy co-location project pipelines. Target acquisition archetypes include specialized thermal engineering firms with two-phase cooling expertise and dielectric fluid management capabilities, given talent scarcity constraints. Monitor proposed amendments to Vietnam's power sector regulations permitting direct renewable supply contracts as the critical inflection signal determining whether northern hydropower or southern solar assets anchor capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Convergence | Factory-integrated power and cooling skids compress deployment timelines for domestic operators competing with international cloud entrants. |
| Direct Power Purchase Agreement Liberalization | Proposed regulatory amendments may permit data centers to contract directly with renewable generators, anchoring expansion to hydropower or solar assets. |
| Liquid Cooling Talent Pipeline Investment | Vietnam's technical education institutions require expanded thermal-fluid engineering programs to address two-phase cooling specialist scarcity. |
| ISO 50001 Certification Acceleration | Streamlined 12-18 month compliance timelines would reduce project financing delays and customer acquisition barriers for efficiency credentials. |
| Legacy Building Management System Integration | New liquid cooling loops must interface with existing SCADA infrastructure without triggering downtime during commissioning. |
Research Methodology
Bottom-up cloud service provider and enterprise demand modeling reconciled against top-down cooling equipment supply tracking forms the analytical core of this study. Primary interviews with data center operators, thermal engineering consultants, procurement officers at Vietnamese banks, and Ministry of Information and Communications licensing officials combined with secondary validation from QCVN regulatory filings, industrial park development databases, and renewable energy project disclosure records. Triangulation across stakeholder inputs and published sources ensures cross-verified market sizing.
Input-output matrices mapping cooling technology adoption rates against rack density thresholds, renewable energy co-location mandates, and permitting timelines generate volume and value outputs across the projection horizon. Segmentation dimensions modeled include cooling technology type, component category, end-user vertical, and deployment modality, with CAGRs derived from regression analysis of historical procurement patterns and forward-looking infrastructure investment announcements. Forecast inputs incorporate hyperscale facility pipeline tracking and hydropower substation proximity scoring for northern corridor clustering analysis.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to power sector direct contracting rules, abrupt base metal price dislocations on commodity exchanges, and geopolitical disruptions affecting dielectric fluid supply chains. Forecasts reflect documented assumptions about technology transition rates and renewable energy project completion schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market