
 Global Laptop Cooling Pads Market | 2026-2036
Global Laptop Cooling Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laptop Cooling Pads Market Outlook
The EU Green Deal is pivoting laptop cooling pad procurement toward lower standby power and recyclable material content. Corsair leverages its gaming peripheral ecosystem to bundle cooling solutions with high-performance notebook lines. Cooler Master anchors its position through thermal engineering heritage and workstation-grade product breadth. DeepCool competes aggressively on price-performance ratios in the entry-level gaming segment across Asian e-commerce channels.
Laptop cooling pads are active or passive thermal management accessories designed to dissipate heat from portable computers, typically incorporating one to six fans with airflow rates between 20 and 80 CFM, aluminum or plastic chassis construction, and ergonomic tilt angles to maintain processor and GPU thermal headroom during sustained workloads. Active cooling configurations dominate volume shipments due to their effectiveness with gaming and workstation laptops, while aluminum material variants command premium positioning based on superior thermal conductivity and durability perceptions. The gamer end-user segment drives the fastest structural expansion as esports participation and AAA title portability requirements intensify thermal stress on compact form factors.
The US EPA ENERGY STAR program and EU Ecodesign Directive constrain standby power draw and fan motor efficiency for electronics accessories sold in their respective jurisdictions, compelling redesigns of control circuitry and motor selection. China's GB standards and MIIT circular economy guidelines impose material recovery and hazardous substance limits on domestic production and import channels. Stakeholders must monitor evolving interoperability requirements between cooling pad USB power delivery and laptop USB-C charging protocols as standardization bodies harmonize specifications.
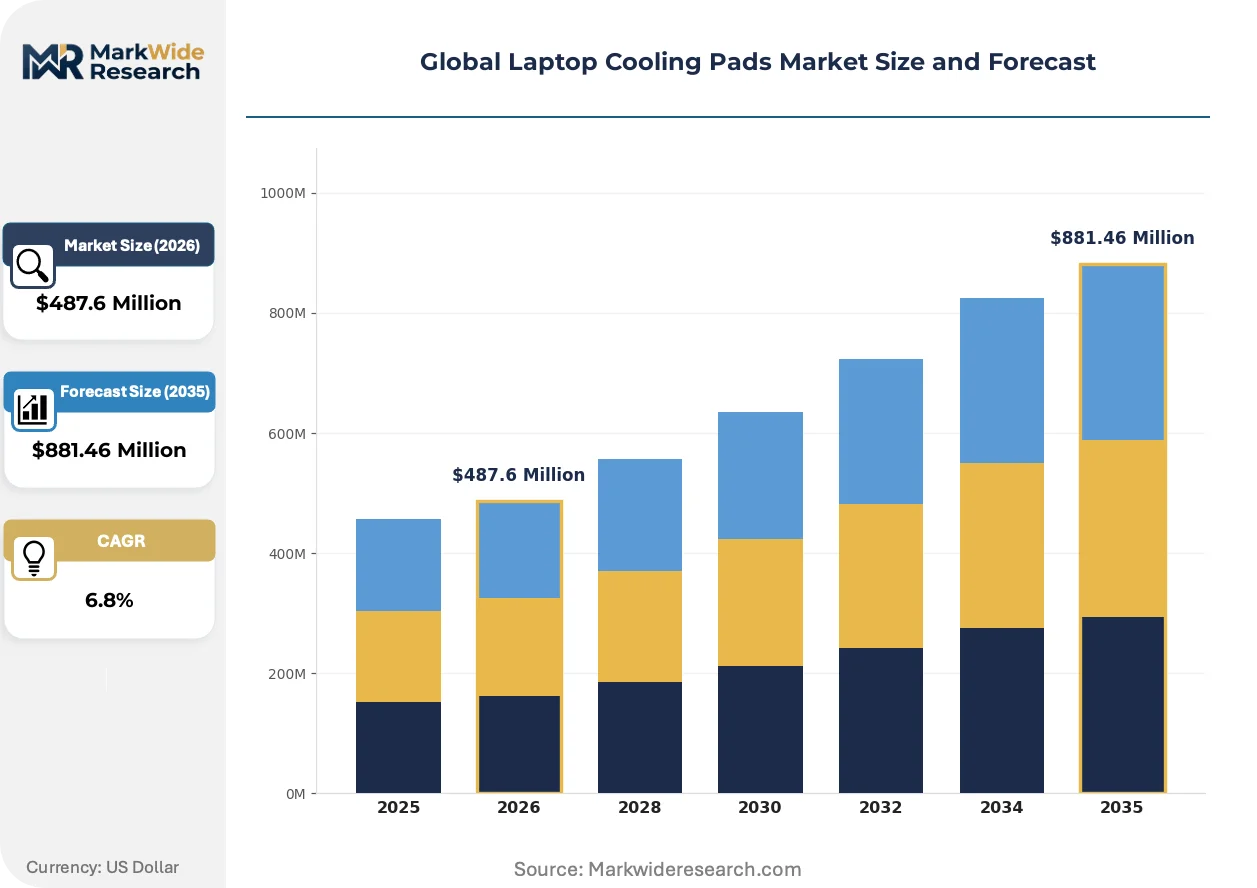
Market Dynamics
Thermal throttling in compact gaming laptops is forcing manufacturers to redesign cooling pad architectures around higher static pressure fans and vapor chamber compatibility, while EU Ecodesign standby power limits compel circuit-level efficiency investments.
Growth Catalysts
- USB-C Power Delivery harmonization:Standardized PD protocols between cooling pads and laptops eliminate adapter friction for mobile workstation users across North America and Western Europe.
- China's domestic OEM bundling:Native laptop manufacturers in the PRC are pre-installing cooling accessories with high-TDP gaming SKUs, normalizing category penetration.
- Aluminum chassis mandates:EU Green Deal circular economy requirements for recyclable content are accelerating metal substitution in premium tier manufacturing.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing for brushless DC motors clusters in China's Inner Mongolia region, creating single-source vulnerability for fan motor assemblies.
- Passive cooling substitution:Laptop manufacturers are integrating graphene thermal spreaders and liquid metal TIMs that reduce external accessory dependency in thin-and-light segments.
- REACH substance restrictions:ECHA limitations on halogenated flame retardants in plastics are forcing reformulation of ABS housings with costlier phosphorus-based alternatives.
Strategic Opportunities
- India's gaming café expansion:Tier-2 and Tier-3 cities are deploying shared high-performance laptop stations that require durable cooling infrastructure for 18-hour daily cycles.
- AI-driven thermal management:Convergence of embedded temperature sensors with machine learning algorithms enables predictive fan curves that differentiate premium offerings.
- Right-to-repair alignment:EU and US state-level repairability mandates create openings for modular cooling pad designs with user-replaceable bearings and filters.
Industry Challenges
- USB-IF certification backlog:Extended timeline for Power Delivery 3.1 compliance testing is delaying product launches by 4-6 months for multi-port designs.
- Acoustic engineering talent scarcity:Fan blade aerodynamics and psychoacoustic optimization expertise concentrates among Taiwanese and Japanese thermal specialists, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laptop Cooling Pads Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Cooling, Passive Cooling, Heat Dissipation, Hybrid Material: Plastic, Aluminum, Fabric, Wood Size: 15 Inch, 17 Inch, 19 Inch, Adjustable End User: Gamers, Students, Professionals, Casual Users |
| Companies Covered | Klim Technologies, Corsair, Cooler Master, Razer, Anker Innovations, Thermaltake, DeepCool, Zalman, Targus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laptop Cooling Pads Market Strategic Shifts
Cooling pad evolution is bifurcating between silent passive designs for professional environments and software-integrated active systems for competitive gaming, with material science and regulatory pressure as twin forcing mechanisms.
Thermoelectric Peltier modules are automating sub-ambient surface temperatures for overclocked GPU configurations. Enthusiast builders and esports competitors are adopting these solid-state cooling elements despite power draw penalties. The technology is automating precision thermal control previously achievable only through liquid cooling loops, compressing the performance gap between portable and desktop thermal solutions.
The EU Ecodesign Directive's 2025 standby power thresholds are forcing redesigns of control circuitry and motor drivers. Manufacturers must now implement zero-watt standby modes or face market exclusion across twenty-seven member states. Gaming-oriented SKUs with always-on RGB and controller hubs face the steepest engineering cost impacts.
Direct-to-consumer channel consolidation is displacing traditional electronics retail for accessory purchases. Amazon and specialized PC component marketplaces now capture the majority of cooling pad volume in North America and Western Europe. China's Tmall and JD.com domestic platforms concentrate even more dramatically, with live-stream commerce driving impulse purchases among younger demographics.
Global Laptop Cooling Pads Market Segmentation
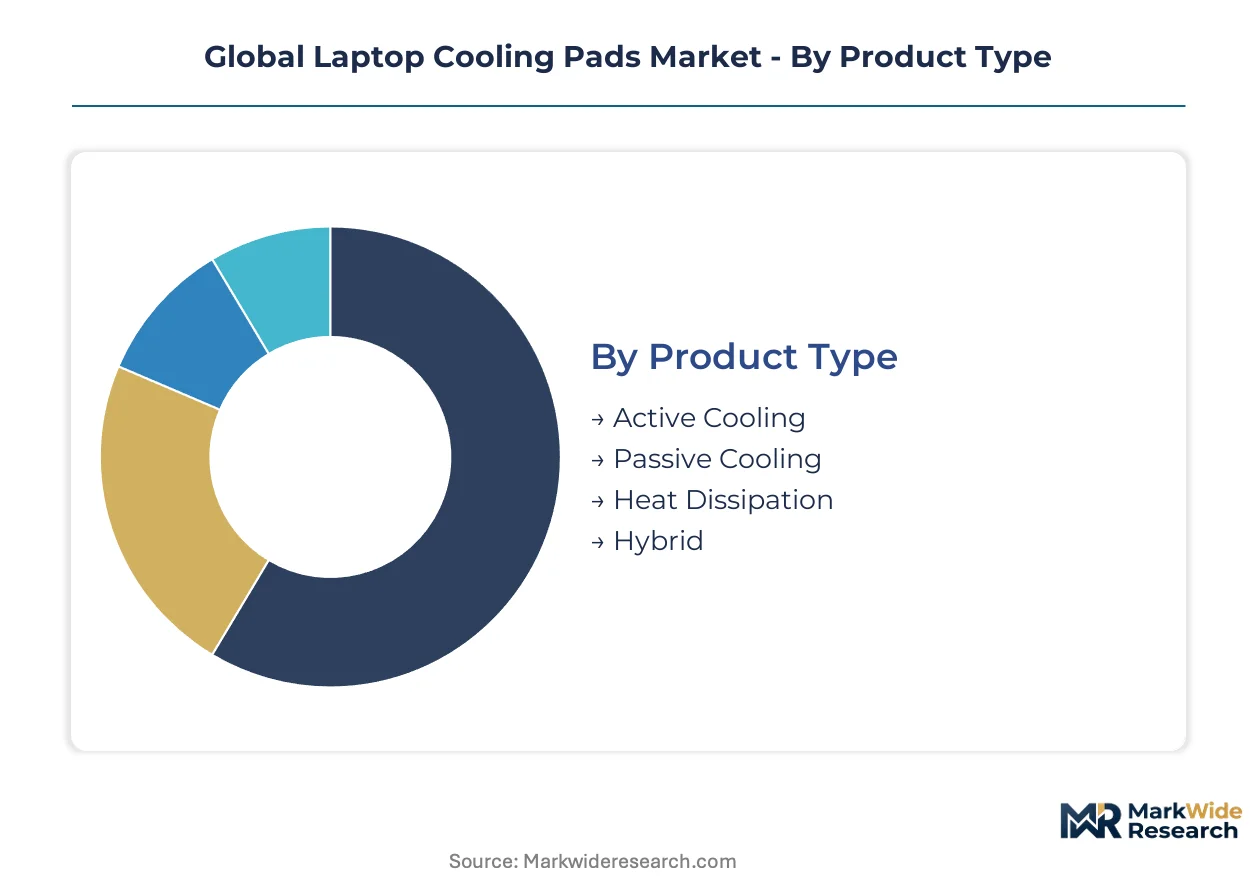
Segmentation in the laptop cooling pad market reveals how thermal management requirements diverge across use cases and form factors. Product architecture, material selection, and end-user workload intensity create distinct commercial pockets with varying margin profiles and certification burdens.
Product Type:
Active cooling configurations require FCC Part 15 electromagnetic compliance in the US and CE marking for EU market access, while passive designs face lighter regulatory loads concentrated on material safety through REACH and RoHS substance restrictions.
- Active Cooling:Configurations incorporate brushless DC fans delivering 20-80 CFM airflow, with USB-powered motor controllers subject to standby power limits under EPA ENERGY STAR and EU Ecodesign Directive thresholds. Gaming laptop users in China and the US drive volume concentration as thermal throttling concerns intensify with compact high-TDP chassis designs.
- Passive Cooling:Aluminum heat sinks and thermal conductive pads operate without electrical components, eliminating electromagnetic certification requirements but still facing EU Green Deal recyclable content mandates. Demand clusters among mobile professionals in Germany and Japan seeking silent operation for conference environments.
- Heat Dissipation:Specialized thermal interface materials and vapor chamber contact plates target workstation-grade laptops with sustained 45W+ processor loads.
- Hybrid:Combines active fan arrays with passive metal mass for thermal buffering, requiring dual compliance pathways for both electronic and material regulations.
Active cooling sits at the top of the volume ranking, with hybrid configurations climbing the fastest as manufacturers balance acoustic performance against thermal headroom requirements.
Material:
Material selection directly determines thermal conductivity performance and circular economy compliance exposure, with aluminum commanding premium positioning through superior heat dissipation coefficients and EU-mandated recyclability credentials.
- Aluminum:Extruded or CNC-machined chassis deliver thermal conductivity of 205 W/mK, enabling passive heat spreading without fan dependency. EU Green Deal ecodesign requirements for recyclable content are accelerating metal substitution in premium tier manufacturing across France, Italy, and the Netherlands.
- Plastic:ABS and polycarbonate housings offer cost advantages at scale but face REACH restrictions on halogenated flame retardants, forcing reformulation with phosphorus-based alternatives that raise unit costs.
- Fabric:Mesh textile surfaces prioritize portability and aesthetic customization for lifestyle-oriented consumers in South Korea and urban China.
- Wood:Bamboo and engineered timber variants target sustainability-conscious segments in Scandinavian markets with biogenic carbon storage appeals.
Plastic retains volume leadership through entry-level price accessibility, while aluminum gains share fastest on regulatory tailwinds and gaming segment thermal performance demands.
Size:
Form factor dimensions correlate with laptop OEM screen size standardization, with 15-inch and 17-inch formats dominating aftermarket replacement cycles while adjustable mechanisms capture multi-device households.
- 15 Inch:Matches the most common laptop display diagonal globally, supporting ultrabook and mainstream notebook thermal envelopes. Students in India and Brazil represent concentrated demand as education-sector laptop penetration deepens.
- 17 Inch:Accommodates desktop replacement gaming laptops with expanded cooling surface area requirements. Esports competitors in Poland and Mexico drive adoption for tournament-grade portable setups.
- 19 Inch:Oversized platforms target mobile workstation users running dual-GPU configurations in engineering and content creation workflows.
- Adjustable:Telescoping or modular designs span 13-inch to 18-inch device compatibility, appealing to multi-laptop households and commercial fleet managers in the US and UK.
15-inch formats anchor volume shipments, with adjustable mechanisms expanding most quickly as device fragmentation across households intensifies.
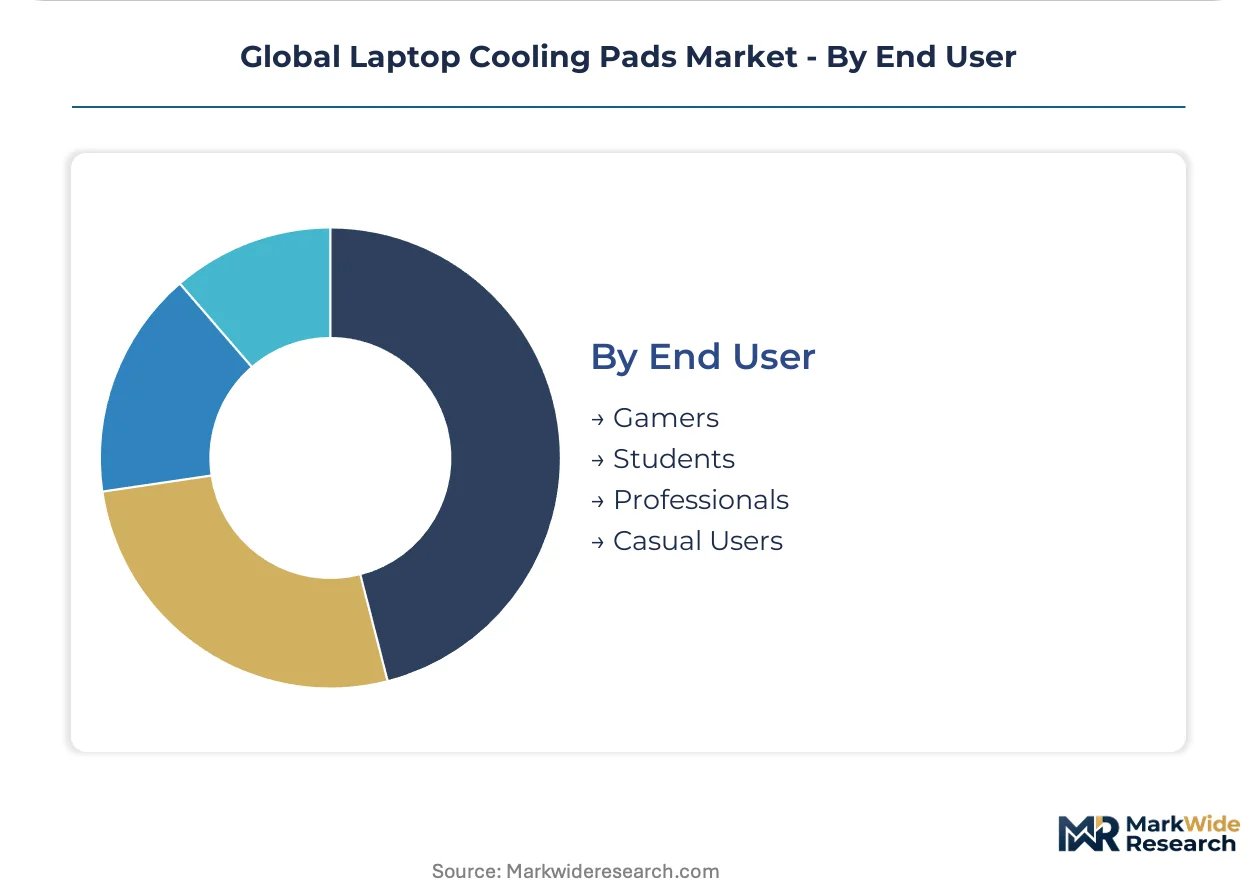
End User:
User segmentation maps thermal management intensity to price elasticity, with gamers accepting premium positioning for performance assurance while casual users prioritize entry-level accessibility.
- Gamers:Demands RGB integration, software-controllable fan curves, and static pressure optimization for sustained AAA title workloads. China's domestic OEM bundling with high-TDP gaming SKUs is normalizing category penetration among this cohort.
- Professionals:Prioritizes acoustic discretion and ergonomic tilt angles for extended productivity sessions. Financial services workers in Singapore and London drive demand for aluminum passive designs compatible with open-plan office noise protocols.
- Students:Price-sensitive segment concentrated in back-to-school purchasing cycles across North American and European retail channels.
- Casual Users:Sporadic thermal management needs for streaming and light productivity, with impulse purchase behavior amplified by live-stream commerce in China's Tmall and JD.com ecosystems.
Gamers command the steepest expansion trajectory, with professionals maintaining stable replacement-driven volume as hybrid work normalization persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's electronics contract manufacturing heritage established the thermal management accessory sector during the 1990s notebook PC boom. Foundries in Taipei and Taoyuan pioneered aluminum extrusion techniques for portable cooling hardware before production diversified across Asia-Pacific.
United States
Mobile workstation procurement by financial services and creative agencies sustains premium cooling pad demand in Manhattan and Los Angeles. The EPA ENERGY STAR program enforces standby power limits below 0.5 watts for USB-powered accessories. Austin's gaming peripheral cluster hosts multiple brands optimizing thermal solutions for esports tournament circuits.
China
Domestic OEM bundling with high-TDP gaming laptops normalizes cooling pad penetration among 400 million PC gamers. MIIT circular economy guidelines mandate material recovery rates for electronics accessories manufactured in Guangdong and Jiangsu. Shenzhen's component ecosystem integrates fan motor assemblies with Tmall and JD.com fulfillment infrastructure.
Germany
Professional users in Frankfurt and Munich prioritize silent aluminum passive designs for open-plan office environments. The EU Ecodesign Directive's 2025 standby power thresholds compel zero-watt circuit redesigns for active cooling products. Bavaria's industrial design studios specialize in ergonomic tilt mechanisms for mobile workstation fleets.
Japan
Corporate procurement policies in Tokyo and Osaka emphasize acoustic discretion for hybrid work settings. METI energy efficiency standards constrain fan motor power consumption in accessories sold domestically. Nagoya's precision manufacturing base supplies high-static-pressure impellers for compact gaming laptop compatibility.
India
Gaming café deployment across Bangalore and Hyderabad creates demand for durable cooling infrastructure operating 18-hour daily cycles. BIS certification requirements for electronic accessories extend product registration timelines by 8-12 weeks. Maharashtra's electronics manufacturing zone attracts assembly operations serving domestic e-commerce channels.
Global Laptop Cooling Pads Market Competitive Environment
Capital-heavy producers with captive aluminum extrusion and injection molding capacity compete with asset-light designers outsourcing fabrication to Shenzhen and Dongguan contract manufacturers. The vendor base stratifies across three tiers: integrated thermal specialists with fan motor R&D capabilities, gaming peripheral brands leveraging ecosystem bundling, and commodity assemblers competing on price-performance ratios. Dominant competitive moves include vertical integration into brushless DC motor production and strategic partnerships with laptop OEMs for pre-installation bundling.
Among the integrated thermal specialists, Cooler Master and DeepCool anchor the engineering-driven tier with heritage in workstation-grade thermal solutions. Corsair occupies a position exemplifying gaming ecosystem leverage, bundling cooling accessories with high-performance notebook lines and RGB-integrated peripheral suites. These three entities represent distinct archetypes: manufacturing depth, gaming brand extension, and price-performance optimization respectively.
| Leading Market Players |
|---|
| Klim Technologies |
| Corsair |
| Cooler Master |
| Razer |
| Anker Innovations |
| Thermaltake |
| DeepCool |
| Zalman |
| Targus |
| Others |
Value Chain & Pricing Dynamics
Aluminum extrusion automation in Guangdong and Jiangsu provinces is compressing unit economics for premium chassis while concentrating fabrication capacity among mid-tier contract manufacturers with captive metalworking capabilities. This production-method transition simultaneously reduces per-unit aluminum processing costs and tightens supplier bargaining power for brands lacking direct foundry relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aluminum-clad gaming SKUs with USB-C PD 3.1 certification from plastic-bodied entry models and unbranded white-label commodities. Price differentiation rests on thermal conductivity certification and fan motor efficiency tier under EPA ENERGY STAR thresholds. Cost compression in the economy tier is intensifying because Shenzhen contract manufacturers are absorbing margin pressure to maintain volume throughput. Students and casual users in India and Brazil exhibit highest price sensitivity, while esports competitors in Poland and Mexico accept premium positioning for static pressure performance.
Supply Chain Analysis
China's MIIT circular economy guidelines and India's PLI scheme for electronics manufacturing are reshaping component sourcing toward domestic-content compliance in both assembly and raw material channels. Brushless DC motor production clusters in China, Taiwan, and Vietnam, with rare earth magnet processing concentrated in Inner Mongolia. Raw material dependencies include aluminum billet, neodymium-iron-boron magnets, and ABS thermoplastics facing REACH reformulation costs. Single-source vulnerability runs through Inner Mongolia rare earth processing for high-performance fan motors. Distribution runs through Amazon and Tmall direct-to-consumer platforms, displacing traditional electronics retail in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by gamer demand-shift toward aluminum chassis with vapor chamber compatibility and sub-10 dB acoustic profiles. Premium specification migration favors manufacturers with captive thermal engineering capabilities.
For Market Incumbents: Anticipate passive cooling substitution from graphene thermal spreaders and liquid metal TIMs by deepening R&D partnerships with laptop OEMs for co-designed thermal solutions. Prioritize backward integration into brushless DC motor production to defend against neodymium supply concentration in Inner Mongolia. Secure USB-IF certification capacity early to avoid Power Delivery 3.1 compliance delays.
For New Entrants and Emerging Players: AI-driven thermal management with embedded temperature sensors and machine learning fan curves offers a technology-first wedge against established brands relying on manual control software. Target India's gaming café infrastructure in Bangalore and Hyderabad with durable 18-hour cycle-rated designs. Pursue right-to-repair modular architectures with user-replaceable bearings as a go-to-market angle in EU markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among aluminum extrusion specialists with dormant gaming peripheral brand assets and underutilized CNC capacity. Long-term viability hinges on regulatory tailwinds from EU Ecodesign recyclable content mandates and USB-C harmonization. Target acquisition archetype: Taiwanese thermal engineering firms with heritage workstation-grade product breadth and dormant consumer channel relationships. Watch USB-IF certification backlog resolution as inflection indicator for multi-port product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive brushless DC manufacturing mitigates Inner Mongolia rare earth concentration risk. |
| USB-C PD 3.1 Certification Investment | Early compliance clears 4-6 month backlog delays for multi-port gaming SKUs. |
| OEM Bundling Partnership | Pre-installation with high-TDP gaming laptops normalizes category penetration in China. |
| Right-to-Repair Modular Design | User-replaceable bearings and filters align with EU and US state-level repairability mandates. |
| AI Thermal Management Platform | Predictive fan curves differentiate premium offerings against manual control competitors. |
Study Parameters
Coverage spans North America, Western Europe, Asia-Pacific, and India, with primary inputs from each region combining structured interviews with thermal engineering directors, gaming peripheral brand managers, laptop OEM procurement leads, and Shenzhen contract manufacturing executives alongside secondary validation. Secondary sources include EPA ENERGY STAR certification databases, EU Ecodesign Directive implementation guidance, MIIT circular economy policy circulars, USB-IF compliance filings, and customs trade data for aluminum extrusion and brushless DC motor trade flows. Bottom-up unit economics modeling triangulates against top-down category spend estimates from e-commerce platform data.
Rate-of-change decomposition separates volume growth from mix-shift toward premium aluminum configurations and active cooling with higher ASPs across the analysis window. Segmentation dimensions modeled include product architecture, material composition, form factor size, and end-user workload intensity. CAGRs derive from logistic adoption curves for USB-C PD harmonization and gamer penetration rates. Industry-specific forecast inputs incorporate thermal design power trajectories from laptop OEM roadmaps and EU Ecodesign standby power threshold implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruption, passive cooling technology substitution rates, and USB-IF certification timeline volatility. Forecasts reflect assumptions around regulatory implementation pacing and laptop TDP evolution without guaranteeing specific outcomes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Middle East District Cooling Market