
 Germany Data Center Cooling Market | 2026-2036
Germany Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Cooling Market Insights
Hyperscale cloud operators is bifurcating demand away from traditional enterprise colocation buyers across Germany's data center landscape. STULZ leverages its precision air conditioning heritage to dominate mission-critical infrastructure deployments. Rittal anchors its position through integrated enclosure and cooling systems that reduce field assembly complexity. Schneider Electric competes via end-to-end electrical and thermal management architectures spanning multiple facility tiers.
Germany data center cooling encompasses engineered thermal management systems—precision air handlers, liquid distribution networks, and heat rejection equipment—designed to maintain inlet temperatures between 18°C and 27°C per ASHRAE guidelines while dissipating heat loads exceeding 50 kW per rack in high-density deployments. These systems serve the fundamental industrial purpose of preventing thermal throttling, equipment degradation, and unplanned outages in compute-intensive environments. Liquid cooling now leads growth trajectories as GPU-heavy AI workloads exceed air-based thermal limits, while free cooling technology commands margin concentration in Germany's temperate climate zones where economizer hours extend operational savings. CRAC units retain volume dominance in legacy facility retrofits where infrastructure replacement cycles lag behind new build specifications.
The Federal Network Agency (Bundesnetzagentur) enforces EnEfG efficiency benchmarks that compel operators to document power usage effectiveness below 1.3 for new installations, directly steering procurement toward advanced cooling architectures. KBA building energy codes and local German municipal heat planning ordinances further constrain site development, embedding thermal reuse requirements into facility approvals. Stakeholders must monitor how the EU AI Act's infrastructure transparency mandates intersect with Germany's forthcoming sector-specific efficiency regulations to anticipate compliance-driven equipment refresh cycles.
Market Dynamics
GPU-intensive AI workloads are compressing thermal design limits across German facilities, forcing operators to abandon legacy air-cooled architectures before natural replacement cycles conclude. This acceleration is fragmenting procurement patterns between retrofit-constrained colocation sites and greenfield hyperscale campuses.
Growth Catalysts
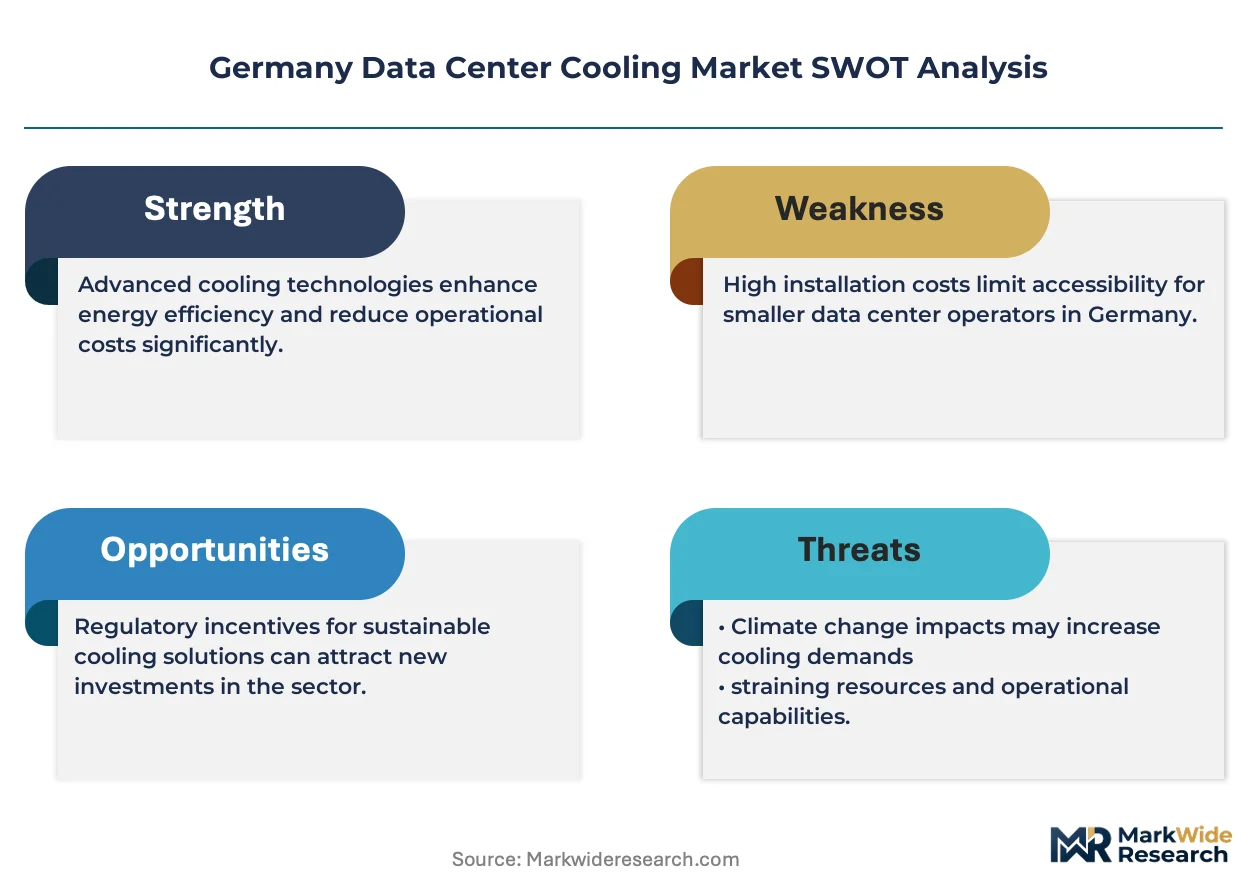
- EnEfG Mandates:Germany's Energy Efficiency Act imposes PUE ceilings below 1.3 for new installations, compelling operators to specify advanced liquid cooling and free cooling economizers rather than conventional CRAC units.
- AI Training Clusters:Hyperscale cloud operators are deploying NVIDIA H100 and Blackwell GPU racks exceeding 40 kW per unit, creating immediate demand for direct-to-chip liquid cooling loops that air systems cannot support.
- Frankfurt Rhine-Main Saturation:Power grid constraints in Germany's primary data center cluster are pushing new capacity toward Berlin-Brandenburg and Magdeburg, where greenfield designs integrate thermal reuse from project inception.
Market Restraints
- Copper and Aluminum Volatility:Liquid cooling manifolds and heat exchangers depend on non-ferrous metals whose price swings compress fabrication margins for German equipment suppliers.
- Skilled Technician Scarcity:Refrigeration engineers certified for flammable refrigerants and high-pressure dielectric fluids remain concentrated in southern Germany, constraining deployment velocity in eastern expansion zones.
- KBA Heat Planning Ordinances:Municipal building codes require district heating integration for facilities above 20 MW IT load, extending permitting timelines and freezing site selection in conservative jurisdictions.
Strategic Opportunities
- Berlin-Brandenburg Greenfield:New hyperscale campuses near the DE-CIX node are specifying thermal reuse loops from day one, creating first-mover advantage for vendors with packaged heat recovery systems.
- Edge Micro-Modular:Factory-integrated cooling modules are penetrating manufacturing automation and autonomous vehicle training sites where on-premise latency requirements override cloud economics.
- EU AI Act Transparency:Infrastructure disclosure mandates for high-risk AI systems will force enterprise operators to document energy consumption, accelerating refresh cycles toward certified efficient cooling architectures.
Industry Challenges
- Dielectric Fluid Supply Security:Single-source dependency on fluorinated and engineered fluid suppliers for immersion and two-phase cooling creates vulnerability to export control disruptions.
- Legacy Air-Handling Retrofit Complexity:Raised-floor facilities built for 8-12 kW racks require structural reinforcement and containment reconfiguration to support rear-door heat exchangers, compressing ROI timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Cooling Market |
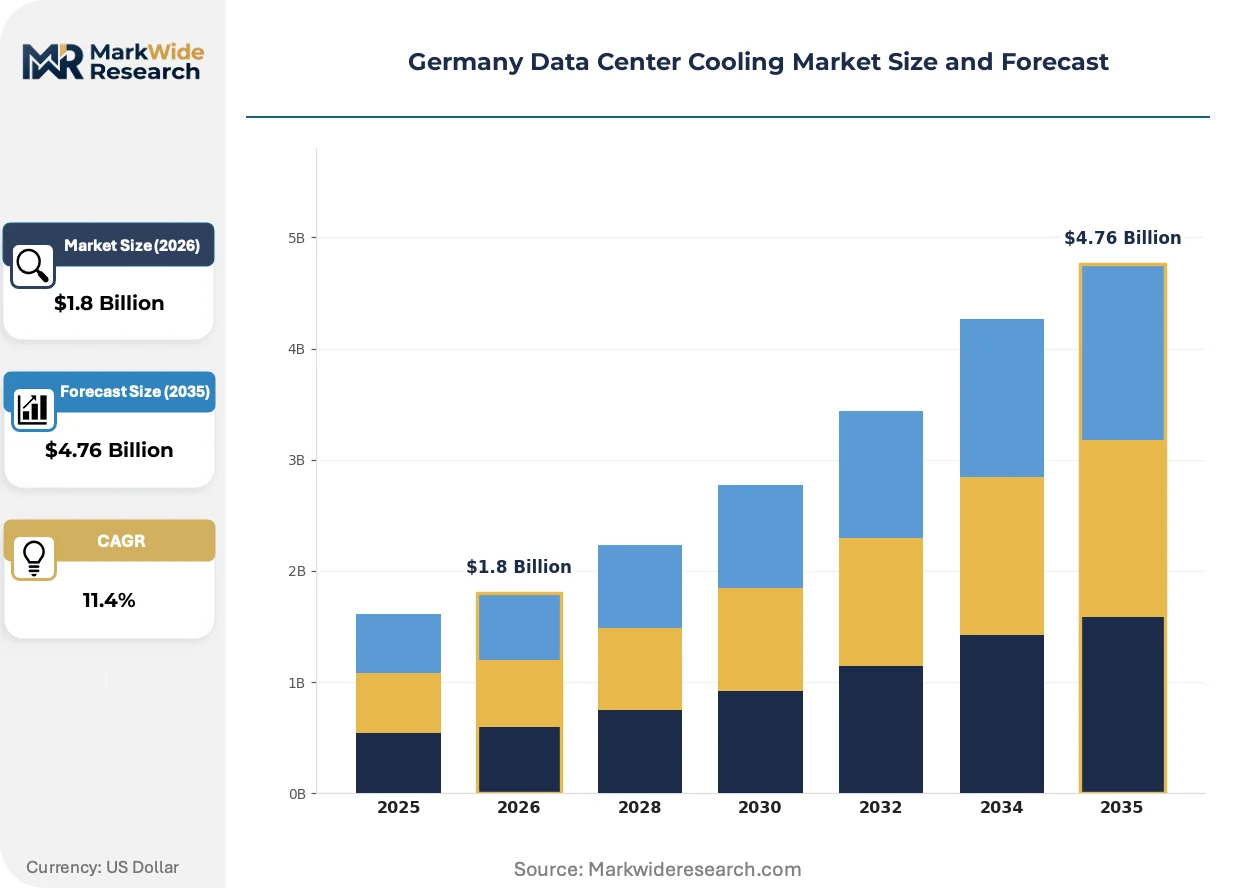
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Evaporative Cooling, Hybrid Cooling End User: Telecommunications, Banking, Cloud Service Providers, Healthcare Product Type: Cooling Towers, Chillers, Heat Exchangers, CRAC Units Technology: Thermal Energy Storage, Direct Expansion, Immersion Cooling, Free Cooling |
| Companies Covered | STULZ, Rittal, Schneider Electric, Vertiv, Carrier, Danfoss, Johnson Controls, Alfa Laval, Daikin Applied, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are fragmenting equipment vendor hierarchies as specialized component suppliers bypass traditional precision air conditioning incumbents. This technological shift is compressing the value chain while expanding the addressable market for subsystem specialists.
Direct-to-chip cold plate assemblies are fragmenting the thermal management stack by separating coolant distribution from heat rejection. Hyperscale operators are qualifying second-source manifold suppliers to reduce dependency on integrated system vendors. This disaggregation is enabling modular procurement where facility engineers specify pumps, heat exchangers, and control logic from distinct suppliers rather than single-source CRAC units.
Germany's Federal Network Agency is tightening EnEfG enforcement through mandatory third-party PUE verification for facilities exceeding 10 MW IT capacity. Operators must submit annual efficiency reports to Bundesnetzagentur auditors, with non-compliance triggering grid connection penalties. This regulatory pressure is accelerating specification of adiabatic free cooling and thermal storage buffers in new Frankfurt-area projects.
Enterprise procurement patterns are compressing vendor evaluation cycles as sustainability committees override traditional facilities management authority. Chief sustainability officers are mandating lifecycle carbon assessments that favor local manufacturing and refrigerant-free architectures over first-cost optimization. This shift is most visible in Mittelstand manufacturing verticals where Scope 3 reporting requirements intersect with on-premise HPC deployments for simulation workloads.
Germany Data Center Cooling Market Segmentation
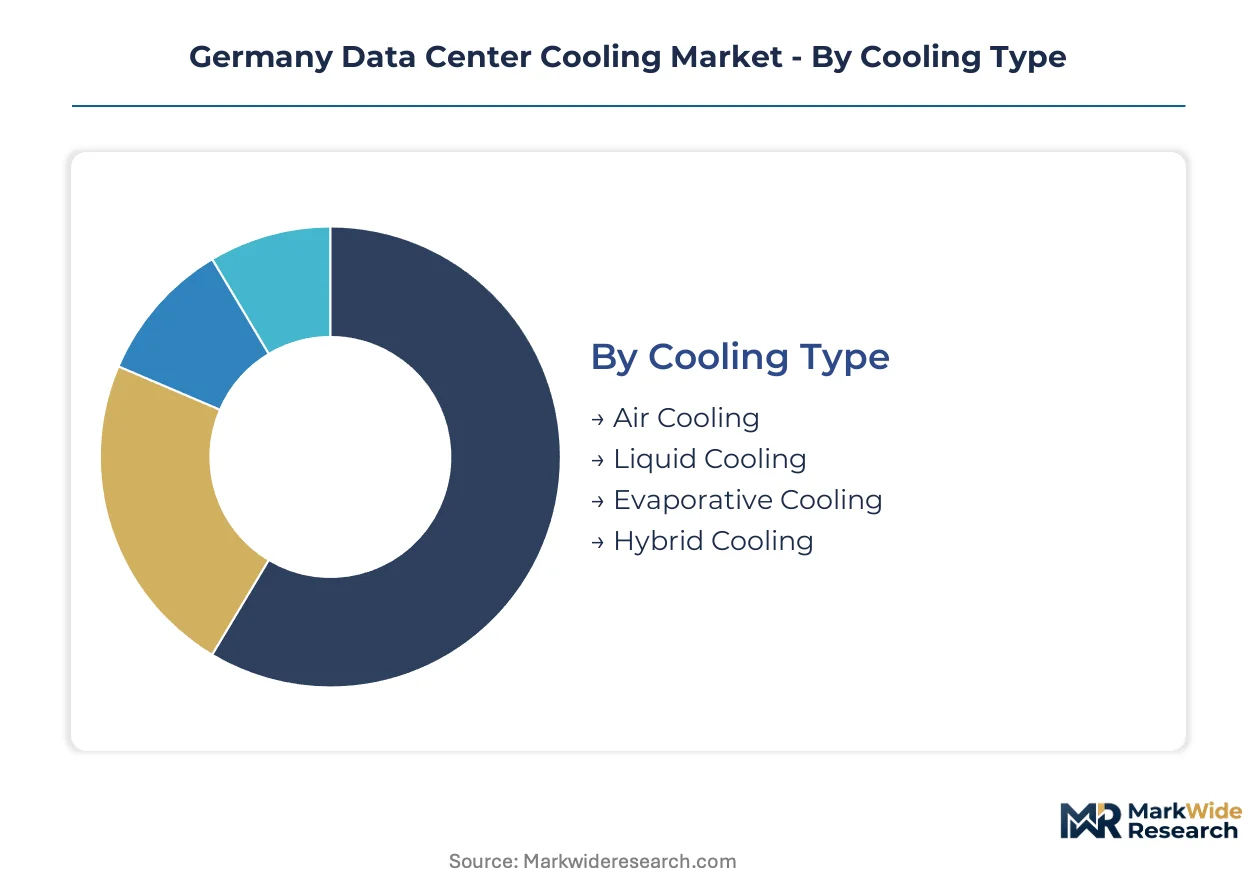
Germany's data center cooling market fragments across thermal architectures, customer verticals, and equipment categories that each carry distinct procurement channels and margin profiles. Understanding these segment boundaries clarifies where EnEfG compliance pressure concentrates versus where legacy replacement cycles dominate purchasing decisions.
Cooling Type:
Channel mix varies sharply: liquid cooling flows primarily through direct OEM relationships with hyperscale operators, while air cooling and hybrid systems move through systems integrators and mechanical contractors serving enterprise colocation.
- Liquid Cooling:Direct-to-chip cold plate assemblies and immersion baths engineered for dielectric fluid circulation at rack densities exceeding 40 kW. Demand concentrates in Frankfurt Rhine-Main hyperscale campuses where NVIDIA H100 and Blackwell GPU clusters exceed air-based thermal limits, with procurement driven by EnEfG PUE mandates below 1.3 that conventional architectures cannot satisfy.
- Air Cooling:Precision air handlers and computer room air conditioners (CRAC) delivering conditioned air through raised-floor plenums. Volume concentrates in legacy enterprise facilities across Mittelstand manufacturing verticals where infrastructure replacement cycles lag behind new build specifications, constrained by structural reinforcement costs for containment reconfiguration.
- Evaporative Cooling:Adiabatic wet-bulb systems leveraging Germany's temperate climate for economizer hours. Procurement flows through specialized HVAC contractors serving Berlin-Brandenburg greenfield sites where municipal heat planning ordinances favor thermal reuse integration.
- Hybrid Cooling:Combined air-liquid architectures with intelligent workload-based switching. Adoption concentrates in cloud service provider edge deployments requiring flexible thermal response across variable compute loads.
By volume, Air Cooling leads. By growth pace, Liquid Cooling is expanding most quickly.
End User:
Cost tier stratification separates these verticals: cloud service providers optimize for total cost of ownership across 15-year facility lifespans, while banking and healthcare prioritize capital expenditure predictability and regulatory audit trails.
- Cloud Service Providers:Hyperscale operators deploying GPU-intensive training clusters at 50+ kW per rack. Procurement concentrates in Magdeburg and Berlin-Brandenburg greenfield campuses where thermal reuse loops are specified from project inception, driven by Bundesnetzagentur efficiency verification requirements for facilities exceeding 10 MW IT capacity.
- Telecommunications:Edge computing deployments for 5G network function virtualization and autonomous vehicle training infrastructure. Demand clusters in manufacturing automation corridors where latency requirements override cloud economics, with procurement favoring factory-integrated micro-modular cooling units.
- Banking:Frankfurt-based financial institutions maintaining on-premise trading infrastructure and risk calculation clusters. Procurement emphasizes certified efficient architectures with documented lifecycle carbon assessments for Scope 3 reporting compliance.
- Healthcare:Hospital data centers and pharmaceutical research HPC supporting molecular simulation workloads. Volume concentrates in Bavarian and Baden-Württemberg life sciences clusters where local manufacturing preferences intersect with refrigerant-free architecture mandates from sustainability committees.
Cloud Service Providers command the premium tier by deployment scale. Healthcare is climbing the fastest as AI-driven diagnostic imaging workloads proliferate.
Product Type:
Margin concentration follows equipment complexity: heat exchangers and integrated cooling towers capture higher value-add than standardized chiller packages, while CRAC units face commoditization pressure from Asian manufacturing.
- Heat Exchangers:Plate-and-frame and shell-and-tube configurations for liquid-to-liquid and liquid-to-air thermal transfer. Demand concentrates in direct-to-chip cooling loops for AI training clusters, with procurement specifying second-source manifold suppliers to reduce dependency on integrated system vendors.
- Cooling Towers:Evaporative heat rejection equipment including open-circuit and closed-circuit designs. Adoption clusters in Frankfurt-area projects where adiabatic free cooling and thermal storage buffers are accelerating under tightened EnEfG enforcement.
- Chillers:Compression and absorption refrigeration packages for centralized chilled water distribution. Procurement flows through mechanical contractors serving legacy facility retrofits where raised-floor reinforcement costs compress ROI timelines.
- CRAC Units:Computer room air conditioners for perimeter and row-based deployment. Volume concentrates in enterprise colocation sites with 8-12 kW legacy rack densities, facing displacement pressure from liquid cooling architectures before natural replacement cycles conclude.
CRAC Units lead by installed base volume. Heat Exchangers are gaining share fastest as liquid cooling disaggregates the thermal management stack.
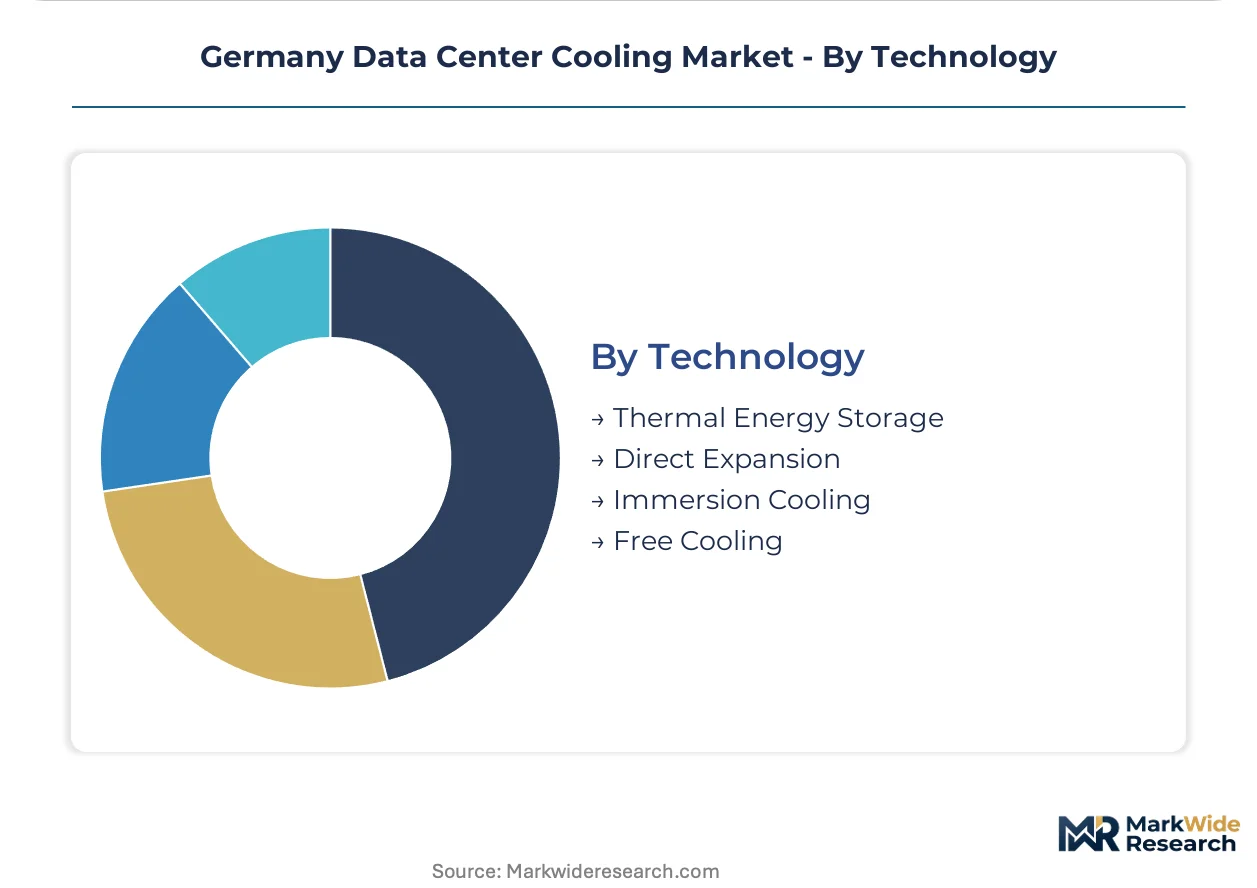
Technology:
Application context determines specification: free cooling and thermal energy storage dominate new construction in Germany's climate zones, while direct expansion persists in retrofit-constrained environments where infrastructure lock-in prevents architectural overhaul.
- Free Cooling:Air-side and water-side economizer systems exploiting ambient temperature differentials. Deployment concentrates in temperate climate zones where operational savings from extended economizer hours justify higher capital expenditure, particularly in Berlin-Brandenburg sites with DE-CIX node proximity.
- Immersion Cooling:Single-phase and two-phase dielectric fluid baths for full server submersion. Adoption clusters in GPU-heavy AI workloads where thermal design limits exceed air-based and even direct-to-chip liquid capabilities, constrained by single-source dependency on fluorinated fluid suppliers.
- Thermal Energy Storage:Ice and chilled water buffer systems for load shifting and emergency cooling capacity. Procurement emphasizes integration with district heating networks under KBA municipal heat planning ordinances for facilities above 20 MW IT load.
- Direct Expansion:Refrigerant-based cooling with evaporator coils proximal to heat loads. Volume persists in eastern expansion zones where skilled refrigeration engineers certified for flammable refrigerants remain scarce, constraining deployment velocity of alternative architectures.
Direct Expansion leads by current deployment volume. Immersion Cooling shows the steepest expansion trajectory as Blackwell-generation GPU racks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main power grid interconnect and DE-CIX internet exchange anchor Germany's data center geography, while the 380kV transmission spine to Berlin-Brandenburg unlocks eastern expansion corridors.
Frankfurt Rhine-Main
GPU clusters exceeding 40 kW per rack concentrate in this saturated cluster. Bundesnetzagentur enforces EnEfG PUE verification for facilities above 10 MW IT capacity. Operators deploy adiabatic free cooling and thermal storage buffers to meet sub-1.3 efficiency mandates.
Berlin-Brandenburg
Greenfield hyperscale campuses specify thermal reuse loops from project inception. KBA municipal heat planning ordinances require district heating integration for facilities above 20 MW. DE-CIX node proximity attracts cloud operators seeking latency advantages over Frankfurt congestion.
Magdeburg
Available grid capacity and cooler ambient temperatures support economizer-heavy designs. EnEfG compliance pressure steers procurement toward liquid cooling architectures. Microsoft and other hyperscalers anchor industrial parks with packaged heat recovery systems.
Bavaria
Life sciences clusters in Munich and Erlangen drive HPC demand for molecular simulation workloads. Local manufacturing preferences intersect with refrigerant-free mandates from sustainability committees. Hospital data centers and pharmaceutical research facilities prioritize certified efficient architectures.
Hamburg
Port logistics and maritime insurance verticals sustain enterprise colocation demand. Legacy raised-floor facilities face retrofit constraints as rack densities climb. Mechanical contractors dominate procurement channels for CRAC unit replacements.
Germany Data Center Cooling Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D velocity. The vendor base shows moderate concentration, with integrated system architects holding share against component specialists. Three archetypes dominate: precision air conditioning heritage players, enclosure-integrated thermal managers, and electrical-thermal end-to-end architects. Competitive moves center on second-source manifold qualification programs and packaged heat recovery system partnerships.
Among Germany-based fabricators, STULZ GmbH and Rittal GmbH occupy positions reflecting distinct strategic origins. STULZ represents the precision air conditioning heritage archetype, while Rittal anchors the enclosure-integrated thermal management tier. Schneider Electric SE, a France-listed electrical specialist, exemplifies the end-to-end architecture approach spanning multiple facility tiers. These three players illustrate how geographic origin and corporate structure shape competitive positioning without determining specific technology adoption rates.
| Leading Market Players |
|---|
| STULZ |
| Rittal |
| Schneider Electric |
| Vertiv |
| Carrier |
| Danfoss |
| Johnson Controls |
| Alfa Laval |
| Daikin Applied |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week lead times for precision-manifold assemblies have concentrated procurement leverage among hyperscale operators with multi-year offtake agreements, while tier-two colocation providers absorb spot-market volatility in copper and aluminum feedstock costs. This inventory compression dynamic rewards vertical integration into heat-exchanger fabrication and penalizes pure-play distributors without captive manufacturing capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EnEfG-certified liquid cooling architectures from legacy CRAC retrofits and commodity air-handling units. Price differentiation hinges on Bundesnetzagentur compliance verification and local manufacturing origin for Scope 3 reporting. Cost compression in standard-tier hybrid systems is intensifying because Asian-manufactured chiller packages flood European spot markets. Cloud service providers exhibit lowest price sensitivity due to 15-year TCO optimization, while Mittelstand manufacturing verticals prioritize capital expenditure predictability over lifecycle efficiency.
Supply Chain Analysis
China and South Korea anchor dielectric fluid and precision pump manufacturing, while Germany and the Netherlands concentrate heat-exchanger and adiabatic cooling tower fabrication. German equipment suppliers draw from copper concentrate originating in Chile and recycled aluminum feedstock from European scrap markets. Single-source vulnerability on fluorinated immersion fluids creates exposure to export control disruptions under EU F-Gas Regulation phase-down schedules. Distribution runs through systems integrators serving enterprise colocation, direct OEM relationships with hyperscale operators, and mechanical contractors for legacy facility retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's data center cooling market sits at a platform-economics inflection where thermal management architectures are disaggregating into interoperable subsystems, enabling modular procurement that bypasses traditional integrated-vendor lock-in.
For Market Incumbents: Shield installed-base revenue streams by certifying second-source manifold suppliers before hyperscale operators complete qualification programs. Prioritize backward integration into heat-exchanger fabrication to capture margin compression from Asian chiller imports. Defend against specialized component suppliers by bundling thermal storage buffers with district heating integration packages for Berlin-Brandenburg greenfield sites. For New Entrants and Emerging Players: Post-warranty service-layer gaps in liquid cooling loop maintenance present immediate white-space opportunity, as incumbent OEMs under-serve distributed edge deployments outside Frankfurt Rhine-Main. Target telecommunications edge computing corridors in Magdeburg and Hamburg where latency requirements override cloud economics. Penetrate through factory-integrated micro-modular cooling units with embedded predictive maintenance software. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EnEfG enforcement tightening and EU AI Act transparency mandates will force equipment refresh cycles regardless of natural replacement timelines. Acquisition target archetype: mid-cap specialists with certified efficient architectures and existing Bundesnetzagentur audit relationships. Monitor PUE verification penalty announcements as inflection signal for accelerated procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Second-Source Manifold Qualification | Reduces hyperscale operator dependency on integrated system vendors like STULZ and Rittal. |
| Thermal Reuse Loop Integration | Satisfies KBA municipal heat planning ordinances for facilities above 20 MW IT load in Berlin-Brandenburg. |
| Dielectric Fluid Supply Diversification | Mitigates single-source vulnerability to EU F-Gas Regulation export control disruptions. |
| Edge Micro-Modular Factory Integration | Captures autonomous vehicle training and manufacturing automation demand outside Frankfurt congestion. |
| Lifecycle Carbon Assessment Certification | Aligns with sustainability committee mandates overriding traditional facilities management authority in Mittelstand verticals. |
Research Methodology
Operator-level perspectives from data center facilities directors, Bundesnetzagentur compliance auditors, mechanical contracting procurement leads, and hyperscale cloud infrastructure planners anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against Bundesnetzagentur enforcement bulletins, KBA building energy code filings, DE-CIX traffic statistics, and SEC capex disclosures from listed cloud operators. Bottom-up equipment shipment tracking and top-down facility capacity modeling were triangulated to derive segment-level estimates.
Sensitivity analysis tested demand elasticity against copper price volatility, skilled refrigeration engineer availability constraints, and EnEfG PUE threshold adjustments. The analytical framework modeled cooling type, end-user vertical, product category, and technology segmentation dimensions across the projection horizon. CAGRs were derived from installed base replacement cycles intersecting with GPU cluster deployment trajectories, incorporating hyperscaler announced capacity additions and municipal permitting velocity in eastern expansion zones.
Forecasts assume regulatory continuity in Germany's Energy Efficiency Act enforcement and EU AI Act infrastructure transparency mandates; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated F-Gas Regulation phase-down schedules disrupting dielectric fluid supply, grid interconnection delays in Berlin-Brandenburg, and copper price spikes exceeding fabrication margin buffers. Recalibration cycles align with material shifts in Bundesnetzagentur penalty enforcement patterns and hyperscale operator greenfield announcement cadence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market