
 Cross-Border Logistics Services Market | 2026-2036
Cross-Border Logistics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cross-Border Logistics Services Market Insights
The shift from single-source freight contracts to multi-source logistics networks is repositioning how manufacturers manage inventory exposure across international borders. DHL Supply Chain leverages its bonded warehouse footprint to anchor pharmaceutical and electronics flows through European customs zones. Kuehne + Nagel competes on ocean-air intermodal density, while DSV A/S extends its acquisition-built road network across Central Asian corridors.
Cross-border logistics services encompass the planning, execution, and control of freight movements, customs clearance, and inventory positioning across sovereign boundaries, typically operating under harmonized tariff codes and trade compliance protocols. Ocean freight remains the volume backbone for bulk commodity and finished goods movements, while air freight captures premium electronics and perishable segments where velocity outweighs unit cost. E-commerce customer types are forcing investments in real-time tracking systems and distributed order management platforms that split inventory across origin and destination markets.
FDA, EPA, and EMA frameworks govern pharmaceutical and hazardous material flows, with customs authorities in Germany, the Netherlands, and Singapore enforcing divergent documentation standards that fragment clearance timelines. The EU AI Act and emerging digital customs protocols will reshape automated classification and risk-scoring requirements for cross-border shipments. Stakeholders must monitor which regulatory clusters adopt mutual recognition agreements versus unilateral digital border controls, as this divergence determines where logistics providers can standardize operating models or must maintain country-specific compliance architectures.
Market Dynamics
Manufacturing reshoring and nearshoring decisions are fragmenting long-haul freight corridors into shorter, more complex multimodal chains that demand real-time customs coordination and distributed inventory nodes.
Growth Catalysts
- E-commerce platform expansion:Southeast Asian digital marketplaces are building proprietary cross-border fulfillment networks that integrate bonded warehousing with last-mile delivery in Vietnam and Indonesia.
- EU Customs Code Reform:Tighter entry documentation for non-union goods is creating specialized demand for customs brokerage and pre-arrival clearance services at Rotterdam and Hamburg ports.
- Multimodal corridor development:The Vietnam-to-China electronics manufacturing corridor requires synchronized ocean-air handoffs and temperature-controlled bonded facilities for semiconductor components.
Market Restraints
- Fuel cost volatility:Bunker fuel price swings directly compress ocean freight margins and force contract renegotiation cycles that destabilize carrier-shipper relationships.
- Concentrated port capacity:Container terminal bottlenecks at Singapore and Shanghai create systemic delays that cascade through transshipment schedules across Southeast Asian lanes.
- Technical interoperability gaps:Non-standardized electronic data interchange protocols between customs authorities fragment automated clearance timelines and increase manual documentation burdens.
Strategic Opportunities
- Underpenetrated Central Asian corridors:Road-rail intermodal networks through Kazakhstan and Uzbekistan offer alternative routes bypassing traditional maritime chokepoints for Europe-Asia freight.
- EU AI Act compliance services:Automated classification and risk-scoring tools for customs declarations create new revenue streams for logistics providers with machine learning capabilities.
- Cold chain pharmaceutical expansion:Temperature-controlled bonded warehousing for biologics and vaccines addresses EMA and FDA dual-jurisdiction requirements at major European hub airports.
Industry Challenges
- Customs technology talent scarcity:Shortages of specialists capable of integrating legacy enterprise resource planning systems with emerging digital customs platforms delay automation timelines.
- Certification timeline compression:Accelerated MDR and IVDR medical device regulations in Europe demand faster validation of temperature monitoring and chain-of-custody documentation.
- Supply chain reconfiguration friction:Shifting manufacturing from China to Vietnam or Mexico requires rebuilding supplier networks and requalifying customs broker relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross-Border Logistics Services Market |
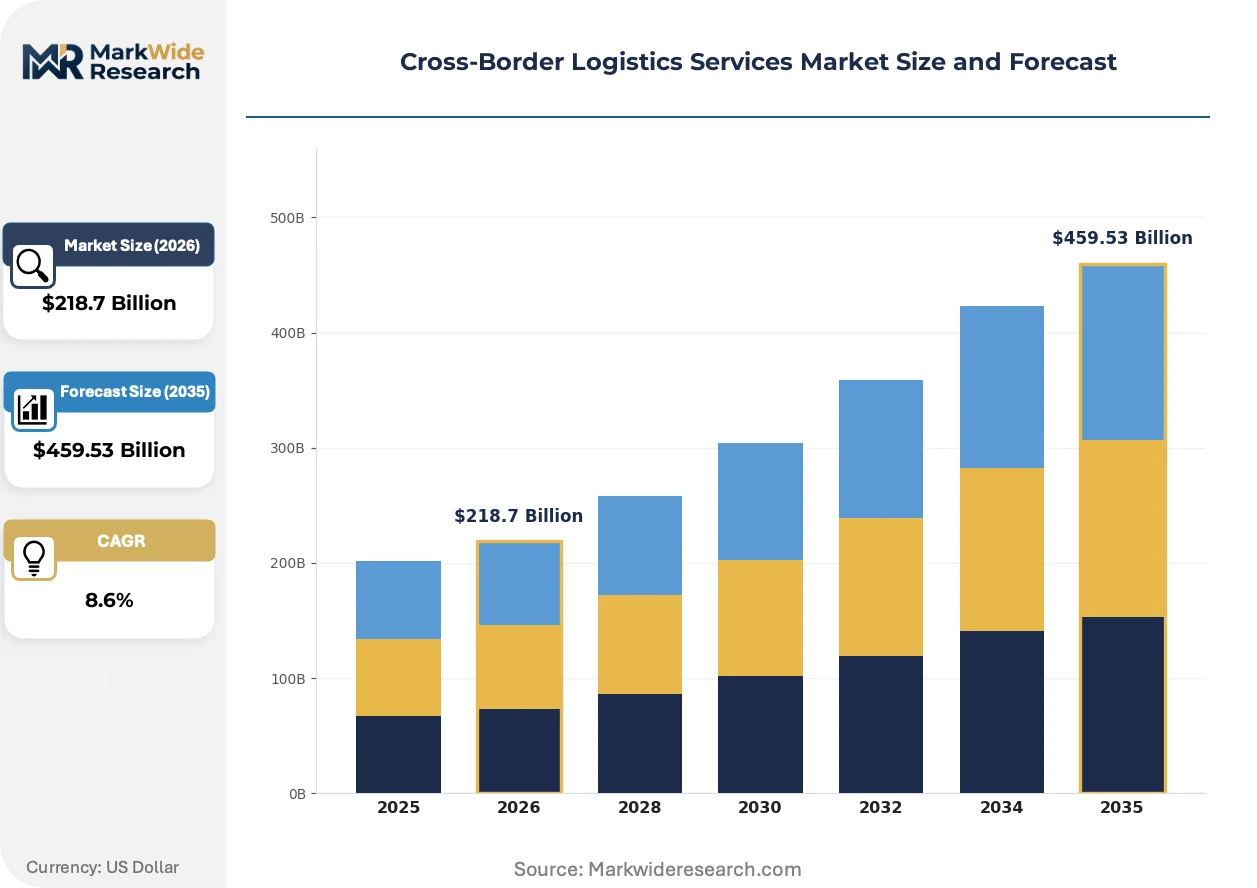
| Market Size in 2026 | $218.7 Billion |
| Market Size in 2035 | $459.53 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Rail Freight, Road Freight Customer Type: Manufacturers, Retailers, Wholesalers, E-commerce Technology: Tracking Systems, Warehouse Management, Order Management, Freight Management Delivery Model: Direct Delivery, Consolidated Delivery, Expedited Delivery, Scheduled Delivery |
| Companies Covered | DHL Supply Chain, FedEx Corporation, UPS Supply Chain Solutions, Kuehne + Nagel, DB Schenker, Maersk Line, DSV A/S, CEVA Logistics, Expeditors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross-Border Logistics Services Market Trends and Innovations
Distributed ledger and artificial intelligence applications are compressing documentation cycles and enabling predictive risk scoring that reshapes how customs clearance operates across sovereign boundaries.
Blockchain-enabled trade documentation is integrating shipment records, bills of lading, and customs declarations into immutable shared ledgers accessible to carriers, brokers, and regulatory authorities simultaneously. Pharmaceutical and electronics exporters in the Germany-Netherlands-Belgium corridor are piloting these systems to reduce document fraud and accelerate pre-arrival clearance. The structural consequence is that customs brokers are integrating compliance verification directly into freight forwarding workflows rather than treating clearance as a separate post-arrival service.
REACH and RoHS substance restrictions are forcing electronics manufacturers to requalify component suppliers and revise material declarations for cross-border shipments entering European customs zones. Industrial consequence includes mandatory re-testing of existing product lines and supplier audit expansion into Southeast Asian sub-tier manufacturers. Electronics logistics providers serving the Netherlands and Germany are responding by building chemical compliance databases that track substance thresholds across supplier tiers.
Shippers are consolidating freight procurement around outcome-based contracts that penalize delays and reward carbon intensity reductions rather than optimizing solely for unit transport cost. Apparel and consumer electronics brands sourcing from Vietnam and Bangladesh are displacing annual rate negotiations with quarterly performance reviews tied to delivery reliability metrics. This behavioral shift is most visible among European retailers with science-based emissions targets that require granular emissions reporting from logistics partners.
Cross-Border Logistics Services Market Segmentation
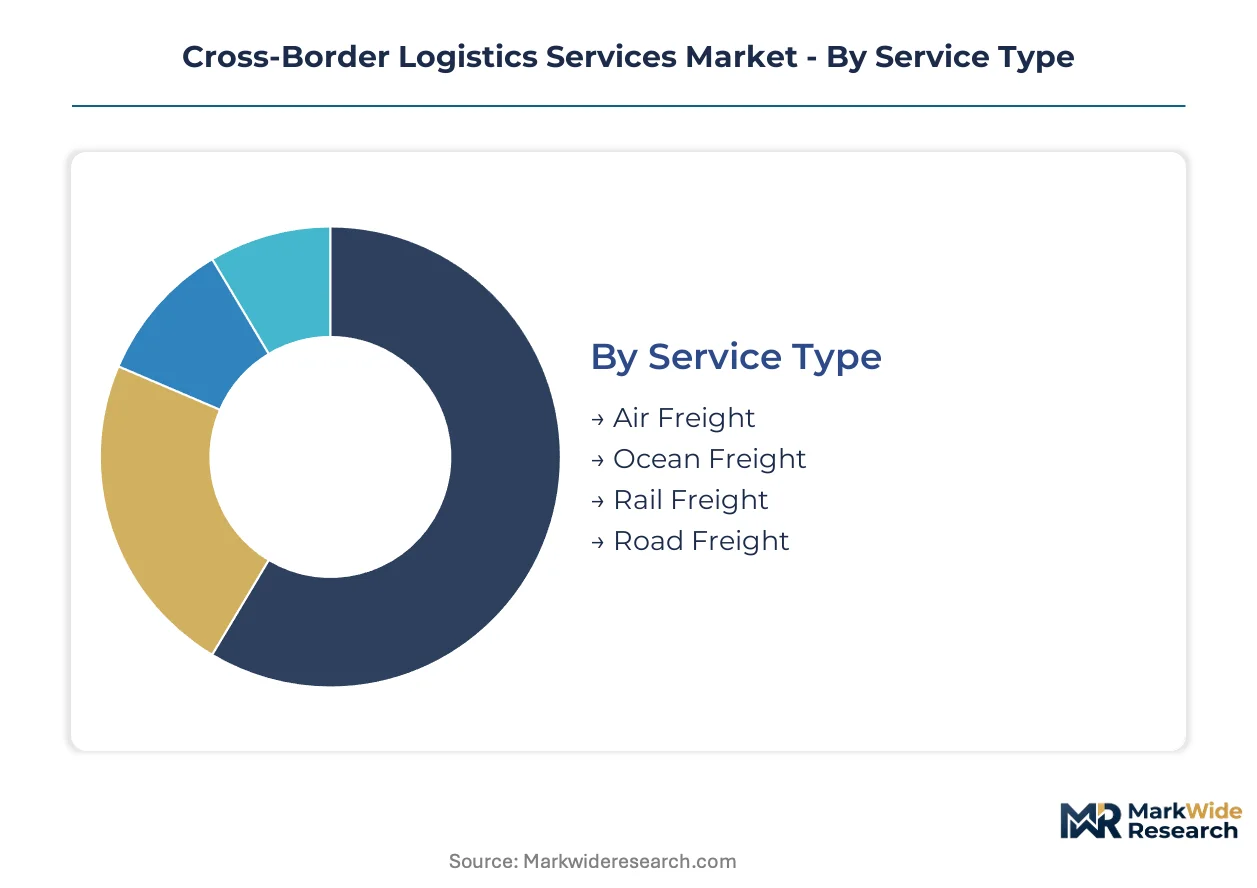
Cross-border logistics providers configure service portfolios around modal trade-offs between velocity and unit cost. Customer type and technology adoption patterns determine margin structure and capital deployment priorities across network nodes.
Service Type:
Ocean freight dominates volume throughput while air freight commands premium pricing for time-sensitive corridors.
- Air Freight:Temperature-controlled cargo holds and express clearance lanes support pharmaceutical and semiconductor shipments. Demand concentrates in the Germany-Netherlands-Belgium corridor where EMA-regulated biologics require cold chain integrity and bonded warehouse handoffs.
- Ocean Freight:Containerized bulk movements anchor intercontinental supply chains with standardized twenty-foot equivalent unit pricing. Electronics exporters from Vietnam to China rely on synchronized ocean-air handoffs at Singapore transshipment hubs to balance cost and velocity.
- Rail Freight:China-Europe block trains through Kazakhstan and Poland offer middle-ground transit times for automotive components and industrial machinery.
- Road Freight:Cross-border trucking networks dominate intra-regional European trade and Central Asian corridor development.
Mature deployment sits with Ocean Freight. Newer deployment is concentrated in Rail Freight.
Customer Type:
Shipper scale and compliance sophistication determine service bundling and contract structure.
- E-commerce:Distributed order management platforms split inventory across origin and destination markets to compress last-mile delivery windows. Southeast Asian digital marketplaces in Vietnam and Indonesia are building proprietary fulfillment networks that integrate bonded warehousing with real-time tracking systems.
- Manufacturers:Just-in-sequence production schedules demand multimodal coordination and pre-arrival customs clearance at Rotterdam and Hamburg ports.
- Retailers:Quarterly performance reviews tied to delivery reliability metrics are displacing annual rate negotiations for apparel and consumer electronics brands.
- Wholesalers:Consolidated procurement patterns favor scheduled delivery models with predictable unit economics.
Established contract frameworks dominate Manufacturer relationships. Steepest expansion trajectory appears in E-commerce.
Technology:
Automation depth separates compliance-capable providers from commodity freight brokers.
- Tracking Systems:Real-time visibility platforms integrate GPS, RFID, and customs status feeds for pharmaceutical and electronics shipments crossing German and Dutch borders.
- Warehouse Management:Bonded facility automation supports FIFO rotation and temperature monitoring for FDA and EMA dual-jurisdiction requirements.
- Order Management:Distributed inventory allocation engines split stock across regional nodes to optimize duty exposure and delivery speed.
- Freight Management:Carrier selection algorithms weigh carbon intensity against transit time for European retailers with science-based emissions targets.
Tracking Systems capture the largest installed base. Order Management platforms are gaining share fastest among Southeast Asian e-commerce corridors.
Delivery Model:
Speed tier selection reflects inventory carrying cost trade-offs and customer penalty clauses.
- Expedited Delivery:Time-definite guarantees with financial penalties for delay support semiconductor and automotive production lines. Electronics manufacturers in the Vietnam-to-China corridor pay premiums for synchronized ocean-air handoffs that prevent line stoppages.
- Consolidated Delivery:Multi-shipment container aggregation reduces per-unit freight costs for small and mid-sized wholesalers.
- Direct Delivery:Dedicated vehicle or vessel allocation bypasses transshipment for high-value pharmaceutical shipments under chain-of-custody protocols.
- Scheduled Delivery:Recurring lane commitments with fixed departure windows support predictable replenishment for retail distribution centers.
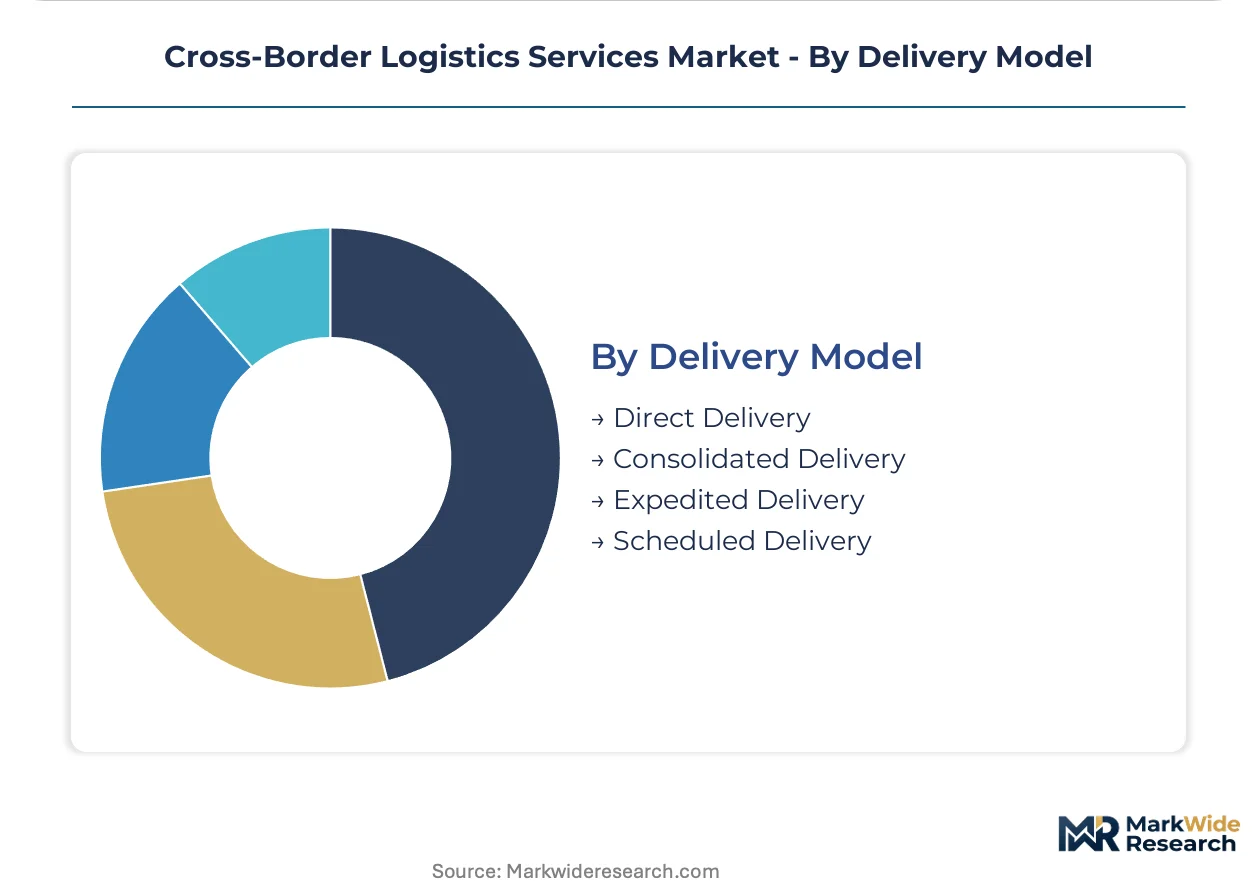
Scheduled Delivery anchors long-term contracts. Expedited Delivery is expanding most quickly among electronics and pharmaceutical shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturing corridors in Vietnam and China concentrate cross-border freight demand, while pharmaceutical hubs in Germany and the Netherlands drive temperature-controlled bonded warehousing requirements.
United States
Pharmaceutical and semiconductor shippers dominate cross-border volume through Los Angeles and New York gateway ports. FDA enforcement of DSCSA track-and-trace mandates accelerates investment in serialized inventory systems. The Texas-Mexico border corridor handles automotive component flows under USMCA rules of origin verification.
Germany
EMA-regulated biologics exports require cold chain integrity through Frankfurt and Munich airport hubs. REACH substance documentation obligations force electronics manufacturers to requalify supplier networks. The Rhine-Ruhr industrial cluster anchors multimodal handoffs between ocean freight at Rotterdam and inland barge networks.
China
Electronics exporters in Shenzhen and Dongguan rely on synchronized ocean-air transshipment through Singapore to balance cost and velocity. SAMR customs digitization initiatives compress clearance timelines at Shanghai and Ningbo container terminals. The Yangtze River Delta concentrates bonded warehousing for semiconductor component staging.
Vietnam
Manufacturing relocation from China drives demand for cross-border road-rail corridors through Lang Son and Lao Cai border crossings. Electronics assemblers in Bac Ninh and Hai Phong require just-in-sequence delivery coordination with Chinese component suppliers. The country's logistics providers are building temperature-controlled facilities to serve pharmaceutical export growth.
Netherlands
Rotterdam port handles pre-arrival clearance for non-union goods under EU Customs Code Reform implementation. EMA and FDA dual-jurisdiction requirements at Schiphol airport drive investment in pharmaceutical cold chain infrastructure. The Randstad logistics cluster integrates customs brokerage with last-mile distribution across northwest European markets.
Cross-Border Logistics Services Market Competitive Landscape
Acquisition-led consolidation dominates the current landscape, with asset-heavy players absorbing regional specialists to extend geographic coverage and modal capabilities. The market structure concentrates around integrated global networks, mid-scale regional operators, and niche customs brokerage specialists. Three archetypes define competitive positioning: harmonized tariff code specialists, multimodal orchestration platforms, and last-mile delivery integrators. M&A activity and bonded warehouse capacity expansion represent the dominant competitive moves as firms defend corridor control.
Within the integrated network tier, DHL Supply Chain, Kuehne + Nagel, and DSV A/S exemplify scale-driven positioning. DHL Supply Chain occupies a position anchored in European pharmaceutical corridors. Kuehne + Nagel represents ocean-air intermodal density specialization. DSV A/S sits within the acquisition-built road network archetype across Central Asian corridors.
| Leading Market Players |
|---|
| DHL Supply Chain |
| FedEx Corporation |
| UPS Supply Chain Solutions |
| Kuehne + Nagel |
| DB Schenker |
| Maersk Line |
| DSV A/S |
| CEVA Logistics |
| Expeditors |
| Others |
Pricing and Supply Chain Analysis
Bunker fuel price indices cascade through ocean freight contracts into three-tier pricing structures across premium, standard, and economy service levels. Electronics manufacturers in Vietnam and pharmaceutical shippers in Germany face divergent cost pass-through mechanics as fuel volatility compresses margins at the standard tier while premium cold-chain services retain pricing power.
Pricing Analysis
Volume throughput concentrates in standardized ocean freight contracts with thin margins, while air freight and temperature-controlled segments capture premium pricing. Price differentiation hinges on customs clearance speed and EMA certification tier for pharmaceutical corridors. Pricing pressure stems from fuel cost volatility forcing quarterly contract renegotiations at Rotterdam and Singapore. Small and mid-sized wholesalers exhibit highest price sensitivity, whereas semiconductor manufacturers prioritize reliability over unit cost.
Supply Chain Analysis
Bonded warehouse capacity rests on real estate availability in the Netherlands, Germany, and Singapore. Container terminal throughput, customs brokerage labor pools, and multimodal handoff infrastructure constitute critical input dependencies. Single-source vulnerability concentrates at Singapore and Shanghai transshipment hubs where terminal bottlenecks cascade through Southeast Asian lanes. Distribution runs through hub-and-spoke networks anchored at Rotterdam port and Schiphol airport for European pharmaceutical flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
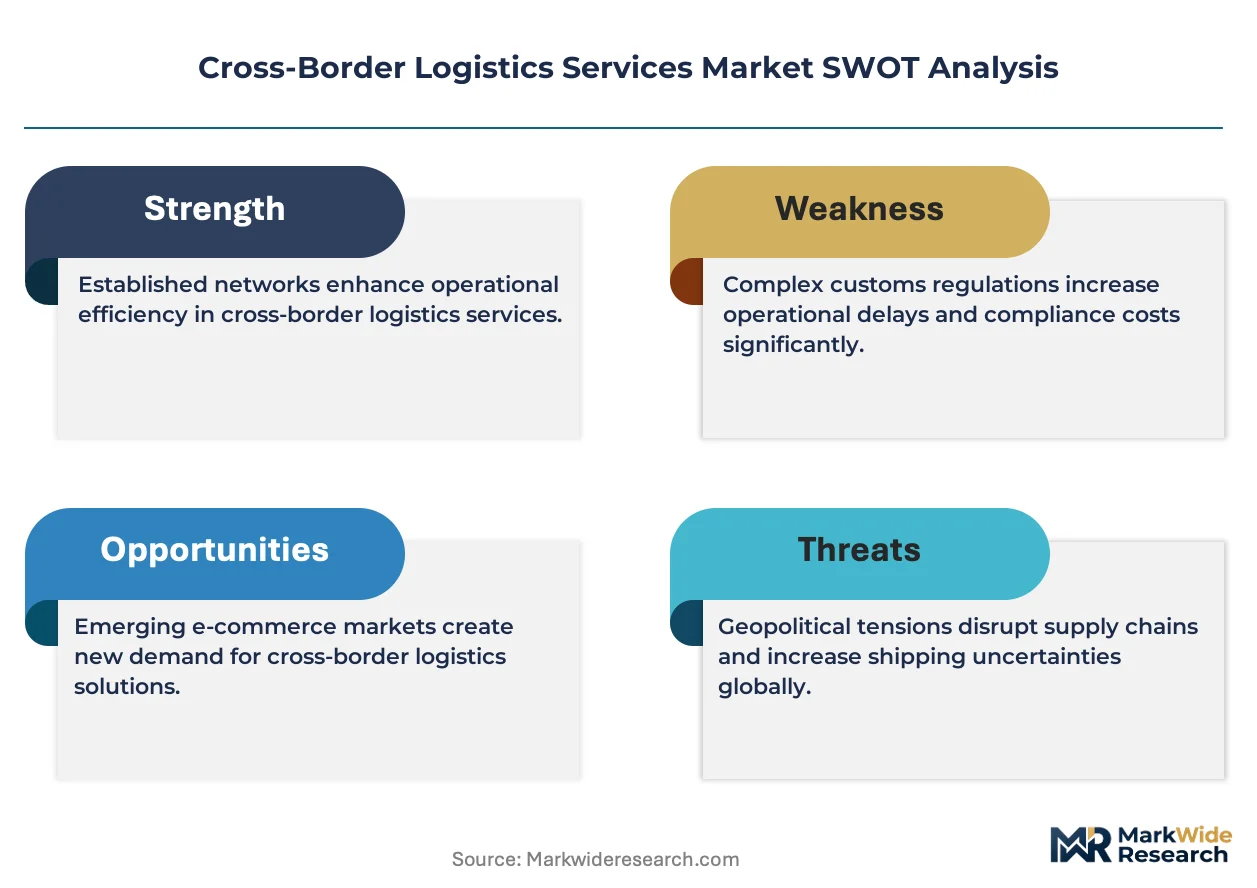
Cross-border logistics services represent a consolidation play as EU Customs Code Reform compliance costs force sub-scale brokers toward acquisition or exit. Digital customs platform investments create winner-take-most dynamics in European pharmaceutical corridors.
For Market Incumbents: Anchor bonded warehouse capacity in the Germany-Netherlands-Belgium corridor to defend pharmaceutical market share against technology-enabled challengers. Acquire regional customs brokerage specialists in Vietnam and Indonesia to capture e-commerce fulfillment growth. Prioritize machine learning capabilities for EU AI Act automated classification requirements. For New Entrants and Emerging Players: Blockchain-enabled trade documentation offers a technology-first wedge into document-intensive pharmaceutical and electronics corridors. Target underpenetrated Central Asian road-rail intermodal routes through Kazakhstan and Uzbekistan as white-space expansion. Lead with pre-arrival clearance speed guarantees rather than competing on base freight rates. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European customs brokers with EMA certification infrastructure and aging founder-owners. Long-term viability hinges on digital customs platform integration capabilities over pure asset ownership. Watch EU mutual recognition agreement negotiations with non-union countries as inflection signal for standardization versus fragmentation returns.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Expansion | Captures pharmaceutical flows under EMA and FDA dual-jurisdiction requirements at Schiphol. |
| Customs Technology Acquisition | Integrates machine learning for EU AI Act automated risk-scoring compliance. |
| Multimodal Corridor Development | Builds road-rail alternatives through Kazakhstan bypassing Singapore congestion. |
| Blockchain Documentation Pilot | Reduces fraud exposure for electronics exporters in the Germany-Netherlands corridor. |
| Temperature-Controlled Facility Buildout | Serves biologics growth with cold chain integrity from Bac Ninh to Frankfurt. |
Research Methodology
Independent corroboration across freight forwarder executives, customs brokerage operators, pharmaceutical supply chain directors, and e-commerce logistics managers underwrites the qualitative findings. Secondary validation draws from SAMR customs digitization disclosures, EU Customs Code Reform implementation notices, EMA cold chain guidance documents, and port authority throughput statistics. Bottom-up carrier capacity assessments and top-down trade flow analysis triangulate market sizing.
Comparable-period anchoring to pre-reform clearance timelines and post-implementation processing rates establishes the forecast baseline. Segmentation models incorporate service type, customer scale, technology adoption depth, and corridor-specific regulatory clusters. CAGRs derive from trade volume elasticity to manufacturing relocation patterns and e-commerce penetration curves across Southeast Asian markets.
Several conditions sit outside the modeled scope, including unilateral digital border control implementations without mutual recognition agreements and abrupt fuel price shocks exceeding historical volatility bands. Forecasts reflect documented assumptions about customs technology adoption timelines and trade policy continuity. A small set of named triggers warrants ongoing watch: EU AI Act enforcement severity, SAMR platform interoperability mandates, and bunker fuel price regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
Texas Freight and Logistics Market