
 Logistics Outsourcing Market | 2026-2036
Logistics Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Logistics Outsourcing Market Outlook
Freight forwarding margin pools is rewriting competitive economics across the logistics outsourcing landscape. DHL Supply Chain & Global Forwarding leverages its air-ocean gateway network to sustain premium positioning on trans-Pacific lanes. Kuehne + Nagel anchors its profitability through pharmaceutical cold-chain specialization, while CEVA Logistics competes on automotive sequencing contracts with embedded just-in-time engineering.
Logistics outsourcing encompasses the delegation of transportation, warehousing, inventory management, and supply chain coordination to external providers operating under service-level agreements with defined cost-per-unit, on-time-in-full, and inventory-accuracy parameters. Its primary commercial purpose is converting fixed logistics infrastructure into variable costs while accessing specialized operational expertise. Transportation management commands the largest revenue share among service types due to fuel and capacity volatility that shippers prefer to transfer. Third-party logistics solutions dominate the solution landscape, though fourth-party logistics arrangements are gaining traction among multinational manufacturers seeking orchestration-layer control. IoT solutions within the technology segment are attracting disproportionate investment as real-time visibility becomes a contractual baseline rather than a premium feature.
FDA regulations on pharmaceutical distribution traceability, EPA emissions standards affecting fleet compliance costs, and EU Green Deal sustainability disclosure requirements are elevating compliance burdens that favor providers with embedded regulatory expertise. India's BIS warehousing standards and CDSCO cold-chain mandates are similarly tightening market access for undercapitalized local operators. Stakeholders must monitor how carbon-accounting rules reshape contract structures and whether automation investments alter the labor-cost arbitrage that has historically defined offshore outsourcing decisions.
Market Dynamics
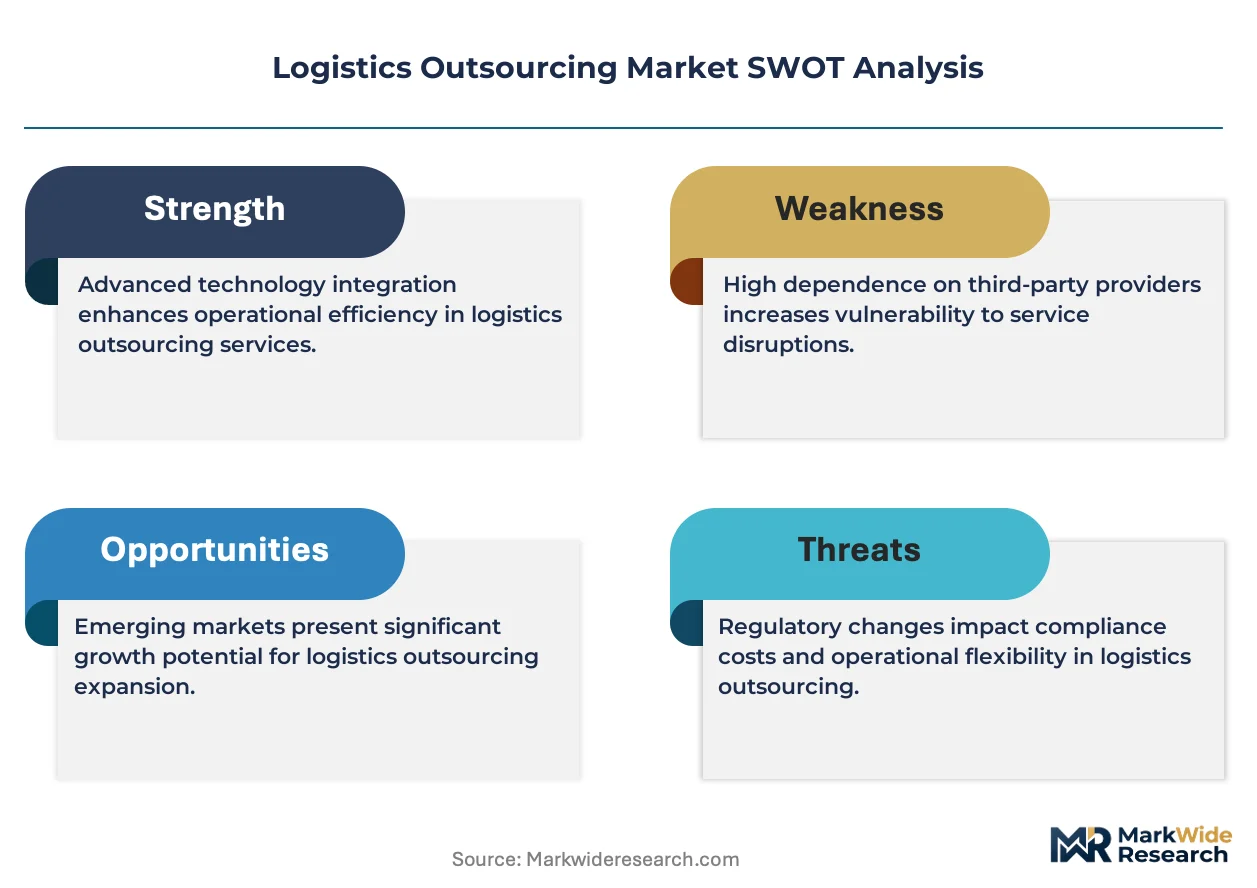
Freight forwarding margin compression is forcing logistics providers to restructure asset-light operating models around specialized vertical expertise rather than commodity capacity brokering.
Growth Catalysts
- EU Green Deal emissions mandates:Mandatory sustainability disclosure requirements are compelling shippers to outsource carbon-accounting capabilities to providers with embedded compliance infrastructure.
- India's manufacturing corridor expansion:Domestic production scaling under the PLI scheme is generating contract logistics demand across automotive and electronics clusters.
- IoT-enabled visibility platforms:Real-time tracking is becoming a contractual baseline, driving replacement of legacy telematics with sensor-integrated fleet management.
Market Restraints
- Fuel cost volatility:Diesel price swings transfer directly to transportation management contracts, compressing provider margins on fixed-rate agreements.
- Warehousing land scarcity:Mumbai and Delhi NCR face industrial zoning constraints that inflate facility costs beyond viable third-party logistics economics.
- Pharmaceutical cold-chain certification complexity:CDSCO traceability requirements demand capital-intensive temperature infrastructure that excludes undercapitalized regional operators.
Strategic Opportunities
- Indonesia's e-commerce fulfillment gap:Archipelago geography creates last-mile fragmentation that rewards providers building multi-modal hub networks.
- Automotive sequencing contracts:Just-in-time engineering embedded in assembly line feed logistics commands premium pricing and multi-year lock-in.
- Battery supply chain localization:EU Critical Raw Materials Act incentives are reshoring cell production and demanding specialized hazardous materials handling.
Industry Challenges
- Warehouse automation technician scarcity:AMR deployment outpaces skilled maintenance workforce availability in emerging markets.
- Legacy WMS integration friction:ERP migration to cloud-native platforms disrupts established shipper-provider data interchange protocols.
- Cross-border customs digitization lag:Non-harmonized single-window systems across ASEAN create clearance bottlenecks for multi-country distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logistics Outsourcing Market |
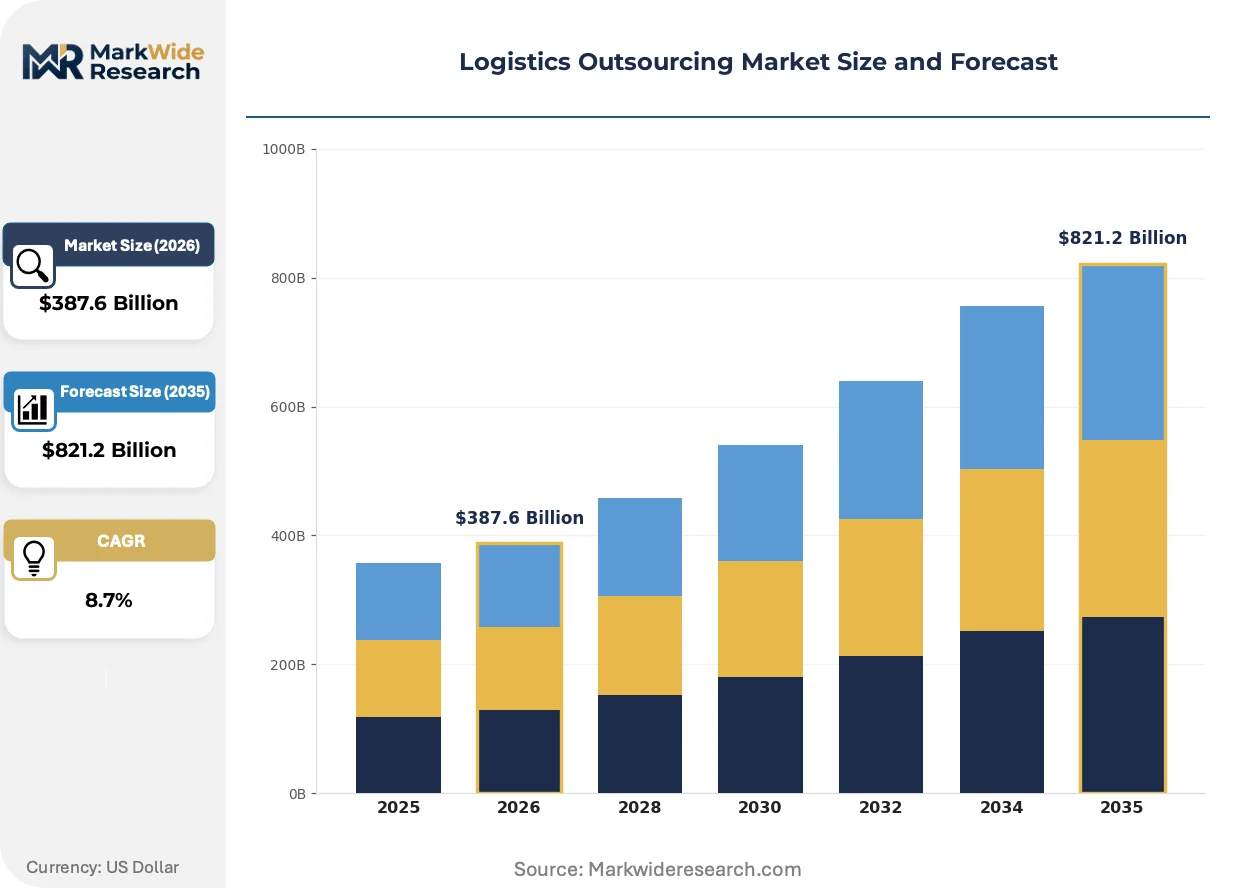
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Warehousing, Freight Forwarding, Supply Chain Consulting End User: E-commerce, Manufacturing, Retail, Pharmaceuticals Solution: Third-Party Logistics, Fourth-Party Logistics, Integrated Logistics, Reverse Logistics Technology: IoT Solutions, Artificial Intelligence, Blockchain, Automation |
| Companies Covered | Amazon, DSV, DHL Supply Chain & Global Forwarding, Kuehne + Nagel, CEVA Logistics, Nippon Express, C.H. Robinson, GXO Logistics, GEODIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logistics Outsourcing Market Strategic Shifts
Digital freight platforms are collapsing traditional brokerage economics while autonomous yard operations and predictive inventory positioning rewrite fulfillment speed benchmarks.
Autonomous mobile robots in warehouse picking operations is rendering obsolete manual cart-based fulfillment in high-velocity e-commerce distribution centers. Fashion and electronics retailers are deploying AMR fleets at scale across European and North American facilities. Labor cost arbitrage that historically justified offshore outsourcing is compressing as automation standardizes unit economics across geographies.
REACH chemical substance registration requirements are extending traceability obligations through logistics networks handling hazardous materials. Third-party logistics providers must now maintain substance-level documentation across multi-leg movements. Specialty chemical and agrochemical shippers are consolidating contracts with providers possessing embedded regulatory data capabilities.
Shippers are unbundling transportation management from warehousing to optimize provider selection by lane and facility performance rather than bundled contract convenience. Large consumer goods manufacturers now tender ocean freight, air cargo, and domestic distribution separately. This pattern is most pronounced in trans-Pacific trade lanes where specialized forwarders compete against integrated supply chain operators.
Logistics Outsourcing Market Segmentation
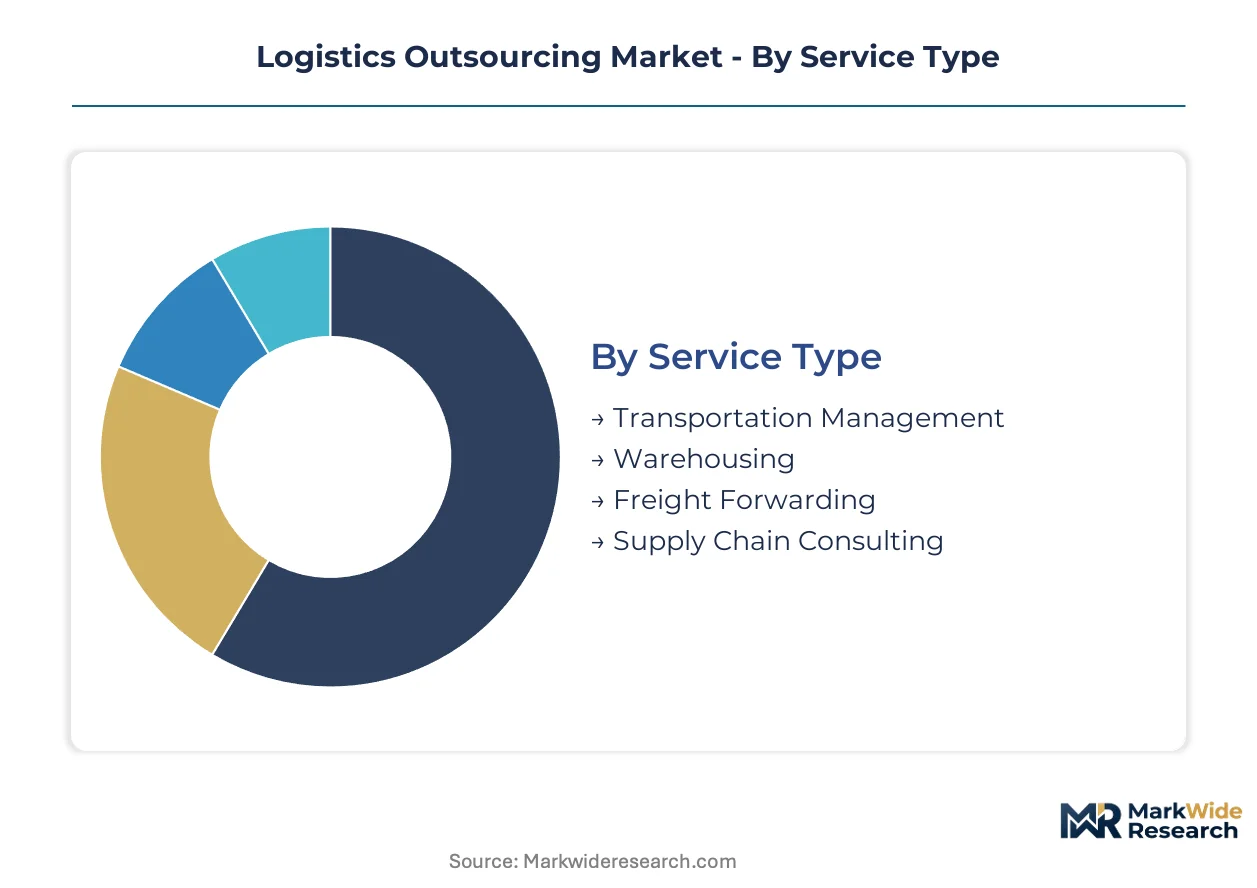
Logistics outsourcing providers structure service portfolios around distinct operational capabilities and client integration depths. Segment boundaries determine contract economics, technology deployment patterns, and regulatory compliance architectures.
Service Type:
Cost tier differentiation separates commodity capacity brokerage from specialized engineering-intensive services.
- Transportation Management:Fuel and capacity volatility transfer pricing risk from shippers to providers under fixed-rate agreements. Demand concentrates in trans-Pacific lanes where DHL and Kuehne + Nagel sustain premium positioning through air-ocean gateway networks. The EU Green Deal emissions mandates are reshaping contract structures around carbon-accounting capabilities.
- Warehousing:Facility operations span ambient storage through temperature-controlled infrastructure with defined inventory-accuracy SLAs. Mumbai and Delhi NCR face industrial zoning constraints that inflate facility costs beyond viable third-party logistics economics for undercapitalized operators.
- Freight Forwarding:Margin compression is forcing restructuring around specialized vertical expertise rather than commodity brokering.
- Supply Chain Consulting:Advisory services embed just-in-time engineering and network optimization for multinational manufacturers.
Transportation Management commands the established base. The steepest expansion runs through Supply Chain Consulting.
End User:
Application-specific requirements dictate provider selection criteria and compliance infrastructure investments.
- E-commerce:Last-mile velocity requirements drive automated fulfillment center deployment across archipelago geographies like Indonesia where multi-modal hub networks reward specialized providers. Real-time tracking is becoming a contractual baseline rather than premium feature.
- Manufacturing:Assembly line feed logistics commands premium pricing through embedded just-in-time engineering and multi-year contract lock-in. India's PLI scheme is generating contract logistics demand across automotive and electronics clusters.
- Retail:Seasonal demand volatility favors variable-cost outsourcing over captive distribution infrastructure.
- Pharmaceuticals:CDSCO cold-chain mandates and FDA traceability requirements demand capital-intensive temperature infrastructure that excludes undercapitalized regional operators.
Manufacturing anchors the revenue base. E-commerce is climbing the fastest as fulfillment networks expand across Asia-Pacific markets.
Solution:
Customer type determines orchestration-layer control depth and provider accountability scope.
- Third-Party Logistics:Operational execution of transportation, warehousing, and inventory management under defined cost-per-unit parameters. Third-Party Logistics dominates current contract volumes as shippers convert fixed infrastructure into variable costs.
- Fourth-Party Logistics:Strategic orchestration across multiple provider networks with end-to-end supply chain accountability. Fourth-Party Logistics arrangements are gaining traction among multinational manufacturers seeking control-layer integration.
- Integrated Logistics:Bundled service delivery combining multiple functional capabilities under single-contract governance.
- Reverse Logistics:Returns processing, refurbishment, and recycling operations with sustainability-linked performance metrics.
Third-Party Logistics holds the installed base. Fourth-Party Logistics shows the steepest adoption trajectory among enterprise shippers.
Technology:
Maturity gradients separate proven deployments from experimental implementations across provider technology stacks.
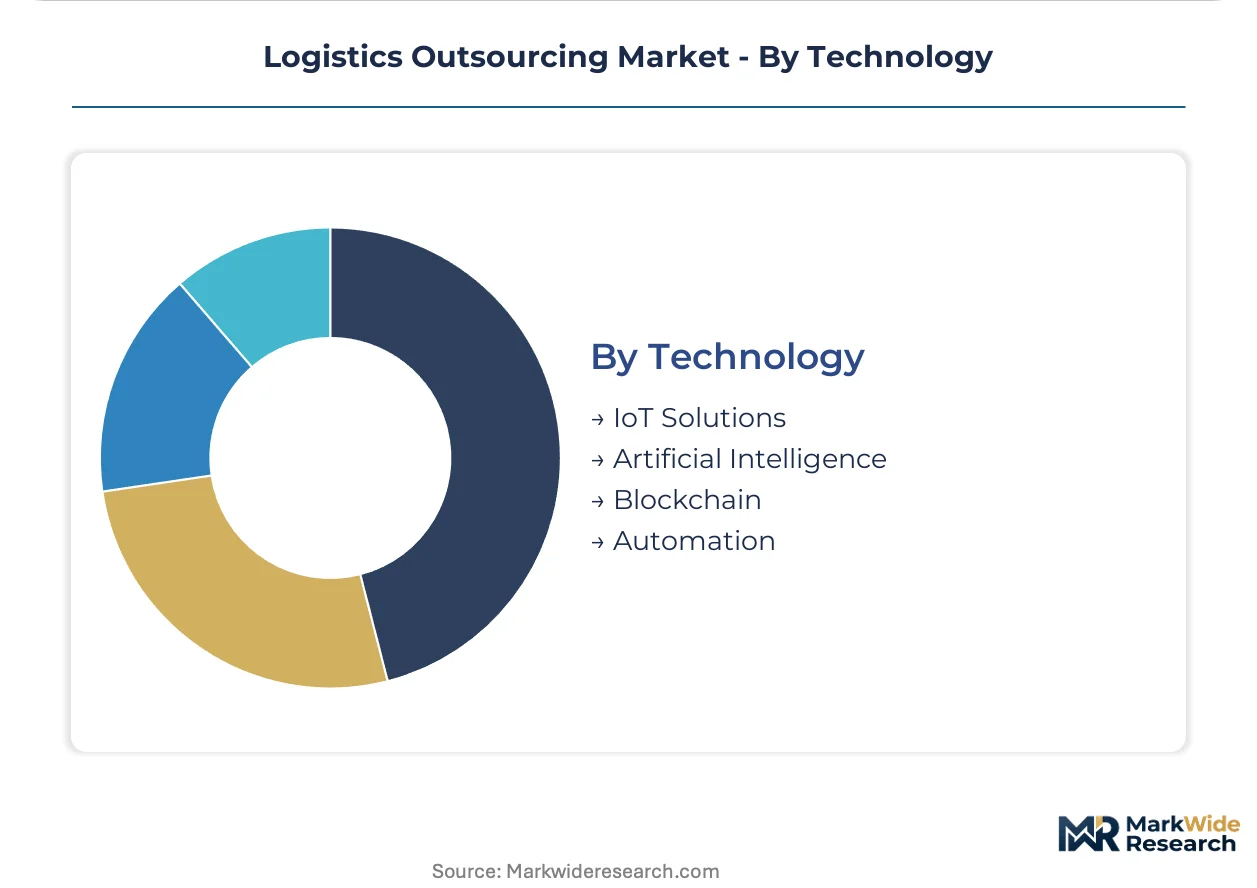
- IoT Solutions:Sensor-integrated fleet management and warehouse monitoring platforms delivering real-time visibility. IoT Solutions are attracting disproportionate investment as visibility becomes contractual baseline.
- Artificial Intelligence:Predictive inventory positioning and demand forecasting algorithms optimizing network deployment. AI deployment is accelerating in high-velocity e-commerce distribution centers.
- Blockchain:Distributed ledger applications for pharmaceutical traceability and cross-border documentation integrity.
- Automation:Autonomous mobile robots in warehouse picking operations rendering manual cart-based fulfillment obsolete across European and North American facilities.
IoT Solutions represent the most widely deployed category. Automation is gaining share fastest as labor cost arbitrage compresses across geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European manufacturers prioritize carbon-accounting integration in provider selection. Asian markets emphasize last-mile velocity over bundled service convenience. North American shippers unbundle transportation from warehousing to optimize lane-specific performance.
United States
E-commerce fulfillment networks and automotive assembly line feed logistics drive contract growth. FDA pharmaceutical traceability mandates and EPA emissions standards elevate compliance infrastructure requirements. The Dallas-Fort Worth metroplex concentrates automated distribution center deployment as retailers regionalize inventory positioning.
Germany
Automotive sequencing contracts and chemical logistics specialization anchor provider revenue. REACH substance registration and EU Green Deal disclosure requirements reshape contract structures around embedded regulatory expertise. The Rhine-Ruhr industrial corridor hosts dense third-party logistics clustering serving manufacturing exporters.
China
Domestic e-commerce platform fulfillment and battery supply chain localization generate contract demand. NMPA pharmaceutical distribution standards and MIIT dual carbon targets tighten operational compliance thresholds. The Yangtze River Delta concentrates automated warehouse deployment as labor cost arbitrage compresses.
India
PLI scheme manufacturing expansion and electronics cluster growth drive contract logistics adoption. BIS warehousing standards and CDSCO cold-chain mandates exclude undercapitalized regional operators. Mumbai and Delhi NCR face industrial zoning constraints that inflate facility costs and favor established providers.
Indonesia
Archipelago e-commerce fulfillment fragmentation rewards multi-modal hub network investments. The country's national logistics regulator is tightening cold-chain certification requirements for pharmaceutical distribution. Java-Bali corridor concentrates automated sorting facility deployment as platform retailers build captive last-mile infrastructure.
Logistics Outsourcing Market Competitive Environment
Capability concentration sits with specialized vertical operators; scale advantage sits with integrated global networks. The market structures around three tiers: asset-heavy integrators commanding trans-Pacific lane premiums, vertical specialists dominating pharmaceutical and automotive cold-chain segments, and digital platforms collapsing traditional brokerage economics. Strategic moves concentrate on automation capital deployment and vertical-specific certification acquisition.
Within the integrated logistics tier, DHL Supply Chain & Global Forwarding and Kuehne + Nagel occupy positions exemplifying gateway-network scale advantages. CEVA Logistics represents the vertical-specialist archetype with embedded automotive engineering capabilities. These three entities anchor competitive dynamics across the pharmaceutical, automotive, and e-commerce fulfillment segments referenced throughout this study.
| Leading Market Players |
|---|
| Amazon |
| DSV |
| DHL Supply Chain & Global Forwarding |
| Kuehne + Nagel |
| CEVA Logistics |
| Nippon Express |
| C.H. Robinson |
| GXO Logistics |
| GEODIS |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta's automated warehouse concentration compresses labor-cost arbitrage across Asian logistics networks, shifting pricing power toward providers with embedded IoT infrastructure and carbon-accounting compliance capabilities.
Pricing Analysis
Long-term offtake agreements dominate contract structures for automotive sequencing and pharmaceutical cold-chain services, while spot-market brokerage prevails in commodity freight forwarding. Three-tier pricing structure across premium, standard, and economy levels separates DHL's gateway-network positioning from regional operators lacking EU Green Deal certification. Cost compression in fixed-rate transportation management contracts is intensifying because diesel volatility transfers directly to provider margins. E-commerce retailers exhibit highest price sensitivity, demanding real-time visibility as a baseline feature rather than a premium upgrade.
Supply Chain Analysis
Extended payment terms from automotive OEMs and supply-chain finance facilities from large consumer goods manufacturers shape working capital dynamics across provider networks. Capacity concentrates in China, Germany, and India for automated material handling equipment and warehouse management systems. Provider profitability rests on diesel fuel, industrial real estate, and skilled automation technician availability. Single-source vulnerability runs through AMR component suppliers concentrated in East Asian manufacturing clusters. Distribution runs through hub-and-spoke networks anchored by multi-modal gateways in Rotterdam, Singapore, and Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Logistics outsourcing fragments across vertical specializations as EU emissions mandates and pharmaceutical traceability requirements create compliance-driven niche markets that reward embedded expertise over scale.
For Market Incumbents: Pre-empt margin erosion in commodity freight forwarding by acquiring cold-chain certification capabilities before CDSCO mandates harden market access in India. Backward integration into autonomous mobile robot maintenance networks addresses technician scarcity threatening automation deployment timelines. Consolidate automotive sequencing contracts through just-in-time engineering investments that lock in multi-year relationships.
For New Entrants and Emerging Players: Indonesia's archipelago e-commerce fulfillment gap offers white-space expansion for providers building multi-modal hub networks beyond Java-Bali corridor concentration. Target pharmaceutical distribution in secondary Indian cities where BIS warehousing standards have excluded undercapitalized regional operators. Lead with IoT-enabled visibility platforms as the go-to-market wedge, positioning real-time tracking as contractual baseline rather than premium feature.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with embedded regulatory data capabilities over asset-heavy integrators facing margin compression. Five-to-ten year viability hinges on carbon-accounting infrastructure ownership as EU Green Deal disclosure requirements harden. Acquisition targets should demonstrate pharmaceutical cold-chain certification or automotive sequencing engineering depth. Watch for automation capital deployment rates as the inflection signal separating scalable providers from labor-dependent competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation Capital Deployment | AMR fleet investments compress labor-cost arbitrage across European and North American distribution centers. |
| Vertical Certification Acquisition | CDSCO cold-chain and REACH substance registration capabilities exclude undercapitalized regional competitors. |
| Carbon-Accounting Infrastructure Buildout | Embedded EU Green Deal compliance expertise reshapes contract structures around sustainability disclosure. |
| Multi-Modal Hub Network Expansion | Archipelago geography in Indonesia rewards providers with integrated air-sea-last-mile capabilities. |
| Automotive Sequencing Engineering | Just-in-time assembly line feed logistics commands premium pricing and multi-year contract lock-in. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings, and EU regulatory submissions preceded structured interviews with supply chain directors at automotive OEMs, pharmaceutical distribution heads, e-commerce fulfillment operators, and third-party logistics procurement leads. Primary fieldwork captured contract structure evolution and automation deployment timelines. Secondary validation drew from BIS warehousing standard documents, CDSCO cold-chain guidelines, and EPA emissions compliance records. Bottom-up provider revenue triangulation against top-down market sizing anchored volume estimates.
Assumptions held fixed include regulatory implementation timelines for EU Green Deal mandates and PLI scheme manufacturing expansion rates in India; fuel price volatility and automation technician supply were varied across sensitivity scenarios. Segmentation modeling spanned service type, end-use vertical, solution tier, and technology deployment maturity. CAGRs derived from logistic curve fitting to adoption patterns observed across the analysis window. Forecast inputs incorporated e-commerce fulfillment network buildout schedules and battery supply chain localization incentives under EU Critical Raw Materials Act.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital freight platforms or hyperscaler captive logistics units would shift outcomes beyond modeled ranges. Macroeconomic contraction, regulatory acceleration, or breakthrough autonomous vehicle deployment would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Turkey Courier Express and Parcel (CEP) Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Logistics Visualization System Market