
 Digital Freight Forwarder Market | 2026-2036
Digital Freight Forwarder Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Freight Forwarder Market Insights
Real-time API connectivity between carrier networks and shipper ERP systems is reshaping how freight contracts are negotiated and executed. Flexport leverages proprietary data infrastructure to anchor trans-Pacific trade lanes. Zencargo competes through deep integration with retailer inventory systems. Sennder specializes in European road freight digitization, controlling pricing algorithms across fragmented carrier bases.
A digital freight forwarder is a technology-enabled logistics intermediary that automates rate procurement, booking, documentation, and shipment tracking through cloud-based platforms, typically integrating EDI, API, and blockchain protocols to replace manual freight brokerage workflows. Ocean freight digitization represents the most mature revenue pool, while AI-driven predictive routing in road freight captures the fastest expansion in margin contribution. Blockchain-enabled document verification across air freight corridors is attracting concentrated R&D investment from platform providers seeking to reduce customs clearance latency.
The EU Green Deal and its embedded CSRD disclosure mandates are forcing logistics platforms to embed emissions calculators directly into quotation workflows, reshaping supplier selection criteria. The U.S. Federal Maritime Commission has intensified scrutiny of detention and demurrage billing transparency, pressuring platforms to standardize fee visibility. Stakeholders must monitor whether regulatory fragmentation between the EU AI Act's algorithmic accountability rules and U.S. DOT autonomous trucking frameworks fragments platform architecture or drives unified compliance investments.
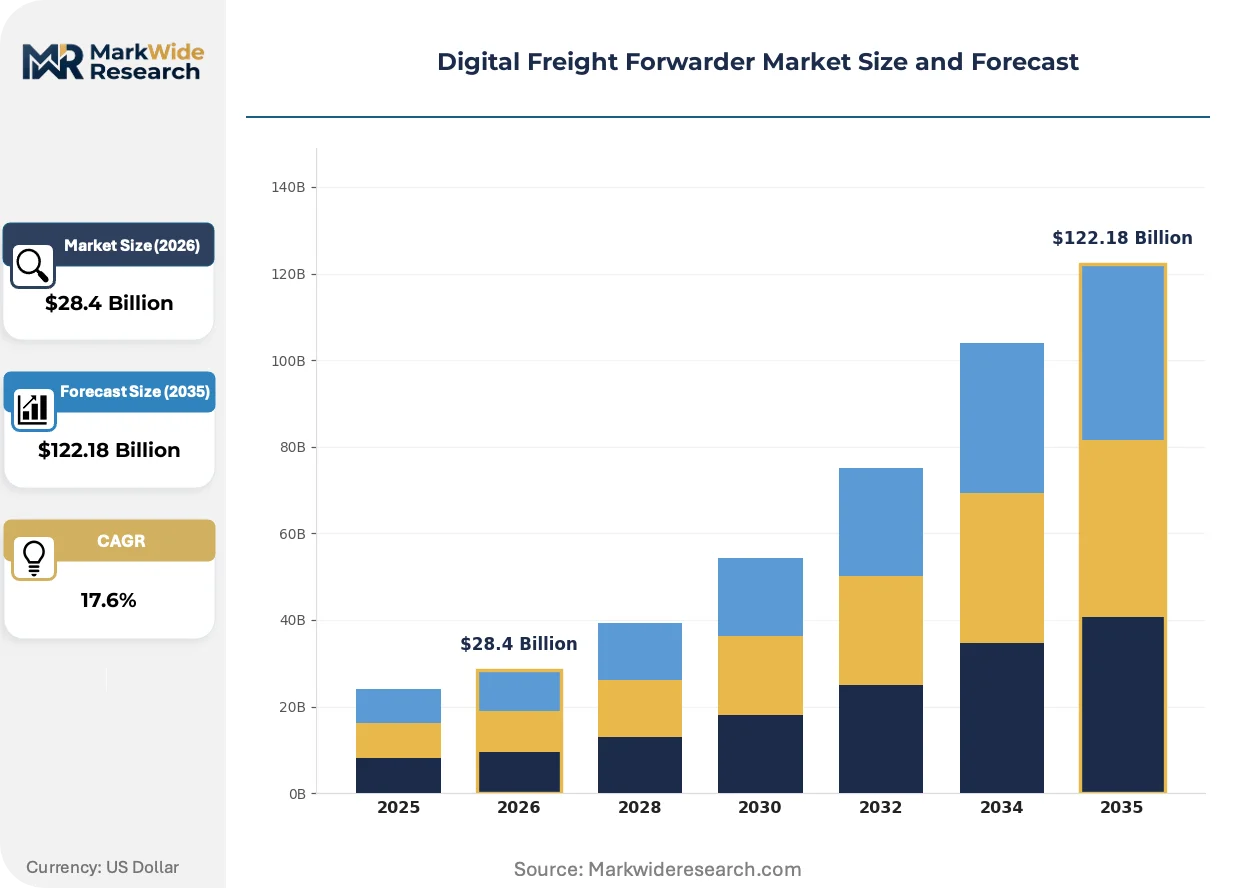
Market Dynamics
Real-time API connectivity between carrier networks and shipper ERP systems is compressing contract negotiation cycles and displacing manual freight brokerage workflows across trans-Pacific and European corridors.
Growth Catalysts
- E-commerce cross-border fulfillment:Online retailers in Germany and the Netherlands are expanding platform adoption to manage Hamburg-Rotterdam corridor traffic and customs documentation automation.
- EU Green Deal CSRD mandates:Embedded emissions calculators in quotation workflows are reshaping supplier selection criteria and accelerating platform upgrades among logistics providers.
- Blockchain document verification:Distributed ledger protocols are reducing air freight customs clearance latency through automated certificate-of-origin validation.
Market Restraints
- Fragmented carrier base concentration:European road freight digitization depends on pricing algorithm control across thousands of small fleet operators with inconsistent data standards.
- Regulatory friction from EU AI Act:Algorithmic accountability rules for automated freight matching are creating compliance architecture conflicts with U.S. DOT autonomous trucking frameworks.
- Detention and demurrage billing opacity:U.S. Federal Maritime Commission transparency scrutiny is forcing platform rebuilds of fee visibility modules.
Strategic Opportunities
- Predictive routing AI in road freight:Machine learning models optimizing European last-mile consolidation are capturing the fastest expansion in platform margin contribution.
- Inventory system integration depth:Direct API connections to retailer warehouse management systems are opening subscription revenue streams beyond transactional freight fees.
- German regulatory corridor leadership:Hamburg port authority digitization incentives are creating reference architecture for North Sea-Baltic multimodal platform deployment.
Industry Challenges
- Legacy EDI protocol migration:Shippers running on EDIFACT and ANSI X12 standards face multi-year integration timelines with cloud-native freight platforms.
- Emissions data verification skill gaps:Platform operators lack personnel trained in ISO 14064-aligned carbon accounting for CSRD-compliant client reporting.
- Multi-jurisdiction compliance synchronization:Engineering teams must reconcile EU Green Deal disclosure rules with U.S. billing transparency mandates within unified codebases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Freight Forwarder Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $122.18 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Road Freight, Rail Freight Technology: Blockchain, IoT, AI, Machine Learning End User: Manufacturers, Retailers, Wholesalers, E-commerce Operational Mode: Non-Asset-Based, Asset-Based, Hybrid, Third-Party Logistics |
| Companies Covered | FreightHub, GoFreight, Flexport, Flock Freight, LoadSmart, Freightos, Zencargo, Unicargo, sennder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Freight Forwarder Market Trends and Innovations
Freight platforms are converging operational technology with financial infrastructure, embedding payment settlement and trade finance directly into shipment execution workflows rather than treating these as separate service layers.
Artificial intelligence for predictive cargo routing is hybridizing traditional static lane pricing with dynamic demand forecasting. Third-party logistics providers in Germany and the Netherlands are adopting these systems within twelve-month procurement cycles. The technology is compressing the spread between spot and contract rates by enabling real-time capacity reallocation.
EU AI Act algorithmic accountability requirements are mandating explainability audits for automated freight matching engines. Platform providers must now document decision logic for carrier selection and pricing recommendations. Road freight digitization specialists serving the Hamburg-Rotterdam corridor are investing in compliance engineering ahead of enforcement timelines.
Shippers are consolidating vendor relationships around platforms offering integrated inventory visibility and freight execution. Retailers with complex European distribution networks are replacing point solutions with unified systems. This consolidation pattern is most pronounced among mid-market e-commerce operators in Germany seeking to reduce supplier management overhead.
Digital Freight Forwarder Market Segmentation
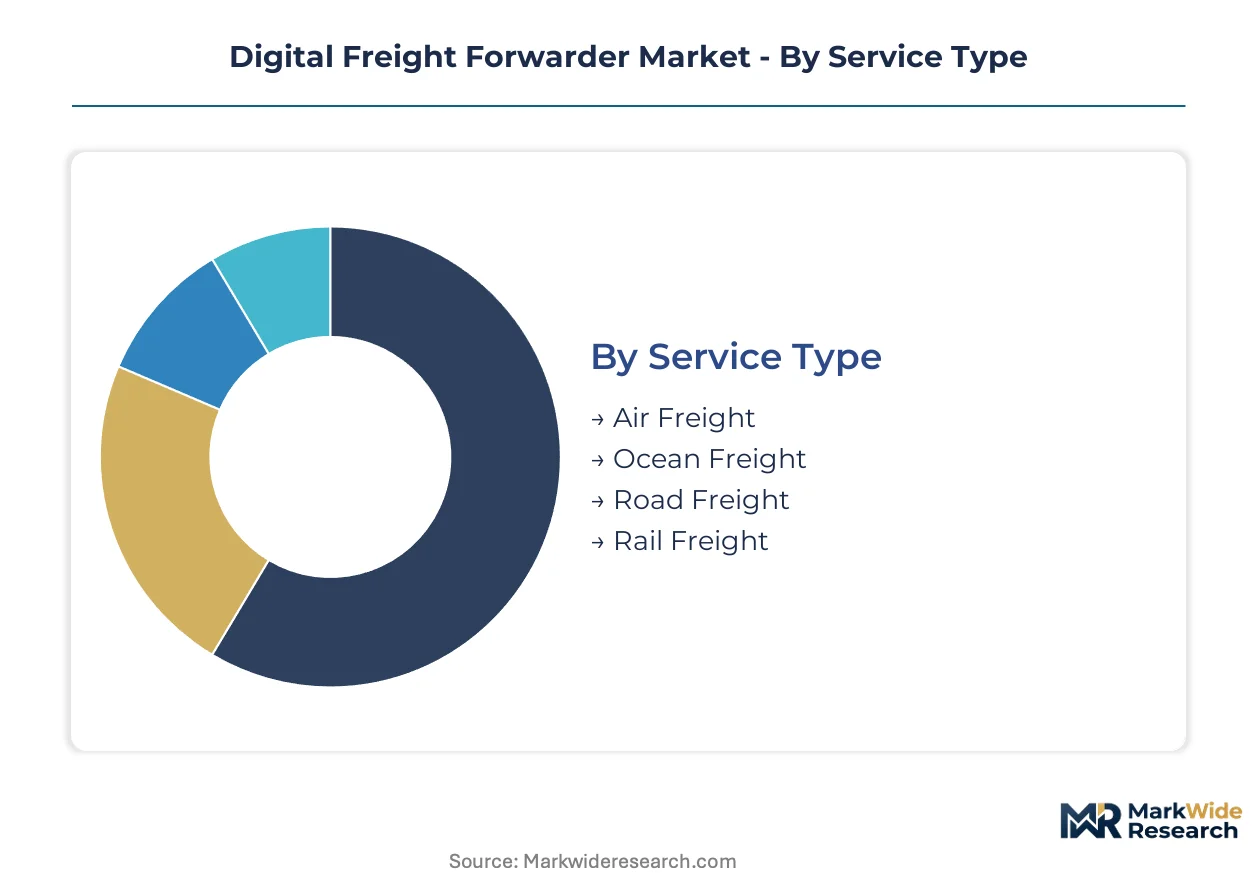
Digital freight forwarders structure their platform architectures around service capabilities, technology stacks, and customer operational profiles. Segment boundaries determine API integration complexity, pricing algorithm design, and regulatory compliance scope across carrier networks.
Service Type:
Mature revenue pools anchor ocean freight digitization, while emerging service layers capture margin expansion through predictive routing and multimodal orchestration.
- Ocean Freight:Container booking automation through API-connected carrier networks dominates transactional volume. German and Dutch e-commerce retailers drive Hamburg-Rotterdam corridor platform adoption for customs documentation workflows. The segment handles the majority of throughput; Road Freight is the fastest mover on share.
- Air Freight:Blockchain-enabled certificate-of-origin verification reduces customs clearance latency across trans-Pacific lanes. EU AI Act algorithmic accountability rules are forcing explainability audits for automated cargo matching engines serving pharmaceutical and electronics shippers.
- Road Freight:European fragmentation demands pricing algorithm control across thousands of small fleet operators with inconsistent telematics standards.
- Rail Freight:Intermodal corridor digitization between North Sea ports and Central European inland terminals remains underdeveloped relative to road and ocean alternatives.
Platform providers concentrate engineering resources where carrier API standardization has reached critical mass.
Technology:
Technology deployment follows a cost-tier logic: foundational infrastructure commands stable investment, while frontier capabilities attract speculative R&D allocation.
- AI:Machine learning models optimize European last-mile consolidation and compress spot-contract rate spreads through real-time capacity reallocation. German third-party logistics providers adopt these systems within accelerated procurement cycles.
- Machine Learning:Predictive cargo routing hybridizes static lane pricing with dynamic demand forecasting across fragmented carrier bases. Retail inventory system integration opens subscription revenue streams beyond transactional freight fees.
- Blockchain:Distributed ledger protocols automate document verification but face multi-year EDIFACT migration timelines with legacy shipper systems.
- IoT:Sensor networks for cargo condition monitoring remain siloed from financial settlement workflows despite technical maturity.
AI absorbs the largest share of platform R&D budgets; Machine Learning climbs fastest in margin contribution per deployment.
End User:
Customer segmentation reflects inventory velocity requirements and cross-border complexity tolerance.
- E-commerce:Mid-market operators in Germany consolidate vendor relationships around unified freight execution and inventory visibility systems to reduce supplier management overhead.
- Retailers:Complex European distribution networks drive replacement of point solutions with integrated platforms spanning warehouse management and carrier procurement.
- Manufacturers:Production-linked shipping schedules demand contract rate stability over spot market flexibility.
- Wholesalers:Batch shipment patterns align poorly with real-time API booking workflows optimized for high-frequency transactional volume.
E-commerce platforms process the highest booking frequency; Retailers expand contract value fastest through system integration depth.
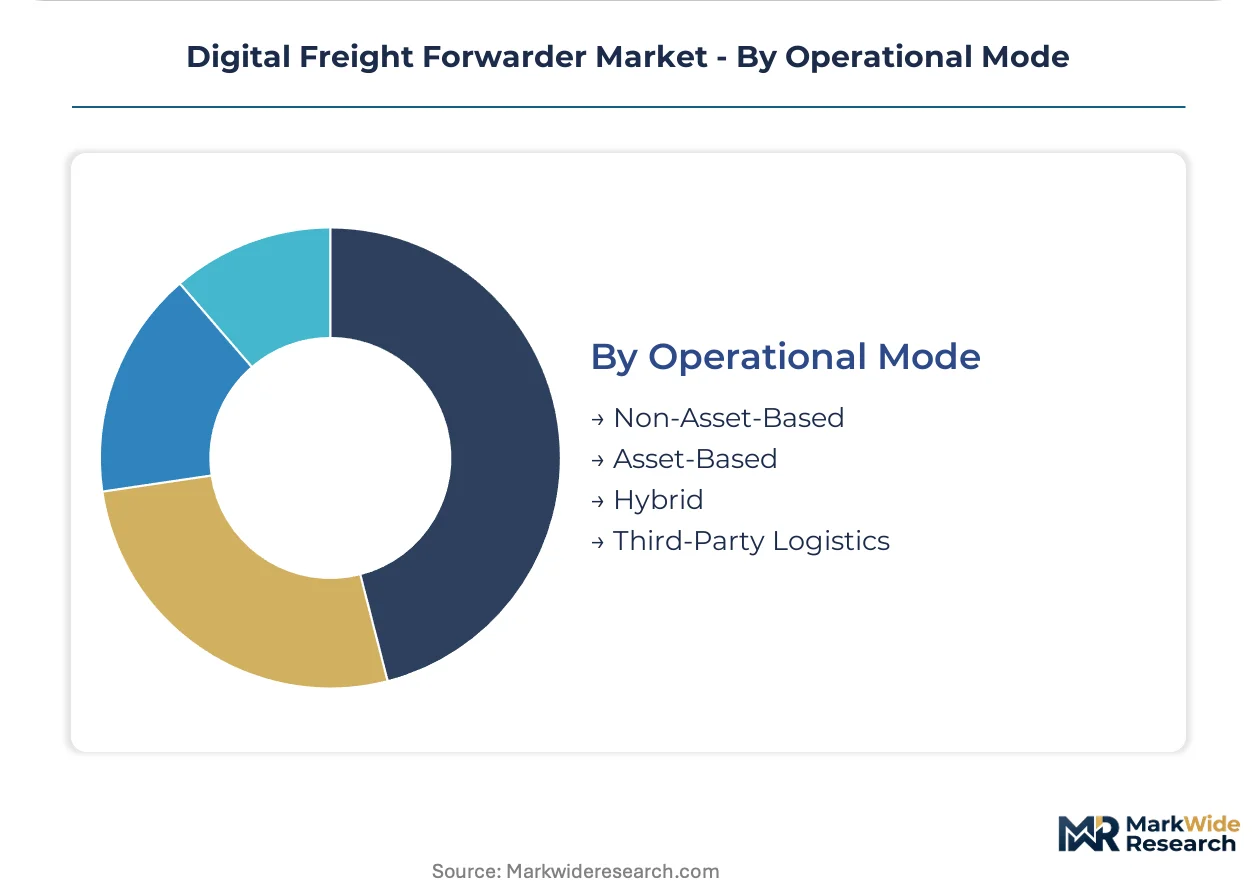
Operational Mode:
Asset ownership profiles determine balance sheet exposure and carrier relationship governance structures.
- Non-Asset-Based:Pure platform models aggregate third-party carrier capacity through algorithmic matching without fleet ownership. EU Green Deal CSRD mandates force embedded emissions calculators into quotation workflows, reshaping supplier selection criteria.
- Hybrid:Partial fleet ownership combined with platform marketplace access enables capacity guarantees during peak demand windows. Hamburg port authority digitization incentives create reference architecture for North Sea-Baltic multimodal deployment.
- Third-Party Logistics:Established 3PL operators retrofit legacy customer relationships with cloud-native booking interfaces.
- Asset-Based:Carrier-owned platforms face conflicts when allocating internal capacity against marketplace demand.
Non-Asset-Based models scale network effects most efficiently; Hybrid approaches gain traction where capacity reliability differentiates procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across major trade corridors are accelerating platform adoption as shippers seek real-time capacity reallocation. Nations with dense manufacturing-to-port linkages dominate transactional volume, while regulatory fragmentation shapes localized compliance architectures.
Germany
E-commerce cross-border fulfillment and Hamburg-Rotterdam corridor traffic drive heavy platform adoption among mid-market retailers. The EU Green Deal CSRD mandates force embedded emissions calculators into quotation workflows, reshaping supplier selection criteria. Hamburg port authority digitization incentives create reference architecture for North Sea-Baltic multimodal deployment.
United States
Trans-Pacific trade lane volume and detention-demurrage billing disputes concentrate platform development on fee transparency modules. The Federal Maritime Commission intensifies scrutiny of billing practices, pressuring standardized visibility. Los Angeles-Long Beach port complex congestion drives adoption of predictive cargo routing for inventory system integration.
Netherlands
Rotterdam-European hinterland connectivity and customs documentation automation attract logistics platform investment. EU AI Act algorithmic accountability rules mandate explainability audits for automated freight matching engines. Eindhoven-based electronics manufacturers integrate warehouse management systems with carrier procurement interfaces.
China
Manufacturing export density and Pearl River Delta port throughput sustain ocean freight digitization demand. Dual carbon goals from MEE tighten emissions reporting requirements for logistics providers. Shenzhen-Dongguan industrial clusters deploy blockchain-enabled certificate-of-origin verification to reduce customs clearance latency.
United Kingdom
Post-Brexit customs complexity and Irish Sea trade friction accelerate documentation automation platform adoption. GDPR data portability rules intersect with freight platform API standards, creating compliance engineering requirements. Felixstowe port digitization and Midlands distribution hub consolidation drive unified system procurement among retailers.
Digital Freight Forwarder Market Competitive Landscape
On the supply side, the industry is bifurcated between asset-light platform aggregators and hybrid operators with partial fleet ownership. Pure marketplace models scale network effects through algorithmic carrier matching without balance sheet exposure to vehicle assets. Two strategic archetypes dominate: ERP-integrated workflow specialists and corridor-specific pricing algorithm controllers. Competitive moves concentrate on strategic partnerships with port authorities and technology licensing for emissions compliance modules.
Within the European road freight digitization tier, sennder exemplifies pricing algorithm control across fragmented carrier bases. Flexport anchors trans-Pacific trade lane infrastructure through proprietary data systems. Zencargo occupies a position exemplifying deep retailer inventory system integration. These three represent distinct competitive vectors: geographic corridor specialization, ocean freight data infrastructure, and warehouse management connectivity.
| Leading Market Players |
|---|
| FreightHub |
| GoFreight |
| Flexport |
| Flock Freight |
| LoadSmart |
| Freightos |
| Zencargo |
| Unicargo |
| sennder |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European road freight is compressing spot rates and forcing small fleet operators toward platform aggregation, while Hamburg-Rotterdam corridor congestion sustains premium pricing for guaranteed capacity slots. This utilization divergence creates tiered supplier behavior: distressed carriers accept algorithmic price discovery, while bottlenecked lanes command fixed-contract premiums.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure blending per-shipment transactional fees with subscription tiers for API integration depth. Three-tier pricing stratifies across enterprise-grade ERP connectivity, standard dashboard access, and economy self-service portals, with differentiation driven by real-time visibility granularity and CSRD-compliant emissions reporting certification. Cost compression in the economy tier is intensifying because fragmented small fleets compete for algorithmic matching slots. Mid-market e-commerce retailers exhibit highest price sensitivity due to thin fulfillment margins, while pharmaceutical shippers prioritize customs clearance speed over rate negotiation.
Supply Chain Analysis
Extended payment terms from German automotive manufacturers are cascading through carrier networks, accelerating demand for supply-chain finance facilities embedded in freight platforms. Carrier capacity concentrates in Germany, the Netherlands, and Poland, with the Hamburg-Rotterdam corridor serving as the primary north-south axis. Platform operations draw from cloud infrastructure services, telematics hardware, and customs brokerage licenses as critical inputs. Single-source vulnerability in API gateway providers poses structural risk to real-time booking reliability. Distribution runs through port-centric consolidation hubs feeding inland container depots and last-mile cross-dock facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital freight forwarding represents a service-attach opportunity where emissions compliance modules and inventory system integration expand recurring revenue faster than core transaction fees. Predictive routing subscriptions and carbon accounting tools now outpace freight margin growth in platform economics.
For Market Incumbents: Harden algorithmic pricing engines against EU AI Act explainability mandates by documenting carrier selection logic and embedding audit trails. Consolidate API standardization partnerships with Hamburg and Rotterdam port authorities to lock in corridor dominance. Vertical integration into customs brokerage licenses defends against specialized documentation automation entrants eroding high-margin air freight segments. For New Entrants and Emerging Players: Mid-market road freight operators in Poland and the Czech Republic represent the most penetrable entry point, where telematics penetration lags German benchmarks but EU funding accelerates digitization. Target pharmaceutical shippers requiring temperature-controlled blockchain verification as a beachhead with premium pricing tolerance. A direct API-to-ERP integration go-to-market angle bypasses incumbent dashboard fatigue among procurement officers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across non-asset-based platform models as cloud infrastructure costs commoditize and carrier network effects compound. Long-term viability favors hybrid operators with selective fleet ownership guaranteeing capacity during Hamburg-Rotterdam peak windows. Acquisition targets should exhibit deep inventory system integration capabilities and CSRD-compliant emissions calculators. The signal to watch is EU Green Deal enforcement timelines accelerating shipper procurement decisions toward certified platforms.| Strategic Initiative | Industry Significance |
|---|---|
| API-ERP Integration Partnership | Direct warehouse management system connectivity locks in retailer subscription revenue beyond transactional fees. |
| CSRD Compliance Module Development | Embedded emissions calculators reshape supplier selection criteria under EU Green Deal mandates. |
| Port Authority Digitization Alliance | Hamburg and Rotterdam reference architectures accelerate multimodal platform deployment across North Sea-Baltic corridors. |
| Blockchain Document Verification | Automated certificate-of-origin validation reduces air freight customs clearance latency for pharmaceutical shippers. |
| Predictive Routing AI Deployment | Machine learning optimization of European last-mile consolidation captures fastest margin expansion in road freight. |
Research Methodology
A standing panel of freight platform CTOs, shipper procurement directors, carrier fleet managers, and customs brokerage operators provided ongoing calibration across the analysis window. Primary interviews combined with secondary validation from EU customs databases, port authority throughput statistics, SEC filings of listed logistics technology providers, and carrier telematics deployment surveys. Bottom-up shipment volume modeling and top-down addressable market sizing were triangulated against platform-reported transaction metrics.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions including service type, technology stack, end-user vertical, and operational mode. CAGRs derived from logistic curve fitting of adoption rates, adjusted for regulatory enforcement timelines and carrier API standardization velocity. Forecast inputs incorporated EU AI Act compliance cost estimates and Hamburg port digitization incentive disbursement patterns.
Macroeconomic conditions sit as an overlay; deviation in container shipping rates, EU carbon credit pricing, or trans-Pacific trade volumes would shift the trajectory. Forecasts reflect documented assumptions about carrier API adoption curves and shipper ERP integration timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Nigeria Freight and Logistics Market