
 In-Silico Drug Discovery Market | 2026-2036
In-Silico Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
In-Silico Drug Discovery Market Outlook
Generative AI for de novo molecular design is reconfiguring how therapeutic candidates progress from target validation to preclinical nomination. Schrödinger, Inc. leverages physics-based simulation platforms to anchor high-value partnerships with large pharmaceutical manufacturers. Insilico Medicine specializes in end-to-end generative pipelines that compress traditional discovery timelines. Exscientia plc operates autonomous design-make-test cycles that differentiate its service model from conventional CRO arrangements.
In-silico drug discovery encompasses computational methods that model molecular behavior, predict protein-ligand interactions, and optimize lead compounds through algorithmic iteration rather than laboratory synthesis alone. These systems typically integrate molecular dynamics simulations with free-energy perturbation calculations to rank compound affinity before physical production, serving the commercial purpose of reducing attrition rates in costly downstream development. Machine learning now dominates the technology segment as pharmaceutical buyers prioritize pattern recognition over rule-based docking scores for novel target classes. Lead optimization captures the fastest-growing application slice because sponsors demand iterative potency refinement without expanding wet-lab footprints. Cloud-based deployment leads the infrastructure dimension as research institutions and CROs seek elastic compute access without capital-intensive server commitments.
The FDA's emerging guidance on model-informed drug development shapes how sponsors structure computational evidence packages for IND meetings. EMA qualification opinions on novel methodologies further determine which in-silico platforms gain regulatory credibility across European submissions. ISO standards for computational model verification provide a cross-border benchmark that contract research organizations increasingly reference in qualification dossiers. Stakeholders must monitor how rapidly regulators incorporate AI-specific credibility frameworks into formal guidance documents.
Market Dynamics
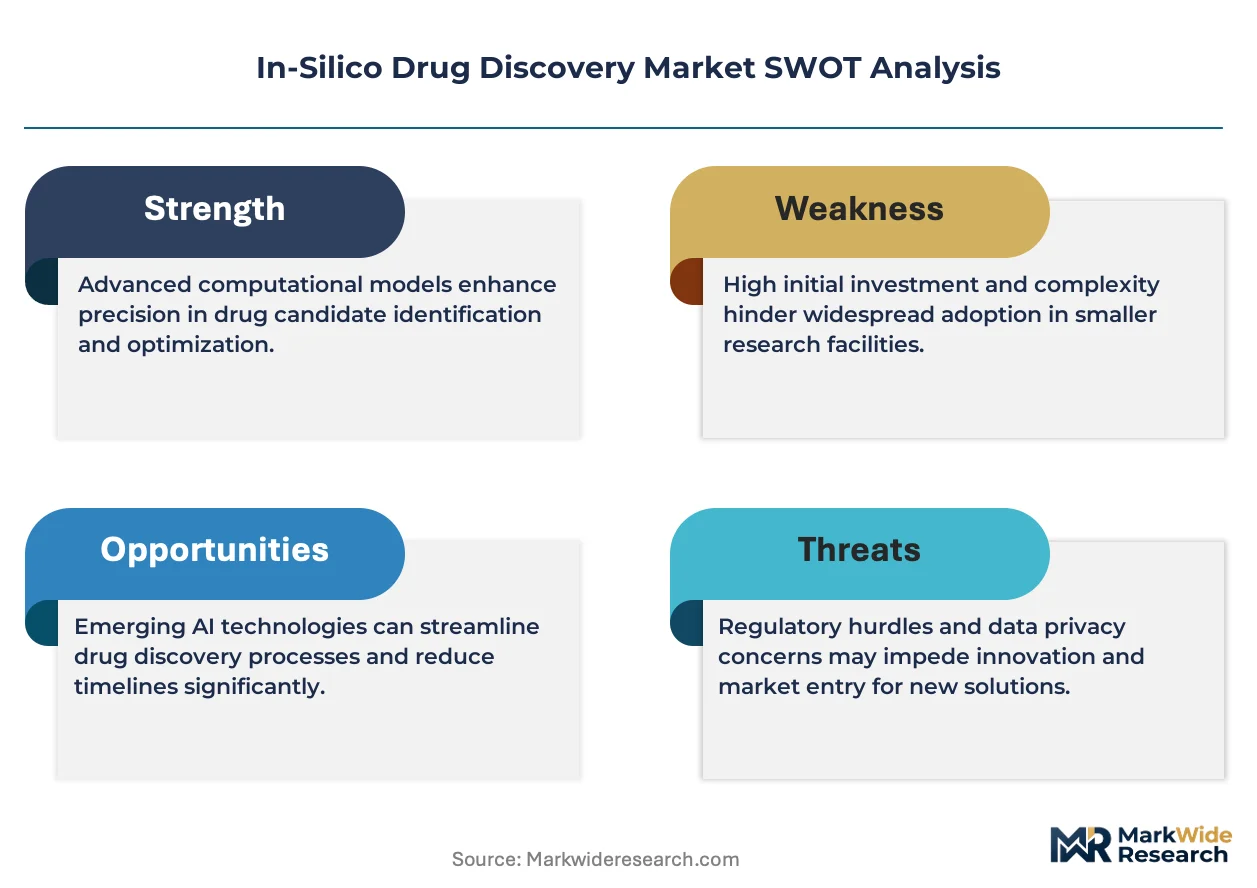
Generative chemistry platforms are compressing discovery timelines from years to months, forcing pharmaceutical sponsors to restructure R&D budgets toward computational infrastructure rather than traditional wet-lab capacity.
Growth Catalysts
- FDA Model-Informed Drug Development guidance:Sponsors now structure IND submissions around computational toxicology evidence, expanding procurement of predictive ADMET platforms.
- Free-energy perturbation methods:Physics-based affinity ranking reduces late-stage attrition in kinase and GPCR programs, cutting synthesis costs for lead optimization.
- United States federal funding:NIH and DARPA open-source cheminformatics infrastructure lowers capital barriers for biotech startups entering target validation.
Market Restraints
- GPU compute cost volatility:Molecular dynamics simulations require sustained access to NVIDIA A100/H100 clusters, exposing mid-size CROs to cloud pricing shocks.
- Training data scarcity:Published protein-ligand binding affinities remain sparse for novel target classes, limiting transfer learning effectiveness in orphan indications.
- EMA qualification timeline friction:Novel methodology opinions for AI-driven toxicity prediction extend platform validation cycles by 18-24 months.
Strategic Opportunities
- Antibody-drug conjugate design:Generative models for linker-payload optimization remain underdeveloped, creating white space for specialized platform builders.
- India's CDSCO pathway:Emerging regulatory clarity on computational bioequivalence studies opens substitute markets for generic sponsors seeking first-filer advantage.
- Quantum-classical hybrid simulation:Convergence of variational quantum eigensolvers with classical force fields promises breakthrough accuracy for metalloenzyme targets.
Industry Challenges
- Computational biologist talent scarcity:Hybrid expertise in physical chemistry and machine learning commands premium compensation, constraining platform scaling.
- Legacy ELN integration complexity:Sponsors face 12-18 month timelines to connect AI prediction engines with existing electronic lab notebook workflows.
- ISO 17025 accreditation gaps:Few contract research organizations hold computational model verification certification, limiting regulatory submission credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Silico Drug Discovery Market |
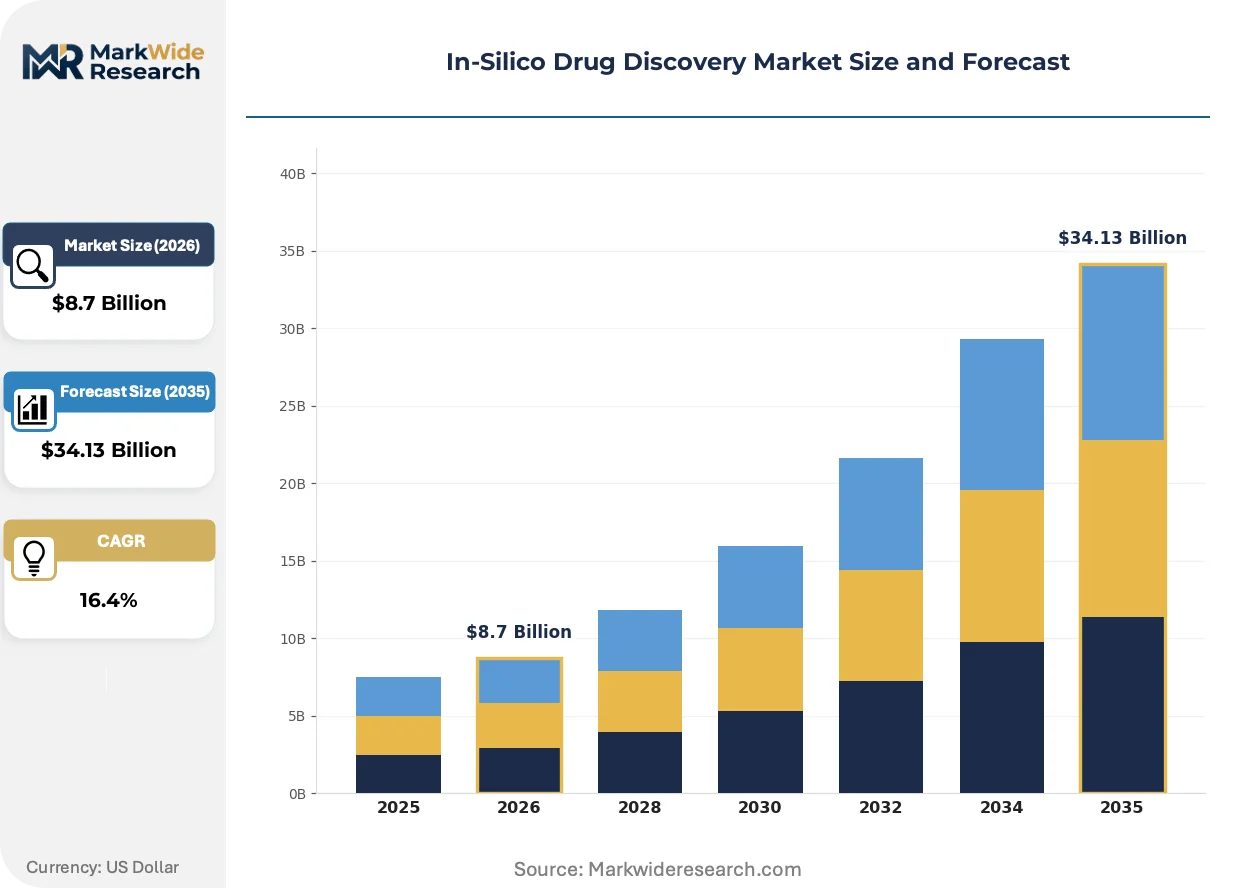
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Molecular Docking, Data Analytics, Simulation Application: Target Identification, Lead Optimization, Toxicity Prediction, Clinical Trials End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, CROs Deployment: Cloud-Based, On-Premises, Hybrid, Software as a Service |
| Companies Covered | Schrödinger, Inc., Insilico Medicine, Atomwise, Inc., BenevolentAI, Exscientia plc, Dassault Systèmes BIOVIA, Recursion Pharmaceuticals, Inc., Owkin, Inc., Simulations Plus, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Silico Drug Discovery Market Strategic Shifts
Differentiable physics engines are merging simulation with optimization, enabling real-time molecular property prediction that reshapes how medicinal chemists prioritize synthesis queues.
AlphaFold-derived structural databases are digitizing target validation workflows for previously intractable membrane proteins. Biotech sponsors now initiate hit-finding campaigns against GPCRs and ion channels without crystallography partnerships, compressing target-to-lead timelines. This capability is digitizing how early-stage portfolios get constructed, reducing dependence on academic structural biology collaborations.
The EU AI Act's risk classification framework for biomedical algorithms is forcing platform vendors to restructure documentation practices. High-risk designations for toxicity prediction models trigger conformity assessment obligations that extend sales cycles. European CROs are responding by pre-qualifying quality management systems against anticipated EMA guidance on AI credibility standards.
Biopharma procurement teams are unbundling software licenses from full-service discovery contracts, favoring API-accessible molecular generation tools over integrated platform subscriptions. Mid-size pharmaceutical buyers now assemble best-of-breed stacks from specialized vendors rather than committing to end-to-end partnerships. This pattern is most visible in the United States, where venture-backed biotechs prioritize flexibility over vendor consolidation.
In-Silico Drug Discovery Market Segmentation
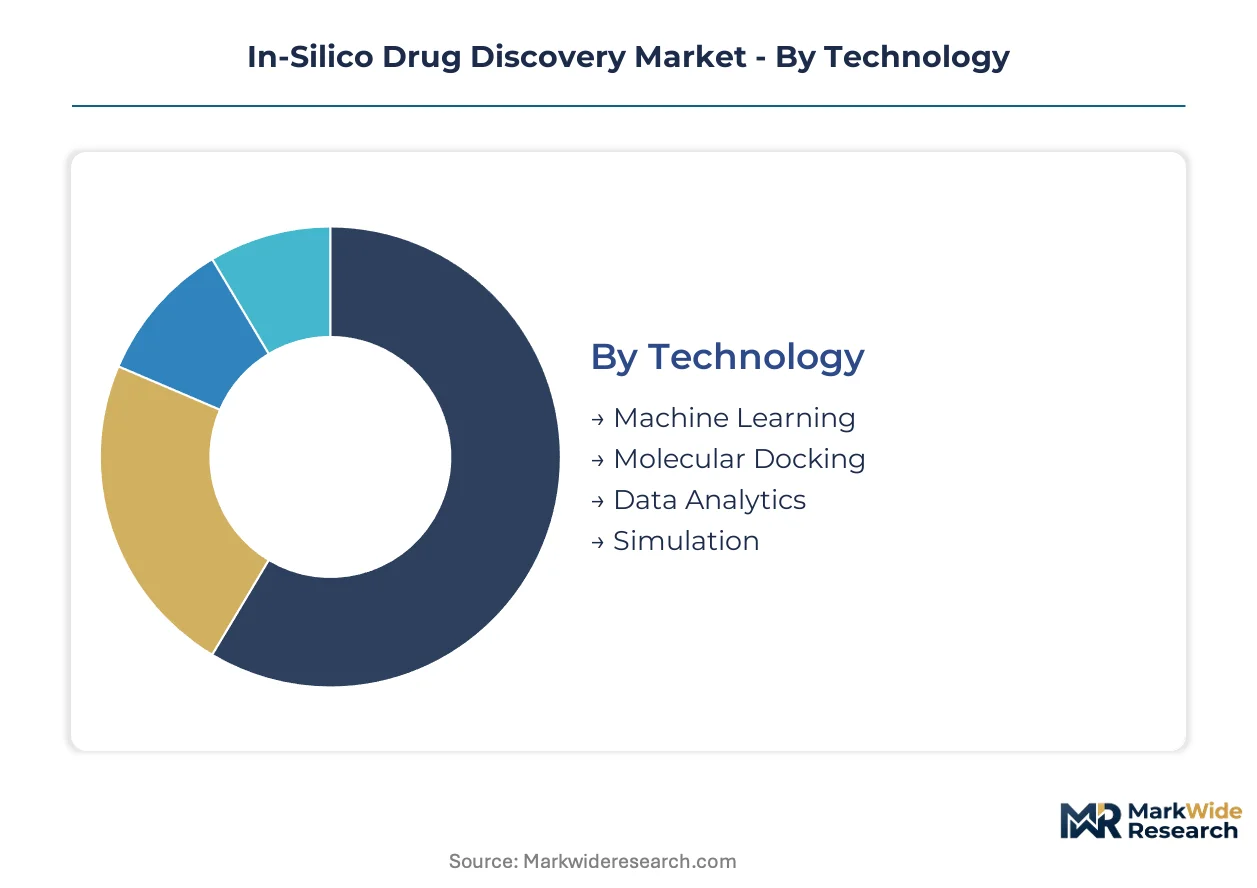
Segmentation in in-silico drug discovery reveals how computational investments flow across technology maturity curves and regulatory validation requirements. Buyers structure procurement around deployment economics and end-user technical capacity rather than uniform platform adoption.
Technology:
Cycle times vary dramatically—physics-based methods require months of parameter tuning while machine learning models retrain within days on new target data.
- Machine Learning:Pattern recognition algorithms process high-dimensional chemical space to predict bioactivity and ADMET properties from sparse training data. Pharmaceutical sponsors in the United States prioritize neural architectures for kinase inhibitor programs where FDA submission packages now incorporate model credibility documentation. GPU cluster access determines which mid-size biotechnology firms can operationalize deep learning pipelines.
- Molecular Docking:Structure-based virtual screening employs scoring functions to rank compound libraries against crystallographic or AlphaFold-derived protein conformations. European CROs leverage EMA-qualified docking protocols for early-stage target validation, though scoring accuracy degrades for metalloenzyme and membrane protein classes where conformational flexibility dominates.
- Data Analytics:Cheminformatics platforms integrate heterogeneous experimental databases to identify structure-activity relationships.
- Simulation:Molecular dynamics and free-energy perturbation calculations rank binding affinity through physics-based sampling.
Molecular docking anchors the volume base while machine learning gains share at the steepest rate.
Application:
Cost tiers stratify sharply—target identification runs on open-source infrastructure while clinical trial simulation demands enterprise licensing and regulatory consulting retainers.
- Lead Optimization:Iterative potency refinement cycles replace serial synthesis with computational prioritization, compressing timelines from years to months. Biotechnology sponsors in Massachusetts and California deploy generative models to explore chemical space beyond patent-protected scaffolds. FDA model-informed drug development guidance elevates computational evidence weighting in pre-IND meetings.
- Target Identification:Multi-omics integration and network pharmacology methods nominate disease-modifying targets from genomic and transcriptomic datasets. NIH-funded academic consortia provide open-access target validation tools that lower capital barriers for startup formation in Cambridge and South San Francisco clusters.
- Toxicity Prediction:Machine learning classifiers flag hepatotoxicity and cardiotoxicity liabilities from molecular structure alone.
- Clinical Trials:Physiologically-based pharmacokinetic modeling and virtual patient simulation optimize dosing regimens.
Target identification commands the widest installed base while lead optimization expands most quickly as sponsors restructure R&D budgets toward computational infrastructure.
End User:
Customer type determines procurement sophistication—pharmaceutical incumbents negotiate enterprise platforms while research institutions assemble grant-funded toolchains.
- Pharmaceutical Companies:Large manufacturers integrate in-silico platforms into centralized therapeutic area workflows, anchoring multi-year partnerships with physics-based simulation vendors. Internal computational chemistry groups at firms headquartered in New Jersey and Basel validate models against proprietary assay databases to support FDA submission credibility.
- CROs:Contract research organizations differentiate through ISO 17025-accredited computational model verification and regulatory qualification dossiers. Mid-size European CROs face 18-24 month EMA opinion timelines for novel AI-driven toxicity methodologies, constraining platform rollout speed.
- Biotechnology Firms:Venture-backed startups prioritize API-accessible molecular generation tools over integrated subscriptions.
- Research Institutions:Academic groups leverage NIH and DARPA open-source cheminformatics infrastructure.
Pharmaceutical companies dominate current procurement value while CROs capture the steepest expansion trajectory as sponsors outsource computational validation.
Deployment:
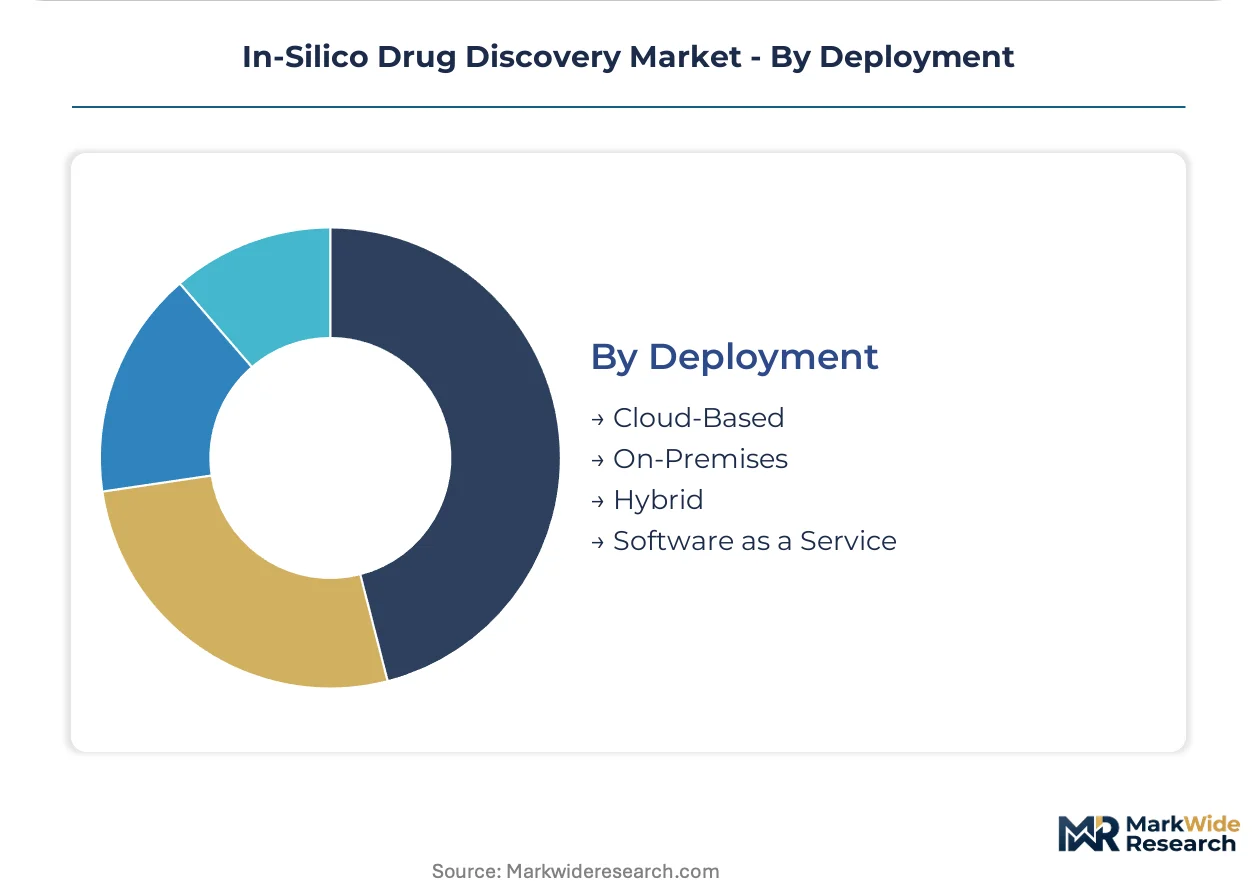
Volume concentrates in elastic compute arrangements that eliminate capital-intensive server commitments for mid-size research organizations.
- Cloud-Based:Elastic GPU and CPU provisioning enables molecular dynamics simulations without fixed infrastructure investment. Biotechnology startups in the United States favor Amazon Web Services and Google Cloud deployments for AlphaFold structure prediction and generative chemistry workloads. NVIDIA A100/H100 pricing volatility exposes sustained simulation budgets to cost shocks.
- Software as a Service:Subscription molecular generation platforms provide browser-accessible tools without local installation or maintenance overhead. European mid-size pharmaceutical buyers unbundle SaaS licenses from full-service discovery contracts to assemble best-of-breed stacks.
- On-Premises:Air-gapped installations serve sponsors with stringent data security requirements for proprietary compound libraries.
- Hybrid:Mixed deployments route sensitive target data to local infrastructure while pushing large-scale screening to cloud burst capacity.
Cloud-based deployment anchors the volume base while software as a service gains share at the steepest rate among venture-backed biotechs prioritizing procurement flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based platform vendors export AI-driven molecular modeling tools to European pharmaceutical sponsors seeking EMA-compliant computational evidence packages. This transatlantic trade corridor channels physics-based simulation licenses and generative chemistry APIs into German and Swiss R&D budgets.
United States
NIH and DARPA funding streams sustain open-source cheminformatics infrastructure that lowers capital barriers for startup formation. FDA model-informed drug development guidance elevates computational toxicology evidence requirements in IND submissions. Greater Boston and South San Francisco clusters concentrate venture-backed biotechs deploying AlphaFold-derived structure prediction for membrane protein targets.
Germany
Boehringer Ingelheim and Merck KGaA anchor procurement of free-energy perturbation platforms for kinase program lead optimization. EMA qualification opinions on novel AI methodologies extend platform validation timelines for domestic CROs. Heidelberg and Munich research consortia integrate EU-funded quantum-classical hybrid simulation projects into metalloenzyme drug discovery pipelines.
Switzerland
Novartis and Roche headquarters drive enterprise licensing of physics-based molecular dynamics engines for therapeutic area workflows. Swissmedic emerging guidance on computational model credibility shapes documentation requirements for toxicity prediction submissions. Basel-Zurich corridor concentrates contract research organizations pursuing ISO 17025 accreditation for computational verification services.
United Kingdom
BenevolentAI and Exscientia plc anchor domestic generative chemistry platform development for autonomous design-make-test cycles. MHRA alignment with FDA model-informed drug development frameworks streamlines transatlantic submission strategies for computational evidence packages. London-Cambridge cluster concentrates AI-first drug discovery startups leveraging UK Research and Innovation funding for target validation infrastructure.
China
NMPA pilot programs on model-informed drug development create regulatory pathways for computational bioequivalence studies in generic drug applications. Domestic pharmaceutical sponsors accelerate procurement of machine learning platforms for hepatotoxicity prediction to support IND dossiers. Shanghai and Beijing clusters concentrate academic-industry partnerships deploying AlphaFold structures for GPCR target validation without crystallography dependencies.
In-Silico Drug Discovery Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement relationships. Large pharmaceutical manufacturers negotiate multi-year enterprise platforms anchoring centralized therapeutic area workflows. Mid-size biotechnology firms assemble best-of-breed stacks from API-accessible molecular generation tools. Two dominant competitive moves structure rivalry: physics-based simulation vendors pursue strategic partnerships with cloud infrastructure providers, while generative AI specialists secure capacity reservations with GPU cluster operators.
Within the physics-based simulation tier, Schrödinger, Inc. and Dassault Systèmes BIOVIA exemplify platform vendors anchoring high-value partnerships through enterprise licensing structures. Among generative chemistry specialists, Insilico Medicine occupies a position representing end-to-end pipeline compression capabilities. Exscientia plc sits within the autonomous design-make-test segment, differentiating service models from conventional CRO arrangements through iterative algorithmic iteration rather than laboratory synthesis alone.
| Leading Market Players |
|---|
| Schrödinger, Inc. |
| Insilico Medicine |
| Atomwise, Inc. |
| BenevolentAI |
| Exscientia plc |
| Dassault Systèmes BIOVIA |
| Recursion Pharmaceuticals, Inc. |
| Owkin, Inc. |
| Simulations Plus, Inc. |
| Others |
Value Chain & Pricing Dynamics
NVIDIA A100/H100 GPU cluster concentration in United States hyperscaler regions anchors margin pools in cloud-based molecular dynamics simulation tiers, while downstream pharmaceutical buyers face escalating compute reservation costs that reshape procurement toward elastic SaaS arrangements.
Pricing Analysis
Cost-plus contracts with NVIDIA GPU indexation dominate enterprise molecular dynamics licensing, though machine learning platform providers increasingly shift toward consumption-based SaaS tiers. Price differentiation separates ISO 17025-accredited CRO verification services from unvalidated software licenses, with certification premiums widening as FDA model-informed drug development guidance elevates evidence standards. Pricing pressure stems from mid-size biotechnology sponsors unbundling full-service discovery contracts into API-accessible toolchains, compressing integrated platform margins. Venture-backed startups in Cambridge and South San Francisco clusters exhibit highest price sensitivity, while Basel and New Jersey headquartered pharmaceutical incumbents absorb premium physics-based simulation costs without volume negotiation.
Supply Chain Analysis
Cloud infrastructure contract manufacturing concentrates in Amazon Web Services, Google Cloud, and Microsoft Azure data center regions across the United States, Ireland, and Singapore, with GPU foundry capacity anchored in Taiwan and South Korea. Raw material dependencies span NVIDIA H100 silicon wafers, high-bandwidth memory modules, and specialized cooling systems for sustained molecular dynamics workloads. Supply chain risk centers on single-source vulnerability to NVIDIA GPU allocation policies and hyperscaler pricing volatility. Distribution runs through direct enterprise licensing to pharmaceutical headquarters, API marketplace integrations for biotech startups, and CRO resale arrangements for regulatory consulting bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where interoperability between AlphaFold-derived structural databases and generative chemistry APIs is displacing vertically integrated discovery workflows, rewarding modular toolchain assembly over end-to-end vendor consolidation.
For Market Incumbents: Build regulatory credibility moats through ISO 17025 accreditation for computational model verification and pre-qualified EMA opinion dossiers. Incumbent physics-based simulation vendors must anchor multi-year enterprise partnerships with cloud infrastructure providers to secure GPU capacity reservations against emerging generative AI specialists. Threat of sponsor unbundling demands defensive API accessibility investments that preserve platform relevance in best-of-breed procurement stacks. For New Entrants and Emerging Players: Establish a beachhead in antibody-drug conjugate linker-payload optimization, where generative models remain underdeveloped relative to small-molecule chemistry. White space concentrates in quantum-classical hybrid simulation for metalloenzyme targets, with Heidelberg and Munich research consortia providing collaborative entry points. Go-to-market angle should emphasize autonomous design-make-test differentiation from conventional CRO service models, targeting venture-backed biotechs in Greater Boston seeking timeline compression without wet-lab footprint expansion. For Investors and Strategic Acquirers: Capital is best deployed toward generative chemistry platforms with demonstrated FDA submission credibility and established GPU cluster operator partnerships for capacity security. Long-term viability over the next decade hinges on regulatory qualification velocity rather than algorithmic novelty alone. Acquisition target archetype combines end-to-end pipeline compression capabilities with EMA opinion track records. Signal to watch is CDSCO pathway clarity on computational bioequivalence studies, which would validate India substitute market strategies for generic sponsor first-filer advantage.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Capacity Reservation Agreements | Secures NVIDIA A100/H100 allocation against cloud pricing volatility for sustained molecular dynamics workloads. |
| ISO 17025 Accreditation Investment | Enables CRO differentiation through computational model verification certification for FDA submission credibility. |
| API-First Platform Unbundling | Captures venture-backed biotech procurement shifting toward modular molecular generation toolchains. |
| EMA Pre-Qualification Dossiers | Accelerates novel AI methodology opinion timelines that currently extend platform validation cycles. |
| Quantum-Classical Hybrid Partnerships | Positions for metalloenzyme target breakthrough accuracy through EU-funded research consortia integration. |
Study Parameters
Desk research of FDA guidance documents, EMA qualification opinions, NIH funding disclosures, and cloud infrastructure capex reports preceded structured interviews with computational chemistry directors, regulatory affairs leads at pharmaceutical sponsors, CRO platform verification specialists, and GPU cluster procurement officers. Primary fieldwork combined with secondary validation against SEC filings, ClinicalTrials.gov records, and ISO certification databases. Bottom-up segmentation modeling triangulated against top-down market sizing from federal funding flows and enterprise licensing disclosures.
Assumption sets held FDA model-informed drug development guidance trajectory and NVIDIA GPU supply allocation policies fixed across the projection horizon, while varying biotechnology startup formation rates and EMA opinion timeline friction. The analytical framework modeled technology segments by deployment economics, application tiers by regulatory validation requirements, and end-user categories by procurement sophistication. CAGRs derived from segment-level growth drivers including AlphaFold structural database expansion, generative chemistry platform maturation, and cloud-based elastic compute adoption curves.
Stress conditions across GPU pricing volatility, training data scarcity for orphan indications, and EMA AI credibility framework implementation speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory qualification timeline shifts and hyperscaler capacity allocation policy changes. Cross-checking against NIH and DARPA funding trajectory disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
H1N1 Vaccination Market