
 Cheese Ripening Enzymes Market | 2026-2036
Cheese Ripening Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Ripening Enzymes Market Analytics
Artisanal cheese production is recalibrating enzyme procurement priorities as craft dairies scale output. Chr. Hansen Holding A/S leverages its microbial strain library to dominate Northern European supply chains. DSM-Firmenich sustains R&D intensity across coagulant-to-ripening enzyme integration. Novonesis anchors global fermentation capacity with specialized protease and lipase portfolios.
Cheese ripening enzymes comprise proteinaceous biocatalysts—primarily proteases, lipases, and esterases—that hydrolyze milk proteins and fats to develop flavor, texture, and aroma during affinage. These enzymes function at specific pH ranges and temperatures, with microbial variants produced via submerged fermentation of Aspergillus or Rhizopus species now displacing traditional animal-derived extracts. Microbial product types command the largest volume share due to cost scalability and kosher-halal compliance, while fungal enzymes capture premium positioning among PDO-protected European producers. Application concentration in Cheddar and Parmesan reflects these varieties' extended aging requirements and corresponding enzyme dosage intensity.
EU REACH and EFSA novel food regulations shape strain approval timelines and labeling requirements for microbial enzyme preparations. FDA GRAS self-determination pathways in the United States create asymmetric market access speeds versus Europe's pre-market authorization rigor. Stakeholders must monitor evolving enzyme origin disclosure mandates and fermentation substrate traceability standards as clean-label enforcement tightens across major dairy markets.
Market Dynamics
Clean-label fermentation protocols are forcing enzyme suppliers to revalidate microbial strain lineages as EFSA novel food scrutiny intensifies across European dairy cooperatives. This regulatory pressure cascades through procurement contracts, favoring certified biological catalysts with full substrate traceability.
Growth Catalysts
- EFSA Novel Food Pathways:Accelerated strain approvals for non-GMO microbial enzymes reduce time-to-market for fermentation-derived lipases. Dutch and Italian cooperatives prioritize suppliers with pre-cleared dossiers.
- PDO-Protected Aging Protocols:France's Appellation d'Origine Contrôlée regulations mandate specific ripening durations, locking in enzyme dosage intensity for Comté and Roquefort production.
- Submerged Fermentation Scale-Up:Aspergillus oryzae cultivation in controlled bioreactors cuts batch-to-batch variability, attracting Cheddar producers seeking kosher-halal compliance without animal-derived extracts.
Market Restraints
- EU REACH Registration Costs:Toxicological dossier preparation for each microbial enzyme variant imposes six-figure compliance burdens on mid-tier fermentation houses.
- Animal-Derived Extract Supply Concentration:Traditional rennet and lipase sourcing from calf stomachs concentrates in Mediterranean abattoir networks, exposing buyers to halal certification volatility.
- pH Stability Limitations:Microbial proteases lose efficacy below pH 5.2, restricting application in high-acid fresh cheese categories where flavor development demands persist.
Strategic Opportunities
- India's Organized Dairy Expansion:Amul and Mother Dairy cooperatives are piloting microbial lipase programs for Paneer aging, creating first-mover advantage for REACH-compliant suppliers.
- Precision Fermentation Convergence:CRISPR-edited Aspergillus strains combined with AI-driven bioprocess optimization promise 40% yield improvements in protease titers.
- Direct-to-Artisan Distribution:Specialty enzyme suppliers bypass traditional dairy ingredient distributors via e-procurement platforms serving French and Italian farmstead producers.
Industry Challenges
- Fermentation Specialist Talent Scarcity:Industrial microbiologists with dairy enzyme experience command premium compensation, constraining R&D expansion at mid-cap suppliers.
- Legacy Coagulant System Integration:Ripening enzyme dosing must synchronize with existing chymosin schedules, complicating process revalidation at multi-product creameries.
- Organic Certification Timeline Compression:USDA Organic and EU Organic enzyme approvals require 18-24 month substrate audits, delaying product launches for clean-label positioned entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Ripening Enzymes Market |
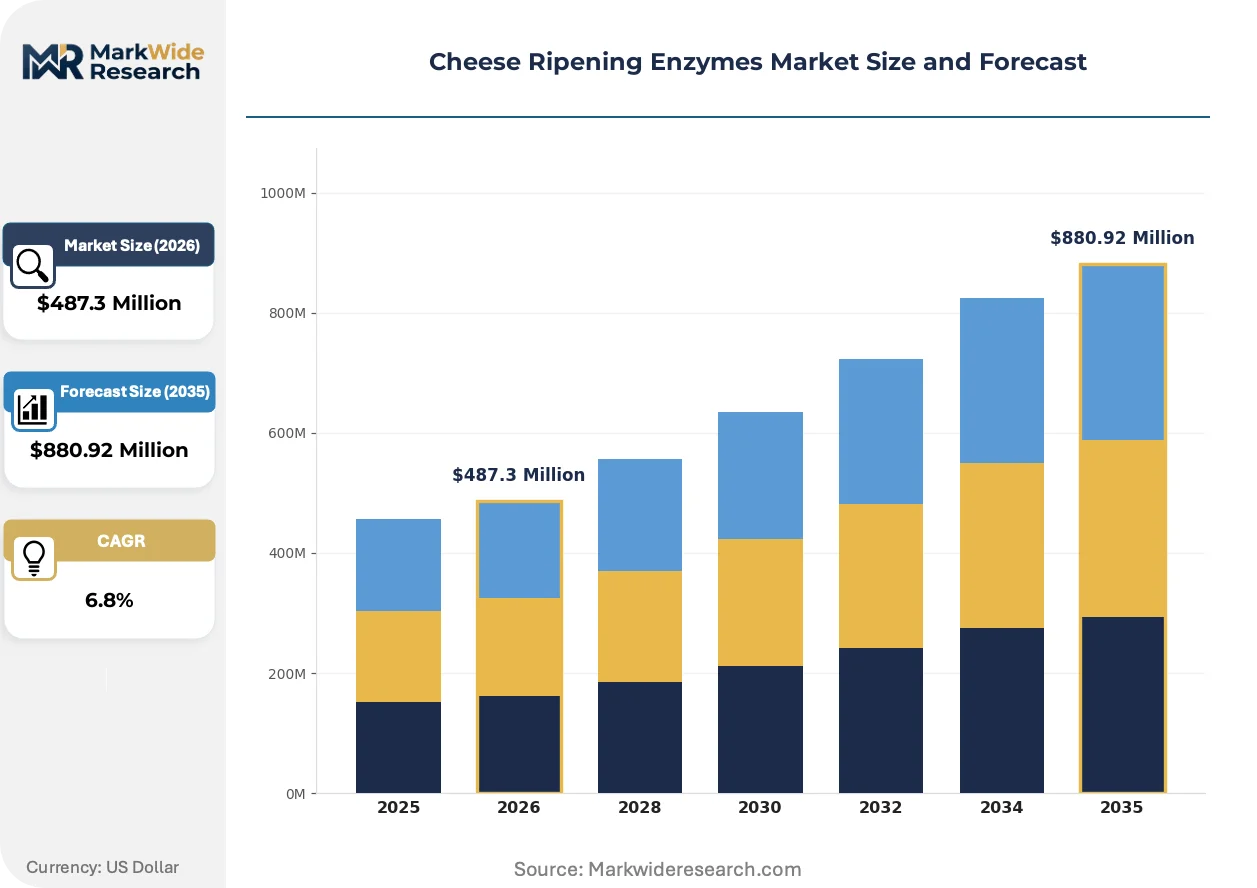
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Animal, Plant, Fungal Application: Cheddar, Mozzarella, Blue Cheese, Parmesan End User: Dairy Manufacturers, Restaurants, Retailers, Food Service Deployment: On-premises, Cloud-based, Hybrid, Automated |
| Companies Covered | Chr. Hansen Holding A/S, DSM Food Specialties, DuPont Nutrition & Biosciences, Novozymes A/S, International Flavors & Fragrances Inc., DSM-Firmenich, Novonesis, Amano Enzyme Inc., Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Ripening Enzymes Market Evolving Landscape
Bioprocess digitization and regulatory disclosure mandates are converging to reshape how enzyme suppliers validate and commercialize microbial catalysts for dairy applications.
CRISPR-edited Aspergillus niger strains with enhanced lipase secretion profiles are integrating into commercial fermentation workflows. Northern European contract manufacturers adopt these platforms within 24-month validation cycles. This gene-editing adoption is compressing strain development timelines from five years to eighteen months while satisfying EFSA's evolving GMO disclosure thresholds.
EU REACH Article 33 substance disclosure requirements now extend to enzyme fermentation substrates, forcing suppliers to map carbon source provenance through multi-tier supplier networks. Industrial consequence includes mandatory substitution of petrochemical-derived media components with agricultural waste streams. Fungal enzyme producers serving PDO-protected French cheesemakers face the steepest compliance ramps.
Artisan creameries now specify enzyme origin certificates in procurement tenders, displacing commodity-grade spot purchasing. French and Italian farmstead producers lead this specification intensity, demanding batch-level strain genealogy documentation. This verification-driven buying pattern concentrates contract volumes with suppliers maintaining integrated quality management systems.
Cheese Ripening Enzymes Market Segmentation
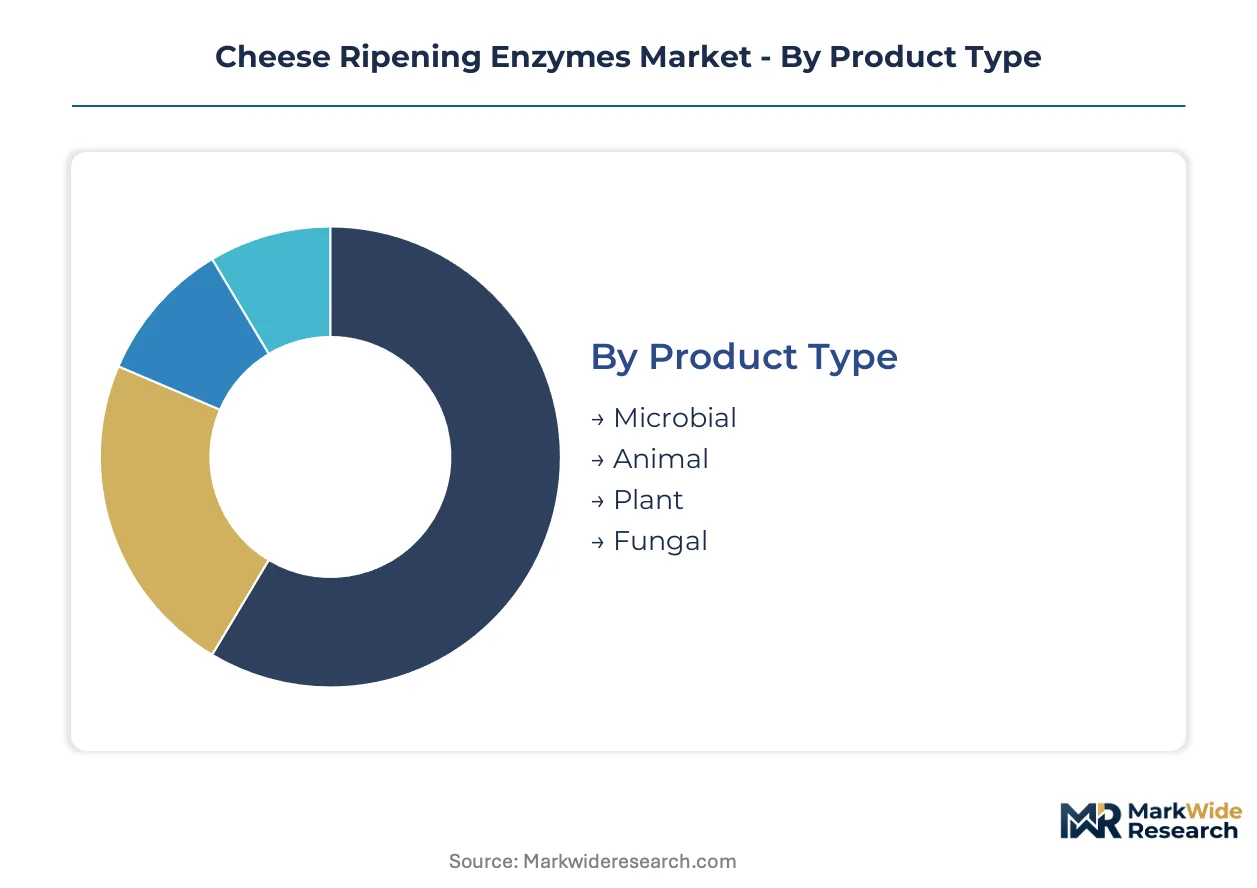
Cheese ripening enzyme suppliers configure production assets around distinct technical specifications and compliance requirements. Segmentation reveals where capital deployment yields margin protection versus commodity exposure.
Product Type:
Capital intensity varies sharply by origin—microbial fermentation requires bioreactor infrastructure, while animal extract processing demands cold-chain abattoir partnerships.
- Microbial:Submerged fermentation of Aspergillus oryzae or Rhizopus species produces kosher-halal compliant proteases and lipases at scale. Dutch and Italian cooperatives dominate procurement as EFSA novel food dossiers clear. Strain validation cycles and REACH registration costs lock out smaller fermentation houses.
- Animal:Calf stomach-derived chymosin and lipase extracts retain premium positioning among PDO-protected French producers. Mediterranean abattoir sourcing concentrates supply risk, with halal certification volatility complicating procurement contracts for Roquefort and Comté makers.
- Plant:Cynara cardunculus thistle extracts serve traditional Portuguese and Spanish sheep's milk cheeses. Limited commercial scale restricts application to artisan niches with heritage labeling requirements.
- Fungal:Aspergillus niger-derived lipases command premium pricing among extended-aging Parmesan producers. CRISPR-edited strain development compresses R&D timelines while satisfying GMO disclosure thresholds.
Most installed capacity flows through Microbial. Expansion is steepest in Fungal.
Application:
Enzyme dosage intensity tracks aging duration and proteolysis requirements, with hard cheeses demanding sustained catalytic activity across 12-36 month maturation cycles.
- Cheddar:Extended aging protocols require lipase-protease combinations that develop crystalline texture and nutty flavor profiles. Wisconsin and Somerset producers drive volume, with kosher-halal compliance shifting procurement toward microbial sources.
- Mozzarella:Minimal ripening demands limit enzyme penetration to specialty aged variants. Italian buffalo milk producers maintain traditional protocols with limited biocatalyst intervention.
- Blue Cheese:Penicillium roqueforti mold activity combines with exogenous lipases to accelerate fat breakdown. French and Danish producers concentrate demand for fungal enzyme systems.
- Parmesan:24-36 month aging mandates high-activity protease persistence at low moisture. Emilia-Romagna cooperatives enforce strict origin documentation, favoring suppliers with integrated traceability systems.
Cheddar captures the largest enzyme volumes by tonnage. Blue Cheese is climbing the fastest as craft dairy experimentation accelerates.
End User:
Procurement sophistication diverges between industrial-scale manufacturers specifying batch-level certificates and food service operators accepting commodity grades.
- Dairy Manufacturers:Integrated creameries in France, Italy, and the Netherlands contract directly for REACH-compliant enzyme preparations with full substrate traceability. Multi-year supply agreements lock in fermentation capacity.
- Restaurants:Specialty cheese aging programs at high-end establishments create spot demand for premium lipase preparations. Limited volume constrains supplier engagement.
- Retailers:Private-label cheese programs drive indirect enzyme procurement through co-manufacturer relationships. Clean-label positioning pressures disclosure standards downstream.
- Food Service:Industrial kitchens and catering operations prioritize cost-stable commodity enzymes with minimal certification overhead.
Dairy Manufacturers absorb the bulk of production capacity. Restaurants are gaining share fastest as direct-to-artisan distribution platforms mature.
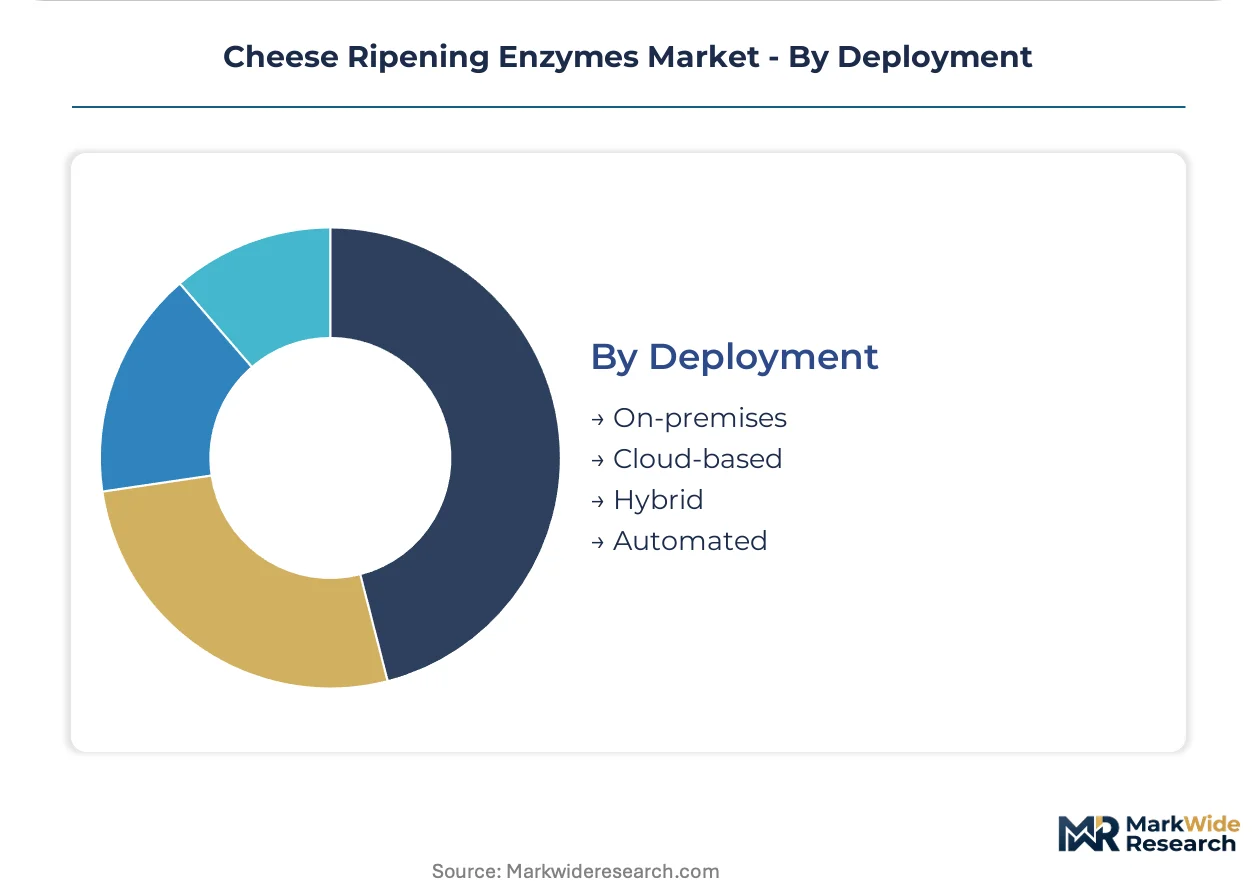
Deployment:
Process control infrastructure investment separates automated dosing systems from manual enzyme addition protocols.
- On-premises:Traditional batch-wise enzyme preparation at farmstead creameries maintains artisan credibility. French AOC regulations implicitly favor manual protocols that preserve heritage methodology.
- Cloud-based:Remote monitoring of fermentation parameters and enzyme activity tracking remains nascent. Early adoption concentrates among Northern European contract manufacturers integrating bioprocess digitization.
- Hybrid:Local enzyme preparation with centralized quality data management bridges artisan positioning and regulatory compliance. Italian cooperatives pilot these configurations.
- Automated:Precision dosing systems synchronize ripening enzyme addition with chymosin schedules. Cheddar producers in Wisconsin and Ireland deploy these to reduce batch-to-batch variability.
On-premises systems retain the largest installed base. Automated deployment is expanding most quickly as multi-product creameries seek process revalidation efficiencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Appellation d'Origine Contrôlée network anchors global cheese ripening enzyme procurement intensity. PDO-protected aging protocols in Comté and Roquefort production lock in sustained biocatalyst demand. EFSA novel food dossier clearances for microbial strains redirect supply contracts toward REACH-registered fermentation houses.
France
Comté and Roquefort producers enforce strict AOC-mandated aging durations, sustaining protease and lipase dosage intensity. EFSA novel food regulations require pre-market authorization for non-GMO microbial strains, favoring suppliers with cleared dossiers. The Jura Mountains and Roquefort-sur-Soulzon clusters concentrate farmstead creamery procurement of fungal enzyme systems.
Italy
Emilia-Romagna cooperatives drive Parmesan's 24-36 month aging enzyme requirements, demanding batch-level strain genealogy documentation. EU REACH Article 33 substrate disclosure mandates force fermentation substrate provenance mapping. The Po Valley dairy belt anchors integrated creamery supply agreements with Northern European enzyme manufacturers.
Netherlands
Dutch dairy cooperatives prioritize kosher-halal compliant microbial lipases for export-oriented Gouda and Edam production. ECHA REACH registration costs impose six-figure toxicological dossier burdens, filtering supplier participation. The Friesland and Noord-Holland cheese clusters pilot hybrid deployment systems linking local enzyme preparation with centralized quality data management.
United States
Wisconsin Cheddar producers drive volume demand for lipase-protease combinations developing crystalline texture profiles. FDA GRAS self-determination pathways accelerate market access versus Europe's pre-market authorization rigor. The Wisconsin and Vermont dairy belts deploy automated dosing systems synchronizing ripening enzyme addition with chymosin schedules.
India
Amul and Mother Dairy cooperatives pilot microbial lipase programs for organized Paneer aging expansion. FSSAI food safety regulations shape strain approval timelines for fermentation-derived biocatalysts. The Gujarat and Maharashtra dairy clusters create first-mover positioning for REACH-compliant suppliers entering South Asian markets.
Cheese Ripening Enzymes Market Competitive Landscape
Strategic partnership formation dominates the current landscape as fermentation specialists seek bioprocess digitization capabilities. The vendor base concentrates around three tiers: integrated biotechnology conglomerates with microbial strain libraries, mid-cap fermentation houses with PDO-protected European relationships, and specialty suppliers serving direct-to-artisan distribution channels. Archetypes span strain-owning platform players, toll-manufacturing contract fermenters, and heritage-focused animal extract processors. M&A activity and precision fermentation capacity expansion constitute the primary competitive vectors.
Within the integrated biotechnology tier, Chr. Hansen Holding A/S and Novonesis occupy positions anchored by microbial strain libraries and global fermentation capacity. DSM-Firmenich represents the converged nutrition-biosciences archetype following specialty ingredient portfolio consolidation. These entities exemplify platform-scale positioning across coagulant-to-ripening enzyme integration. Mid-cap fermentation houses with established EFSA dossier clearances and REACH registration completion sit within a defended niche serving European cooperative procurement.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DSM Food Specialties |
| DuPont Nutrition & Biosciences |
| Novozymes A/S |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich |
| Novonesis |
| Amano Enzyme Inc. |
| Kerry Group plc |
| Others |
Value Network & Pricing Analysis
Fermentation substrate costs cascade through three distinct pricing tiers as REACH-registered bioreactor capacity concentrates in Northern European supply chains. Animal-derived extract scarcity in Mediterranean abattoir networks compresses margins for traditional rennet suppliers while microbial alternatives capture volume premiums through kosher-halal certification.
Pricing Analysis
Distributor margins absorb 15-25 points before enzymes reach farmstead creameries, with direct procurement contracts bypassing this layer for integrated dairy manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates PDO-certified fungal lipases from commodity microbial preparations and unbranded animal extracts. Pricing pressure stems from EFSA novel food dossier preparation costs filtering through to per-kilogram rates. Small-scale artisan producers exhibit highest price sensitivity, while Emilia-Romagna cooperatives prioritize traceability documentation over unit cost.
Supply Chain Analysis
EU REACH Article 33 certification requirements gate supplier participation, forcing substrate provenance documentation through multi-tier networks. Bioreactor capacity concentrates in the Netherlands, Denmark, and Germany, with animal extract processing anchored in Spanish and Italian abattoir corridors. Production draws from agricultural waste streams, pharmaceutical-grade glucose, and specialty nitrogen sources as fermentation feedstocks. Single-source vulnerability persists in CRISPR-edited strain licensing, where patent concentration limits alternative sourcing. Distribution runs through dairy ingredient distributors, direct-to-artisan e-procurement platforms, and cooperative purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA GRAS self-determination pathways and EFSA pre-market authorization rigor creates 18-24 month cost differentials for strain commercialization, rewarding suppliers with dual-continent dossier capabilities.
For Market Incumbents: Anticipate precision fermentation yield improvements compressing protease production economics by half within the analysis window. Defend position by deepening captive strain libraries through CRISPR-edited Aspergillus development partnerships and locking multi-year substrate supply agreements with agricultural waste processors before REACH disclosure mandates tighten further. For New Entrants and Emerging Players: Launch via direct-to-artisan e-procurement platforms serving French and Italian farmstead producers bypassing traditional distributor markups. White-space concentrates in India's organized dairy expansion, where Amul and Mother Dairy cooperatives pilot microbial lipase programs without established supplier relationships. Target PDO-protected aging protocols with batch-level genealogy documentation as the entry wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap fermentation houses face six-figure REACH registration burdens without platform-scale revenue to amortize compliance costs. Long-term viability favors entities controlling integrated strain development, bioprocess optimization, and regulatory dossier clearance capabilities. Watch for EFSA novel food approval velocity as the signal indicating which supplier portfolios can sustain European market access.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Development Partnership | Compresses R&D timelines from five years to eighteen months while satisfying EFSA GMO thresholds. |
| REACH-Compliant Substrate Sourcing | Substitutes petrochemical-derived media with agricultural waste streams ahead of Article 33 enforcement. |
| Direct-to-Artisan Distribution Platform | Bypasses traditional dairy ingredient distributors serving French and Italian farmstead producers. |
| Dual-Continent Regulatory Dossier Clearance | Captures FDA GRAS acceleration benefits while maintaining EFSA novel food market access. |
| Precision Fermentation Capacity Expansion | Integrates AI-driven bioprocess optimization with CRISPR-edited Aspergillus platforms for yield gains. |
Research Methodology
Multiple input streams — primary interviews with fermentation specialists and dairy cooperative procurement directors, trade data from customs and dairy industry associations, and regulatory filings with EFSA and FDA — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC filings of listed enzyme manufacturers, EU REACH registration databases, and dairy cooperative annual reports. Cross-referencing against EMA submissions and FSSAI strain approval records anchored geographic coverage.
Historical capacity utilization and pricing patterns were cross-referenced against expert panel inputs from industrial microbiologists and creamery operations managers. Segmentation modeling tracked product origin, cheese variety application, end-user procurement sophistication, and deployment system automation level across the projection horizon. CAGRs were derived from enzyme dosage intensity curves mapped to aging duration requirements, with regulatory approval timelines and fermentation yield improvement trajectories as key sensitivity inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory reclassifications of gene-edited strains and abrupt shifts in halal certification standards for animal-derived extracts. Forecasts reflect assumptions about continued PDO protocol adherence and stable fermentation substrate agricultural supply. A model refresh is warranted upon material change in EFSA novel food approval velocity or REACH enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Avocado Oil Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Sunflower Oil Market
Ingredients
Egg White Powder Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
North America Agar Market
Ingredients
Pea Flour Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Cocoa Maker Market
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
Agar Agar Flakes Market
Ingredients
GCC Egg Powder Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
India Bakery Ingredients Market
Ingredients
Middle East and Africa Fermented Ingredients Market