
 Blue Cheese Market | 2026-2036
Blue Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Blue Cheese Market Analysis
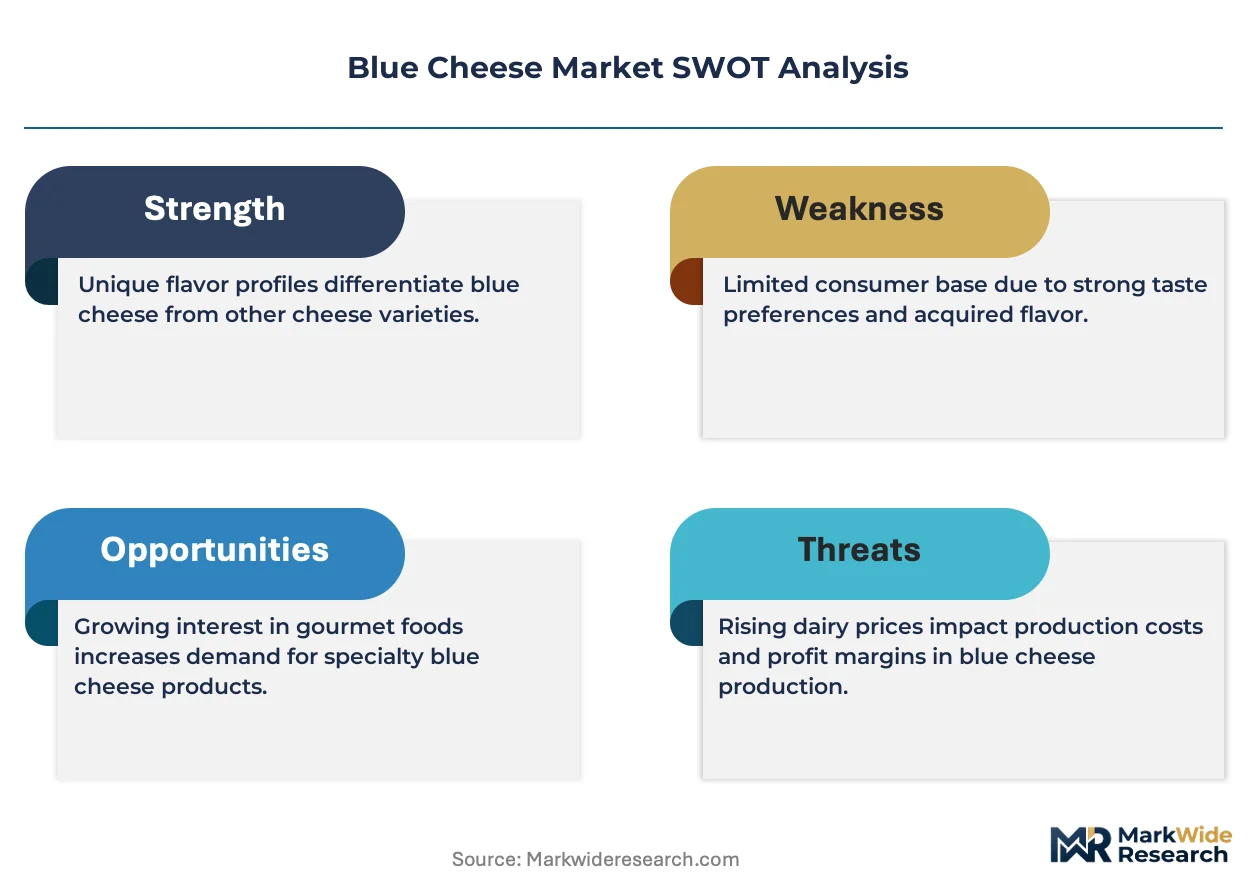
Precision fermentation and controlled-environment aging is reshaping how blue cheese producers manage Penicillium roqueforti cultivation and texture consistency across batches. Lactalis Heritage Group leverages its vertical integration from dairy farming to affineur operations across multiple European facilities. Savencia SA anchors its competitive position through specialized Roquefort and Bleu d'Auvergne production under strict AOP protocols. Arla Foods amba extends its reach through sustained investment in Northern European cow's milk blue cheese varieties.
Blue cheese denotes a mold-ripened cheese category characterized by Penicillium roqueforti or related cultures introduced via needle piercing, producing distinctive blue-green veining within a moisture content typically ranging from 42% to 50%. The cheese serves commercial food manufacturing, restaurant plating, and retail deli counters where pungency intensity and crumble texture determine application suitability. Cow's milk variants dominate volume throughput across retail and food service channels, while sheep's milk Roquefort commands concentrated margin pools through its protected designation of origin status. Crumbly texture profiles lead demand in salad and burger topping applications, whereas creamy formats compete for premium cheeseboard positioning in direct-to-consumer and specialty retail segments.
EFSA microbiological standards and EU PDO enforcement mechanisms govern production claims and cross-border distribution access for protected varieties such as Roquefort, Gorgonzola, and Stilton. FDA pasteurization requirements and USDA organic certification pathways shape US import eligibility and domestic manufacturing compliance for producers targeting North American distribution. Stakeholders must monitor evolving allergen labeling mandates and alternative protein substitution threats as consumer dietary diversification pressures traditional dairy positioning.
Market Dynamics
Precision fermentation and controlled-environment aging are compressing batch-to-batch variability in Penicillium roqueforti cultivation, forcing traditional affineurs to retool facility investments or cede share to technology-enabled competitors.
Growth Catalysts
- EFSA microbiological standards:Harmonized EU safety protocols reduce cross-border compliance duplication for PDO-certified producers, accelerating distribution scale for Roquefort and Bleu d'Auvergne exporters.
- Artisanal dining procurement:Premium food service channels in France and the United States are expanding blue cheese placement as experiential tasting menus anchor customer acquisition strategies.
- Sheep's milk Roquefort AOP:Protected designation enforcement creates margin insulation unavailable to generic blue cheese variants, concentrating investment in Aveyron basin production capacity.
Market Restraints
- Raw milk input volatility:Seasonal fluctuations in sheep's milk supply from Lacaune breed herds constrain Roquefort output predictability and inflate working capital requirements.
- FDA pasteurization requirements:Import eligibility barriers for non-thermized European varieties limit US market penetration for traditional raw-milk affineurs.
- Plant-based cheese substitution:Fermented cashew and coconut oil alternatives are capturing trial among flexitarian consumers in Northern European retail channels.
Strategic Opportunities
- Direct-to-consumer affineur channels:E-commerce subscription models for aged cheese assortments bypass wholesale margin compression in France and Belgium.
- USDA organic certification pathways:Premium positioning through certified organic cow's milk blue cheese variants opens shelf space in Whole Foods and specialty retail.
- Salad and burger topping applications:Crumbly texture formats are penetrating fast-casual restaurant chains seeking distinctive flavor differentiation without kitchen complexity.
Industry Challenges
- Master affineur skill scarcity:Traditional cave-aging expertise transfer is lagging retirement curves in Roquefort-sur-Soulzon production clusters.
- PDO compliance documentation:Multi-year audit trails for AOP certification create administrative burden for small-scale producers seeking export market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue Cheese Market |
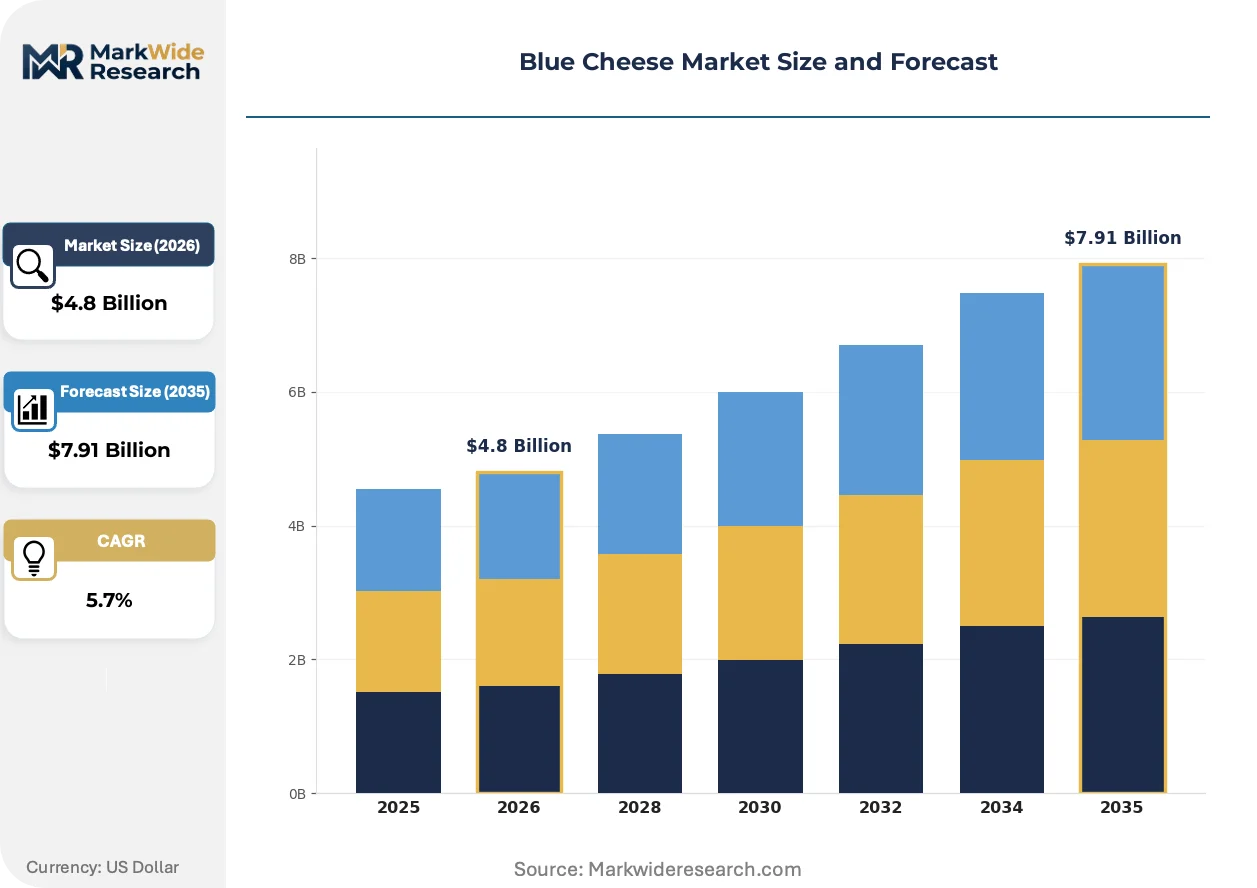
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roquefort, Gorgonzola, Stilton, Maytag Milk Source: Cow, Sheep, Goat, Mixed Texture: Soft, Semi-Hard, Crumbly, Creamy Distribution Channel: Retail, Wholesale, Online, Food Service |
| Companies Covered | Lactalis Heritage Group, Savencia SA, Arla Foods amba, Saputo Inc., Rogue Creamery, Roquefort Société, Bel Group, Kraft Heinz Company, Fonterra Co-operative Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue Cheese Market Emerging Trajectories
Bioprocess engineering and sensor-driven quality control are rewriting production economics for mold-ripened cheese, compressing the advantage of terroir-based legacy methods.
Precision fermentation platforms for Penicillium roqueforti inoculum standardization are rendering obsolete the variability inherent in traditional spore propagation. Mid-scale producers in Denmark and the Netherlands are adopting bioreactor-cultured starter cultures at accelerating rates. This shift is compressing the quality premium historically commanded by artisan affineurs dependent on ambient microflora.
EU Green Deal agricultural emissions targets are tightening manure management requirements for dairy suppliers across France's Aveyron region. Compliance investments in anaerobic digestion and feed additives are redirecting capital from affineur facility expansion. Sheep's milk Roquefort producers face disproportionate impact due to dispersed pasture-based supply chains and limited consolidation options.
Specialty retailers are unbundling cheeseboard assembly from restaurant service, creating direct procurement relationships with affineurs that bypass traditional wholesale distributors. This channel disintermediation is most visible in Paris and New York, where curated subscription boxes and tasting events capture margin previously allocated to food service intermediaries. End-use buyers now demand traceability documentation and batch-specific flavor profiles that legacy distribution infrastructure cannot provide.
Blue Cheese Market Segmentation
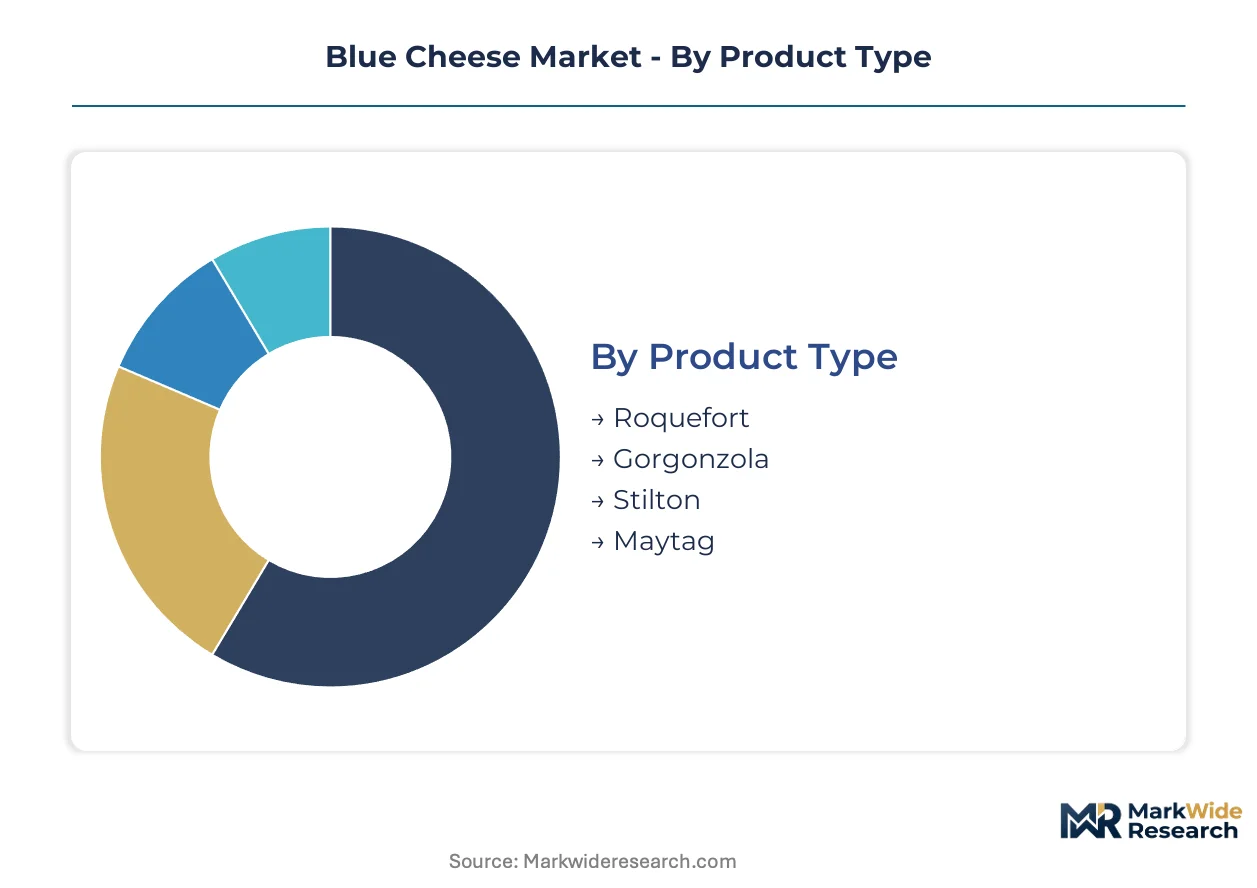
Blue cheese producers face divergent margin structures across texture formats and distribution channels. Each segmentation dimension carries distinct regulatory burdens and end-user specifications that reshape investment priorities.
Product Type:
Use-case intensity varies from crumbly salad applications to creamy cheeseboard presentations, with protected designation status determining export eligibility and pricing power.
- Roquefort:Sheep's milk blue cheese aged in Aveyron basin caves under strict AOP protocols. French food service channels and US specialty retailers concentrate procurement around this variety due to its protected status and consistent Penicillium roqueforti veining.
- Gorgonzola:Italian cow's milk variety with PDO enforcement across Lombardy and Piedmont production zones. Northern European retail delis and pizza manufacturing operations drive volume demand for both dolce and piccante expressions.
- Stilton:English cow's milk blue cheese restricted to Derbyshire, Nottinghamshire, and Leicestershire counties. British cheeseboard traditions and Commonwealth export markets sustain its positioning.
- Maytag:American cow's milk variety produced in Iowa with distinct cave-aging methods. Domestic US specialty retail and farm-to-table restaurant channels anchor its regional presence.
The dominant share belongs to Roquefort, while Gorgonzola is closing the gap fastest.
Milk Source:
Cost tier differentiation separates commodity cow's milk throughput from premium sheep and goat milk positioning.
- Cow:Industrial-scale dairy operations supply volume throughput for Gorgonzola, Stilton, and Maytag production. Lower input costs enable competitive pricing in retail and food service channels where margin compression is acute.
- Sheep:Lacaune breed herds in France's Aveyron region supply Roquefort's protected milk pool. Seasonal supply constraints and higher fat content command premium positioning in direct-to-consumer and specialty export markets.
- Goat:Smaller-scale herding operations produce tangy flavor profiles for niche positioning. Artisan affineurs in France and Spain target health-conscious consumers seeking alternative milk proteins.
- Mixed:Blended milk formulations balance cost and flavor complexity for mid-tier retail placement. Dutch and Danish producers leverage this approach for private-label supermarket contracts.
Cow milk retains volume leadership, though sheep milk claims the steepest expansion trajectory in premium channels.
Texture:
Application requirements dictate texture selection, with food manufacturing favoring mechanical stability and cheeseboard service demanding sensory complexity.
- Soft:High moisture content above 50% creates spreadable consistency for dolce-style Gorgonzola. Italian restaurant plating and European retail deli counters drive placement.
- Semi-Hard:Intermediate moisture range suits slicing applications in sandwich and burger assembly. US fast-casual chains specify this format for kitchen operational efficiency.
- Crumbly:Lower moisture and mechanical fragility make this ideal for automated salad topping dispensers and pizza finishing. Maytag and Stilton variants dominate this functional segment.
- Creamy:Modified aging protocols yield smooth mouthfeel for cheeseboard and dessert applications. French affineurs command premium pricing in Paris and New York direct-to-consumer channels.
Crumbly formats lead food service volume, while creamy textures are expanding most quickly in specialty retail.
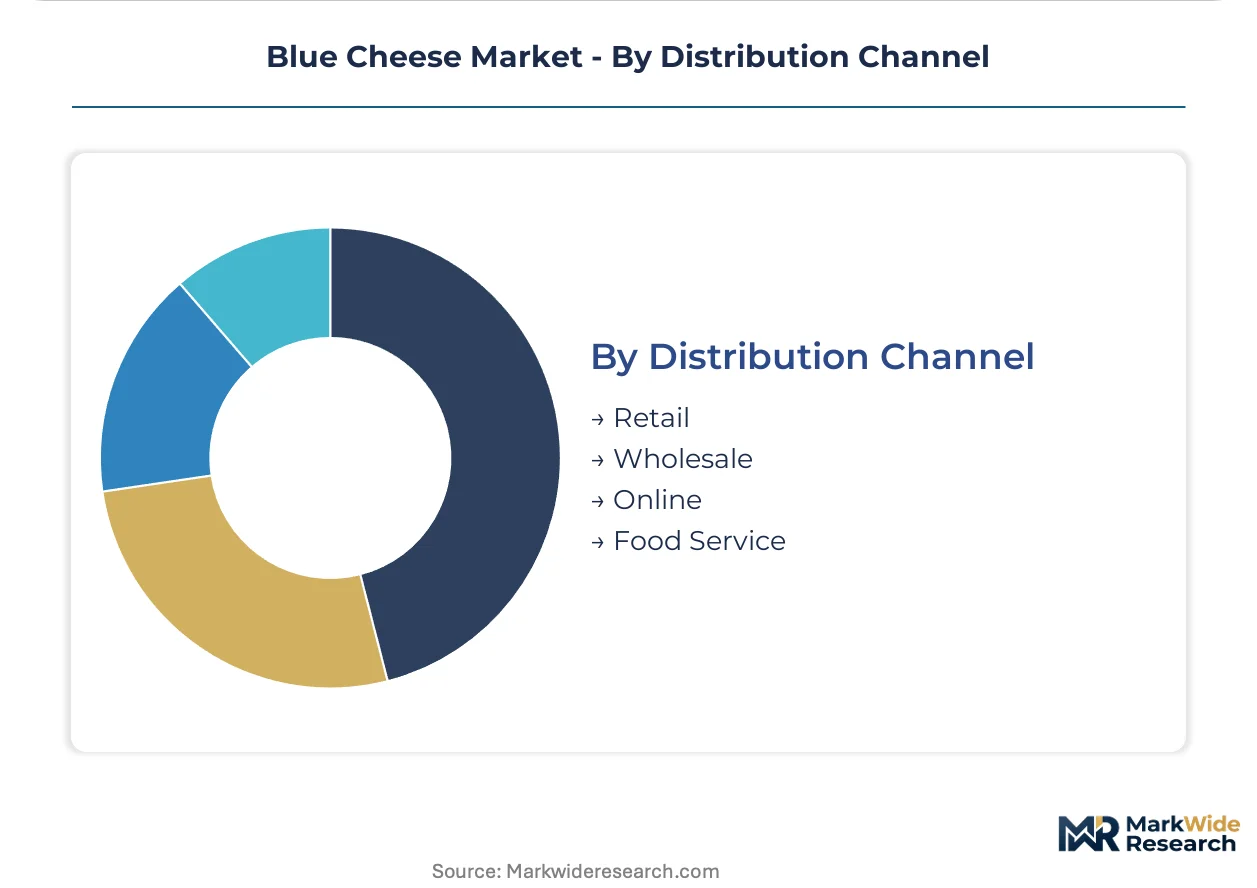
Distribution Channel:
Customer type concentration separates institutional procurement from individual purchasing patterns.
- Retail:Supermarket deli counters and specialty cheese shops manage cold chain requirements for consumer-facing sales. EFSA labeling mandates and allergen disclosure protocols shape shelf placement.
- Wholesale:Distributor intermediaries aggregate supply from multiple affineurs for restaurant and catering procurement. Margin compression here pushes producers toward direct relationships.
- Online:Subscription boxes and curated assortments bypass traditional distribution tiers. Paris and New York urban clusters show strongest adoption for traceability-focused purchasing.
- Food Service:Restaurant kitchens and institutional cafeterias prioritize consistent supply and standardized portioning. Fast-casual burger chains specify crumbly formats for operational simplicity.
Food service captures the largest throughput, yet online channels are gaining share fastest among premium-seeking consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium food service buyers concentrate procurement decisions in France and the United States, where artisanal dining experiences drive Roquefort and domestic blue cheese placement. Regulatory enforcement of protected designation frameworks shapes cross-border trade access and production investment patterns.
France
Roquefort AOP certification anchors domestic consumption and export positioning through strict EFSA microbiological standards compliance. EU PDO enforcement mechanisms govern production claims for Roquefort-sur-Soulzon cave-aged varieties. The Aveyron basin production cluster concentrates affineur expertise and Lacaune breed sheep's milk supply chains.
United States
Fast-casual restaurant chains and specialty retailers drive demand for crumbly salad toppings and cheeseboard formats. FDA pasteurization requirements limit import eligibility for non-thermized European varieties while shaping domestic manufacturing compliance. Iowa-based cave-aging operations anchor regional Maytag production for farm-to-table channels.
Italy
Gorgonzola dolce and piccante varieties serve Northern European retail delis and pizza manufacturing operations through consistent volume throughput. EFSA harmonized safety protocols reduce cross-border compliance duplication for Lombardy and Piedmont producers. The Po Valley dairy belt concentrates industrial-scale cow's milk processing infrastructure.
United Kingdom
Stilton's restricted production geography across Derbyshire, Nottinghamshire, and Leicestershire sustains cheeseboard traditions and Commonwealth export markets. British food safety regulators enforce geographic indication protections that limit competitive entry. The East Midlands cluster maintains cooperative dairy supply relationships for PDO-certified output.
Denmark
Mid-scale producers adopt bioreactor-cultured Penicillium roqueforti starter cultures at accelerating rates, compressing traditional quality premiums. EU Green Deal agricultural emissions targets tighten manure management requirements for dairy suppliers. Danish affineurs leverage precision fermentation platforms to standardize batch-to-batch consistency for private-label supermarket contracts.
Blue Cheese Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures in retail, food service, and direct-to-consumer segments. The vendor base stratifies between vertically integrated dairy conglomerates and terroir-focused affineur operations. Three archetypes dominate: PDO-certified heritage producers, technology-enabled mid-scale fermenters, and commodity-scale dairy processors. Competitive moves concentrate on backward integration into captive milk supply and e-commerce subscription channel development.
Within the heritage-producer tier, Lactalis Heritage Group and Savencia SA exemplify European affineur archetypes with protected designation operations. Arla Foods amba anchors the Northern European cow's milk blue cheese segment through sustained facility investment. These three entities occupy positions spanning from AOP-certified Roquefort production to precision-fermentation adoption, representing the spectrum from tradition-bound to technology-enabled competitive positioning.
| Leading Market Players |
|---|
| Lactalis Heritage Group |
| Savencia SA |
| Arla Foods amba |
| Saputo Inc. |
| Rogue Creamery |
| Roquefort Société |
| Bel Group |
| Kraft Heinz Company |
| Fonterra Co-operative Group |
| Others |
Supply Flow & Price Mechanics
Seasonal Lacaune sheep's milk volatility determines both Roquefort's three-tier pricing spread and the dispersed pasture-based supply chain configuration across France's Aveyron basin. Affineurs absorb working capital inflation during low-yield months while EU Green Deal compliance costs redirect investment from cave-aging facility expansion.
Pricing Analysis
Cost-plus contracts indexed to Lacaune sheep's milk commodity benchmarks dominate Roquefort procurement, while cow's milk Gorgonzola and Stilton variants trade on spot dairy markets. Price differentiation rests on AOP certification tier and affineur brand heritage, with Roquefort-sur-Soulzon cave-aged lots commanding substantial premiums over thermized alternatives. Cost compression in mid-tier retail channels intensifies as precision-fermentation competitors standardize batch consistency at lower unit economics. Food service buyers exhibit highest price sensitivity due to standardized portioning requirements, whereas direct-to-consumer subscribers prioritize traceability over per-kilogram cost.
Supply Chain Analysis
Extended payment terms from French wholesale distributors strain small-scale affineur cash flows, accelerating supply-chain finance facility adoption. Raw material sourcing concentrates in France's Aveyron region for sheep's milk, Italy's Po Valley for Gorgonzola cow's milk, and England's East Midlands for Stilton production. The supply chain rests on Penicillium roqueforti starter culture propagation, cave-aging infrastructure, and cold-chain logistics for finished goods. Single-source vulnerability in master affineur expertise transfer threatens Roquefort-sur-Soulzon production continuity. Distribution runs through wholesale intermediaries for restaurant procurement, with direct-to-consumer e-commerce bypassing traditional tiers in Paris and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traditional cave-aging expertise is retiring faster than knowledge transfer mechanisms can replenish, compressing the viable producer base and amplifying acquisition premiums for AOP-certified operations. This capability scarcity reshapes competitive dynamics across heritage and technology-enabled producer tiers.
For Market Incumbents: Entrench AOP-certified positioning through accelerated master affineur apprenticeship programs and captive Lacaune herd supply contracts. Precision-fermentation entrants threaten quality-premium erosion; backward integration into sheep's milk cooperatives secures input cost predictability. Channel control via direct-to-consumer subscription platforms captures margin otherwise lost to wholesale intermediaries.
For New Entrants and Emerging Players: USDA organic-certified cow's milk blue cheese for US specialty retail represents the most penetrable entry point, given FDA pasteurization barriers blocking European raw-milk imports. Fast-casual burger chain crumbly-format supply contracts offer volume traction without affineur heritage requirements. Go-to-market execution should leverage precision-fermentation consistency guarantees to bypass traditional aging expertise barriers.
For Investors and Strategic Acquirers: EU Green Deal agricultural emissions enforcement reshapes the acquisition landscape by elevating compliance capital requirements for pasture-based sheep's milk suppliers. Long-term viability favors AOP-certified assets with existing anaerobic digestion infrastructure and direct-to-consumer channel development. Monitor EFSA microbiological standard revisions as inflection indicators for cross-border export eligibility and valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lacaune Herd Supply | Captive sheep's milk sourcing insulates Roquefort producers from seasonal price volatility in Aveyron basin auctions. |
| Precision Fermentation Platform Deployment | Bioreactor-cultured Penicillium roqueforti standardization compresses batch variability for mid-scale Danish and Dutch competitors. |
| Direct-to-Consumer Subscription Launch | Paris and New York urban clusters enable margin capture bypassing traditional wholesale distribution tiers. |
| USDA Organic Certification Investment | Premium shelf space access in Whole Foods and specialty retail channels differentiates cow's milk variants. |
| EU Green Deal Compliance Infrastructure | Anaerobic digestion and feed additive investments satisfy tightening manure management requirements for Aveyron dairy suppliers. |
Methodological Framework
Initial hypotheses were tested against primary input from affineur operations directors, dairy cooperative procurement managers, specialty retail category buyers, and food service distribution executives, then refined through secondary validation. Primary fieldwork encompassed structured interviews across France's Aveyron basin, Italy's Po Valley, and England's East Midlands production clusters. Secondary sources included EFSA microbiological safety filings, EU PDO registration databases, FDA import refusal data, and national dairy trade statistics. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Demand-supply balance dynamics across the analysis window integrated milk source segmentation, texture format application requirements, and distribution channel throughput capacity. The analytical framework modeled product type, milk source, texture profile, and regional regulatory cluster dimensions. CAGRs derived from historical trajectory analysis adjusted for precision-fermentation adoption curves and EU agricultural emissions policy implementation timelines. Forecast inputs incorporated Lacaune herd population trends and fast-casual restaurant chain procurement specifications.
Practitioners should monitor EFSA standard revisions, FDA pasteurization enforcement shifts, and precision-fermentation cost curves for early signals requiring forecast reassessment. Projections reflect assumptions regarding AOP certification continuity, sheep's milk supply stability, and alternative protein substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low Fat Butter Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
North America Cheese Market
Dairy Products
Ricotta Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Kefir Market
Dairy Products
Processed Cheese Market
Dairy Products
Paneer Market
Dairy Products
Low-Calorie Butter Market