
 Generalized Anxiety Disorder Treatment Market | 2026-2036
Generalized Anxiety Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Generalized Anxiety Disorder Treatment Market Foresight
The FDA's accelerated approval framework is broadening the cost-of-entry calculus for anxiolytic developers, forcing smaller entrants to front-load biomarker validation and adaptive trial design. Pfizer Inc. leverages its established psychiatric portfolio to sustain formulary access across major commercial payers. Eli Lilly and Company anchors its position through R&D intensity in next-generation serotonergic mechanisms. AstraZeneca competes via geographic dominance in European reimbursement markets where centralized health technology assessments govern pricing.
Generalized Anxiety Disorder treatment encompasses pharmacological and psychotherapeutic interventions targeting persistent, excessive worry through modulation of monoamine neurotransmission or cognitive restructuring protocols. Selective Serotonin Reuptake Inhibitors remain the first-line pharmacologic standard, typically dosed at 20-60 mg daily with onset measured across 4-6 weeks. Serotonin-Norepinephrine Reuptake Inhibitors command premium positioning in patients with comorbid pain syndromes, creating a distinct margin pool. Cognitive Behavioral Therapy dominates the therapy area segment as the most reimbursed non-pharmacologic modality, while digital therapeutics represent the fastest-growing delivery mode as synchronous telehealth platforms integrate prescription-grade software interventions.
The FDA's psychiatric drug guidance, EMA's centralized marketing authorization procedures, and HIPAA interoperability mandates collectively shape product standards, trial endpoints, and market access pathways across jurisdictions. These frameworks elevate documentation burdens for novel mechanisms while creating compliance moats for incumbents with established regulatory infrastructure. Stakeholders must monitor evolving digital therapeutics classification criteria, as FDA determinations on software-as-a-medical-device status will redirect R&D capital toward either regulated prescription pathways or direct-to-consumer wellness positioning.
Market Dynamics
FDA's accelerated approval pathway for psychiatric therapeutics is compressing clinical timelines while elevating biomarker validation requirements, forcing developers to front-load adaptive trial infrastructure and reshape capital allocation toward earlier-stage evidence generation.
Growth Catalysts
- Commercial payer mandates:United States commercial insurers have broadened mental health parity enforcement, expanding reimbursable access to cognitive behavioral therapy and pharmacologic interventions.
- Telehealth infrastructure:Synchronous digital platforms now integrate prescription-grade software interventions, creating reimbursable channels for remote therapeutic delivery.
- SNRI mechanism expansion:Serotonin-norepinephrine reuptake inhibitors command premium formulary positioning in patients with comorbid pain syndromes, opening distinct margin pools.
Market Restraints
- Regulatory documentation burdens:FDA psychiatric drug guidance and EMA centralized marketing authorization procedures elevate trial endpoint complexity and extend validation timelines for novel mechanisms.
- Specialist concentration:Prescribing authority for advanced anxiolytics concentrates among board-certified psychiatrists, creating geographic access gaps in rural United States regions.
- Generic SSRI substitution:Selective serotonin reuptake inhibitor commoditization limits pricing power for first-line pharmacologic entrants.
Strategic Opportunities
- Digital therapeutics classification:FDA determinations on software-as-a-medical-device status will redirect R&D capital toward regulated prescription pathways with durable reimbursement codes.
- European HTA positioning:Centralized health technology assessment frameworks in Germany, France, and the United Kingdom reward robust cost-effectiveness data with premium pricing corridors.
- Behavioral health center expansion:Rising patient volumes at specialized outpatient facilities are expanding the addressable base for integrated pharmacologic and psychotherapeutic protocols.
Industry Challenges
- Biomarker validation complexity:Accelerated approval pathways require front-loaded neuroimaging and peripheral biomarker infrastructure that many mid-cap developers lack.
- HIPAA interoperability mandates:Digital therapeutic platforms face technical and compliance friction when integrating prescription-grade software with existing electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generalized Anxiety Disorder Treatment Market |
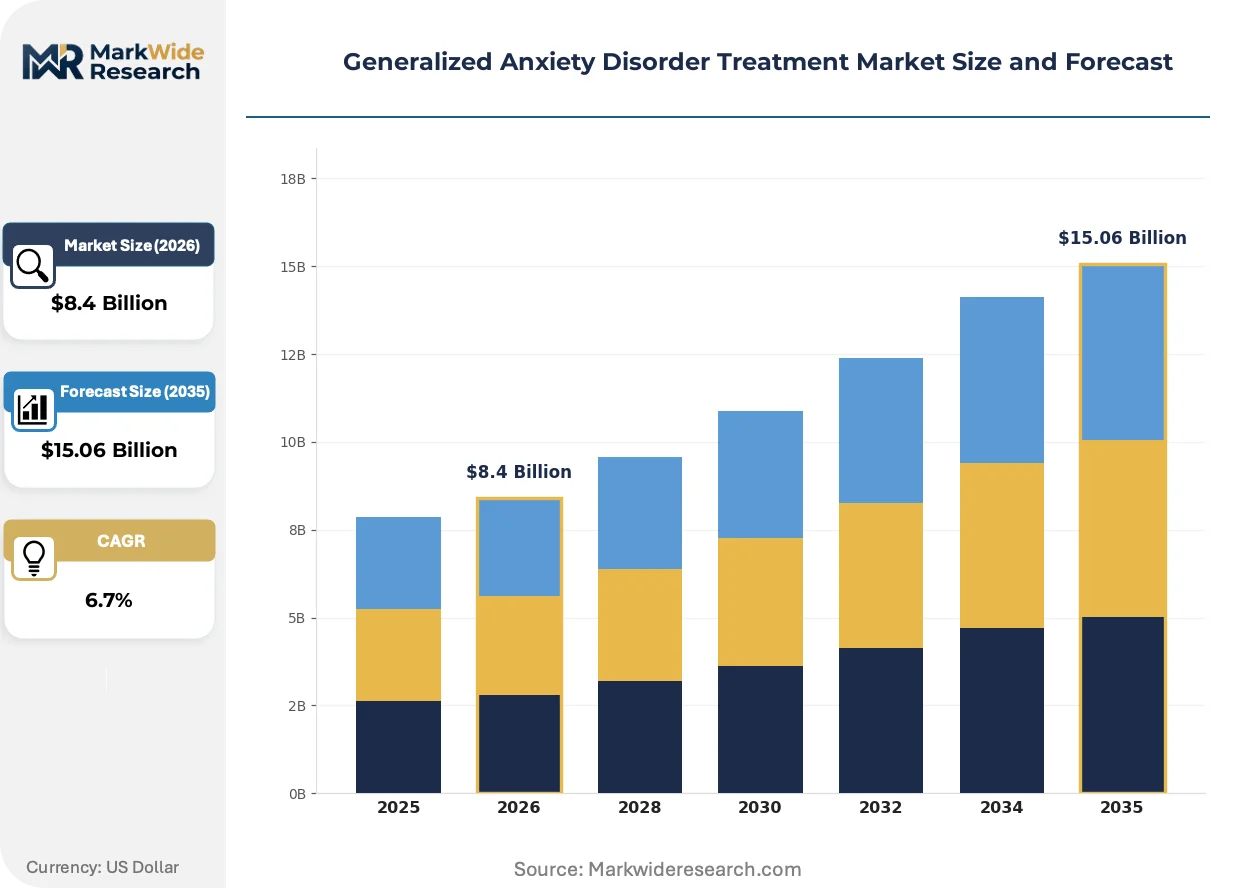
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
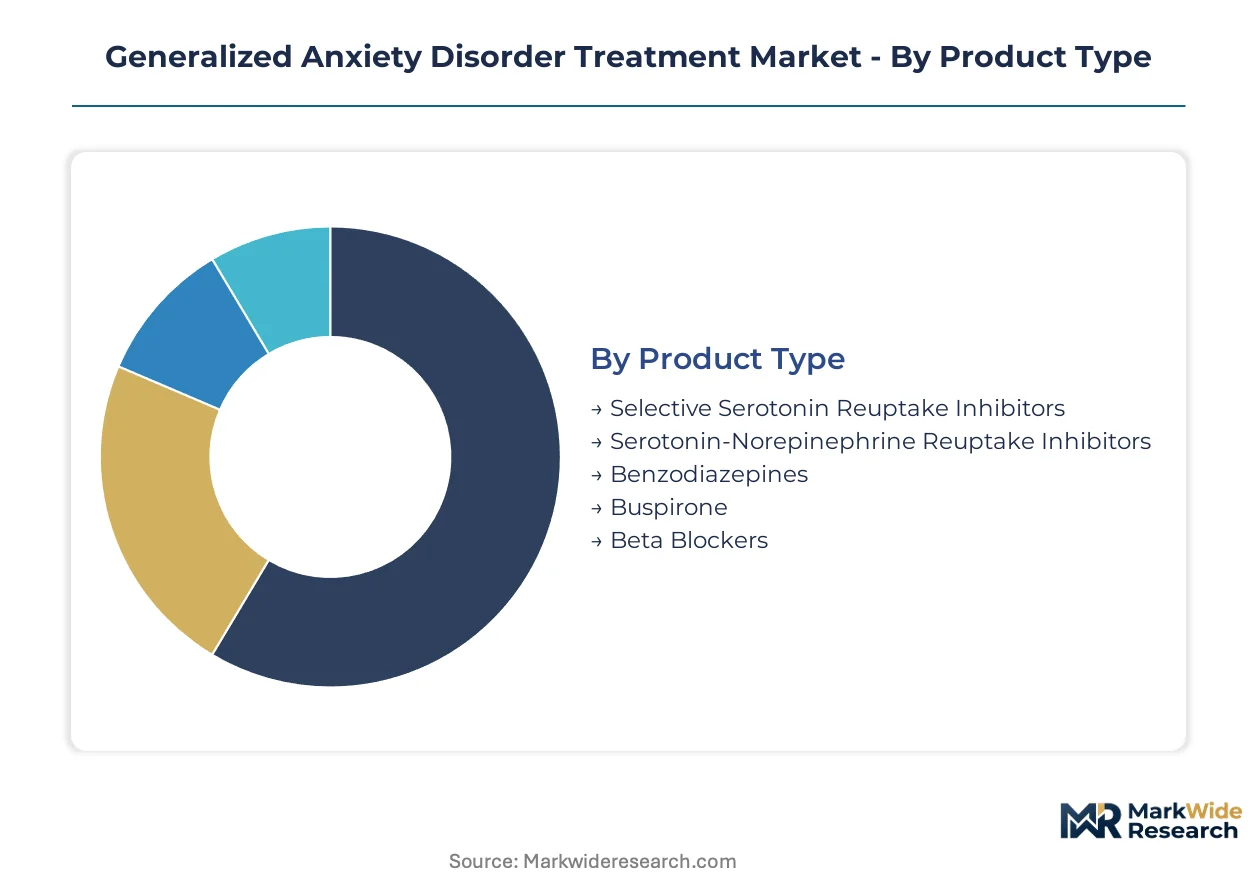
| Segmentation | Product Type: Selective Serotonin Reuptake Inhibitors, Serotonin-Norepinephrine Reuptake Inhibitors, Benzodiazepines, Buspirone, Beta Blockers Therapy Area: Cognitive Behavioral Therapy, Mindfulness-Based Therapy, Psychodynamic Therapy, Acceptance and Commitment Therapy, Exposure Therapy End User: Psychiatric Clinics, Behavioral Health Centers, Outpatient Facilities, Telemedicine Services, Counseling Practices Delivery Mode: Oral, Intravenous, Sublingual, Transdermal Patch, Digital Therapeutics |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, AstraZeneca, GlaxoSmithKline plc, Merck & Co. Inc., Johnson & Johnson, Bristol-Myers Squibb, H. Lundbeck A/S, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generalized Anxiety Disorder Treatment Market Shifts & Advancements
Digital therapeutic platforms are fragmenting traditional care delivery hierarchies while regulatory frameworks scramble to classify software interventions alongside conventional pharmacologic standards.
Prescription digital therapeutics is decentralizing point-of-care authority from psychiatrists to primary care physicians and licensed clinical social workers. Large United States health systems are embedding FDA-cleared software interventions into employee assistance programs and student health portals. This diffusion is compressing the traditional specialist referral bottleneck while creating new liability frameworks for non-physician prescribers.
EMA's centralized marketing authorization procedures are harmonizing psychiatric drug standards across Germany, France, Italy, and Spain, forcing developers to consolidate previously fragmented national submission strategies. Manufacturers now prioritize unified European trial designs over country-specific protocols. This consolidation favors incumbents with established regulatory infrastructure and disadvantages smaller entrants lacking pan-European compliance capabilities.
Employer-sponsored benefit design is unbundling mental health services from traditional medical plan structures, with Fortune 500 companies contracting directly with digital therapeutic vendors for anxiety management programs. Third-party administrators and benefits consultants are displacing traditional payer intermediaries in procurement decisions. This channel shift is most visible in technology and financial services verticals with concentrated white-collar workforces.
Generalized Anxiety Disorder Treatment Market Segmentation
Segmentation in the Generalized Anxiety Disorder treatment market reveals how capital allocation, reimbursement codes, and regulatory pathways diverge across therapeutic modalities. Understanding these divisions exposes where margin pools concentrate and where new entrants face structural barriers to entry.
Product Type:
Capital intensity varies sharply across pharmacologic mechanisms, with novel compound development demanding substantially greater upfront investment than generic formulation or repurposing strategies.
- Selective Serotonin Reuptake Inhibitors:First-line serotonergic modulation agents, typically dosed at 20-60 mg daily with therapeutic onset across 4-6 weeks. Demand concentrates in United States outpatient facilities where commercial payer parity mandates have broadened reimbursable access, though generic substitution has compressed pricing power for originator brands.
- Serotonin-Norepinephrine Reuptake Inhibitors:Dual-mechanism agents commanding premium formulary positioning in patients with comorbid chronic pain syndromes. United States commercial payers reimburse these at higher tiers when fibromyalgia or neuropathic pain indications accompany anxiety diagnoses, creating distinct margin pools unavailable to pure anxiolytic competitors.
- Benzodiazepines:GABA-A receptor agonists with rapid anxiolytic onset but restricted long-term prescribing due to dependence liability and DEA scheduling constraints.
- Buspirone:Azapirone-class partial 5-HT1A agonist lacking sedation or abuse potential, positioned for patients with substance use history.
- Beta Blockers:Off-label sympatholytic agents targeting somatic anxiety manifestations, particularly performance anxiety subtypes.
Most installed capacity flows through Selective Serotonin Reuptake Inhibitors. Expansion is steepest in Serotonin-Norepinephrine Reuptake Inhibitors.
Therapy Area:
Reimbursement density and session frequency requirements create divergent economics across psychotherapeutic modalities, with standardized protocols attracting greater payer investment than open-ended exploratory approaches.
- Cognitive Behavioral Therapy:Structured, time-limited protocol emphasizing cognitive restructuring and behavioral activation. United States behavioral health centers have scaled group and individual CBT delivery in response to commercial payer mandates, while EMA-aligned European markets require health technology assessment submission for sustained reimbursement.
- Acceptance and Commitment Therapy:Third-wave behavioral intervention integrating mindfulness with values-based action frameworks. Telemedicine services in the United States have adopted ACT protocols for digital delivery, exploiting its modular structure for asynchronous platform integration and stepped-care algorithms.
- Mindfulness-Based Therapy:Manualized meditation and awareness training protocols, often delivered in group formats to optimize clinician throughput.
- Psychodynamic Therapy:Long-term exploratory intervention with limited standardized outcome measurement, constraining payer enthusiasm.
- Exposure Therapy:Systematic desensitization protocols targeting specific phobic or anticipatory anxiety triggers.
Reimbursement volume concentrates in Cognitive Behavioral Therapy. Digital adaptation is advancing most rapidly in Acceptance and Commitment Therapy.
End User:
Prescribing authority and formulary control shift dramatically across care settings, with specialized facilities capturing complex cases while primary touchpoints manage stable maintenance therapy.
- Behavioral Health Centers:Dedicated outpatient facilities integrating pharmacologic and psychotherapeutic protocols under unified care coordination. Rising patient volumes in United States metropolitan markets have expanded the addressable base, with these centers capturing bundled reimbursement for integrated treatment episodes.
- Telemedicine Services:Synchronous and asynchronous platforms delivering remote therapeutic access. FDA determinations on prescription digital therapeutics classification are redirecting vendor R&D toward regulated software-as-a-medical-device pathways with durable reimbursement codes.
- Psychiatric Clinics:Specialist-led settings with authority for advanced anxiolytic prescribing, including controlled substances and novel mechanisms.
- Outpatient Facilities:General medical settings with limited psychiatric specialization, relying on primary care prescribing patterns.
- Counseling Practices:Licensed clinical social worker and psychologist practices with restricted pharmacologic scope, concentrating on talk therapy delivery.
Service volume concentrates in Behavioral Health Centers. Capacity addition is accelerating fastest in Telemedicine Services.
Delivery Mode:
Manufacturing complexity and regulatory burden scale with route of administration sophistication, with novel delivery technologies demanding specialized infrastructure unavailable to generic manufacturers.
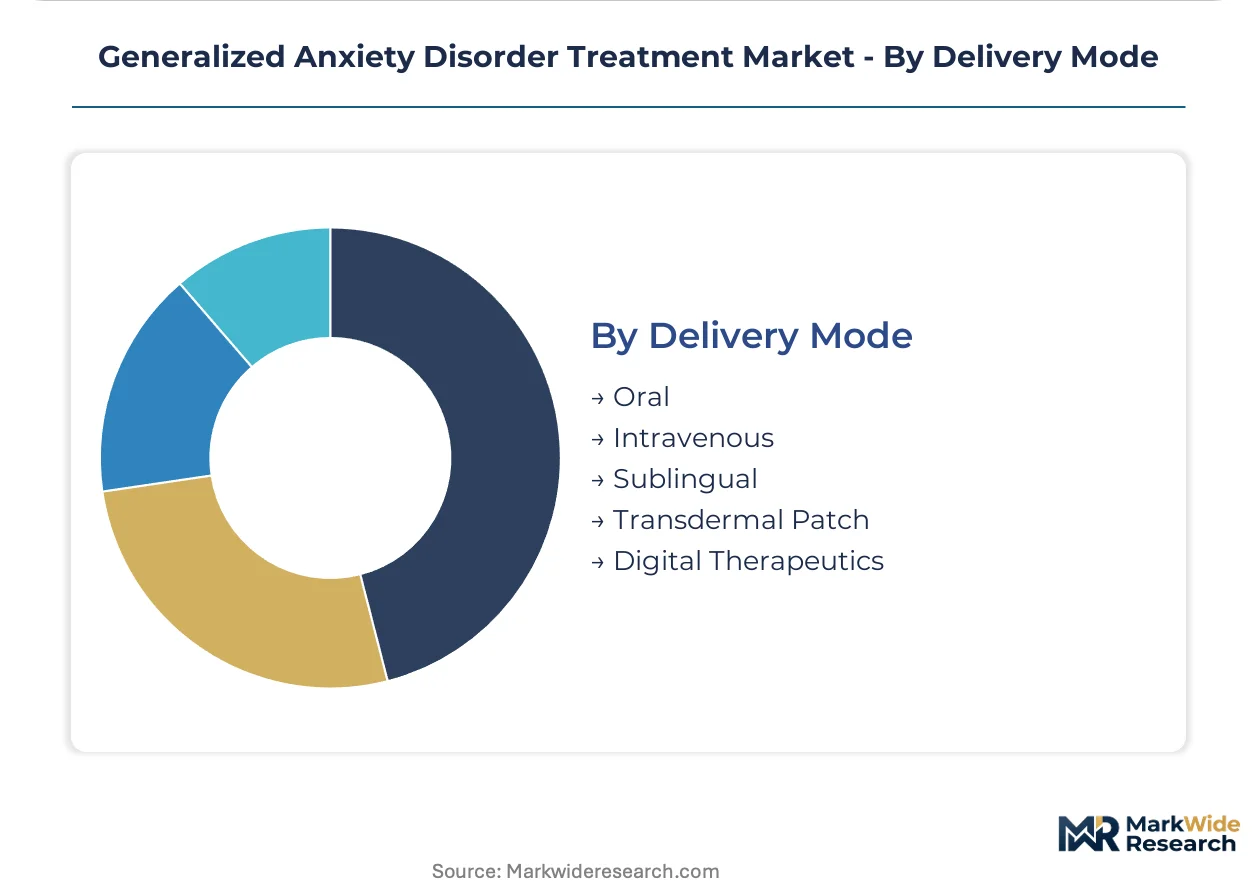
- Oral:Tablet and capsule formulations dominating first-line pharmacologic intervention. United States commercial formularies prioritize oral generics for initial therapy steps, with prior authorization requirements gating access to alternative routes.
- Digital Therapeutics:Prescription-grade software interventions delivered through synchronous telehealth platforms or standalone applications. FDA's evolving classification criteria for software-as-a-medical-device status are compressing development timelines for validated digital protocols while elevating evidence requirements.
- Intravenous:Hospital and infusion center administration for acute agitation or treatment-resistant cases requiring rapid onset.
- Sublingual:Rapid-absorption formulations targeting breakthrough anxiety episodes with faster onset than conventional oral routes.
- Transdermal Patch:Steady-state delivery systems with limited current anxiolytic application, more common in pain or motion sickness indications.
Dose administration concentrates through Oral delivery. Regulatory investment is flowing most heavily into Digital Therapeutics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Psychiatrists and clinical psychologists concentrate in metropolitan corridors across five countries, anchoring regional demand patterns for anxiolytic interventions and structured psychotherapy protocols.
United States
Commercial payer parity enforcement and employer-sponsored mental health unbundling drive demand expansion. FDA's accelerated approval pathways for novel anxiolytic compounds compress development timelines while elevating biomarker requirements. The Boston-Cambridge corridor hosts dense clusters of psychiatric research institutions and digital therapeutic developers.
Germany
Centralized health technology assessment frameworks reward robust cost-effectiveness data with premium pricing corridors for serotonergic interventions. EMA's centralized marketing authorization procedures harmonize standards across member states, consolidating previously fragmented national submission strategies. The Rhine-Main region concentrates pharmaceutical regulatory consulting and health economics expertise.
United Kingdom
NHS England's Improving Access to Psychological Therapies program sustains reimbursable volume for cognitive behavioral protocols. The National Institute for Health and Care Excellence maintains stringent evidence thresholds for formulary inclusion of novel mechanisms. London's Maudsley NHS Foundation Trust anchors specialist referral networks for treatment-resistant anxiety disorders.
Japan
PMDA's psychiatric drug review standards emphasize long-term safety databases for anxiolytic approvals, extending validation timelines for foreign entrants. METI's healthcare digitization initiatives accelerate telemedicine infrastructure for remote therapeutic delivery. The Tokyo-Osaka corridor concentrates board-certified psychiatrists and university-affiliated anxiety specialty clinics.
India
CDSCO's streamlined approval pathways for fixed-dose combinations attract generic manufacturers to the anxiolytic segment. The country's central bank monitors foreign direct investment in pharmaceutical manufacturing under automatic route liberalization. Hyderabad and Ahmedabad host contract research organizations supporting adaptive trial design for psychiatric indications.
Generalized Anxiety Disorder Treatment Market Competitive Landscape
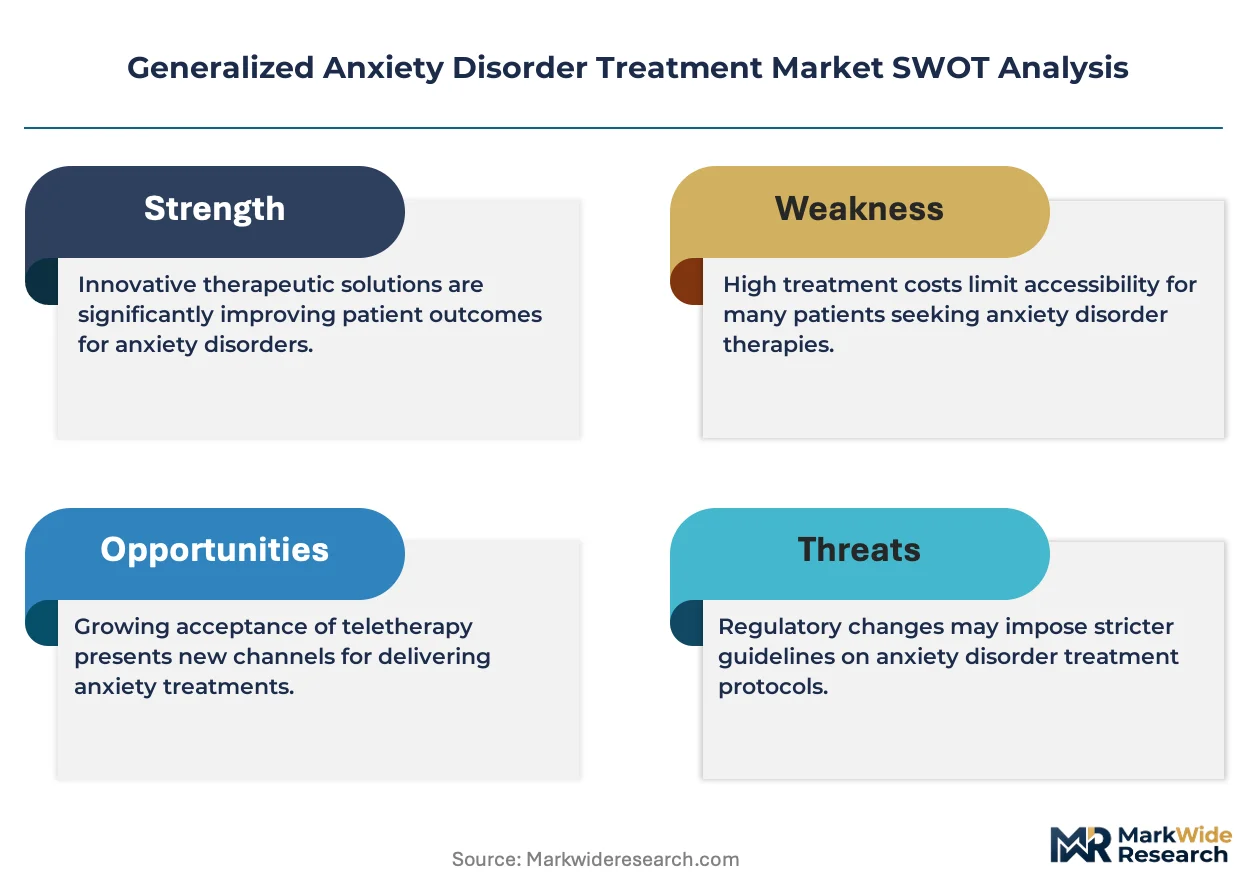
Diversified conglomerates compete with focused pure-play specialists across the anxiolytic landscape, creating a tiered structure where scale advantages in regulatory infrastructure confront agility in novel mechanism development. Consolidation pressures intensify as accelerated approval pathways demand front-loaded biomarker validation capabilities. Three archetypes dominate: integrated pharmaceutical conglomerates with psychiatric portfolios, mid-cap neuropsychiatric specialists, and emerging digital therapeutic platforms. Competitive moves concentrate on M&A for pipeline access and strategic partnerships for biomarker infrastructure.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Eli Lilly and Company exemplify scale-driven archetypes with established regulatory infrastructure and formulary relationships. AstraZeneca occupies a position within the European-focused tier, leveraging centralized health technology assessment expertise. These three entities represent contrasting geographic and strategic positioning within the competitive matrix.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| AstraZeneca |
| GlaxoSmithKline plc |
| Merck & Co. Inc. |
| Johnson & Johnson |
| Bristol-Myers Squibb |
| H. Lundbeck A/S |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
HIPAA interoperability mandates gate qualified supply for prescription-grade digital therapeutic platforms while simultaneously restricting premium-tier pricing access to vendors with certified electronic health record integration capabilities. This regulatory filter compresses margins for mid-tier developers lacking compliance infrastructure while concentrating pricing power among incumbents with established hospital system contracts.
Pricing Analysis
The bundled-vs-unbundled service split dominates pricing architecture across the Generalized Anxiety Disorder treatment landscape. United States behavioral health centers command bundled reimbursement rates for integrated pharmacologic and psychotherapeutic episodes, while telemedicine platforms unbundle discrete software interventions into subscription tiers. Price differentiation hinges on FDA clearance status and health technology assessment certification in European markets. Pricing pressure stems from generic SSRI commoditization in first-line pharmacologic segments. Employer-sponsored benefit plans exhibit highest price sensitivity, whereas hospital procurement committees prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on Indian and Chinese contract manufacturing organizations for serotonergic compounds, with United States and European facilities handling final formulation and packaging. Specialty chemical inputs for novel anxiolytic mechanisms draw from German and Swiss precision chemical producers. Single-source vulnerability concentrates in high-potency API synthesis for controlled-substance analogs. Distribution runs through three-tier pharmaceutical wholesaling networks in North America and direct-to-pharmacy models in European centralized procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Generalized Anxiety Disorder treatment market represents a late-cycle quality story as patient demand shifts toward FDA-cleared digital therapeutics with validated biomarker endpoints over unregulated wellness applications.
For Market Incumbents: Deepen vertical integration into biomarker validation infrastructure to defend against accelerated approval pathway requirements that favor developers with front-loaded neuroimaging capabilities. Consolidate formulary access through exclusive contracting with expanding behavioral health center networks. Prioritize R&D investment in next-generation serotonergic mechanisms with dual pain-anxiety indications to capture premium reimbursement tiers unavailable to pure anxiolytic competitors. For New Entrants and Emerging Players: Prescription digital therapeutics with asynchronous delivery protocols offer the most penetrable white-space opportunity, as synchronous telehealth platforms face clinician throughput constraints. Target employer-sponsored benefit channels in technology and financial services verticals where procurement authority has shifted to third-party administrators. Pursue FDA software-as-a-medical-device clearance as the primary go-to-market credential, bypassing the specialist referral bottleneck that constrains traditional pharmaceutical launches. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap neuropsychiatric specialists because accelerated approval pathways demand biomarker infrastructure that fragments development capabilities across smaller entities. The five-to-ten year viability window favors platforms with integrated digital-pharmacologic protocols over pure-play compound developers. Acquisition targets should demonstrate pan-European regulatory submission capabilities or established health technology assessment relationships. Watch FDA determinations on digital therapeutics classification criteria as the critical inflection signal for capital allocation toward regulated versus direct-to-consumer positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Infrastructure Investment | FDA's accelerated approval pathway elevates biomarker validation requirements that compress development timelines for prepared developers. |
| Digital Therapeutics Classification Pursuit | Software-as-a-medical-device determinations redirect R&D capital toward regulated prescription pathways with durable reimbursement codes. |
| European HTA Positioning | Centralized health technology assessment frameworks in Germany and France reward robust cost-effectiveness data with premium pricing corridors. |
| Behavioral Health Center Partnership | Rising patient volumes at specialized outpatient facilities expand the addressable base for integrated treatment episode bundling. |
| Biomarker Platform Acquisition | Front-loaded neuroimaging and peripheral biomarker capabilities create compliance moats against smaller entrants lacking validation infrastructure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at major commercial payers, and behavioral health center medical directors with secondary validation against FDA filings, EMA submission databases, ClinicalTrials.gov protocols, and hospital procurement records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segment-level estimates.
Segment-weighting approaches distributed value and volume across pharmacologic mechanism, therapy area modality, end-user setting, and delivery mode dimensions throughout the projection horizon. CAGRs derived from fitted growth curves applied to patient prevalence data and reimbursement rate trajectories, with cross-validation against historical analogs from adjacent psychiatric indications. Forecast inputs incorporated FDA approval probability assessments and European health technology assessment timeline assumptions.
The model holds under stable regulatory classification criteria for digital therapeutics and sustained commercial payer parity enforcement; deviation in FDA software-as-a-medical-device determinations or Medicare reimbursement rate adjustments would shift volume projections materially. Forecasts reflect documented assumptions regarding patient diagnosis rates and treatment-seeking behavior. A small set of named triggers warrants ongoing watch: digital therapeutics classification rulings, European HTA body consolidation patterns, and employer benefit unbundling velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market