
 Change and Configuration Management Market | 2026-2036
Change and Configuration Management Market Size, Share, and Industry Trends Forecast 2026-2036
Change and Configuration Management Market Analysis
Modular platform bundling is consolidating buyer choice across the Change and Configuration Management landscape, as vendors merge incident, change, and asset modules into unified suites. IBM Corporation leverages its Watson AI layer to differentiate predictive risk scoring within change workflows. ServiceNow Inc. anchors enterprise adoption through its ITSM-native configuration management database architecture. BMC Software Inc. specializes in mainframe-era configuration control extended to distributed cloud resources.
Change and Configuration Management encompasses the systematic governance of IT infrastructure modifications, version control, and baseline integrity through automated discovery, dependency mapping, and approval orchestration. The discipline ensures operational continuity by enforcing standardized change windows, rollback protocols, and audit trails across physical, virtual, and containerized environments. Cloud-based deployment models represent the fastest-expanding segment, driven by multi-tenant elasticity and API-native integration with DevOps pipelines. Consulting services command premium pricing due to bespoke maturity assessments and framework customization for regulated industries. Hybrid deployment retains durable share among manufacturing and telecommunications end users with latency-sensitive edge operations.
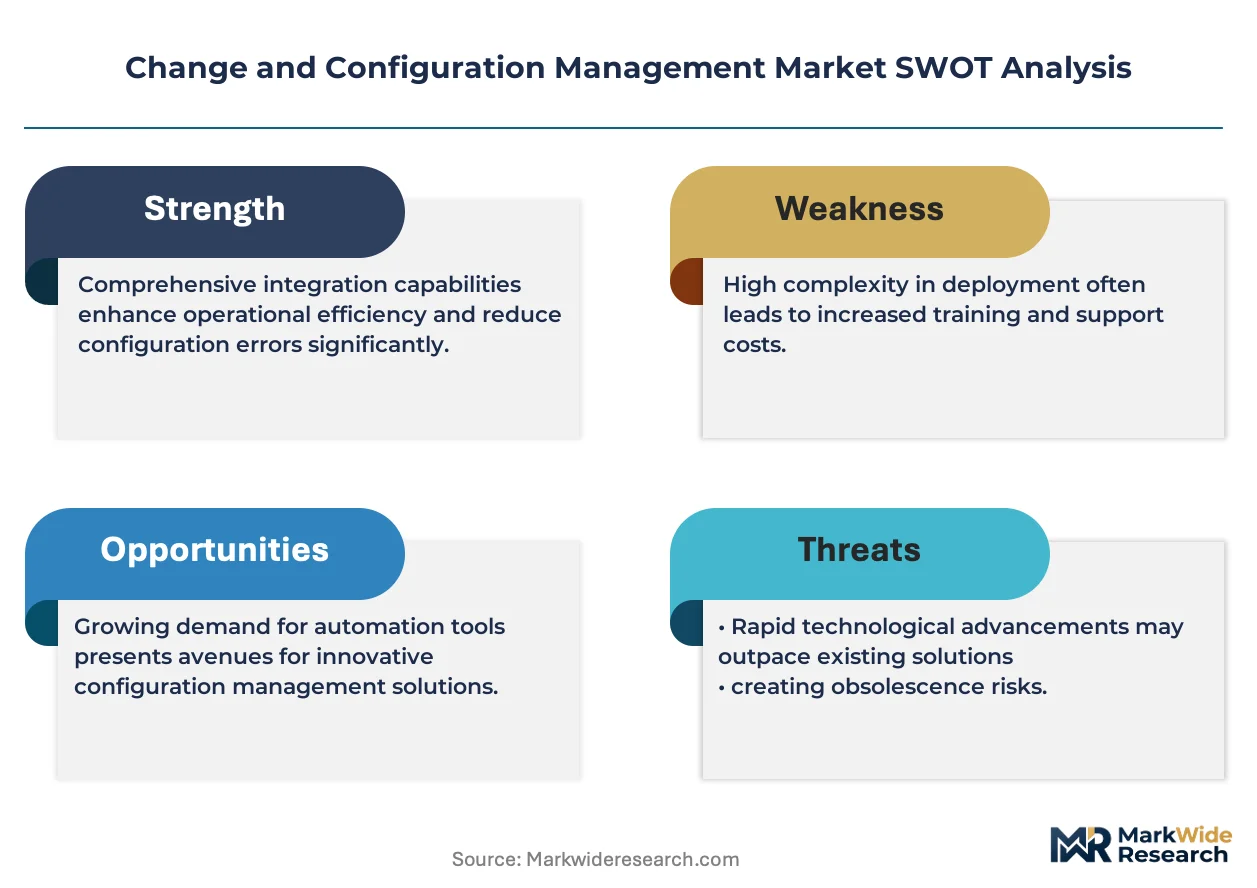
NIST, ISO/IEC 20000, and ITIL 4 frameworks collectively mandate auditable change records and configuration baselines, compelling enterprises to replace ad-hoc spreadsheets with certified platforms. The EU AI Act and sectoral digital operational resilience standards in Europe are extending configuration governance into automated decision systems. Stakeholders must evaluate whether their current tooling can map AI model versions, training data snapshots, and inference infrastructure as regulated configuration items.
Market Dynamics
Hybrid cloud complexity is forcing enterprises to abandon siloed change tools for unified platforms that span on-premise, multi-cloud, and edge infrastructure. Financial services and automotive manufacturers now mandate real-time configuration drift detection as a condition of operational approval.
Growth Catalysts
- Zero-trust mandates:NIST cybersecurity frameworks in the United States require continuous configuration verification and automated rollback capabilities, compelling federal contractors and critical infrastructure operators to upgrade legacy systems.
- Automotive standardization:German OEMs and industrial conglomerates are deploying enterprise-wide configuration databases to manage software-defined vehicle architectures and connected factory systems.
- DevOps pipeline integration:API-native change orchestration is electrifying adoption among cloud-native enterprises seeking to embed governance directly into CI/CD workflows without velocity trade-offs.
Market Restraints
- Implementation cost concentration:Multi-year deployment cycles for enterprise-scale configuration management databases require sustained professional services investment, pricing out mid-market buyers.
- Legacy system entrenchment:Mainframe-era configuration control tools in banking and telecommunications resist displacement due to decades of embedded business logic and compliance certification.
- Skills scarcity:Certified ITIL 4 practitioners and cloud infrastructure architects command premium compensation, constraining vendor delivery capacity and customer self-sufficiency.
Strategic Opportunities
- AI governance extension:EU AI Act compliance requirements create demand for configuration items tracking model versions, training data snapshots, and inference infrastructure as regulated assets.
- Edge computing penetration:Manufacturing and telecommunications operators with latency-sensitive distributed operations seek hybrid deployment models combining cloud elasticity with local configuration control.
- Consulting service premiumization:Bespoke maturity assessments and framework customization for regulated industries command pricing multiples above standard software licensing.
Industry Challenges
- Integration complexity:Enterprises struggle to reconcile agent-based discovery tools with containerized and serverless environments, creating visibility gaps in modern infrastructure estates.
- Audit trail fragmentation:Distributed teams using multiple change management tools generate inconsistent documentation, complicating ISO/IEC 20000 certification and regulatory examination preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Change and Configuration Management Market |
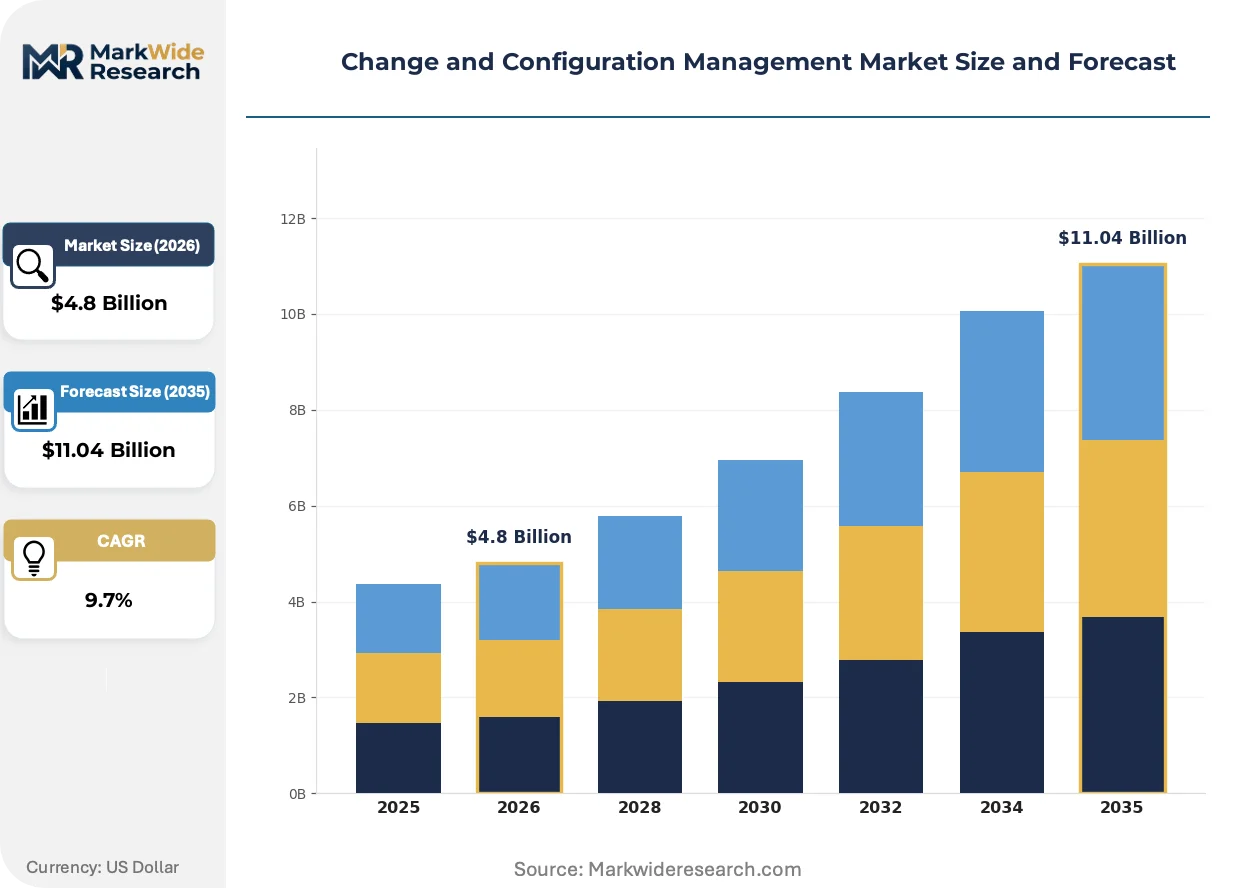
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Training, Support Deployment Model: On-Premise, Cloud-Based, Hybrid, Remote End User: IT Services, Telecommunications, Manufacturing, Retail Solution: Software, Platform, Framework, Toolset |
| Companies Covered | IBM Corporation, Microsoft Corporation, Amazon Web Services, BMC Software Inc., ServiceNow Inc., Hewlett Packard Enterprise, Atlassian Corporation Plc, Oracle Corporation, Broadcom Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Change and Configuration Management Market Emerging Trajectories
Artificial intelligence is electrifying competitive positioning across the Change and Configuration Management landscape, with predictive risk scoring and automated dependency mapping emerging as primary differentiators. Vendors are racing to embed machine learning into change approval workflows before standardization freezes architectural choices.
Machine learning-powered risk prediction is electrifying enterprise change workflows by analyzing historical incident patterns and infrastructure topology to flag high-risk modifications before deployment. Fortune 500 technology and financial services teams are adopting these capabilities at accelerated procurement cycles, compressing traditional pilot phases. This capability is electrifying vendor differentiation, as platforms without predictive layers face displacement in competitive evaluations.
EU AI Act implementation timelines are mandating configuration governance extensions into automated decision systems, requiring auditable records of model lineage and training data provenance. Industrial consequence includes new procurement specifications for MLOps-integrated change management in European banking and insurance. German automotive manufacturers and French pharmaceutical groups are most affected, embedding these requirements into supplier qualification criteria.
Enterprise buyers are consolidating vendor relationships around modular platform bundles that unify incident, change, and asset management within single architectural footprints. Traditional best-of-breed procurement for specialized configuration tools is losing share to integrated suites offering native CMDB connectivity. This consolidation pattern is most visible in United States healthcare systems and United Kingdom government digital transformation programs, where procurement complexity reduction outweighs feature depth preferences.
Change and Configuration Management Market Segmentation
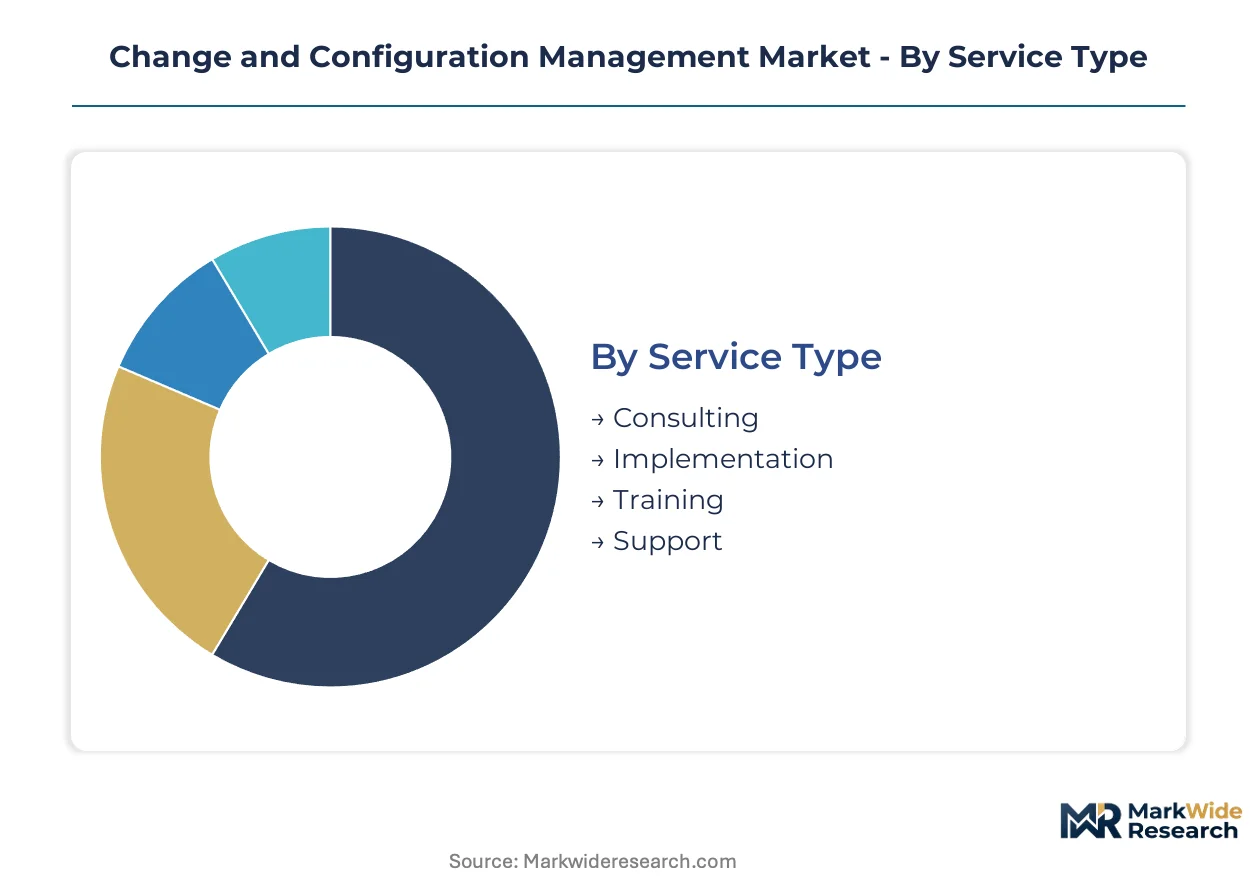
Change and Configuration Management procurement patterns diverge sharply across deployment models and service types, with regulated enterprises favoring hybrid architectures while cloud-native adopters prioritize API-native platforms. Understanding these segment boundaries clarifies where vendor consolidation versus specialization strategies succeed.
Service Type:
Buyer differentiation hinges on internal ITIL maturity and regulatory exposure rather than organization size alone.
- Consulting:Bespoke maturity assessments and framework customization for banking and pharmaceutical sectors command pricing premiums above standard software licensing. German automotive OEMs and United States federal contractors drive concentration here as NIST cybersecurity frameworks mandate certified implementation partners.
- Implementation:Multi-year deployment cycles for enterprise-scale configuration management databases demand sustained professional services investment, pricing out mid-market buyers. Financial services firms in New York and London represent the core demand cluster for these complex rollouts.
- Training:Certified ITIL 4 practitioners command premium compensation, constraining vendor delivery capacity and customer self-sufficiency.
- Support:24/7 operational continuity contracts concentrate among telecommunications operators and healthcare systems with zero-downtime requirements.
Volume sits with Implementation; growth tilts toward Consulting.
Deployment Model:
Latency sensitivity and data sovereignty requirements split buyers between edge-resident control and cloud elasticity.
- Cloud-Based:Multi-tenant elasticity and API-native integration with DevOps pipelines attract cloud-native enterprises seeking governance embedded directly into CI/CD workflows. United States technology firms and United Kingdom digital transformation programs lead procurement here.
- Hybrid:Manufacturing and telecommunications operators with latency-sensitive distributed operations combine cloud elasticity with local configuration control. German industrial conglomerates standardizing enterprise-wide configuration databases anchor this segment.
- On-Premise:Mainframe-era configuration control tools in banking resist displacement due to decades of embedded business logic.
- Remote:Distributed workforce enablement drives adoption among professional services firms with geographically dispersed IT teams.
Hybrid retains durable share; cloud-based deployment climbs the fastest.
End User:
Operational technology convergence versus pure IT infrastructure management separates buyer priorities across verticals.
- IT Services:Managed service providers bundle change and configuration capabilities into multi-tenant offerings for mid-market clients lacking internal expertise.
- Telecommunications:Real-time configuration drift detection is now mandated as a condition of operational approval for 5G network slicing and edge computing infrastructure.
- Manufacturing:Software-defined vehicle architectures and connected factory systems in Germany require enterprise-wide configuration databases spanning OT and IT domains.
- Retail:Seasonal demand spikes drive preference for elastic cloud deployment with rapid provisioning of configuration baselines across distributed store networks.
IT Services dominates current volume; Manufacturing shows steepest expansion trajectory.
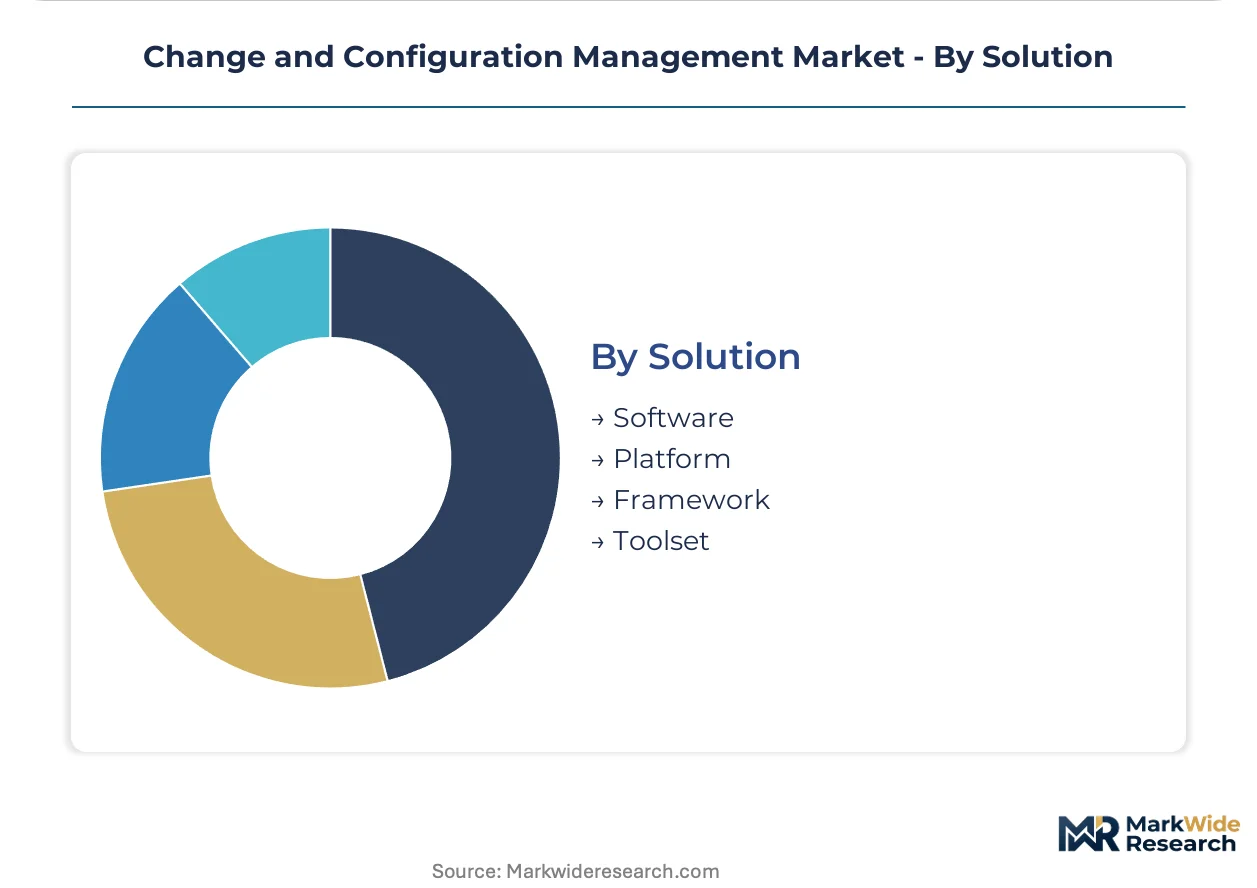
Solution:
Architectural integration depth versus functional specialization determines platform selection criteria.
- Software:Standalone change management applications face displacement as buyers consolidate around unified suites with native CMDB connectivity.
- Platform:Modular bundles unifying incident, change, and asset management within single architectural footprints are gaining share from best-of-breed procurement.
- Framework:ITIL 4 and ISO/IEC 20000-certified methodology implementations concentrate among regulated industries requiring auditable process documentation.
- Toolset:Specialized discovery and dependency mapping utilities persist in heterogeneous environments with legacy infrastructure components.
Platform solutions capture volume; Framework adoption accelerates fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Change and Configuration Management solutions concentrate where financial services and automotive manufacturing demand rigorous IT governance. The United States leads procurement volume through federal cybersecurity mandates, while Germany anchors European standardization efforts for industrial digitization.
United States
Financial services firms in New York and federal contractors near Washington D.C. drive procurement of automated configuration tools for hybrid cloud estates. NIST cybersecurity frameworks mandate continuous verification capabilities, compelling critical infrastructure operators to upgrade legacy systems. Silicon Valley technology clusters accelerate adoption of API-native platforms embedded within DevOps pipelines.
Germany
Automotive OEMs and industrial conglomerates standardize enterprise-wide configuration databases for software-defined vehicle architectures. The EU AI Act extends governance requirements into automated decision systems, mandating auditable model lineage records. Manufacturing hubs in Bavaria and Baden-Württemberg embed these specifications into supplier qualification criteria.
United Kingdom
Government digital transformation programs consolidate vendor relationships around unified suites with native CMDB connectivity. ISO/IEC 20000 certification requirements concentrate procurement among regulated industries requiring auditable process documentation. London-based financial services and healthcare systems prioritize procurement complexity reduction over feature depth.
Japan
Telecommunications operators mandate real-time configuration drift detection for 5G network slicing infrastructure. METI industrial digitization initiatives accelerate replacement of spreadsheet-based change tracking with certified platforms. Manufacturing clusters in Nagoya and Osaka deploy hybrid deployment models combining cloud elasticity with local control.
India
IT services providers bundle change and configuration capabilities into multi-tenant offerings for mid-market clients lacking internal expertise. RBI cybersecurity guidelines for financial institutions drive demand for compliant change management platforms. Bangalore and Hyderabad technology corridors concentrate delivery capacity for global managed service contracts.
Change and Configuration Management Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Enterprise software majors leverage existing ITSM relationships to bundle configuration management into broader service management suites. Three strategic archetypes dominate: platform consolidators unifying incident, change, and asset modules; cloud-native specialists emphasizing API-first architecture; and legacy mainframe-era vendors extending configuration control to distributed resources. Competitive moves concentrate on M&A for capability gaps and strategic partnerships for DevOps pipeline integration.
Within the platform consolidator tier, IBM Corporation and ServiceNow Inc. exemplify divergent approaches to market positioning. IBM leverages AI-enhanced risk prediction layered across enterprise change workflows, while ServiceNow anchors adoption through ITSM-native configuration management database architecture. BMC Software Inc. occupies a specialized position extending mainframe-era configuration discipline into hybrid cloud environments.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| BMC Software Inc. |
| ServiceNow Inc. |
| Hewlett Packard Enterprise |
| Atlassian Corporation Plc |
| Oracle Corporation |
| Broadcom Inc |
| Others |
Supply Flow & Price Mechanics
Professional services labor costs cascade through Change and Configuration Management pricing tiers, with certified ITIL 4 practitioners and cloud infrastructure architects commanding premium compensation that concentrates in New York and London financial services clusters before diffusing into standardized SaaS subscription models for mid-market buyers.
Pricing Analysis
Margin tightening in enterprise implementation tiers reflects multi-year deployment cycles for configuration management databases that demand sustained professional services investment. Three-tier pricing structure across premium consulting engagements, standard platform licensing, and economy self-service SaaS separates buyers by ITIL maturity and regulatory exposure. Cost-down pressure on mid-market subscriptions accelerates because vendor delivery capacity constrains customer self-sufficiency. Federal contractors and German automotive OEMs show least price sensitivity; mid-market IT services firms exhibit highest elasticity.
Supply Chain Analysis
Freight costs for on-premise hardware appliances and edge computing nodes concentrate supply chain expenditure in United States, Germany, and Japan manufacturing corridors. Software development draws from Indian technology corridors, Eastern European engineering hubs, and Silicon Valley AI research clusters. Single-source vulnerability around certified ITIL 4 training capacity creates delivery bottlenecks. Distribution runs through direct enterprise sales for large accounts and hyperscaler marketplaces for cloud-native adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Change and Configuration Management vendors are racing to secure upstream control over AI training data and downstream integration with DevOps pipeline orchestration as the defining vertical-integration contest.
For Market Incumbents: Acquire specialized MLOps governance startups before EU AI Act compliance deadlines harden procurement specifications. Consolidate incident, change, and asset modules into unified suites with native CMDB connectivity to displace best-of-breed point solutions. Cloud-native specialists embedding governance into CI/CD workflows threaten displacement of legacy platform architectures. For New Entrants and Emerging Players: Launch via API-first marketplace distribution targeting United States technology firms and United Kingdom government digital transformation programs. Manufacturing OT-IT convergence in Germany and real-time drift detection mandates in telecommunications represent the most penetrable white-space. Position around edge-resident configuration control for latency-sensitive distributed operations. For Investors and Strategic Acquirers: NIST cybersecurity framework procurement announcements from federal contractors are the leading indicator that zero-trust compliance spending is accelerating. Platforms with predictive risk scoring capabilities and automated dependency mapping represent the preferred acquisition archetype over the coming decade. Watch for EU AI Act implementation timelines triggering MLOps-integrated change management procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Extension | EU AI Act mandates auditable model lineage records for European banking and insurance procurement. |
| Platform Integration | Native CMDB connectivity displaces standalone change management applications in healthcare systems. |
| Edge Computing Penetration | Hybrid deployment models capture manufacturing and telecommunications latency-sensitive operations. |
| Strategic Partnership | DevOps pipeline integration embeds governance into CI/CD workflows without velocity trade-offs. |
| Acquisition of Specialist Firm | MLOps governance startups harden compliance specifications before standardization freezes architectural choices. |
Methodological Framework
Document review covered SEC filings from enterprise software majors, hyperscaler capex disclosures, and ITIL certification body records, complemented by interviews with CTOs at financial services firms, IT procurement officers in German automotive OEMs, platform engineers at cloud-native enterprises, and integration specialists at managed service providers. Secondary validation drew from NIST cybersecurity framework documentation, EU AI Act implementation guidance, and ISO/IEC 20000 certification databases. Bottom-up deployment model sizing and top-down regulatory mandate impact assessment were triangulated against vendor revenue disclosures.
Market size and growth trajectory outputs were generated through segmentation modeling across deployment models, service types, end-user verticals, and solution architectures. CAGRs were derived from regression analysis of historical procurement patterns against regulatory mandate timelines and cloud adoption curves. Forecast inputs incorporated ITIL 4 practitioner supply constraints, federal cybersecurity spending authorization trends, and software-defined vehicle architecture deployment schedules from German automotive manufacturers.
Regulatory enforcement delays, cloud migration cost overruns, and AI governance standardization failures are the dominant revision risks that could compress or extend projected expansion timelines. Stakeholders should weight assumptions against their own operating context and certification readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Location As a Service Market
Digital Solutions
Product Data Management Market