
 Product Data Management Market | 2026-2036
Product Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Product Data Management Market Outlook
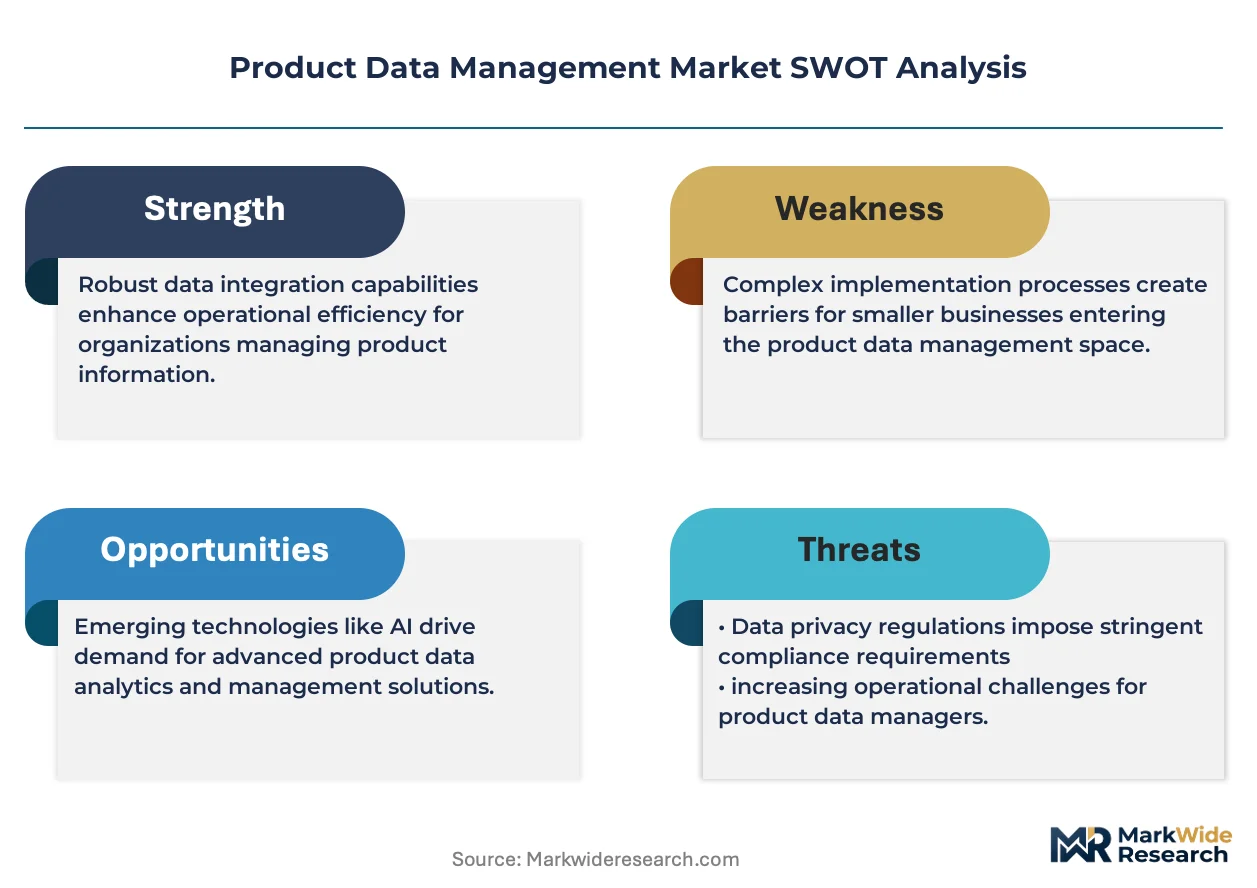
REACH compliance is pivoting how European manufacturers evaluate PDM vendors, elevating data lineage and material traceability from nice-to-have features to contractual requirements. Siemens Teamcenter leverages its embedded CAD heritage to anchor aerospace and defense workflows where configuration management carries regulatory weight. Oracle competes through database-layer integration that sustains enterprise loyalty among Fortune 500 manufacturers with heterogeneous ERP estates.
Product Data Management denotes the systematic governance of technical specifications, digital assets, and lifecycle metadata across design, production, and commercial channels, typically operating through centralized repositories with version control, access permissions, and API connectivity to CAD, ERP, and CRM systems. Cloud Platforms are capturing disproportionate growth as manufacturers retire on-premises PLM footprints, while Data Quality Management commands premium pricing because inaccurate attribution propagates downstream into regulatory filings and channel partner disputes. Workflow Automation remains a mature margin pool where incumbents defend renewal revenue through deep ERP integration rather than feature innovation.
FDA 21 CFR Part 11 and EU MDR impose validation requirements on PDM systems serving medical device manufacturers, forcing vendors to maintain audit trails and electronic signature capabilities that smaller cloud-native entrants struggle to certify. Germany's KBA enforces type-approval documentation standards that automotive suppliers must satisfy through traceable product data architectures. Stakeholders should monitor how CSRD sustainability disclosure rules expand the scope of mandatory product attributes, as this will determine whether PDM platforms absorb ESG data management or cede that territory to specialized carbon accounting software.
Market Dynamics
Cloud migration mandates from the EU AI Act and parallel data governance frameworks are compressing replacement cycles for legacy PLM estates, forcing manufacturers to re-platform technical data infrastructure on accelerated timelines.
Growth Catalysts
- REACH compliance mandates:European chemical disclosure rules now require material traceability that only modern PDM architectures can deliver, elevating data lineage to a contractual requirement in supplier agreements.
- Automotive engineering unification:German OEMs and Tier-1 suppliers are consolidating engineering and commercial data streams to satisfy KBA type-approval documentation standards.
- Medical device validation:FDA 21 CFR Part 11 and EU MDR impose audit trail and electronic signature requirements that drive certified PDM procurement among device manufacturers.
Market Restraints
- Cloud certification costs:FDA and EMA validation protocols for cloud-native platforms impose six-figure compliance burdens that deter mid-market manufacturers from migrating off legacy systems.
- ERP integration complexity:Heterogeneous enterprise software estates, particularly among Fortune 500 manufacturers with decades of Oracle or SAP investment, create switching friction that prolongs sales cycles.
- Specialized talent scarcity:Configuration management expertise combining PLM domain knowledge with modern API architecture skills concentrates in Munich, Stuttgart, and Wolfsburg, limiting vendor delivery capacity elsewhere.
Strategic Opportunities
- CSRD sustainability integration:The EU's Corporate Sustainability Reporting Directive expands mandatory product attributes, creating white space for PDM platforms to absorb ESG data management or defend against specialized carbon accounting entrants.
- Workflow automation convergence:Manufacturers in Baden-Württemberg are demanding unified platforms that merge PDM governance with automated engineering change workflows, displacing point solutions.
- Medical device aftermarket:Post-market surveillance requirements under EU MDR create recurring revenue streams for PDM vendors serving device manufacturers with field feedback integration.
Industry Challenges
- Legacy CAD migration:Aerospace and defense contractors face multi-year data migration projects to preserve configuration-controlled design histories while modernizing repository architectures.
- Cross-functional alignment:Engineering, quality, and commercial teams maintain conflicting data taxonomies that complicate enterprise PDM deployments and extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Data Management Market |
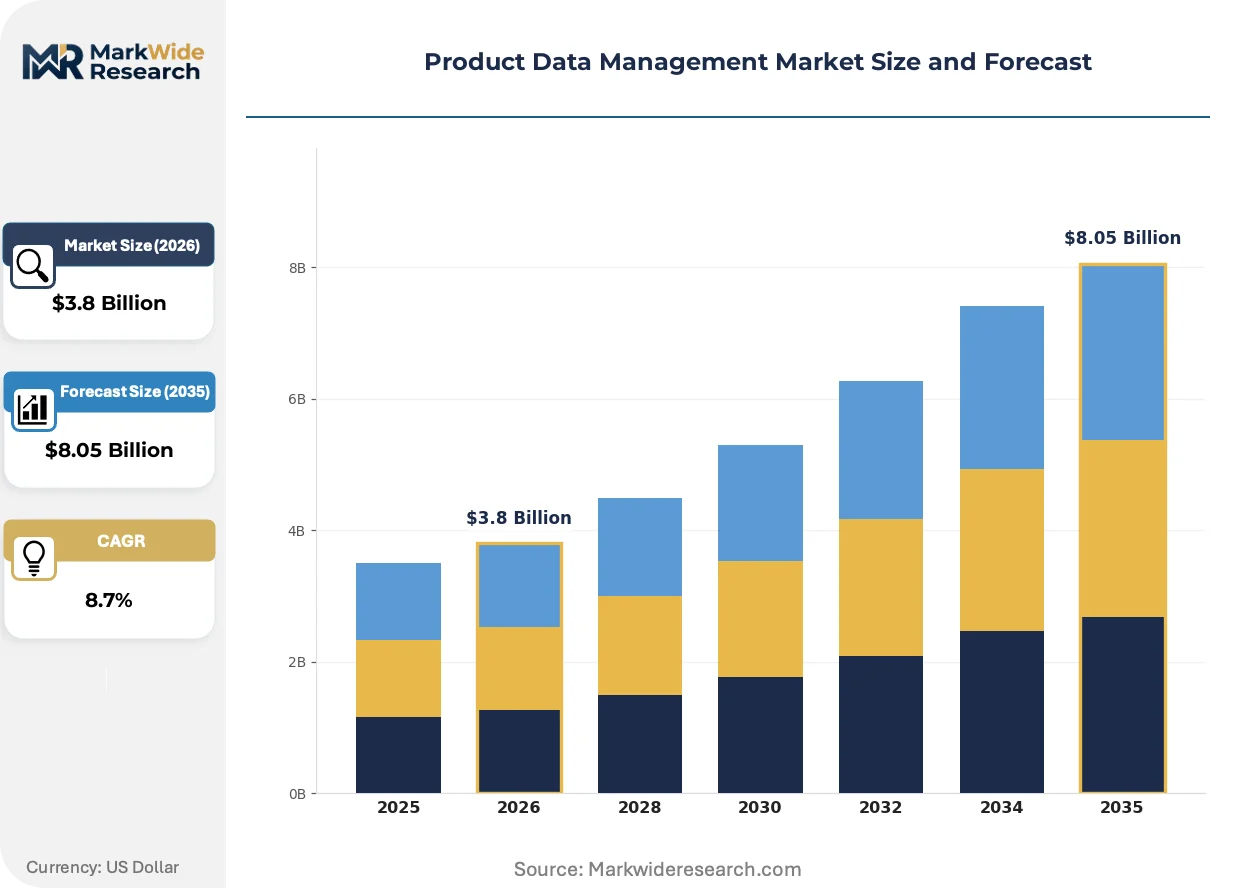
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Platforms, On-Premises Systems, Integration Tools End User: Manufacturers, Retailers, Distributors, E-commerce Platforms Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Servers Feature: Data Quality Management, Workflow Automation, Multi-Channel Management, Reporting & Analytics |
| Companies Covered | Informatica, Siemens Teamcenter, Oracle, SAP, PTC Windchill, Stibo Systems, Salsify, Inriver, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Data Management Market Strategic Shifts
Digital thread architectures are displacing document-centric workflows across discrete manufacturing, compressing the distance between design intent and production execution.
Graph-based data models are expanding into aerospace supply chains where Siemens Teamcenter and rival platforms compete to capture multi-level bill-of-material relationships. Airbus and Safran suppliers in Toulouse and Hamburg are piloting these architectures to compress configuration audit cycles from weeks to days. The technology is expanding into commercial aviation aftermarket services, enabling predictive maintenance through unified product genealogy.
REACH substance restrictions are forcing reformulation data tracking that legacy PLM systems cannot accommodate without architectural overhaul. Chemical manufacturers in Ludwigshafen and Leverkusen now demand material composition databases that propagate automatically into safety data sheets. Automotive seating and interior suppliers face the steepest compliance burden, driving replacement of decade-old PDM instances.
Subscription pricing models are displacing perpetual licenses among Mittelstand manufacturers seeking to preserve capital for production equipment. Procurement committees in Bavaria and North Rhine-Westphalia now evaluate total cost of ownership over five-year horizons rather than upfront license fees. This shift favors vendors with consumption-based metering that aligns costs with actual data transaction volumes.
Product Data Management Market Segmentation
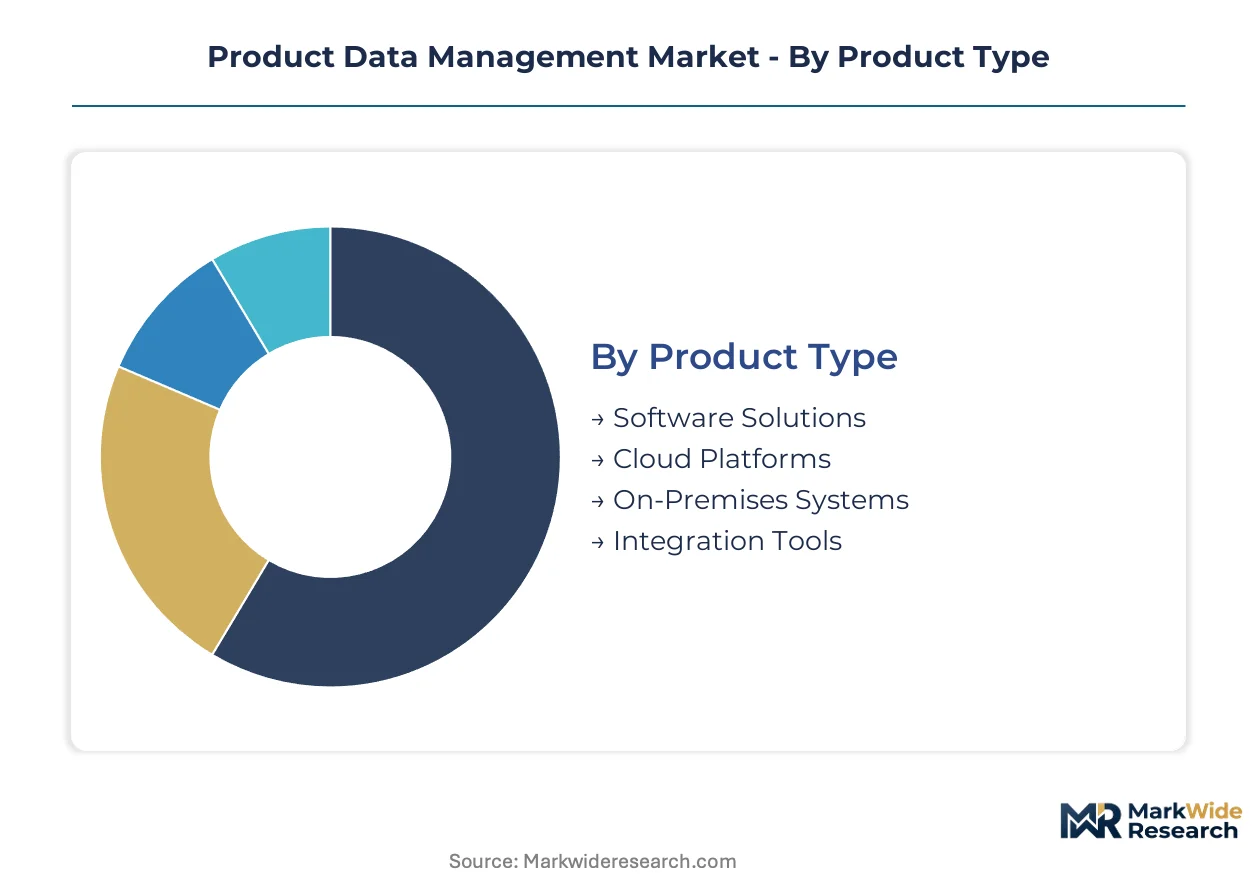
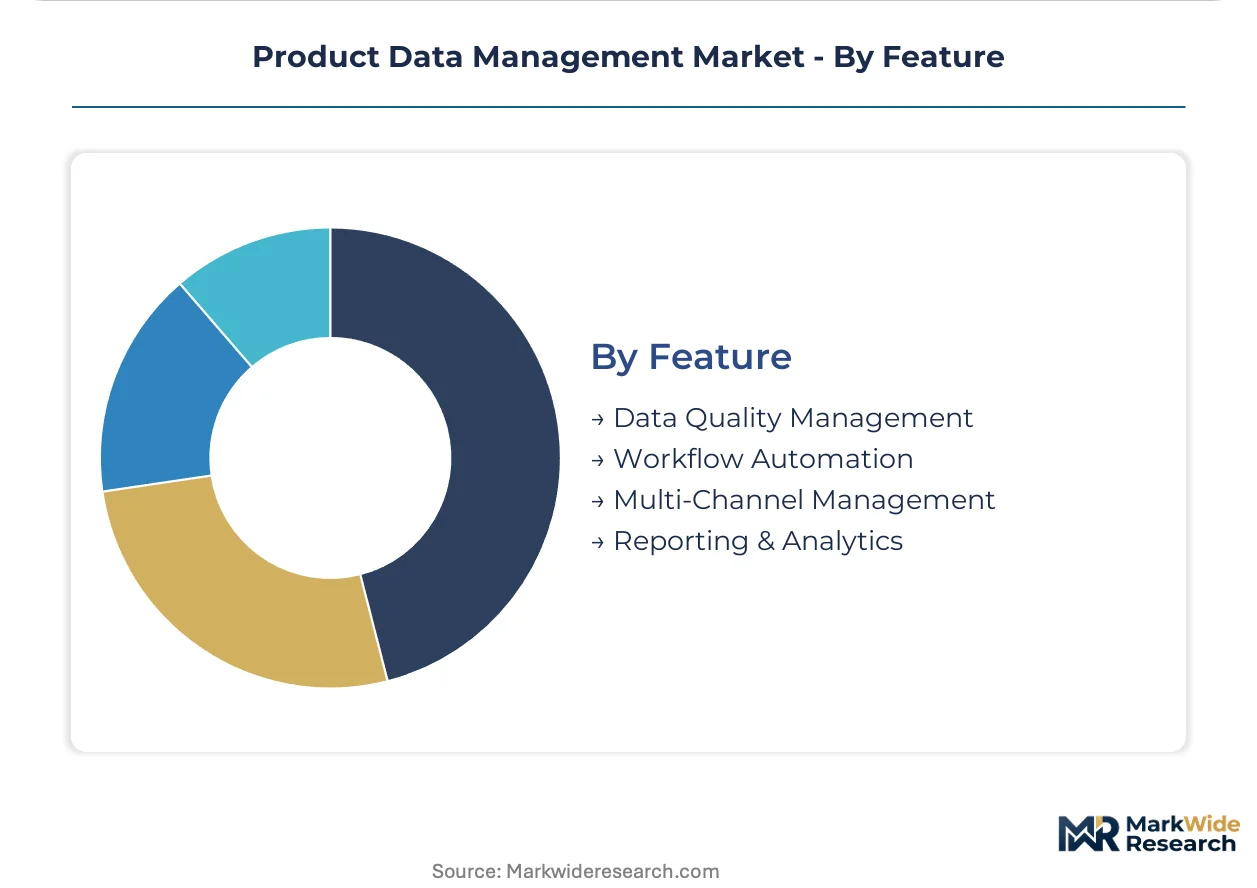
Product Data Management market segmentation reveals how technical architecture choices determine integration depth and regulatory compliance burden. Deployment models and feature sets vary sharply between standalone governance tools and embedded enterprise systems.
Product Type:
Integration depth separates standalone software from embedded systems that anchor broader PLM estates.
- Software Solutions:Modular applications addressing specific data governance workflows without full PLM commitment. German automotive suppliers in Baden-Württemberg deploy these to satisfy KBA documentation requirements while preserving legacy CAD investments.
- Cloud Platforms:Scalable architectures with API-native connectivity to ERP and CRM systems. REACH compliance mandates are accelerating replacement of on-premises estates among European chemical manufacturers who need real-time material traceability across distributed supply chains.
- On-Premises Systems:Repository architectures maintained within manufacturer data centers for maximum configuration control. Aerospace contractors in Toulouse and Hamburg retain these for defense-classified programs where air-gapped security is non-negotiable.
- Integration Tools:Middleware and connectors bridging heterogeneous software estates. Oracle and SAP customers with decades of ERP investment use these to avoid full platform replacement while achieving data unification.
Cloud Platforms lead volumes today; Software Solutions are gaining share fastest among mid-market manufacturers seeking modular procurement.
End User:
Customer type determines whether PDM serves production engineering or commercial operations as the primary data authority.
- Manufacturers:Discrete and process producers governing technical specifications through design-to-production lifecycles. FDA 21 CFR Part 11 validation requirements force medical device makers in Massachusetts and Minnesota to maintain audit trails that cloud-native entrants struggle to certify.
- Retailers:Multi-channel merchants synchronizing product attribution across physical and digital storefronts. EU MDR post-market surveillance rules are expanding their data retention obligations beyond traditional commercial parameters.
- Distributors:Intermediaries requiring attribution consistency across supplier networks. CSRD sustainability disclosure mandates are forcing these players to capture carbon footprint data previously outside their technical scope.
- E-commerce Platforms:Digital-native retailers with real-time catalog management and dynamic pricing engines. Their API-first architectures favor cloud PDM deployments with consumption-based metering over perpetual license models.
Manufacturers dominate revenue concentration; E-commerce Platforms are expanding most quickly as digital retail penetration deepens.
Deployment:
Architecture choice reflects data sovereignty requirements and validation protocol complexity.
- Public Cloud:Shared infrastructure with vendor-managed security and automatic scaling. Subscription pricing aligns costs with transaction volumes, appealing to Mittelstand capital preservation strategies.
- Private Cloud:Dedicated single-tenant environments with customizable security boundaries. Swiss pharmaceutical manufacturers and Swissmedic-regulated operations favor these for clinical trial data segregation.
- Hybrid Cloud:Architectures splitting sensitive data on-premises while leveraging cloud elasticity for non-critical workloads. Automotive OEMs use this to protect powertrain IP while enabling supplier collaboration portals.
- Local Servers:Physical hardware within manufacturer facilities. Defense contractors facing ITAR and export control requirements maintain these for air-gapped configuration management.
Hybrid Cloud leads new deployment decisions; Public Cloud is climbing the fastest as EU AI Act data governance frameworks accelerate migration timelines.
Feature:
Capability prioritization separates compliance-driven procurement from efficiency-focused investment.
- Data Quality Management:Validation engines ensuring attribute accuracy across source systems. REACH substance tracking and safety data sheet propagation require these capabilities, commanding premium pricing due to regulatory filing consequences of error.
- Workflow Automation:Engineered change routing and approval orchestration. Mature margin pool where incumbents defend renewals through deep ERP integration rather than feature differentiation.
- Multi-Channel Management:Attribution synchronization across wholesale, retail, and direct-to-consumer channels. E-commerce platforms in Bavaria and North Rhine-Westphalia evaluate these for five-year total cost of ownership against point solutions.
- Reporting & Analytics:Dashboard and visualization tools for product performance and compliance status. CSRD expansion of mandatory product attributes is driving convergence with ESG data management requirements.
Data Quality Management commands highest pricing; Workflow Automation holds largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Configuration management expertise clusters in Stuttgart, Munich, and Wolfsburg, anchoring European PDM procurement gravity. This talent concentration shapes vendor delivery capacity and customer sophistication across multiple geographies.
Germany
KBA type-approval documentation standards force automotive suppliers to unify engineering and commercial data streams. REACH compliance mandates elevate material traceability to contractual requirements in supplier agreements. Mittelstand exporters in Bavaria and Baden-Württemberg now evaluate total cost of ownership over five-year horizons rather than upfront license fees.
United States
FDA 21 CFR Part 11 validation requirements drive certified PDM procurement among medical device manufacturers in Massachusetts and Minnesota. Cloud certification protocols impose six-figure compliance burdens that deter mid-market manufacturers from migrating off legacy systems. Aerospace contractors in Seattle and Los Angeles retain on-premises systems for ITAR-controlled programs requiring air-gapped security.
France
Airbus and Safran suppliers in Toulouse pilot graph-based data models to compress configuration audit cycles from weeks to days. ANSM medical device regulations extend post-market surveillance data retention obligations beyond traditional commercial parameters. Commercial aviation aftermarket services in Paris are adopting predictive maintenance through unified product genealogy architectures.
Switzerland
Swissmedic-regulated pharmaceutical manufacturers favor private cloud deployments for clinical trial data segregation. Precision engineering clusters in Basel and Zurich demand API-native connectivity to heterogeneous ERP estates. Subscription pricing models align costs with actual data transaction volumes, appealing to capital preservation strategies among Mittelstand-scale exporters.
China
MIIT industrial software integration policies accelerate replacement of legacy PLM footprints among state-owned automotive groups. Dual carbon goals under MEE supervision expand mandatory product attributes into carbon footprint tracking. Yangtze River Delta manufacturers are consolidating technical data infrastructure on compressed timelines driven by data governance frameworks.
Product Data Management Market Competitive Environment
The competitive structure tilts toward diversified technology conglomerates with embedded CAD heritage and database-layer integration capabilities. Siemens Teamcenter leverages aerospace configuration management relationships where regulatory weight determines procurement decisions. Oracle sustains enterprise loyalty through ERP integration depth among Fortune 500 manufacturers with heterogeneous software estates. The dominant competitive moves are cloud platform replacement cycles accelerated by EU AI Act mandates and subscription pricing model adoption to align vendor costs with customer transaction volumes.
Within the diversified technology tier, Siemens Teamcenter and Oracle exemplify contrasting integration strategies—CAD-anchored workflows versus database-layer connectivity. Stibo Systems and Salsify occupy positions in the master data management specialization vector serving multi-channel attribution requirements. Informatica represents the data integration archetype bridging heterogeneous enterprise software estates without full platform replacement.
| Leading Market Players |
|---|
| Informatica |
| Siemens Teamcenter |
| Oracle |
| SAP |
| PTC Windchill |
| Stibo Systems |
| Salsify |
| Inriver |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Enterprise software license index movements cascade through PDM vendor pricing tiers, compressing margins on perpetual-license maintenance streams while expanding subscription-based recurring revenue pools among cloud-native deployments.
Pricing Analysis
Bundle-unbundle service splits separate platform licensing from implementation and validation support, creating three-tier pricing stratification across premium certification-grade, standard enterprise, and economy mid-market levels. Price differentiation hinges on FDA 21 CFR Part 11 validation depth and ERP integration complexity, with aerospace and medical device buyers showing lowest sensitivity due to regulatory filing consequences. Pricing pressure stems from REACH compliance mandates forcing architectural overhauls that vendors absorb through compressed professional services margins. Mittelstand manufacturers in Bavaria exhibit highest price sensitivity, evaluating five-year total cost of ownership against capital preservation priorities.
Supply Chain Analysis
Configuration management talent scarcity in Stuttgart, Munich, and Wolfsburg constrains vendor delivery capacity and elongates implementation timelines for enterprise deployments. Supply concentration rests on Germany, the United States, and Switzerland, with cloud infrastructure dependencies on hyperscale providers and specialized compliance certification services. Single-source vulnerability runs through concentrated PLM domain expertise pools, where API architecture skills intersecting with regulatory knowledge remain scarce outside German automotive clusters. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for complex ERP integration projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Product Data Management functions as a stable compounder anchored by regulatory compliance mandates that perpetually refresh replacement cycles across manufacturing verticals.
For Market Incumbents: Lock in renewal revenue through deep ERP integration moats that increase switching costs for Fortune 500 manufacturers with heterogeneous Oracle and SAP estates. Prioritize certification investment in FDA 21 CFR Part 11 and EU MDR validation protocols to defend against cloud-native entrants struggling with six-figure compliance burdens. Channel control through systems integrator partnerships in German industrial clusters limits emerging competitor access to Mittelstand procurement committees. For New Entrants and Emerging Players: Capture CSRD sustainability data management white space before specialized carbon accounting software cedes territory, targeting mid-market chemical manufacturers in Ludwigshafen and Leverkusen facing REACH substance tracking mandates. The most penetrable segment lies among automotive seating and interior suppliers confronting steepest compliance burdens without legacy PLM sunk costs. API-first go-to-market positioning aligns with e-commerce platform procurement preferences for consumption-based metering. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms possessing pre-built FDA and EMA validation documentation that accelerates mid-market manufacturer migration timelines. Long-term viability across the analysis window favors vendors absorbing ESG data management scope rather than ceding to point solutions. Monitor EU AI Act implementation enforcement as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity sustains renewal revenue among heterogeneous enterprise software estates. |
| Certification Investment | FDA 21 CFR Part 11 validation protocols defend aerospace and medical device procurement decisions. |
| Geographic Expansion | Munich and Stuttgart talent clusters anchor European delivery capacity for Mittelstand exporters. |
| Acquisition of Specialist Firm | Graph-based data model capabilities compress configuration audit cycles for Airbus suppliers. |
| Product Launch | CSRD-aligned sustainability modules capture ESG data management scope from carbon accounting entrants. |
Study Parameters
Direct dialogue with PLM implementation consultants, enterprise IT procurement officers, automotive platform engineers, and regulatory compliance directors grounded qualitative findings, cross-referenced against SEC 10-K filings, EU MDR guidance documents, KBA type-approval standards, and hyperscaler cloud revenue disclosures. Bottom-up deployment estimates triangulated with top-down market sizing across software solutions, cloud platforms, and integration tools categories.
Segment-level outputs across deployment models, end-user verticals, and feature capabilities were validated against primary field intelligence throughout the projection horizon. CAGRs were derived from replacement cycle velocity analysis incorporating EU AI Act migration mandates and REACH compliance deadlines. Industry-specific inputs included KBA documentation standard enforcement timelines and FDA validation protocol cost structures.
Regulatory enforcement delays, cloud certification backlog accumulation, and ERP integration project cancellations are the dominant revision risks to modeled forecasts. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Voice Remote Control Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
US Customer Communication Management (CCM) Market