
 Canada Digital Twin Market | 2026-2036
Canada Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Digital Twin Market Insights
The Canada digital twin landscape is pivoting between premium enterprise-grade platforms with full physics-based simulation and commodity SaaS offerings limited to basic dashboarding. ThoughtWire leverages its healthcare specialization to anchor complex hospital system modeling in Ontario and British Columbia. Siemens competes through its industrial automation heritage, sustaining deep manufacturing integration across automotive and energy verticals. Microsoft extends cloud infrastructure dominance by positioning Azure Digital Twins as the underlying fabric for third-party developers nationwide.
A digital twin constitutes a dynamic virtual representation of a physical object, system, or process that ingests real-time sensor data and applies physics-based or data-driven models to simulate behavior, predict performance, and optimize operations. The technology relies on IoT connectivity protocols, spatial computing frameworks, and API architectures that synchronize state changes between physical and virtual instances. Manufacturing applications currently lead deployment scale due to immediate ROI visibility from reduced unplanned downtime, while healthcare and urban planning segments represent faster-growing opportunity pools where regulatory compliance and infrastructure modernization create structural demand. Cloud-based deployment dominates new implementations for scalability, though hybrid architectures retain margin concentration in defense and critical infrastructure contexts where data sovereignty requirements restrict full off-premise migration.
Health Canada and PMRA impose traceability and validation standards that shape digital twin specifications in pharmaceutical and medical device manufacturing, while the Canadian Standards Association and federal cybersecurity frameworks govern critical infrastructure implementations. Provincial privacy legislation, notably Quebec's Law 25 and British Columbia's enhanced public-sector data protocols, creates compliance complexity that favors vendors with embedded governance tooling. Stakeholders must monitor evolving federal critical infrastructure designation rules and provincial procurement mandates to anticipate which deployment architectures and certification pathways will determine market access.
Market Dynamics
Physics-based simulation capabilities are compressing deployment timelines for Canadian manufacturers, while Health Canada traceability mandates force pharmaceutical facilities to rebuild validation protocols around real-time data architectures.
Growth Catalysts
- Health Canada PMRA Traceability Mandates:Pharmaceutical and medical device manufacturers must implement validated digital records for batch genealogy, forcing facility-wide digital twin deployments to satisfy inspection readiness.
- Ontario Manufacturing Density:Automotive and aerospace clusters around Toronto-Waterloo generate concentrated demand for asset mirroring solutions that reduce unplanned downtime in capital-intensive production lines.
- Azure Cloud Infrastructure Penetration:Provincial procurement frameworks increasingly specify cloud-native architectures, accelerating SaaS delivery models for mid-market industrial adopters.
Market Restraints
- Specialized Talent Scarcity:Industrial IoT systems engineers with physics modeling expertise command premium compensation, inflating implementation costs for complex deployments.
- Quebec Law 25 Compliance Burden:Provincial privacy legislation imposes data residency and consent management requirements that complicate cross-border cloud synchronization for national operators.
- Legacy OT System Entrenchment:Decades-old SCADA and PLC infrastructures in established manufacturing facilities resist API-based integration without expensive middleware layers.
Strategic Opportunities
- British Columbia Public-Sector Modernization:Provincial infrastructure agencies are piloting urban-scale digital twins for transportation and utilities coordination, creating reference architectures for municipal adoption.
- AI-Physics Model Convergence:Machine learning surrogate models are reducing computational load for real-time simulation, enabling edge deployment in bandwidth-constrained environments.
- Federal Critical Infrastructure Designation:Evolving cybersecurity frameworks for energy and water systems will mandate continuous monitoring architectures that favor twin-based anomaly detection.
Industry Challenges
- Interoperability Protocol Fragmentation:Competing IoT standards and vendor-specific data formats force costly custom integration work for multi-site deployments.
- Validation Documentation Burden:Health Canada GxP requirements demand extensive qualification evidence for software changes, slowing agile iteration cycles in regulated environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Digital Twin Market |
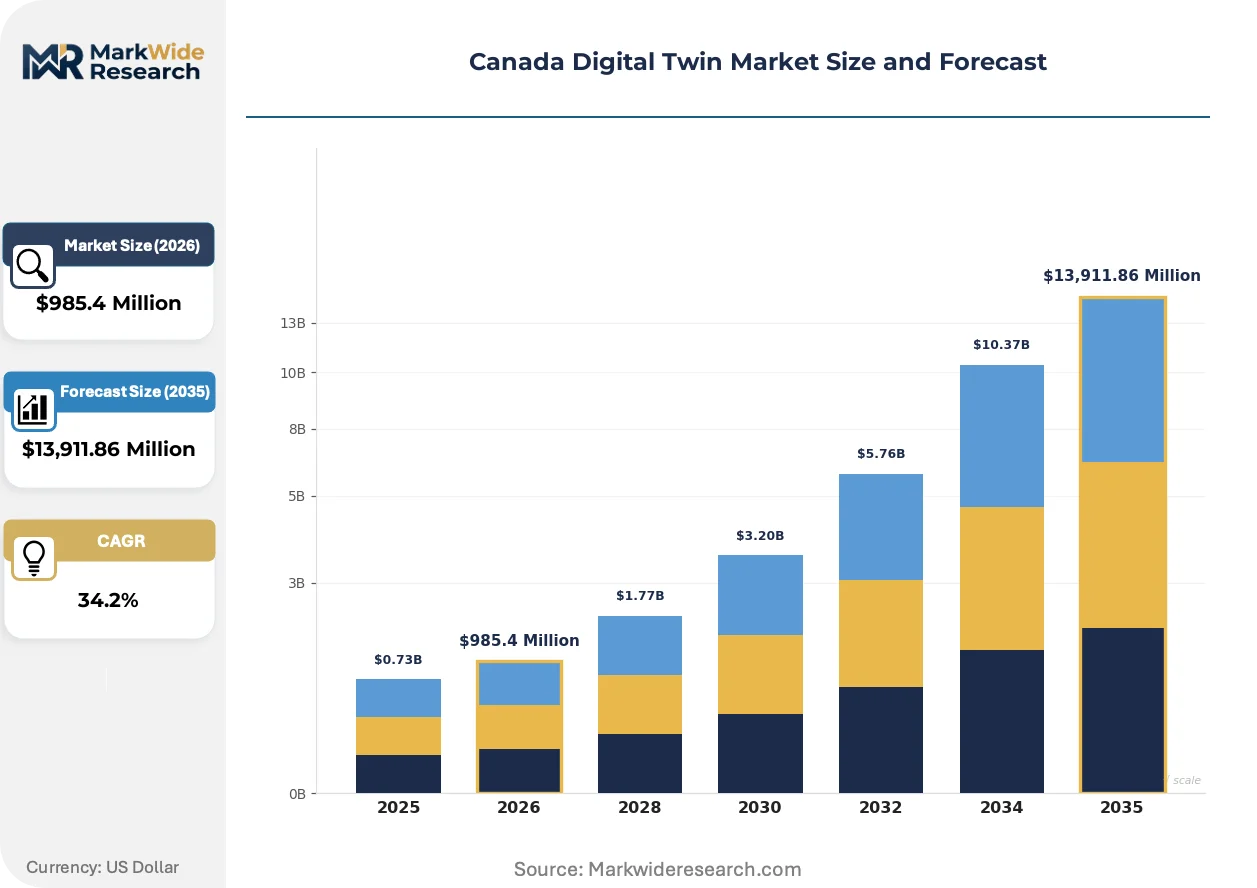
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $13,911.86 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Urban Planning, Healthcare, Energy Management Technology: AI, IoT, Big Data, AR End User: Aerospace, Construction, Automotive, Telecommunications Deployment: Cloud-based, On-premises, Hybrid, Edge Computing |
| Companies Covered | ThoughtWire, Verto Health, Luxolis Inc., Automate Canada, Arcadis Canada, SolidCAD, DCS Digital, Microsoft, Siemens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Digital Twin Market Trends and Innovations
Digital twin architectures are fragmenting between lightweight dashboarding tools and full-fidelity simulation stacks, with Canadian adopters prioritizing hybrid deployments that balance cloud scalability against data sovereignty constraints.
Physics engine software is modularizing into composable microservices that separate visualization, simulation, and data ingestion layers. Automotive suppliers in Ontario are adopting these architectures to swap simulation backends without rebuilding frontend interfaces. This decomposition is modularizing vendor lock-in risks and accelerating procurement cycles for specialized components.
Health Canada tightened validation guidance for computerized systems in GxP environments, requiring documented evidence of data integrity controls throughout digital twin lifecycles. Pharmaceutical contract manufacturers are responding by embedding automated audit trails and electronic signature workflows into their virtual facility models. The regulatory pressure is compressing vendor selection criteria toward platforms with pre-validated module libraries.
Asset-as-a-service contracting is displacing perpetual license purchases among capital-constrained municipal infrastructure operators. Water utilities in Alberta and Saskatchewan are procuring digital twin capabilities through operational expenditure models that tie vendor compensation to uptime outcomes. This payment restructuring is visible most acutely in provinces with constrained infrastructure budgets and aging treatment facilities.
Canada Digital Twin Market Segmentation
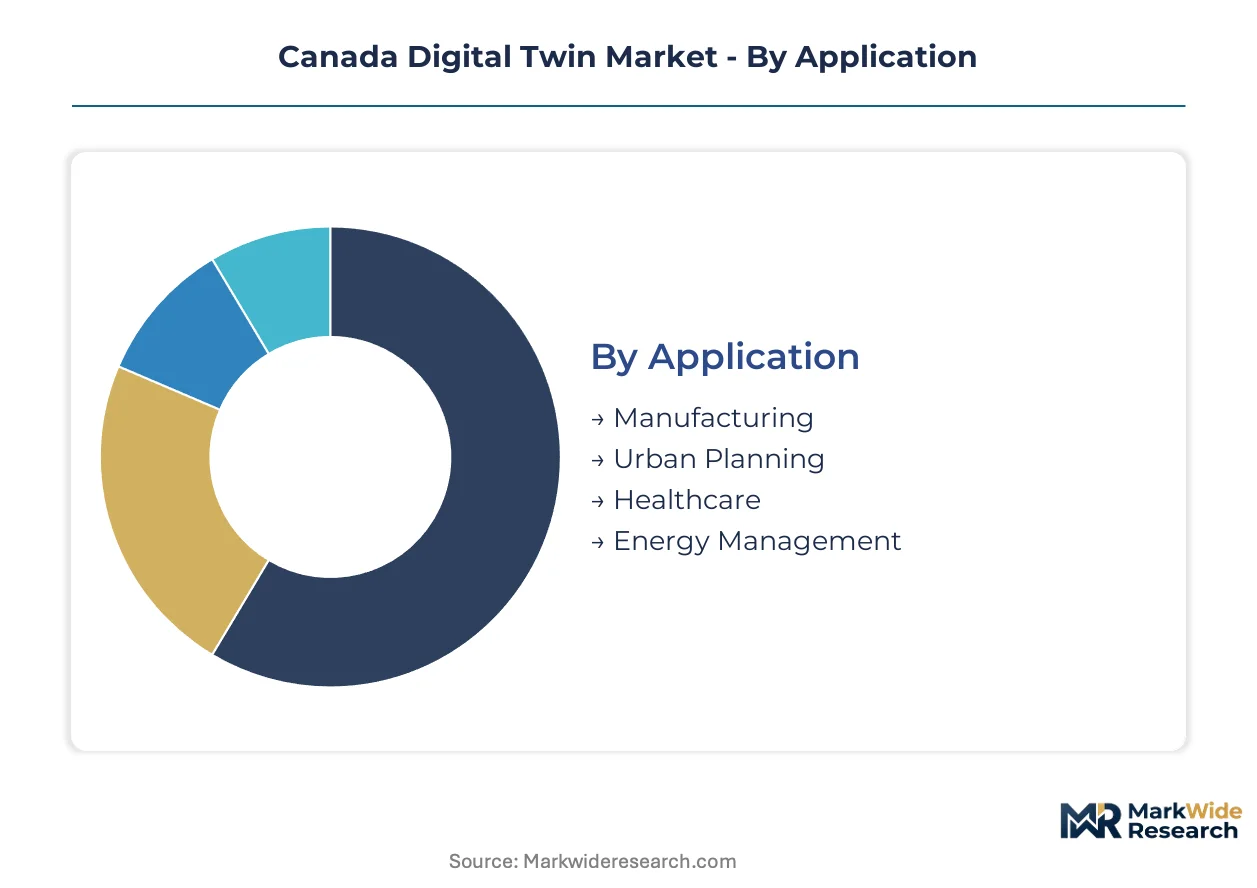
Segmentation reveals how digital twin architectures diverge across Canadian industrial contexts. Deployment patterns cluster around regulatory pressure points and legacy infrastructure constraints. Technology choices reflect the tension between cloud scalability and data sovereignty requirements.
Application:
Supply concentration in Ontario manufacturing clusters shapes deployment scale across application categories.
- Manufacturing:Real-time asset mirroring integrates with SCADA and PLC systems to simulate production line behavior. Automotive and aerospace facilities in the Toronto-Waterloo corridor deploy these systems to compress unplanned downtime intervals. Health Canada traceability mandates force pharmaceutical manufacturers to validate batch genealogy through twin architectures.
- Healthcare:Hospital system modeling synchronizes patient flow, equipment utilization, and facility energy loads. British Columbia and Ontario health authorities pilot these implementations for emergency department optimization. ThoughtWire anchors specialized deployments in these provinces.
- Urban Planning:Municipal infrastructure coordination requires geospatial layering with utility and transportation networks. British Columbia provincial agencies pilot reference architectures for transportation-utility coordination.
- Energy Management:Grid and facility-level optimization models integrate renewable intermittency with demand response protocols. Alberta utilities leverage these for aging treatment facility modernization.
Manufacturing absorbs the bulk of installed capacity; healthcare is expanding most quickly.
Technology:
Cost tier differentiation separates enterprise physics engines from commodity dashboarding tools.
- AI:Machine learning surrogate models reduce computational load for real-time simulation. Edge deployment in bandwidth-constrained environments accelerates adoption across remote industrial sites.
- IoT:Sensor connectivity protocols synchronize physical-virtual state changes through API architectures. Manufacturing facilities prioritize MQTT and OPC-UA integration for legacy equipment retrofit.
- Big Data:Data lake architectures ingest historical performance records for predictive model training. Pharmaceutical manufacturers embed automated audit trails to satisfy Health Canada validation requirements.
- AR:Spatial computing overlays visualize twin outputs for field technician guidance. Maintenance applications in aerospace and energy verticals drive pilot deployments.
IoT anchors current infrastructure investment; AI is climbing the fastest.
End User:
Customer type determines procurement complexity and validation burden intensity.
- Automotive:Production line digital twins simulate welding, painting, and assembly sequences. Ontario suppliers adopt modular microservices to swap simulation backends without frontend rebuilds.
- Aerospace:MRO and manufacturing applications require AS9100-aligned validation protocols. Precision component tracking demands high-fidelity physics modeling.
- Construction:Building information modeling integration supports project lifecycle coordination. Infrastructure operators in British Columbia pilot urban-scale implementations.
- Telecommunications:Network infrastructure twins model 5G deployment density and fiber optic routing. Federal critical infrastructure designation rules shape security architecture requirements.
Automotive absorbs the bulk of installed capacity; telecommunications is gaining share fastest.
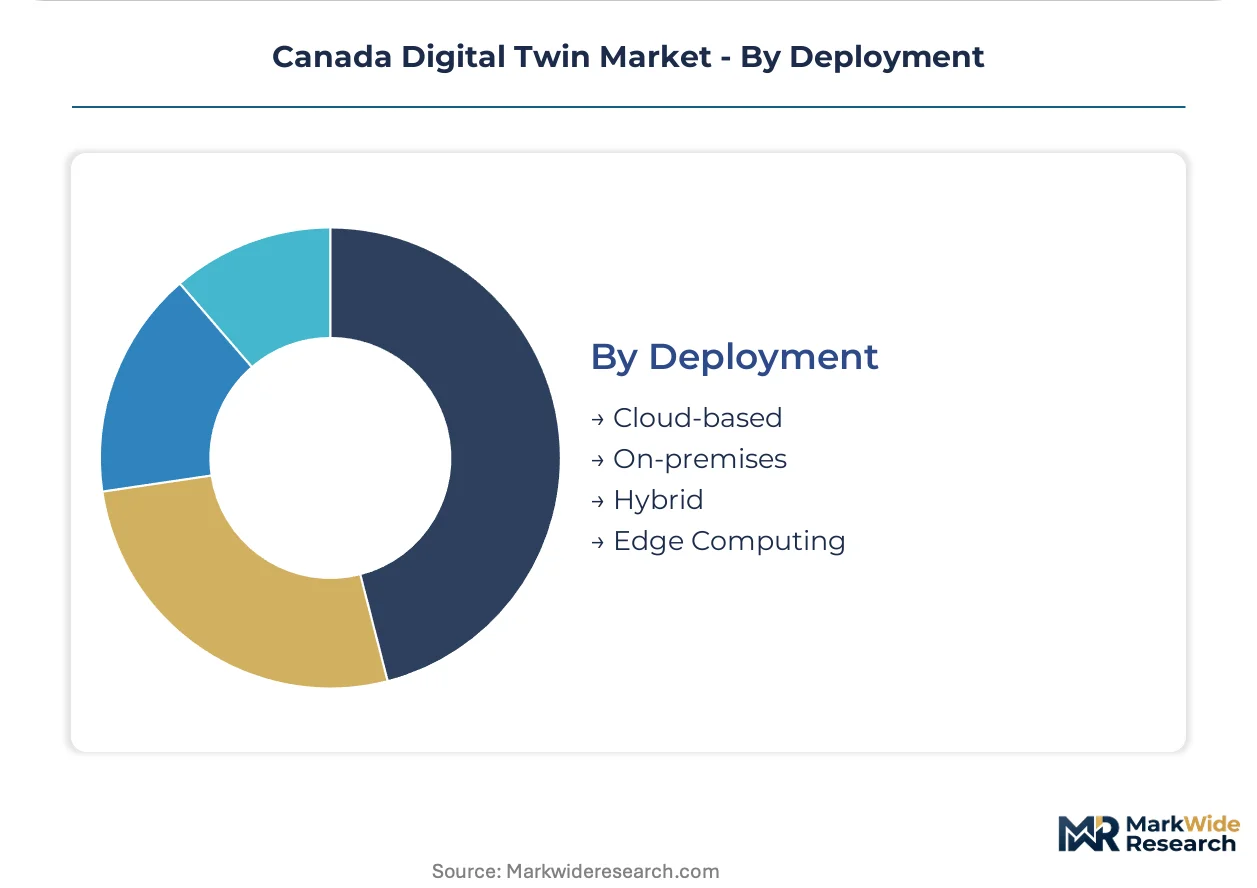
Deployment:
Margin concentration varies with data residency constraints and sovereignty requirements.
- Cloud-based:Provincial procurement frameworks increasingly specify cloud-native architectures. Azure penetration accelerates SaaS delivery for mid-market industrial adopters.
- Hybrid:Split architectures retain sensitive simulation workloads on-premises while leveraging cloud visualization. Quebec Law 25 compliance drives this configuration for cross-border operators.
- On-premises:Defense and critical infrastructure contexts restrict full off-premise migration. Data sovereignty requirements sustain margin concentration in these deployments.
- Edge Computing:Localized processing reduces latency for real-time control loops. Bandwidth-constrained environments in remote resource extraction sites prioritize this architecture.
Cloud-based deployments dominate new implementations; edge computing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Toronto-Waterloo technology corridor anchors Canadian digital twin deployment, concentrating software development talent and industrial pilot programs in Ontario's manufacturing heartland.
Ontario
Automotive and aerospace clusters around Toronto-Waterloo generate concentrated demand for asset mirroring solutions that compress unplanned downtime. Health Canada traceability mandates force pharmaceutical manufacturers in Mississauga and Hamilton to validate batch genealogy through twin architectures. Siemens and Microsoft maintain deep integration partnerships with Tier-1 suppliers throughout the Golden Horseshoe.
Quebec
Provincial privacy legislation imposes data residency requirements that complicate cross-border cloud synchronization for national operators. Law 25 compliance drives hybrid deployment configurations among Montreal-based pharmaceutical contract manufacturers. The province's aerospace supply chain in Longueuil and Mirabel pilots modular microservices for MRO applications.
British Columbia
Provincial infrastructure agencies pilot urban-scale digital twins for transportation-utility coordination in Metro Vancouver. ThoughtWire anchors specialized hospital system modeling deployments for health authorities in Victoria and Vancouver. Municipal procurement frameworks specify cloud-native architectures for mid-market adopters.
Alberta
Water utilities procure digital twin capabilities through operational expenditure models tied to uptime outcomes. Aging treatment facilities in Calgary and Edmonton drive asset-as-a-service contracting for capital-constrained operators. Energy sector applications concentrate on grid optimization models integrating renewable intermittency.
Atlantic Canada
Federal critical infrastructure designation rules shape security architecture requirements for Halifax telecommunications and port logistics operators. Provincial procurement mandates accelerate SaaS delivery models for mid-market industrial adopters in New Brunswick manufacturing corridors. Defence and marine applications sustain margin concentration in on-premises deployments.
Canada Digital Twin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment complexity and validation depth. The vendor base stratifies between enterprise-grade platforms with full physics-based simulation and lightweight dashboarding tools. Three archetypes dominate: cloud hyperscalers extending infrastructure dominance, industrial automation incumbents leveraging manufacturing heritage, and vertical specialists anchoring regulated industry deployments. Competitive moves concentrate on strategic partnerships for regulatory pre-validation and modular microservices decomposition to reduce vendor lock-in.
Within the vertical specialist tier, ThoughtWire exemplifies healthcare-focused deployment archetypes, while Verto Health occupies a position among clinical workflow optimization providers. Among global technology platforms, Microsoft represents cloud-native infrastructure extension strategies, and Siemens anchors industrial automation heritage across automotive and energy verticals. These named entities sit within broader competitive dynamics where regulatory compliance capabilities determine procurement outcomes more than raw technology specifications.
| Leading Market Players |
|---|
| ThoughtWire |
| Verto Health |
| Luxolis Inc. |
| Automate Canada |
| Arcadis Canada |
| SolidCAD |
| DCS Digital |
| Microsoft |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration into cloud hyperscaler partnerships anchors supply positioning and pricing power for Canadian digital twin vendors. Microsoft Azure's infrastructure dominance compresses compute costs for SaaS delivery while Health Canada validation requirements sustain premium pricing for GxP-compliant modules.
Pricing Analysis
Value-based pricing tied to uptime outcomes anchors municipal infrastructure contracts in Alberta and Saskatchewan water utilities. Three-tier pricing structure across premium physics-engine, standard IoT-dashboard, and economy SaaS levels differentiates by validation depth and integration complexity. Pricing pressure stems from mid-market manufacturers demanding commodity dashboarding tools over full-fidelity simulation. Pharmaceutical and aerospace buyers show lowest price sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for GPU and edge-computing hardware essential to real-time simulation workloads. Cloud infrastructure draws from US hyperscaler data centers, while IoT sensor manufacturing rests on China and Vietnam for cost-optimized components. Tariff exposure on Chinese electronics intensifies margin pressure for hardware-dependent deployments. Distribution runs through systems integrators and OEM channel partners with manufacturing automation heritage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian digital twin adoption sits in a technology-transition phase as AI-physics surrogate models displace legacy computational fluid dynamics engines. Machine learning compression of simulation workloads is rewriting deployment economics across bandwidth-constrained industrial sites.
For Market Incumbents: Deepen vertical integration into pre-validated module libraries for Health Canada GxP environments. Threat from cloud-native entrants with modular microservices architectures demands defensive certification investments. Prioritize backward integration into edge hardware distribution to capture margin concentration in Quebec Law 25 hybrid deployments.
For New Entrants and Emerging Players: The mid-market price-point gap between Siemens enterprise platforms and commodity SaaS dashboarding tools creates white-space opportunity. Target Ontario automotive suppliers seeking modular simulation backends without frontend rebuild costs. Lead with asset-as-a-service contracting to displace perpetual license incumbents in capital-constrained municipal utilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertical-specialist acquisition by cloud hyperscalers seeking regulated-industry credibility. Long-term viability favors vendors with embedded governance tooling for provincial privacy legislation compliance. Watch Health Canada critical infrastructure designation rules as inflection signal for defense and energy sector demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Digital Twins partnerships with ThoughtWire accelerate hospital system modeling in British Columbia and Ontario health authorities. |
| Acquisition of Specialist Firm | Industrial automation incumbents acquire healthcare-focused deployers to capture Health Canada validation expertise and pre-built GxP modules. |
| Strategic Partnership | Systems integrators partner with municipal infrastructure agencies to pilot urban-scale twins for transportation-utility coordination in Metro Vancouver. |
| Geographic Expansion | Cloud-native vendors expand Quebec presence with Law 25-compliant hybrid architectures for Montreal pharmaceutical contract manufacturers. |
| Product Launch | Edge-deployed AI surrogate models launch for bandwidth-constrained resource extraction sites in Alberta and Saskatchewan. |
Research Methodology
Document review covered Health Canada GxP guidance documents, PMRA traceability mandates, and provincial procurement frameworks, complemented by interviews with plant engineers at Ontario automotive facilities, biomedical engineers in British Columbia health authorities, and regulatory affairs leads at pharmaceutical contract manufacturers. Secondary validation drew from Azure infrastructure penetration disclosures, Siemens industrial automation segment reports, and municipal infrastructure budget allocations. Bottom-up deployment estimates triangulated against top-down market sizing across the analysis window.
Cross-referencing historical adoption curves with expert panel input shaped the analytical framework across technology, application, and deployment model dimensions. CAGRs derived from fitted growth curves incorporating IoT sensor installation rates, cloud infrastructure expansion, and regulatory mandate enforcement timelines. Industry-specific inputs included Health Canada inspection readiness requirements and Quebec Law 25 compliance cost estimates.
Underlying measurement precision varies by segment; manufacturing deployment counts carry tighter precision than emerging healthcare pilots. Forecasts reflect assumptions about regulatory enforcement intensity and cloud infrastructure subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Global Product Lifecycle Management Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Global Digital Assurance Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Warranty Management System Market