
 Global Organizational Change Management Software Market | 2026-2036
Global Organizational Change Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organizational Change Management Software Market Foresight
Platform licensing revenue is reconfiguring margin pools away from perpetual on-premise deployments toward recurring SaaS arrangements. ServiceNow leverages its IT workflow heritage to anchor enterprise-scale change orchestration across Fortune 500 accounts. Whatfix competes through embedded adoption analytics that map software usage to transformation outcomes. WalkMe sustains differentiation via its digital adoption platform architecture, which overlays guidance across heterogeneous application stacks without native integration dependencies.
Organizational change management software encompasses cloud-deployed, on-premise, and hybrid systems that apply structured methodologies—stakeholder analysis, impact assessment, resistance management, and training orchestration—to guide workforce transitions during operational transformations. These platforms integrate communication workflows, learning delivery, and progress telemetry to reduce productivity loss during mergers, digital overhauls, and regulatory-driven restructuring. Cloud-based and SaaS deployment modes now command the dominant share of new bookings, while hybrid configurations retain traction among financial services and healthcare providers with segmented data sovereignty requirements. The solution offering dimension shows communication management and training management modules generating the strongest attach rates, whereas resistance management tools remain underpenetrated outside North American and Western European buyer bases.
The EU AI Act and GDPR impose documentation and audit-trail mandates that elevate demand for change governance platforms with embedded compliance logging. The US SEC climate disclosure rules and OSHA change management guidelines for process safety similarly shape product requirements across regulated industries. Stakeholders must monitor how generative AI integration into enterprise software accelerates the cadence of workforce reskilling cycles and whether vendor roadmaps incorporate native AI copilot support for change practitioner workflows.
Market Dynamics
The convergence of generative AI deployment with workforce reskilling mandates is compressing implementation timelines and forcing platform vendors to embed real-time adaptation capabilities into change orchestration workflows.
Growth Catalysts
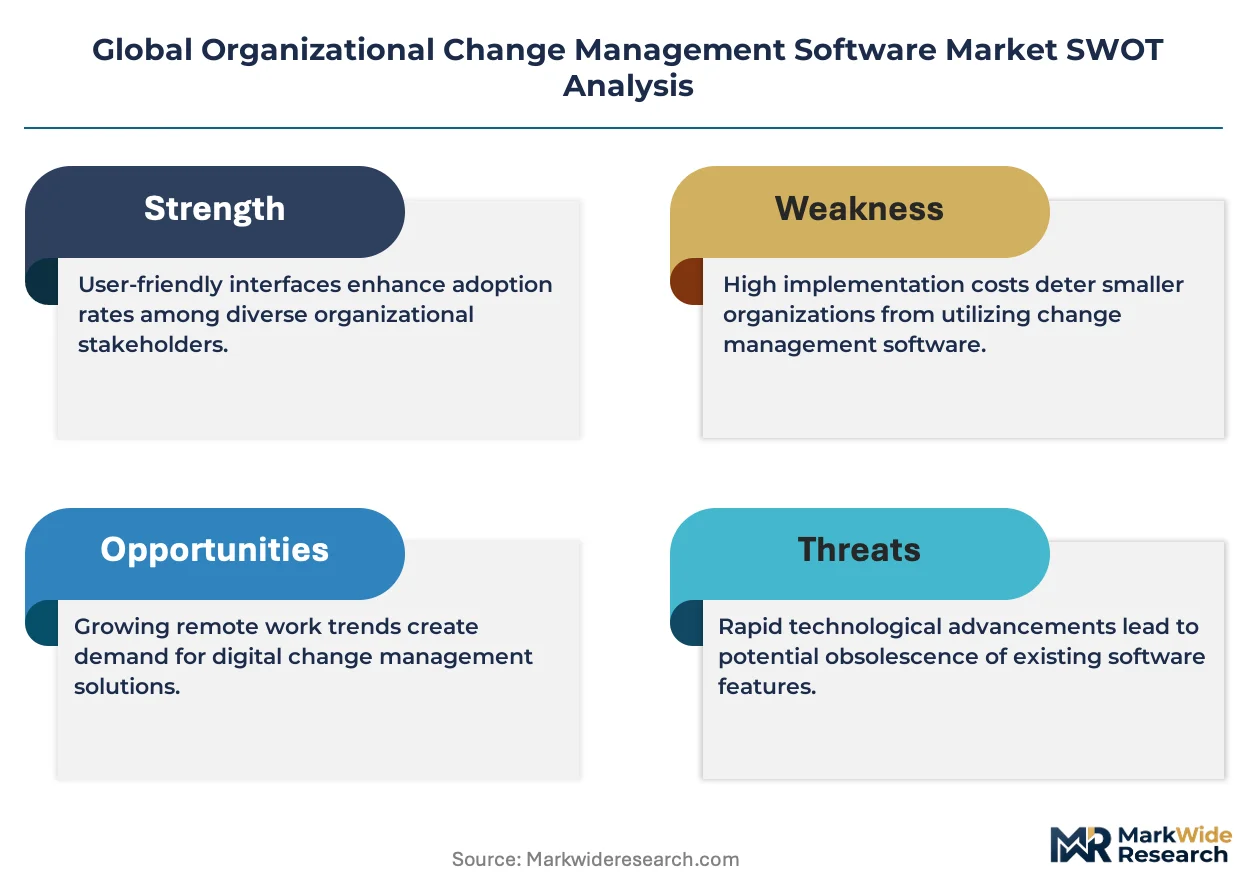
- EU AI Act Documentation Mandates:European enterprises must maintain audit trails for algorithmic decision systems, elevating demand for change governance platforms with embedded compliance logging and automated documentation workflows.
- Healthcare Digital Transformation:Hospital systems and pharmaceutical manufacturers are deploying structured change methodologies to manage electronic health record migrations and AI-assisted diagnostic tool rollouts.
- Cloud-Native SaaS Migration:Enterprise IT departments are replacing perpetual on-premise licenses with subscription-based deployment models that require continuous workforce enablement rather than one-time training events.
Market Restraints
- Data Sovereignty Segmentation:Financial services and healthcare providers in Germany, Switzerland, and France maintain hybrid infrastructure requirements that complicate vendor cloud migration roadmaps and extend sales cycles.
- Integration Technical Debt:Legacy ERP systems from the 1990s and 2000s lack API-native architectures, forcing expensive middleware development for change management platform connectivity.
- Specialized Talent Scarcity:The shortage of certified change management practitioners with both behavioral science credentials and enterprise software implementation experience limits deployment velocity.
Strategic Opportunities
- India Enterprise Expansion:Domestic conglomerates and multinational shared service centers in Bangalore, Mumbai, and Hyderabad are investing in change platforms to manage AI-driven operational restructuring and regulatory compliance.
- Resistance Management Module Penetration:Behavioral analytics tools for identifying and mitigating workforce opposition remain underdeployed outside North American and Western European buyer bases, creating expansion runway.
- Native AI Copilot Integration:Embedding generative AI assistants directly into practitioner workflows for stakeholder mapping, communication drafting, and impact assessment represents unclaimed product differentiation territory.
Industry Challenges
- Cross-Functional Coordination Complexity:Change initiatives require synchronized execution across HR, IT, operations, and legal departments with conflicting priorities and misaligned incentive structures.
- Measurement Attribution Gaps:Quantifying productivity recovery timelines and ROI from change management investments remains methodologically contested, complicating procurement justification.
- Generative AI Reskilling Velocity:The cadence of workforce adaptation cycles is accelerating beyond traditional change methodology frameworks, straining platform configuration capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organizational Change Management Software Market |
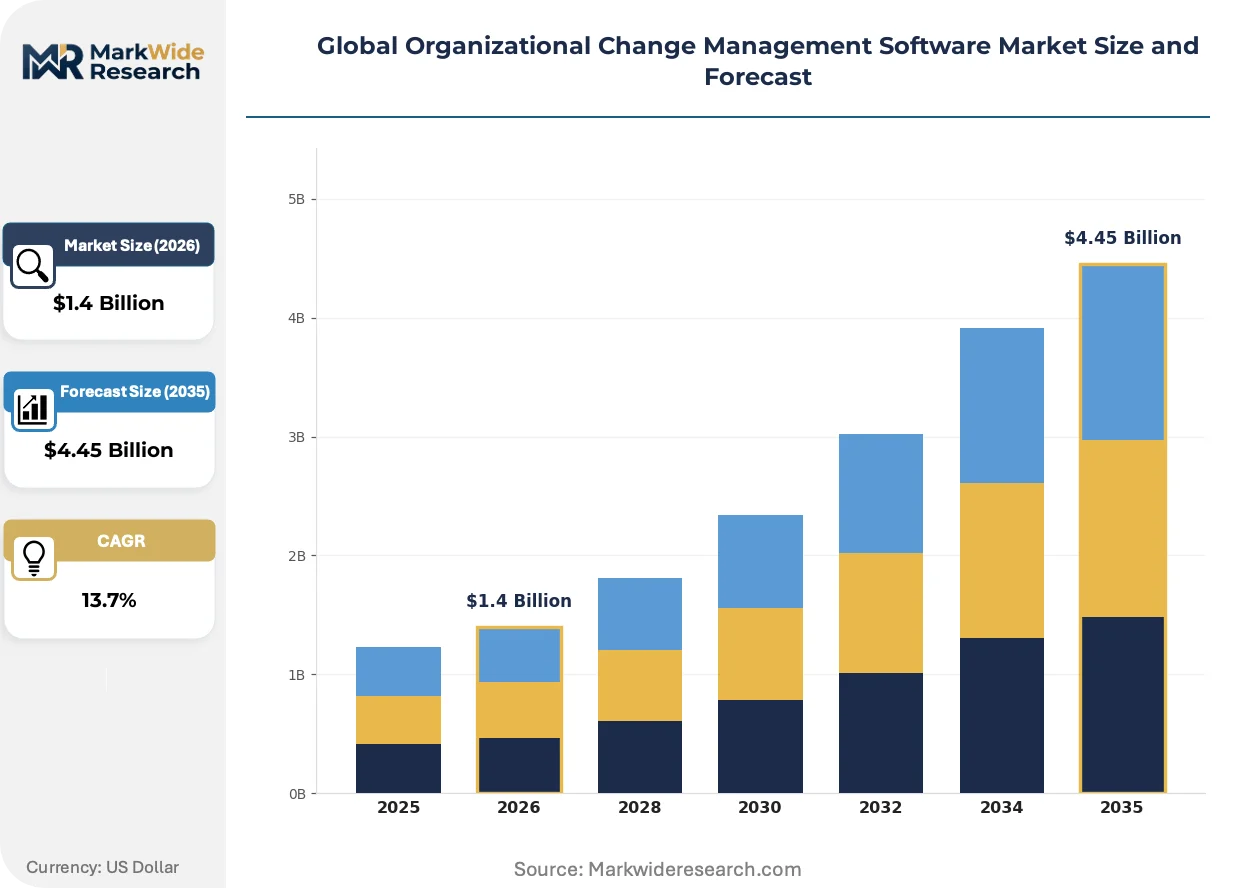
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Offering: Communication Management, Training Management, Stakeholder Analysis, Impact Assessment, Resistance Management Use Case: Mergers & Acquisitions, Business Process Reengineering, Digital Transformation, Cultural Change, Regulatory Compliance End User: Financial Services, Manufacturing Firms, IT & Software Companies, Healthcare Providers, Educational Institutions |
| Companies Covered | ServiceNow, WalkMe, Whatfix, Prosci Suite, OCM Solution, The Change Compass, BMC Helix, Canfigure, AssurX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organizational Change Management Software Market Shifts & Advancements
Generative AI integration is fundamentally altering how change practitioners design stakeholder interventions, compressing content development cycles and enabling personalized communication at scale previously requiring manual customization.
Embedded adoption analytics is hybridizing traditional change management platforms with real-time software usage telemetry. Healthcare providers and financial institutions in the United States are deploying these converged systems to correlate training completion with actual application proficiency. The structural consequence is a shift from activity-based metrics to outcome-based accountability in vendor-client relationships.
The EU AI Act and GDPR documentation requirements are mandating embedded compliance logging within change governance workflows. European enterprises must demonstrate traceable decision pathways for workforce restructuring and algorithmic tool deployment. Healthcare systems in Germany and France are responding by prioritizing vendors with pre-configured audit trail modules over generalist platforms.
Buyer procurement patterns are fragmenting as mid-market enterprises bypass traditional RFP processes in favor of self-service product-led growth trials. Direct platform experimentation through freemium tiers is displacing consultant-mediated vendor selection in technology and professional services sectors. This behavioral shift is most pronounced in India and the United States, where IT decision-makers prioritize immediate usability validation over lengthy procurement cycles.
Global Organizational Change Management Software Market Segmentation
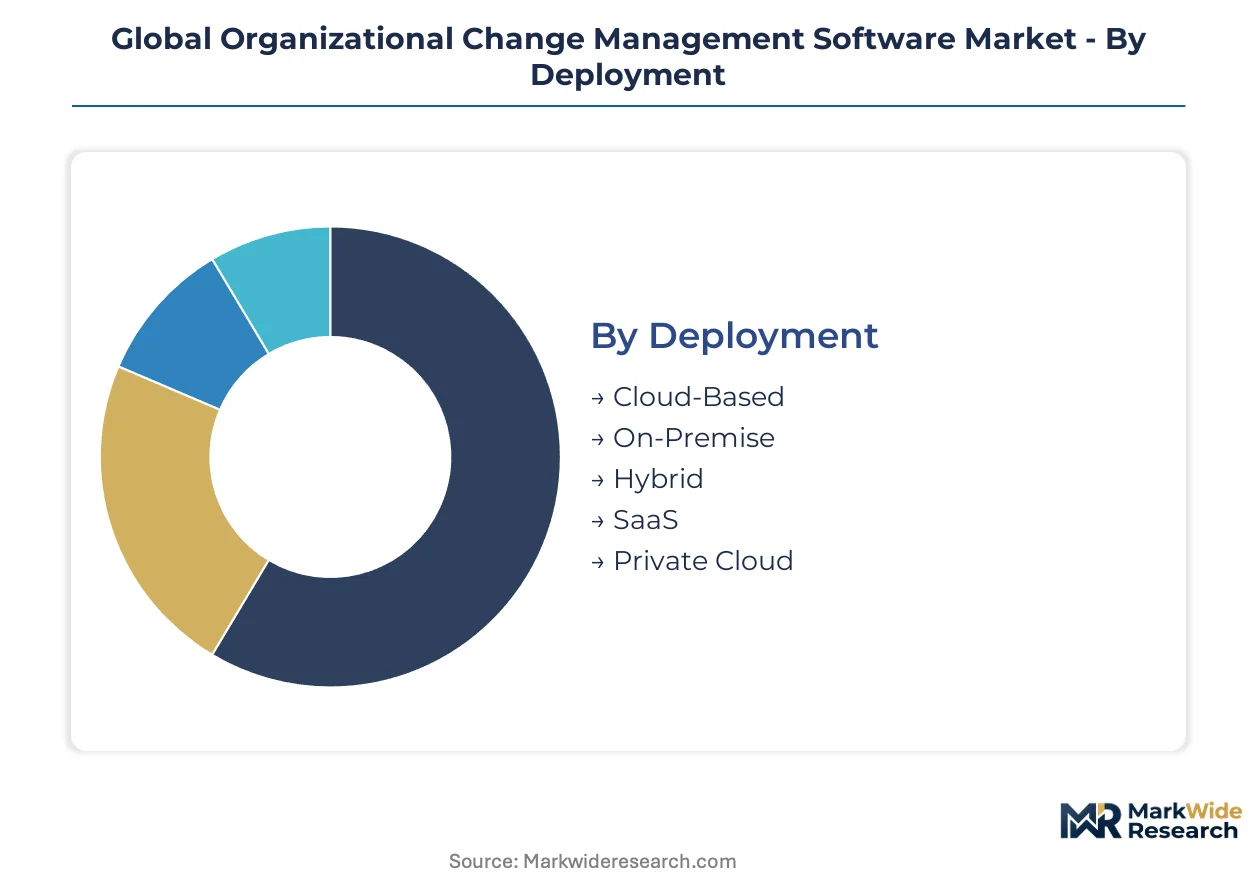
Segmentation in organizational change management software reveals how deployment architectures, functional modules, and industry-specific use cases create distinct competitive battlegrounds. Vendors must align product roadmaps with the operational realities of regulated industries and the technical constraints of legacy infrastructure.
Deployment:
Mature cloud architectures now dominate new bookings while hybrid configurations persist in sectors with stringent data sovereignty requirements.
- Cloud-Based:Multi-tenant architectures enable rapid provisioning and automatic feature updates without client-side infrastructure maintenance. Healthcare providers in the United States and Germany are concentrating demand here, driven by HIPAA and GDPR compliance requirements that favor vendor-managed security certifications.
- SaaS:Subscription billing models align vendor incentives with continuous customer success rather than one-time license transactions. Financial services firms in India and the United States favor this mode for its operational expenditure treatment and rapid scaling capabilities during merger integration periods.
- On-Premise:Perpetual licenses retained by defense contractors and classified government facilities with air-gapped network requirements.
- Hybrid:Split configurations serving German and Swiss financial institutions subject to BaFin and FINMA data localization mandates.
- Private Cloud:Single-tenant deployments isolating pharmaceutical manufacturers' clinical trial data from co-tenant exposure risks.
Cloud-Based retains volume leadership; SaaS holds the steepest expansion curve.
Solution Offering:
Functional module attach rates vary sharply by buyer sophistication, with advanced analytics capabilities commanding premium pricing in North American and Western European accounts.
- Communication Management:Workflow engines orchestrating targeted messaging across email, mobile, and collaboration platforms during transformation programs. Manufacturing firms in Germany deploy these modules to coordinate shop-floor announcements during operational restructuring.
- Training Management:Learning delivery systems tracking certification completion and competency validation against role-specific requirements. Healthcare providers in the United States prioritize this functionality for Joint Commission accreditation maintenance during EHR system migrations.
- Stakeholder Analysis:Mapping tools identifying influence networks and resistance vectors within organizational hierarchies.
- Impact Assessment:Quantification engines estimating productivity disruption and recovery timelines for proposed operational changes.
- Resistance Management:Behavioral analytics platforms detecting workforce opposition patterns through sentiment analysis and engagement telemetry. This segment remains underpenetrated outside North American and Western European buyer bases despite its criticality in transformation success.
Communication Management commands the broadest install base; Resistance Management offers the largest untapped expansion runway.
Use Case:
Application intensity correlates with regulatory pressure and competitive disruption velocity, creating divergent implementation complexity profiles.
- Digital Transformation:Comprehensive programs replacing legacy operational models with AI-enabled workflows and cloud-native architectures. IT and software companies in India and the United States are deploying structured methodologies here to manage workforce reskilling at scale.
- Regulatory Compliance:Structured responses to EU AI Act documentation mandates, SEC climate disclosure rules, and OSHA process safety guidelines. European enterprises must demonstrate traceable decision pathways for algorithmic tool deployment and workforce restructuring.
- Mergers & Acquisitions:Integration playbooks harmonizing disparate cultures, systems, and processes during corporate combinations.
- Business Process Reengineering:Radical operational redesign initiatives targeting cost structure transformation.
- Cultural Change:Long-term behavioral modification programs addressing organizational values and collaboration norms.
Digital Transformation absorbs the largest implementation investment; Regulatory Compliance is climbing fastest as enforcement deadlines approach.
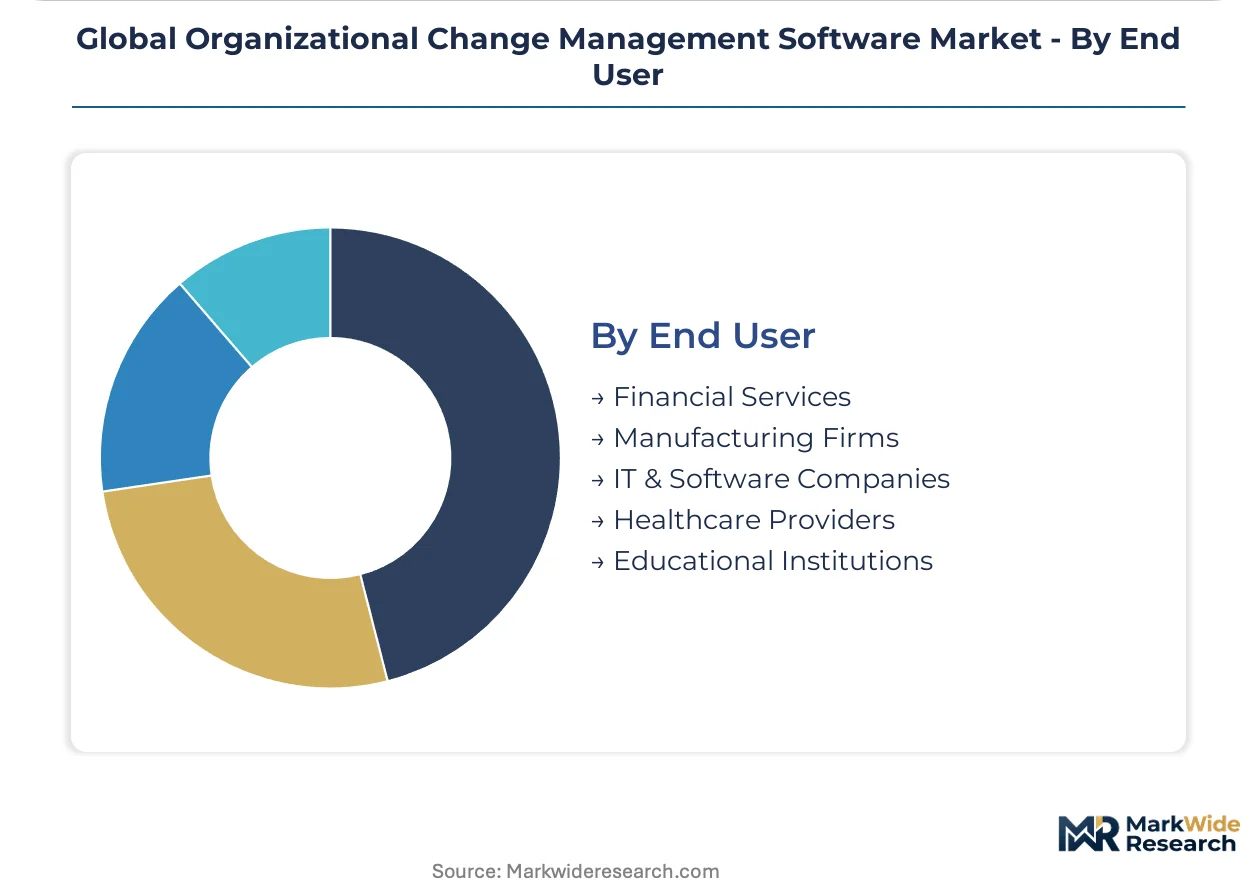
End User:
Industry-specific procurement patterns reflect divergent risk tolerances, regulatory exposure, and workforce composition characteristics.
- Healthcare Providers:Hospital systems and pharmaceutical manufacturers managing electronic health record migrations, AI-assisted diagnostic rollouts, and FDA validation requirements. German and French healthcare systems prioritize vendors with pre-configured audit trail modules.
- Financial Services:Banks, insurers, and asset managers navigating SEC climate disclosure rules, GDPR compliance, and algorithmic trading system governance. Swiss and German institutions maintain hybrid infrastructure requirements complicating vendor cloud migration roadmaps.
- Manufacturing Firms:Industrial conglomerates coordinating operational restructuring across distributed production facilities.
- IT & Software Companies:Technology vendors managing their own workforce adaptation to generative AI integration and agile methodology scaling.
- Educational Institutions:Universities and training organizations deploying change methodologies for curriculum transformation and administrative modernization.
Healthcare Providers lead current procurement volume; Financial Services is gaining share fastest as regulatory deadlines compress implementation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States buyers prioritize real-time adoption analytics, while European procurement emphasizes audit-trail compliance, and Indian demand concentrates on workforce reskilling at scale for AI integration.
United States
Healthcare systems and financial services firms drive platform adoption for electronic health record migrations and SEC climate disclosure compliance. HIPAA and OSHA guidelines shape vendor selection criteria. Hospital networks in Boston and San Francisco deploy change orchestration tools to manage Joint Commission accreditation during digital transformation.
Germany
Industrial conglomerates and automotive manufacturers anchor European demand for structured change methodologies during operational restructuring. BaFin data localization mandates and EU AI Act documentation requirements elevate hybrid deployment preferences. Manufacturing clusters in Bavaria and Baden-Württemberg coordinate shop-floor transformation across distributed production facilities.
India
Domestic conglomerates and multinational shared service centers invest in change platforms for AI-driven operational restructuring. RBI guidelines on digital banking transformation and SEBI disclosure mandates accelerate procurement timelines. Technology corridors in Bangalore, Mumbai, and Hyderabad concentrate implementation activity for workforce reskilling programs.
United Kingdom
Financial services and professional services sectors lead adoption for merger integration and regulatory compliance workflows. GDPR documentation requirements and FCA operational resilience rules shape product specifications. London-based asset managers and insurers prioritize vendors with embedded compliance logging for algorithmic system governance.
France
Healthcare providers and pharmaceutical manufacturers navigate CNIL data protection mandates and EU AI Act enforcement deadlines. ANSM validation requirements for clinical systems elevate demand for pre-configured audit trail modules. Hospital systems in Paris and Lyon prioritize change governance platforms with traceable decision pathways for workforce restructuring.
Global Organizational Change Management Software Market Competitive Landscape
Capability concentration sits with specialized digital adoption platforms; scale advantage sits with enterprise workflow incumbents. The market structures around three tiers: IT heritage platforms with cross-functional workflow integration, standalone adoption specialists with embedded analytics, and emerging challengers with AI-native architectures. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio expansion into adjacent workforce enablement categories.
Within the IT heritage tier, ServiceNow leverages its workflow automation foundation to anchor enterprise-scale change orchestration. Among specialized adoption platforms, WalkMe and Whatfix exemplify the embedded analytics archetype, mapping software usage telemetry to transformation outcomes without requiring native integration dependencies. These three companies represent the primary competitive vectors shaping procurement patterns across Fortune 500 accounts and mid-market enterprises.
| Leading Market Players |
|---|
| ServiceNow |
| WalkMe |
| Whatfix |
| Prosci Suite |
| OCM Solution |
| The Change Compass |
| BMC Helix |
| Canfigure |
| AssurX |
| Others |
Supply & Pricing Matrix
Transatlantic fiber-optic cable routes linking Frankfurt to Mumbai carry the data traffic that underpins SaaS delivery economics, compressing latency costs for European-Indian hybrid deployments while amplifying price differentiation between cloud-native and on-premise tiers. This infrastructure geography concentrates vendor margin leverage in multi-tenant architectures and fragments pricing power across legacy integration dependencies.
Pricing Analysis
Long-term subscription offtakes dominate enterprise procurement, with three-year SaaS contracts anchoring vendor revenue predictability against quarterly renegotiation cycles. Pricing stratifies across enterprise, mid-market, and departmental tiers based on user-count thresholds and API integration depth. Cost compression in mid-market segments intensifies as Indian buyers negotiate volume discounts against US reference pricing. Healthcare providers exhibit lowest price sensitivity due to Joint Commission compliance requirements, while manufacturing firms in Germany drive hardest bargain terms.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize vendor financing arrangements with systems integrators, compressing working capital cycles for implementation partners. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure sourcing from AWS, Azure, and GCP data center regions. Dependency on third-party AI model APIs from OpenAI and Anthropic creates single-source vulnerability for generative AI copilot features. Distribution runs through direct enterprise sales teams supplemented by channel partners in regulated industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified change management practitioners with both behavioral science credentials and enterprise software implementation experience remain scarce across all major markets, constraining deployment velocity and elevating vendor delivery costs. This capability gap shapes competitive positioning and investment prioritization.
For Market Incumbents: Entrench workflow integration depth across IT service management platforms to defend against digital adoption specialists encroaching on core accounts. Invest in native AI copilot development for practitioner productivity rather than bolt-on partnerships. Capacity addition in Bangalore and Hyderabad addresses talent scarcity for implementation delivery. For New Entrants and Emerging Players: Build out resistance management module penetration in Asia-Pacific and Latin American markets where behavioral analytics remain underdeployed. Target mid-market enterprises in India bypassing traditional RFP processes through product-led growth freemium tiers. Channel partnerships with regional systems integrators accelerate trust-building in compliance-sensitive buyer segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified enterprise software conglomerates where change management modules represent non-core portfolio elements. Long-term viability hinges on AI-native architecture migration capability and vertical-specific compliance pre-configuration. Monitor EU AI Act enforcement deadline proximity as demand inflection signal for audit-trail-enabled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Native AI Copilot Integration | Embedding generative AI assistants into practitioner workflows differentiates vendor roadmaps for Fortune 500 procurement committees. |
| Vertical Compliance Pre-Configuration | Pre-built EU AI Act and GDPR audit trail modules accelerate European healthcare and financial services sales cycles. |
| Product-Led Growth Expansion | Freemium tier experimentation displaces consultant-mediated vendor selection in Indian and US mid-market segments. |
| Hybrid Deployment Architecture | Split cloud-on-premise configurations address BaFin and FINMA data localization mandates for German and Swiss institutions. |
| Resistance Management Module Development | Behavioral analytics for workforce opposition detection unlocks expansion runway outside North American and Western European bases. |
Research Methodology
Operator-level perspectives from change management practitioners, IT procurement officers, HR transformation leads, and systems integration partners anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU regulatory documentation, hyperscaler capex disclosures, and healthcare accreditation databases. Bottom-up deployment estimates triangulated against top-down market sizing across cloud, SaaS, hybrid, and on-premise architectures.
Scenario-bracketing around regulatory enforcement timelines and AI adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment mode, solution module type, use case intensity, and end-user industry vertical. CAGRs derived from installed base growth rates, pricing trajectory assumptions, and replacement cycle compression. Forecast inputs incorporated EU AI Act implementation phases and healthcare digital transformation budget allocations.
Practitioners should monitor generative AI reskilling cycle acceleration and compliance enforcement deadline proximity for early signals of demand inflection. Forecasts reflect documented assumptions regarding vendor consolidation patterns and cloud migration velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Lending Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Global AI Writing Assistant Software Market
Software & Services
Global Absence Management Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Software Consulting Market
Software & Services
OCR Scanning Software Market
Software & Services
Photo Editing Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Global Funeral Home Software Market
Software & Services
Performing Arts Software Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Smartphone Applications Market
Software & Services
Global Open Source Services Market
Software & Services
Sports League Management Software Market