
 Saudi Arabia Digital Twin Market | 2026-2036
Saudi Arabia Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Digital Twin Market Insights
Subscription-based software-defined feature layers is rebalancing how vendors monetize digital twin deployments across Saudi industrial clients. Siemens AG leverages its industrial automation heritage to anchor large-scale manufacturing implementations in Jubail Industrial City. PTC Inc. specializes in IoT-connected product lifecycle management for discrete manufacturing segments. Dassault Systèmes competes through deep 3D experience platform integration with aerospace and defense supply chains.
A digital twin constitutes a dynamic virtual replica of a physical asset, system, or process that ingests real-time sensor data and applies physics-based simulation models to mirror operational behavior, typically operating at sub-second latency thresholds for predictive control applications. Its primary commercial purpose centers on optimizing asset performance, reducing unplanned downtime, and accelerating design iteration cycles across capital-intensive industries. Software Solutions and IoT Platforms together command the dominant margin pool, with cloud-based deployment architectures expanding fastest as telecom infrastructure modernizes under the National Transformation Program. Smart Cities applications within the end-user dimension are attracting disproportionate capital allocation relative to current revenue contribution.
The Saudi Data and Artificial Intelligence Authority and the Communications, Space and Technology Commission jointly shape data sovereignty requirements and cross-border cloud governance for digital twin implementations. The National Cybersecurity Authority mandates encryption and access protocols that directly influence platform architecture decisions by foreign vendors. Stakeholders must monitor how NEOM's regulatory sandbox experiments with autonomous digital infrastructure governance may establish precedents for broader national standardization.
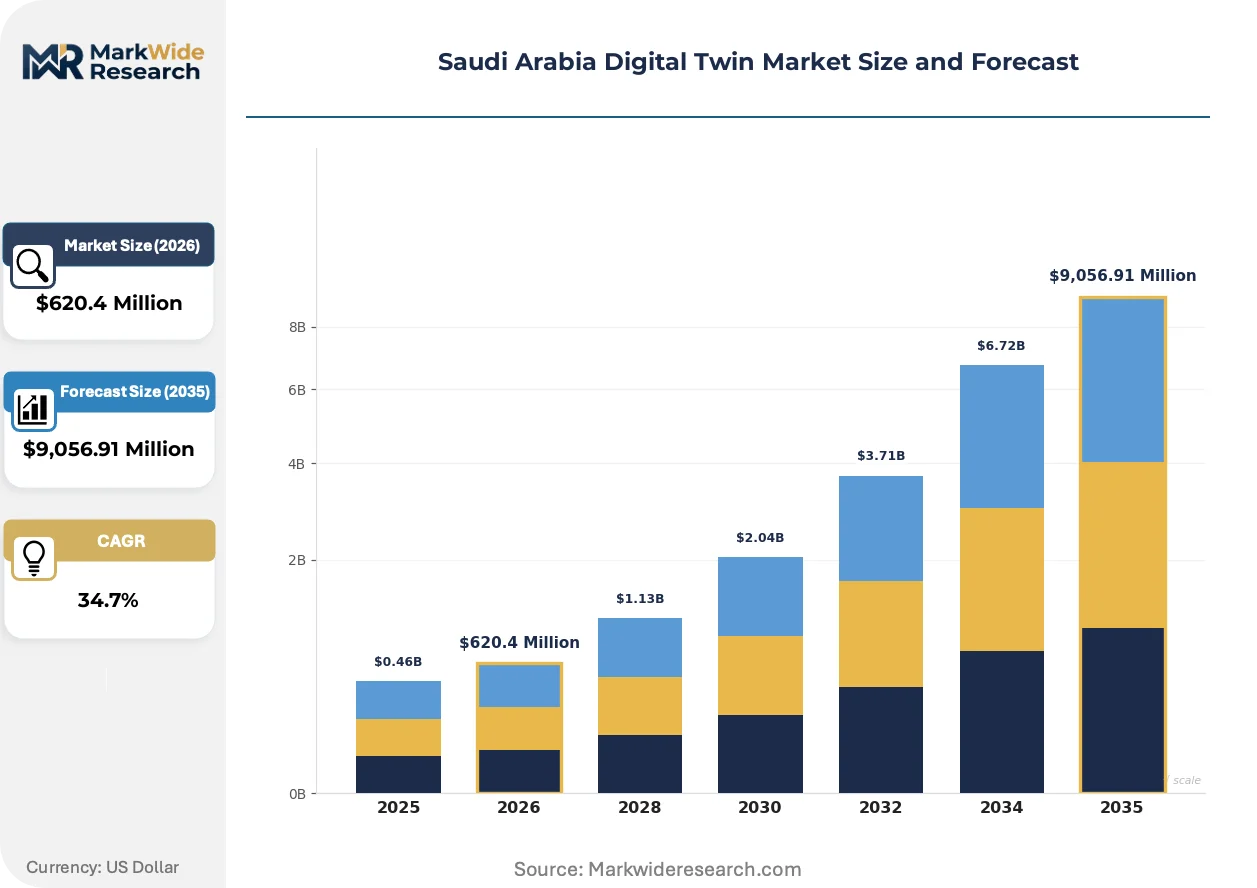
Market Dynamics
Subscription-based software-defined feature layers is rebalancing how vendors monetize digital twin deployments across Saudi industrial clients, compressing upfront licensing into recurring revenue streams that align vendor incentives with long-term operational outcomes.
Growth Catalysts
- NEOM's regulatory sandbox:Autonomous digital infrastructure governance experiments establish precedents for broader national standardization, reducing compliance friction for platform vendors entering the Kingdom.
- Smart cities capital allocation:Municipal infrastructure planning in Riyadh and NEOM accelerates adoption across urban water, transport, and energy networks, creating reference architectures for secondary cities.
- Aramco's operational digitalization:Real-time asset mirroring requirements across upstream and downstream facilities generate sustained demand for high-fidelity physics-based simulation models.
Market Restraints
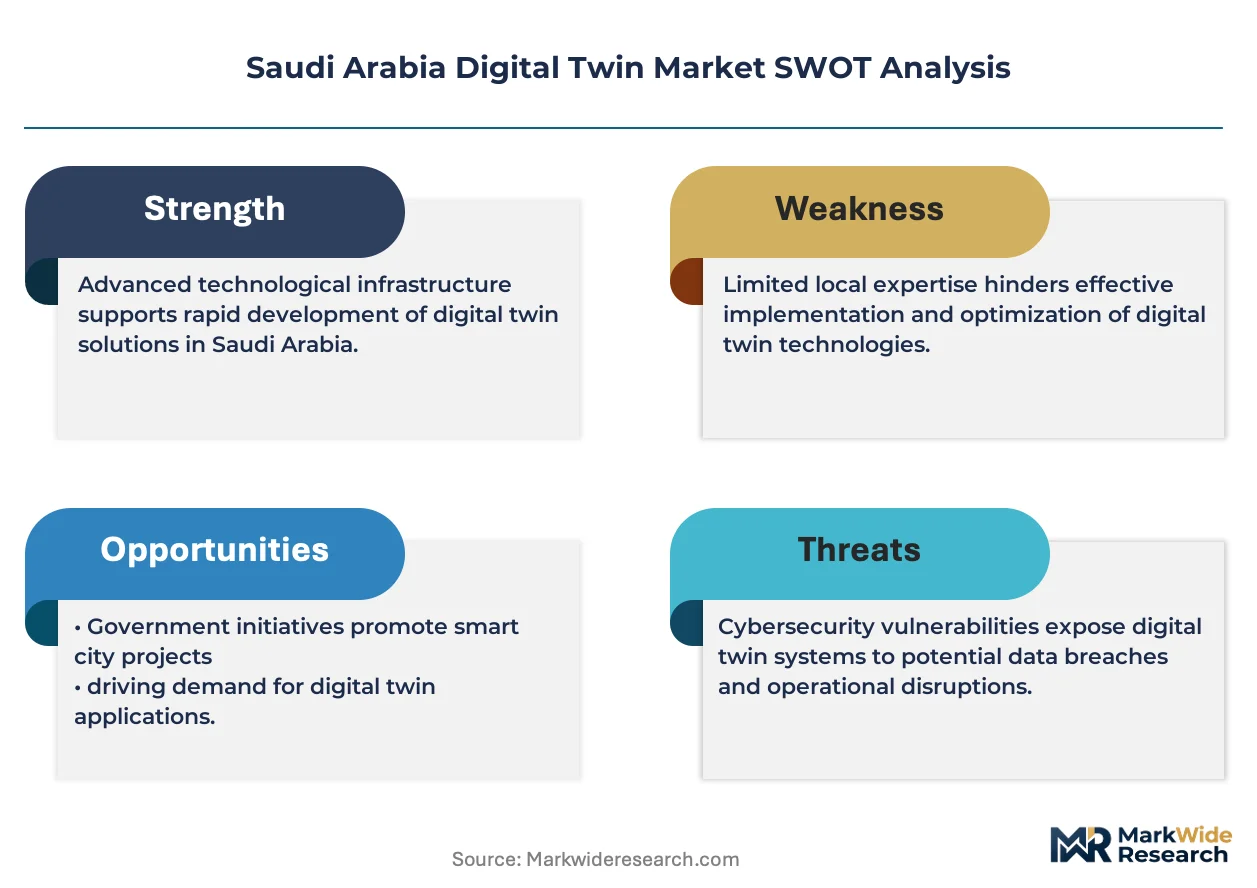
- Data sovereignty compliance costs:Cross-border cloud governance mandates from the Communications, Space and Technology Commission force foreign vendors to localize infrastructure, inflating platform architecture investments.
- Encryption protocol fragmentation:National Cybersecurity Authority access requirements diverge from ISO 27001 baselines, complicating multi-tenant SaaS deployments for international software providers.
- Telecom infrastructure gaps:Sub-second latency thresholds for predictive control applications remain unattainable in peripheral industrial zones outside Jubail and Yanbu, constraining edge deployment scope.
Strategic Opportunities
- Qassim and Asir manufacturing clusters:Underpenetrated mid-tier industrial cities lack dedicated digital twin service providers, opening channel partnerships with regional system integrators.
- AI-model-as-a-service convergence:Physics-informed neural networks bundled with twin platforms create new revenue streams distinct from core licensing, capturing value from predictive maintenance outcomes.
- Saudi Data and Artificial Intelligence Authority interoperability mandates:Mandatory interoperable digital standards for critical national assets compel vendor consolidation around open APIs, favoring platform-agnostic middleware specialists.
Industry Challenges
- Industrial data science talent scarcity:Physics-based simulation expertise combined with IoT systems engineering commands premium compensation, constraining implementation velocity for mid-market deployments.
- Legacy SCADA integration complexity:Brownfield facilities in the Eastern Province operate proprietary protocols from the 1990s, requiring costly protocol translation layers that erode project margins.
- Certification timeline uncertainty:Absence of standardized digital twin validation frameworks from the Saudi Standards, Metrology and Quality Organization delays procurement approvals for safety-critical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Digital Twin Market |
| Market Size in 2026 | $620.4 Million |
| Market Size in 2035 | $9,056.91 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, IoT Platforms, Services, Consulting End User: Manufacturing, Healthcare, Energy, Smart Cities Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution: Visualization Tools, Simulations, Analytics, Monitoring Systems |
| Companies Covered | PTC Inc., IBM Corporation, Siemens AG, GE Digital, Microsoft Corporation, Dassault Systèmes, ANSYS Inc., Bentley Systems Incorporated, Autodesk Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Digital Twin Market Trends and Innovations
Real-time sensor fusion architectures are displacing batch-processed simulation workflows across Saudi energy and manufacturing verticals, compressing decision latency from hours to seconds and enabling closed-loop autonomous control.
Digital thread technology is converging with generative design algorithms to compress product development cycles for aerospace suppliers in the King Abdulaziz City for Science and Technology corridor. Tier-one contractors are adopting these integrated workflows to meet localization requirements under the National Industrial Development and Logistics Program. The structural consequence is a collapse in physical prototyping demand, with simulation-first validation becoming the default for defense-adjacent manufacturing.
The Saudi Data and Artificial Intelligence Authority's governance frameworks now mandate explainable AI for predictive maintenance applications operating on critical national infrastructure. This industrial consequence forces platform vendors to retrofit black-box machine learning models with physics-based constraint layers, increasing computational overhead but reducing liability exposure. Energy sector operators in the Eastern Province are responding by demanding model interpretability dashboards as standard procurement terms.
Asset-as-a-service contracting is displacing capital-heavy ownership models for high-value rotating equipment in petrochemical complexes. Procurement teams at SABIC affiliates now specify outcome-based availability guarantees rather than hardware specifications, transferring operational risk to OEM-integrator consortia. This pattern is most visible in Yanbu Industrial City, where steam turbine maintenance contracts now bundle digital twin monitoring with spare parts logistics.
Saudi Arabia Digital Twin Market Segmentation
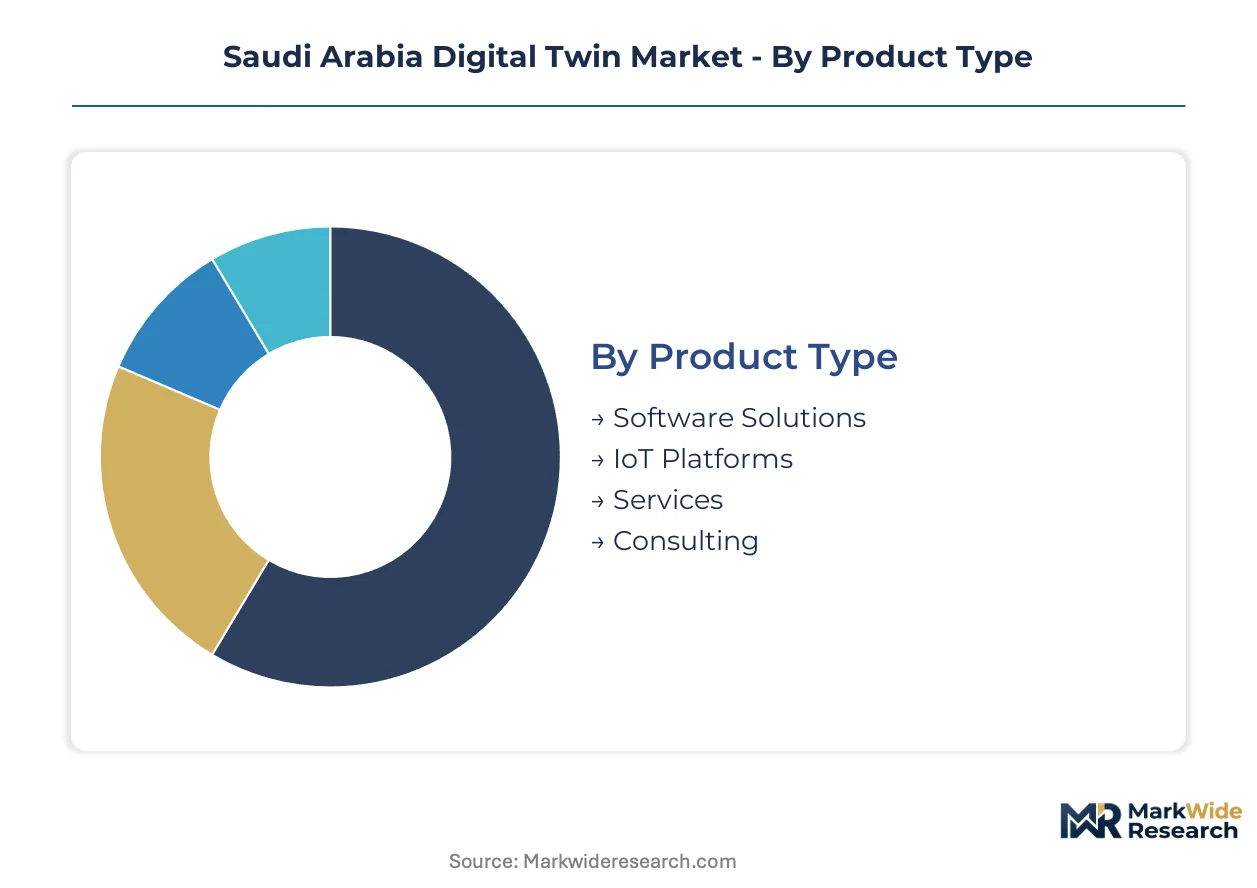
Digital twin procurement patterns in Saudi Arabia diverge sharply across buyer sophistication tiers. Capital-intensive operators in the Eastern Province prioritize high-fidelity physics simulation, while municipal clients emphasize interoperability mandates from the Saudi Data and Artificial Intelligence Authority.
Product Type:
Buyers differentiate primarily by internal IT maturity and data science headcount, not by asset scale alone.
- Software Solutions:Physics-based simulation engines and model orchestration layers form the technical core of most deployments. Aramco's upstream facilities drive demand for sub-second latency process twins that mirror hydrocarbon flow dynamics in real time.
- IoT Platforms:Sensor ingestion middleware and edge connectivity stacks bridge operational technology with enterprise systems. NEOM's autonomous infrastructure experiments are accelerating adoption of platform-agnostic data pipelines that comply with SDAIA interoperability standards.
- Services:Implementation and integration support from regional system integrators addresses talent scarcity in physics-based simulation expertise.
- Consulting:Strategy advisory around digital thread architecture and change management for brownfield SCADA modernization projects.
Volume sits with Software Solutions; growth tilts toward IoT Platforms.
End User:
Application context determines fidelity requirements and procurement authority structures more than budget size.
- Energy:Upstream oilfield operators and downstream petrochemical complexes deploy the most computationally intensive twins. Yanbu Industrial City facilities require continuous asset mirroring for rotating equipment with predictive maintenance models trained on decade-long operational histories.
- Smart Cities:Municipal infrastructure planning in Riyadh generates demand for urban-scale digital replicas spanning water distribution, transport networks, and district cooling. SDAIA governance frameworks mandate these implementations serve as reference architectures for secondary cities.
- Manufacturing:Discrete and process manufacturers in Jubail Industrial City adopt product lifecycle twins to meet National Industrial Development and Logistics Program localization requirements.
- Healthcare:Hospital infrastructure and medical device fleet management applications remain nascent, constrained by absence of standardized validation frameworks from the Saudi Food and Drug Authority.
Revenue concentrates in Energy; Smart Cities claims the steepest expansion trajectory.
Deployment:
Latency tolerance and data sovereignty risk jointly determine architecture selection.
- Cloud-Based:Scalable compute for non-time-critical analytics and long-term simulation model training. Communications, Space and Technology Commission cross-border governance mandates force foreign vendors to localize infrastructure, inflating platform investments.
- Edge Computing:Sub-second predictive control applications in peripheral industrial zones where telecom infrastructure gaps persist outside Jubail and Yanbu.
- Hybrid:Split architectures retaining sensitive physics models on-premises while pushing aggregated analytics to sovereign cloud instances.
- On-Premises:Air-gapped deployments for defense-adjacent manufacturing and critical national infrastructure subject to National Cybersecurity Authority encryption protocols.
Adoption favors Hybrid; Edge Computing is climbing the fastest as telecom modernization accelerates under the National Transformation Program.
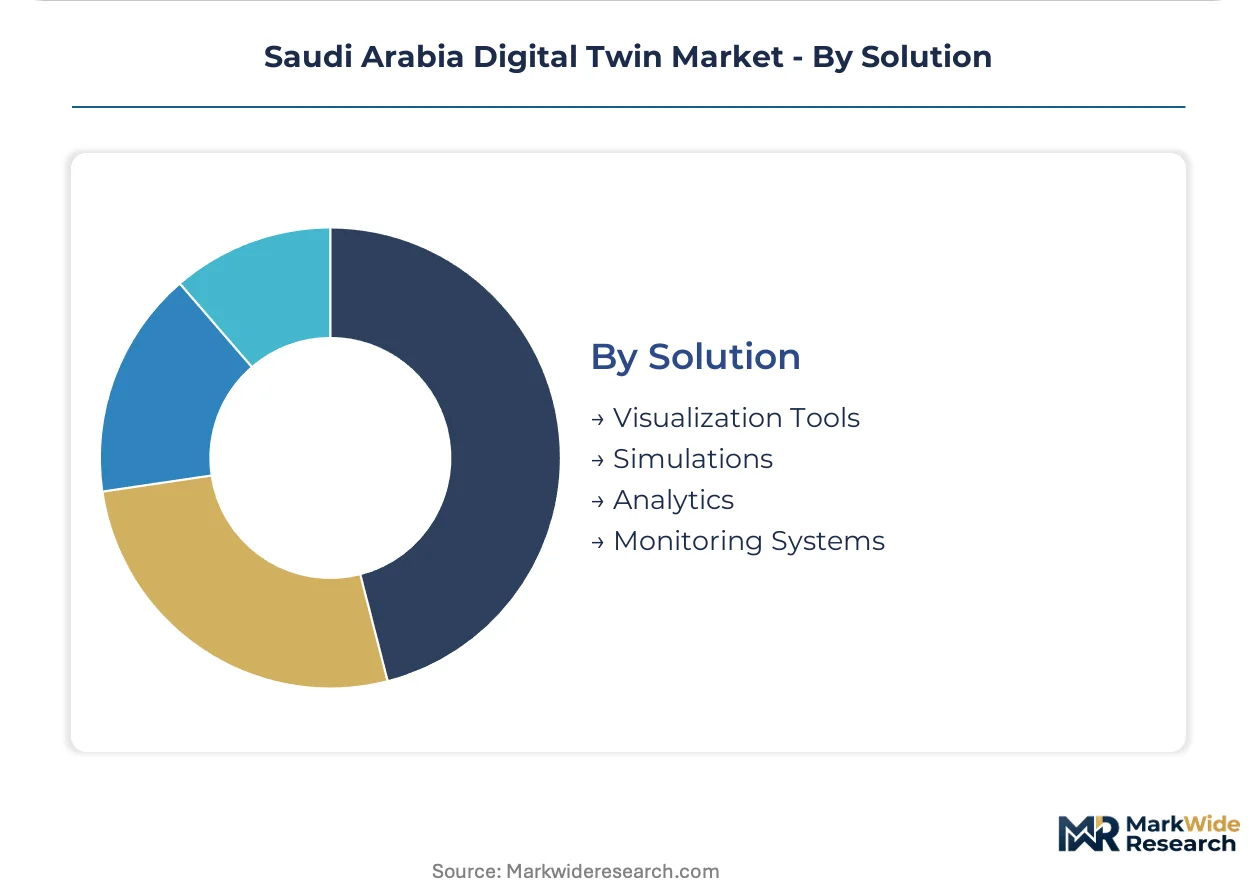
Solution:
Functional layer specialization reflects whether buyers prioritize operational visibility or predictive autonomy.
- Simulations:Physics-based digital replicas enabling what-if scenario testing without physical intervention. Aerospace suppliers in the King Abdulaziz City for Science and Technology corridor deploy these for generative design validation.
- Analytics:Predictive maintenance algorithms and performance optimization engines. SDAIA's explainable AI mandates now require model interpretability dashboards as standard procurement terms.
- Visualization Tools:3D immersive interfaces for non-technical stakeholders and regulatory compliance documentation.
- Monitoring Systems:Real-time asset health dashboards integrating sensor feeds with threshold-based alerting for operations teams.
Deployment breadth favors Simulations; Analytics is gaining share fastest through AI-model-as-a-service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity concentrates in the Eastern Province's petrochemical complexes while consumption spreads across Riyadh's smart city infrastructure and NEOM's experimental zones. This geographic split shapes vendor deployment strategies and data sovereignty architecture decisions.
Eastern Province
Upstream oilfield operators and downstream petrochemical facilities drive demand for high-fidelity process twins. The Saudi Data and Artificial Intelligence Authority mandates interoperable standards for critical national infrastructure. Yanbu Industrial City facilities deploy continuous asset mirroring for rotating equipment with predictive maintenance models.
Riyadh
Municipal infrastructure planning generates demand for urban-scale digital replicas spanning water distribution and transport networks. The National Transformation Program accelerates telecom modernization enabling cloud-based twin deployments. King Abdulaziz City for Science and Technology corridor aerospace suppliers adopt generative design validation workflows.
NEOM Northwest
Autonomous digital infrastructure governance experiments establish precedents for broader national standardization. The regulatory sandbox reduces compliance friction for platform vendors entering experimental zones. Linear city construction creates reference architectures for secondary cities under SDAIA interoperability mandates.
Jubail Industrial City
Process manufacturers adopt product lifecycle twins to meet National Industrial Development and Logistics Program localization requirements. Discrete manufacturing segments require IoT-connected asset management platforms. Brownfield SCADA integration challenges persist with proprietary protocols from the 1990s.
Western Region
Peripheral industrial zones outside Yanbu face telecom infrastructure gaps constraining edge deployment scope. Sub-second latency thresholds for predictive control applications remain unattainable in underpenetrated manufacturing clusters. Channel partnerships with regional system integrators target Qassim and Asir expansion.
Saudi Arabia Digital Twin Market Competitive Landscape
Capital-heavy industrial automation producers compete with asset-light software platform designers for twin deployment contracts across Saudi industrial clients. The vendor base stratifies into three tiers: integrated conglomerates with hardware-software stacks, specialized simulation engine developers, and cloud-native IoT platform providers. Siemens AG anchors large-scale manufacturing implementations through its industrial automation heritage. PTC Inc. and Dassault Systèmes occupy distinct positioning vectors in discrete manufacturing and aerospace supply chains respectively. Dominant competitive moves include subscription-based feature layer monetization and sovereign cloud infrastructure localization.
Within the integrated industrial tier, Siemens AG exemplifies the capital-heavy archetype leveraging automation hardware dominance. Among specialized software developers, PTC Inc. and Dassault Systèmes represent contrasting approaches to product lifecycle management and 3D experience platforms. These three anchors illustrate how vendor consolidation around open APIs favors platform-agnostic middleware specialists under SDAIA interoperability mandates.
| Leading Market Players |
|---|
| PTC Inc. |
| IBM Corporation |
| Siemens AG |
| GE Digital |
| Microsoft Corporation |
| Dassault Systèmes |
| ANSYS Inc. |
| Bentley Systems Incorporated |
| Autodesk Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud compute spot price indices cascade through Saudi digital twin deployments into three-tier pricing structures across premium, standard, and economy levels, with sovereign data center localization costs amplifying margin pressure on foreign platform vendors serving SDAIA-mandated implementations.
Pricing Analysis
Cost-down pressure on mid-market SaaS tiers accelerates because Aramco's procurement teams demand outcome-based availability guarantees rather than perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels separates physics-simulation fidelity grades, with ISO 27001-equivalent certification tiers commanding 40-60% premiums. Municipal smart city buyers in Riyadh exhibit highest price sensitivity due to fixed budget cycles under the National Transformation Program, while defense-adjacent manufacturing in the King Abdulaziz City corridor shows lowest sensitivity given air-gapped deployment mandates from the National Cybersecurity Authority.
Supply Chain Analysis
Dual-sourcing requirements from the Saudi Data and Artificial Intelligence Authority compel foreign vendors to qualify secondary cloud infrastructure partners beyond primary hyperscaler relationships. Supply concentrates in the United States, Germany, and China for industrial IoT sensor hardware, while physics-simulation engine development draws from France and the United Kingdom. Proprietary edge computing chipsets and sovereign cloud data center construction materials represent critical input dependencies. Single-source vulnerability persists in sub-second latency networking equipment for peripheral industrial zones. Distribution runs through Riyadh-based system integrators with Eastern Province technical deployment capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's digital twin market constitutes a vertical-integration race where platform vendors capture margin by internalizing physics-simulation engine development rather than licensing from specialized software houses.
For Market Incumbents: Anchor defensive positioning through backward integration into sovereign cloud infrastructure construction, neutralizing SDAIA data sovereignty compliance costs that erode SaaS margins. Consolidate around open API middleware layers to capture value from vendor fragmentation under interoperability mandates. Siemens AG's industrial automation hardware-software stack exemplifies this integrated model. Threat substitution from cloud-native IoT platform providers demands preemptive channel control in underpenetrated Qassim manufacturing clusters. For New Entrants and Emerging Players: AI-model-as-a-service bundling offers a technology-first wedge into predictive maintenance outcome contracts displacing capital-heavy equipment sales at SABIC affiliates. Target white-space expansion in Asir and Qassim mid-tier industrial cities lacking dedicated digital twin service providers. NEOM's regulatory sandbox experiments with autonomous digital infrastructure governance create reference architecture opportunities transferable to secondary municipal implementations under SDAIA standardization precedents. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform-agnostic middleware specialists with pre-qualified National Cybersecurity Authority encryption protocols in the Eastern Province petrochemical corridor. Long-term viability hinges on 5-10 year localization requirement maturation under the National Industrial Development and Logistics Program. Watch for inflection signals in Saudi Standards, Metrology and Quality Organization digital twin validation framework publication, which would unlock safety-critical application procurement approvals currently frozen.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Localization | SDAIA data sovereignty mandates force foreign vendors to deploy Saudi-based data centers, inflating platform architecture investments. |
| Physics-Informed Neural Network Development | Explainable AI mandates from SDAIA compel retrofit of black-box models with physics-based constraint layers, increasing computational overhead. |
| Open API Middleware Platform Consolidation | Interoperability standards for critical national assets favor vendor consolidation around platform-agnostic integration specialists. |
| Edge Computing Telecom Partnership | National Transformation Program infrastructure modernization enables sub-second latency deployments in peripheral industrial zones. |
| Outcome-Based Availability Contracting | SABIC procurement teams now specify performance guarantees rather than hardware specifications, transferring operational risk to OEM-integrator consortia. |
Research Methodology
Multi-period observation of NEOM construction milestone velocity, Aramco digitalization program procurement disclosures, and SDAIA regulatory publication timelines anchored the trend analysis, supplemented by interviews with platform engineering directors, municipal smart city procurement officers, industrial automation channel partners, and physics-simulation technical leads. Secondary validation drew from Communications, Space and Technology Commission spectrum allocation records, National Cybersecurity Authority encryption protocol advisories, and National Transformation Program telecom infrastructure budget disclosures. Bottom-up deployment sizing across Eastern Province petrochemical facilities and top-down policy impact assessment were triangulated to cross-validate market trajectory.
Segment-weighting approaches applied differential growth coefficients across software solutions, IoT platforms, services, and consulting layers, with deployment architecture splits modeled across cloud-based, edge computing, hybrid, and on-premises configurations. End-user segmentation incorporated energy, smart cities, manufacturing, and healthcare verticals with distinct latency tolerance and data sovereignty risk profiles. CAGRs were derived from installation base expansion rates, subscription renewal velocity, and average revenue per user trajectories across the projection horizon. Physics-simulation computational intensity requirements and sovereign cloud localization cost curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential SDAIA interoperability mandate delay, NEOM regulatory sandbox experiment termination, and Aramco upstream digitalization program scope revision. Forecasts reflect assumptions around sustained National Transformation Program telecom infrastructure investment and stable National Cybersecurity Authority encryption protocol continuity. Deviation in Saudi Standards, Metrology and Quality Organization digital twin validation framework publication timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Thin Client Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
US Digital Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Product As a Service Market
Digital Solutions
Digital Manufacturing Market