
 Location As a Service Market | 2026-2036
Location As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Location As a Service Market Outlook
Premium accuracy tier is rotating toward the center of competitive strategy in Location As a Service. HERE Technologies leverages its automotive-grade mapping heritage to sustain dominance in HD positioning for autonomous systems. Google LLC anchors consumer-facing location intelligence through deep integration with mobile operating systems. Esri specializes in enterprise geographic information systems, occupying a defensible position in government and utility verticals.
Location As a Service denotes cloud-delivered positioning, mapping, and spatial analytics capabilities provisioned through subscription or API-based models, typically achieving sub-meter accuracy through fused GPS, Wi-Fi, and Bluetooth signal triangulation. The primary commercial purpose centers on enabling real-time asset visibility, geofenced operational control, and route optimization without capital-intensive infrastructure deployment. Real-Time Location Services commands the largest revenue share as retail chains and healthcare providers mandate continuous inventory and patient flow monitoring. Mapping Solutions represents the fastest-expanding category, driven by logistics companies requiring dynamic route recalculation amid supply network volatility. Analytics Tools captures concentrated margin pools, since fleet management operators pay premium rates for predictive dwell-time and fuel-efficiency algorithms.
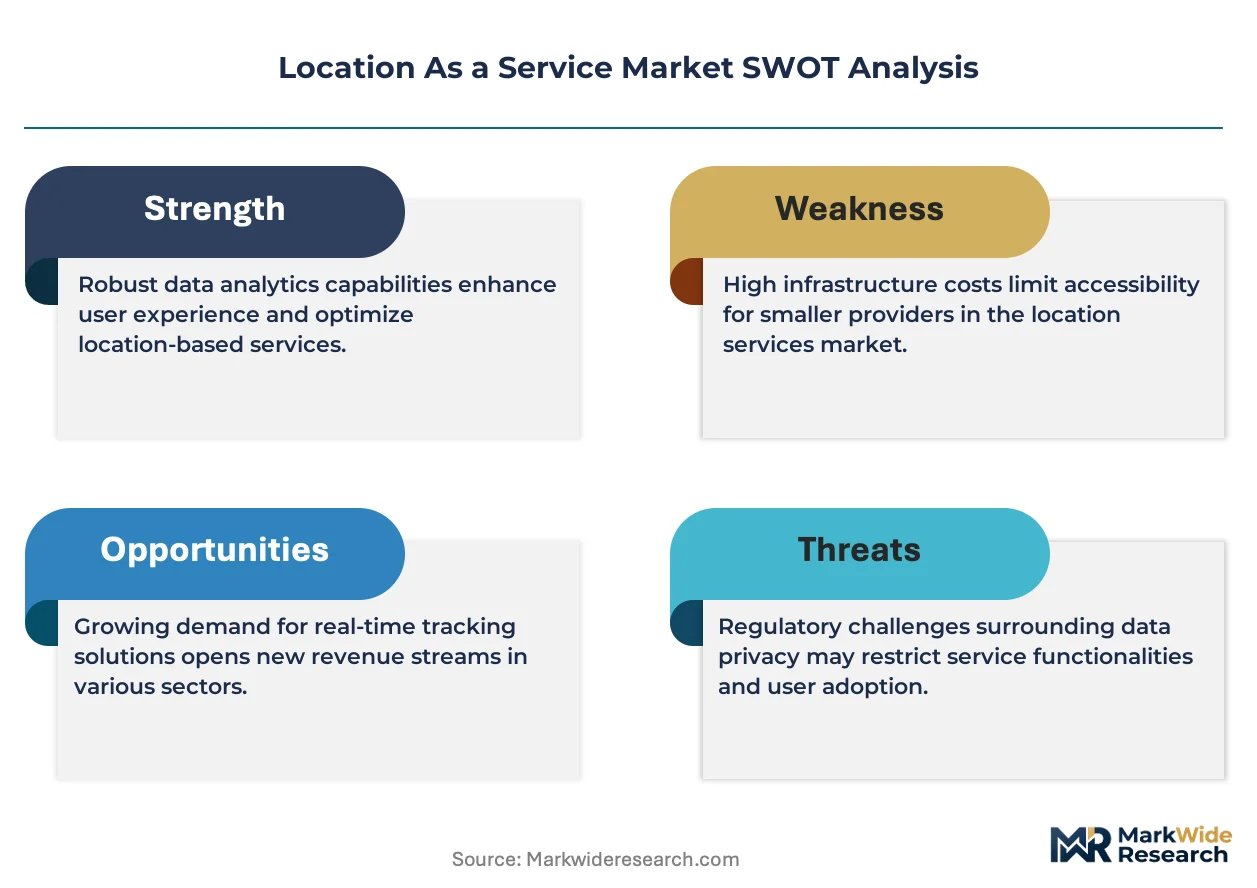
The EU AI Act imposes algorithmic transparency obligations on automated location decision systems, while GDPR restricts cross-border movement of geospatial personal data, compelling providers to regionalize data residency architectures. The FCC in the United States enforces E911 location accuracy mandates that directly shape handset and network positioning specifications. Stakeholders must weigh regulatory fragmentation against platform standardization bets when allocating R&D budgets across jurisdictional deployment roadmaps.
Market Dynamics
Automotive OEMs are consolidating their location data procurement around single-vendor HD mapping contracts, compressing supplier margins while elevating technical certification barriers for platform providers.
Growth Catalysts
- Germany's Industrial Cluster Density:Automotive manufacturers in Stuttgart and Munich are mandating centimeter-level positioning for autonomous test fleets, pulling cloud-based location services into production workflows.
- EU AI Act Algorithmic Transparency:Automated geofencing and predictive routing systems now face explainability requirements, creating certified-provider advantages over unregulated competitors.
- Bluetooth Low Energy Mesh:Indoor positioning infrastructure is achieving sub-meter accuracy without dedicated hardware, enabling rapid deployment in healthcare and retail environments.
Market Restraints
- GDPR Cross-Border Data Friction:Geospatial personal data residency requirements force redundant infrastructure deployment, raising operational costs for multi-national platform operators.
- Precision Agriculture Input Volatility:GNSS correction service subscriptions face pricing pressure from commodity crop margins, limiting farmer willingness to pay for premium accuracy tiers.
- Signal Fusion Complexity:Urban canyon multipath interference degrades GPS reliability, requiring expensive sensor fusion development that smaller providers cannot fund.
Strategic Opportunities
- India's Logistics Digitization:National highway corridor modernization and e-commerce fulfillment expansion are creating first-mover advantages for API-based fleet tracking platforms.
- 5G Network Positioning Convergence:Cellular tower triangulation is merging with satellite navigation, enabling indoor-outdoor seamless tracking without dedicated beacon hardware.
- FCC E911 Phase II Mandates:Vertical positioning requirements for emergency response are driving handset manufacturer demand for barometric-altitude fusion algorithms.
Industry Challenges
- Geospatial Data Science Talent Scarcity:Platform providers compete for machine learning engineers capable of optimizing signal fusion models across heterogeneous sensor inputs.
- Automotive Safety Certification Timelines:ISO 26262 functional safety validation for autonomous positioning systems extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location As a Service Market |
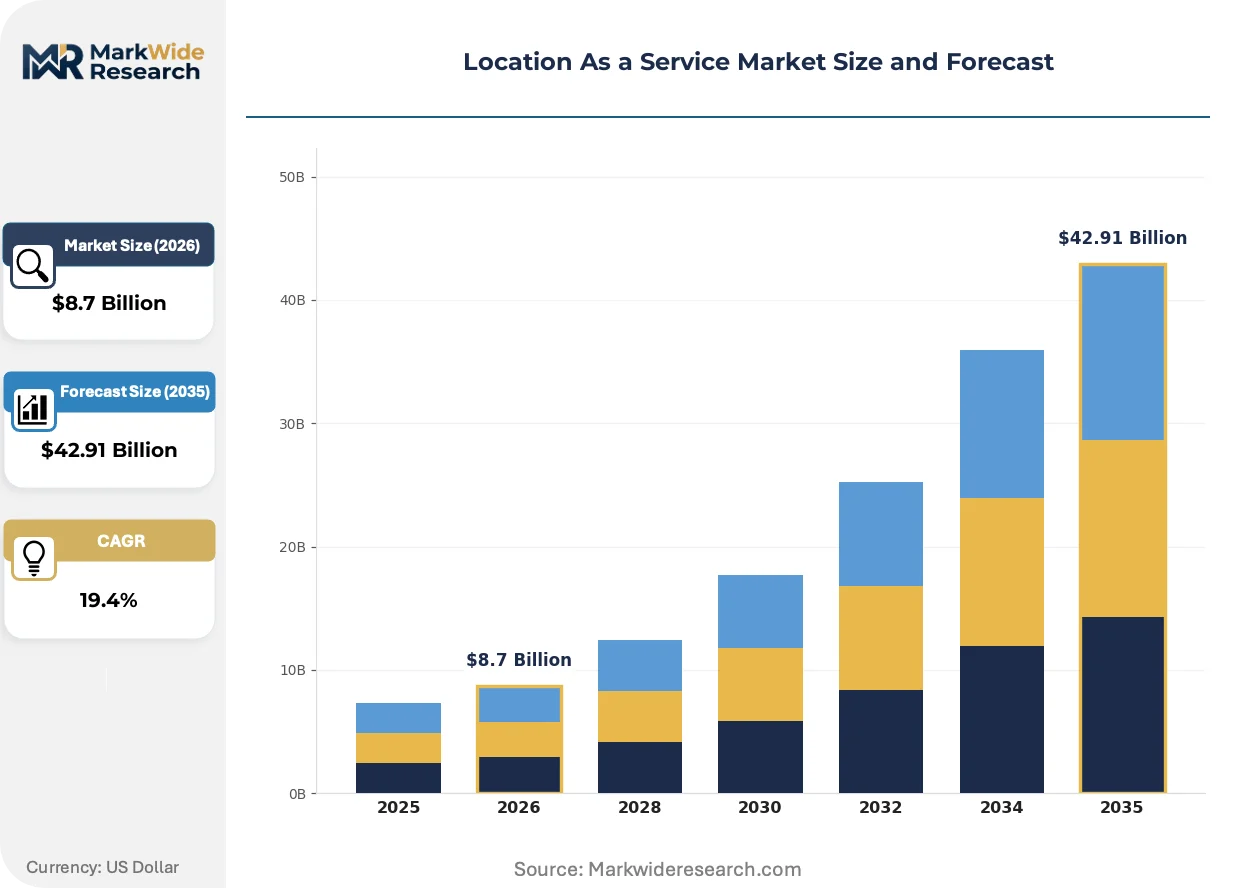
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real-Time Location Services, Geofencing, Mapping Solutions, Analytics Tools End User: Retail Chains, Logistics Companies, Healthcare Providers, Educational Institutions Technology: GPS, Wi-Fi, RFID, Bluetooth Application: Amenities Management, Asset Tracking, Emergency Response, Fleet Management |
| Companies Covered | Google LLC, HERE Technologies, Esri, Cisco Systems, Inc., IBM Corporation, Qualcomm Technologies, Inc., Microsoft Corporation, TomTom N.V., Foursquare Labs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location As a Service Market Strategic Shifts
Location platform architecture is splitting between consumer-grade convenience and industrial-grade precision, with diverging technical roadmaps and pricing models emerging for each path.
Multi-constellation GNSS receivers incorporating Galileo, BeiDou, and NavIC signals alongside GPS are achieving faster time-to-first-fix and urban accuracy improvements. Agricultural equipment manufacturers and surveying instrument vendors are embedding these chipsets as standard configurations. The hardware layer is bifurcating between low-cost single-frequency modules for consumer applications and dual-frequency precise-point-positioning chipsets for commercial and industrial deployments.
The EU AI Act's risk-based classification system places automated vehicle navigation and emergency response geolocation into high-risk categories requiring conformity assessment. Platform providers must document algorithmic decision pathways and maintain human oversight interfaces. European automotive OEMs are restructuring supplier contracts to transfer compliance liability onto location service vendors.
Enterprise buyers are consolidating location data procurement under centralized IT procurement functions rather than distributed operational budgets. Fleet operators and facility managers now face enterprise software procurement teams demanding API standardization and volume-based pricing. This pattern is most pronounced in Germany's automotive supplier network and the Netherlands' logistics hub operators.
Location As a Service Market Segmentation
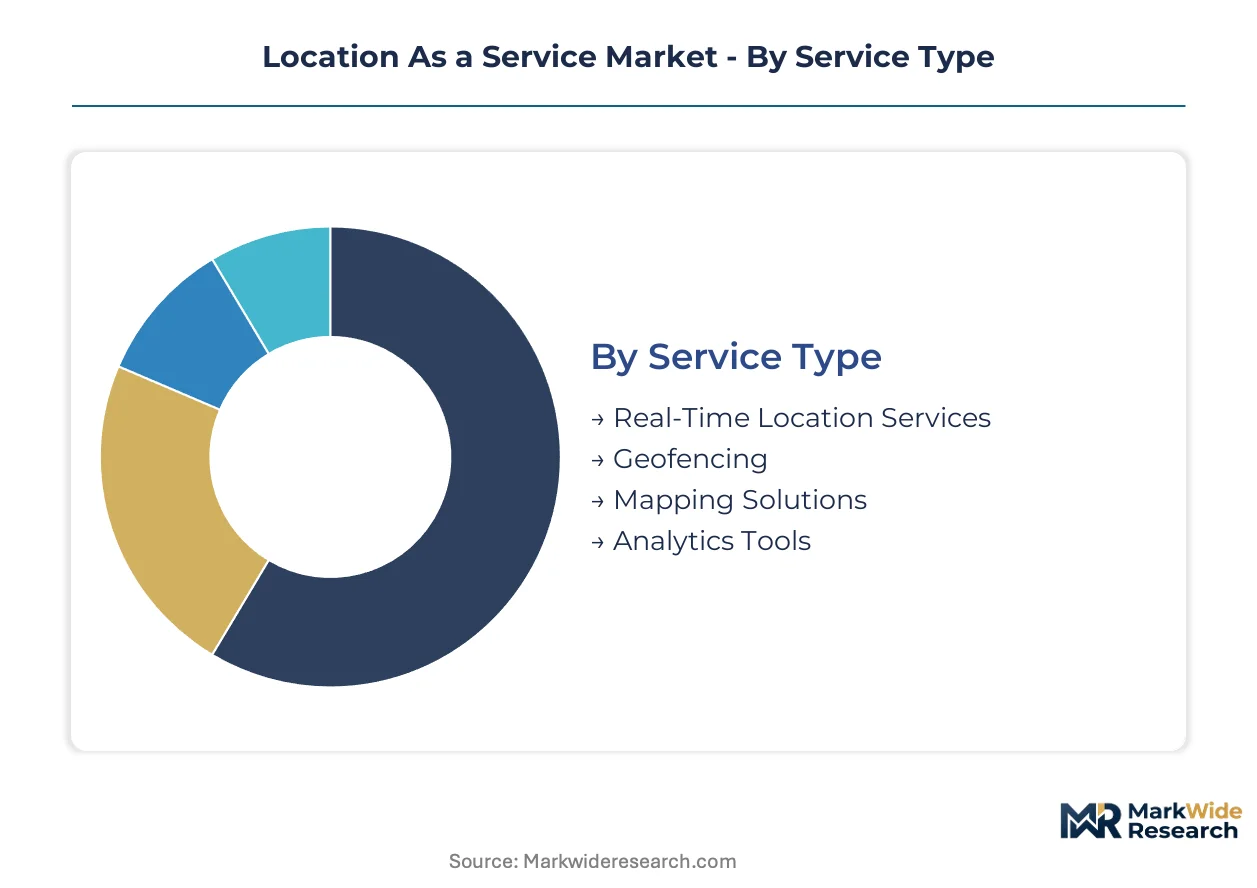
Location As a Service providers structure their commercial models around distinct service tiers, each carrying different margin profiles and deployment complexity. Segmentation clarity enables buyers to match technical specifications against operational requirements without over-provisioning capabilities.
Service Type:
Channel distribution varies sharply across service tiers, with API-first platforms capturing developer-led adoption while enterprise sales teams drive high-value mapping contracts.
- Real-Time Location Services:Continuous position streaming through cloud APIs enables inventory tracking and patient flow monitoring. Retail chains in Germany mandate these capabilities for omnichannel fulfillment synchronization. Bluetooth Low Energy mesh deployments are reducing hardware dependency for indoor implementations.
- Mapping Solutions:Dynamic route recalculation engines process traffic, construction, and weather inputs for logistics optimization. Fleet operators across India's national highway corridors are integrating these APIs into transport management systems amid infrastructure modernization. Cloud-native architectures allow rapid scaling without on-premise mapping database maintenance.
- Geofencing:Virtual perimeter triggers automate operational controls when assets cross defined boundaries.
- Analytics Tools:Predictive algorithms optimize dwell times and fuel efficiency for fleet management operators.
Real-Time Location Services dominates installed base. Mapping Solutions is where expansion concentrates.
End User:
Procurement sophistication varies by vertical, with logistics companies consolidating vendor relationships while healthcare providers fragment purchasing across departmental budgets.
- Logistics Companies:Fleet visibility and route optimization drive subscription commitments. European road freight operators face EU AI Act compliance requirements for automated dispatch systems, elevating vendor selection criteria beyond price.
- Healthcare Providers:Patient tracking and equipment location systems reduce operational delays. Hospital networks in Stuttgart and Munich are deploying centimeter-grade indoor positioning for emergency response workflows.
- Retail Chains:Inventory accuracy and click-and-collect coordination shape technology investments.
- Educational Institutions:Campus safety and resource scheduling applications define procurement scope.
Logistics Companies anchor current revenue. Healthcare Providers represent the steepest expansion trajectory.
Technology:
Signal fusion approaches determine accuracy ceilings and infrastructure requirements, with multi-constellation GNSS chipsets displacing single-system receivers in commercial deployments.
- GPS:Satellite navigation remains the foundational positioning layer. Dual-frequency receivers incorporating L5 signals achieve faster urban convergence for automotive and surveying applications.
- Bluetooth:Low Energy mesh networks deliver sub-meter indoor accuracy without dedicated beacon hardware. Healthcare facilities in the Netherlands deploy these configurations for rapid infrastructure rollout.
- Wi-Fi:Fingerprinting approaches leverage existing access point infrastructure for coarse indoor positioning.
- RFID:Passive and active tag systems serve asset identification at discrete checkpoints rather than continuous tracking.
GPS underpins the broadest deployment footprint. Bluetooth is climbing the fastest among emerging infrastructure configurations.
Application:
Use case maturity determines pricing power, with safety-critical applications commanding certification premiums over operational efficiency tools.
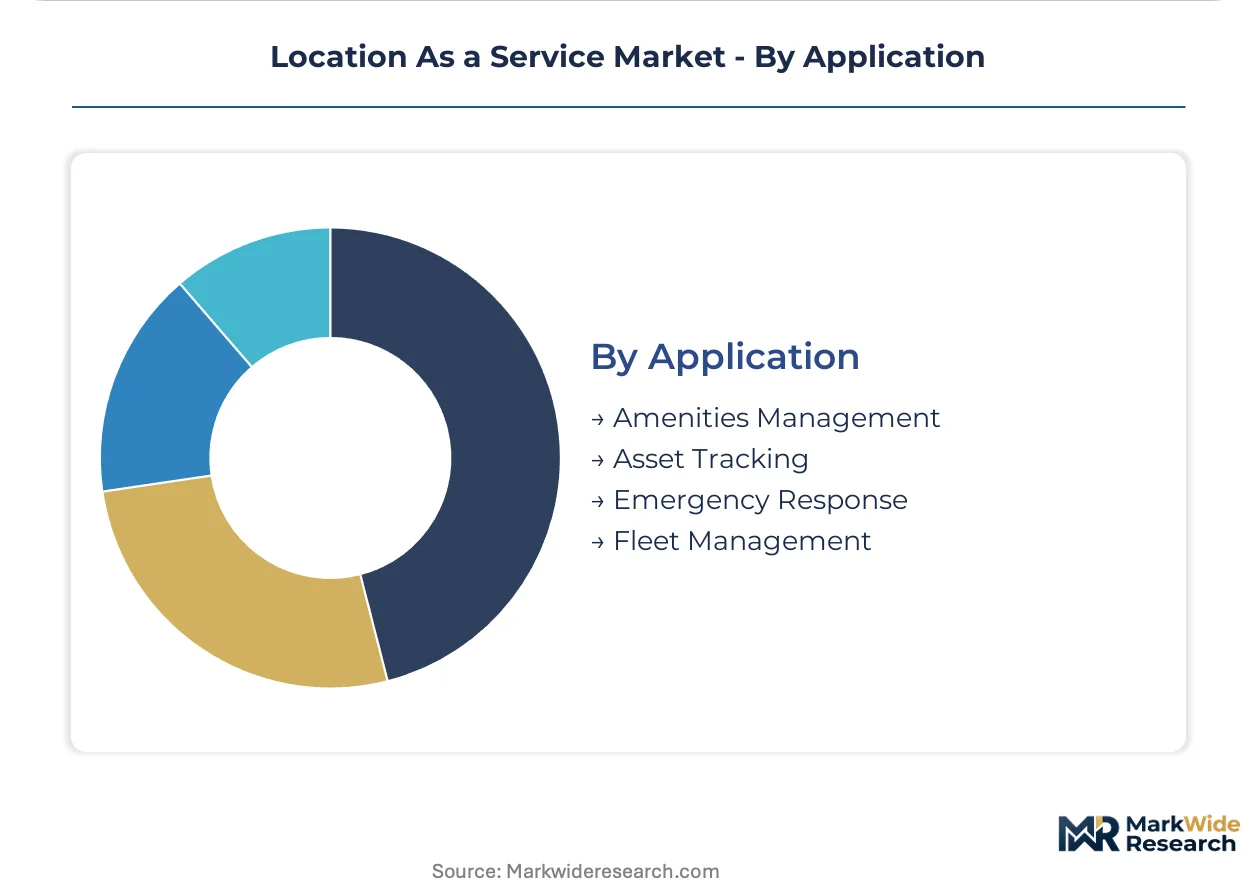
- Fleet Management:Vehicle tracking and driver behavior analytics dominate commercial adoption. Indian e-commerce fulfillment networks are scaling API-based implementations across multi-modal transport operations.
- Asset Tracking:High-value equipment and inventory visibility solutions serve industrial and retail verticals. German automotive suppliers mandate these capabilities for just-in-sequence production logistics.
- Emergency Response:FCC E911 Phase II vertical positioning requirements drive handset manufacturer demand for barometric-altitude fusion.
- Amenities Management:Facility utilization and visitor navigation applications serve commercial real estate operators.
Fleet Management holds the largest active deployment base. Asset Tracking is gaining share fastest among precision-dependent industrial users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a location services trade surplus driven by automotive-grade mapping exports, while India and the United States import cloud positioning infrastructure to support logistics digitization and emergency response mandates.
United States
FCC E911 Phase II mandates propel vertical positioning demand from handset manufacturers and emergency response systems. The FAA regulates drone navigation services requiring geofencing compliance for commercial unmanned aerial operations. California's Silicon Valley hosts dense clusters of API-first location platforms serving ride-hailing and delivery applications.
Germany
Automotive OEMs in Stuttgart and Munich mandate centimeter-grade positioning for autonomous test fleets and production logistics. The EU AI Act imposes algorithmic transparency requirements on automated geofencing systems, elevating certified provider selection criteria. Bavaria's industrial corridor anchors HD mapping development for commercial vehicle navigation.
India
National highway corridor modernization and e-commerce fulfillment expansion drive API-based fleet tracking procurement. The Ministry of Road Transport and Highways mandates GPS-enabled toll collection and commercial vehicle monitoring under FASTag integration. Maharashtra's Mumbai-Pune logistics belt concentrates demand for real-time asset visibility solutions.
China
MIIT promotes BeiDou navigation adoption across industrial and consumer applications through domestic chipset requirements. The country's national data security framework restricts cross-border geospatial data flows, compelling regional cloud infrastructure deployment. The Yangtze River Delta manufacturing belt integrates indoor positioning for smart factory and warehouse automation.
United Kingdom
Transport for London mandates open data standards for mobility services, creating standardized API demand from transit technology vendors. The Information Commissioner's Office enforces GDPR-aligned geospatial personal data handling for location analytics providers. London's financial district drives precision mapping requirements for insurance risk assessment and property valuation platforms.
Location As a Service Market Competitive Environment
Concentration sits with automotive-grade mapping specialists and cloud-native platform providers, creating a bifurcated structure where heritage geospatial data assets compete against developer-centric API economies. The vendor landscape organizes around three strategic archetypes: HD mapping incumbents with vehicle safety certification, hyperscale cloud operators leveraging mobile OS integration, and enterprise GIS specialists serving regulated verticals. Competitive moves center on automotive OEM data procurement consolidation and compliance-driven supplier certification transfers.
Within the automotive-grade tier, HERE Technologies and TomTom N.V. occupy positions defined by HD map accuracy and safety validation heritage. Google LLC exemplifies the mobile-OS-anchored archetype through deep consumer platform integration. Esri sits within the enterprise GIS specialization, serving government and utility procurement functions with geographic information system platforms.
| Leading Market Players |
|---|
| Google LLC |
| HERE Technologies |
| Esri |
| Cisco Systems, Inc. |
| IBM Corporation |
| Qualcomm Technologies, Inc. |
| Microsoft Corporation |
| TomTom N.V. |
| Foursquare Labs Inc. |
| Others |
Value Chain & Pricing Dynamics
Thirty-to-forty-five-day API provisioning lead times concentrate pricing power with hyperscale cloud operators possessing redundant data center footprints across Germany, India, and the United States. Inventory sits in software-defined capacity rather than physical stock, yet GDPR-mandated data residency requirements force geographic infrastructure duplication that feeds into subscription tiering.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 26262 certification grade and volume scale, with automotive-grade HD mapping commanding five-to-ten-fold premiums over consumer API tiers. Cost compression in the standard tier is intensifying because logistics operators consolidate procurement under enterprise IT functions. Healthcare providers exhibit highest price sensitivity due to departmental budget fragmentation, while autonomous vehicle programs show lowest sensitivity given safety-critical liability exposure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for multi-constellation GNSS chipset sourcing. Hardware supply concentrates in Taiwan, South Korea, and China, with cloud software layers drawing from distributed engineering talent pools in California, Bavaria, and Bangalore. Single-source vulnerability sits with BeiDou/Galileo receiver module suppliers facing MIIT export licensing friction. Distribution runs through API-first developer platforms and direct enterprise sales teams serving automotive OEM procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized IT procurement functions as fleet operators and automotive OEMs consolidate vendor relationships, fragmenting pricing leverage for point-solution providers.
For Market Incumbents: Fortify automotive safety certification moats through accelerated ISO 26262 validation cycles for autonomous positioning systems. Deepen backward integration into dual-frequency GNSS chipset supply through captive partnerships with Taiwan semiconductor foundries. HERE Technologies and TomTom N.V. face margin compression from OEM single-vendor consolidation mandates. For New Entrants and Emerging Players: Differentiate on Bluetooth Low Energy mesh indoor positioning for healthcare facilities lacking dedicated beacon infrastructure. White-space targets include India's Mumbai-Pune logistics corridor and Netherlands hospital networks seeking rapid deployment without hardware capital expenditure. API-first developer evangelism unlocks adoption before enterprise sales engagement. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core geospatial software units lacking cloud-native architecture. Long-term viability favors platforms with GDPR-compliant regional data residency and EU AI Act algorithmic transparency documentation. Watch FCC E911 Phase II vertical positioning mandate adoption curves as handset manufacturer demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Safety Certification Investment | ISO 26262 validation unlocks OEM procurement consolidation contracts amid liability transfer restructuring. |
| GDPR-Compliant Regional Data Center Expansion | German automotive suppliers mandate data residency for autonomous test fleet geofencing operations. |
| Bluetooth Low Energy Mesh Platform Launch | Netherlands healthcare networks deploy rapid indoor positioning without dedicated beacon hardware capital. |
| 5G Network Positioning Convergence Partnership | Cellular tower triangulation merges with satellite navigation for seamless indoor-outdoor tracking. |
| API-First Developer Ecosystem Cultivation | India logistics digitization creates first-mover advantage through transport management system integration. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, automotive OEM platform engineers, healthcare IT procurement managers, and cloud API product leads; and secondary validation against SEC hyperscaler capex disclosures, FCC E911 mandate filings, EU AI Act regulatory texts, and automotive production databases. Bottom-up service tier sizing triangulated against top-down geographic demand aggregation.
Across the projection horizon, the analytical framework modeled service type, end-user vertical, technology stack, and application use case dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic infrastructure investment patterns. Forecast inputs incorporated 5G network positioning deployment timelines and EU AI Act compliance cost absorption curves.
The analysis sits within stated boundaries; outcomes outside sustained automotive OEM consolidation, GDPR enforcement intensity, or GNSS chipset supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation pace and cloud infrastructure buildout cadence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Trade Management Software Market
Digital Solutions
API Management Market