
 Mobile Resource Management Solutions Market | 2026-2036
Mobile Resource Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Resource Management Solutions Market Outlook
Aftermarket service revenue is tilting toward recurring platform licensing as fleet operators prioritize predictable operational expenditure models. CalAmp Corporation leverages its cellular gateway heritage to sustain device-to-cloud connectivity margins. Geotab anchors North American market presence through open-platform telematics architecture that competes with closed-ecosystem alternatives.
Mobile resource management solutions encompass integrated hardware-software systems that capture vehicle location, driver behavior, and asset status through GPS receivers, cellular modems, and onboard diagnostics interfaces for centralized fleet command. These systems serve commercial operators seeking to reduce fuel consumption, enforce hours-of-service compliance, and optimize route density across distributed vehicle networks. Software and cloud-based technology segments lead current deployment value as operators shift capital away from dedicated server infrastructure toward subscription analytics platforms. Hardware retains structural importance in emerging fleet segments where ruggedized devices and dual-mode satellite-cellular modems still dominate initial outfitting decisions.
The Federal Motor Carrier Safety Administration's electronic logging device mandate shapes North American product specifications and compliance reporting workflows, while the European Union's General Data Protection Regulation constrains cross-border driver data processing architectures. Japan's Ministry of Economy, Trade and Industry promotes connected vehicle standards that influence regional telematics protocol adoption. Fleet operators and solution vendors must monitor evolving cybersecurity certification requirements as connected vehicle attack surfaces expand.
Market Dynamics
Fleet operators are abandoning capital-intensive server infrastructure in favor of subscription-based cloud analytics platforms, compressing deployment timelines from months to days while reshaping vendor revenue models toward recurring licensing streams.
Growth Catalysts
- FMCSA Electronic Logging Device Mandate:United States federal compliance requirements compel commercial carriers to adopt certified telematics hardware, creating baseline demand for integrated GPS-cellular logging systems across interstate freight operations.
- IoT Sensor Convergence:Multi-modal asset tracking combining temperature, vibration, and fuel-level sensors enables cold-chain logistics operators to monetize real-time cargo condition data through premium service tiers.
- Last-Mile Density Pressures:E-commerce fulfillment networks in Germany and Japan are deploying dynamic route optimization algorithms to reduce per-stop delivery costs amid urban congestion constraints.
Market Restraints
- Semiconductor Supply Concentration:Cellular modem chipset fabrication concentrates among Taiwanese and South Korean foundries, exposing hardware vendors to allocation volatility and extended lead times for ruggedized vehicle gateways.
- GDPRCross-Border Data Friction:European Union data localization requirements constrain centralized fleet analytics architectures, forcing operators to maintain regional data residency infrastructure that fragments platform economics.
- Legacy Radio Substitution:Narrowband push-to-talk systems in municipal and utility fleets resist full telematics displacement due to hardened reliability requirements in emergency response scenarios.
Strategic Opportunities
- India Fleet Formalization:Small commercial vehicle operators in India remain underpenetrated by subscription telematics, presenting whitespace for low-ARPU, high-volume platform models localized to Hindi and regional language interfaces.
- Carbon Accounting Integration:EU CSRD disclosure mandates create demand for fuel consumption telemetry that feeds directly into scope-1 emissions reporting workflows for logistics enterprises.
- Edge-AI Video Analytics:Onboard camera systems with real-time driver behavior inference are converging with traditional GPS tracking, enabling unified safety scoring that insurers in Japan are beginning to reference for premium pricing.
Industry Challenges
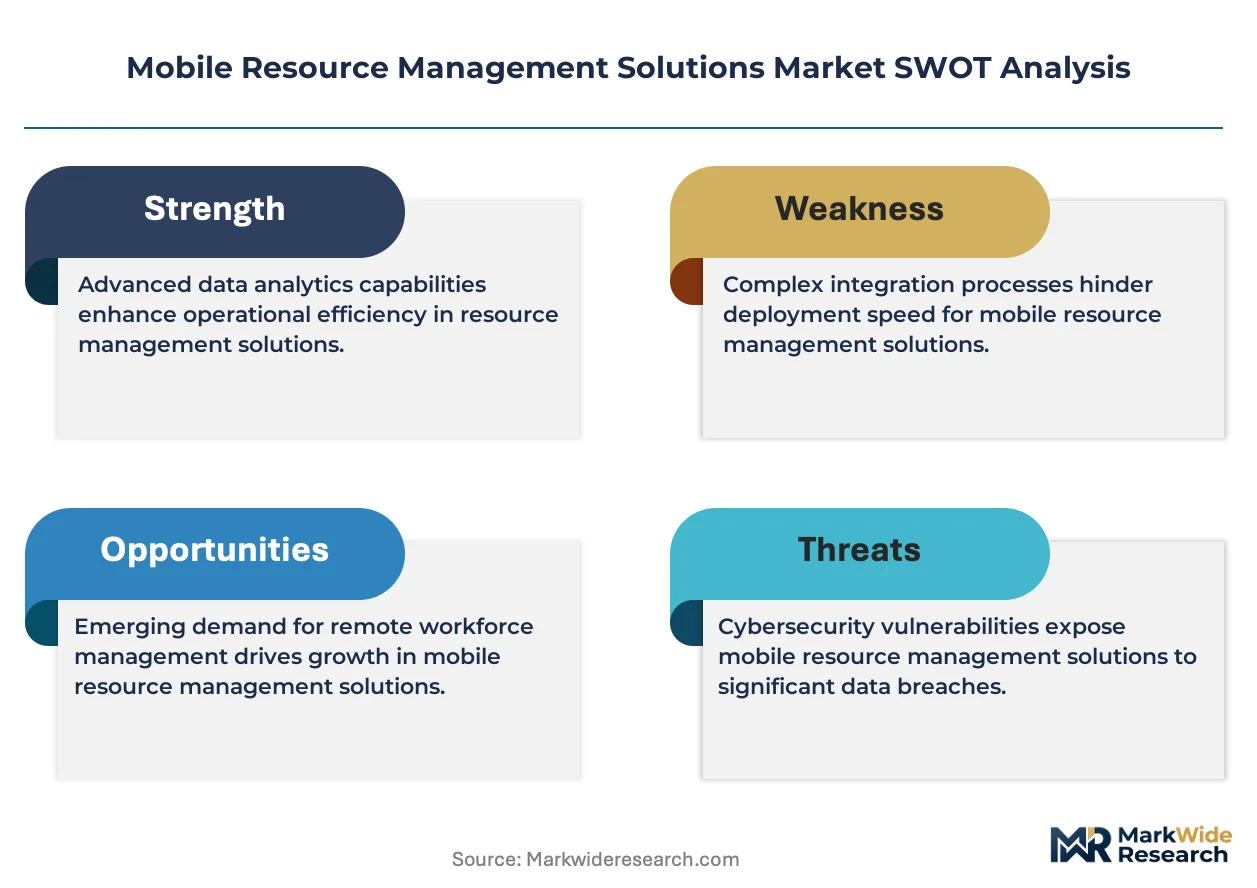
- Cybersecurity Certification Complexity:UN R155 vehicle cybersecurity regulations and emerging ISO/SAE 21434 standards impose multi-year compliance timelines on hardware vendors seeking type approval in regulated markets.
- Legacy Fleet Management System Integration:Enterprise carriers with decades-old dispatch software face API fragmentation and data schema misalignment when connecting cloud-native telematics platforms to on-premise ERP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Resource Management Solutions Market |
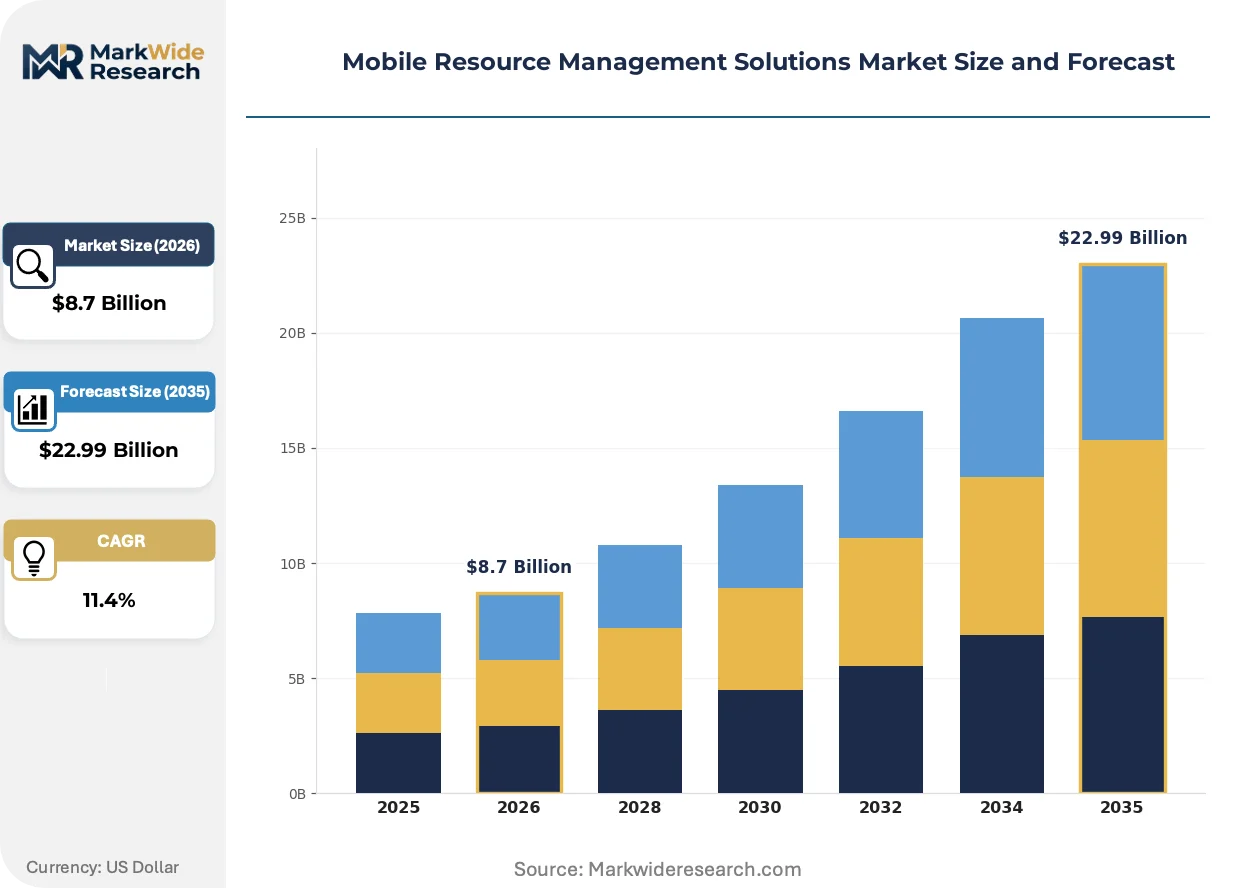
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Solutions, Services Application: Fleet Management, Field Service Management, Asset Tracking, Workforce Management End User: Logistics, Construction, Oil & Gas, Retail Technology: GPS, RFID, IoT, Cloud-Based |
| Companies Covered | AT&T, CalAmp Corporation, Geotab, SkyBitz, Spireon, Fleet Complete, Coretex, ERoad, Lytx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Resource Management Solutions Market Strategic Shifts
Telematics architectures are bifurcating between lightweight smartphone-dependent solutions for small fleets and heavy industrial-grade platforms for enterprise operators, with the middle tier eroding as deployment economics polarize.
Cellular-to-satellite hybrid connectivity modules are rendering obsolete single-mode GPS trackers that lose signal coverage in remote mining corridors and trans-oceanic shipping lanes. Heavy-haul operators in Australian and Canadian resource extraction zones are adopting these dual-network devices at accelerated replacement cycles. The technology is rendering obsolete the historical trade-off between connectivity cost and geographic coverage completeness.
Japan's METI connected vehicle standards and the EU's Cyber Resilience Act are mandating over-the-air update capabilities and incident response protocols for all networked vehicle components. These frameworks compel hardware vendors to maintain decade-long software support commitments that alter product lifecycle economics. Commercial fleet segments in Germany and Japan are responding by prioritizing vendors with demonstrated long-term platform roadmaps over low-cost hardware suppliers.
Small-fleet buyers are consolidating vendor relationships around integrated insurance-telematics bundles that combine hardware, connectivity, and usage-based coverage in single monthly payments. Traditional insurance brokers and independent telematics resellers face disintermediation as direct carrier partnerships capture this segment. This consolidation pattern is most visible in United States commercial auto markets where Progressive and Nationwide have built captive telematics platforms.
Mobile Resource Management Solutions Market Segmentation
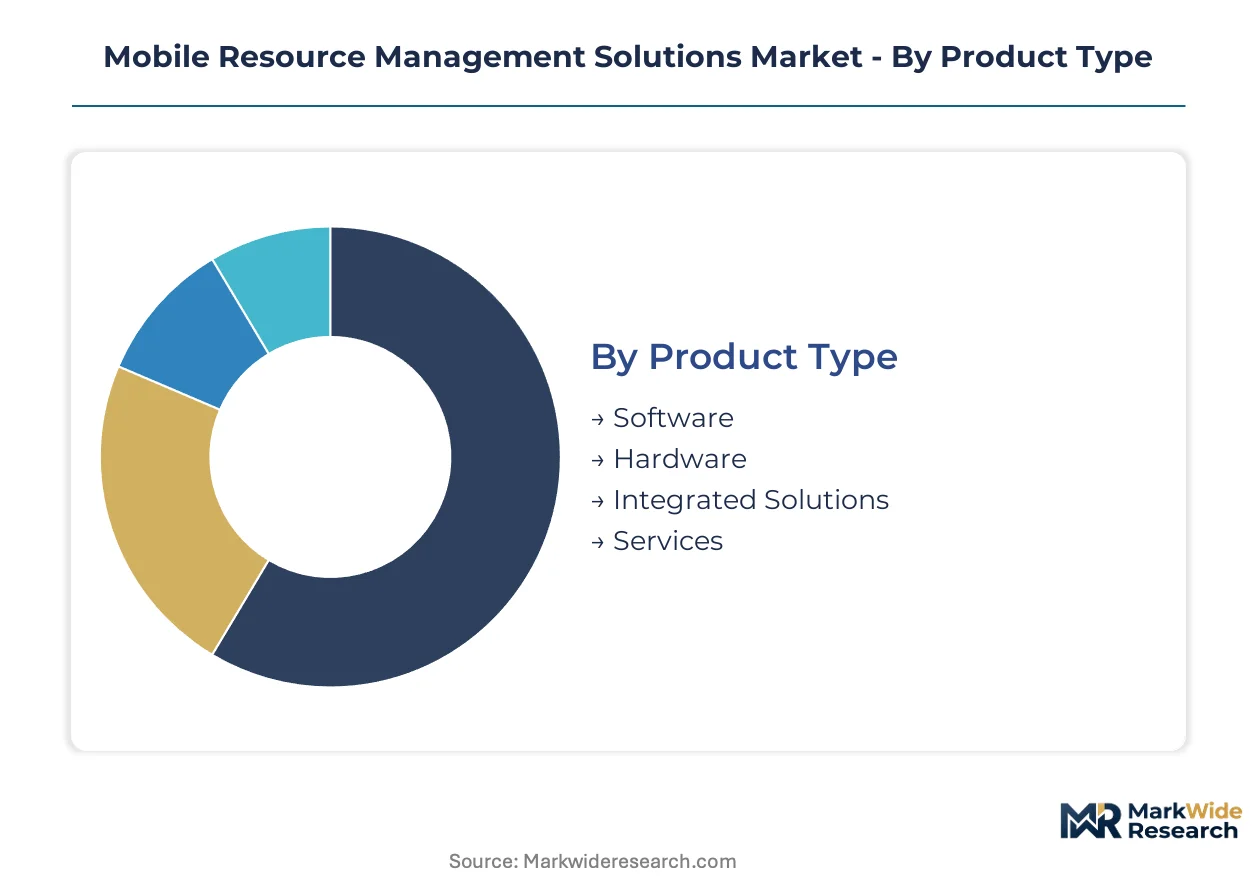
Mobile resource management solutions fragment across hardware-software boundaries, operational use cases, and connectivity modalities. Each segmentation axis reveals distinct procurement patterns and margin structures that vendors must navigate.
Product Type:
Cost tier differentiation separates capital-intensive hardware purchases from recurring software subscriptions, reshaping vendor cash flow profiles.
- Software:Cloud-native analytics platforms process telematics streams into fuel efficiency dashboards and compliance reports. Fleet operators in the United States prioritize these subscription models to convert capital expenditure into predictable operational outlays.
- Hardware:Ruggedized GPS-cellular gateways, OBD-II dongles, and satellite modems form the physical data collection layer. German logistics carriers demand hardened devices with decade-long software support commitments under emerging EU cybersecurity mandates.
- Integrated Solutions:Bundled hardware-software packages with unified support contracts.
- Services:Installation, training, and managed analytics outsourcing.
Hardware commands the established base. The steepest expansion runs through software.
Application:
Operational workflow integration determines deployment complexity and platform stickiness across fleet environments.
- Fleet Management:Real-time vehicle tracking, route optimization, and driver behavior monitoring dominate commercial trucking implementations. Japanese e-commerce fulfillment networks deploy dynamic routing algorithms to compress last-mile delivery windows amid urban density constraints.
- Asset Tracking:Multi-modal cargo monitoring combines temperature, vibration, and location sensors for cold-chain integrity. German pharmaceutical distributors leverage these capabilities to monetize premium service tiers with real-time condition documentation.
- Field Service Management:Technician dispatch coordination with parts inventory visibility.
- Workforce Management:Mobile employee time tracking and task allocation systems.
Fleet management anchors current revenue. Asset tracking is gaining share fastest as sensor convergence accelerates.
End User:
Industry verticals impose divergent durability, connectivity, and compliance requirements on solution specifications.
- Logistics:Interstate freight operators constitute the core demand base, driven by FMCSA electronic logging mandates and fuel cost pressures. United States long-haul carriers represent the most penetrated segment with mature telematics adoption.
- Oil & Gas:Remote extraction operations require satellite-cellular hybrid connectivity for pipeline and equipment monitoring. Canadian oil sands operators deploy these dual-mode devices where terrestrial networks fail.
- Construction:Heavy equipment tracking and unauthorized use prevention.
- Retail:Last-mile delivery fleet optimization for omnichannel fulfillment.
Logistics holds the volume base. Oil & Gas shows the steepest expansion trajectory as remote asset monitoring demands intensify.
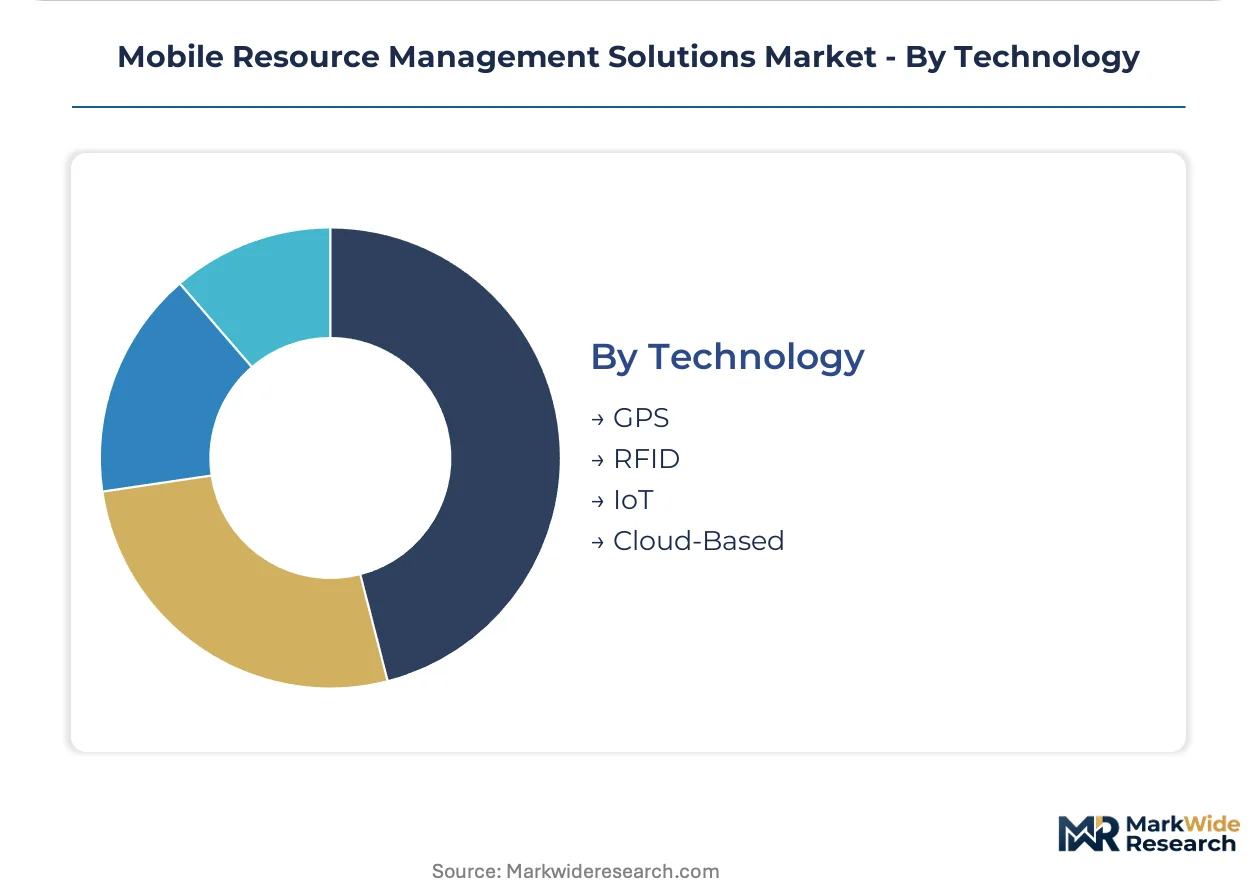
Technology:
Connectivity modality selection dictates coverage completeness, data latency, and infrastructure dependency for deployment architectures.
- Cloud-Based:Centralized data processing and analytics delivery via subscription platforms. Fleet operators across Germany and Japan abandon on-premise servers for these architectures to compress deployment timelines from months to days.
- IoT:Sensor network convergence enabling multi-parameter asset monitoring beyond location alone. Cold-chain logistics in the United States integrate temperature and humidity telemetry for regulatory documentation.
- GPS:Satellite positioning for vehicle and asset location determination.
- RFID:Short-range identification for yard management and inventory tracking.
GPS provides the foundational layer. Cloud-based architectures are climbing the fastest as subscription economics displace capital expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Small-fleet operators in India resist subscription models, while German logistics carriers absorb premium pricing for decade-long software support commitments. United States buyers occupy a middle tier, prioritizing predictable operational expenditure over lowest first cost.
United States
Interstate freight operators drive baseline demand through FMCSA electronic logging device mandates. The Federal Motor Carrier Safety Administration compels certified telematics hardware across commercial trucking fleets. Dallas-Fort Worth and Chicago freight corridors host dense vendor deployment activity for long-haul compliance systems.
Germany
Last-mile e-commerce fulfillment networks compress delivery windows amid urban congestion constraints. The EU General Data Protection Regulation constrains cross-border driver data processing architectures. Rhine-Ruhr logistics clusters maintain regional data residency infrastructure to satisfy localization requirements.
Japan
Metropolitan delivery density pressures accelerate dynamic route optimization algorithm adoption. The Ministry of Economy, Trade and Industry promotes connected vehicle standards influencing regional telematics protocol selection. Tokyo-Osaka freight corridors prioritize vendors with demonstrated long-term platform roadmaps.
India
Small commercial vehicle operators remain underpenetrated by subscription telematics, presenting whitespace for low-ARPU platform models. The country's national automotive regulator enforces localization requirements for connected vehicle components. Maharashtra and Gujarat logistics hubs show early traction for Hindi-localized fleet management interfaces.
Canada
Remote oil sands extraction operations demand satellite-cellular hybrid connectivity where terrestrial networks fail. Transport Canada maintains vehicle cybersecurity certification requirements aligned with UN R155 regulations. Alberta resource extraction zones drive accelerated replacement cycles for dual-network ruggedized gateways.
Mobile Resource Management Solutions Market Competitive Environment
Capability concentration sits with cellular gateway heritage players; scale advantage sits with open-platform telematics architects. The vendor base stratifies across three tiers: integrated hardware-software bundlers, pure-play cloud analytics platforms, and cellular carrier captive offerings. Dominant competitive moves include strategic partnerships between insurers and telematics platforms, plus portfolio diversification into edge-AI video analytics.
Within the cellular heritage tier, CalAmp Corporation and AT&T occupy positions anchored by device-to-cloud connectivity margins. Geotab exemplifies the open-platform archetype competing against closed-ecosystem alternatives. Fleet Complete represents the integrated bundler model serving mid-market operators seeking unified support contracts.
| Leading Market Players |
|---|
| AT&T |
| CalAmp Corporation |
| Geotab |
| SkyBitz |
| Spireon |
| Fleet Complete |
| Coretex |
| ERoad |
| Lytx |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwanese cellular modem foundries is compressing hardware margins while amplifying pricing power for semiconductor suppliers serving ruggedized vehicle gateway manufacturers. Fleet operators absorb these cost transfers through elongated subscription contracts that convert capital volatility into predictable operational expenditure.
Pricing Analysis
Recurring platform licensing revenue drives lifetime value for solution vendors as fleet operators abandon perpetual hardware purchases. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade analytics bundles from lightweight smartphone-dependent offerings for small fleets. Pricing pressure stems from semiconductor allocation volatility and extended lead times for cellular chipsets. Small-fleet operators in India exhibit highest price sensitivity, resisting subscription models in favor of low-ARPU transactional arrangements.
Supply Chain Analysis
Cellular modem chipset fabrication draws from Taiwan, South Korea, and mainland China foundries, exposing hardware vendors to geographic concentration risk. Ruggedized GPS gateways rest on GPS receivers, cellular modems, and onboard diagnostics interfaces as core component inputs. Single-source vulnerability in Taiwanese semiconductor fabrication creates allocation volatility for vehicle gateway manufacturers. Distribution runs through direct carrier partnerships, independent telematics resellers, and integrated hardware-software bundlers serving mid-market fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Resource Management Solutions Market sits in early-cycle expansion as FMCSA electronic logging mandates and EU carbon disclosure regulations accelerate telematics penetration among previously unserved fleet segments.
For Market Incumbents: Entrench platform stickiness through decade-long software support commitments that satisfy emerging EU Cyber Resilience Act requirements. Deepen backward integration into cellular gateway manufacturing to mitigate Taiwanese foundry allocation volatility threatening hardware margins. Prioritize certification investment for UN R155 vehicle cybersecurity compliance ahead of regulatory deadlines. For New Entrants and Emerging Players: Build out low-ARPU, high-volume platform models localized to Hindi and regional Indian language interfaces where small commercial vehicle operators remain underpenetrated. Target cold-chain logistics asset tracking applications in Germany where pharmaceutical distributors monetize premium service tiers through real-time condition documentation. Pursue direct insurance carrier partnerships to capture disintermediated telematics-insurance bundles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native analytics platforms with demonstrated long-term roadmaps in Japan and Germany. Five-to-ten year viability favors vendors with cellular gateway heritage sustaining device-to-cloud connectivity margins. Monitor edge-AI video analytics convergence with traditional GPS tracking as inflection indicator for unified safety scoring adoption by Japanese insurers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telematics streams with ERP systems to resolve API fragmentation in legacy fleet management environments. |
| Geographic Expansion | Captures whitespace in Indian logistics hubs through Hindi-localized interfaces and low-ARPU subscription models. |
| Strategic Partnership | Combines telematics hardware with usage-based insurance coverage in single monthly payments for small-fleet consolidation. |
| Acquisition of Specialist Firm | Adds edge-AI video analytics capabilities for real-time driver behavior inference converging with GPS tracking. |
| Product Launch | Introduces cellular-to-satellite hybrid connectivity modules replacing obsolete single-mode GPS trackers in remote extraction zones. |
Study Parameters
Initial hypotheses were tested against primary input from fleet operations directors, telematics platform engineers, cellular carrier partnership managers, and aftermarket service heads, then refined against secondary validation. SEC 10-K filings, FMCSA compliance certification databases, EU regulatory submission records, and customs trade data provided quantitative grounding. Bottom-up fleet penetration estimates and top-down market sizing were triangulated to reconcile segment-level demand with aggregate value projections.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation across deployment model, fleet size tier, vertical application, connectivity modality, and regional regulatory cluster. CAGRs were derived from installed base growth rates and average revenue per user trajectories. Forecast inputs incorporated FMCSA mandate compliance timelines, EU CSRD disclosure phase-ins, and semiconductor foundry capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by cellular carrier captive offerings or hyperscaler cloud platforms would shift outcomes. Regulatory acceleration in vehicle cybersecurity certification or data localization requirements could compress deployment timelines. Cross-checking against fleet operator capex surveys and telematics vendor booking disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
India PLM Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
China Digital Twin Market
Digital Solutions
AQI App Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Global Tracking As a Service Market