
 Global Configuration Management Software Market | 2026-2036
Global Configuration Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Configuration Management Software Market Foresight
Perpetual license revenue is narrowing as subscription and consumption-based pricing models capture a larger share of customer lifetime value. Microsoft Corporation leverages its Azure ecosystem to embed configuration management within broader cloud service bundles. ServiceNow Inc. anchors its position by linking configuration data to IT service management workflows. HashiCorp Inc. specializes in infrastructure-as-code tooling that appeals to DevOps-centric buyers seeking programmable control.
Configuration management software automates the tracking, maintenance, and governance of hardware and software configurations across distributed IT environments, typically operating through agent-based or agentless discovery mechanisms that maintain centralized configuration item databases. Its primary purpose is to ensure system consistency, accelerate incident resolution, and enforce compliance against defined baselines. Cloud deployment now leads spending as enterprises abandon capital-intensive on-premises data centers, while change management solutions within the solution type category command premium pricing due to their direct impact on audit readiness and uptime guarantees.
The U.S. Federal Risk and Authorization Management Program (FedRAMP) and the EU NIS2 Directive are reshaping procurement criteria by mandating continuous configuration monitoring for critical infrastructure operators. ISO/IEC 20000 service management standards further reinforce baseline requirements for configuration control in outsourced IT environments. Stakeholders must weigh the trade-off between platform consolidation and best-of-breed specialization as vendor ecosystems expand beyond traditional IT operations into security and FinOps domains.
Market Dynamics
Multi-cloud sprawl is forcing enterprise IT departments to abandon manual configuration tracking in favor of automated, policy-driven governance tools that enforce consistency across distributed infrastructure estates.
Growth Catalysts
- EU NIS2 Directive:The directive mandates continuous configuration monitoring for critical infrastructure operators across member states, compelling energy and transport sectors to upgrade legacy systems.
- Industry 4.0 integration:German industrial manufacturers are embedding configuration management into smart factory deployments to maintain operational technology alignment with IT systems.
- Agentless discovery mechanisms:These technologies reduce deployment friction in containerized environments, accelerating adoption among DevOps teams managing ephemeral cloud workloads.
Market Restraints
- Skill scarcity in infrastructure-as-code:Organizations face prolonged hiring cycles for Terraform and Ansible specialists, delaying implementation timelines.
- Vendor lock-in risks:Deep integration with hyperscaler ecosystems creates switching costs that deter mid-market buyers from committing to platform-native solutions.
- Legacy asset persistence:Mainframe and on-premises hardware estates resist automated discovery, fragmenting configuration databases and diluting governance coverage.
Strategic Opportunities
- FinOps convergence:Configuration data linked to cloud cost analytics enables chargeback accuracy and waste identification, opening new buyer budgets.
- India's digital infrastructure buildout:Data center expansion under the country's PLI scheme creates demand for configuration tools that manage hybrid cloud estates.
- Security posture integration:Merging configuration drift detection with vulnerability management addresses CISO priorities for attack surface reduction.
Industry Challenges
- CMDB accuracy maintenance:Configuration item databases degrade rapidly without automated reconciliation, undermining incident response and change advisory board decisions.
- Cross-functional alignment:IT operations, security, and finance teams maintain conflicting data models, complicating unified configuration governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Configuration Management Software Market |
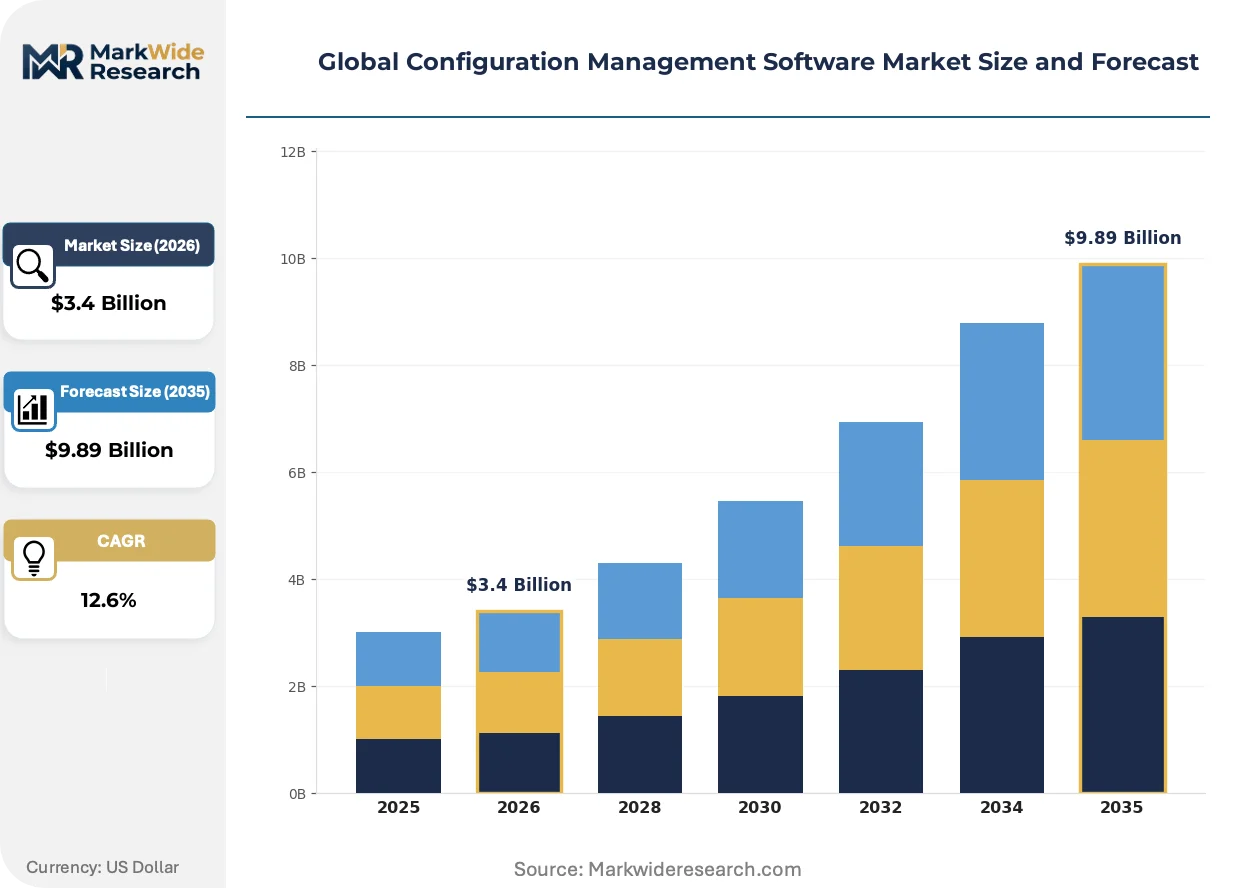
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.89 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Private Cloud, Public Cloud Solution Type: Continuous Integration, Change Management, Asset Management, Compliance Management, Version Control Application: Software Development, IT Operations, Network Management, Database Management, Application Lifecycle Management End User Industry: Telecommunications, Financial Services, Manufacturing, Healthcare Providers, Government Agencies |
| Companies Covered | Oracle Corporation, Hewlett Packard Enterprise Development LP, Amazon Web Services Inc., BMC Software Inc., VMware Inc., Microsoft Corporation, ServiceNow Inc., HashiCorp Inc., International Business Machines Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Configuration Management Software Market Shifts & Advancements
Configuration management is converging with adjacent IT disciplines as buyers reject point solutions in favor of integrated platforms that span operations, security, and financial accountability.
GitOps workflows are rendering obsolete traditional push-based configuration deployment models. Platform engineering teams at software-centric enterprises are adopting declarative infrastructure definitions stored in version control. This shift is compressing the market for standalone configuration agents that require manual orchestration.
REACH compliance obligations in Europe are extending chemical industry requirements into software supply chains, mandating software bill of materials documentation for configuration tools that manage manufacturing execution systems. Process industry buyers in Germany and the Netherlands are prioritizing vendors with pre-built compliance templates.
Consumption-based pricing is displacing perpetual licensing for configuration management modules. Enterprise buyers in North America are negotiating usage-tiered contracts tied to node counts or API call volumes. This pattern is most visible among SaaS-native vendors serving mid-market technology companies with variable infrastructure scaling needs.
Global Configuration Management Software Market Segmentation
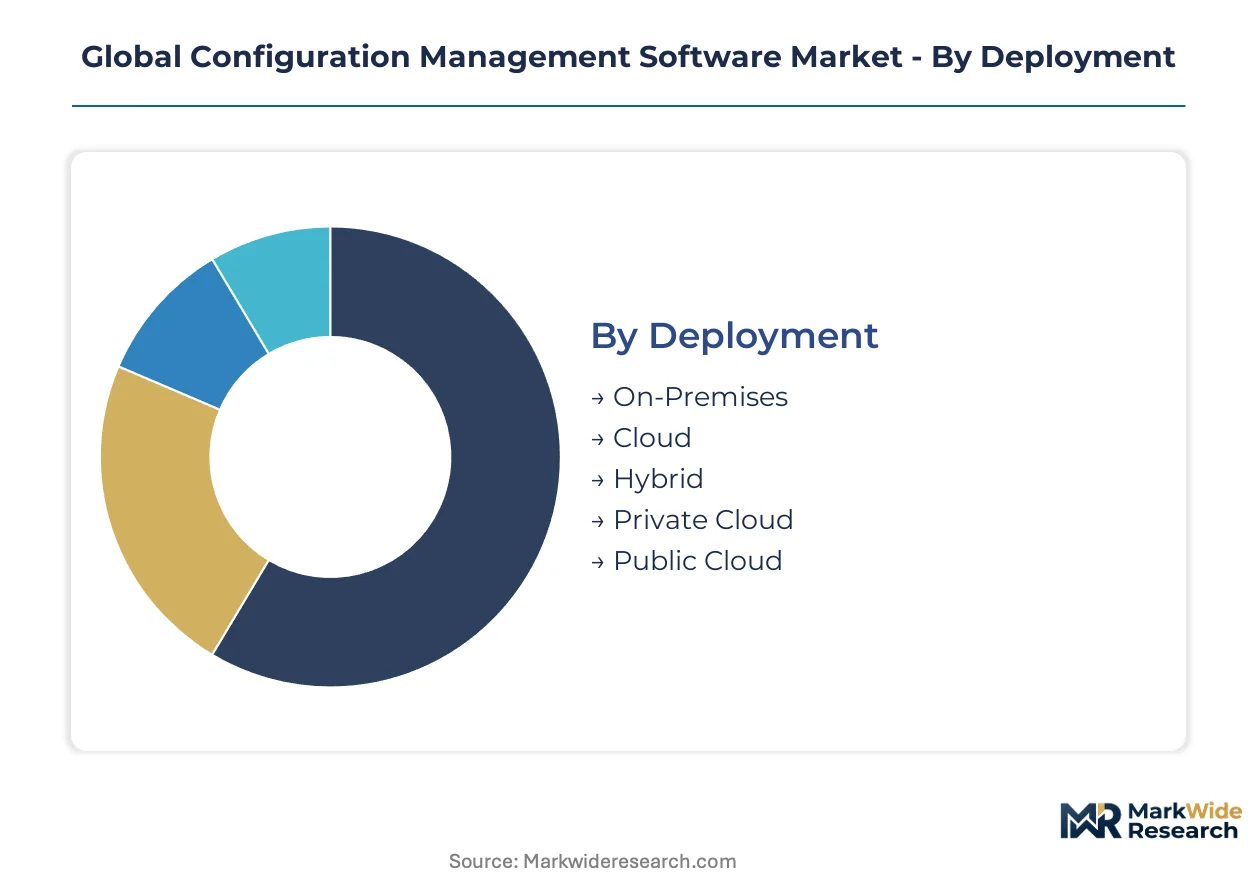
Configuration management software segments reflect divergent technical requirements across deployment architectures, operational workflows, and regulatory environments. Buyers prioritize segments that minimize integration friction with existing toolchains while satisfying sector-specific compliance mandates.
Deployment:
After-sales service intensity varies sharply across deployment modes, with cloud-native implementations demanding continuous vendor engagement for patch management and API compatibility maintenance.
- Cloud:Multi-tenant SaaS architectures eliminate infrastructure provisioning overhead for buyers. German automotive suppliers and Dutch chemical manufacturers favor this mode to satisfy EU NIS2 Directive monitoring requirements without capital expenditure.
- Hybrid:Split workloads between on-premises control planes and cloud-based data lakes address sovereignty concerns. India's data center operators under the PLI scheme deploy hybrid stacks to retain sensitive configuration data domestically while leveraging global analytics.
- On-Premises:Air-gapped installations persist in defense and classified government facilities requiring physical network isolation.
- Private Cloud:Single-tenant virtualized environments serve financial institutions with dedicated compliance boundaries.
- Public Cloud:Shared infrastructure pools suit mid-market technology firms with variable scaling needs and limited operational staff.
Cloud holds the largest share; momentum sits with hybrid configurations bridging sovereignty and agility requirements.
Solution Type:
Cost tier differentiation separates premium workflow-orchestration modules from baseline repository tools, with pricing scaling linearly against audit automation depth.
- Change Management:Formalized approval gates and rollback orchestration protect production stability. Financial services buyers in London and Singapore pay premium licensing for change advisory board integration that satisfies Basel operational risk frameworks.
- Compliance Management:Automated evidence collection and control mapping reduce audit preparation labor. Healthcare providers across the US deploy these modules to streamline HIPAA security rule documentation.
- Continuous Integration:Pipeline-triggered configuration validation accelerates software delivery velocity.
- Asset Management:Hardware and software inventory reconciliation maintains CMDB accuracy for incident correlation.
- Version Control:Baseline snapshotting and drift detection preserve configuration state history.
Change Management commands premium pricing; Compliance Management is expanding most quickly under tightening sectoral mandates.
Application:
Customer type concentration shapes feature roadmaps, with enterprise IT operations teams demanding broader ecosystem connectors than specialized development shops.
- IT Operations:Event correlation and automated remediation reduce mean time to resolution for infrastructure incidents. Telecommunications carriers in South Korea and Brazil prioritize these capabilities to maintain SLA commitments across distributed cell tower networks.
- Software Development:Environment parity enforcement eliminates configuration drift between staging and production. DevOps teams at SaaS vendors in Tel Aviv and Toronto adopt infrastructure-as-code integration to accelerate release cadence.
- Network Management:Device configuration templating and bulk policy push streamline router and switch administration.
- Database Management:Schema versioning and parameter standardization protect data platform stability.
- Application Lifecycle Management:Cross-stage traceability links requirements to deployed configurations.
IT Operations maintains dominant deployment volume; Software Development exhibits the steepest expansion trajectory as platform engineering matures.
End User Industry:
Margin profiles diverge across verticals, with regulated sectors accepting higher per-seat costs in exchange for pre-validated control frameworks and vendor audit support.
- Financial Services:Real-time configuration drift detection supports fraud prevention and trading system integrity. Banks in Switzerland and Australia mandate these tools under national operational resilience standards enforced by FINMA and APRA respectively.
- Government Agencies:Classification-bound procurement and FedRAMP authorization requirements favor established vendors with existing authority-to-operate credentials. US federal and state entities drive demand for on-premises deployment modes.
- Telecommunications:Massive infrastructure scale necessitates automated discovery across heterogeneous equipment generations.
- Manufacturing:OT-IT convergence in smart factories extends configuration governance to industrial control systems.
- Healthcare Providers:Patient data protection priorities elevate security configuration validation above functional feature breadth.
Financial Services contributes the highest revenue per deployment; Government Agencies are gaining share fastest through digital modernization appropriations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity, absorbing premium licensing for compliance-integrated suites, while mid-market technology firms in India and Brazil negotiate aggressively on consumption-tiered contracts.
United States
Federal modernization appropriations and FedRAMP authorization requirements drive procurement from defense contractors and civilian agencies. The US Federal Risk and Authorization Management Program mandates continuous configuration monitoring for cloud service providers. Washington DC and Northern Virginia host dense clusters of system integrators deploying multi-cloud governance tools for intelligence community clients.
Germany
Industrial manufacturers embedding configuration management into Industry 4.0 deployments generate concentrated demand from automotive and chemical sectors. The EU NIS2 Directive compels energy and transport operators to upgrade legacy monitoring systems. Stuttgart and Munich manufacturing corridors prioritize vendors offering pre-built templates for REACH compliance in software supply chains.
United Kingdom
Financial services buyers in London pay premium licensing for change advisory board integration satisfying Basel operational risk frameworks. The Financial Conduct Authority's operational resilience rules enforce configuration drift detection for trading infrastructure. The City of London and Canary Wharf fintech clusters drive demand for real-time synchronization between development and production environments.
India
Data center expansion under the PLI scheme creates demand for hybrid cloud configuration tools among domestic operators and hyperscaler local zones. The country's central bank guidelines on IT governance push scheduled commercial banks toward automated baseline enforcement. Mumbai and Bangalore technology corridors exhibit steep adoption curves among platform engineering teams at SaaS exporters.
Japan
Telecommunications carriers prioritize automated discovery across heterogeneous equipment generations to maintain SLA commitments across distributed cell tower networks. METI's cybersecurity framework for critical infrastructure mandates configuration item documentation for industrial control systems. Tokyo and Osaka enterprise IT departments favor agentless mechanisms to reduce deployment friction in containerized environments.
Global Configuration Management Software Market Competitive Landscape
Capability concentration sits with specialized infrastructure-as-code vendors; scale advantage sits with hyperscaler ecosystems bundling configuration modules within broader cloud service portfolios. The market structure reflects a tiered hierarchy where platform consolidators compete against best-of-breed specialists for DevOps-centric buyers. Dominant archetypes include cloud-native SaaS providers, legacy enterprise software incumbents, and open-source tooling specialists. Competitive moves center on strategic partnerships linking configuration data to adjacent IT disciplines and portfolio diversification into FinOps and security posture management.
Within the cloud-native tier, HashiCorp Inc. and ServiceNow Inc. exemplify divergent strategic positioning—one anchoring programmable infrastructure control for engineering-led buyers, the other linking configuration databases to IT service management workflows for operations-centric procurement committees. Microsoft Corporation occupies a scale-driven position leveraging Azure ecosystem integration to embed configuration governance within existing enterprise relationships. These three companies represent the archetype spectrum from specialized DevOps tooling to integrated platform suites.
| Leading Market Players |
|---|
| Oracle Corporation |
| Hewlett Packard Enterprise Development LP |
| Amazon Web Services Inc. |
| BMC Software Inc. |
| VMware Inc. |
| Microsoft Corporation |
| ServiceNow Inc. |
| HashiCorp Inc. |
| International Business Machines Corporation |
| Others |
Supply & Pricing Matrix
Specialized DevOps tooling talent clusters in the San Francisco Bay Area and Tel Aviv, anchoring premium margin capture in the infrastructure-as-code tier where Terraform and Ansible expertise commands outsized licensing leverage.
Pricing Analysis
Extended professional services and managed support contracts drive lifetime value as enterprise buyers negotiate multi-year subscriptions bundled with implementation assistance. SaaS-tiered pricing stratifies across enterprise, mid-market, and developer tiers, with differentiation hinging on API call volumes and node count thresholds. Cost compression in the mid-market tier is intensifying because hyperscaler bundling erodes standalone vendor pricing power. Government agencies and regulated financial institutions exhibit lowest price sensitivity, absorbing premium licensing for FedRAMP-authorized and compliance-integrated suites.
Supply Chain Analysis
US export controls on advanced cloud orchestration technologies limit flows of certain encryption-enhanced configuration agents to designated markets, constraining vendor distribution strategies. Software development concentrates in the United States, Ireland, and India, with Indian engineering centers feeding global SaaS delivery infrastructure. Cloud compute capacity, open-source repository access, and API ecosystem partnerships constitute critical input dependencies. Single-source vulnerability in hyperscaler infrastructure creates concentration risk for multi-tenant SaaS vendors. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organizations face prolonged hiring cycles for infrastructure-as-code specialists, compressing implementation timelines and elevating services-dependent vendors who can bridge capability gaps.
For Market Incumbents: Harden platform stickiness by deepening integration with IT service management workflows and security posture management tools, defending against hyperscaler bundling that threatens standalone pricing power. Prioritize certification investment in FedRAMP and EU NIS2 compliance to maintain procurement eligibility in regulated sectors. For New Entrants and Emerging Players: India's domestic data center operators under the PLI scheme represent underpenetrated demand for hybrid cloud configuration governance, offering white-space expansion without direct hyperscaler competition. Target mid-market SaaS exporters in Bangalore and Mumbai with consumption-based pricing and localized support capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SaaS-native configuration management as cloud infrastructure commoditizes delivery infrastructure. Platform engineering tooling specialists with established GitOps workflows represent viable acquisition targets. Watch hyperscaler partnership announcement velocity as an inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding configuration agents within Azure and AWS marketplaces captures procurement workflows. |
| Strategic Partnership | Alliances with ServiceNow and BMC link configuration data to incident response pipelines. |
| Acquisition of Specialist Firm | Buying Terraform or Ansible expertise accelerates infrastructure-as-code capability depth. |
| Geographic Expansion | Establishing delivery centers in India and Germany addresses PLI scheme and NIS2 demand. |
| Product Launch | Introducing FinOps-integrated modules opens chargeback and cloud cost optimization budgets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory documentation. Interviews with CTOs, IT procurement officers, platform engineers, and channel partners informed demand-side validation. Bottom-up sizing of vendor revenue streams and top-down cross-check against enterprise software spending patterns ensured triangulation integrity.
Forecast inputs include deployment model adoption curves, organization size penetration rates, vertical regulatory intensity, and regional cloud infrastructure buildout trajectories. Segmentation dimensions span deployment architecture, solution type, application workflow, and end-user industry vertical. CAGRs derive from regression analysis of historical spending patterns against projected infrastructure expansion. Hyperscaler partnership velocity and compliance mandate implementation timelines constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive bundling moves by Microsoft or Amazon Web Services would shift outcomes beyond modeled parameters. Material shifts in EU NIS2 enforcement rigor or FedRAMP authorization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Relational Database Management System Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Image Analysis Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
SRM Software Market
Software & Services
Global Translation Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Runtime Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Digital Illustration App Market
Software & Services
Global Backup Restore Software Market
Software & Services
Data Preparation Tools Market
Software & Services
Business Analytics Software Market
Software & Services
Category Management Software Market