
 Distributed Order Orchestration Market | 2026-2036
Distributed Order Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Order Orchestration Market Analytics
Modular solution bundling is hardening as the dominant procurement pattern, with buyers favoring composable platforms over monolithic suites. Oracle Corporation leverages deep ERP integration to anchor enterprise accounts in complex manufacturing environments. SAP SE competes through native supply-chain connectivity that sustains renewal rates among European industrials. Blue Yonder Group Inc. specializes in AI-native fulfillment optimization, differentiating its position in grocery and pharmaceutical verticals where shelf-life constraints dominate routing logic.
Distributed order orchestration denotes a software architecture that automates order promising, sourcing, and fulfillment across heterogeneous inventory nodes through real-time API mesh and event-driven logic. Its primary commercial purpose is to minimize split shipments, reduce stockouts, and optimize last-mile cost by dynamically matching demand signals with available-to-promise inventory. Cloud-based deployment leads absolute spend as enterprises retire legacy on-premises order-management systems, while hybrid configurations capture the fastest growth among mid-market retailers seeking phased migration paths. AI-driven automation concentrates margin pools in predictive exception handling and autonomous replenishment triggers, though API integration remains the foundational enabler that unlocks multi-node visibility.
The EU AI Act imposes risk-classification requirements on automated order-routing decisions, compelling vendors to embed explainability layers and human-in-the-loop protocols. The US Federal Trade Commission scrutinizes algorithmic pricing collusion risks embedded in dynamic fulfillment optimization, shaping how platforms architect competitive-intelligence firewalls. ISO 27001 and SOC 2 Type II certifications increasingly gate enterprise procurement, particularly among healthcare and financial-services end users bound by HIPAA and SEC cybersecurity rules. Stakeholders must weigh the trade-off between real-time automation depth and audit-ready transparency as regulatory scrutiny intensifies across jurisdictions.
Market Dynamics
Cloud migration mandates under Europe's GDPR and the EU AI Act are forcing enterprises to modernize fragmented order-management stacks, while labor shortages across fulfillment networks accelerate automation procurement.
Growth Catalysts
- GDPR-driven platform modernization:European retailers must retire legacy on-premises systems to achieve data sovereignty compliance, creating replacement demand for cloud-native orchestration architectures with embedded privacy controls.
- Omnichannel complexity:United States-based e-commerce retailers require unified inventory visibility across fragmented fulfillment nodes to minimize split shipments and optimize last-mile routing decisions.
- AI-native fulfillment optimization:Grocery and pharmaceutical verticals deploy predictive exception handling to manage shelf-life constraints and autonomous replenishment triggers across temperature-controlled distribution networks.
Market Restraints
- API integration complexity:Heterogeneous inventory nodes running disparate ERP systems require expensive custom middleware development before real-time event-driven orchestration becomes operational.
- EU AI Act compliance costs:Risk-classification requirements for automated order-routing decisions mandate explainability layers and human-in-the-loop protocols that extend deployment timelines and inflate professional services spend.
- Concentrated cloud infrastructure dependency:Mid-market retailers face vendor lock-in risks as hyperscale providers capture orchestration platform hosting, limiting negotiation leverage over data egress and compute pricing.
Strategic Opportunities
- Hybrid deployment models:Mid-market retailers in Germany and France seek phased migration paths combining on-premises order promising with cloud-based fulfillment optimization to manage capex cycles.
- ISO 27001 certification arbitrage:Healthcare and financial-services end users bound by HIPAA and SEC cybersecurity rules will pay premiums for vendors with pre-certified audit-ready transparency architectures.
- Edge computing convergence:Integration of IoT sensor streams with distributed order orchestration enables real-time inventory positioning in autonomous warehouse robotics and drone last-mile networks.
Industry Challenges
- Explainable AI talent scarcity:Vendors struggle to recruit engineers capable of embedding interpretability layers into neural network-based routing algorithms without degrading sub-second decision latency.
- Legacy system integration friction:Enterprises running decades-old mainframe-based order management face data schema incompatibilities that prolong API mesh deployment and inflate professional services margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Order Orchestration Market |
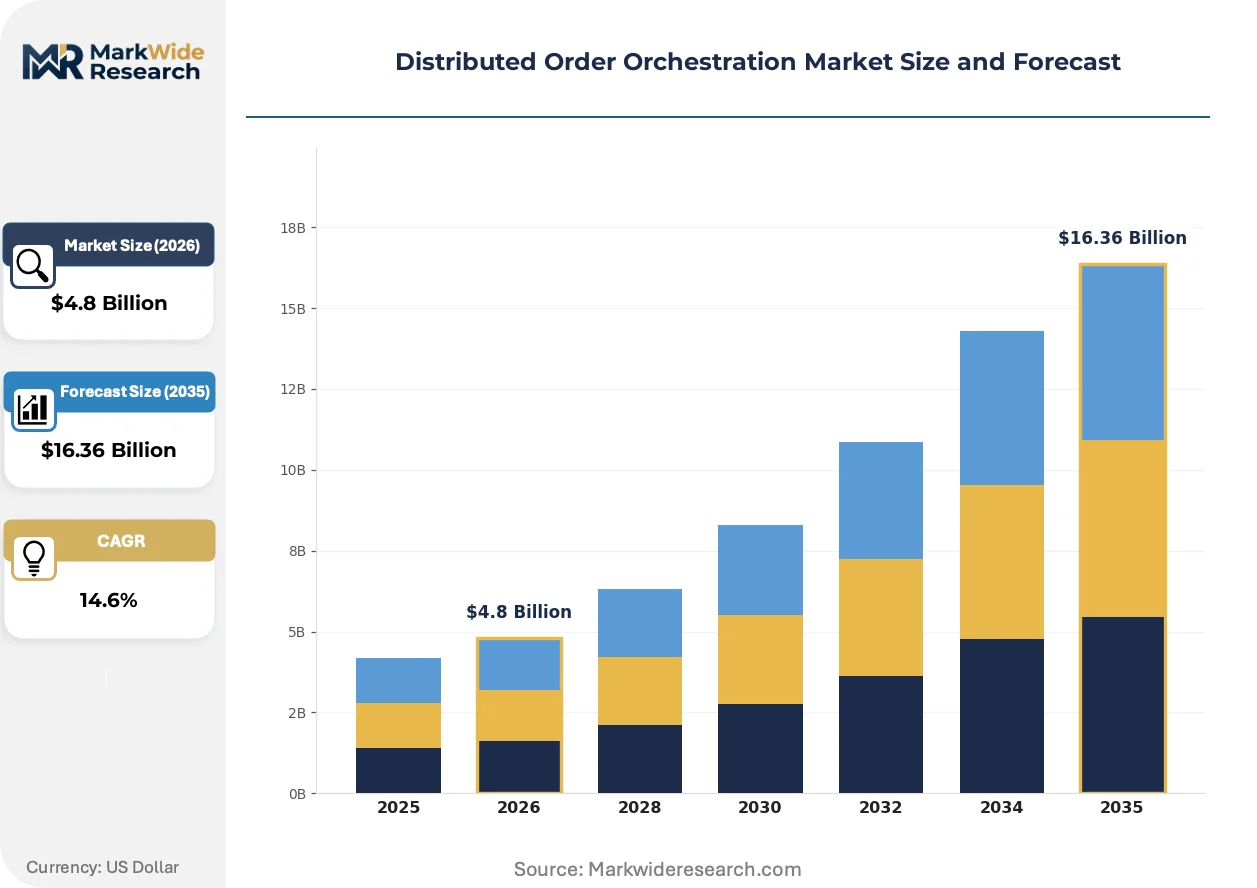
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Retail, E-Commerce, Manufacturing, Logistics Solution Type: Inventory Management, Shipping Optimization, Order Processing, Reporting Tools Technology: AI-Driven Automation, API Integration, Machine Learning, Data Analytics |
| Companies Covered | Oracle Corporation, IBM Corporation, SAP SE, Salesforce Inc., Microsoft Corporation, Manhattan Associates, E2open Inc., Kinaxis Inc., Blue Yonder Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Order Orchestration Market Evolving Landscape
Event-driven architecture is displacing batch-processing paradigms across order orchestration stacks, compressing inventory promising windows from hours to milliseconds while enabling dynamic fulfillment network reconfiguration.
Composable microservices architecture is overtaking monolithic suite deployments. Cloud-native API meshes enable retailers to swap individual orchestration components without platform-wide replacement. Mid-market buyers in the United States and United Kingdom favor this modular bundling to preserve existing ERP investments while layering best-of-breed fulfillment optimization.
The EU AI Act's risk-classification framework is reshaping vendor development roadmaps. Automated order-routing systems now require embedded audit trails and human override capabilities before deployment in European markets. Healthcare distributors bound by MDR traceability requirements face the steepest compliance burdens, driving consolidation toward vendors with pre-built explainability modules.
Subscription-based platform licensing is displacing perpetual software ownership in procurement patterns. Enterprise buyers favor consumption-aligned pricing tied to order volume or node count rather than upfront capex commitments. This shift concentrates most visibly among United States-based omnichannel retailers managing seasonal demand volatility across fragmented fulfillment networks.
Distributed Order Orchestration Market Segmentation
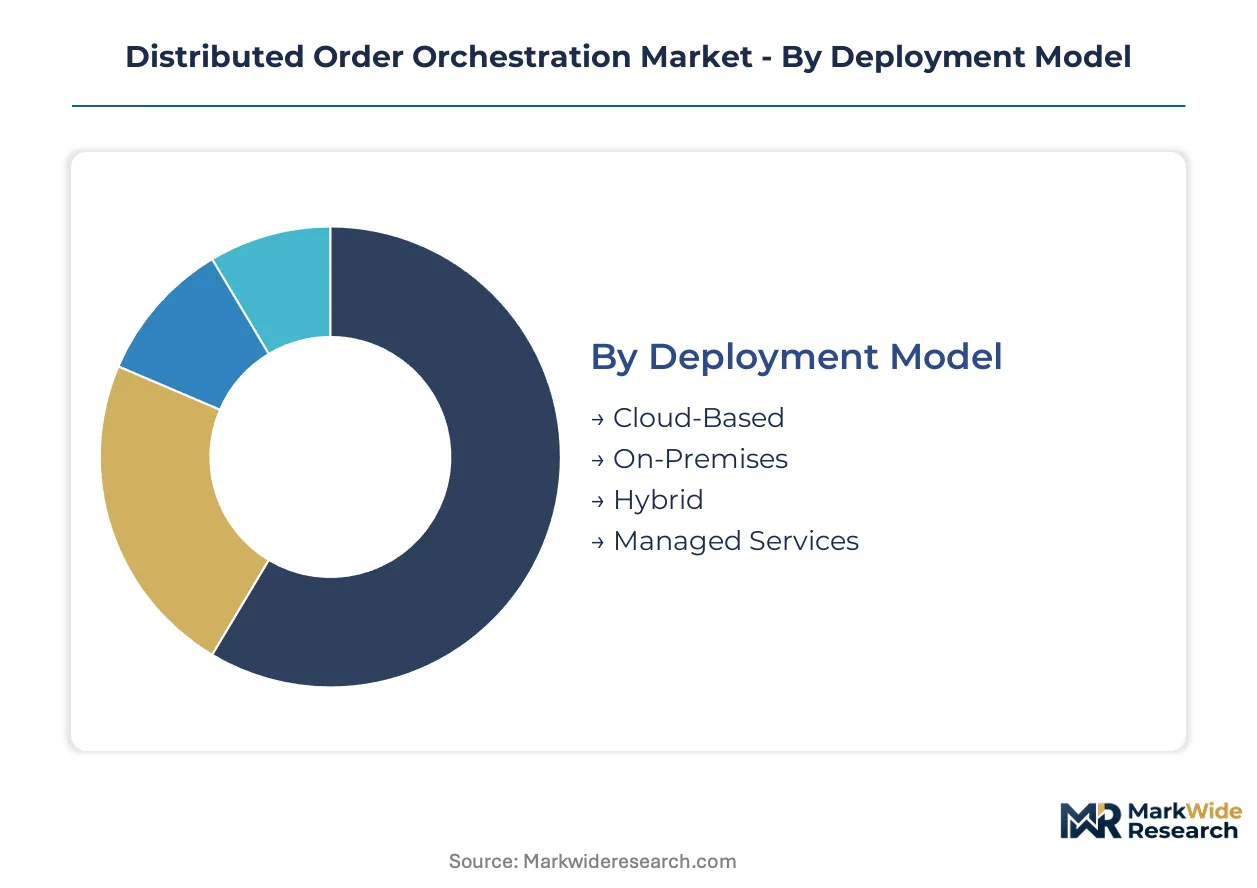
Distributed order orchestration platforms serve heterogeneous buyer profiles with divergent technical debt tolerance, compliance burdens, and automation maturity. Segmentation reveals where procurement budgets concentrate and which architectural approaches capture expansion opportunities across fragmented fulfillment networks.
Deployment Model:
Cost tier separates buyers in this category, with capital availability and risk tolerance determining architecture selection.
- Cloud-Based:Multi-tenant SaaS architectures with auto-scaling compute and embedded GDPR data-sovereignty controls dominate enterprise replacement cycles. Retailers in Germany and France prioritize these platforms to retire legacy on-premises stacks while minimizing upfront capex exposure.
- Hybrid:Split configurations combining on-premises order promising engines with cloud-based fulfillment optimization capture mid-market retailers seeking phased migration paths. United States-based omnichannel operators favor this model to preserve existing ERP investments while layering AI-native routing capabilities.
- On-Premises:Single-tenant installations persist among defense contractors and classified supply chains with air-gapped security mandates.
- Managed Services:Third-party operated platforms appeal to small e-commerce merchants lacking internal DevOps capacity.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations.
End User:
Application context dictates functional requirements, with vertical-specific constraints shaping vendor selection criteria.
- E-Commerce:Pure-play digital retailers require real-time inventory visibility across fragmented drop-ship networks and third-party logistics nodes. United States-based operators drive demand for sub-second promising engines capable of minimizing split shipments across distributed fulfillment centers.
- Retail:Brick-and-mortar chains with omnichannel footprints need unified stock pools connecting stores, dark stores, and regional distribution centers. European grocery operators under MDR traceability requirements prioritize platforms with embedded audit trails for temperature-controlled routing decisions.
- Manufacturing:Make-to-order and engineer-to-order producers leverage orchestration for available-to-promise calculations across multi-echelon supply networks.
- Logistics:Third-party fulfillment providers white-label orchestration capabilities to offer value-added inventory positioning services to shipper clients.
Revenue concentrates in E-Commerce; Retail represents the steepest expansion trajectory.
Solution Type:
Margin pools vary by functional depth, with predictive capabilities commanding premium pricing over transactional modules.
- Inventory Management:Real-time ATP engines with multi-node visibility and safety-stock optimization anchor platform value propositions. Pharmaceutical distributors deploy these modules to manage shelf-life constraints across temperature-controlled networks.
- Shipping Optimization:Dynamic carrier selection and last-mile cost minimization algorithms concentrate demand among high-volume e-commerce operators facing margin compression from free shipping expectations.
- Order Processing:Workflow automation for order capture, validation, and routing persists as a commodity function with limited differentiation.
- Reporting Tools:Dashboard and analytics modules increasingly bundle as table stakes rather than standalone revenue drivers.
Adoption clusters around Inventory Management; Shipping Optimization gains share fastest.
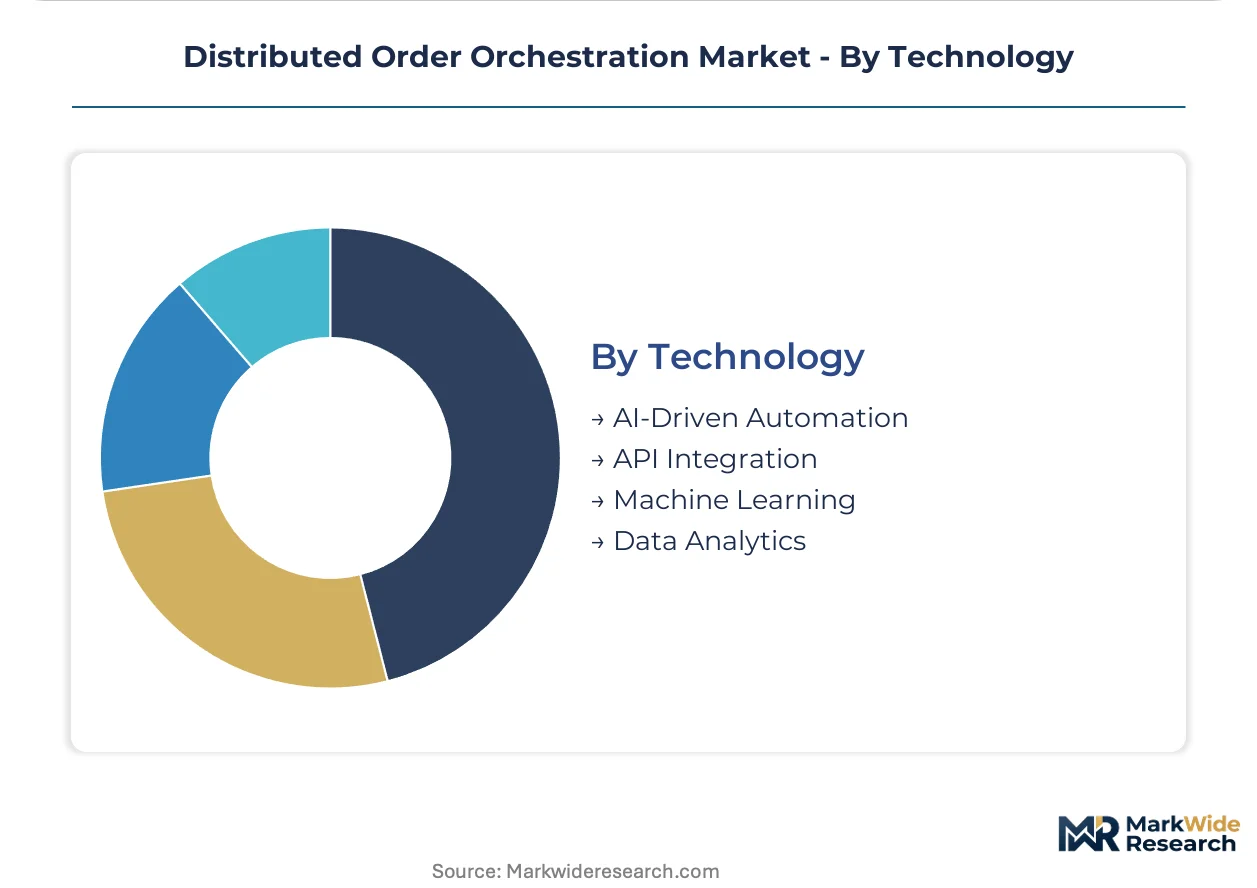
Technology:
Maturity stage separates buyers, with early adopters pursuing neural network architectures while mainstream enterprises prioritize proven integration layers.
- API Integration:Event-driven mesh architectures enabling real-time data exchange across heterogeneous ERP systems constitute the foundational enabler for all other capabilities. Mid-market retailers in the United States and United Kingdom prioritize pre-built connectors to SAP, Oracle, and Microsoft Dynamics environments.
- AI-Driven Automation:Autonomous replenishment triggers and predictive exception handling concentrate in grocery and pharmaceutical verticals where shelf-life constraints demand sub-second routing recalculation. EU AI Act compliance costs slow European deployment timelines.
- Machine Learning:Demand forecasting and lead-time prediction modules attract manufacturers seeking to reduce safety stock without service-level degradation.
- Data Analytics:Descriptive and diagnostic capabilities increasingly embed as standard features rather than differentiated premium tiers.
Deployment volume favors API Integration; AI-Driven Automation climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and Western Europe, while consumption spreads across retail and manufacturing hubs in Asia-Pacific and the Middle East. Cloud infrastructure deployment follows data sovereignty requirements, fragmenting platform hosting across jurisdictional boundaries.
United States
Omnichannel retailers in the United States drive demand for real-time inventory promising across fragmented fulfillment nodes. FTC scrutiny of algorithmic pricing collusion shapes how vendors architect competitive-intelligence firewalls. The Pacific Northwest and Greater Boston anchor cloud-native platform development, with Seattle-based hyperscalers capturing orchestration hosting contracts.
Germany
German automotive and industrial manufacturers pursue unified available-to-promise visibility across multi-echelon supplier networks. GDPR data sovereignty mandates force retirement of legacy on-premises order management systems. The Bavaria and Baden-Württemberg industrial corridors concentrate platform modernization budgets among engineer-to-order producers.
United Kingdom
British grocery and pharmaceutical distributors deploy predictive exception handling to manage shelf-life constraints across temperature-controlled networks. The UK Medicines and Healthcare products Regulatory Agency enforces traceability requirements that favor vendors with embedded audit trails. The London-Southeast corridor dominates procurement decision-making for European headquarters of multinational retailers.
China
Chinese e-commerce platforms require sub-second order routing across vast drop-ship networks and third-party logistics nodes. The Ministry of Industry and Information Technology imposes data localization requirements that favor domestic cloud orchestration providers. The Yangtze River Delta and Pearl River Delta concentrate fulfillment automation investment among cross-border export retailers.
India
Indian omnichannel retailers seek phased cloud migration paths to preserve existing ERP investments while layering AI-native capabilities. The Reserve Bank of India and Securities and Exchange Board of India cybersecurity guidelines shape vendor selection among financial services end users. Maharashtra and Karnataka anchor platform deployment among Bangalore-based e-commerce operators and Mumbai-headquartered conglomerates.
Distributed Order Orchestration Market Competitive Landscape
The competitive structure tilts toward enterprise software incumbents with deep ERP integration capabilities. Three archetypes dominate: legacy suite vendors extending order management modules, pure-play supply chain specialists with AI-native architectures, and hyperscale cloud providers bundling orchestration into broader platform offerings. Strategic moves concentrate on API ecosystem expansion and vertical-specific compliance certification to capture regulated industry accounts.
Within the enterprise suite tier, Oracle Corporation, SAP SE, and IBM Corporation exemplify divergent integration strategies. Oracle leverages deep ERP connectivity to anchor manufacturing accounts with complex available-to-promise requirements. SAP sustains renewal momentum among European industrials through native supply chain data models. IBM occupies a hybrid position, combining legacy middleware strengths with cloud-native orchestration services for financial services clients bound by stringent audit requirements.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| SAP SE |
| Salesforce Inc. |
| Microsoft Corporation |
| Manhattan Associates |
| E2open Inc. |
| Kinaxis Inc. |
| Blue Yonder Group Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up platform specialists now control substantial orchestration software assets, concentrating supply-side discipline and enforcing subscription-based pricing rigor across fragmented buyer segments. This ownership pattern tightens margin management while accelerating cloud-native delivery model standardization.
Pricing Analysis
Cost compression in mid-market SaaS tiers reflects hyperscale cloud hosting fee pass-throughs and API integration professional services margin erosion. Three-tier pricing structure across premium, standard, and economy levels separates enterprise accounts with embedded AI modules from basic inventory visibility subscriptions. ISO 27001 certification premiums widen price spreads, with healthcare and financial services buyers absorbing higher per-node costs. E-commerce retailers exhibit acute price sensitivity, while defense contractors and classified supply chains accept substantial premiums for air-gapped single-tenant deployments.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for ERP-integrated orchestration platforms, while cloud-native specialists distribute through marketplace listings and systems integrator partnerships. Software development concentrates in the United States, Germany, and India, with Seattle, Munich, and Bangalore anchoring engineering talent pools. Platform architectures draw from open-source middleware components, proprietary neural network training pipelines, and hyperscale compute infrastructure. Single-source vulnerability in cloud infrastructure hosting creates concentration risk as AWS, Azure, and GCP capture orchestration platform deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
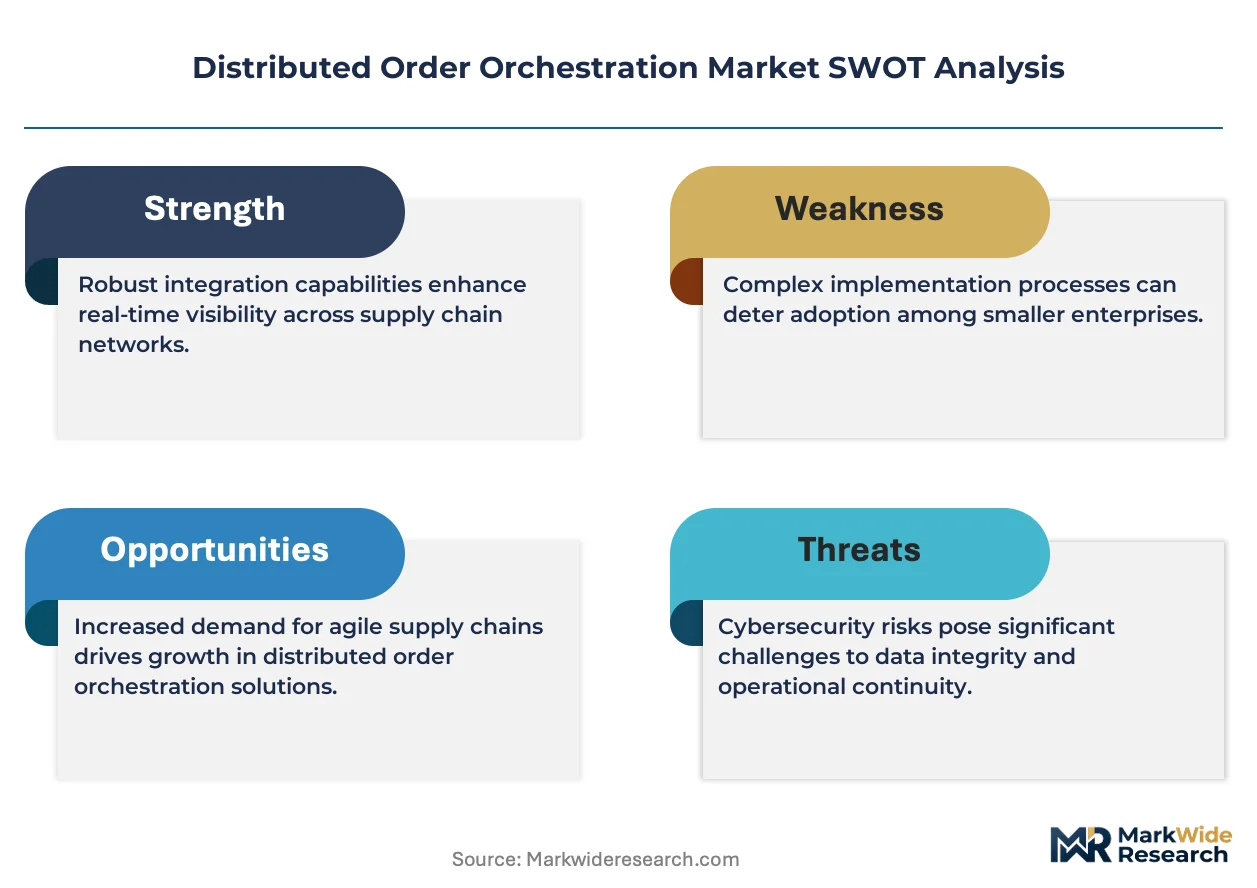
Distributed order orchestration functions as a consolidation play where EU AI Act compliance costs and API integration complexity force weaker vendors toward strategic exits or acquisition.
For Market Incumbents: Anchor enterprise renewal rates through deep ERP connector ecosystems that embed Oracle, SAP, and Microsoft Dynamics integration as switching-cost barriers. Prioritize explainable AI module pre-certification to capture healthcare distributors under MDR traceability mandates before smaller competitors achieve compliance. Defend against pure-play AI-native entrants by accelerating human-in-the-loop protocol deployment across European deployments. For New Entrants and Emerging Players: The mid-market hybrid deployment gap between cloud-native premium offerings and legacy on-premises economy tiers offers white-space entry. Target United States-based omnichannel retailers seeking phased migration paths combining existing ERP investments with AI-native fulfillment optimization. Pursue grocery and pharmaceutical vertical specialization where shelf-life constraint algorithms command pricing premiums unavailable in commoditized order processing modules. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market SaaS vendors with proven API mesh architectures but strained balance sheets from prolonged EU AI Act compliance investment. Monitor explainable AI talent acquisition velocity as the inflection indicator separating viable platforms from stranded technology bets. Long-term viability accrues to vendors controlling proprietary training datasets from temperature-controlled distribution network deployments.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Pre-built ERP connectors reduce deployment friction and accelerate time-to-value for manufacturing accounts. |
| Vertical Compliance Certification | Embedded MDR and HIPAA audit trails unlock healthcare procurement budgets closed to generalist competitors. |
| Hybrid Deployment Architecture | Split on-premises and cloud configurations capture mid-market retailers with phased modernization requirements. |
| Edge Computing Convergence | IoT sensor integration enables real-time inventory positioning in autonomous warehouse robotics networks. |
| Consumption-Based Licensing Transition | Order-volume-aligned pricing reduces upfront capex barriers and aligns vendor revenue with customer growth. |
Research Methodology
SEC 10-K filings, EU regulatory compliance databases, and hyperscaler capex disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with CTOs, IT procurement officers, platform integration specialists, and supply chain directors at e-commerce operators, grocery distributors, and pharmaceutical logistics providers validated architectural adoption patterns. Bottom-up and top-down triangulation cross-checked node-count estimates against cloud infrastructure spend attribution.
Bottom-up modeling aggregated deployment counts by organization size and vertical, while top-down analysis tracked enterprise software spend allocation trends across the projection horizon. Segmentation dimensions included deployment model, end-user vertical, solution functional depth, and technology maturity stage. CAGRs derived from logistic diffusion curves fitted to cloud migration mandate timelines and API integration completion rates.
Inputs from regulatory filing databases and vendor certification registries were available through the study window; gaps in private mid-market transaction pricing introduce uncertainty bands around hybrid deployment value estimates. Forecasts reflect assumptions regarding EU AI Act enforcement intensity and labor shortage persistence across fulfillment networks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Product Data Management Market
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Tail Spend Management Solutions Market