
 Immunology Market | 2026-2036
Immunology Market Size, Share, and Industry Trends Forecast 2026-2036
Immunology Market Intelligence
The therapeutic landscape is pivoting away from traditional small-molecule drugs towards large-molecule biologics, fundamentally altering treatment economics for chronic conditions. Roche leverages its extensive biologics manufacturing capacity to maintain a leading position in oncology and autoimmune treatments. AbbVie specializes in monoclonal antibody therapies, particularly for inflammatory diseases. Pfizer competes across both small molecules and a growing portfolio of vaccines and advanced biologics.
Immunology is the branch of biomedical science concerned with the structure and function of the immune system in states of both health and disease. It involves studying host defense mechanisms, cellular components like lymphocytes, and molecular components such as cytokines. Monoclonal antibodies constitute the dominant product type, valued for their specificity in treating complex autoimmune disorders. The vaccines segment, while mature, continues to evolve for emerging infectious diseases, complemented by immunosuppressants for transplant rejection.
Stringent regulatory frameworks from the US FDA, the European EMA, and China's NMPA dictate market access for new therapies. Their rigorous standards for clinical trial efficacy and safety, along with post-market surveillance, shape product development cycles and costs. Navigating the evolving landscape of personalized medicine and cell therapy regulations will be critical for pipeline success.
Market Dynamics
The immunology market's core dynamic is the transition from broad-spectrum immunosuppressants to precision biologics and cell therapies. This shift, enabled by advances in genomics and high-throughput screening, fundamentally alters research priorities, manufacturing requirements, and treatment cost structures.
Growth Catalysts
- Advanced Therapeutic Modalities:The application of gene-editing tools like CRISPR-Cas9 in developing CAR-T and other cell therapies is creating new treatment paradigms for cancers and autoimmune disorders, stimulating significant R&D investment.
- Regulatory Incentives:Accelerated approval pathways, such as the FDA's Regenerative Medicine Advanced Therapy (RMAT) designation, shorten development timelines for innovative cell therapies targeting serious conditions, encouraging pipeline investment.
- Demographic Shifts:Aging populations in developed nations, including Japan and Germany, are leading to a higher incidence of age-related immune system decline and autoimmune diseases, directly expanding the addressable patient population.
Market Restraints
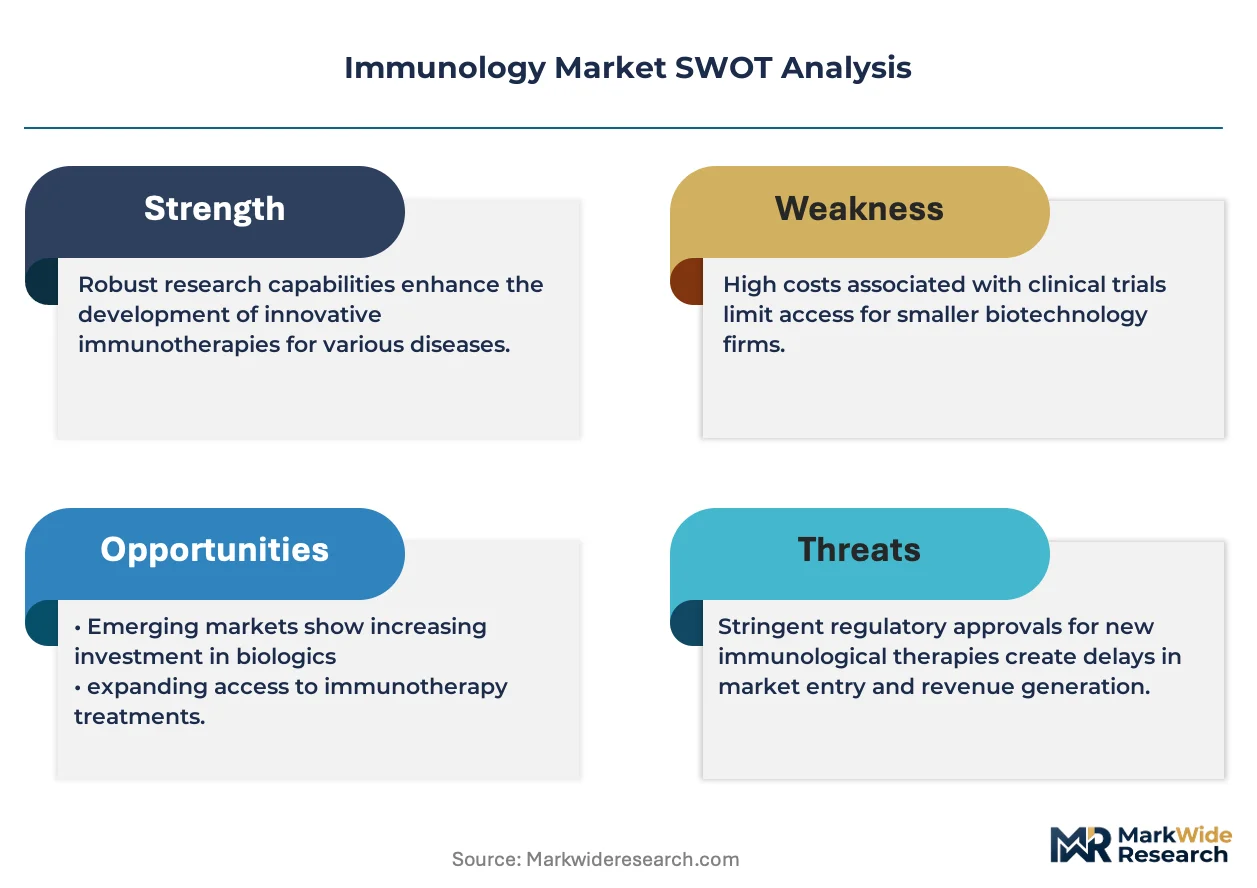
- High Development Costs:The substantial financial investment required for biologic and cell therapy research, clinical trials, and specialized manufacturing facilities acts as a significant barrier to entry and market expansion.
- Stringent Regulatory Hurdles:Rigorous and lengthy clinical trial standards imposed by agencies like the EMA and NMPA, while ensuring safety, can delay market access for new therapies by several years.
- Technical Efficacy Limits:Challenges such as the immunogenicity of monoclonal antibodies and off-target effects of gene therapies can limit therapeutic efficacy and pose safety risks, constraining clinical adoption.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Latin America, particularly Brazil, offer substantial growth potential as healthcare spending increases and access to advanced autoimmune treatments improves.
- Microbiome Therapeutics:The emerging field of microbiome modulation presents a novel opportunity to develop therapies for immune-mediated conditions like inflammatory bowel disease and allergies by targeting gut bacteria.
- AI in Drug Discovery:The convergence of artificial intelligence with genomic data analysis allows for the rapid identification of novel drug targets and predictive biomarkers, shortening preclinical development cycles.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of bioinformaticians, data scientists, and technicians skilled in cell therapy manufacturing creates operational bottlenecks that hinder research and production scale-up.
- Cold Chain Logistics:Maintaining the integrity of temperature-sensitive biologics and living cell therapies requires a complex and costly cold chain, posing significant logistical and financial challenges for distribution.
- Intellectual Property Complexity:The dense patent landscape surrounding foundational technologies like monoclonal antibodies and CRISPR creates a litigious environment and complicates licensing negotiations for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunology Market |
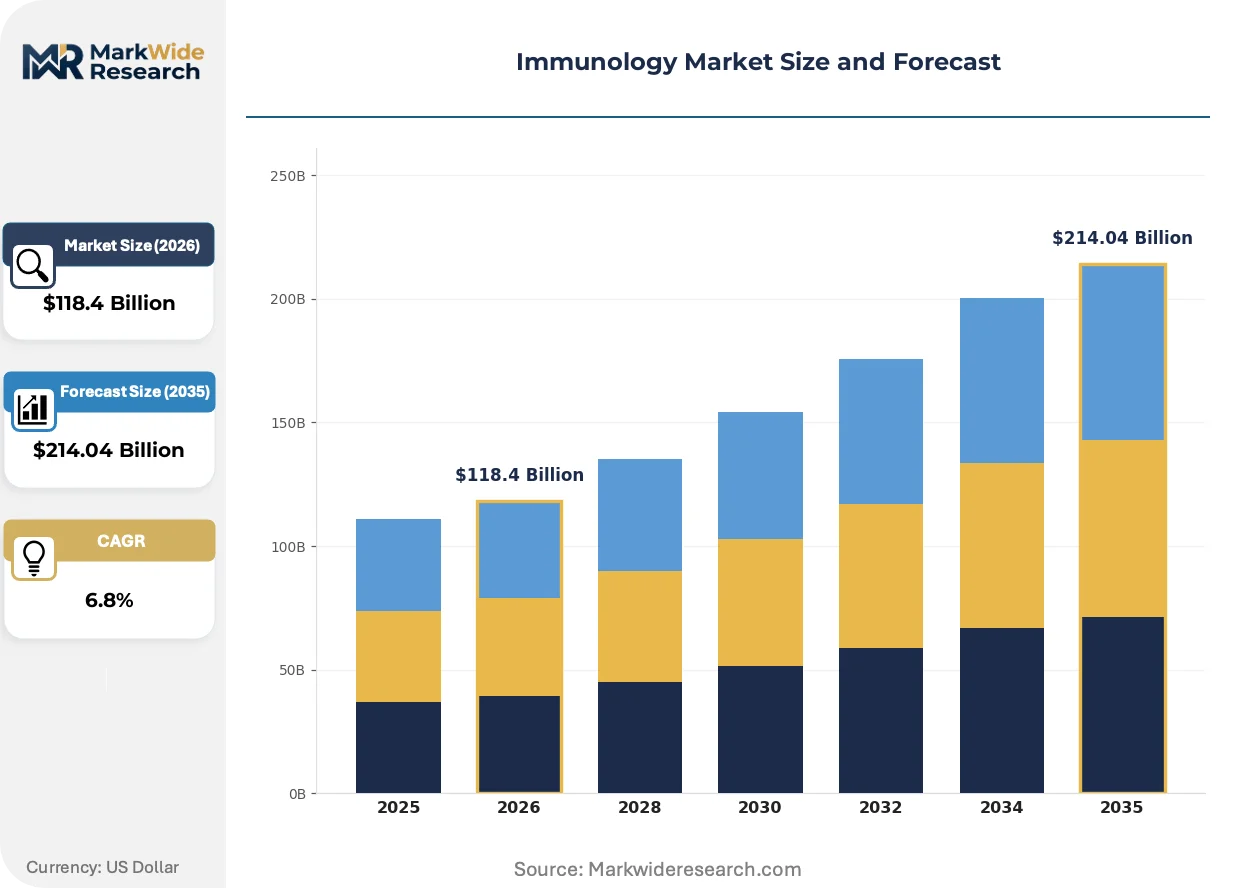
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $214.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Immunosuppressants, Cytokines, Adjuvants Therapy Area: Autoimmune Disorders, Infectious Diseases, Allergies, Transplant Rejection End User: Hospitals, Research Institutes, Diagnostic Labs, Biopharmaceutical Companies Delivery Mode: Injectable, Oral, Topical, Nasal, Intravenous |
| Companies Covered | Roche, Pfizer, AbbVie, GSK, Regeneron Pharmaceuticals, Amgen, Novartis, Sanofi, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunology Market Strategic Shifts & Innovations
The field's innovation is defined by the integration of computational biology with clinical immunology. This creates predictive frameworks for patient response, moving treatment selection beyond generalized protocols and toward personalized therapeutic strategies based on individual immune profiles.
Multi-omics platforms integrate genomics, proteomics, and metabolomics data to create a comprehensive biological profile of a patient's immune status. Biopharmaceutical firms are rapidly adopting these platforms within clinical trials to stratify patient populations and identify predictive biomarkers for treatment response. This data-intensive approach is converging with artificial intelligence algorithms to build models that forecast therapeutic efficacy and potential adverse events for individual patients.
European Medicines Agency (EMA) regulations, specifically the PRIME (PRIority MEdicines) scheme, offer enhanced support for medicines targeting an unmet medical need. This initiative provides early and proactive regulatory dialogue, which can accelerate the assessment of promising new immunotherapies. The oncology and rare autoimmune disease segments benefit most, as developers gain valuable scientific advice that can streamline clinical development and expedite patient access.
A definitive shift toward value-based healthcare agreements is altering how providers and payers approach the procurement of expensive immunology drugs. Health systems are increasingly moving from traditional fee-for-service payments to outcome-based contracts where reimbursement is linked directly to the measured effectiveness of a therapy. This trend is most visible in the United States and select European countries for managing chronic inflammatory diseases.
Immunology Market Segmentation
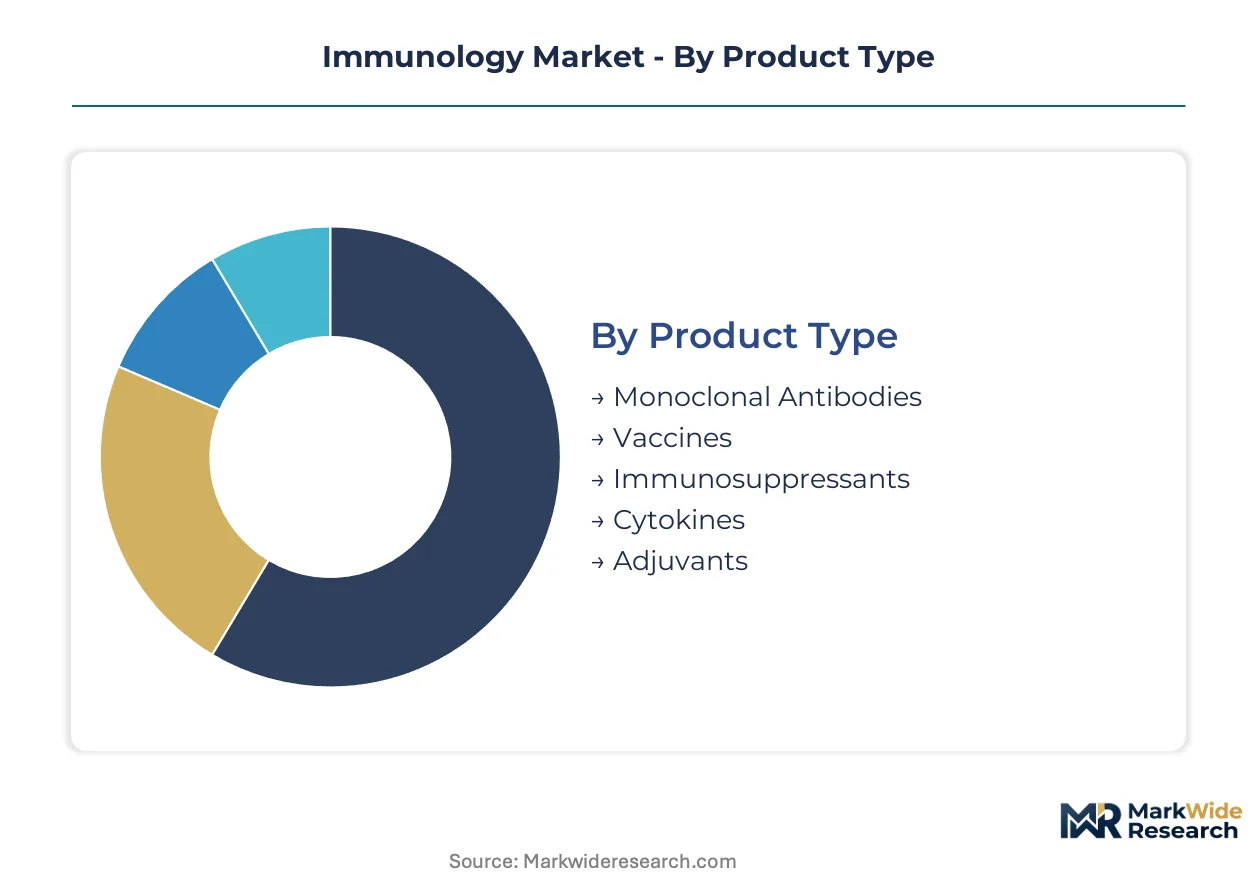
The immunology market's segmentation reflects the diverse mechanisms and applications of immune-modulating therapies. Understanding these distinct segments provides clarity on where innovation is driving value and how different patient needs are being addressed. This granular view helps stakeholders identify specific growth pockets and strategic investment areas within the complex therapeutic landscape.
Product Type:
The technology underpinning immunology treatments defines the product type segment, ranging from highly specific biologics to broad-acting small molecules.
- Monoclonal Antibodies:These highly specific proteins target particular antigens on immune cells or pathogens, offering precise therapeutic action for autoimmune disorders. Demand concentrates in biopharmaceutical companies in the United States and China due to extensive R&D and manufacturing capabilities.
- Vaccines:Biological preparations stimulate an immune response against specific diseases, preventing future infections through active immunization. Although mature, the segment for infectious diseases continues to evolve, supported by public health initiatives globally.
- Immunosuppressants:These agents reduce the strength of the body's immune system, primarily used to prevent organ rejection after transplantation.
- Cytokines:Signaling proteins mediate and regulate immunity, inflammation, and hematopoiesis, finding applications in oncology and infectious disease management.
- Adjuvants:Substances added to vaccines to enhance the immune response, improving vaccine efficacy and reducing antigen dosage requirements.
Mature deployment sits with Immunosuppressants. Newer deployment is concentrated in Monoclonal Antibodies.
Therapy Area:
Application of immunology therapies across various conditions shapes the therapy area segment, highlighting distinct patient populations and disease burdens.
- Autoimmune Disorders:Conditions where the immune system mistakenly attacks the body's own tissues, such as rheumatoid arthritis and psoriasis, represent a significant therapeutic focus. Growth is particularly pronounced in therapies leveraging precision biologics, altering treatment economics for chronic conditions.
- Infectious Diseases:The segment involves treatments and preventive measures against pathogenic microorganisms, including viral, bacterial, and parasitic infections. Although vaccines are mature, new therapies for emerging infectious diseases drive continuous innovation and investment from pharmaceutical companies.
- Allergies:Hypersensitivity reactions to normally harmless substances, ranging from seasonal rhinitis to severe anaphylaxis, require targeted immunomodulation.
- Transplant Rejection:The immune system's response to a transplanted organ, necessitating immunosuppressive regimens to ensure graft survival, remains a critical area.
The segment addressing Autoimmune Disorders holds significant revenue, while Infectious Diseases demonstrates the steepest expansion trajectory.
End User:
The primary customer type for immunology products dictates the end-user segment, influencing distribution channels and product formulation.
- Biopharmaceutical Companies:These entities are significant consumers for R&D and manufacturing of novel immunotherapies, particularly in the United States and China. Their internal research drives demand for advanced diagnostic tools and raw materials for biologics.
- Hospitals:Healthcare facilities provide direct patient care, administering a wide range of immunology treatments for acute and chronic conditions. They represent a major point of consumption for injectable biologics and immunosuppressants.
- Research Institutes:Academic and private research centers conduct fundamental and translational immunology studies, requiring specialized reagents and equipment.
- Diagnostic Labs:These facilities perform tests to identify immune system disorders, infections, and monitor treatment efficacy using immunology-related assays.
Demand from Hospitals accounts for a substantial share, with Biopharmaceutical Companies showing considerable potential.
Delivery Mode:
The method of administration for immunology drugs defines the delivery mode segment, impacting patient adherence and logistical considerations.
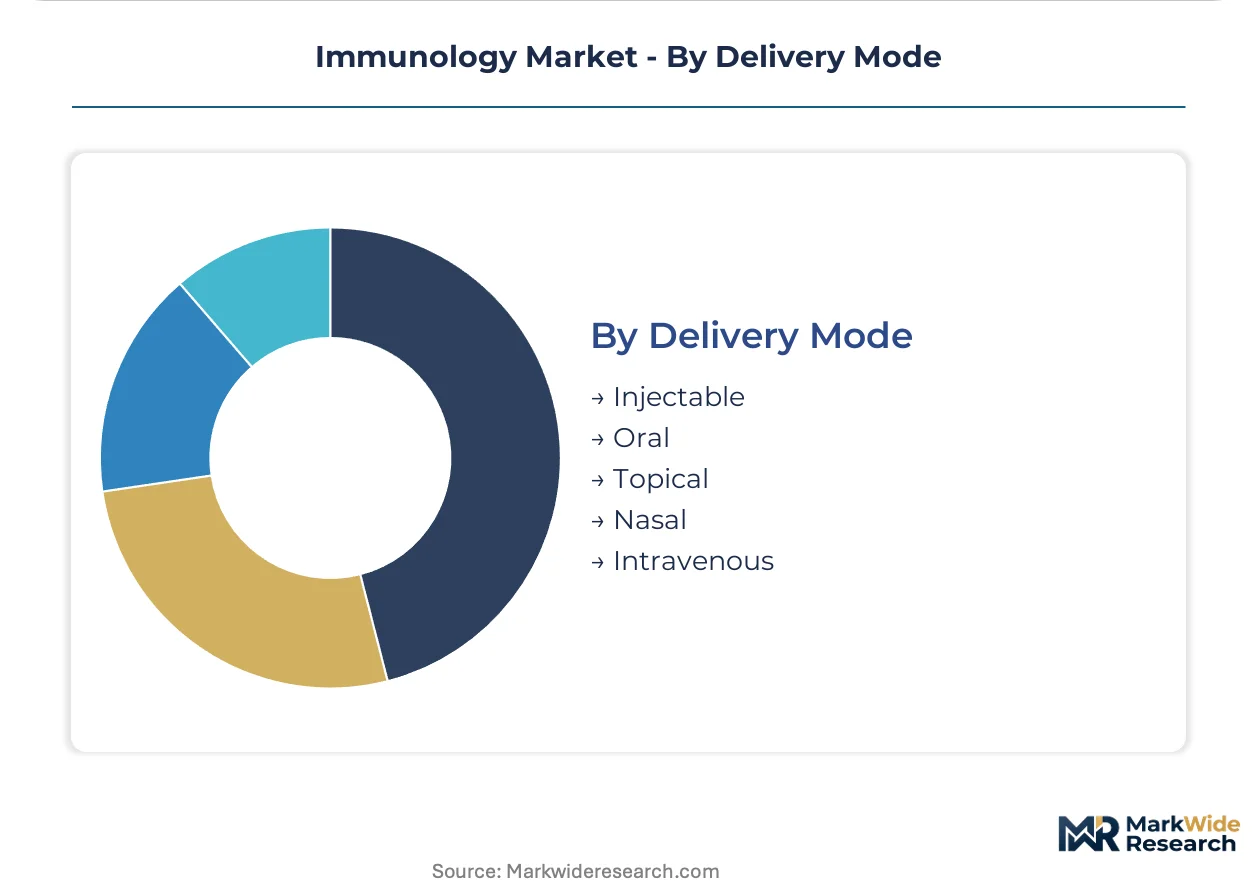
- Injectable:This mode includes subcutaneous and intramuscular injections, commonly used for monoclonal antibodies and vaccines due to their large molecular size. It offers precise dosing and rapid systemic absorption for many biologic therapies.
- Intravenous:Administration directly into a vein provides immediate and complete bioavailability, often preferred for high-dose biologics or in critical care settings. Many cell therapies and complex biologics are delivered intravenously in hospitals.
- Oral:Medications taken by mouth offer convenience for patients but are less common for large-molecule biologics due to degradation in the digestive tract.
- Topical:Applied to the skin or mucous membranes, this mode is suitable for localized immune responses, such as some allergy treatments or dermatological conditions.
- Nasal:Administration through the nasal passages allows for local or systemic effects, with potential for vaccine delivery and rapid absorption.
Traditional administration routes like Injectable maintain market dominance, as novel approaches like Nasal gain acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for immunology therapies concentrates significantly within biopharmaceutical companies in the United States and China. These nations drive substantial investment in research and development for novel treatments. The global market shows varying growth patterns influenced by regulatory frameworks and demographic shifts.
United States
Demand for advanced biologics and cell therapies is high, driven by a robust R&D ecosystem. The US FDA's accelerated approval pathways, such as RMAT designation, shorten development timelines for innovative immunotherapies. Boston and San Francisco Bay Area clusters lead in biotech innovation, fostering new therapeutic applications.
China
Biopharmaceutical companies in China exhibit significant demand for monoclonal antibodies and novel gene therapies. China's NMPA has streamlined drug approval processes, encouraging domestic and international pipeline investment. Shanghai and Beijing serve as major hubs for biopharma R&D, attracting substantial capital for immunology research.
Germany
An aging population in Germany creates substantial demand for autoimmune disease treatments and advanced vaccines. The European Medicines Agency (EMA) regulations, including the PRIME scheme, support accelerated assessment of promising immunotherapies. The Munich and Berlin regions host numerous biotech firms, specializing in precision immunology and cell therapy development.
Japan
Japan's rapidly aging demographic fuels demand for therapies addressing age-related immune decline and chronic autoimmune conditions. The PMDA ensures rigorous standards for clinical trial efficacy and safety, guiding product development. The Tokyo-Yokohama region is a center for pharmaceutical innovation, focusing on personalized medicine approaches.
Brazil
Underpenetrated markets in Brazil present substantial growth potential for advanced autoimmune treatments as healthcare spending increases. ANVISA's regulatory framework is evolving to improve access to novel biologics. São Paulo's biomedical cluster is expanding, attracting investment for local manufacturing and distribution of immunotherapies.
Immunology Market Key Industry Players
R&D investment dominates the current landscape, driving the transition towards precision biologics and cell therapies. The market structure features established biopharmaceutical giants alongside agile biotech startups. Three strategic archetypes emerge: large-scale biologics manufacturers, specialized cell and gene therapy developers, and technology-focused firms leveraging AI in drug discovery. Portfolio diversification into advanced therapeutic modalities, strategic partnerships, and geographic expansion into underpenetrated markets are key competitive moves.
Specialists in large-molecule biologics manufacturing, such as Roche, exemplify the established biopharmaceutical archetype. Roche leverages extensive manufacturing capacity to maintain leading positions in oncology and autoimmune treatments, influencing treatment economics. AbbVie represents a focused approach, specializing in monoclonal antibody therapies, particularly for inflammatory diseases. Pfizer, with its diversified portfolio, occupies a position across both traditional small molecules and a growing range of advanced biologics and vaccines.
| Leading Market Players |
|---|
| Roche |
| Pfizer |
| AbbVie |
| GSK |
| Regeneron Pharmaceuticals |
| Amgen |
| Novartis |
| Sanofi |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Stringent regulatory frameworks from the US FDA and European EMA elevate development costs for novel immunotherapies, compelling suppliers to invest in specialized manufacturing and impacting pricing structures.
Pricing Analysis
High R&D investment drives a market where premium pricing dominates low-volume, high-value precision biologics, while traditional vaccines operate on higher volume and lower per-unit margins. Value-based healthcare agreements and long-term contracts define the dominant pricing model. Efficacy, regulatory approval, and specialized manufacturing serve as key differentiation drivers. Pricing pressure stems from the need to recoup substantial development costs, with health systems exhibiting the highest price sensitivity for chronic treatments.
Supply Chain Analysis
The supply of complex biologics and cell therapies relies heavily on specialized raw materials like cell culture media and advanced bioreactors. Geographic concentration for these inputs is notable in the United States, China, and Germany. Cold chain logistics presents a significant structural risk, requiring precise temperature control for sensitive products. Distribution runs through hospitals and specialized clinics for direct patient administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunology market is in a significant technology-transition phase, as precision biologics and cell therapies displace broad-spectrum immunosuppressants.
For Market Incumbents: Hedge against pipeline obsolescence by aggressively investing in advanced therapeutic modalities like CAR-T cell therapies. Diversify portfolios into novel biologics and establish strategic partnerships for specialized manufacturing capacity. This mitigates threats from agile biotech startups and technical efficacy limits of legacy drugs, leveraging existing R&D and manufacturing scale.
For New Entrants and Emerging Players: The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation in the United States opens a window for expedited development of innovative cell therapies. Target underpenetrated markets like Brazil for autoimmune treatments or focus on microbiome therapeutics. Leverage AI in drug discovery to identify novel targets, offering a go-to-market angle for unmet medical needs.
For Investors and Strategic Acquirers: The window for entry favors specialized biotech firms with strong intellectual property in gene editing or cell therapy platforms. High unmet medical need in chronic autoimmune disorders ensures long-term viability over a five-to-ten year horizon. Seek companies with validated CRISPR-Cas9 technologies. Successful Phase 3 clinical trial readouts for personalized medicine approaches serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates the validation of novel immunotherapies for complex autoimmune disorders. |
| Regulatory Approval Pathway | Navigating the EMA's PRIME scheme can expedite market access for innovative treatments. |
| Licensing Agreement | Securing rights to CRISPR-Cas9 technology enables new gene-editing therapeutic development. |
| Manufacturing Scale-Up | Expanding biologics production capacity supports growing demand for monoclonal antibodies. |
| Pipeline Diversification | Investing in microbiome therapeutics addresses emerging immune-mediated conditions like IBD. |
Research Approach
Trade association data, regulatory filings from the US FDA, and customs records anchored secondary inputs, providing foundational market intelligence. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and R&D scientists validated market dynamics. This approach integrated both bottom-up and top-down triangulation for robust data synthesis.
Market dimensions were modeled at a granular level, segmenting by product type, therapy area, end-user, and delivery mode across the analysis window. Regional regulatory clusters were also incorporated. Compound annual growth rates were derived from historical growth trends and projected technology adoption rates. Clinical trial success rates and regulatory approval timelines served as key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-Cas9 applications would alter the outlook. Unexpected clinical trial failures or major shifts in payer reimbursement policies represent risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Pharyngitis Treatment Market