
 Canada Neurology Devices Market | 2026-2036
Canada Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Neurology Devices Market Outlook
ISO 13485 certification for quality management systems is rotating as the primary gatekeeper for market access, filtering out suppliers lacking documented design controls and risk management protocols. Medtronic PLC leverages its captive manufacturing infrastructure to sustain catheter supply chains serving Canadian stroke centers. Boston Scientific Corporation anchors its position through deep electrophysiology specialization, while Stryker Corporation competes across surgical navigation and neurovascular intervention platforms.
Neurology devices encompass instruments, implants, and systems engineered for diagnosis, treatment, or monitoring of disorders affecting the central and peripheral nervous systems, typically incorporating biocompatible polymers, platinum-iridium electrodes, or titanium alloy housings with functional tolerances measured in micrometers for intracranial placement. Therapeutic devices command substantial margin pools due to recurring consumable attachments and procedure-linked replacement cycles, while neurostimulation technology leads growth trajectories driven by expanding deep brain stimulation indications and spinal cord therapy protocols. Diagnostic equipment remains structurally mature with replacement demand tied to hospital capital budget cycles rather than clinical expansion.
Health Canada enforces Medical Devices Regulations under the Food and Drugs Act, classifying implantable neural devices as Class III or IV with mandatory premarket licensing and post-market surveillance obligations. The Canadian Standards Association (CSA) publishes electrical safety and electromagnetic compatibility benchmarks that shape product design requirements for devices deployed in hospital environments. Provincial health technology assessment bodies, including Ontario's Health Quality Ontario and Quebec's Institut national d'excellence en santé et en services sociaux, condition reimbursement and procurement decisions on demonstrated clinical utility. Stakeholders must monitor evolving evidentiary thresholds for neurotechnology funding as provincial budgets face competing demands from aging demographics and chronic disease management programs.
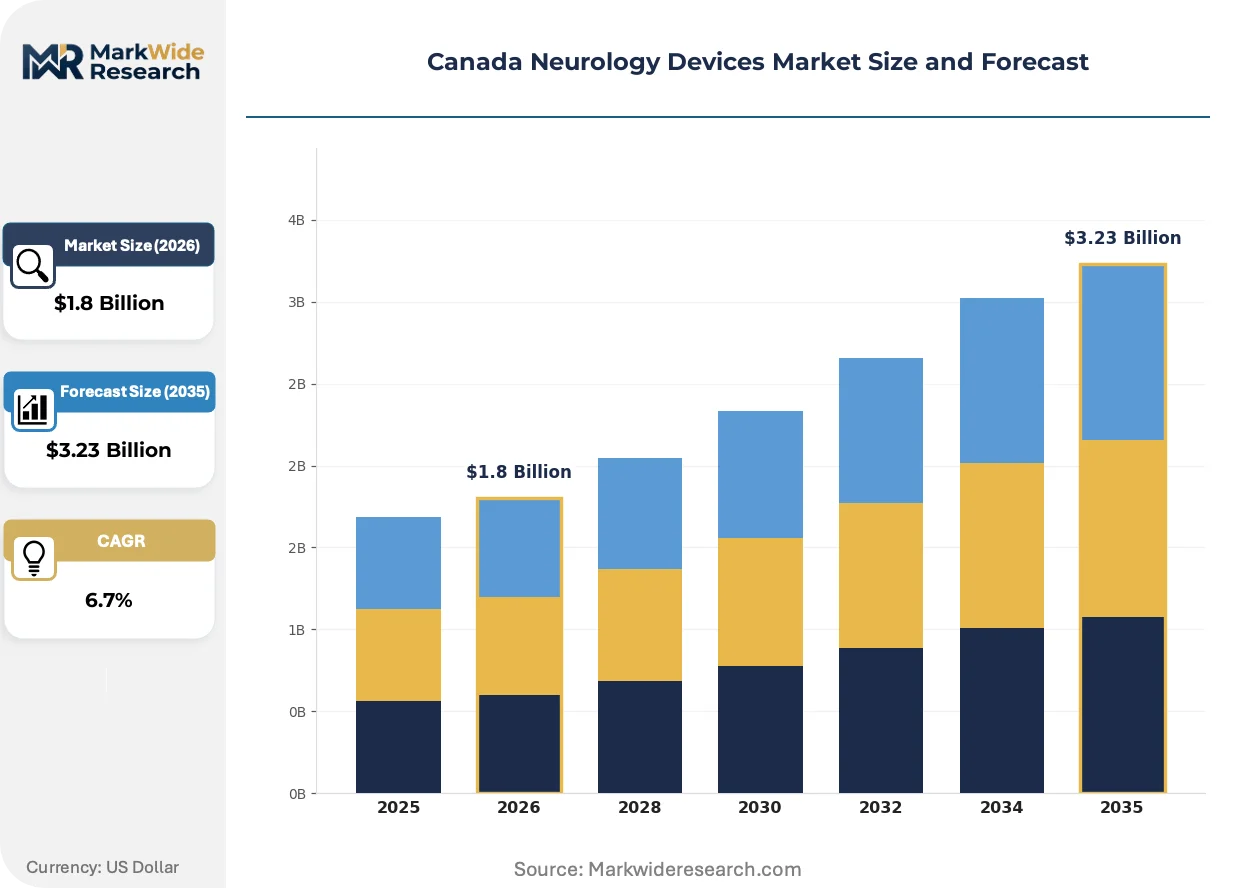
Market Dynamics
Health Canada's Medical Devices Regulations are tightening premarket review pathways for implantable neural interfaces, forcing manufacturers to front-load clinical evidence generation and quality system documentation before market entry.
Growth Catalysts
- Deep Brain Stimulation Expansion:Neurologists at Toronto Western Hospital and McGill University Health Centre are broadening DBS indications beyond Parkinson's disease into obsessive-compulsive disorder and treatment-resistant depression, driving device demand.
- ISO 13485 Certification Mandate:Health Canada now treats this quality management standard as a de facto prerequisite for Class III and IV device licensing, filtering out underqualified suppliers and elevating compliant manufacturers.
- Provincial Neurointerventional Investment:Ontario's Ministry of Health and Quebec's Ministère de la Santé et des Services sociaux are funding dedicated stroke suite expansions in tertiary centers across Ottawa, Hamilton, and Quebec City.
Market Restraints
- Platinum-Iridium Electrode Cost Volatility:Supply concentration among specialty metal refiners creates input price instability for neurostimulation lead manufacturers serving Canadian hospitals.
- Health Canada Licensing Timelines:Mandatory premarket licensing for Class IV implantable neural devices extends review cycles to 18-24 months, compressing effective patent life and delaying revenue recognition.
- Reimbursement Uncertainty:Ontario's Health Quality Ontario and Quebec's INESSS apply divergent evidentiary thresholds for novel neurotechnology funding, creating provincial patchwork access.
Strategic Opportunities
- Remote Patient Monitoring Integration:Home-based neurostimulation parameter adjustment and seizure detection systems are opening ambulatory care channels beyond traditional hospital-based implantation.
- Alberta and British Columbia Market Development:Calgary's Foothills Medical Centre and Vancouver General Hospital are building neurointerventional capabilities, offering first-mover positioning outside the saturated Ontario-Quebec corridor.
- CSA Electrical Safety Alignment:Early adoption of Canadian Standards Association electromagnetic compatibility benchmarks creates product differentiation for manufacturers targeting hospital procurement tenders.
Industry Challenges
- Neurointerventional Specialist Shortage:Canadian residency programs produce insufficient interventional neuroradiologists to staff expanding stroke center networks, constraining procedure volume growth.
- Legacy EMR Integration Complexity:Surgical navigation and neurostimulation programming systems require costly customization to interface with provincial electronic medical record platforms like Ontario's eHealth Ontario infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Neurology Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Therapeutic Devices, Monitoring Systems, Surgical Instruments Technology: Electrophysiology, Neurostimulation, Imaging, Robotics End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Application: Dementia, Epilepsy, Parkinson's Disease, Stroke |
| Companies Covered | Medtronic PLC, Boston Scientific Corporation, Stryker Corporation, Abbott Laboratories, B. Braun Melsungen AG, Johnson & Johnson, Penumbra Inc., MicroPort Scientific Corporation, Nihon Kohden Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Neurology Devices Market Strategic Shifts
Neurology device development is pivoting toward closed-loop adaptive systems and minimally invasive delivery mechanisms, with Canadian hospital procurement increasingly favoring technologies that reduce length-of-stay and enable same-day discharge protocols.
Directional lead technology with independent current control is decomposing the traditional four-contact deep brain stimulation paradigm into segmented steering arrays. Neurosurgeons at Toronto's Krembil Research Institute are implanting these systems at accelerating rates. The technology is decomposing hardware standardization across manufacturers and forcing proprietary programming ecosystem lock-in.
Health Canada's 2023 guidance on machine learning-enabled medical devices is requiring algorithm change control plans and locked algorithm specifications for neurodiagnostic AI. Manufacturers must submit predetermined modification protocols before licensing. Diagnostic imaging software vendors serving Montreal's research cluster are restructuring development pipelines to accommodate locked-model validation requirements.
Hospital value analysis committees in Ontario and Quebec are unbundling device procurement from technical support and training services, forcing manufacturers to price hardware and clinical education separately. Medtronic and Boston Scientific have responded with modular service tiering. This unbundling is most visible in Toronto's University Health Network and McGill University Health Centre, where procurement teams negotiate device and service contracts through distinct RFP processes.
Canada Neurology Devices Market Segmentation
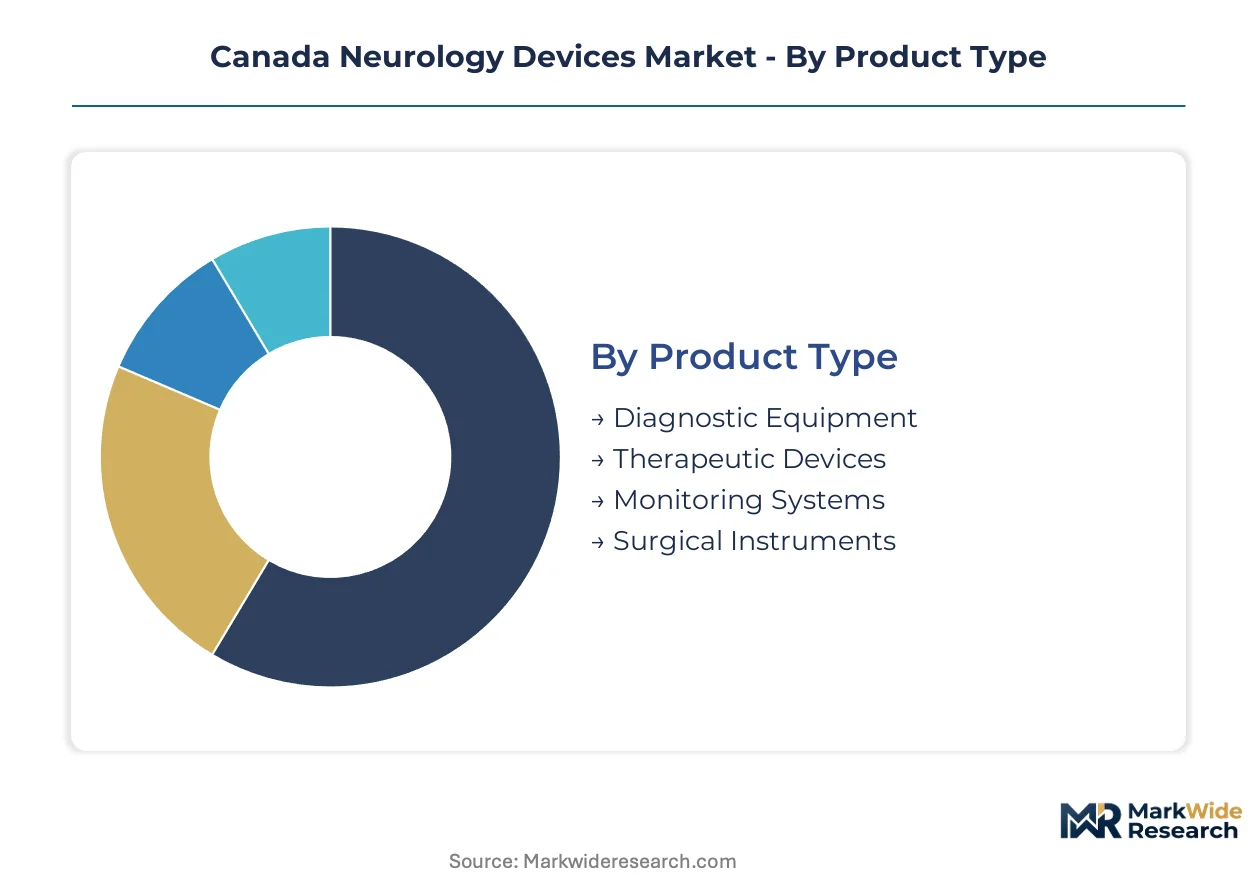
Neurology device procurement in Canada fragments across distinct technical categories, each governed by separate regulatory pathways and provincial reimbursement protocols. Understanding these divisions reveals where Health Canada's MDR enforcement and ISO 13485 certification requirements concentrate market power.
Product Type:
Therapeutic devices and diagnostic equipment anchor domestic hospital procurement in Ontario and Quebec, while monitoring systems and surgical instruments show stronger export-linked supply chains serving North American distribution networks.
- Therapeutic Devices:These systems incorporate biocompatible polymers and platinum-iridium electrodes with micrometer tolerances for intracranial placement. Toronto Western Hospital and McGill University Health Centre are expanding deep brain stimulation programs for obsessive-compulsive disorder and treatment-resistant depression, driving recurring consumable demand and procedure-linked replacement cycles.
- Diagnostic Equipment:Structural MRI and CT neuroimaging platforms with specialized head coils and diffusion tensor imaging capabilities. Replacement demand concentrates in hospital capital budget cycles across Ontario's hospital corridor rather than clinical expansion, constraining growth velocity.
- Monitoring Systems:Continuous EEG and intracranial pressure sensors for seizure detection and trauma management.
- Surgical Instruments:Microdissection tools, cranial fixation systems, and stereotactic frames for neurosurgical access.
Therapeutic devices command the established base. The steepest expansion runs through monitoring systems.
Technology:
Cost tiering separates premium neurostimulation platforms from commoditized imaging hardware, with electrophysiology occupying a mid-tier position where software-enabled feature differentiation sustains margins.
- Neurostimulation:Implantable pulse generators with directional lead technology and independent current control enabling segmented steering arrays. Toronto's Krembil Research Institute is implanting these systems at accelerating rates, forcing proprietary programming ecosystem lock-in across manufacturers.
- Electrophysiology:Mapping catheters and ablation systems for arrhythmia and functional neurosurgery. Boston Scientific Corporation anchors Canadian market position through deep specialization here, with catheter supply chains serving stroke centers across Ontario and Quebec.
- Imaging:MRI-compatible hardware and contrast delivery systems for neurodiagnostic protocols.
- Robotics:Surgical navigation platforms and stereotactic guidance systems for precision implantation.
Neurostimulation claims the revenue concentration. Imaging hardware faces replacement-cycle compression.
End User:
Volume distribution favors tertiary hospital networks over distributed care settings, with research institutions representing a specialized procurement channel where pilot programs precede broader provincial adoption.
- Hospitals:Tertiary neurointerventional suites in Ottawa, Hamilton, and Quebec City are receiving provincial funding for stroke center expansion. Health Canada's Class III and IV licensing requirements and 18-24 month review cycles compress effective patent life for implantable devices deployed here.
- Research Institutions:Montreal's research cluster drives early adoption of machine learning-enabled neurodiagnostic AI. Health Canada's 2023 guidance requires locked algorithm specifications and predetermined modification protocols, restructuring vendor development pipelines.
- Clinics:Outpatient neurology practices with limited procedural capabilities.
- Rehabilitation Centers:Post-acute care facilities for stroke and traumatic brain injury recovery.
Hospitals absorb the procedural volume. Research institutions set the technology trajectory.
Application:
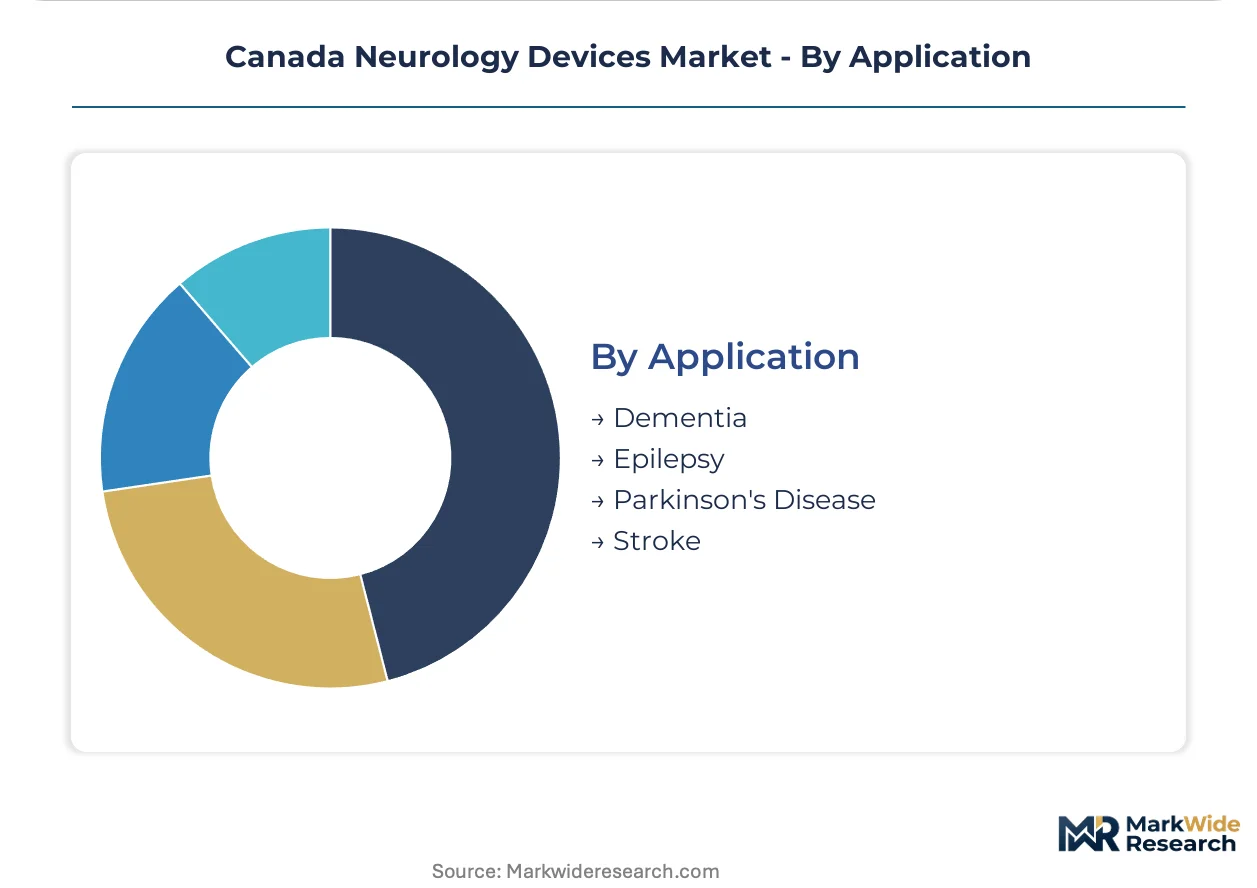
Clinical maturity varies sharply across indications, with Parkinson's disease representing an established reimbursement pathway while dementia applications face evidentiary threshold disputes at Ontario's Health Quality Ontario and Quebec's INESSS.
- Stroke:Neurointerventional thrombectomy devices and aspiration systems for acute ischemic intervention. Ontario's Ministry of Health and Quebec's Ministère de la Santé et des Services sociaux are funding dedicated suite expansions, though specialist shortage constrains procedure volume growth.
- Parkinson's Disease:Deep brain stimulation for motor symptom management with established provincial funding protocols. Directional lead technology is broadening therapeutic targeting precision at Toronto Western Hospital.
- Epilepsy:Responsive neurostimulation and vagus nerve stimulation for drug-resistant seizure disorders.
- Dementia:Diagnostic biomarker platforms and experimental neuromodulation protocols with unproven reimbursement pathways.
Stroke intervention is gaining share fastest. Dementia applications confront funding uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Canada Highway and CN Rail network underpin Ontario and Quebec's dominance in neurology device distribution, while West Coast ports anchor British Columbia's emerging import corridor for Pacific-originated neurointerventional equipment.
Ontario
Toronto Western Hospital and the University Health Network drive deep brain stimulation volumes for obsessive-compulsive disorder and treatment-resistant depression. Health Canada's Medical Devices Regulations classify implantable neural interfaces as Class III or IV, mandating 18-24 month premarket licensing cycles that compress effective patent life. Ottawa's civic hospital network is expanding neurointerventional suites with provincial Ministry of Health funding.
Quebec
McGill University Health Centre anchors Montreal's research cluster with accelerating directional lead implantations. The Institut national d'excellence en santé et en services sociaux applies stringent evidentiary thresholds for novel neurotechnology reimbursement, creating funding uncertainty for experimental protocols. Quebec City's tertiary centers are receiving Ministère de la Santé et des Services sociaux capital allocations for dedicated stroke suites.
Alberta
Calgary's Foothills Medical Centre is building neurointerventional capabilities outside the saturated Ontario-Quebec corridor. The Canadian Standards Association's electromagnetic compatibility benchmarks shape procurement requirements for devices deployed in hospital environments. Edmonton's academic medical centers are evaluating remote patient monitoring integration for home-based neurostimulation parameter adjustment.
British Columbia
Vancouver General Hospital offers first-mover positioning for manufacturers targeting Pacific Rim supply chains. Health Canada's 2023 machine learning-enabled medical device guidance requires locked algorithm specifications for neurodiagnostic AI vendors. Victoria's Island Health authority is constrained by capital budget cycles tied to diagnostic equipment replacement rather than clinical expansion.
Atlantic Canada
Halifax's QEII Health Sciences Centre concentrates interventional neuroradiology capacity for the Maritime provinces. Provincial health technology assessment bodies in New Brunswick and Nova Scotia condition procurement on demonstrated clinical utility. St. John's Memorial University hospital network faces specialist shortage constraints that limit procedure volume growth across Newfoundland and Labrador.
Canada Neurology Devices Market Competitive Environment
Listed leaders compete with private specialists across catheter supply chains and neurostimulation platforms, producing a consolidated structure where three multinational corporations capture the majority of implantable device revenue. The vendor base stratifies into captive manufacturing specialists, electrophysiology-focused divisions, and diversified surgical navigation platforms. Dominant competitive moves include ISO 13485 certification pre-positioning before Health Canada licensing submissions and modular service tiering that unbundles hardware procurement from clinical education contracts.
Within the diversified surgical technology tier, Medtronic PLC, Boston Scientific Corporation, and Stryker Corporation occupy positions that exemplify distinct strategic archetypes. Medtronic represents captive manufacturing infrastructure sustaining neurovascular catheter supply chains. Boston Scientific anchors electrophysiology specialization with mapping catheter portfolios. Stryker exemplifies cross-platform competition spanning surgical navigation and neurointerventional systems. These three entities collectively shape procurement dynamics in Toronto's hospital corridor and Montreal's research cluster.
| Leading Market Players |
|---|
| Medtronic PLC |
| Boston Scientific Corporation |
| Stryker Corporation |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Penumbra Inc. |
| MicroPort Scientific Corporation |
| Nihon Kohden Corporation |
| Others |
Value Chain & Pricing Dynamics
Directional lead technology displacing conventional four-contact deep brain stimulation systems is redrawing procurement economics across Ontario and Quebec, compressing hardware standardization while amplifying proprietary programming ecosystem premiums. This substitution simultaneously concentrates supply relationships with captive manufacturers and fragments pricing power across segmented steering array tiers.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-compliant Class IV implantable neural interfaces and lower-tier diagnostic hardware. Three-tier pricing structure across premium, standard, and economy levels separates directional lead neurostimulation platforms from electrophysiology mapping systems and commoditized surgical instruments. Pricing pressure stems from provincial health technology assessment bodies unbundling device procurement from technical support contracts. Academic medical centers in Toronto's hospital corridor exhibit highest price sensitivity due to constrained capital budgets, while research institutions in Montreal's cluster prioritize performance specifications over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate neurointerventional catheter supply chains serving Canadian stroke centers, though platinum-iridium electrode manufacturers maintain strategic stockpiles against specialty metal refiner concentration. Supply concentrates in the United States, Germany, and Ireland for implantable pulse generators, while Japan and South Korea anchor electrophysiology component sourcing. Raw material dependencies center on platinum-iridium alloys, biocompatible polymers, and titanium alloy housings. Single-source vulnerability in specialty metal refining creates structural risk. Distribution runs through hospital procurement committees and group purchasing organizations with provincial tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's neurology devices market sits at an inflection where Health Canada's machine learning-enabled medical device guidance is restructuring development pipelines for neurodiagnostic AI vendors. This regulatory pivot favors manufacturers with locked algorithm validation capabilities and predetermined modification protocols.
For Market Incumbents: Compound market position by deepening captive manufacturing infrastructure for catheter supply chains and accelerating ISO 13485 certification pre-positioning ahead of licensing submissions. Defend against emerging modular service tiering demands from Ontario's University Health Network and McGill University Health Centre by unbundling hardware and clinical education contracts through distinct RFP-responsive structures.
For New Entrants and Emerging Players: Remote patient monitoring integration represents the most penetrable service-layer gap where incumbents under-serve home-based neurostimulation parameter adjustment demand. Target Alberta's Foothills Medical Centre and British Columbia's Vancouver General Hospital for first-mover positioning outside the saturated Ontario-Quebec corridor. Pursue CSA electromagnetic compatibility early adoption as procurement differentiation lever.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors electrophysiology-focused specialists with deep catheter supply chain relationships. Long-term viability hinges on reimbursement strategy execution across divergent provincial evidentiary thresholds. Acquisition target archetype: mid-cap manufacturers with Health Canada Class III/IV licensing track records and directional lead technology portfolios. Watch for interventional neuroradiologist residency program expansion as volume growth inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class IV Licensing Pathway | Premarket approval for implantable neural interfaces compresses effective patent life and delays revenue recognition cycles. |
| ISO 13485 Certification Investment | Quality management documentation serves as de facto gatekeeper filtering underqualified suppliers from Ontario and Quebec procurement. |
| Provincial Hospital System Partnership | Toronto's University Health Network and McGill University Health Centre anchor volume concentration for directional lead deployments. |
| Software Companion Development | Locked algorithm specifications for machine learning-enabled neurodiagnostic AI comply with Health Canada's 2023 guidance requirements. |
| Reimbursement Strategy Alignment | Demonstrated clinical utility thresholds at Ontario's Health Quality Ontario and Quebec's INESSS condition funding access. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neurointerventional neuroradiologists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers. Secondary validation drew from Health Canada Medical Devices Regulations filings, provincial health technology assessment body reports, hospital procurement databases, and Canadian Standards Association electromagnetic compatibility benchmarks. Bottom-up procedure volume modeling and top-down market sizing triangulation anchored value estimates.
Across the analysis window, forecasts integrated therapeutic device, diagnostic equipment, monitoring system, and surgical instrument segmentation with technology tier, end-user channel, and clinical application dimensions. CAGRs derived from procedure volume growth rates, replacement cycle compression, and provincial funding allocation trajectories. Neurostimulation indication expansion and neurointerventional suite capital deployment schedules served as key forecast inputs.
Forecasts assume regulatory continuity in Health Canada's Medical Devices Regulations and provincial reimbursement protocols; material policy shifts would require re-modeling. Revision becomes warranted when interventional neuroradiologist supply constraints or platinum-iridium cost volatility cross thresholds that materially alter procedure volume or input cost assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Sciatica Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Diabetic Neuropathy Market
Neurology
Vocal Cord Paralysis Market
Neurology
Neurology Devices Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Spasticity Treatment Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Europe Neurology Monitoring Market
Neurology
United States Neurology Devices Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Cluster Headache Syndrome Market
Neurology
Central Nervous System Lymphoma Treatment Market