
 Mild Cognitive Impairment Market | 2026-2036
Mild Cognitive Impairment Market Size, Share, and Industry Trends Forecast 2026-2036
Mild Cognitive Impairment Market Foresight
Subscription-based cognitive monitoring software is expanding how pharmaceutical firms monetize patient engagement beyond one-time drug sales. Biogen leverages its neurology franchise to sustain high R&D intensity in amyloid-targeting programs. Eisai Co., Ltd. anchors its competitive position through deep specialization in Alzheimer's and MCI therapeutic development. Eli Lilly and Company differentiates via broad clinical trial infrastructure that spans multiple cognition biomarker platforms.
Mild cognitive impairment denotes a transitional clinical state between normal aging and dementia, characterized by measurable decline in one or more cognitive domains without significant functional impairment, typically assessed through neuropsychological testing and biomarker confirmation. The condition serves as a critical intervention window for delaying progression to Alzheimer's disease and related dementias. Pharmaceuticals dominates current revenue as cholinesterase inhibitors and emerging disease-modifying therapies capture early-stage patient pools, while diagnostics is gaining structural importance as blood-based biomarker assays reduce reliance on costly PET imaging. Hospitals remain the primary end-user channel for initial diagnosis, though home care delivery modes are expanding fastest as remote cognitive monitoring technologies mature.
FDA's accelerated approval pathway for Alzheimer's disease drugs directly shapes MCI therapeutic development timelines and investment thresholds, while EMA's qualification opinion process for digital biomarkers influences how monitoring devices gain market access in Europe. Japan's PMDA has streamlined its Sakigake designation system to prioritize cognitive disorder innovations, creating a tripartite regulatory environment that rewards biomarker-validated interventions. Stakeholders must monitor how payer evidence requirements evolve for pre-dementia populations, as reimbursement decisions will determine whether the addressable patient base expands beyond specialty memory clinics into primary care workflows.
Market Dynamics
FDA's accelerated approval pathway for Alzheimer's therapeutics is compressing clinical trial timelines and redirecting capital toward biomarker-validated MCI interventions, fundamentally restructuring how pharmaceutical firms prioritize early-stage neurodegenerative pipelines.
Growth Catalysts
- Blood-based biomarker assays:Plasma p-tau217 testing is displacing costly PET imaging in United States memory clinics, expanding diagnostic accessibility to primary care settings.
- Japan's Sakigake designation:PMDA's priority review system for cognitive disorder innovations is accelerating market entry timelines for disease-modifying therapies.
- Reimbursement alignment:Germany's statutory health insurance framework now covers pre-dementia cognitive assessments, incentivizing earlier patient identification.
Market Restraints
- Specialist workforce scarcity:Neurologist and neuropsychologist shortages in rural United States regions constrain diagnostic throughput expansion.
- Biomarker validation costs:EMA qualification opinion requirements for novel digital cognitive assessments impose substantial evidence-generation burdens on device developers.
- Amyloid-targeting safety concerns:ARIA monitoring requirements following anti-amyloid therapy approvals add treatment complexity and infrastructure costs.
Strategic Opportunities
- Remote monitoring platforms:Smartphone-based cognitive assessment tools are penetrating Japan's aging rural prefectures where clinic access is limited.
- Primary care integration:Germany's dementia care networks present white space for MCI screening protocols outside specialist memory clinics.
- Digital biomarker convergence:Wearable sleep and activity sensors combined with speech analytics are creating composite cognitive decline indicators.
Industry Challenges
- Cross-functional talent gaps:Neuroimaging biostatisticians and digital health regulatory specialists remain scarce across European development teams.
- Legacy EHR interoperability:Cognitive assessment data fragmentation between hospital systems and emerging monitoring platforms complicates longitudinal patient tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mild Cognitive Impairment Market |
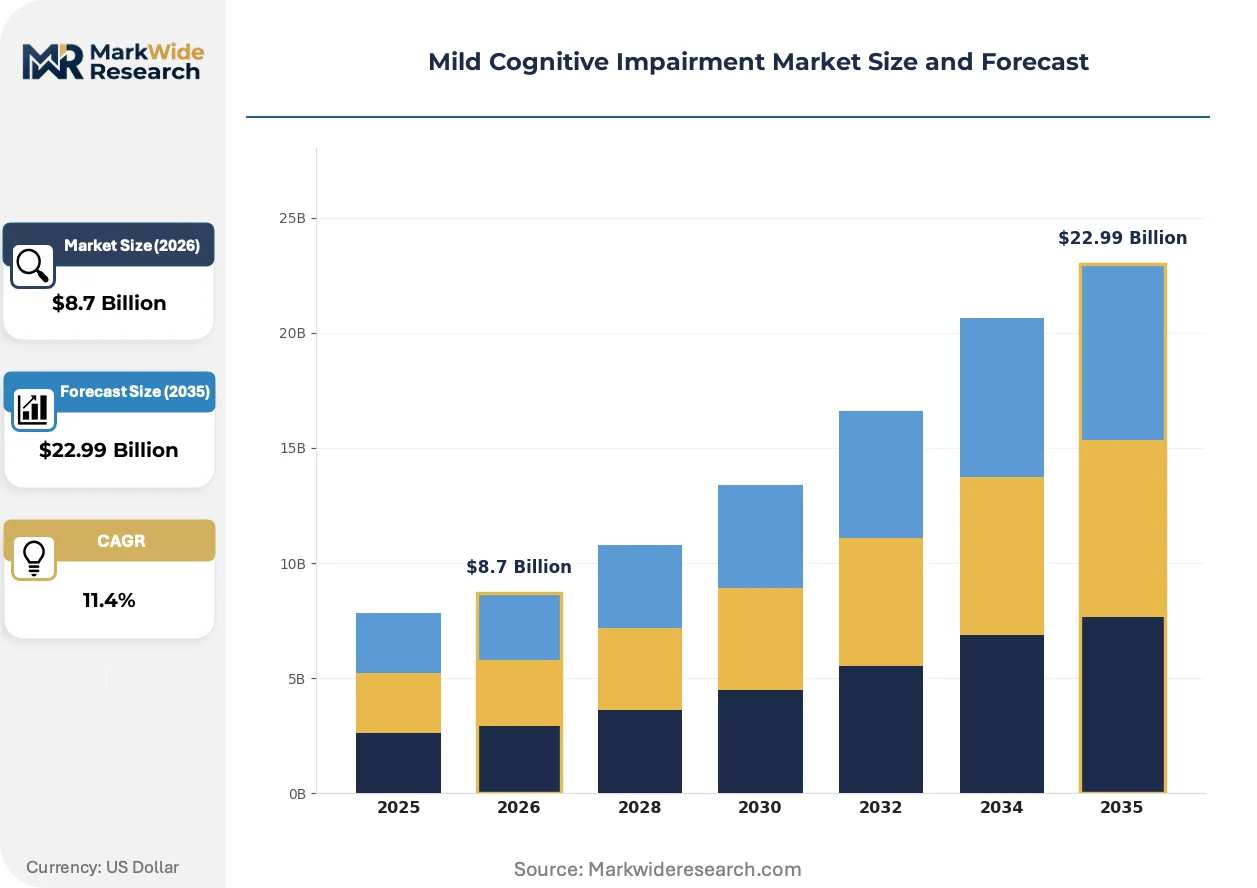
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Therapeutics, Diagnostics, Monitoring Devices Application: Memory Improvement, Cognitive Enhancement, Behavioral Therapy, Neuroprotection End User: Clinics, Research Institutions, Home Care, Hospitals Delivery Mode: Oral, Intravenous, Transdermal, Inhalation |
| Companies Covered | Johnson & Johnson Services, Inc., Pfizer Inc., Novartis AG, AbbVie Inc., Eli Lilly and Company, Biogen, Eisai Co., Ltd., Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mild Cognitive Impairment Market Shifts & Advancements
Neurotechnology convergence is dissolving boundaries between diagnostic hardware, therapeutic delivery, and longitudinal patient management, creating integrated care models that span hospital, home, and virtual environments.
Multimodal digital biomarker platforms are unifying previously siloed cognitive, functional, and physiological data streams into single patient dashboards. Memory clinics in the United States and Germany are piloting these integrated systems for MCI progression monitoring. This unification is compressing the interval between symptom detection and therapeutic intervention decisions.
EMA's qualification opinion process for digital biomarkers is formalizing evidentiary standards for cognitive monitoring devices seeking European market access. Device manufacturers must now demonstrate analytical and clinical validity against traditional neuropsychological batteries. Neurology practices in France and the Netherlands are adapting procurement criteria to prioritize EMA-recognized digital endpoints.
Patient advocacy groups are demanding earlier access to disease-modifying therapies, pressuring payers to expand pre-dementia reimbursement coverage. United States Medicare Advantage plans are piloting MCI-specific benefit categories that bundle diagnostic testing with care coordination services. This behavioral shift is most pronounced in Florida and Arizona retirement corridors where consumer expectations drive plan differentiation.
Mild Cognitive Impairment Market Segmentation
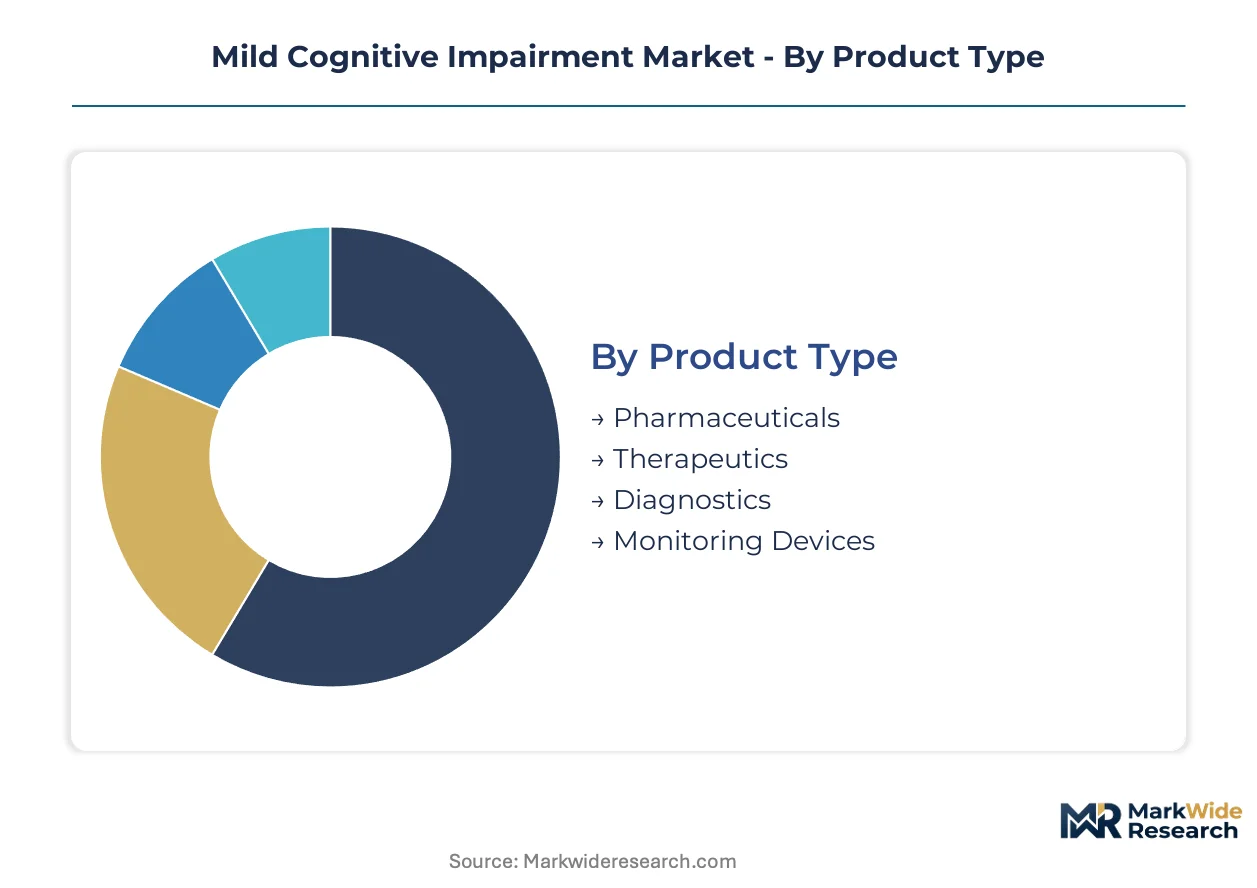
Segmentation in the MCI market reveals how therapeutic development priorities diverge from diagnostic infrastructure investments. Product portfolios must align with distinct reimbursement pathways across pharmaceuticals, devices, and monitoring platforms.
Product Type:
Pharmaceuticals command premium pricing through disease-modifying mechanisms, while diagnostics and monitoring devices compete on volume accessibility and recurring revenue models.
- Pharmaceuticals:Cholinesterase inhibitors and emerging anti-amyloid monoclonal antibodies target measurable cognitive decline biomarkers. United States Medicare coverage decisions for lecanemab and donanemab are reshaping patient eligibility criteria and prescriber workflows.
- Therapeutics:Non-pharmacological interventions including cognitive training protocols and neuromodulation devices address patients ineligible for drug therapy. Germany's statutory health insurance pilot programs for computerized cognitive rehabilitation are expanding addressable populations beyond medication responders.
- Diagnostics:Blood-based p-tau217 and p-tau181 assays reduce dependency on PET imaging infrastructure. Clinical laboratory networks in Japan and the United States are scaling high-throughput platforms for primary care screening.
- Monitoring Devices:Wearable sensors and smartphone-based cognitive assessment tools enable longitudinal tracking outside clinical settings. Rural prefectures in Japan with limited neurology access represent concentrated deployment zones for remote monitoring solutions.
Mature deployment sits with Pharmaceuticals. Newer deployment is concentrated in Monitoring Devices.
Application:
Applications stratify across symptomatic management versus disease-modification claims, with regulatory approval pathways determining commercial viability.
- Memory Improvement:Pharmacological and device-based interventions targeting episodic memory deficits represent the most clinically validated indication. Memory clinics in the United States prioritize amnestic MCI subtypes for therapeutic enrollment.
- Cognitive Enhancement:Multidomain cognitive training and lifestyle interventions address attention, processing speed, and executive function. Research institutions in Germany are conducting large-scale trials on multimodal lifestyle interventions for non-amnestic MCI presentations.
- Behavioral Therapy:Psychosocial interventions manage neuropsychiatric symptoms including depression and apathy that accelerate functional decline. Home care delivery models in Japan integrate caregiver-supported behavioral protocols for community-dwelling patients.
- Neuroprotection:Disease-modifying approaches aim to halt or reverse underlying neurodegenerative pathology. FDA accelerated approval pathways for amyloid-targeting therapies are concentrating investment in neuroprotective mechanisms.
Clinical validation concentrates in Memory Improvement. Steepest expansion trajectory is occurring in Neuroprotection.
End User:
End user channels reflect the tension between specialist diagnostic accuracy and population-scale screening accessibility.
- Clinics:Memory clinics and neurology practices deliver definitive diagnosis through comprehensive neuropsychological batteries and biomarker confirmation. United States academic medical centers are consolidating MCI subspecialty services to manage complex differential diagnoses.
- Research Institutions:Clinical trial sites and academic centers generate evidence for novel therapeutic and diagnostic platforms. EMA-qualified digital biomarker development concentrates in Netherlands and United Kingdom research consortia.
- Home Care:Remote monitoring and caregiver-mediated interventions extend care beyond facility-based settings. Japan's super-aged municipalities are deploying home-based cognitive assessment technologies to reduce institutionalization rates.
- Hospitals:Inpatient and outpatient departments manage acute presentations and comorbid conditions requiring multidisciplinary coordination. German dementia care networks embed hospital-based MCI screening within chronic disease management pathways.
Diagnostic authority rests with Clinics. Volume expansion is climbing the fastest in Home Care.
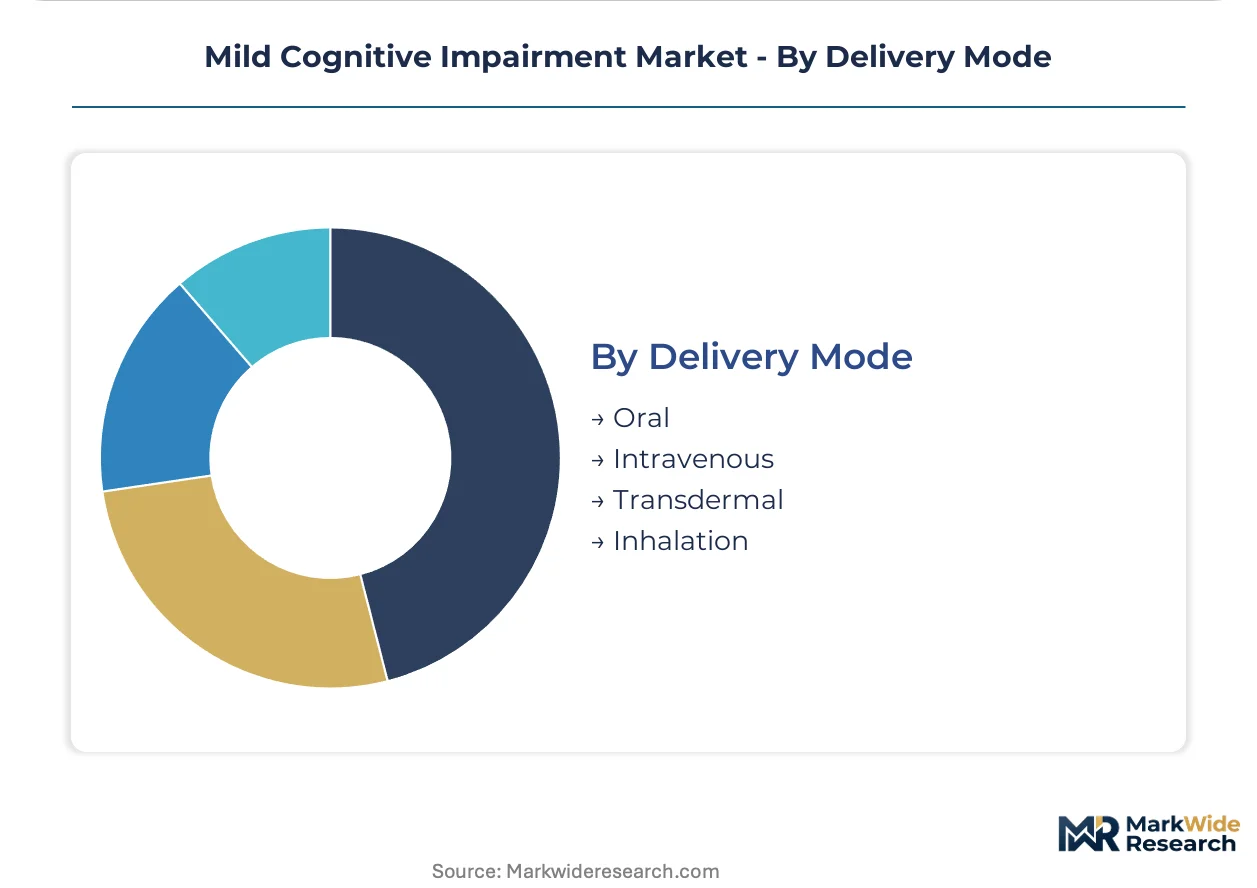
Delivery Mode:
Delivery mode selection balances bioavailability requirements with patient adherence and administration setting constraints.
- Oral:Small-molecule cholinesterase inhibitors and emerging oral amyloid-targeting agents enable self-administration and broad prescriber adoption. Primary care physicians in Germany increasingly initiate oral MCI therapies following biomarker confirmation.
- Intravenous:Monoclonal antibody infusions require specialized infusion centers with ARIA monitoring capabilities. United States infusion networks are expanding capacity to accommodate anti-amyloid therapy demand.
- Transdermal:Patch-based delivery systems improve adherence in patients with swallowing difficulties or medication regimen complexity. Japan's aging population with polypharmacy burdens shows concentrated demand for simplified delivery formats.
- Inhalation:Nasal delivery routes for insulin-based and other neuroprotective compounds target direct brain penetration. Research-stage programs are evaluating inhalation pharmacokinetics for MCI applications.
Established utilization concentrates in Oral delivery. Infrastructure investment is concentrating in Intravenous administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic infrastructure concentrates in the United States, Germany, and Japan, while therapeutic production spans multinational pharmaceutical networks. Consumption patterns diverge between memory clinic density in urban centers and emerging home-based monitoring in rural prefectures.
United States
FDA's accelerated approval pathway for amyloid-targeting therapies compresses clinical trial timelines and redirects venture capital toward pre-dementia interventions. Medicare Advantage plans in Florida and Arizona pilot MCI-specific benefit categories bundling diagnostics with care coordination. Boston's academic medical centers consolidate subspecialty services to manage complex differential diagnoses.
Germany
Statutory health insurance frameworks now reimburse pre-dementia cognitive assessments, incentivizing earlier patient identification outside specialist channels. EMA qualification opinion requirements for digital biomarkers shape how monitoring devices gain European market access. Dementia care networks in Bavaria and North Rhine-Westphalia embed hospital-based screening within chronic disease management pathways.
Japan
PMDA's Sakigake designation system prioritizes cognitive disorder innovations, accelerating market entry for disease-modifying therapies. Super-aged municipalities deploy home-based assessment technologies to reduce institutionalization rates. Rural prefectures with limited neurology access represent concentrated deployment zones for remote monitoring solutions.
United Kingdom
NHS England's dementia strategy expands memory clinic capacity to reduce diagnostic waiting times for at-risk populations. MHRA post-Brexit regulatory autonomy enables streamlined approval for novel cognitive assessment devices. Research consortia in Oxford and Cambridge concentrate EMA-qualified digital biomarker development.
Switzerland
Swissmedic's alignment with EMA standards facilitates parallel market access for diagnostic platforms targeting European patients. Private health insurance models support premium-tier cognitive monitoring subscriptions beyond statutory coverage. Basel's pharmaceutical cluster anchors neurology franchise development for multinational firms.
Mild Cognitive Impairment Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light diagnostic developers and digital health platforms for MCI market positioning. The structure consolidates around large-cap neurology franchises with approved amyloid-targeting therapies, mid-tier biotechs with pipeline assets, and emerging device specialists with biomarker platforms. Strategic archetypes include integrated pharma-neuroscience conglomerates, pure-play cognitive assessment developers, and hybrid therapeutics-diagnostics firms. Dominant competitive moves center on biomarker validation partnerships and memory clinic network acquisitions.
Among integrated pharmaceutical conglomerates, Johnson & Johnson Services, Inc., Pfizer Inc., and Novartis AG occupy positions spanning therapeutic development through diagnostic distribution. These firms exemplify the capital-intensive archetype sustaining high R&D intensity in disease-modifying programs. Their geographic footprints and clinical trial infrastructures anchor competitive positioning across United States and European regulatory environments.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Novartis AG |
| AbbVie Inc. |
| Eli Lilly and Company |
| Biogen |
| Eisai Co., Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Plasma p-tau217 assay commercialization is simultaneously collapsing diagnostic cost structures and redistributing manufacturing value toward high-throughput clinical laboratory networks in the United States and Japan. This biomarker transition concentrates production economics in automated immunoassay platforms while fragmenting service delivery across point-of-care and centralized lab models.
Pricing Analysis
Cost-down pressure on blood-based biomarker testing accelerates as Medicare coverage determinations for lecanemab and donanemab expand prescriber demand for accessible pre-dementia screening. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated laboratory-developed tests from CLIA-waived point-of-care devices and research-use-only assays. Price differentiation rests on biomarker panel complexity and reimbursement code eligibility rather than brand premium. Primary care physician offices exhibit highest price sensitivity, while academic medical centers absorb premium pricing for comprehensive neuropsychological correlation services.
Supply Chain Analysis
Single-source vulnerability sits with monoclonal antibody production for anti-amyloid therapeutics, where bioreactor capacity concentrates in the United States, Ireland, and Switzerland. Raw material dependencies include recombinant protein expression systems, synthetic peptide antigens for diagnostic assays, and specialized fluorophores for imaging agents. Supply chain risk centers on ARIA monitoring infrastructure shortages constraining infusion center expansion. Distribution runs through specialty pharmacy networks for therapeutics and clinical laboratory networks for diagnostics, with direct-to-patient remote monitoring platforms emerging as a parallel channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's accelerated approval pathway functions as a cost-of-compliance moat, where biomarker validation requirements and ARIA monitoring infrastructure investments filter out undercapitalized competitors from the disease-modifying therapy segment.
For Market Incumbents: Lock in memory clinic network relationships through exclusive diagnostic platform partnerships before blood-based assays democratize access to primary care. Defend therapeutic margins by securing preferred infusion center capacity in Florida and Arizona retirement corridors. Counter emerging digital biomarker entrants by embedding wearable monitoring into existing patient support programs. For New Entrants and Emerging Players: The price-point gap between premium monoclonal antibody infusions and economy-tier cholinesterase inhibitors creates white space for oral amyloid-targeting small molecules and transdermal delivery systems. Target Germany's dementia care networks for MCI screening protocol integration outside specialist channels. Lead with reimbursement strategy centered on statutory health insurance pilot program eligibility. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical conglomerates seeking neurology franchise expansion. Long-term viability favors platform companies combining diagnostic biomarker validation with therapeutic patient identification capabilities. Watch FDA label expansion decisions for blood-based screening assays as the inflection signal for primary care market access.| Strategic Initiative | Industry Significance |
|---|---|
| Blood-Based Biomarker Validation | FDA qualification of plasma p-tau217 assays displaces PET imaging infrastructure requirements in United States memory clinics. |
| ARIA Monitoring Infrastructure Buildout | Specialized infusion center networks in Arizona and Florida secure patient access for anti-amyloid monoclonal antibody therapies. |
| Digital Biomarker EMA Qualification | European qualification opinion process for wearable cognitive monitoring devices opens reimbursement pathways in Germany and Netherlands. |
| Primary Care Screening Integration | Germany's dementia care network pilots embed hospital-based MCI assessment within chronic disease management workflows. |
| Remote Monitoring Platform Deployment | Japan's super-aged municipalities deploy smartphone-based cognitive assessment in rural prefectures with neurologist shortages. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. FDA accelerated approval pathway documentation, EMA qualification opinion records, ClinicalTrials.gov entries, and Medicare coverage determination databases provided validation benchmarks. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment sizing.
Reconciliation of prescription data, diagnostic procedure volumes, and reimbursement claims across the projection horizon informed the analytical framework. Segmentation dimensions included treatment line, biomarker platform type, administration route, and regional regulatory cluster. CAGRs derived from logistic diffusion modeling of biomarker adoption curves and therapeutic eligibility expansion. Forecast inputs incorporated PMDA Sakigake designation timelines and Germany's statutory health insurance pilot program scaling assumptions.
Inputs from FDA, EMA, and PMDA regulatory databases were available through the study window; gaps in real-world evidence generation for digital biomarker endpoints introduce uncertainty bands around monitoring device adoption trajectories. Forecasts reflect assumptions on biomarker reimbursement code expansion and amyloid-targeting therapy label broadening. Regulatory pathway delays, ARIA safety signal emergence, or payer coverage restrictions could materially revise outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Italy Neurology Devices Market
Neurology
Neurological Biomarkers Market
Neurology
Chronic Brain Damage Management Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
Chordoma Disease Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Chiari Malformation Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Hydrocephalus Market
Neurology
Intracranial Aneurysm Market
Neurology
Neurology Services Market