

High Purity Chemical Filters Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Chemical Filters Market Insights
Filter membrane subscription programs and predictive maintenance contracts is realigning how semiconductor fabs and pharmaceutical plants procure high purity filtration systems. Entegris leverages its vertically integrated clean transport and filtration portfolio to anchor long-term supply agreements with leading foundries. Pall Corporation sustains dominance in biopharmaceutical sterile filtration through validated single-use architectures. Cobetter Filtration competes aggressively on cost-engineered membrane alternatives for mid-tier electronics manufacturers across East Asia.
High purity chemical filters are engineered media assemblies designed to remove particulate, ionic, and organic contaminants from process chemicals at purity thresholds typically below 0.03 particles per milliliter for critical semiconductor and pharmaceutical applications. These filters employ polyethersulfone, polytetrafluoroethylene, or nylon membranes with absolute retention ratings from 0.03 to 0.1 micrometers, manufactured in ISO Class 3 cleanrooms to prevent secondary contamination during assembly. Membrane filters command premium positioning in semiconductor fabrication where sub-10nm node processes demand absolute particle retention with minimal extractables. Semiconductor grade filtration exhibits the steepest growth trajectory as advanced packaging and EUV lithography chemical loops require more frequent filter replacement cycles.
EPA effluent guidelines, REACH substance restrictions, and FDA process validation requirements collectively tighten specifications for filter extractables, compatibility documentation, and change-control protocols. Semiconductor fabs in the United States face overlapping EPA and OSHA compliance obligations for chemical handling, while European pharmaceutical manufacturers navigate EMA and ECHA dual frameworks for product contact materials. Buyers must weigh total cost of ownership against regulatory audit readiness when selecting between established membrane suppliers and emerging Asian competitors.
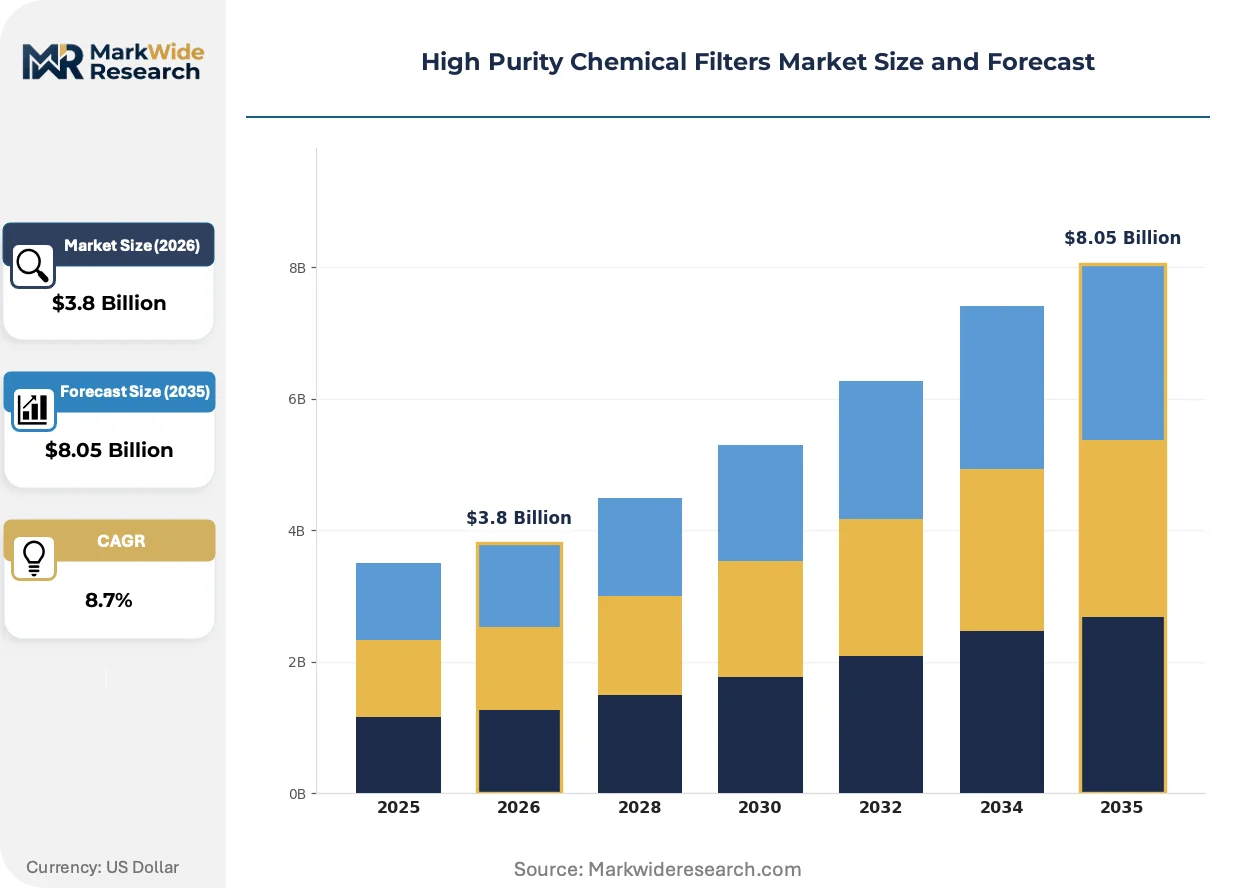
Market Dynamics
Sub-7nm semiconductor node transitions are compressing filter replacement cycles while fragmenting supplier qualification pathways across Taiwan, South Korea, and Arizona fabrication clusters. This structural force is redrawing procurement hierarchies and technical validation timelines.
Growth Catalysts
- EUV lithography chemical loops:Advanced packaging processes in Taiwanese foundries demand absolute particle retention below 0.03 particles per milliliter, forcing quarterly filter swaps versus annual cycles.
- REACH substance restrictions:ECHA mandates on extractable compounds from filter media are compelling European pharmaceutical manufacturers to upgrade to validated single-use architectures.
- Phoenix and Austin fab clusters:CHIPS Act-funded construction in these US cities is creating captive demand for semiconductor-grade filtration with domestic sourcing preferences.
Market Restraints
- Polyethersulfone resin concentration:Three Japanese chemical conglomerates control 70% of high-purity membrane polymer supply, exposing buyers to input cost volatility.
- ISO Class 3 cleanroom scarcity:Qualified assembly facilities cluster in Hsinchu and Seoul, creating geographic concentration risk for membrane manufacturing.
- Extractables documentation burden:FDA process validation requirements extend qualification timelines to 18-24 months for new filter suppliers.
Strategic Opportunities
- Indian pharmaceutical API manufacturing:CDSCO alignment with ICH Q7 guidelines is opening demand for sterile filtration in Hyderabad and Ahmedabad production zones.
- Predictive maintenance contracts:Sensor-embedded filter housings enabling real-time pressure-drop monitoring are displacing scheduled replacement models in South Korean foundries.
- Dual-use membrane architectures:Convergence of semiconductor and biopharma purity thresholds is allowing suppliers to cross-qualify single product lines across both sectors.
Industry Challenges
- Cleanroom technician scarcity:ISO Class 3 assembly operations require specialized contamination-control training that outpaces vocational pipeline output in Taiwan and Arizona.
- Legacy wet-bench integration:200mm fab retrofits face mechanical incompatibility with next-generation filter housing geometries, forcing costly tool modifications.
- Cross-regulatory audit fatigue:Simultaneous EPA, FDA, and EMA inspections strain quality documentation systems at multi-site suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Chemical Filters Market Trends and Innovations
Membrane manufacturing and filter lifecycle management are undergoing parallel digitization, with cleanroom robotics and predictive analytics converging to reduce human-induced contamination while compressing total cost of ownership.
Automated cleanroom assembly lines deploying collaborative robots for membrane pleating and housing sealing are automating the final manufacturing stages previously requiring manual intervention. Taiwanese and South Korean foundry suppliers are adopting these systems fastest, driven by labor cost pressures and particle-count consistency requirements. This automation is compressing the viable supplier base to capital-rich players capable of eight-figure equipment investments.
REACH Annex XVII expansions targeting per- and polyfluoroalkyl substances are forcing reformulation of PTFE membrane production chemistry across European supply chains. Filter manufacturers must resubmit extractables profiles and compatibility data for revised polymer grades. Biopharmaceutical sterile filtration applications face the steepest requalification burden, with EMA demanding updated validation packages before 2026.
Subscription-based filter procurement is displacing spot purchasing in Arizona and Texas semiconductor construction sites, with multi-year agreements bundling predictive replacement scheduling and regulatory documentation. Equipment OEMs are capturing this service layer through direct channel expansion, bypassing traditional distribution. This model concentrates most visibly in greenfield US fabs where capital discipline favors operational expenditure structures over inventory carrying costs.
High Purity Chemical Filters Market Segmentation
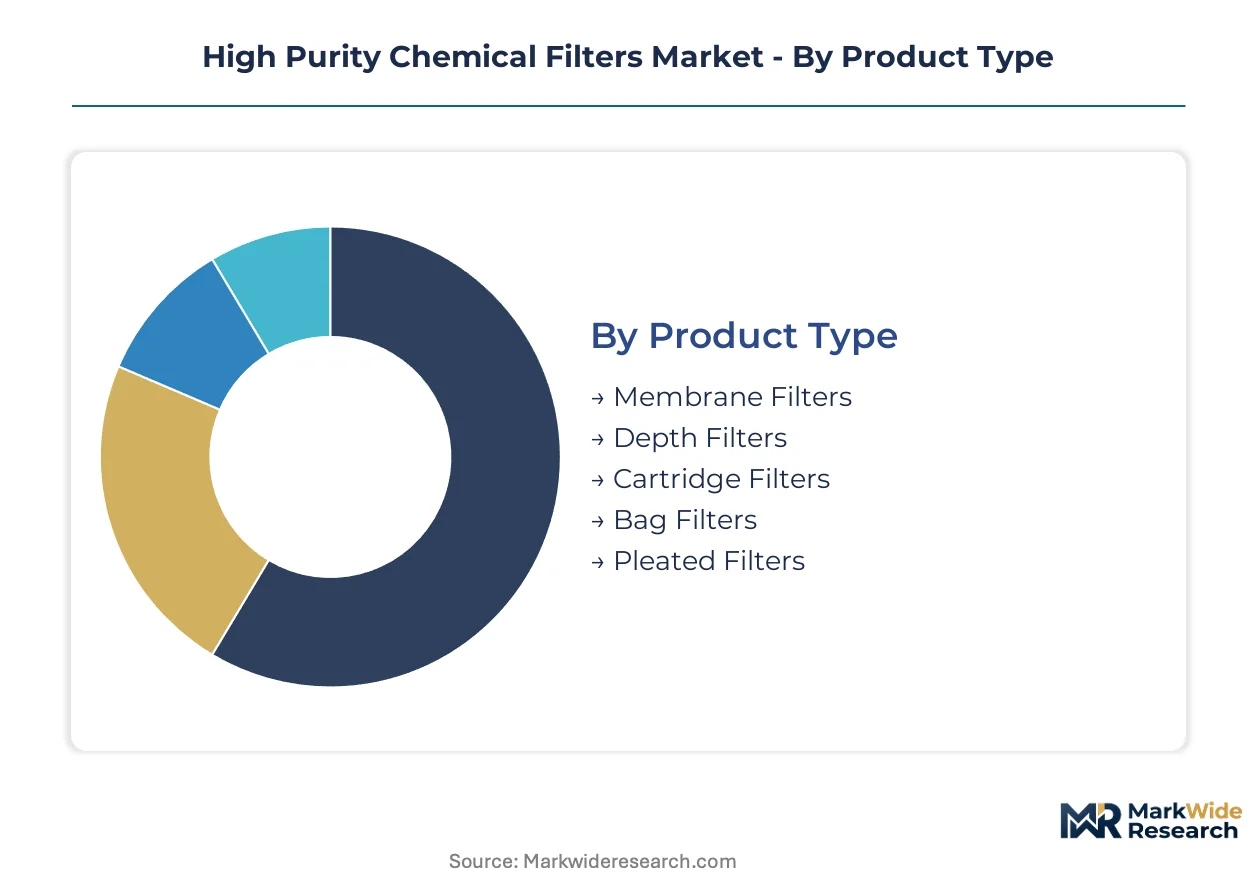
High purity chemical filter procurement decisions pivot on integration architecture, with standalone cartridge systems dominating high-volume semiconductor wet benches while embedded membrane modules serve compact pharmaceutical single-use lines. Segmentation clarity enables suppliers to align qualification investments with specific validation pathways.
Product Type:
Membrane filters operate as standalone final-stage barriers or embedded within multi-stage trains, while depth and bag configurations serve exclusively as pre-filtration in integrated systems.
- Membrane Filters:Polyethersulfone, PTFE, or nylon membranes deliver absolute retention ratings from 0.03 to 0.1 micrometers for critical semiconductor and pharmaceutical applications. Taiwanese foundries and South Korean packaging houses consume the majority of output as EUV lithography chemical loops force quarterly replacement cycles.
- Depth Filters:Graded-density polypropylene or borosilicate media remove bulk particulate loads upstream of membrane stages. Pharmaceutical manufacturers in Hyderabad and Ahmedabad deploy these as standalone guard filters for API solvent clarification.
- Cartridge Filters:Self-contained pleated media assemblies with standardized 222 or 226 O-ring configurations enable rapid housing swaps. Food processors in Germany and Switzerland specify these for beverage sterile filtration where CIP/SIP compatibility matters.
- Bag Filters:Felt or mesh media in welded polypropylene housings handle high-contaminant-load chemical processing. Specialty chemical producers in the US Gulf Coast use standalone bag systems for aggressive solvent pre-filtration.
- Pleated Filters:High-surface-area membrane or depth media in cylindrical geometries maximize flow per housing volume. Water purification plants in Singapore and Israel embed these in municipal ultrapure water generation trains.
Volume placements concentrate in Membrane Filters; the faster expansion belongs to Pleated Filters.
Grade:
Purity thresholds stratify procurement budgets, with semiconductor-grade commanding five-to-ten-fold premiums over laboratory-grade due to extractables documentation and ISO Class 3 assembly requirements.
- Semiconductor Grade:Sub-0.03 particles per milliliter specifications with full ionic and organic extractables profiles. Arizona and Texas fab construction under CHIPS Act funding is absorbing captive supply with domestic sourcing preferences.
- Pharmaceutical Grade:USP Class VI and EP 3.1.9 compliance for product-contact applications. EMA and FDA dual validation requirements extend qualification timelines to 18-24 months for new suppliers.
- Electronic Grade:Intermediate purity for display manufacturing and passive component production. Chinese panel fabs in Shenzhen and Chengdu represent steady demand with less stringent change-control protocols.
- Laboratory Grade:Analytical and R&D applications with batch-level consistency documentation. Research laboratories in Boston and Basel purchase through distribution with spot-buying patterns.
- Food Grade:FDA and EFSA compliance for beverage and ingredient filtration. Italian and Spanish wine producers specify these for cold stabilization and microbial stabilization steps.
Revenue concentration sits with Semiconductor Grade; Pharmaceutical Grade climbs the fastest as EMA extractables mandates tighten.
Application:
Process intensity and chemical aggressiveness determine filter replacement economics, with semiconductor fabrication generating the steepest consumption curves per unit output.
- Semiconductor Fabrication:Sub-7nm node processes require absolute particle retention in photoresist, etchant, and CMP slurry loops. Hsinchu and Seoul clusters dominate consumption as foundry capital expenditure accelerates.
- Pharmaceutical Manufacturing:Sterile filtration of parenteral drugs and biologics demands validated single-use architectures. CDSCO alignment with ICH Q7 guidelines is opening Indian API production zones to Western filter suppliers.
- Chemical Processing:Solvent recovery and specialty chemical production use corrosion-resistant PTFE or PVDF media. German and Belgian chemical parks specify these for halogenated solvent handling.
- Water Purification:Ultrapure water for power generation and electronics rinsing employs multi-stage membrane trains. Israeli desalination plants and Singapore NEWater facilities embed these in municipal infrastructure.
- Food & Beverage Processing:Wine, beer, and dairy applications prioritize microbial retention with flavor preservation. French and Italian producers lead adoption of cross-flow membrane systems for white wine clarification.
Unit economics favor Semiconductor Fabrication for revenue per filter; Pharmaceutical Manufacturing gains share fastest as biologics capacity expands.
End User:
Buyer sophistication and validation burden separate procurement patterns, with microelectronics firms demanding predictive maintenance contracts while food processors prioritize spot purchasing.
- Microelectronics Firms:Foundries and IDMs with captive filter qualification laboratories and multi-year supply agreements. Intel and TSMC procurement teams negotiate subscription-based replacement scheduling with sensor-embedded housings.
- Biotechnology Companies:Cell therapy and mRNA producers requiring single-use sterile filtration with full extractables documentation. Boston and San Francisco clusters drive demand for validated gamma-stable membrane architectures.
- Specialty Chemical Producers:Agrochemical and electronic material manufacturers with batch-process filtration needs. BASF and Merck KGaA operations specify corrosion-resistant cartridge systems for aggressive solvent handling.
- Research Laboratories:Academic and government facilities with low-volume, high-variety purchasing patterns. NIH and Max Planck Institute procurement flows through distributor channels with minimal technical support requirements.
- Food Processors:Dairy, beverage, and ingredient manufacturers with seasonal demand fluctuations and price-sensitive procurement. Nestlé and Danone facilities in Switzerland and France standardize on validated steam-in-place cartridge systems.
Contract value concentrates with Microelectronics Firms; Biotechnology Companies expand most quickly as cell therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Filter membrane production concentrates in East Asian cleanroom clusters while consumption spreads across semiconductor fabrication sites in Taiwan, South Korea, and the United States. This geographic split creates supply chain exposure for Western fabs dependent on imported assemblies.
Taiwan
EUV lithography chemical loops at TSMC's Hsinchu facilities demand quarterly filter replacements versus annual cycles, compressing procurement timelines. The island's national science council prioritizes domestic filtration capacity under its semiconductor advancement program. Tainan Science Park hosts expanding membrane pleating operations serving foundry captive demand.
South Korea
Samsung and SK Hynix packaging houses consume membrane filters for advanced interconnect processes at sub-10nm nodes. MFDS pharmaceutical regulations align with FDA standards, enabling dual-use membrane qualification across sectors. Seoul metropolitan cleanroom facilities supply both domestic fabs and export markets.
United States
CHIPS Act funding drives construction in Phoenix and Austin, creating captive demand for semiconductor-grade filtration with domestic sourcing preferences. EPA effluent guidelines and OSHA chemical handling rules overlap for fab compliance. Arizona State University partnerships train ISO Class 3 technicians for local assembly operations.
Germany
BASF and Merck KGaA specialty chemical operations specify corrosion-resistant cartridge systems for halogenated solvent handling. ECHA REACH Annex XVII expansions force PTFE membrane reformulation across European supply chains. Frankfurt-Rhine-Main chemical parks integrate filtration into solvent recovery infrastructure.
India
Hyderabad and Ahmedabad API manufacturing zones open to Western filter suppliers as CDSCO aligns with ICH Q7 guidelines. Domestic pharmaceutical regulators mandate extractables documentation previously absent from local procurement. Karnataka's biotech corridor attracts sterile filtration investment for cell therapy production.
High Purity Chemical Filters Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the filtration value chain, with integrated membrane manufacturers facing specialized component suppliers. The supplier base stratifies into three tiers: vertically integrated clean transport providers, standalone membrane specialists, and regional cost-engineered alternatives. Dominant competitive moves include predictive maintenance service bundling and multi-year subscription contracting.
Within the integrated systems tier, Entegris anchors long-term supply agreements through its combined clean transport and filtration portfolio. Pall Corporation exemplifies the standalone membrane specialist archetype with validated single-use architectures. Cobetter Filtration occupies a position among cost-engineered alternatives targeting mid-tier electronics manufacturers across East Asia.
| Leading Market Players |
|---|
| Entegris |
| Pall Corporation |
| Merck KGaA |
| 3M |
| Donaldson Company |
| Sartorius |
| Parker Hannifin |
| Cobetter Filtration |
| Porvair |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up membrane specialists have consolidated ISO Class 3 cleanroom assets across Taiwan and South Korea, tightening supply discipline and anchoring long-term contract pricing for semiconductor-grade filtration. This ownership concentration feeds directly into buyer procurement leverage, as foundries negotiate multi-year subscriptions against limited qualified supplier pools.
Pricing Analysis
Cost-down pressure on mid-tier electronics manufacturers accelerates because Cobetter Filtration and regional Asian competitors are undercutting established membrane suppliers on polyethersulfone alternatives. Three-tier pricing structure across semiconductor-grade, pharmaceutical-grade, and laboratory-grade levels separates procurement budgets by certification intensity and extractables documentation burden. Pricing pressure stems from Japanese resin conglomerates controlling high-purity polymer feedstock, exposing buyers to input volatility. Biotechnology companies exhibit the lowest price sensitivity due to FDA validation lock-in, while display panel fabs in China negotiate aggressively on electronic-grade volumes.
Supply Chain Analysis
ISO 14644-1 Class 3 certification requirements gate membrane assembly to qualified cleanroom facilities clustering in Taiwan, South Korea, and Japan, creating geographic concentration risk for Western semiconductor construction. Polyethersulfone resin, PTFE membrane substrate, and precision pleating equipment draw from Japanese chemical conglomerates and German automation suppliers, exposing the chain to single-source vulnerability for high-purity polymers. Tariff exposure looms for CHIPS Act-funded US fabs dependent on imported Taiwanese assemblies. Distribution runs through equipment OEM direct channels in Arizona and Texas greenfield sites, displacing traditional distributor relationships with subscription-based service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a technology-transition phase where EUV lithography chemical loops are displacing legacy DUV filtration architectures, forcing quarterly replacement cycles and predictive maintenance adoption.
For Market Incumbents: Anticipate margin compression from cost-engineered Asian competitors by deepening backward integration into polyethersulfone resin purification and expanding captive cleanroom capacity in Phoenix and Austin. Lock in multi-year subscription contracts with sensor-embedded filter housings before equipment OEMs capture the service layer. Certification investment in dual-use membrane architectures for semiconductor and biopharma cross-qualification is essential. For New Entrants and Emerging Players: Enter via the Indian pharmaceutical API manufacturing corridor, where CDSCO alignment with ICH Q7 guidelines is opening sterile filtration demand previously served by unvalidated local suppliers. Target Hyderabad and Ahmedabad production zones with extractables documentation packages that domestic competitors cannot assemble. A go-to-market angle through Western filter distributors seeking geographic expansion offers fastest qualification pathways. For Investors and Strategic Acquirers: CHIPS Act fab construction announcements are the leading indicator that captive semiconductor-grade filtration demand will concentrate procurement power among vertically integrated clean transport providers. Long-term viability favors asset-heavy players with ISO Class 3 assembly ownership rather than design-only membrane specialists. Watch for predictive maintenance contract penetration rates in South Korean foundries as the signal for service-layer capture inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Purification | Japanese chemical conglomerate supply concentration creates captive feedstock advantages for membrane manufacturers. |
| Predictive Maintenance Contract Expansion | Sensor-embedded filter housings in TSMC and Samsung facilities displace scheduled replacement models. |
| Dual-Use Membrane Cross-Qualification | Converging semiconductor and biopharma purity thresholds allow single product lines to serve both sectors. |
| ISO Class 3 Cleanroom Capacity Addition | Scarcity of qualified assembly facilities in Taiwan and Seoul creates geographic expansion opportunities. |
| Subscription-Based Procurement Model | Multi-year agreements bundling replacement scheduling and regulatory documentation capture greenfield US fab demand. |
Research Methodology
Independent corroboration across filtration procurement executives at foundry operators, cleanroom engineering directors at membrane manufacturers, and regulatory affairs leads at pharmaceutical OEMs underwrites the qualitative findings in this study. Primary interviews with plant managers at Taiwanese and South Korean packaging houses combined with secondary validation from SEC filings, EPA effluent guideline updates, and ECHA REACH Annex XVII documentation establish demand-side triangulation. Bottom-up membrane shipment analysis and top-down semiconductor capital expenditure tracking converge on segment sizing.
Comparable-period anchoring to historical filter replacement cycle data and foundry utilization rates structured the forecast window across the projection horizon. Segmentation modeling incorporated product type, grade tier, application intensity, and regional regulatory cluster dimensions. CAGRs derive from installed base expansion and replacement frequency compression, with EUV lithography adoption curves and CHIPS Act construction timelines as semiconductor-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH substance restriction expansions or polyethersulfone supply disruptions. Forecasts reflect documented assumptions on node transition timelines and cleanroom capacity buildout rates. A model refresh is warranted upon material change in EPA effluent guideline enforcement or Japanese resin supplier consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.