

ePTFE Filter Film Market Size, Share, and Industry Trends Forecast 2026-2036
ePTFE Filter Film Market Insights
Maintenance contracts and membrane replacement services is expanding as a recurring revenue layer that shifts vendor economics from unit sales to lifecycle partnerships. W. L. Gore & Associates leverages its vertical integration across resin through finished membrane to sustain premium positioning in critical applications. Donaldson Company anchors its industrial filtration portfolio with extensive aftermarket service networks. Pall Corporation specializes in validation protocols that pharmaceutical clients require for regulatory compliance.
Expanded polytetrafluoroethylene filter film consists of a microporous membrane created through mechanical stretching of PTFE resin, producing interconnected fibrils with pore sizes typically ranging from 0.1 to 10 micrometers for precise particulate and microbial retention. The material serves primarily as a chemically inert barrier in aggressive environments where thermal stability and hydrophobicity prevent contamination across air, liquid, and sterile process streams. Microporous film dominates current volume owing to its established role in HVAC and industrial dust collection, while composite film commands margin premiums through layered constructions that combine ePTFE with polypropylene or polyester supports for mechanical durability. Electronics protection applications accelerate fastest as semiconductor fabricators adopt finer filtration grades to protect advanced lithography processes from airborne molecular contamination.
EPA National Ambient Air Quality Standards and FDA Good Manufacturing Practice requirements shape product specifications by mandating verified filtration efficiency and extractable testing for pharmaceutical and environmental applications. ISO 16890 for air filter testing and ISO 29463 for HEPA and ULPA filters provide international benchmarks that manufacturers must meet for cross-border equipment supply. REACH restrictions in Europe limit certain fluoropolymer processing aids, creating compliance complexity for producers serving multiple regulatory jurisdictions. Stakeholders must monitor evolving PFAS regulatory classifications and assess alternative chemistries before jurisdictions impose production or use limitations.
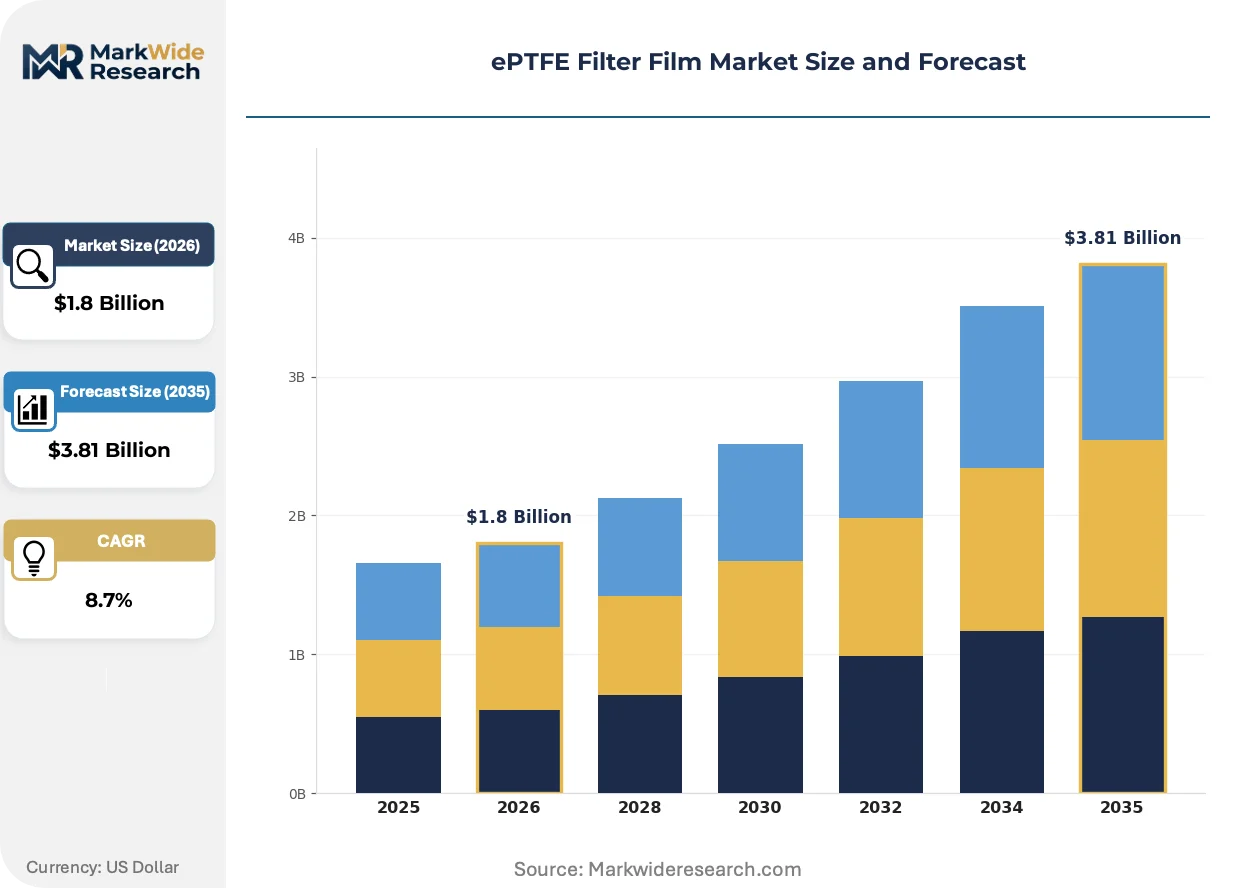
Market Dynamics
Semiconductor fabrication nodes below 7nm demand sub-0.1 micrometer filtration precision, forcing membrane manufacturers to stretch ePTFE fibril structures beyond conventional mechanical limits while maintaining pore uniformity across roll widths exceeding two meters.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightened particulate limits for industrial emissions mandate high-efficiency filtration in cement, steel, and chemical processing facilities across the United States.
- Biologics manufacturing expansion:Single-use sterile filtration systems in antibody and cell therapy production require validated ePTFE membranes with documented extractable profiles.
- Lithium-ion battery dry rooms:Electrode manufacturing environments in China and South Korea specify ultra-low moisture transmission rates that only hydrophobic ePTFE barriers reliably achieve.
Market Restraints
- Fluoropolymer resin supply concentration:Virgin PTFE resin production clusters among three chemical conglomerates, exposing membrane converters to feedstock allocation constraints and price volatility.
- REACH fluoropolymer processing aid restrictions:ECHA scrutiny of perfluorinated surfactants complicates European manufacturing compliance without equivalent substitutes for pore formation.
- Electrospun nanofiber substitution:Polyimide and polyvinylidene fluoride nanofiber media achieve comparable filtration efficiency at lower basis weights in HVAC pre-filtration applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO alignment with PIC/S standards drives import substitution of validated filtration components for sterile injectable production.
- Hydrogen electrolyzer humidity management:Proton exchange membrane electrolysis systems require precisely calibrated moisture barriers in balance-of-plant gas handling.
- EU F-Gas Regulation phase-down:Refrigeration system leak detection and recovery equipment specifications expand demand for chemically resistant membrane sensors.
Industry Challenges
- Cleanroom validation protocol complexity:Pharmaceutical clients require 12-18 month qualification timelines for new membrane lots, compressing product development cycles.
- Skilled biaxial stretching technicians:Precision control of fibril formation demands operators with polymer physics expertise that training programs have not scaled to match fabrication capacity expansion.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ePTFE Filter Film Market Trends and Innovations
Membrane architecture is fragmenting into application-specific constructions that sacrifice universal compatibility for targeted performance optimization in extreme operating environments.
Multilayer composite constructions pairing ePTFE active layers with polypropylene or polyethylene terephthalate nonwoven supports is overtaking monolithic microporous film in semiconductor cleanroom HVAC specifications. Fabricators in Taiwan and South Korea specify these laminates for mechanical durability during pleating and extended service intervals. The shift is compressing demand for unsupported ePTFE in mid-efficiency applications while elevating technical barriers for converters lacking lamination expertise.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of processing aids used in ePTFE expansion. ECHA substance evaluation timelines create regulatory uncertainty for European production facilities. Membrane manufacturers are responding by qualifying alternative surfactant systems and accelerating documentation for polymer-of-low-concern exemptions ahead of 2025 restriction deadlines.
Equipment OEMs are unbundling membrane replacement services from initial system sales, creating dedicated aftermarket revenue streams. Donaldson Company and Pall Corporation have restructured field service organizations around predictive maintenance contracts. This reconfiguration is most advanced in United States pharmaceutical and food processing installations where unplanned downtime costs exceed membrane replacement expenses by orders of magnitude.
ePTFE Filter Film Market Segmentation
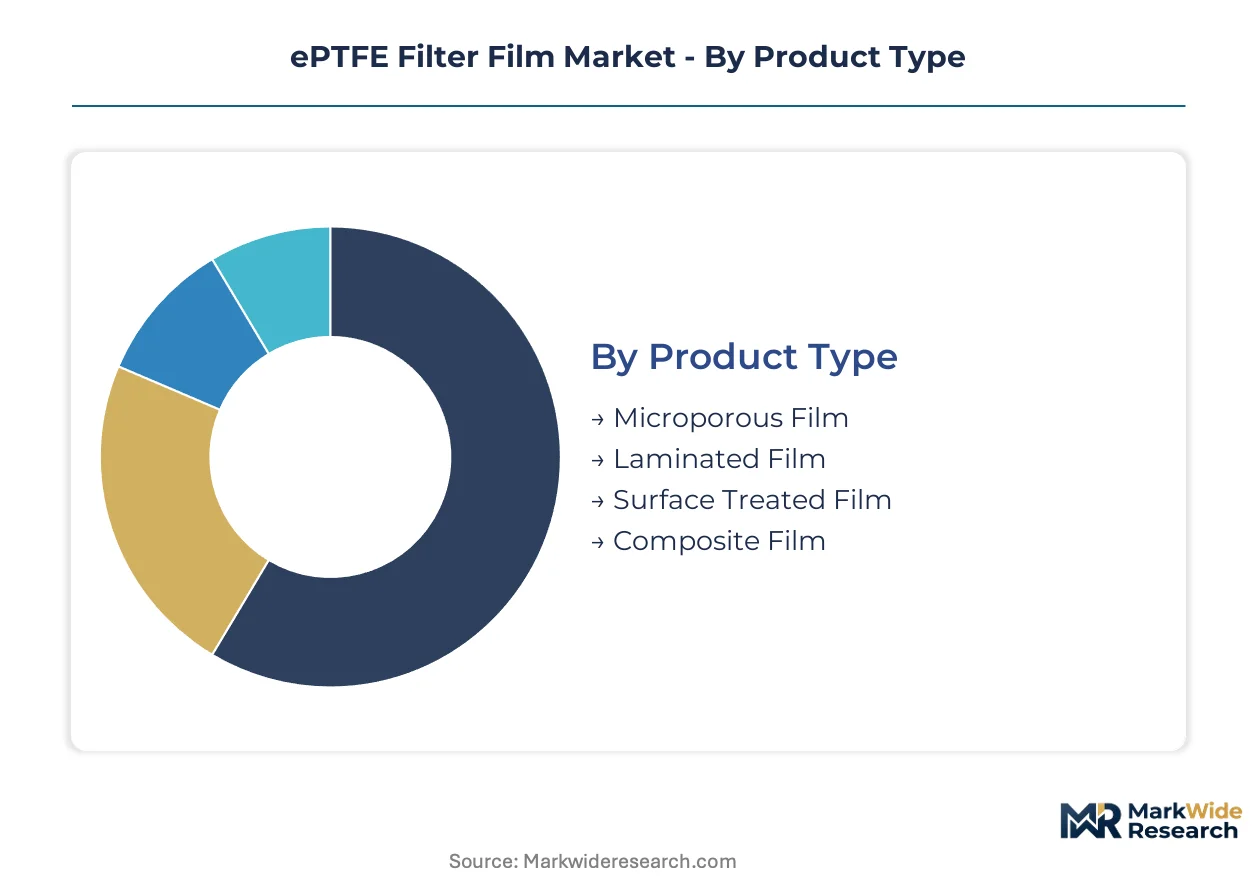
ePTFE filter film segmentation reflects divergent technical requirements across sterile process validation, semiconductor contamination control, and industrial emissions compliance. Product architecture, application environment, and end-user regulatory exposure create distinct purchasing criteria that reshape vendor specialization.
Product Type:
Customization intensity spans from commodity microporous rolls to engineered composite laminates requiring application-specific qualification protocols.
- Microporous Film:Monolithic expanded PTFE structures with fibril-based porosity serve HVAC dust collection and general industrial ventilation. Cement producers in the United States and steel mills in China specify these films for EPA and MEE particulate compliance.
- Laminated Film:ePTFE active layers bonded to polypropylene or polyester nonwoven supports dominate semiconductor cleanroom specifications in Taiwan and South Korea. Fabricators prize mechanical durability during pleating and extended service intervals in sub-0.1 micrometer filtration environments.
- Surface Treated Film:Chemical functionalization modifies hydrophobicity or charge characteristics for specialized liquid filtration.
- Composite Film:Multi-layer constructions combining ePTFE with fluorinated ethylene propylene or perfluoroalkoxy alkane layers command premium positioning in aggressive chemical processing.
Most installed capacity flows through Microporous Film. Expansion is steepest in Laminated Film.
Application:
Volume concentration sits with mature air handling systems while value creation migrates toward contamination-sensitive electronics manufacturing.
- Air Filtration:HVAC and industrial dust collection applications consume standard-efficiency microporous media. EPA National Ambient Air Quality Standards enforcement drives replacement cycles in United States cement, steel, and chemical facilities.
- Electronics Protection:Semiconductor lithography and wafer handling environments demand sub-0.1 micrometer filtration precision against airborne molecular contamination. Fabricators below 7nm nodes in Taiwan, South Korea, and the United States specify validated membrane lots with documented cleanliness protocols.
- Liquid Filtration:Pharmaceutical sterile processing and chemical purification employ hydrophobic barriers for aggressive solvent streams.
- Medical Devices:Implantable and diagnostic applications require biocompatibility testing and FDA 510(k) or PMA pathway documentation.
Air Filtration retains the largest installed base. Electronics Protection is climbing the fastest as advanced node fabrication expands.
End User Industry:
Procurement sophistication separates validated pharmaceutical buyers from price-sensitive industrial operators.
- Pharmaceutical Manufacturers:Single-use sterile filtration systems for antibody and cell therapy production demand extractable profiles and 12-18 month lot qualification timelines. FDA Good Manufacturing Practice requirements and EMA guidelines shape supplier selection across United States and European facilities.
- Semiconductor Fabricators:Cleanroom HVAC and process equipment specifications prioritize particle retention efficiency and membrane uniformity across two-meter roll widths. Taiwan and South Korean fabricators lead adoption of finer filtration grades for sub-7nm production nodes.
- Chemical Processing:Corrosion-resistant barriers for chlorine, sulfuric acid, and fluorinated compound handling emphasize material inertness over validation documentation.
- Food & Beverage Producers:Venting and sterile air applications balance regulatory compliance with operational cost constraints.
Pharmaceutical Manufacturers deploy the most rigorous qualification protocols. Semiconductor Fabricators are gaining share fastest as fabrication capacity concentrates in East Asia.
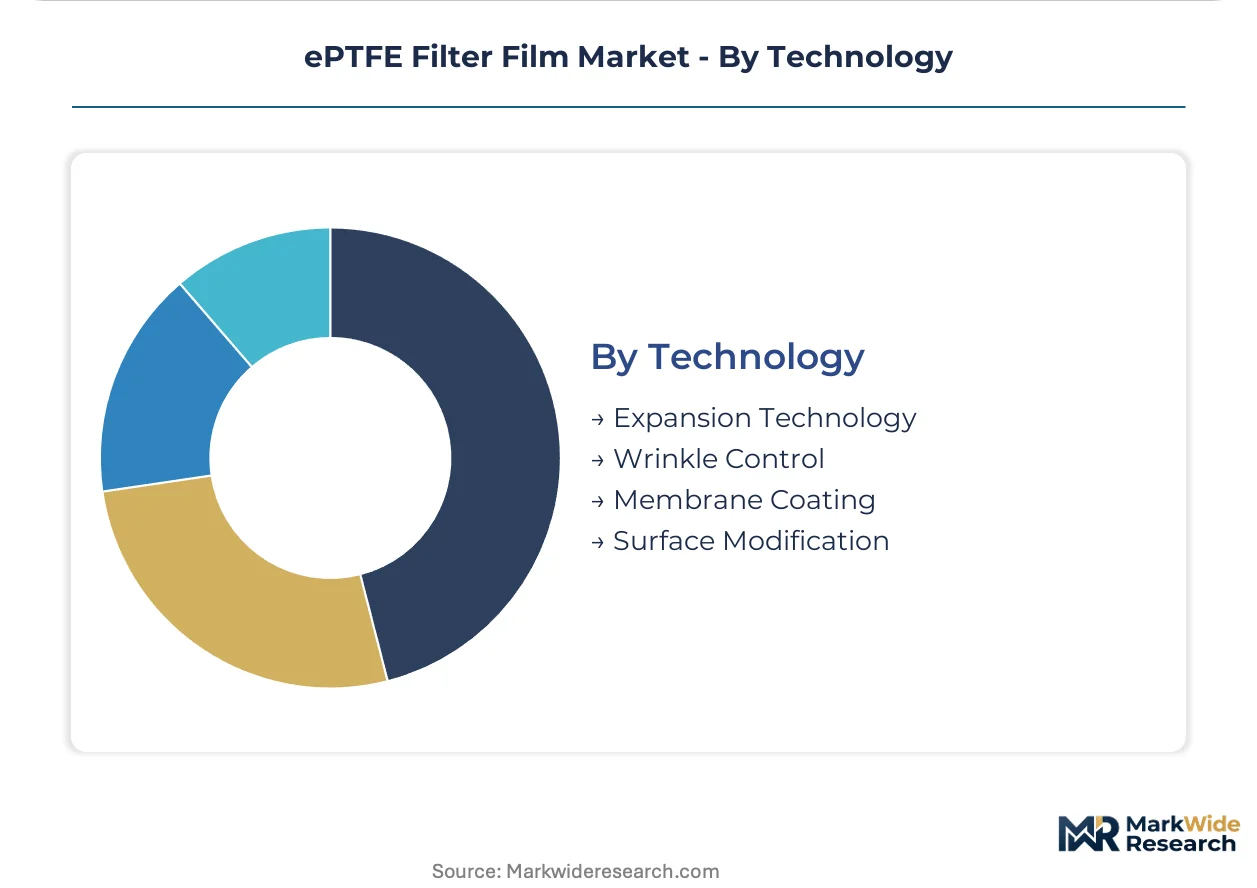
Technology:
Process control differentiation separates commodity converters from precision membrane specialists.
- Expansion Technology:Biaxial stretching of PTFE resin creates microporous fibril structures with pore size distributions from 0.1 to 10 micrometers. Mastery of temperature and strain rate controls separates premium suppliers from commodity producers.
- Wrinkle Control:Tension management during expansion prevents defects that compromise filtration uniformity in wide-format rolls required by semiconductor fabricators.
- Membrane Coating:Functional layer deposition modifies surface energy or adds catalytic properties for specialized chemical processing applications.
- Surface Modification:Plasma treatment or chemical grafting adjusts hydrophobicity for liquid-liquid separation or enhanced particle capture.
Expansion Technology underpins the majority of production capacity. Wrinkle Control is expanding most quickly as roll width requirements exceed two meters for cleanroom HVAC specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's semiconductor fabrication expansion outpaces United States pharmaceutical demand in absolute volume growth, though the latter commands higher unit values per square meter of membrane.
United States
EPA National Ambient Air Quality Standards enforcement drives replacement cycles in cement and steel facilities. FDA Good Manufacturing Practice requirements shape supplier selection for sterile injectable production. The Gulf Coast chemical processing corridor and Boston-Cambridge biotech cluster anchor demand for validated membrane lots.
China
MEE particulate compliance mandates reshape industrial emissions control investments. Dual carbon goals accelerate cleanroom construction for domestic semiconductor self-sufficiency. Yangtze River Delta fabrication facilities below 7nm nodes specify sub-0.1 micrometer filtration precision.
Germany
REACH fluoropolymer processing aid restrictions complicate manufacturing compliance for membrane converters. ECHA substance evaluation timelines create regulatory uncertainty ahead of 2025 deadlines. The Rhine-Ruhr industrial belt and Bavarian automotive electronics cluster drive HVAC and process filtration specifications.
South Korea
Samsung and SK Hynix fabrication capacity expansion concentrates demand for laminated composite films. MFDS alignment with PIC/S standards elevates pharmaceutical filtration validation protocols. The Seoul Capital Area and Busan-Ulsan electronics corridor lead adoption of two-meter roll width specifications.
India
CDSCO alignment with PIC/S standards drives import substitution for sterile injectable production. PLI scheme incentives attract semiconductor assembly and test facilities. Maharashtra and Gujarat pharmaceutical manufacturing clusters require documented extractable profiles for single-use filtration systems.
ePTFE Filter Film Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical validation protocols favoring established membrane suppliers while industrial HVAC applications tolerate broader sourcing. The market structure concentrates around three to five vertically integrated resin-to-membrane producers alongside regional converters serving price-sensitive dust collection. Two archetypes dominate: premium-tier validators with 12-18 month qualification timelines, and scale-driven commodity suppliers optimizing roll width throughput. Competitive moves center on backward integration into PTFE resin supply and predictive maintenance service bundling.
Among United States-based fabricators, W. L. Gore & Associates exemplifies premium-tier positioning through captive resin production, while Donaldson Company anchors industrial aftermarket service networks. Pall Corporation occupies a specialized position in pharmaceutical validation protocols. These three represent distinct strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Donaldson Company |
| Pall Corporation |
| Saint-Gobain Performance Plastics |
| Nitto Denko |
| Zeus Industrial Products |
| Markel Corporation |
| Suzhou Cobetter Filtration Equipment |
| Shanghai JINYOU Fluorine Materials |
| Others |
Pricing and Supply Chain Analysis
Virgin PTFE resin costs flow from three chemical conglomerates through membrane converters to end-users, with pharmaceutical validation tiers commanding five-fold premiums over industrial dust collection grades due to extractable documentation and lot qualification overhead.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-efficiency microporous film used in cement and steel emissions compliance. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical membranes from semiconductor cleanroom specifications and commodity HVAC rolls. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the standard tier intensifies because electrospun nanofiber substitutes achieve comparable efficiency at lower basis weights. Industrial operators in cement and steel exhibit the highest price sensitivity, while pharmaceutical manufacturers prioritize documented extractable profiles over unit cost.
Supply Chain Analysis
Photoresist-grade purity PTFE resin supply rests on Japanese and American specialty chemical producers, with Chinese converters dependent on imported feedstock for sub-0.1 micrometer membrane production. Raw material inputs draw from fluoropolymer resin, perfluorinated surfactant processing aids, and polypropylene or polyester nonwoven supports for laminated constructions. Single-source vulnerability concentrates in virgin resin allocation, where three producers control global supply. Distribution runs through direct OEM partnerships for semiconductor and pharmaceutical accounts, with industrial HVAC channels flowing through regional distributors and aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between REACH-restricted European production and Asian fabrication capacity expansion, where regulatory compliance costs in Germany and resin supply proximity in China create divergent cost structures for identical membrane specifications.
For Market Incumbents: Cement premium positioning through captive resin production and validation protocol depth that pharmaceutical clients require for FDA and EMA compliance. Defend against electrospun nanofiber substitution in HVAC pre-filtration by accelerating lamination expertise for composite film specifications. Prioritize backward integration into PTFE resin supply to insulate margin structures from feedstock allocation constraints.
For New Entrants and Emerging Players: Launch via contract manufacturing partnerships serving Indian pharmaceutical clusters where CDSCO alignment with PIC/S standards drives import substitution demand. Target semiconductor assembly and test facilities attracted by India's PLI scheme incentives, where filtration validation requirements remain less stringent than wafer fabrication. Penetrate through specialized surface modification capabilities for hydrogen electrolyzer humidity management applications.
For Investors and Strategic Acquirers: Consolidation pressure builds where converters lack lamination expertise required for two-meter roll width cleanroom specifications demanded by Taiwan and South Korean fabricators. Five-to-ten year viability favors membrane specialists with documented pharmaceutical validation histories over commodity dust collection suppliers. Acquisition target archetype: regional converters with installed biaxial stretching capacity and untapped pharmaceutical certification pathways. Watch ECHA substance evaluation timelines for perfluorinated surfactant restrictions as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive PTFE production insulates margin structures from three-producer allocation constraints. |
| Lamination Capacity Expansion | Composite film expertise captures semiconductor cleanroom specifications in Taiwan and South Korea. |
| Pharmaceutical Validation Investment | Documented extractable profiles unlock FDA and EMA-compliant sterile injectable filtration contracts. |
| Predictive Maintenance Service Bundling | Aftermarket contracts with United States food and pharmaceutical processors reduce customer churn. |
| Alternative Surfactant Qualification | REACH-compliant processing aids preserve European manufacturing access ahead of restriction deadlines. |
Research Methodology
Direct dialogue with membrane production engineers, pharmaceutical quality assurance directors, semiconductor fab facility managers, and industrial procurement leads grounded the qualitative foundation. Secondary validation drew from EPA enforcement records, FDA 510(k) filings, ECHA substance evaluation documentation, and SEC disclosures from listed filtration suppliers. Bottom-up and top-down triangulation cross-checked installed capacity estimates against end-use demand segmentation.
Bottom-up modeling aggregated individual facility capacities and qualification timelines across product tiers, while top-down approaches calibrated against regulatory-driven replacement cycles and fabrication capacity expansion announcements. Segmentation dimensions spanned product architecture, application environment, end-user regulatory exposure, and regional production hub. CAGRs were derived from slope analysis of volume trajectories against regulatory implementation schedules and technology node transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PFAS regulatory reclassification scenarios and fluoropolymer resin supply disruption events. A small set of named triggers warrants ongoing watch: ECHA restriction finalization, sub-5nm lithography filtration precision requirements, and Chinese domestic resin capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.