
 China Automotive Logistics Market | 2026-2036
China Automotive Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Logistics Market Outlook
Asset-light leasing and third-party fleet financing is tilting competitive dynamics toward operators with scalable balance sheets rather than pure asset ownership. SAIC Anji Logistics leverages its captive OEM relationship to sustain dedicated vehicle-carrying capacity across eastern China. Sinotrans Co. Ltd anchors multimodal operations through rail-water intermodal terminals at coastal ports. DB Schenker differentiates via control of European-China automotive parts corridors.
China automotive logistics encompasses the planning, execution, and control of vehicle and component movement across inbound supply chains, finished-vehicle distribution, and aftermarket parts networks, typically operating within temperature ranges of minus 25 to plus 60 degrees Celsius for sensitive electronics transport and requiring just-in-sequence delivery windows of under four hours at assembly plants. Its primary commercial purpose is reducing inventory carrying costs while maintaining production continuity for vehicle manufacturers. Road-based finished-vehicle transport dominates volume but faces margin compression from fuel cost volatility and toll structures, while rail delivery mode is gaining structural share for long-haul NEV distribution due to lower per-unit damage rates and government freight rail subsidies. Warehousing services capture disproportionate margin pools as OEMs outsource parts consolidation centers to specialized third-party operators.
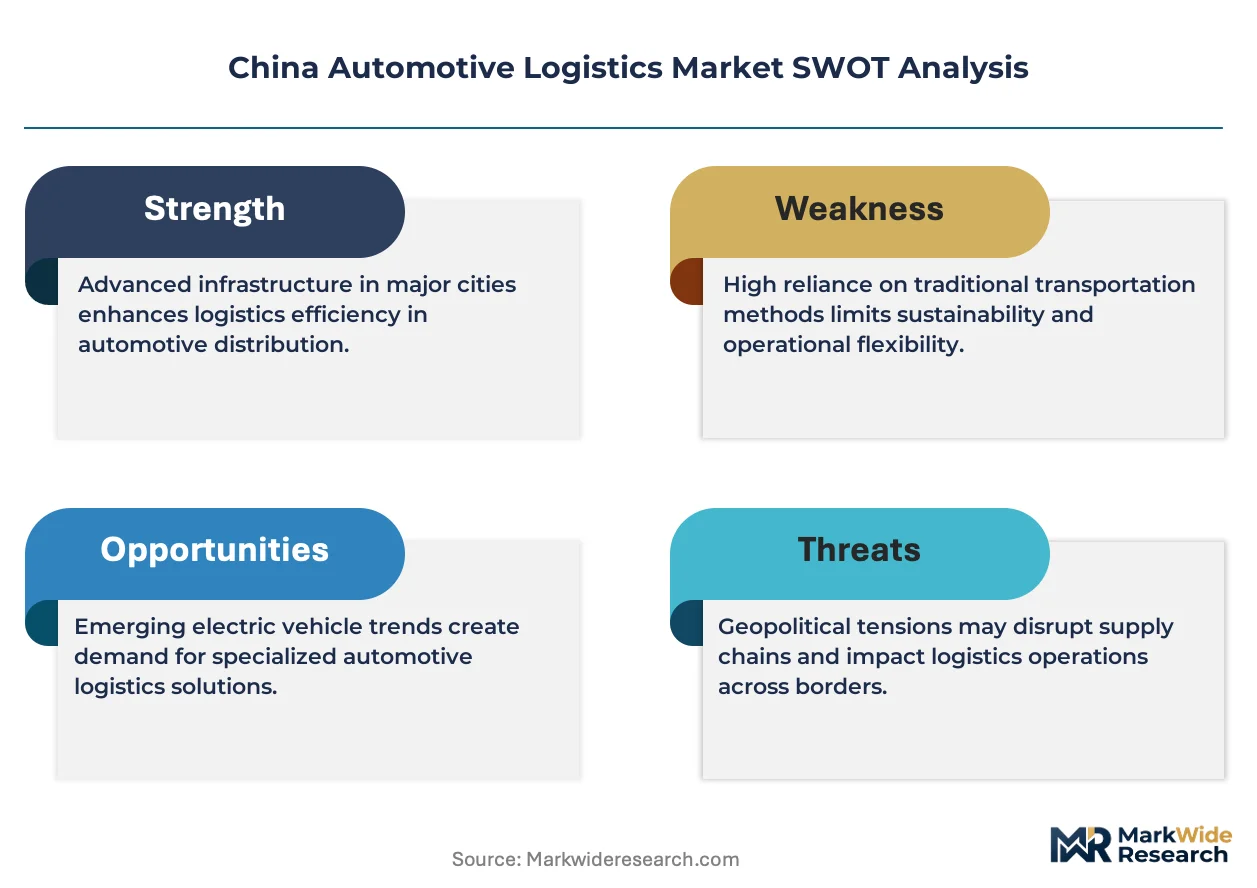
MIIT enforces GB standards for commercial vehicle emissions and NEV logistics facility electrification, while SAMR monitors anti-competitive practices in port and rail access that shape market entry for new logistics providers. The country's national automotive regulator coordinates with MEE on green transport corridors that mandate low-emission zones in major manufacturing cities. Stakeholders must monitor how dual carbon policy implementation affects diesel fleet replacement timelines and charging infrastructure requirements at distribution hubs.
Market Dynamics
MIIT emissions mandates and dual carbon policy implementation are forcing fleet operators to accelerate diesel-to-electric transitions while NEV manufacturers scale domestic production, creating simultaneous pressure on transport capacity and infrastructure investment timelines.
Growth Catalysts
- NEV Credit Policies:MIIT's new energy vehicle credit system mandates logistics fleets serving OEMs to meet electrification thresholds, pulling dedicated vehicle-carrying capacity toward compliant operators.
- Yangtze River Delta Concentration:Manufacturing clusters around Shanghai generate dense outbound finished-vehicle flows that justify specialized rail-water intermodal terminal investments.
- Rail Freight Subsidies:Government freight rail subsidies reduce per-unit damage rates for long-haul NEV distribution, shifting modal share away from road transport for inter-provincial moves.
Market Restraints
- Diesel Fleet Stranded Assets:Accelerated GB standards compliance timelines compress residual value recovery for existing commercial vehicle assets before electrification replacement.
- Charging Infrastructure Gaps:Distribution hubs in tier-two manufacturing cities lack grid capacity for overnight fleet charging, constraining operational radius for electric vehicle carriers.
- Port Access Concentration:SAMR-monitored anti-competitive practices in coastal port and rail terminal access limit market entry for specialized automotive logistics providers.
Strategic Opportunities
- Western China Expansion:Underpenetrated NEV production bases in Sichuan and Chongqing lack mature finished-vehicle logistics networks, creating first-mover terminal infrastructure opportunities.
- Aftermarket Parts Consolidation:OEM outsourcing of parts consolidation centers to third-party operators captures disproportionate margin pools versus commoditized transport services.
- Battery Supply Chain Integration:Just-in-sequence delivery windows for lithium-ion cells at assembly plants require temperature-controlled logistics capabilities distinct from traditional automotive freight.
Industry Challenges
- Electrification Skill Gaps:Fleet maintenance technicians require retraining on high-voltage systems and thermal management for electric commercial vehicles, extending workforce transition timelines.
- Multi-Modal Coordination Complexity:Rail-water intermodal handoffs at coastal ports demand synchronized scheduling systems that legacy road-centric operators lack.
- GB Standards Certification Lag:Commercial vehicle emissions compliance verification creates fleet deployment delays during peak seasonal production surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Logistics Market |
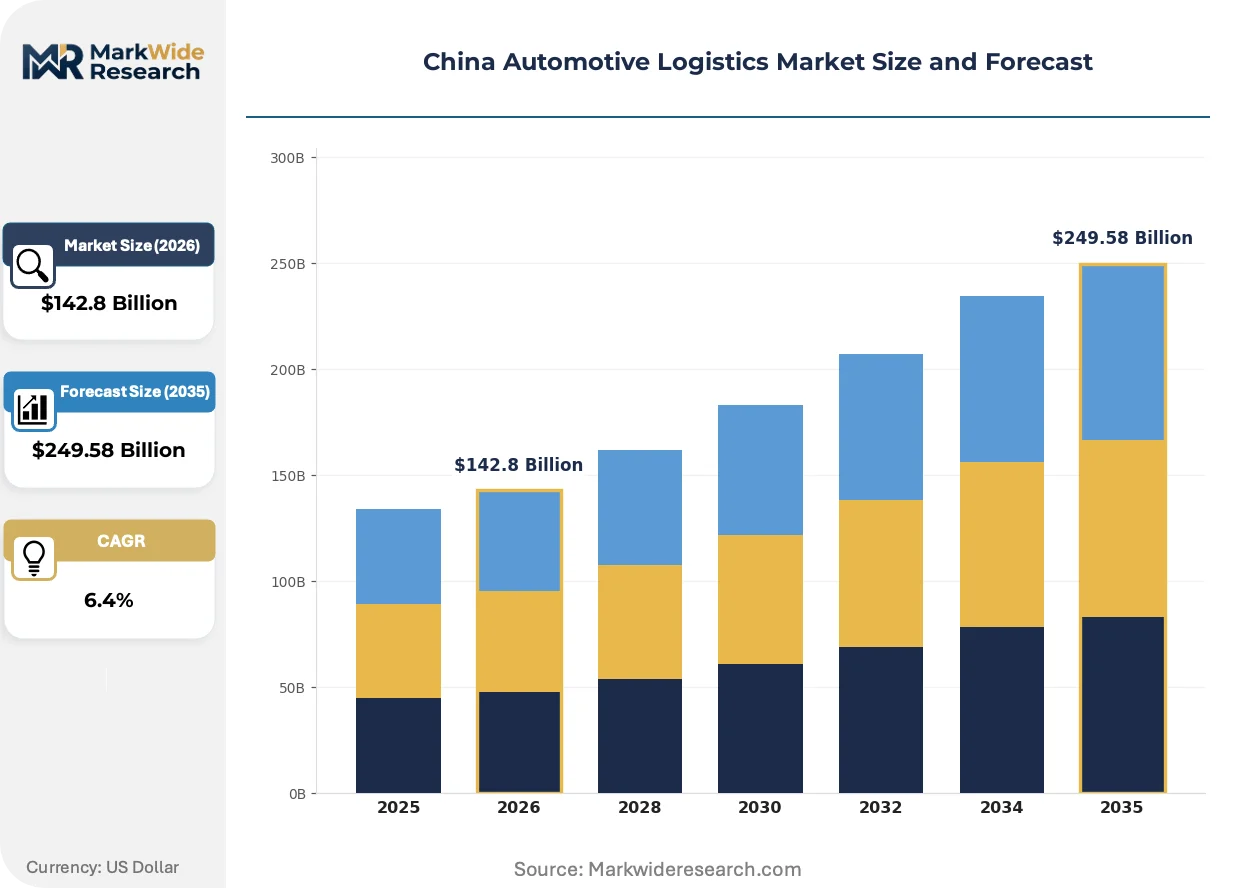
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $249.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Inventory Management Delivery Mode: Road, Rail, Sea, Air Client Type: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers Technology: Telematics, RFID, Automation, Blockchain |
| Companies Covered | SAIC Anji Logistics, Sinotrans Co. Ltd, China Ocean Shipping (Group) Company, DHL Supply Chain, DB Schenker, CEVA Logistics, Nippon Express, Yusen Logistics Co. Ltd, HYCX Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Logistics Market Strategic Shifts
Digital freight platforms and autonomous yard operations are compressing vehicle turnaround times at manufacturing plants while battery-electric commercial vehicles reshape fleet economics. These shifts are redrawing competitive boundaries between asset-heavy operators and technology-enabled intermediaries.
Autonomous yard tractors are migrating from pilot deployments at single OEM plants to multi-facility networks across eastern China. SAIC and BYD manufacturing complexes in Shanghai and Shenzhen are adopting these systems for finished-vehicle marshalling. The technology is migrating from proof-of-concept status to operational scale, compressing labor costs and reducing damage incidents during vehicle positioning.
Dual carbon policy implementation is tightening MEE coordination with MIIT on green transport corridors that mandate low-emission zones in major manufacturing cities. Logistics providers must electrify distribution hub fleets serving Beijing, Shanghai, and Guangzhou or face exclusion from OEM tender processes. NEV manufacturers with captive logistics arms are responding fastest due to aligned electrification roadmaps.
Just-in-sequence procurement contracts are displacing traditional parts warehousing arrangements for electronics and battery modules at assembly plants. Tier-one suppliers now bear inventory carrying costs until four-hour delivery windows, shifting working capital burdens upstream. This pattern is most visible in Anhui and Jiangsu province facilities supplying Tesla and NIO production lines.
China Automotive Logistics Market Segmentation
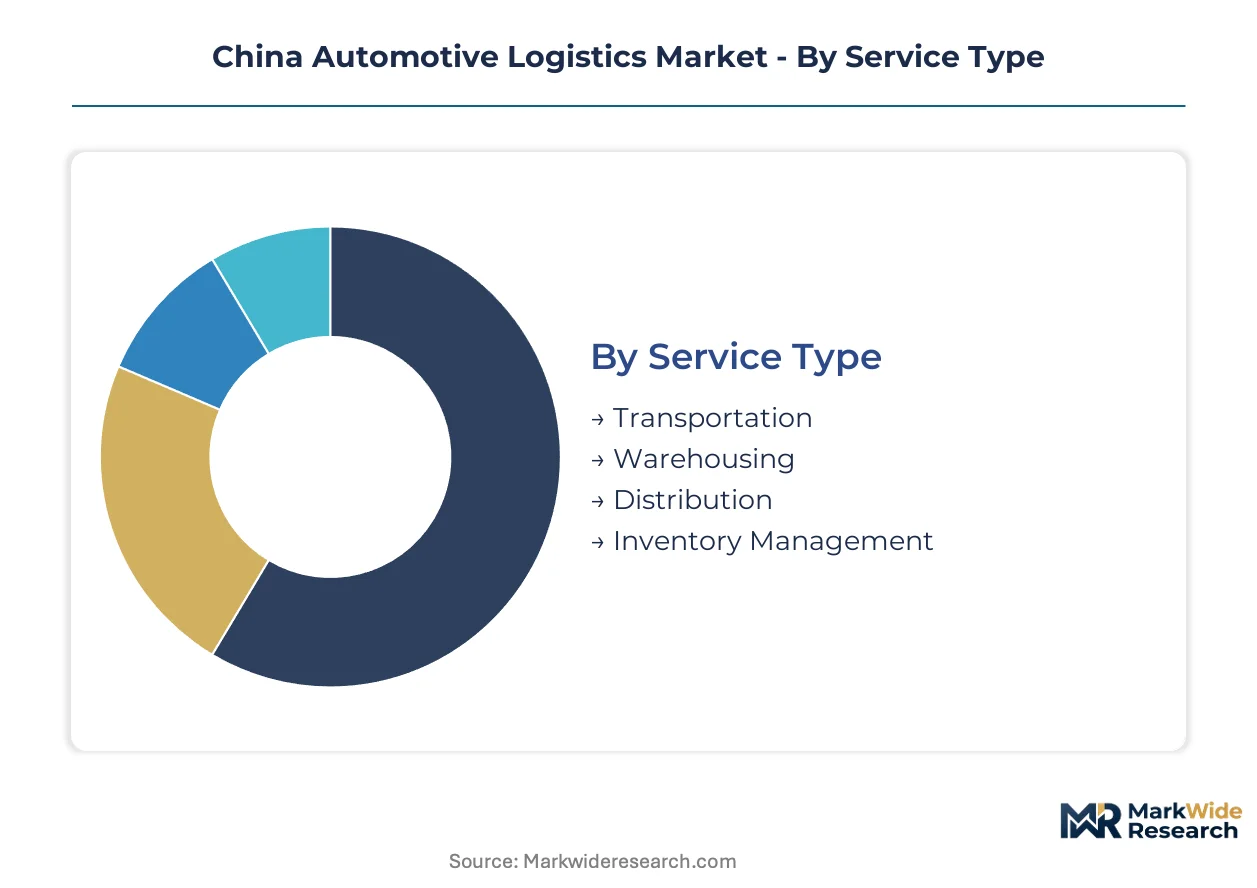
China automotive logistics segmentation reveals how service intensity varies dramatically across the vehicle lifecycle. After-sales parts networks demand fundamentally different fulfillment architectures than inbound supply chains or finished-vehicle distribution.
Service Type:
After-sales-service intensity peaks in segments managing unpredictable demand patterns and reverse logistics flows, while production-bound services operate on rigid just-in-sequence schedules.
- Transportation:Finished-vehicle carriers and parts haulers move goods across road, rail, and multimodal corridors. NEV manufacturers in the Yangtze River Delta generate dense outbound flows that justify dedicated fleet capacity.
- Warehousing:Temperature-controlled facilities store lithium-ion batteries and electronic components within minus 25 to plus 60 degrees Celsius ranges. Parts consolidation centers around Shanghai capture disproportionate margin pools as OEMs outsource inventory management.
- Distribution:Last-mile delivery networks connect regional hubs to dealerships and aftermarket service points. Tier-two manufacturing cities face charging infrastructure gaps that constrain electric fleet deployment radius.
- Inventory Management:Vendor-managed inventory systems synchronize supplier production with assembly plant consumption patterns. Four-hour delivery windows at Tesla and NIO facilities in Anhui and Jiangsu shift working capital burdens upstream to tier-one suppliers.
By volume, Transportation leads. By growth pace, Inventory Management is ahead.
Delivery Mode:
Modal choice reflects cost tier positioning against damage sensitivity and delivery velocity requirements.
- Road:Dominant mode for short-haul finished-vehicle moves and just-in-sequence parts delivery. Fuel cost volatility and toll structures compress margins for dedicated vehicle carriers serving eastern China OEM clusters.
- Rail:Structural share gains for long-haul NEV distribution due to lower per-unit damage rates and MIIT-coordinated freight rail subsidies. Sinotrans anchors multimodal operations through rail-water intermodal terminals at coastal ports.
- Sea:Coastal and inland waterway transport handles bulk component imports and export vehicle shipments. Port access concentration under SAMR monitoring limits market entry for specialized automotive logistics providers.
- Air:Premium freight for prototype parts, urgent tooling, and high-value electronics. Limited volume but critical for maintaining production continuity during supply disruptions.
Road retains volume dominance. Rail is climbing the fastest on government subsidy alignment with NEV distribution needs.
Client Type:
Customer type determines contract structure, margin profile, and technology integration depth.
- OEMs:Captive logistics arms like SAIC Anji leverage dedicated vehicle-carrying capacity across eastern China. These operators face MIIT mandates to electrify distribution hub fleets serving Beijing, Shanghai, and Guangzhou.
- Tier-1 Suppliers:Bear inventory carrying costs under just-in-sequence contracts until four-hour delivery windows at assembly plants. Electronics and battery module suppliers in Jiangsu province face compressed working capital cycles.
- Dealerships:Receive finished vehicles through regional distribution centers and coordinate aftermarket parts replenishment. Western China expansion into Sichuan and Chongqing creates first-mover terminal infrastructure opportunities.
- Aftermarket Providers:Manage unpredictable demand patterns for replacement parts and reverse logistics flows. Outsourced parts consolidation to third-party operators captures higher margins than commoditized transport services.
OEMs anchor volume concentration. Aftermarket Providers are gaining share fastest on outsourcing trends.
Technology:
Technology adoption stratifies by deployment maturity and integration complexity with legacy fleet systems.
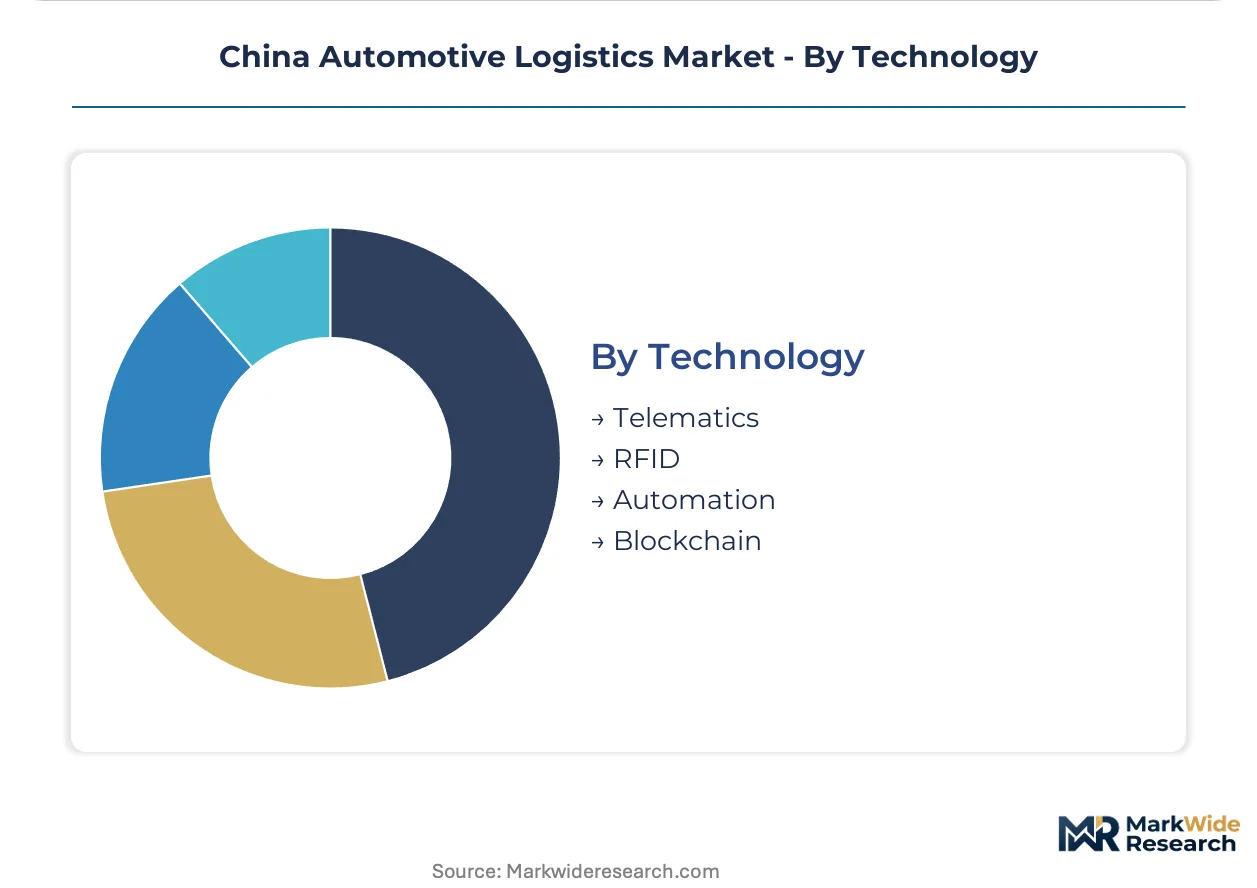
- Telematics:Fleet tracking and route optimization systems monitor vehicle location, fuel consumption, and driver behavior. Digital freight platforms compress turnaround times at manufacturing plants.
- RFID:Parts and vehicle identification systems enable inventory visibility across warehouse and transport nodes. Assembly plants use automated scanning for just-in-sequence verification.
- Automation:Autonomous yard tractors migrate from pilot deployments at SAIC and BYD facilities in Shanghai and Shenzhen to multi-facility networks. The technology reduces labor costs and damage incidents during vehicle positioning.
- Blockchain:Emerging applications for supply chain documentation and cross-border customs processing. Limited operational scale but pilot programs target battery provenance tracking for NEV credit compliance.
Telematics holds volume leadership. Automation is expanding most quickly on labor cost reduction and damage prevention metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEV manufacturers and captive logistics arms concentrate procurement power in coastal manufacturing belts, forcing specialized providers to cluster around Shanghai, Shenzhen, and Tianjin assembly corridors.
Yangtze River Delta
Tesla and NIO production lines in Anhui and Jiangsu provinces generate dense outbound finished-vehicle flows. MIIT freight rail subsidies pull intermodal investment toward Shanghai's deepwater terminals. SAIC Anji Logistics anchors dedicated vehicle-carrying capacity across the manufacturing cluster.
Pearl River Delta
BYD manufacturing complexes in Shenzhen drive just-in-sequence parts demand for battery module delivery. Guangzhou and Shenzhen municipal authorities enforce low-emission zones under MEE-coordinated green transport corridors. Autonomous yard tractors migrate from pilot status to multi-facility networks here.
Beijing-Tianjin-Hebei
MIIT emissions mandates compress diesel fleet replacement timelines for operators serving northern OEM plants. SAMR-monitored port access at Tianjin limits specialized automotive logistics market entry. Distribution hubs face electrification requirements or exclusion from tender processes.
Sichuan-Chongqing
Underpenetrated NEV production bases lack mature finished-vehicle logistics networks. Western expansion creates first-mover terminal infrastructure opportunities for rail-water intermodal operators. Tier-two manufacturing cities here face charging infrastructure gaps that constrain electric fleet deployment radius.
Shandong Peninsula
Parts consolidation centers around Qingdao and Yantai capture disproportionate margin pools as OEMs outsource inventory management. Temperature-controlled warehousing for lithium-ion batteries operates within strict thermal parameters. Electronics suppliers face compressed working capital cycles under four-hour delivery windows.
China Automotive Logistics Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure tilting toward scalable balance sheets rather than pure asset ownership. Consolidation pressures mount as electrification mandates and NEV credit policies raise compliance barriers. Three archetypes dominate: captive OEM logistics arms, multimodal infrastructure operators, and international corridor specialists. Competitive moves concentrate on fleet electrification partnerships and rail-water terminal capacity expansion.
Among captive OEM logistics arms, SAIC Anji Logistics exemplifies the integrated operator archetype leveraging dedicated vehicle-carrying relationships. Sinotrans Co. Ltd occupies the multimodal infrastructure position through rail-water intermodal terminals at coastal ports. DB Schenker represents the international corridor specialist, anchoring European-China automotive parts networks. These three players illustrate how competitive positioning stratifies across asset control, modal integration depth, and geographic scope.
| Leading Market Players |
|---|
| SAIC Anji Logistics |
| Sinotrans Co. Ltd |
| China Ocean Shipping (Group) Company |
| DHL Supply Chain |
| DB Schenker |
| CEVA Logistics |
| Nippon Express |
| Yusen Logistics Co. Ltd |
| HYCX Group |
| Others |
Value Chain & Pricing Dynamics
Shanghai's Yangtze River Delta manufacturing cluster concentrates finished-vehicle logistics capacity, granting dedicated fleet operators pricing power over OEMs facing MIIT electrification mandates. This geographic chokepoint lets compliant carriers command premium rates while diesel-dependent competitors absorb residual value compression.
Pricing Analysis
Certification level under GB standards and NEV credit compliance creates the primary spread between rate tiers. Three-tier pricing structure across electrified, transitioning, and diesel-dependent fleet operators reflects MIIT mandate alignment. Pricing pressure stems from fuel cost volatility and toll structures compressing margins for road-based carriers. Tier-one suppliers under just-in-sequence contracts exhibit highest price sensitivity due to compressed working capital cycles, while captive OEM logistics arms show lowest sensitivity through integrated cost absorption.
Supply Chain Analysis
Extended payment terms from OEM procurement teams and supply-chain finance facilities anchor supplier liquidity management. Component sourcing draws from Germany, Japan, and domestic China for precision electronics and battery management systems. Lithium carbonate, automotive-grade steel, and semiconductor chips constitute critical input dependencies. Single-source vulnerability concentrates in high-voltage battery cell supply. Distribution runs through rail-water intermodal terminals at coastal ports before final road delivery to assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China automotive logistics sits in early-cycle expansion as NEV production scaling outpaces mature logistics infrastructure deployment, creating penetration gaps for electrified fleet operators.
For Market Incumbents: Build regulatory compliance moats through accelerated GB standards certification and captive charging infrastructure at distribution hubs. Fleet electrification partnerships with grid operators defend against emerging asset-light digital freight platforms. Vertical integration into battery temperature-controlled warehousing locks in tier-one supplier contracts. For New Entrants and Emerging Players: Western China underpenetration in Sichuan and Chongqing NEV production corridors offers first-mover rail-water terminal infrastructure opportunities. Target aftermarket parts consolidation centers where outsourcing trends concentrate margin pools above commoditized transport. Lead with electrified fleet capabilities to bypass diesel stranded asset risks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multimodal infrastructure operators with rail-water terminal control over pure road carriers. Five-to-ten year viability hinges on MIIT policy continuity and dual carbon implementation pace. Acquisition targets should demonstrate electrified fleet scale and OEM captive relationships. Monitor freight rail subsidy renewal announcements as inflection indicators for modal share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | MIIT compliance mandates require charging infrastructure co-investment with grid operators at distribution hubs. |
| Rail-Water Terminal Expansion | Government freight subsidies pull intermodal investment toward Shanghai and Shenzhen deepwater corridors. |
| Autonomous Yard Operations Deployment | SAIC and BYD manufacturing complexes compress labor costs through multi-facility autonomous tractor networks. |
| Battery Supply Chain Integration | Temperature-controlled logistics capabilities for lithium-ion cells capture just-in-sequence contract premiums. |
| Aftermarket Parts Consolidation Acquisition | OEM outsourcing of inventory management captures margin pools above commoditized finished-vehicle transport. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM logistics directors, Tier 1 supplier procurement leads, fleet operations managers, and rail-water terminal operators. Secondary validation incorporated MIIT regulatory filings, SAMR competition notices, vehicle production databases, and customs trade flows. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Calibration against historical production volumes and modal share shifts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, delivery mode, client archetype, and technology adoption tier. CAGRs derived from production growth correlations and infrastructure investment trajectories. NEV penetration curves and freight rail subsidy schedules constituted industry-specific forecast inputs.
Practitioners should monitor MIIT emissions mandate acceleration and dual carbon policy implementation timelines for early signals of fleet replacement demand. Forecasts reflect assumptions regarding regulatory continuity and infrastructure buildout pace. Macroeconomic slowdown, subsidy withdrawal, or technological disruption in battery logistics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Germany Express Delivery Market