
 Asia-Pacific FMCG Logistics Market | 2026-2036
Asia-Pacific FMCG Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific FMCG Logistics Market Outlook
Third-party cold storage capacity across Southeast Asia is hardening as ambient warehouse stock ages. DHL Group leverages its multi-temperature zone networks to anchor pharmaceutical distribution across Singapore and Thailand. Nippon Express sustains dominant port-to-warehouse throughput in Japan's Kanto region. CEVA Logistics competes through dedicated FMCG contract operations in Australia's urban last-mile corridors.
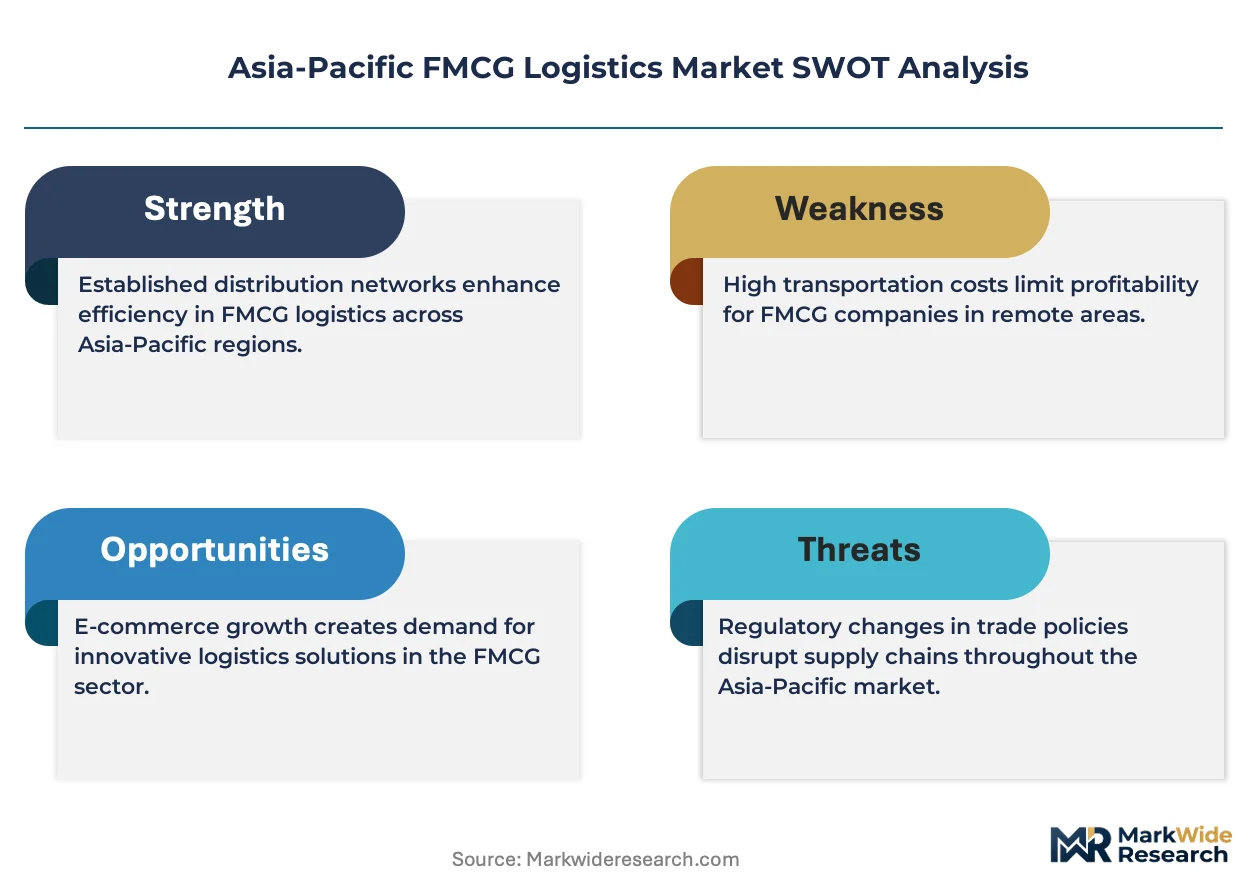
Asia-Pacific FMCG logistics encompasses the planning, execution, and control of physical flows for fast-moving consumer goods across temperature-controlled, ambient, and frozen supply chains, typically requiring inventory turns under thirty days and order accuracy above 99.5 percent. The sector's primary purpose is to minimize stockouts at retail shelves while compressing cash-to-cash cycles for manufacturers and distributors. Transportation services occupy the largest value pool given fragmented road networks and inter-island shipping dependencies across Indonesia and the Philippines. Warehousing with automated systems represents the fastest-expanding segment as labor costs rise in China's eastern provinces. E-commerce platforms as end users are pulling demand toward same-day fulfillment architectures, reshaping footprint requirements in India's tier-two cities.
China's MEE enforces escalating emissions standards for diesel freight fleets, while India's CEA mandates cold chain energy efficiency disclosures under revised building codes. Japan's METI subsidizes hydrogen fuel cell trials for medium-duty delivery vehicles, tightening total cost of ownership benchmarks for logistics providers. Stakeholders must weigh asset-light partnerships against captive infrastructure bets as regulatory compliance costs diverge across national boundaries.
Market Dynamics
India's PLI scheme for logistics infrastructure and China's dual carbon goals are forcing fleet operators into electrification commitments faster than total cost of ownership parity would otherwise justify. These overlapping mandates compress capital planning horizons while fragmenting equipment procurement across incompatible national standards.
Growth Catalysts
- Pharmaceutical cold chain mandates:India's CDSCO and China's NMPA enforce temperature integrity documentation for biologics distribution, pulling investment into validated refrigerated transport.
- E-commerce fulfillment densification:Same-day delivery promises from major platforms concentrate warehousing demand in Vietnam's manufacturing corridors and Indonesia's urban periphery.
- Renewable energy integration:Solar-powered warehouse installations spread across Thailand and Malaysia as grid reliability concerns intersect with corporate sustainability targets.
Market Restraints
- Diesel fleet stranding risk:China's MEE emissions tier upgrades threaten premature obsolescence for internal combustion assets purchased under previous regulatory assumptions.
- Inter-island shipping bottlenecks:Indonesia's archipelago geography locks dependence on aging roll-on/roll-off vessel capacity with limited reefer plug availability.
- Land acquisition friction:India's state-level warehouse construction permitting varies dramatically, stretching facility development timelines in Maharashtra versus Karnataka.
Strategic Opportunities
- Hydrogen fuel cell trials:Japan's METI subsidizes medium-duty hydrogen delivery vehicle pilots, creating early-mover positioning for fleet operators willing to absorb technology risk.
- Cross-border ASEAN consolidation:Vietnam-to-Thailand manufacturing corridor logistics remain underdeveloped relative to production volumes, offering greenfield network construction potential.
- Automated sortation retrofit:Labor cost escalation in China's eastern provinces accelerates robotic goods-to-person system deployment in existing ambient facilities.
Industry Challenges
- Refrigerant technician scarcity:Cold chain equipment maintenance depends on certified specialists whose training pipelines lag fleet electrification timelines across the Philippines and Indonesia.
- Multi-temperature zone complexity:Pharmaceutical distributors struggle to reconcile validated cold chain protocols with ambient FMCG consolidation pressures in shared distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific FMCG Logistics Market |
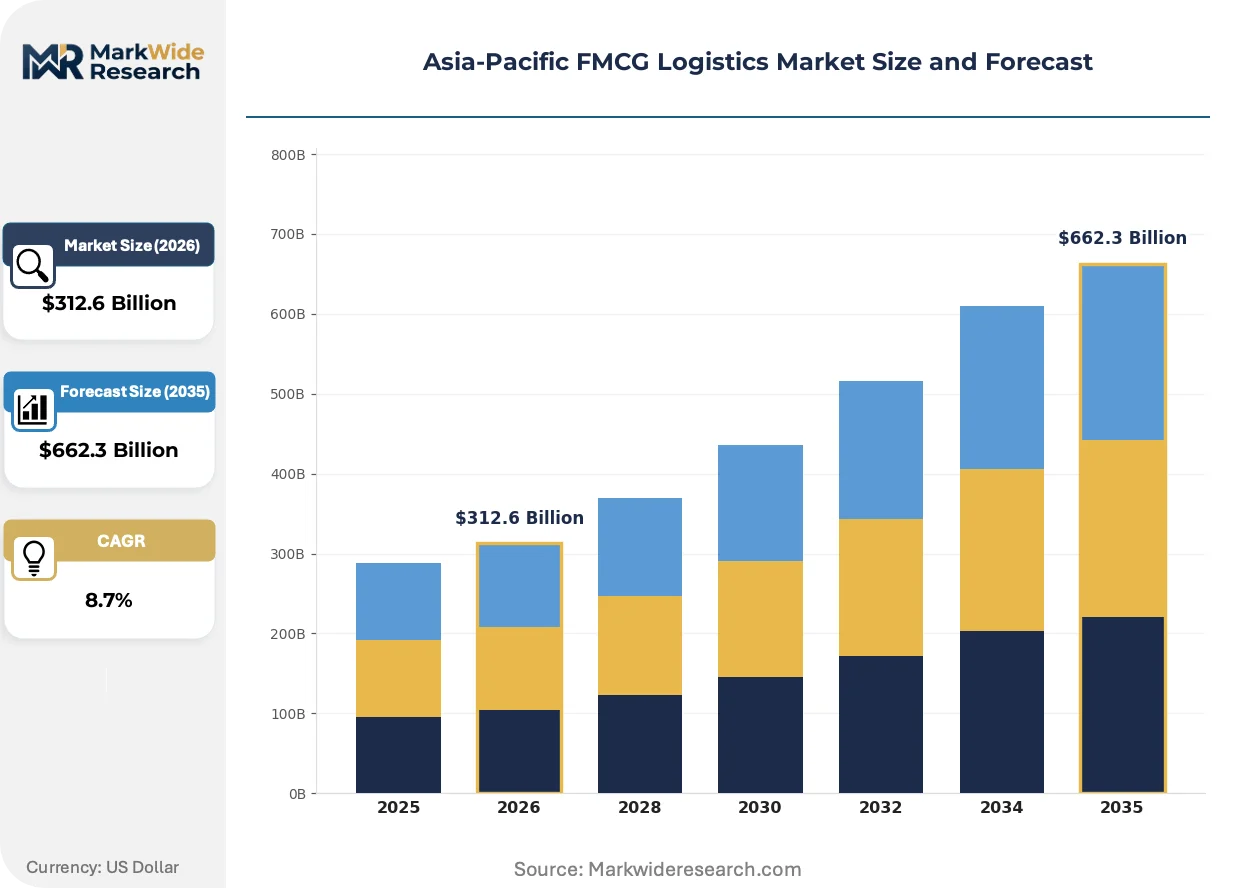
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding End User: Retailers, Wholesalers, E-commerce Platforms, Manufacturers Technology: IoT Solutions, Automated Systems, Supply Chain Software, Blockchain Packaging Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Eco-friendly Packaging |
| Companies Covered | Agility Logistics, FedEx, DHL Group, DB Schenker, XPO Logistics, C.H. Robinson Worldwide Inc., CEVA Logistics, Nippon Express, Kuehne + Nagel International AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific FMCG Logistics Market Strategic Shifts
Digital freight matching platforms and autonomous yard management systems are compressing asset utilization gaps that previously absorbed 15-20 percent of fleet capacity. These technologies intersect with regulatory emissions tracking requirements to reshape procurement specifications.
Autonomous mobile robots are expanding into ambient warehouse operations as labor availability tightens in China's Pearl River Delta manufacturing zones. Third-party logistics providers in Guangdong province deploy these systems to maintain throughput during seasonal demand spikes. The technology is expanding into smaller facility footprints previously considered below automation viability thresholds.
China's dual carbon goals mandate progressively stricter diesel freight emissions disclosures through the MEE's corporate environmental information system. Fleet operators must retrofit existing vehicles or accelerate replacement cycles to maintain operating permits in Beijing and Shanghai metropolitan areas. Pharmaceutical distributors face compounded compliance burdens as cold chain energy efficiency reporting layers onto transport emissions documentation.
Direct-to-store delivery models displace traditional distributor intermediaries as modern trade retailers in Indonesia and Vietnam consolidate procurement authority. Manufacturers now contract dedicated fleet capacity rather than relying on fragmented local transport brokers. This concentration is most visible in Jakarta's urban core and Ho Chi Minh City's industrial periphery where real-time inventory visibility determines shelf space allocation.
Asia-Pacific FMCG Logistics Market Segmentation
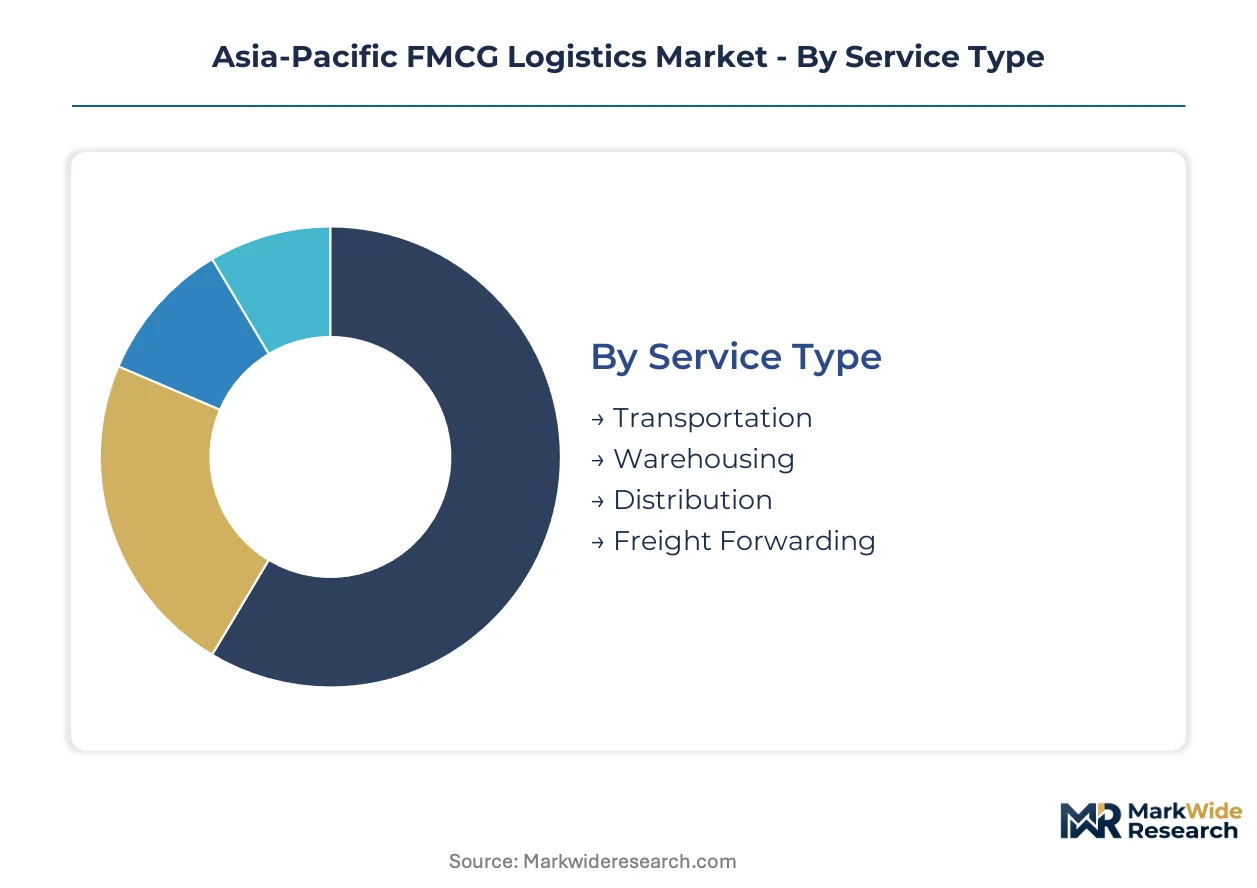
Segmentation in Asia-Pacific FMCG logistics reveals how service complexity, technology adoption, and end-user requirements fragment procurement decisions across the region's diverse regulatory and infrastructure environments. Each dimension carries distinct margin profiles and capital intensity thresholds that shape provider specialization strategies.
Service Type:
Standalone transportation services operate independently from embedded warehousing and distribution networks, while integrated offerings bundle multiple functions under single contract structures.
- Transportation:Road freight dominates given fragmented highway networks across Indonesia and the Philippines, with inter-island shipping dependencies creating modal complexity. Demand concentrates in Vietnam's manufacturing corridors where factory-to-port movements require dedicated fleet commitments under tight lead time constraints.
- Warehousing:Automated ambient facilities represent the fastest-expanding segment as labor costs rise in China's eastern provinces. Cold storage capacity hardens across Southeast Asia as pharmaceutical and perishable food retailers deepen temperature-controlled inventory requirements.
- Distribution:Last-mile networks serve modern trade retailers consolidating procurement authority in Jakarta and Ho Chi Minh City. Direct-to-store models displace traditional broker intermediaries.
- Freight Forwarding:Cross-border ASEAN consolidation remains underdeveloped relative to production volumes, creating greenfield network construction potential.
Transportation leads volumes today; warehousing is gaining share fastest.
End User:
Procurement patterns diverge sharply between asset-heavy manufacturers seeking captive control and asset-light platforms prioritizing variable cost structures.
- E-commerce Platforms:Same-day fulfillment architectures reshape footprint requirements in India's tier-two cities. These users pull demand toward urban periphery warehousing with robotic sortation systems.
- Retailers:Modern trade consolidation concentrates logistics authority among hypermarket and supermarket chains. Real-time inventory visibility determines shelf space allocation negotiations.
- Manufacturers:FMCG producers balance captive fleet investments against third-party partnerships as regulatory compliance costs diverge across national boundaries.
- Wholesalers:Traditional distributor intermediaries face margin compression as direct contracting models expand.
Retailers anchor current contract values; e-commerce platforms are climbing the fastest.
Technology:
Maturity gradients separate proven deployments from pilot-stage innovations, with implementation risk concentrated among emerging categories.
- Automated Systems:Autonomous mobile robots expand into ambient warehouse operations as labor availability tightens in China's Pearl River Delta. Guangdong province deployments maintain throughput during seasonal demand spikes.
- IoT Solutions:Temperature and location sensors enable pharmaceutical cold chain integrity documentation required by India's CDSCO and China's NMPA. Fleet emissions tracking intersects with MEE disclosure mandates.
- Supply Chain Software:Digital freight matching platforms compress asset utilization gaps that previously absorbed significant fleet capacity.
- Blockchain:Traceability applications remain pilot-stage across most national markets, with limited interoperability between competing platforms.
IoT Solutions dominate current implementation; automated systems show the steepest expansion trajectory.
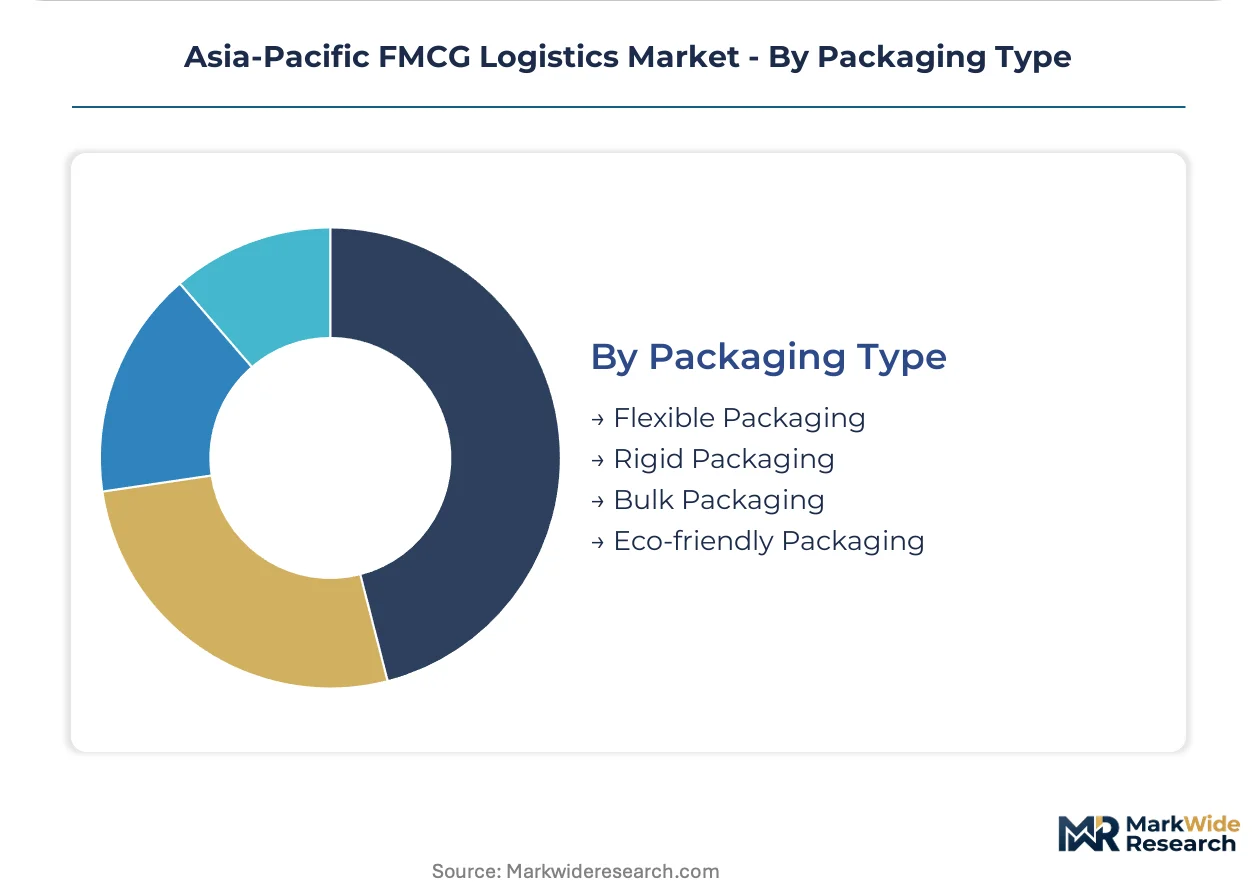
Packaging Type:
Cost and sustainability pressures stratify material selection across temperature requirements and shipment consolidation patterns.
- Flexible Packaging:Lightweight films reduce transport cost per unit in high-velocity ambient FMCG movements. Material innovations respond to corporate sustainability targets without compromising barrier properties.
- Eco-friendly Packaging:Biodegradable and recyclable formats spread as modern trade retailers impose procurement specifications. Solar-powered warehouse installations in Thailand and Malaysia align with packaging sustainability narratives.
- Rigid Packaging:Structural protection requirements concentrate in pharmaceutical and premium food segments with higher damage cost exposure.
- Bulk Packaging:Consolidation economics favor intermediate bulk containers for manufacturer-to-distributor movements with lower handling frequency.
Flexible packaging holds volume leadership; eco-friendly formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fleet electrification mandates outpace India's infrastructure incentives, yet both reshape capital deployment across the region. Vietnam and Indonesia concentrate e-commerce fulfillment demand, while Japan pilots hydrogen alternatives. Australia's urban corridors automate last-mile operations.
China
Dual carbon goals and MEE emissions disclosures accelerate diesel fleet replacement in Beijing and Shanghai metropolitan areas. Pharmaceutical distributors layer cold chain energy reporting onto transport compliance documentation. The Yangtze River Delta manufacturing belt demands factory-to-port movements with compressed lead times.
India
PLI scheme subsidies for logistics infrastructure pull investment into tier-two city warehousing networks. CDSCO temperature integrity mandates drive validated refrigerated transport procurement for biologics distribution. Maharashtra's permitting friction stretches facility timelines against Karnataka's streamlined approvals.
Japan
METI hydrogen fuel cell subsidies for medium-duty vehicles tighten total cost of ownership benchmarks for delivery fleets. Kanto region port-to-warehouse throughput sustains dominant logistics positioning. Tokyo metropolitan area emissions zones favor early technology adopters absorbing pilot-stage risk.
Vietnam
Manufacturing corridor expansion from Ho Chi Minh City's industrial periphery generates dedicated fleet commitments for export-bound movements. Same-day fulfillment architectures reshape urban periphery warehousing specifications. Factory-to-port logistics remain underdeveloped relative to production volumes, creating network construction gaps.
Indonesia
E-commerce platform consolidation concentrates procurement authority in Jakarta's urban core. Inter-island shipping dependencies lock reliance on aging roll-on/roll-off capacity with limited reefer plug availability. Direct-to-store delivery models displace fragmented local transport brokers in modern trade retail.
Asia-Pacific FMCG Logistics Market Competitive Environment
Japanese and German operators anchor premium-tier cold chain and contract logistics positions; Southeast Asian specialists hold fragmented last-mile brokerage capacity. The market structures around three archetypes: integrated multi-temperature zone network operators, port-centric freight forwarders with captive warehousing, and urban last-mile dedicated fleet contractors. Competitive moves concentrate on cross-border ASEAN network construction and automated sortation retrofit in aging ambient facilities.
Within the integrated network tier, DHL Group and Nippon Express occupy positions shaped by multi-decade infrastructure accumulation. DHL Group represents pharmaceutical distribution anchoring across Singapore and Thailand temperature-controlled corridors. Nippon Express exemplifies port-to-warehouse throughput dominance in Japan's Kanto industrial belt. CEVA Logistics sits within the contract operations specialization, reflecting dedicated FMCG service architectures in Australia's urban last-mile zones.
| Leading Market Players |
|---|
| Agility Logistics |
| FedEx |
| DHL Group |
| DB Schenker |
| XPO Logistics |
| C.H. Robinson Worldwide Inc. |
| CEVA Logistics |
| Nippon Express |
| Kuehne + Nagel International AG |
| Others |
Value Chain & Pricing Dynamics
Certified refrigerant technician pools in Indonesia's archipelago widen labor-cost differentials between temperature-controlled and ambient logistics tiers, compressing margins on pharmaceutical cold chain services while standard freight rates face downward pressure from automated warehouse competition in China's eastern provinces.
Pricing Analysis
Capacity additions in Vietnam's manufacturing corridors are reshaping price floors for factory-to-port movements as dedicated fleet commitments multiply. Three-tier pricing structure across premium cold chain, standard contract logistics, and economy spot freight segments stratifies by certification grade and volume scale. Cost compression in economy tier freight is intensifying because digital freight matching platforms erode broker intermediation margins. Small-batch pharmaceutical distributors exhibit highest price sensitivity; multinational FMCG manufacturers with captive volumes show least.
Supply Chain Analysis
Regional distribution centers in China's Yangtze River Delta, India's Maharashtra-Karnataka corridor, and Thailand's Eastern Economic Zone anchor hub-and-spoke patterns for cross-border ASEAN movements. Refrigerated transport equipment, warehouse automation systems, and last-mile delivery fleets draw from manufacturing bases in China, Japan, and South Korea. Single-source vulnerability concentrates in inter-island shipping capacity across Indonesia's archipelago where aging roll-on/roll-off vessel availability limits reefer plug access. Distribution runs through modern trade retail consolidation in Jakarta and Ho Chi Minh City with direct-to-store models displacing fragmented broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific FMCG logistics constitutes a late-cycle quality story as pharmaceutical cold chain mandates and e-commerce same-day fulfillment specifications pull demand toward premium-tier service capabilities with validated temperature integrity and robotic sortation infrastructure.
For Market Incumbents: Hedge diesel fleet stranding risk by accelerating electrification pilots in Beijing and Shanghai metropolitan zones ahead of MEE emissions tier enforcement. Consolidate cross-border ASEAN network control through greenfield regional distribution center construction in Vietnam-to-Thailand manufacturing corridors before specialist competitors anchor positions. For New Entrants and Emerging Players: E-commerce platform procurement teams represent the most accessible channel partner type for automated last-mile service pilots in India's tier-two cities. Target underdeveloped factory-to-port logistics in Vietnam's industrial periphery with dedicated fleet offerings. Penetrate through outcome-based contracts tying fees to inventory accuracy and lead time performance rather than asset rental rates. For Investors and Strategic Acquirers: Japanese trading houses with captive industrial distribution networks are the most active acquirer in this space, seeking cold chain capability to integrate with existing chemical and pharmaceutical trade flows. Five-to-ten year viability favors operators with multi-temperature zone infrastructure and regulatory compliance automation. Watch for inflection when India's PLI scheme logistics subsidies shift from greenfield construction to operational efficiency mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Fuel Cell Fleet Pilot | METI subsidies in Japan's Kanto region tighten total cost of ownership benchmarks for medium-duty delivery vehicles. |
| Automated Sortation Retrofit | Robotic goods-to-person deployment in Guangdong province ambient facilities maintains throughput during seasonal demand spikes. |
| Cross-Border ASEAN Network Buildout | Greenfield construction in Vietnam-to-Thailand corridors captures manufacturing volume ahead of incumbent saturation. |
| Multi-Temperature Zone Certification | CDSCO and NMPA pharmaceutical cold chain mandates validate investment in temperature integrity documentation systems. |
| Solar-Powered Warehouse Installation | Grid reliability concerns in Thailand and Malaysia intersect with corporate sustainability targets to accelerate renewable integration. |
Study Parameters
Coverage spans China, India, Japan, Southeast Asia, and Australia, with primary inputs from each market through structured interviews with fleet operations directors, pharmaceutical distribution managers, e-commerce fulfillment heads, and cold chain equipment procurement leads. Secondary validation draws from MEE emissions disclosures, CDSCO regulatory filings, METI subsidy announcements, and ASEAN customs trade data. Bottom-up service provider capacity assessments triangulate against top-down end-user demand modeling.
Granularity-level modeling disaggregates transportation, warehousing, distribution, and freight forwarding service types with separate treatment of cold chain and ambient temperature requirements. End-user segmentation distinguishes e-commerce platforms, modern trade retailers, manufacturers, and traditional wholesalers with distinct procurement pattern assumptions. CAGRs derive from logistic curve adoption modeling for automation technologies and regulatory compliance cost pass-through coefficients. Forecast inputs incorporate fleet electrification mandate timelines and inter-island shipping capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement consistency across China's provincial MEE implementations and India's state-level warehouse permitting variance. Outputs reflect documented assumptions around technology adoption rates and infrastructure subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market