
 Malaysia Freight and Logistics Market | 2026-2036
Malaysia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Freight and Logistics Market Outlook
Buyer concentration among e-commerce platforms is hardening as Shopee, Lazada, and TikTok Shop consolidate parcel volumes into fewer, larger logistics contracts. POS Malaysia Bhd leverages its nationwide postal infrastructure to compete for government and rural delivery mandates. DHL Group sustains premium express services through its Kuala Lumpur International Airport hub operations. J&T Express anchors the high-volume, low-cost parcel segment with automated sorting investments across Peninsular Malaysia.
Freight and logistics encompasses the physical movement, storage, and coordination of goods through multimodal networks involving road haulage, maritime container handling, air cargo terminals, and bonded warehousing facilities with temperature-controlled zones for perishables. Its primary purpose is reducing inventory carrying costs while ensuring time-definite delivery for manufacturing supply chains and consumer distribution. Transportation services dominate revenue generation due to fuel surcharges and fleet utilization economics, while cold chain application commands premium pricing from pharmaceutical and fresh food shippers. Warehousing services are expanding fastest as bonded facilities multiply around Port Klang and Senai Airport to serve regional distribution strategies.
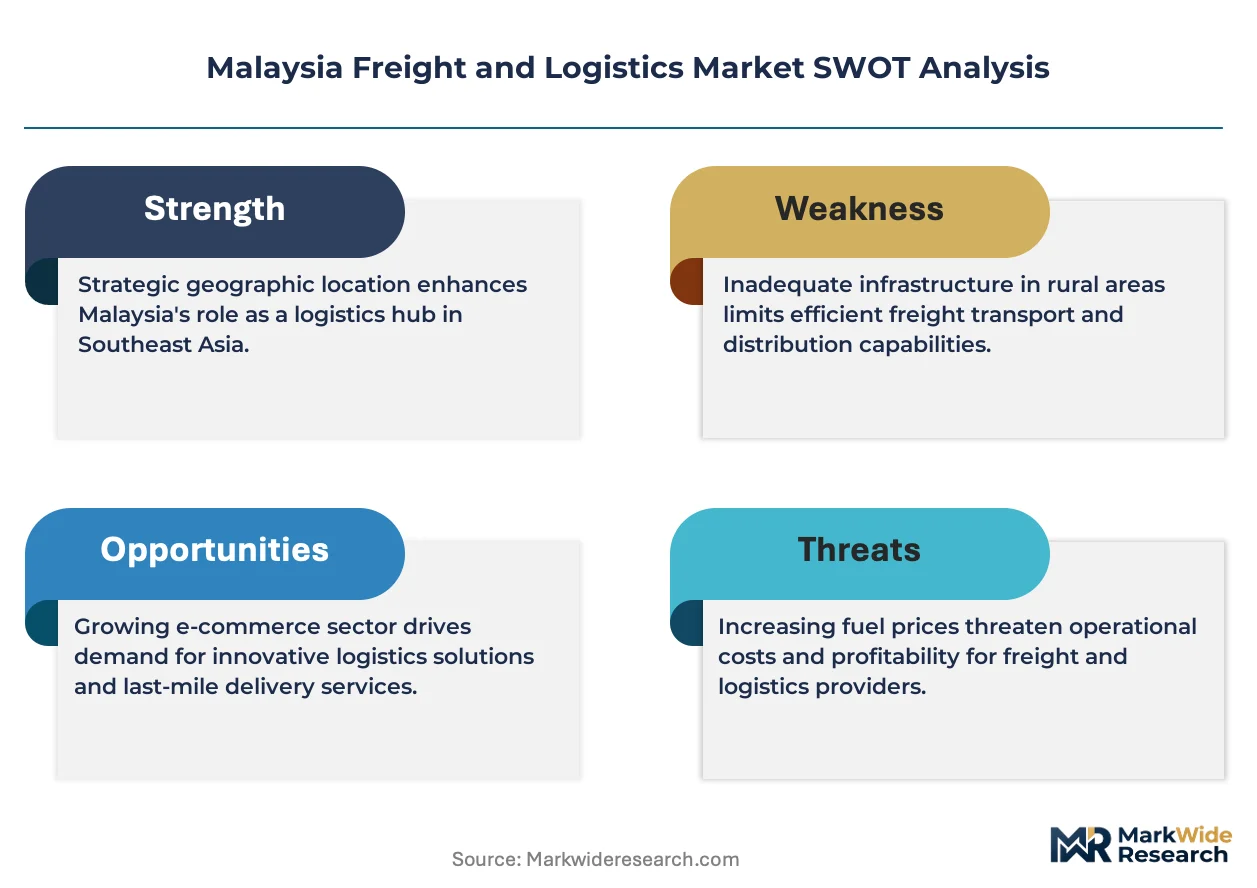
Malaysia's Ministry of Transport enforces commercial vehicle licensing and road safety standards that directly shape fleet modernization requirements and operator compliance costs. The Royal Malaysian Customs Department administers the Digital Free Trade Zone protocols and ASEAN Single Window integration, determining cross-border clearance speed and bonded warehouse eligibility. BIS-equivalent standards for container weighing and dangerous goods handling further structure equipment investment cycles. Stakeholders must weigh automation deployment timelines against the risk of regulatory fragmentation if ASEAN member states diverge on digital customs interoperability.
Market Dynamics
Parcel consolidation among Shopee, Lazada, and TikTok Shop is compressing logistics margins while forcing fleet automation investments across Peninsular Malaysia's distribution corridors.
Growth Catalysts
- Digital Free Trade Zone protocols:The Royal Malaysian Customs Department's ASEAN Single Window integration accelerates cross-border clearance speeds and bonded warehouse eligibility for e-commerce fulfillment.
- Last-mile automation:Automated sorting hubs in Shah Alam and Johor Bahru reduce per-parcel handling costs for high-volume e-commerce delivery networks.
- Peninsular Malaysia corridor density:Concentrated demand along the Klang Valley-to-Port Klang axis generates route efficiencies unavailable in archipelago logistics markets.
Market Restraints
- Diesel price volatility:Fleet operators absorb fuel surcharge fluctuations that constitute 35-40% of road haulage operating costs, compressing contract margins on fixed-rate B2B agreements.
- Port Klang container terminal concentration:Over 70% of Malaysia's maritime container throughput flows through two terminal operators, creating bottleneck vulnerability during peak seasonal surges.
- Driver shortage structural ceiling:Heavy vehicle license issuance rates trail fleet expansion requirements, particularly for refrigerated and dangerous goods endorsements.
Strategic Opportunities
- East Malaysia underpenetration:Sabah and Sarawak's e-commerce delivery networks remain 40-50% less dense than Peninsular Malaysia, offering first-mover consolidation potential for parcel operators.
- Cold chain pharmaceutical expansion:Temperature-controlled last-mile capabilities for biologics and vaccines command 3-4x standard parcel pricing with limited specialized competition.
- Senai Airport bonded zone expansion:The Iskandar Malaysia corridor's free zone status enables regional distribution hub positioning for ASEAN market access.
Industry Challenges
- Warehouse management system integration:Legacy inventory platforms at mid-tier 3PLs resist API connectivity with Shopee and Lazada seller dashboards, forcing manual order reconciliation.
- Refrigerated fleet capex intensity:Multi-temperature zone vehicles require 2.5x standard truck investment with 7-year depreciation schedules that strain SME operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Freight and Logistics Market |
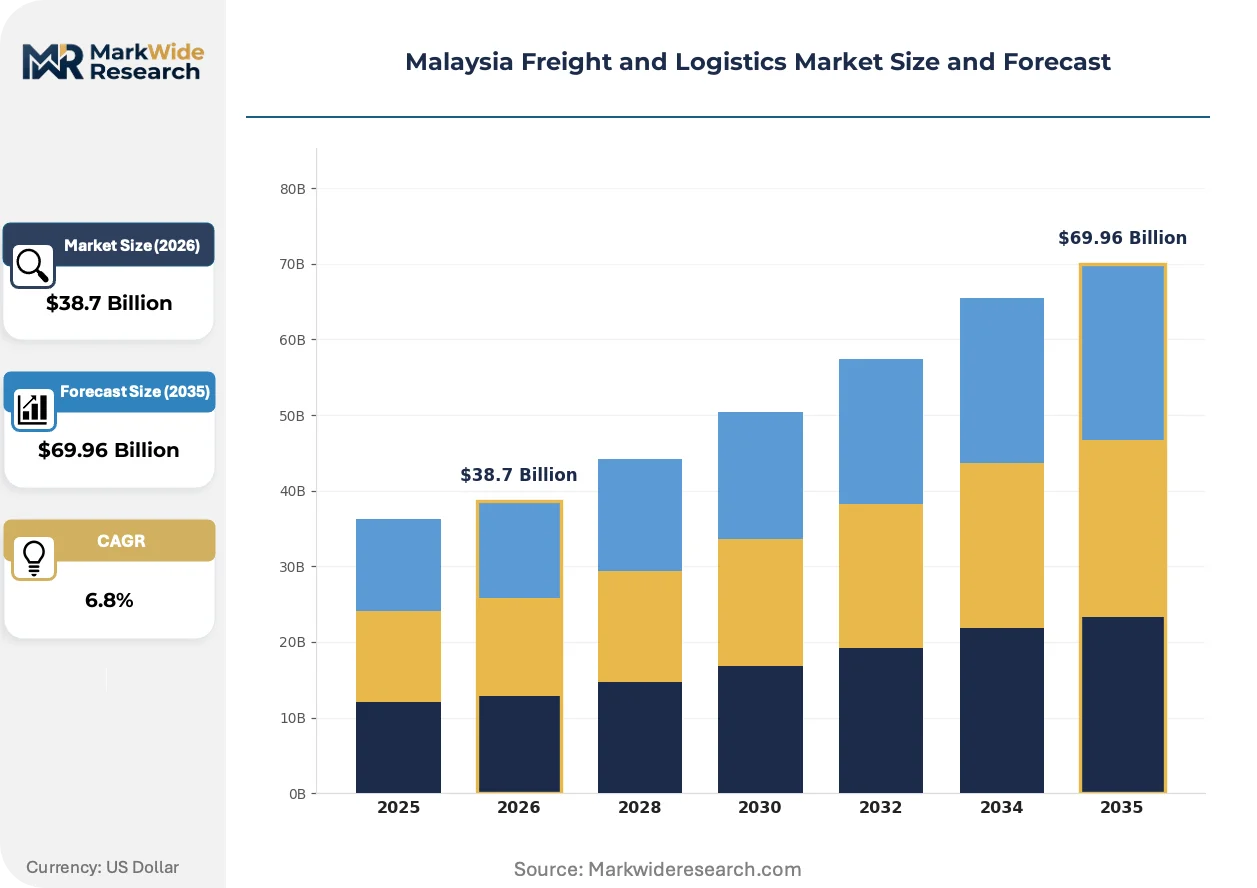
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Last-Mile Delivery End User: Retail, Manufacturing, E-Commerce, Healthcare Technology: Automation, Tracking Systems, Cloud Solutions, IoT Application: Cold Chain, Bulk Transport, Containerized Shipping, Project Cargo |
| Companies Covered | POS Malaysia Bhd, DHL Group, J&T Express, City-Link Express, GDEX Group, CJ Logistics Corporation, Tiong Nam Logistics Holdings Berhad, GEODIS, MMC Corporation Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Freight and Logistics Market Strategic Shifts
Automation investments are compressing unit economics in parcel sorting while regulatory digitization reshapes customs clearance workflows across Malaysian trade corridors.
Autonomous mobile robots in sortation facilities are consolidating manual pick-and-pack operations into centralized hub architectures. E-commerce fulfillment centers in Selangor deploy robotic palletizing systems that reduce labor headcount by 60% on night shifts. This consolidation is eliminating sub-scale regional depots and concentrating volume through Shah Alam and Petaling Jaya mega-hubs.
The Royal Malaysian Customs Department's Digital Free Trade Zone mandate requires real-time manifest submission through the uCustoms platform. This policy shift eliminates paper-based clearance for cross-border e-commerce parcels below RM500. Small parcel operators without integrated customs APIs face exclusion from TikTok Shop and Shopee cross-border programs.
Buyer concentration among platform sellers is rotating procurement toward outcome-based delivery guarantees rather than per-kilometer rates. Third-party logistics contracts now specify 24-hour delivery windows with penalty clauses rather than fuel-adjusted tariffs. This shift is most visible in Klang Valley consumer electronics distribution, where Lazada's fulfillment mandates determine 3PL selection criteria.
Malaysia Freight and Logistics Market Segmentation
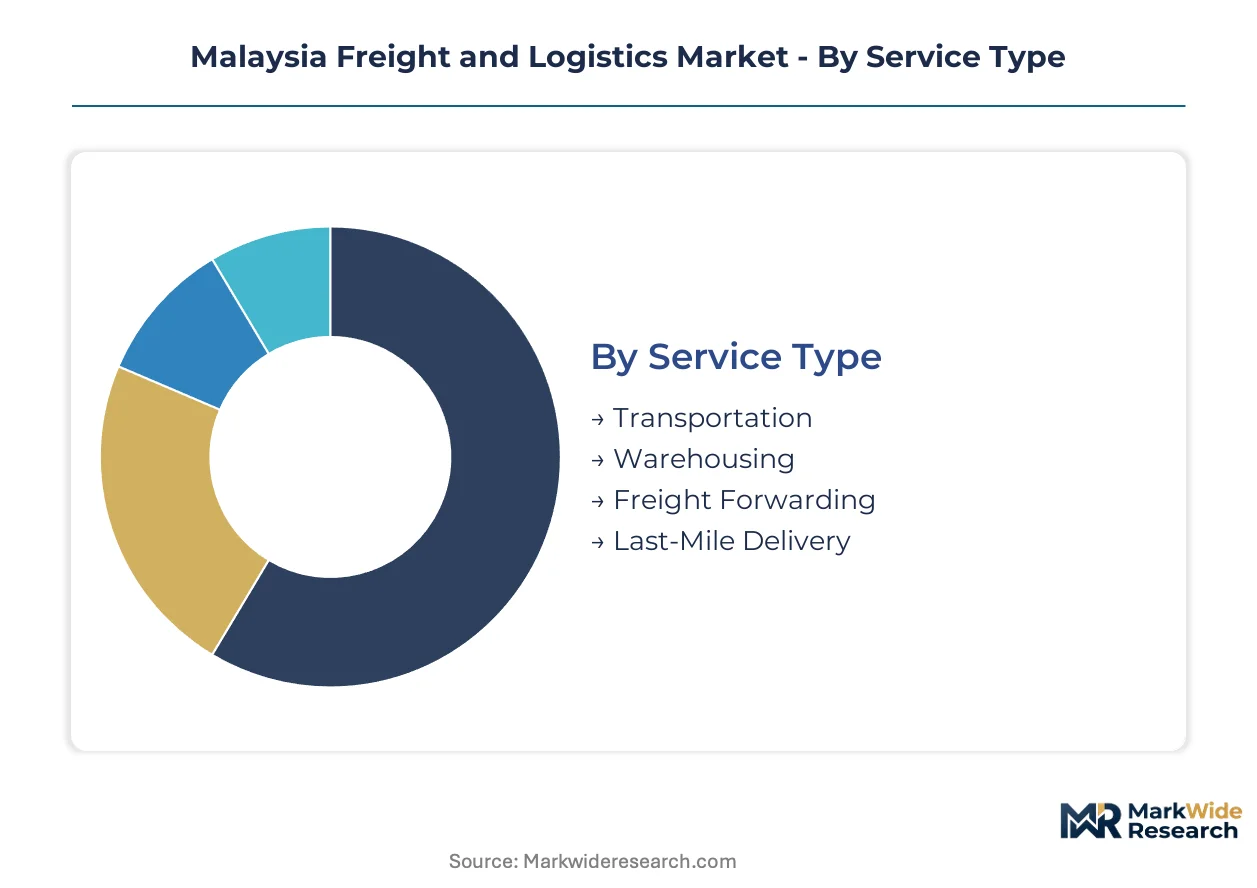
Malaysia's freight and logistics market segments reveal distinct operational architectures. Transportation services dominate revenue through fuel-linked tariffs, while warehousing expands fastest around Port Klang's bonded zones. Technology adoption separates integrated operators from legacy competitors unable to meet e-commerce platform API requirements.
Service Type:
Standalone transportation services operate independently of embedded fulfillment networks, while warehousing and last-mile delivery increasingly integrate into end-to-end platform ecosystems.
- Transportation:Road haulage and maritime container movement generate the largest revenue pool through distance-based tariffs and fuel surcharge mechanisms. Fleet operators serving the Klang Valley corridor capture density advantages unavailable in East Malaysia's dispersed routes.
- Warehousing:Bonded storage facilities around Port Klang and Senai Airport enable duty-deferred inventory positioning for regional distribution strategies. Cold storage commands premium pricing from pharmaceutical shippers requiring temperature-validated chain of custody.
- Freight Forwarding:Customs brokerage and multimodal coordination services consolidate shipments across fragmented SME exporters. Royal Malaysian Customs Department's uCustoms platform integration now determines competitive viability.
- Last-Mile Delivery:Parcel networks serving Shopee, Lazada, and TikTok Shop concentrate volume through automated Shah Alam sorting hubs. Driver shortages and diesel price volatility compress margins on fixed-rate platform contracts.
Transportation leads volumes today; last-mile delivery is gaining share fastest through e-commerce platform procurement consolidation.
End User:
Cost tier separation distinguishes high-volume platform contracts from specialized healthcare and manufacturing logistics requiring compliance documentation.
- Retail:Department store and supermarket distribution networks demand scheduled replenishment with penalty clauses for stockout events. Cold chain requirements from fresh food categories drive refrigerated fleet investment.
- Manufacturing:Electronics and automotive component supply chains require just-in-time delivery windows tied to production schedules. Penang and Johor Bahru industrial zones generate concentrated demand for bonded warehousing.
- E-Commerce:Platform sellers procure logistics through outcome-based delivery guarantees rather than per-kilometer rates. Shopee and Lazada fulfillment mandates determine 3PL selection criteria in Selangor.
- Healthcare:Pharmaceutical and medical device distribution requires temperature-controlled transport with GDP certification. Biologics and vaccine shipments command 3-4x standard parcel pricing with limited specialized competition.
E-commerce leads volume expansion; healthcare logistics commands the steepest pricing premium per kilogram handled.
Technology:
Application maturity separates proven tracking infrastructure from emerging IoT deployments still seeking scale economics.
- Automation:Robotic palletizing and autonomous mobile robots consolidate manual operations in Shah Alam and Petaling Jaya mega-hubs. Night shift labor headcount reductions of 60% justify capital deployment timelines.
- Tracking Systems:GPS and RFID infrastructure provides shipment visibility required by platform seller dashboards. Real-time manifest submission through uCustoms eliminates paper-based clearance for cross-border parcels.
- Cloud Solutions:Warehouse management system APIs enable direct order reconciliation with Shopee and Lazada seller platforms. Legacy inventory platforms at mid-tier 3PLs resist connectivity, forcing manual intervention.
- IoT:Sensor networks for temperature monitoring and predictive maintenance remain in pilot deployment. Cold chain pharmaceutical applications show strongest adoption trajectory among compliance-sensitive shippers.
Tracking systems dominate installed base; IoT is climbing the fastest as sensor costs decline and pharmaceutical validation requirements harden.
Application:
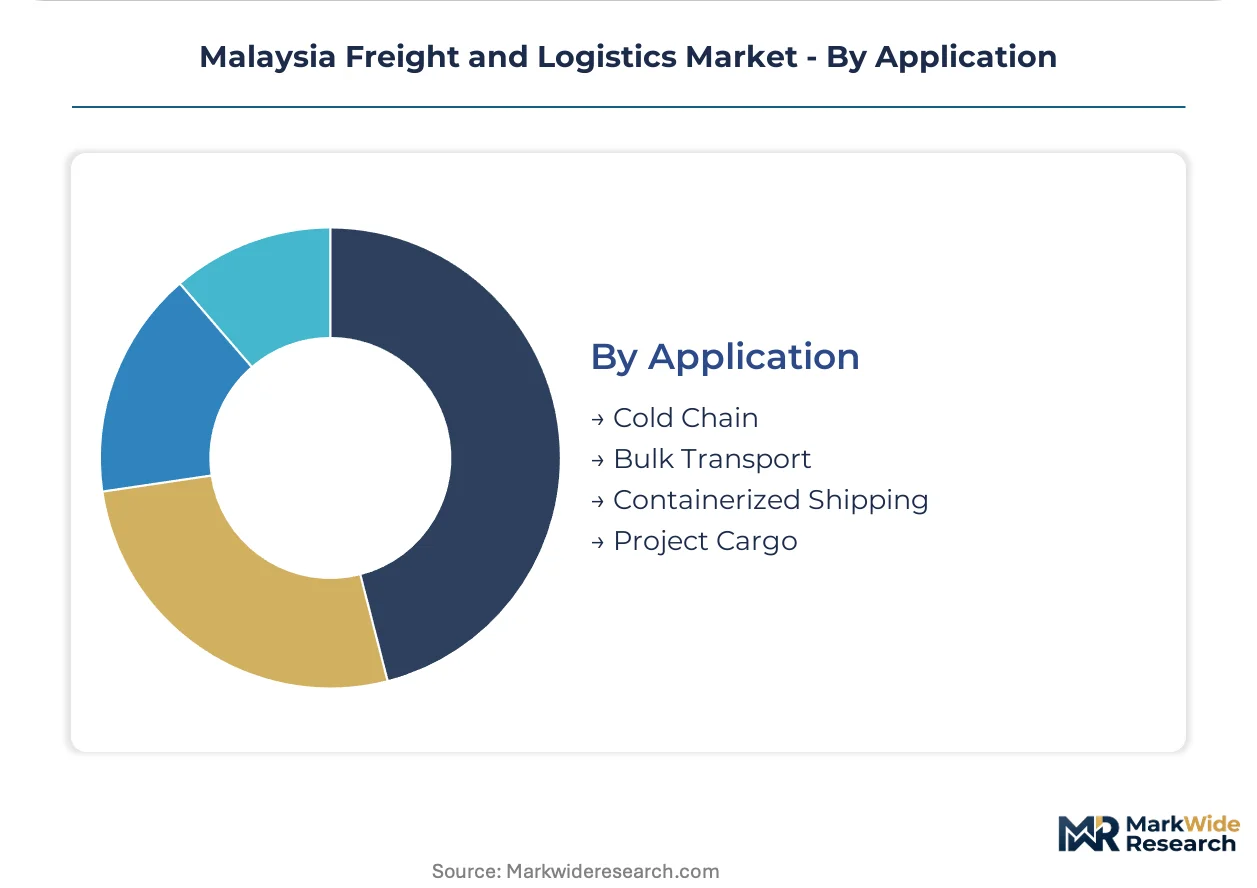
Geographic concentration shapes competitive dynamics, with cold chain and containerized shipping anchoring Peninsular Malaysia while project cargo serves East Malaysia infrastructure development.
- Cold Chain:Temperature-controlled storage and transport for perishables, pharmaceuticals, and chemicals requires multi-zone vehicle fleets. GDP-certified operators capture vaccine and biologics distribution with limited competition.
- Bulk Transport:Uncontainerized commodities including palm oil, petroleum products, and construction materials move through dedicated terminal infrastructure. Port Klang liquid bulk facilities serve regional energy trading.
- Containerized Shipping:Standardized maritime containers dominate manufactured goods trade through Port Klang's two-terminal concentration. Over 70% of national throughput creates bottleneck vulnerability during peak surges.
- Project Cargo:Oversized and heavy-lift shipments support infrastructure construction in Sabah and Sarawak. East Malaysia's underpenetrated logistics networks offer first-mover consolidation potential for specialized operators.
Containerized shipping leads throughput volumes; cold chain is expanding most quickly through pharmaceutical distribution requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's archipelago logistics complexity contrasts sharply with Thailand's concentrated Bangkok-Chonburi corridor density, while Vietnam's northern manufacturing belt generates fundamentally different freight patterns than either neighbor.
Indonesia
E-commerce parcel volumes from Tokopedia and Shopee Indonesia strain Java-centric distribution networks. The country's national logistics regulator enforces mandatory domestic shipping preference rules under the National Logistics Ecosystem program. The Jakarta-Bandung-Surabaya triangle concentrates automated sorting investments while outer islands remain dependent on inter-island ferry connections.
Thailand
Automotive component exports and electronics manufacturing drive just-in-time delivery requirements through Eastern Economic Corridor facilities. Thailand's Ministry of Transport coordinates ASEAN Single Window implementation with cross-border truck queue reduction targets. The Bangkok-Chonburi-Rayong axis hosts bonded warehouses serving regional distribution strategies for Japanese automotive OEMs.
Vietnam
North American-bound manufacturing relocation from China accelerates deep-water port demand at Hai Phong and Cai Mep. Vietnam Customs operates the automated VNACCS/VCIS platform for electronic manifest processing. The Hanoi-Hai Phong-Quang Ninh manufacturing belt generates concentrated container traffic that outpaces southern logistics infrastructure development.
Singapore
Transhipment dominance at PSA Corporation terminals anchors regional maritime connectivity for intra-ASEAN trade flows. The Maritime and Port Authority of Singapore mandates low-carbon fuel standards under the Green Port Programme. Jurong Island's petrochemical cluster generates specialized tanker and liquid bulk logistics demand distinct from containerized general cargo.
Philippines
Archipelago e-commerce fulfillment struggles with Manila port congestion and Visayas-Mindanao inter-island connectivity gaps. The Bureau of Customs administers the Customs Modernization and Tariff Act for electronic payment and risk-based inspection. The Cavite-Laguna-Batangas corridor concentrates warehousing development serving Greater Manila consumption demand.
Malaysia Freight and Logistics Market Competitive Environment
Peninsular Malaysia operators anchor the high-volume parcel tier; East Malaysia specialists hold project cargo and bulk commodity positions. The market structures around three strategic archetypes: postal infrastructure incumbents with universal service obligations, global express networks with air hub dominance, and automated parcel specialists scaling through platform contracts. Competitive moves concentrate on automated sorting hub deployment and cold chain fleet expansion.
Among Malaysia-based operators, POS Malaysia Bhd exemplifies the postal infrastructure archetype leveraging nationwide last-mile reach. DHL Group and J&T Express occupy contrasting positions on the premium express versus high-volume automation spectrum. These three anchors represent the competitive tension between legacy universal service mandates and platform-driven parcel consolidation economics.
| Leading Market Players |
|---|
| POS Malaysia Bhd |
| DHL Group |
| J&T Express |
| City-Link Express |
| GDEX Group |
| CJ Logistics Corporation |
| Tiong Nam Logistics Holdings Berhad |
| GEODIS |
| MMC Corporation Berhad |
| Others |
Value Chain & Pricing Dynamics
Shopee and Lazada's consolidated procurement mandates are compressing per-parcel margins across Peninsular Malaysia's logistics networks, forcing operators to automate Shah Alam sorting hubs or exit fixed-rate platform contracts entirely. This buyer-side consolidation is reshaping supply chain investments toward density-dependent route structures that only mega-hub architectures can serve profitably.
Pricing Analysis
Capacity additions in Selangor and Johor are reshaping price floors for last-mile delivery as J&T Express and City-Link Express deploy automated sorting infrastructure that cuts unit handling costs. Three-tier pricing structure across premium express, standard parcel, and economy deferred-delivery levels separates DHL's air-hub services from ground-based competitors. Cost compression in the standard tier is intensifying because diesel price volatility absorbs 35-40% of road haulage operating budgets. SME manufacturers show highest price sensitivity, while pharmaceutical shippers accept premium cold-chain tariffs for GDP-certified chain of custody.
Supply Chain Analysis
Single-source vulnerability sits with Port Klang's two-terminal concentration, where over 70% of Malaysia's maritime container throughput creates bottleneck exposure during peak seasonal surges. Equipment manufacturing draws from China, South Korea, and Japan for automated sorting systems and refrigerated vehicle components. Diesel fuel, palletized handling equipment, and bonded warehouse construction materials constitute critical input dependencies. Tariff exposure on Chinese-manufactured automation hardware presents structural risk as ASEAN customs integration proceeds. Distribution runs through Klang Valley corridor consolidation before radiating to East Malaysia's underpenetrated Sabah and Sarawak networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's freight and logistics market offers margin expansion through automation-driven cost compression in parcel handling and premium-tier cold-chain pricing for pharmaceutical distribution. Fleet operators capturing bonded zone positioning around Senai Airport can extract regional distribution premiums unavailable to Peninsular-only competitors.
For Market Incumbents: Deploy automated sorting hub capacity in Shah Alam and Petaling Jaya to defend fixed-rate e-commerce contracts against J&T Express's volume-scale economics. Integrate Royal Malaysian Customs Department's uCustoms API to maintain eligibility for TikTok Shop and Shopee cross-border programs as digital clearance mandates harden. Backward integration into refrigerated fleet ownership protects margin erosion from third-party truck leasing volatility. For New Entrants and Emerging Players: Specialized pharmaceutical distributors lacking temperature-validated last-mile capabilities represent the most penetrable buyer archetype in Malaysia's healthcare logistics segment. East Malaysia's Sabah and Sarawak corridors offer 40-50% lower delivery network density than Peninsular standards, enabling first-mover consolidation through project cargo and bulk commodity positioning. Partner with Senai Airport's bonded zone operators to anchor ASEAN regional distribution mandates from Iskandar Malaysia's free trade status. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier 3PLs possessing warehouse management system API connectivity to Shopee and Lazada seller dashboards but lacking capital for automated hub deployment. Long-term viability hinges on regulatory digitization compliance and cold-chain certification depth rather than pure fleet scale. Watch Royal Malaysian Customs Department's ASEAN Single Window integration pace as inflection indicator for cross-border clearance speed premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Hub Deployment | Shah Alam mega-hubs reduce night-shift labor headcount by 60% for parcel operators. |
| Cold Chain Fleet Expansion | GDP-certified refrigerated vehicles capture vaccine distribution at 3-4x standard parcel pricing. |
| Bonded Warehouse Positioning | Senai Airport free zone status enables duty-deferred ASEAN regional distribution strategies. |
| Customs API Integration | uCustoms platform connectivity determines eligibility for TikTok Shop cross-border programs. |
| East Malaysia Network Buildout | Sabah and Sarawak's underpenetrated corridors offer first-mover consolidation potential. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, e-commerce platform logistics procurement managers, Royal Malaysian Customs Department officials, cold-chain pharmaceutical shippers, and bonded warehouse operators with secondary validation. Trade flow databases, container terminal throughput records, commercial vehicle licensing statistics, and ASEAN Single Window implementation reports anchored supply-side modeling. Bottom-up parcel volume estimates and top-down GDP-linked freight demand projections triangulated market sizing.
Historical reference periods spanning pre-pandemic baselines through post-Digital Free Trade Zone implementation established trajectory anchors across the projection horizon. Segmentation modeling incorporated service type, end-user industry, technology adoption tier, and application mode with geographic concentration weights for Klang Valley versus East Malaysia corridors. CAGRs derived from elasticity-adjusted freight demand against fixed asset capacity expansion schedules, with diesel price volatility and driver shortage constraints as scenario variables.
Underlying measurement precision varies by segment; transportation and warehousing services carry tighter precision than emerging IoT-enabled cold chain tracking. Forecasts reflect assumptions about ASEAN customs interoperability, e-commerce platform procurement consolidation pace, and refrigerated fleet investment cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Europe Logistics Automation Market