
 Horizontal Machining Center Market | 2026-2036
Horizontal Machining Center Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Machining Center Market Analysis
The distributor-dealer channel for capital machine tools is narrowing as OEMs build direct digital sales platforms and captive service networks. Okuma leverages its North American technical centers to anchor aftermarket revenue streams independent of third-party distributors. Makino competes through application-specific engineering support in aerospace and medical end uses, while DMG MORI sustains global coverage via a hybrid model blending company-owned showrooms with selective regional partners.
A horizontal machining center positions the spindle parallel to the worktable, enabling chip evacuation via gravity and supporting pallet-based tombstone fixtures that machine four to six faces per setup; this geometry suits high-volume, tight-tolerance production of prismatic metal components. Five-axis configurations command the strongest margin pools in aerospace and medical applications where complex contouring eliminates multiple setups. CNC platforms dominate unit volume across automotive and industrial job shops, while multi-tasking variants that integrate turning and milling operations represent the fastest-growing product category as Tier-1 manufacturers consolidate machine counts.
EPA emissions standards and OSHA machine guarding regulations shape equipment specifications in the United States, while CE marking and the EU Machinery Directive govern market access across Europe. Japan's METI energy-efficiency benchmarks and China's GB standards for precision machine tools add compliance layers for exporters serving Asia-Pacific demand. Stakeholders must monitor how additive-hybrid technology integration and evolving carbon-border adjustment mechanisms reshape capital allocation timelines for fleet replacement decisions.
Market Dynamics
Hybrid additive-subtractive platforms are compressing traditional machine replacement cycles as aerospace and medical manufacturers consolidate multi-operation workflows onto single platforms. The EU Green Deal's carbon-border adjustment mechanism and EPA industrial emissions guidelines are accelerating capital equipment turnover toward energy-efficient architectures.
Growth Catalysts
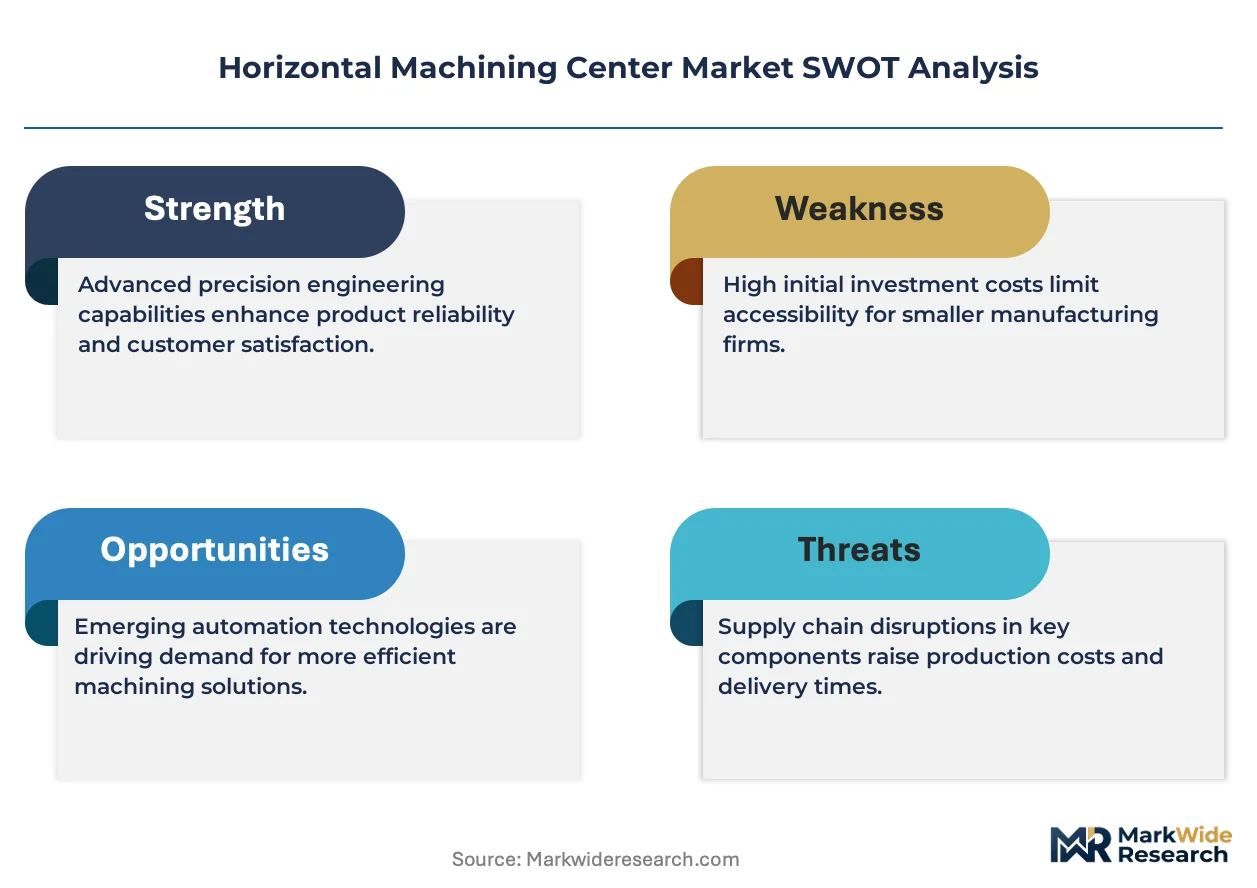
- Aerospace Titanium Machining:North American and European airframe manufacturers are expanding HMC fleets to machine titanium structural components. Pallet-based tombstone fixtures enable four-to-six-face machining per setup, reducing work-in-process inventory.
- EU Green Deal Mandates:Tighter energy-efficiency benchmarks under the EU Machinery Directive are pushing metalworking shops toward hybrid and automation-integrated platforms. CE marking requirements favor precision equipment with documented carbon footprints.
- Five-Axis Contouring Demand:Complex medical implant geometries are eliminating multiple setups through simultaneous five-axis machining. This configuration commands the strongest margin pools in tight-tolerance applications.
Market Restraints
- High-Precision Ball Screw Volatility:Japanese and German suppliers dominate ultra-precision linear motion components. Input cost swings for ground-grade ball screws compress OEM margin buffers during contract negotiations.
- China GB Standards Friction:Exporters face extended certification timelines under China's precision machine tool standards and MIIT energy-efficiency benchmarks. Compliance documentation requirements add six-to-nine-month market entry delays.
- Additive Manufacturing Substitution:Powder-bed fusion and directed energy deposition are capturing low-volume, high-complexity aerospace geometries previously routed to hog-out machining. Near-net-shape production reduces raw material waste but displaces HMC spindle hours.
Strategic Opportunities
- India PLI Scheme Tailwind:India's production-linked incentive scheme for precision manufacturing equipment creates localized assembly incentives. Domestic aerospace and defense procurement mandates favor suppliers with in-country technical centers.
- Medical Implant Automation Convergence:Integration of robotic part handling with in-process probing and laser measurement is collapsing lot sizes in orthopedic manufacturing. This technology pairing enables lights-out production of patient-specific devices.
- Direct Digital Sales Channels:OEMs are bypassing traditional distributor-dealer networks through captive e-commerce platforms and remote application engineering. This channel innovation captures aftermarket service revenue previously fragmented across third parties.
Industry Challenges
- CNC Programming Talent Scarcity:Five-axis simultaneous machining and multi-tasking turn-mill operations require specialized CAM programming expertise. Job shops report twelve-to-eighteen-month lead times for qualified applications engineers.
- Legacy Control Architecture Integration:Brownfield facilities with Fanuc, Siemens, or Heidenhain legacy controls face protocol mismatches when retrofitting automation cells. Fieldbus standardization gaps between generations create commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horizontal Machining Center Market |
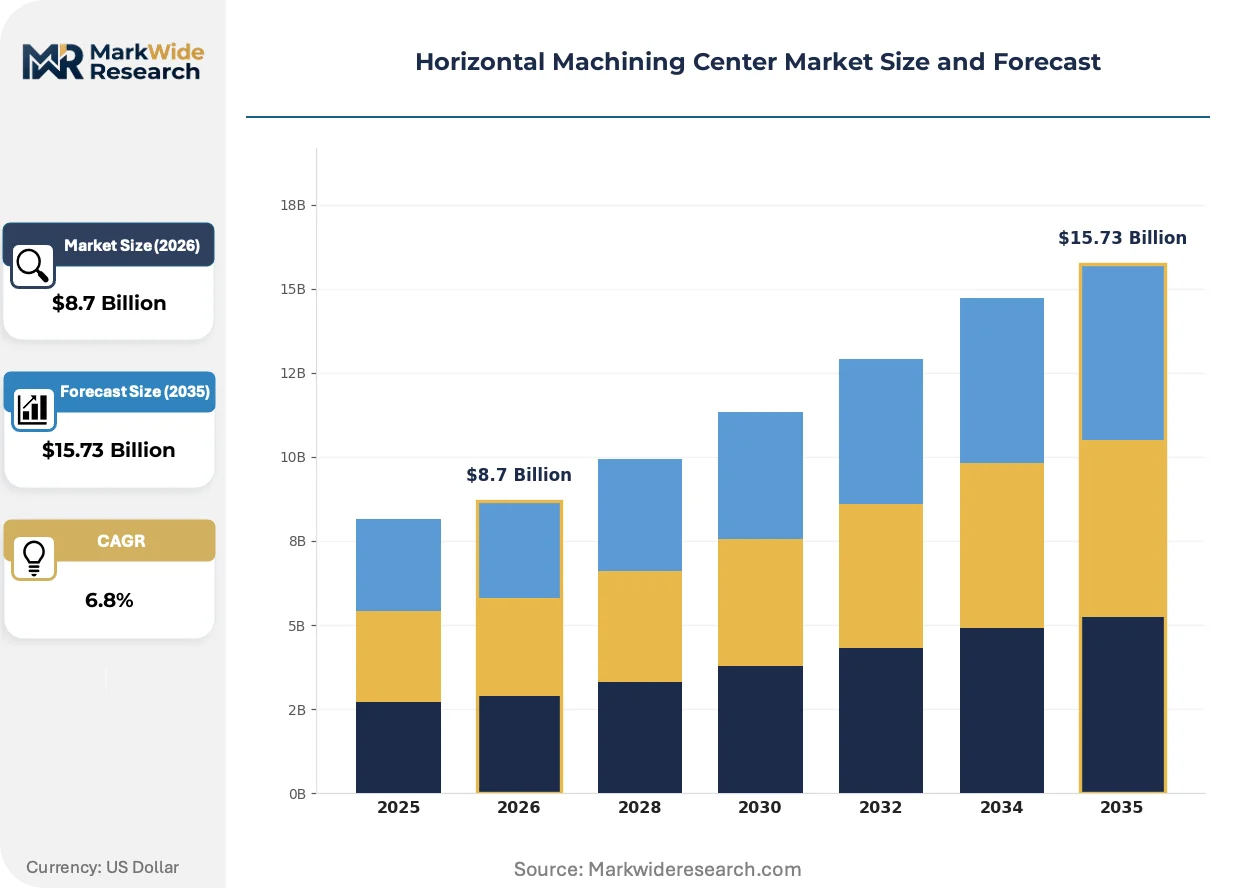
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5-Axis, 3-Axis, CNC, Multi-Tasking Application: Aerospace, Automotive, Industrial, Medical End User: OEMs, Job Shops, Tier-1 Manufacturers, Aftermarket Providers Technology: Hybrid, Additive Manufacturing, Conventional Machining, Automation |
| Companies Covered | Okuma, Makino, DMG MORI, Hurco, Grob, Yamazaki Mazak, Heller Maschinenfabrik, Mazak Corporation, Haas Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Machining Center Market Emerging Trajectories
Additive-hybrid machining centers are collapsing the boundary between roughing and finishing operations. Regulatory pressure on industrial emissions is reshaping equipment specifications across multiple jurisdictions. Distribution disintermediation is reallocating margin pools from third-party dealers toward captive service networks.
Integrated laser metal deposition heads on HMC platforms enable in-situ repair and feature addition on large aerospace components. Tier-1 airframe manufacturers in Germany and Japan are adopting these systems for titanium and Inconel structural parts. This architecture is collapsing the traditional separation between machining and welding workflows into unified production cells.
The EU F-Gas Regulation and EPA SNAP program are phasing out high-global-warming-potential refrigerants in machine tool cooling systems. Equipment manufacturers must redesign thermal management architectures to qualify for CE marking and OSHA-compliant export. Medical and semiconductor end-use segments are responding fastest, specifying hydrocarbon or CO2-based cooling in new capital requests.
Outcome-based service contracts are displacing traditional time-and-materials maintenance agreements in high-volume automotive applications. Tier-1 suppliers in the United States and Japan are contracting for guaranteed uptime per spindle hour rather than per-incident repair. This model concentrates service revenue with OEMs possessing remote diagnostic infrastructure and regional parts depots.
Horizontal Machining Center Market Segmentation
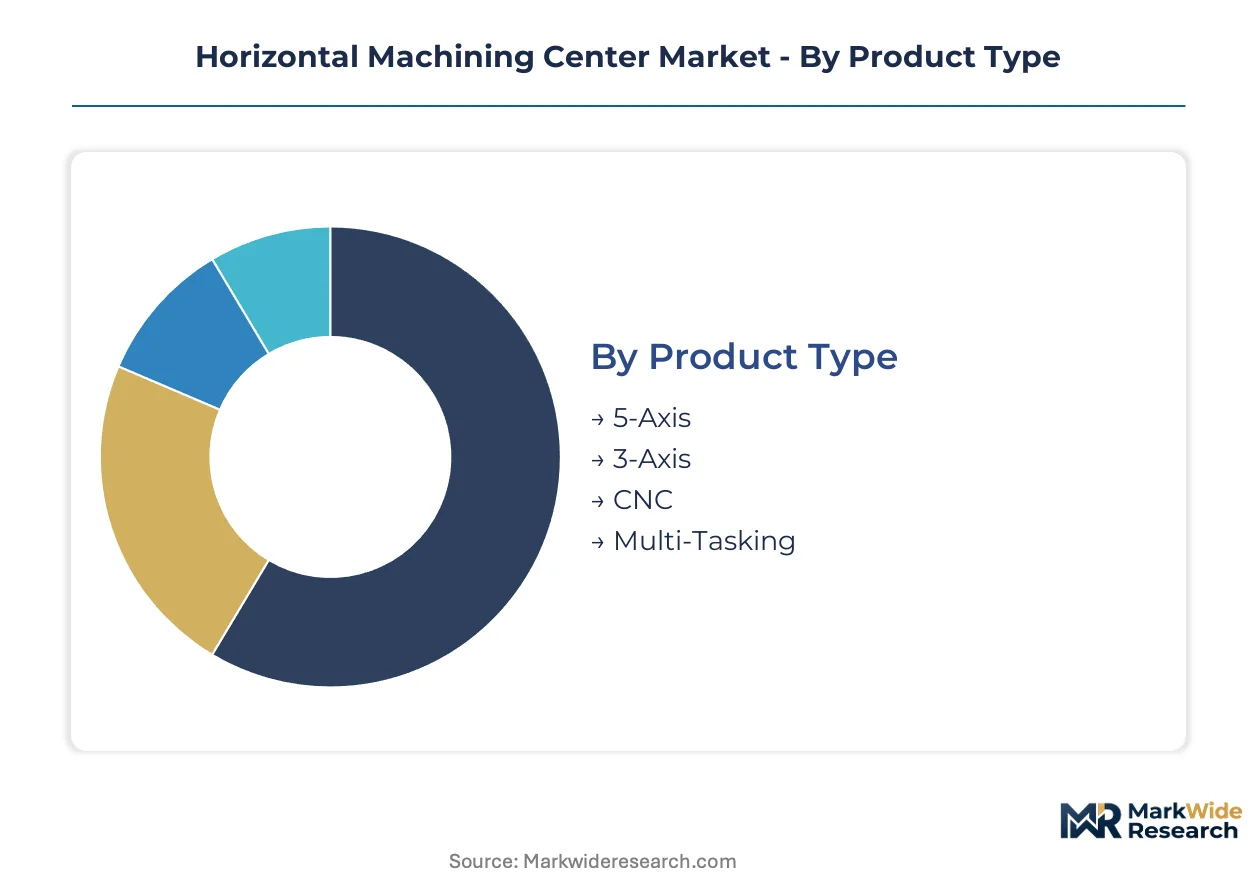
Horizontal machining center procurement patterns diverge sharply by product complexity and end-use tolerance requirements. Aerospace and medical buyers prioritize five-axis contouring capabilities, while automotive volume manufacturers optimize for pallet-based throughput and integration density.
Product Type:
Cost tier stratification separates premium five-axis platforms from standardized three-axis workhorses in capital allocation decisions.
- 5-Axis:Simultaneous contouring architectures machine complex titanium and Inconel geometries without multiple setups. Aerospace manufacturers in Germany and Japan specify these configurations for structural airframe components where tolerance stacking elimination justifies acquisition premiums.
- Multi-Tasking:Integrated turning-milling platforms consolidate operation counts onto single spindles. Tier-1 automotive suppliers in the United States deploy these systems to compress floor space and reduce work-in-process inventory across powertrain machining lines.
- CNC:Programmable three-axis platforms dominate unit volume in general industrial job shops.
- 3-Axis:Entry-level configurations serve high-volume prismatic production with simpler kinematic demands.
5-Axis holds installed capacity in aerospace clusters. Multi-Tasking is rotating up the share rankings in automotive consolidation programs.
Application:
End-use tolerance requirements and material hardness dictate spindle specification and fixture architecture across customer segments.
- Aerospace:Titanium and superalloy machining demands rigid spindle designs with through-tool coolant delivery. North American airframe OEMs specify HMC fleets with 50-taper spindles and pallet pools exceeding 20 stations for unmanned production of structural brackets and landing gear components.
- Medical:Orthopedic implant geometries require sub-micron positioning repeatability and thermal stability. Swiss and German device manufacturers prioritize machines with hydrocarbon cooling systems compliant with EU F-Gas Regulation phase-out timelines.
- Automotive:Powertrain block and head machining prioritizes metal removal rates and automation integration.
- Industrial:General metalworking applications span mold-and-die production to fluid power component manufacturing.
Aerospace commands specification leadership. Medical is expanding fastest on implant volume growth and regulatory cooling mandates.
End User:
Customer type determines procurement scale, financing structure, and service contract complexity in equipment sourcing.
- Tier-1 Manufacturers:High-volume production mandates drive fleet standardization and predictive maintenance contracts. Japanese automotive suppliers contract for guaranteed spindle uptime rather than per-incident service, concentrating aftermarket revenue with OEMs possessing remote diagnostic infrastructure.
- Job Shops:Flexible lot-size requirements favor quick-change fixturing and broad CAM compatibility. These operators in the United States report eighteen-month lead times for qualified five-axis programmers, constraining technology adoption velocity.
- OEMs:Captive production facilities prioritize integration with existing control architectures and automation cells.
- Aftermarket Providers:Repair and remanufacturing specialists concentrate on legacy control retrofit and spindle rebuild services.
Tier-1 Manufacturers anchor order backlogs. Job Shops are rotating up the share rankings as reshoring initiatives expand domestic metalworking capacity.
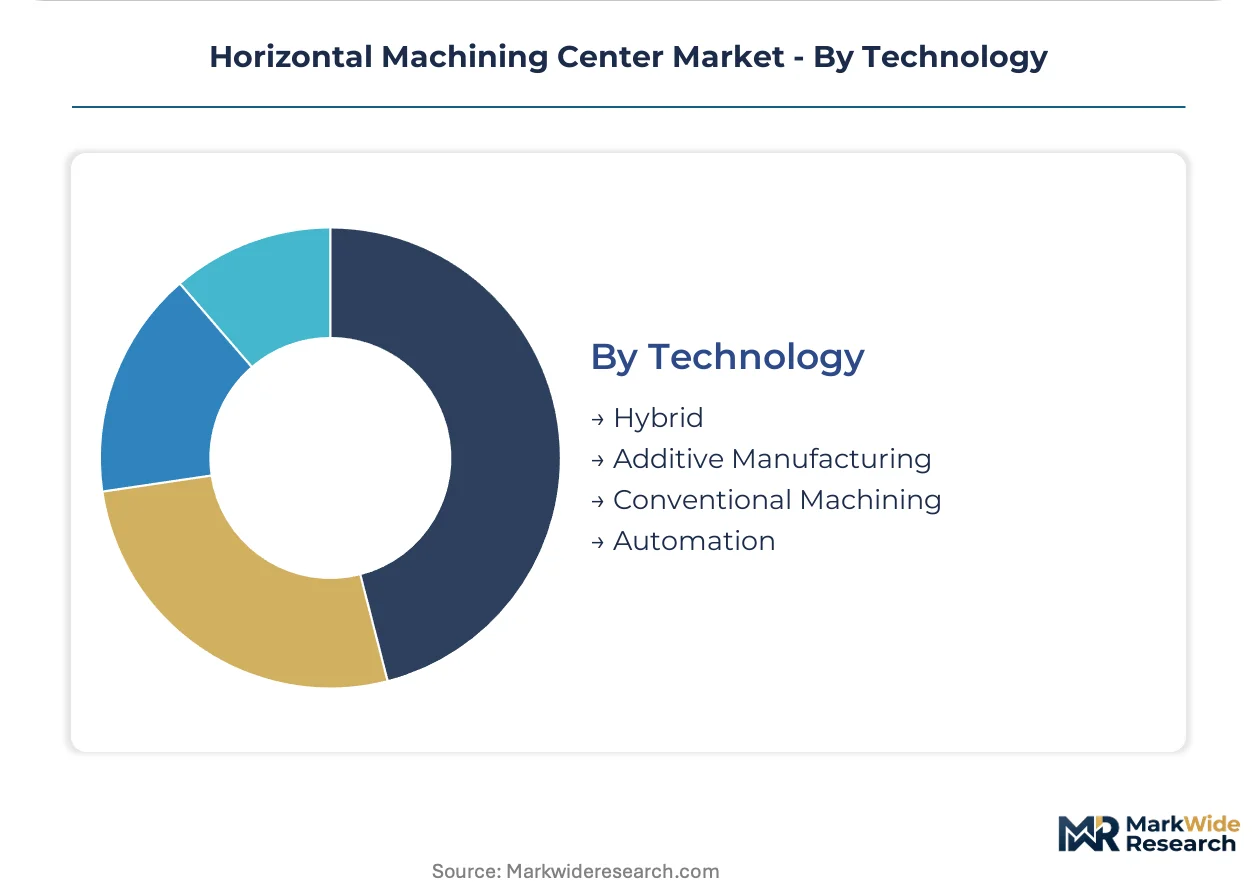
Technology:
Process integration maturity separates experimental hybrid platforms from proven conventional architectures in capital planning horizons.
- Hybrid:Additive-subtractive platforms integrate laser metal deposition heads for in-situ repair and feature addition. German aerospace Tier-1s deploy these systems for titanium structural components, collapsing traditional separations between machining and welding workflows.
- Automation:Robotic part handling with in-process probing enables lights-out production. Medical implant manufacturers in Japan specify these configurations for patient-specific device lot sizes below 50 units.
- Conventional Machining:Established subtractive-only platforms retain dominance in cost-sensitive high-volume applications.
- Additive Manufacturing:Standalone powder-bed systems capture low-complexity geometries previously routed to hog-out machining, displacing some HMC spindle hours in aerospace prototyping.
Conventional Machining holds installed capacity. Hybrid is rotating up the share rankings as EU Green Deal carbon-border mechanisms accelerate equipment turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machine tool manufacturers command pricing premiums exceeding 30% over comparable Japanese platforms in aerospace procurement tenders. Japanese builders counter with faster delivery cycles and localized technical centers in North America. Chinese domestic suppliers undercut both on initial acquisition cost while facing extended certification timelines in Western markets.
United States
Boeing and Lockheed Martin procurement programs are expanding HMC fleets for titanium structural components. EPA industrial emissions guidelines and OSHA machine guarding regulations shape equipment specifications for domestic metalworking shops. Wichita, Kansas and Seattle, Washington aerospace clusters anchor capital equipment demand for multi-pallet tombstone configurations.
Germany
Airbus supply chain mandates and automotive powertrain consolidation are driving five-axis platform adoption. CE marking requirements and the EU Machinery Directive enforce energy-efficiency benchmarks with documented carbon footprints. Stuttgart and Munich precision manufacturing clusters prioritize hybrid additive-subtractive platforms for Inconel medical implant production.
Japan
Domestic aerospace Tier-1s and medical device exporters are specifying hydrocarbon-cooled systems ahead of F-Gas Regulation phase-outs. METI energy-efficiency benchmarks favor automation-integrated architectures with remote diagnostic capabilities. Nagoya and Osaka industrial corridors concentrate technical center infrastructure for Southeast Asian market support.
China
State-owned aerospace conglomerates are expanding captive machining capacity for C919 airframe programs. GB standards for precision machine tools and MIIT energy-efficiency compliance add six-to-nine-month market entry delays for foreign OEMs. Shenyang and Xi'an aviation industrial bases prioritize domestic supplier qualification over import procurement.
India
Defense procurement localization mandates under the PLI scheme for precision manufacturing equipment are reshaping capital allocation. Domestic aerospace and defense procurement rules favor suppliers with in-country technical centers. Bangalore and Hyderabad precision engineering clusters are expanding HMC adoption for satellite component machining.
Horizontal Machining Center Market Vendor Landscape
Premium-system integrators and volume-platform builders split the market along application-complexity lines. German and Japanese OEMs anchor the high-margin aerospace-medical tier with application-specific engineering support. Taiwanese and Chinese suppliers occupy cost-sensitive job shop segments. Consolidation pressure is accelerating through direct digital sales channel expansion and captive aftermarket service network buildout.
Among Japanese precision machinery builders, Okuma and Makino exemplify the application-engineering archetype with North American technical center infrastructure. DMG MORI represents the hybrid-model specialist blending company-owned showroom presence with selective regional partnerships. These three anchors illustrate divergent responses to distributor disintermediation pressure across major demand clusters.
| Leading Market Players |
|---|
| Okuma |
| Makino |
| DMG MORI |
| Hurco |
| Grob |
| Yamazaki Mazak |
| Heller Maschinenfabrik |
| Mazak Corporation |
| Haas Automation |
| Others |
Supply Flow & Price Mechanics
The Yokohama-Hamburg maritime corridor's container rate volatility feeds directly into landed cost spreads between Japanese and German OEMs, compressing margin buffers for precision ball screw imports while amplifying price differentiation between configured-to-order five-axis platforms and standardized three-axis units.
Pricing Analysis
Configured-to-order pricing for five-axis simultaneous contouring platforms commands spreads exceeding standard three-axis configurations by factors tied to application engineering intensity and CE marking documentation depth. Pricing stratifies across aerospace-certified, automotive-volume, and job-shop economy tiers, with differentiation driven by spindle taper specification and pallet pool integration density. Cost compression in the economy tier intensifies as Taiwanese builders expand direct digital sales channels. Job shops exhibit highest price sensitivity due to capital constraint structures, while Tier-1 aerospace manufacturers prioritize specification compliance over acquisition cost.
Supply Chain Analysis
Extended payment terms from Japanese and German linear motion component suppliers have become standard for qualified OEM procurement relationships, with supply-chain finance facilities bridging working capital gaps for tier-two machine builders. Ultra-precision ball screw production concentrates in Japan, Germany, and Switzerland, while cast iron bed structures and servo motor assemblies draw from Chinese and South Korean manufacturing bases. Single-source vulnerability in ground-grade ball screw supply creates exposure during contract renegotiation cycles. Distribution runs through OEM captive technical centers for premium platforms and regional equipment distributors for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as additive-hybrid technology integration and reshoring mandates splinter demand across application-specific niches previously served by general-purpose platforms.
For Market Incumbents: Build captive service network moats by consolidating aftermarket revenue through remote diagnostic infrastructure and regional parts depot density. Defend against additive manufacturing substitution by embedding laser metal deposition capabilities into existing five-axis architectures. Deepen backward integration into spindle cartridge production to buffer margin compression from Japanese ball screw suppliers.
For New Entrants and Emerging Players: India's PLI scheme precision manufacturing equipment tier represents the most penetrable entry point for mid-market builders lacking established aerospace certification portfolios. Medical implant automation convergence in Japan and Germany offers secondary white-space for robotic part handling integration specialists. Establish go-to-market presence through localized technical center partnerships rather than distributor dependency.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized machine tool divisions lacking standalone aftermarket service infrastructure. Long-term viability favors platforms with demonstrated integration paths to hybrid additive-subtractive architectures. Monitor EU carbon-border adjustment mechanism implementation velocity as fleet replacement demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Development | Additive-subtractive integration captures aerospace repair workflows previously outsourced to welding cells. |
| Captive Service Network Expansion | Remote diagnostic infrastructure locks in aftermarket revenue from Tier-1 automotive uptime contracts. |
| Direct Digital Channel Buildout | E-commerce platforms bypass distributor margin extraction in cost-sensitive job shop segments. |
| Backward Integration into Spindles | In-house cartridge production buffers OEMs against Japanese ultra-precision component supply volatility. |
| India Technical Center Establishment | Localized assembly qualification unlocks PLI scheme procurement mandates for defense aerospace programs. |
Methodological Framework
Desk research of customs trade databases, METI machine tool production statistics, and EU Machinery Directive certification registries preceded structured interviews with aerospace procurement directors, Tier-1 automotive manufacturing engineers, medical device quality managers, and aftermarket service heads. Primary fieldwork across German precision manufacturing clusters, Japanese industrial corridors, and North American aerospace hubs combined with secondary validation from SEC equipment manufacturer filings and production capacity disclosures. Bottom-up unit shipment modeling and top-down capital expenditure triangulation anchored volume estimates.
Assumption sets held energy-efficiency regulatory stringency and carbon-border mechanism implementation schedules fixed while varying aerospace production rate scenarios and reshoring initiative funding levels across the projection horizon. Segmentation dimensions modeled include product architecture complexity, end-use tolerance requirements, control system generation, and regional regulatory compliance tier. CAGRs derived from equipment replacement cycle compression analysis and technology substitution elasticity estimates, with specific inputs from titanium machining demand curves and F-Gas Regulation cooling system phase-out timelines.
Practitioners should monitor additive manufacturing capability maturation and EU Green Deal enforcement velocity for early signals of capital allocation timeline shifts. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology substitution rates. Macroeconomic contraction, trade barrier escalation, or breakthrough near-net-shape production economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Collating Machinery Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Road Roller Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Global Riveting Equipment Market