
 Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market | 2026-2036
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market Insights
The capital-intensity divergence between large-scale injectable manufacturers and niche neuromodulator developers is bifurcating competitive dynamics across the region. Teva Pharmaceutical Industries leverages its established sterile manufacturing footprint to sustain hospital pharmacy contracts in Israel and Australia. Takeda anchors its position through deep relationships with Japanese neurocritical care networks, while Sun Pharmaceutical Industries competes on cost-engineered antiplatelet supply to Indian public health systems.
Aneurysmal subarachnoid hemorrhage drugs comprise pharmaceutical agents targeting cerebral vasospasm prevention, blood pressure modulation, and secondary ischemia mitigation following arterial rupture, with intravenous nimodipine formulations representing the most widely administered acute intervention. These therapeutics serve primarily to reduce delayed cerebral ischemia incidence and improve functional outcomes in neurointensive care settings. Vasospasm-prophylaxis drugs occupy the dominant revenue position given their mandatory status in post-hemorrhage protocols, while intra-arterial administration routes capture premium pricing due to catheterization complexity and specialized neuroradiology requirements. Hospital pharmacies control the bulk of distribution volume through direct-to-ward dispensing tied to stroke center accreditation standards.
Japan's PMDA and Australia's TGA enforce divergent neurocritical drug stability and bioequivalence requirements that shape regional formulation strategies and trial placement decisions. India's CDSCO and China's NMPA maintain distinct import licensing frameworks for controlled anticoagulant substances, creating fragmented market access conditions. Stakeholders must monitor evolving stroke center certification criteria across South Korea, Singapore, and Thailand to anticipate procurement channel shifts and reimbursement tier realignments.
Market Dynamics
Hospital-based stroke center accreditation programs across the Asia-Pacific are mandating standardized vasospasm-prophylaxis protocols, concentrating procurement authority in tertiary neurocritical care networks and compressing formulary flexibility for acute hemorrhage interventions.
Growth Catalysts
- PMDA Streamlined Pathways:Japan's pharmaceutical regulator accelerated neurocritical drug approval timelines in response to aging-population hemorrhagic stroke burden, reducing time-to-market for intravenous nimodipine formulations.
- Interventional Neuroradiology Expansion:Eastern China's tertiary hospitals are scaling catheterization laboratory capacity, creating demand pull for intra-arterial drug delivery systems.
- Vasospasm-Prophylaxis Protocol Mandates:Australian and South Korean stroke center certification standards now require documented prophylaxis administration, embedding pharmaceutical agents into acute care workflows.
Market Restraints
- Controlled Substance Import Licensing:India's CDSCO and China's NMPA maintain divergent anticoagulant import frameworks, fragmenting cross-border supply continuity for critical hemorrhage interventions.
- Sterile Manufacturing Concentration:Injectable formulation capacity clusters in Japan and Australia, creating geographic supply vulnerability for markets dependent on imported finished doses.
- Bioequivalence Testing Divergence:Australia's TGA and Japan's PMDA enforce non-harmonized stability requirements, forcing duplicate formulation development and raising registration costs.
Strategic Opportunities
- Southeast Asia Stroke Center Buildout:Thailand and Vietnam are constructing tertiary neurocritical units without established formulary relationships, creating first-mover positioning for protocol-integrated suppliers.
- Pre-Hospital Administration Routes:Ambulance-based nimodipine delivery systems are emerging as a channel innovation, extending pharmaceutical touchpoints beyond hospital pharmacy control.
- PLI Scheme Alignment:India's production-linked incentive framework for pharmaceuticals offers cost-offset potential for domestic sterile injectable manufacturing investments.
Industry Challenges
- Neurointensive Care Specialist Scarcity:Trained neuroradiologists and neurocritical pharmacists remain concentrated in Japan, Australia, and eastern China, limiting protocol adoption velocity in emerging stroke centers.
- Catheterization Laboratory Capex Requirements:Intra-arterial drug administration infrastructure demands specialized angiography suites, constraining site expansion beyond well-capitalized urban hospital systems.
- Multinational Trial Placement Complexity:Divergent PMDA, TGA, and NMPA clinical data requirements complicate regional study design, extending development timelines for novel vasospasm agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market |
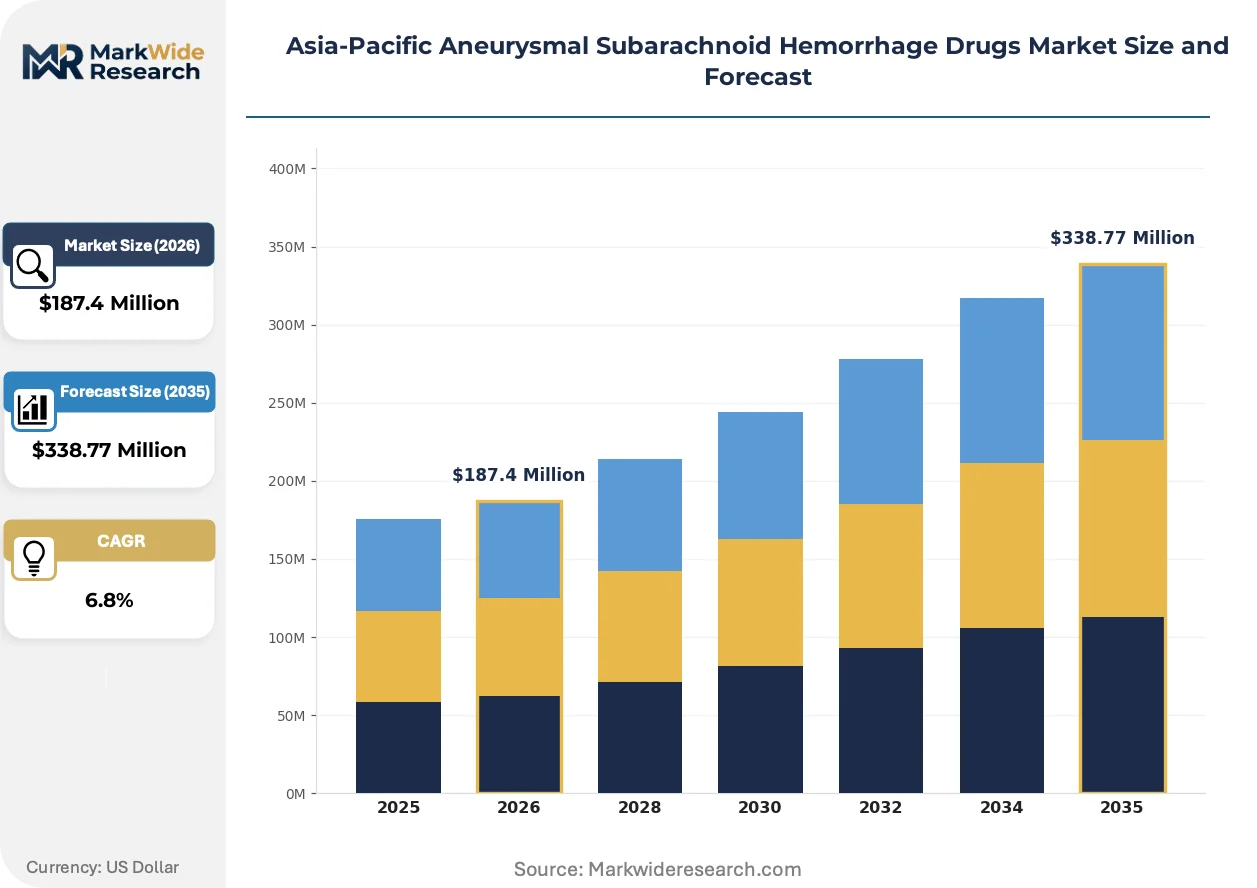
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiplatelet Agents, Anticoagulants, Vasospasm-Prophylaxis Drugs, Neuromodulators Administration Route: Intravenous, Oral, Intra-arterial, Subcutaneous Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Clinics End User: Hospitals, Rehabilitation Centers, Outpatient Facilities, Diagnostic Laboratories |
| Companies Covered | Teva Pharmaceutical Industries, Mylan, Takeda, Orexo, Arbor Pharmaceuticals, Pfizer, Johnson & Johnson, Pharmaxis, Sun Pharmaceutical Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market Trends and Innovations
Neurocritical care pharmaceutical delivery is separating into two distinct technical trajectories: precision intra-arterial systems for tertiary centers and streamlined intravenous protocols for rapid deployment. This technical divergence is reshaping R&D allocation and partnership strategies across the region.
Extended-release nimodipine formulations are bifurcating competitive positioning in Japan's stroke center networks. Tertiary hospitals in Tokyo and Osaka are adopting catheter-directed intra-arterial microinfusion systems that enable localized vasodilation with reduced systemic hypotension risk. This technology is bifurcating the market into high-complexity neuroradiology suites and standard neurointensive care wards, compressing investment returns for manufacturers without dual-platform capabilities.
Australia's TGA introduced enhanced stability testing requirements for temperature-sensitive neurocritical injectables in 2023, mandating real-world cold chain validation data alongside standard accelerated aging studies. This regulatory tightening has delayed registration timelines for several Asian-manufactured nimodipine candidates. Australian hospital pharmacies are responding by consolidating procurement around established suppliers with demonstrated logistics infrastructure.
Hospital pharmacy consortium purchasing is consolidating procurement authority in eastern China's provincial stroke networks. Single-source contracts covering multiple tertiary centers are displacing individual hospital formulary decisions, compressing supplier margins while extending volume commitments. This behavioral shift is most visible in Jiangsu and Zhejiang provinces, where provincial health commissions have centralized neurocritical drug tendering.
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market Segmentation
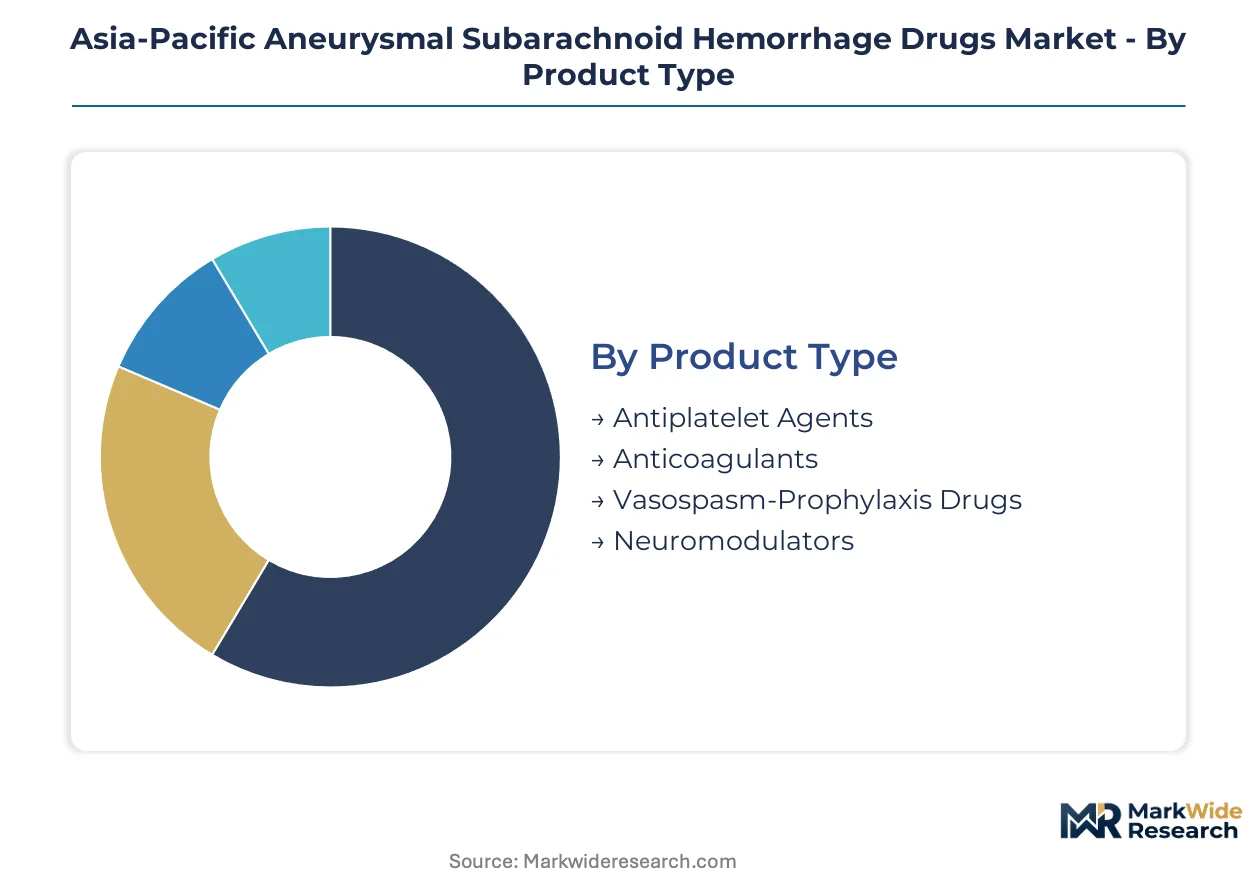
Segmentation in the Asia-Pacific aneurysmal subarachnoid hemorrhage drugs market reveals how procurement authority, clinical workflow integration, and regulatory compliance requirements concentrate value capture across distinct product and channel configurations. Understanding these divisions exposes where formulation investments and distribution partnerships yield sustainable access.
Product Type:
Margin pools concentrate in vasospasm-prophylaxis agents given their protocol-mandated status across accredited stroke centers, while antiplatelet and anticoagulant categories face pricing pressure from tender consolidation.
- Vasospasm-Prophylaxis Drugs:Intravenous nimodipine formulations dominate acute neurocritical protocols. Tertiary stroke centers in Tokyo, Osaka, and eastern China's Jiangsu province mandate documented prophylaxis administration, embedding these agents into reimbursement workflows and creating recurring revenue visibility for suppliers with cold chain logistics capabilities.
- Antiplatelet Agents:Post-intervention clot prevention drives sustained demand following aneurysm coiling or clipping procedures. Indian public health systems source cost-engineered generic supplies through centralized CDSCO-regulated tenders, compressing branded margins while expanding volume access.
- Anticoagulants:Controlled substance frameworks in China and India fragment import licensing pathways. These agents require specialized handling protocols in neurointensive settings where bleeding risk management is critical.
- Neuromodulators:Emerging category targeting secondary ischemia mitigation through targeted neural pathway modulation. Development pipelines focus on extended-release depot formulations to reduce dosing frequency in prolonged ICU stays.
Vasospasm-prophylaxis drugs hold installed capacity. Neuromodulators are rotating up the share rankings.
Administration Route:
Route selection determines reimbursement tier placement and capital equipment requirements, with intra-arterial delivery commanding premium positioning tied to neuroradiology suite investments.
- Intravenous:Standard-of-care delivery for nimodipine and adjunctive therapies across neurointensive wards. Hospital pharmacy control over ward-level dispensing creates formulary stickiness for suppliers with established sterile manufacturing footprints in Japan and Australia.
- Intra-arterial:Catheter-directed microinfusion enables localized vasodilation with reduced systemic hypotension risk. Eastern China's expanding catheterization laboratory capacity in Hangzhou and Nanjing tertiary hospitals drives demand pull for specialized delivery systems and trained neuroradiologist support.
- Oral:Transition-phase administration for stable patients moving from acute to subacute care. Bioequivalence testing divergence between PMDA and TGA stability requirements complicates regional formulation strategies.
- Subcutaneous:Limited current application in SAH protocols, primarily reserved for anticoagulant bridge therapy in specific comorbidity profiles.
Intravenous routes hold installed capacity. Intra-arterial delivery is rotating up the share rankings.
Distribution Channel:
Channel structure reflects stroke center accreditation concentration, with hospital pharmacy dominance in tertiary networks and emerging pre-hospital touchpoints disrupting traditional ward-based dispensing.
- Hospital Pharmacies:Direct-to-ward dispensing tied to stroke center certification standards controls bulk procurement volume. Australian and South Korean accreditation programs mandate documented pharmaceutical administration, embedding hospital pharmacy authority into quality metrics.
- Retail Pharmacies:Limited role in acute SAH management given the neurocritical care setting requirement. Post-discharge maintenance therapy for secondary prevention represents marginal opportunity.
- Online Pharmacies:Regulatory constraints on controlled substance distribution limit penetration. Cold chain requirements for temperature-sensitive neurocritical injectables create logistical barriers.
- Clinics:Ambulance-based nimodipine delivery systems are emerging as channel innovation, extending pharmaceutical touchpoints beyond traditional hospital pharmacy control in Australian and Japanese emergency medical services networks.
Hospital pharmacies hold installed capacity. Pre-hospital clinic-adjacent channels are rotating up the share rankings.
End User:
End-user concentration mirrors interventional neuroradiology capacity distribution, with tertiary hospitals capturing complex cases and rehabilitation centers extending pharmaceutical exposure into recovery phases.
- Hospitals:Tertiary stroke centers with catheterization laboratory infrastructure anchor demand. Provincial health commissions in China's Jiangsu and Zhejiang provinces have centralized neurocritical drug tendering, consolidating procurement authority.
- Rehabilitation Centers:Extended-care facilities manage secondary prevention and functional recovery protocols. These settings represent emerging formulary expansion opportunity as length-of-stay compression shifts patients earlier into subacute care.
- Outpatient Facilities:Limited acute SAH management role. Follow-up monitoring and medication adherence programs for high-risk vascular patients create niche pharmaceutical touchpoints.
- Diagnostic Laboratories:Ancillary role in biomarker-guided therapy selection and treatment response monitoring. Cerebral vasospasm risk stratification using circulating markers is gaining traction in Japanese neurocritical networks.
Hospitals hold installed capacity. Rehabilitation centers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese tertiary stroke centers exhibit lowest demand elasticity due to protocol-mandated vasospasm prophylaxis, while Indian public procurement channels show highest price sensitivity under centralized CDSCO tenders. Australian and South Korean markets sit mid-range, balancing reimbursement security against formulary consolidation pressures.
Japan
PMDA streamlined neurocritical drug approval pathways in response to aging-population hemorrhagic stroke burden. METI production-linked incentives support domestic sterile injectable manufacturing capacity expansion. Tokyo and Osaka tertiary hospitals anchor regional demand through catheter-directed intra-arterial microinfusion adoption.
China
Eastern provincial health commissions in Jiangsu and Zhejiang have centralized neurocritical drug tendering across multiple tertiary centers. NMPA maintains distinct import licensing frameworks for controlled anticoagulant substances, fragmenting cross-border supply continuity. Hangzhou and Nanjing hospitals are scaling catheterization laboratory capacity fastest.
Australia
TGA introduced enhanced stability testing requirements for temperature-sensitive neurocritical injectables in 2023, mandating real-world cold chain validation. Hospital pharmacy consortium purchasing is consolidating procurement authority in tertiary stroke networks. Melbourne and Sydney stroke center accreditation programs now require documented prophylaxis administration.
India
CDSCO-regulated centralized tenders for cost-engineered generic antiplatelet supplies compress branded margins while expanding volume access. The PLI scheme for pharmaceuticals offers cost-offset potential for domestic sterile injectable manufacturing investments. Maharashtra and Gujarat public health systems drive procurement concentration.
South Korea
MFDS stroke center certification standards mandate documented pharmaceutical administration, embedding hospital pharmacy authority into quality metrics. Neurointensive care specialist scarcity limits protocol adoption velocity outside Seoul Capital Area. Samsung Medical Center and Asan Medical Center anchor tertiary demand concentration.
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific aneurysmal subarachnoid hemorrhage drugs market. Large-scale injectable manufacturers leverage established sterile manufacturing footprints to sustain hospital pharmacy contracts, while niche neuromodulator developers pursue extended-release depot formulations. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with neurocritical portfolios, regional sterile manufacturing specialists, and cost-engineered generic suppliers targeting public procurement channels. Competitive moves center on catheterization laboratory partnership networks and cold chain logistics infrastructure investments.
Among Israel-based and Japan-based integrated pharmaceutical groups, Teva Pharmaceutical Industries and Takeda occupy anchor positions representing the vertically integrated archetype. Sun Pharmaceutical Industries exemplifies the cost-engineered generic supplier model targeting price-sensitive public health systems. These three entities collectively illustrate how geographic manufacturing concentration and regulatory relationship depth determine market access trajectories across divergent national frameworks.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Mylan |
| Takeda |
| Orexo |
| Arbor Pharmaceuticals |
| Pfizer |
| Johnson & Johnson |
| Pharmaxis |
| Sun Pharmaceutical Industries |
| Others |
Pricing and Supply Chain Analysis
Intra-arterial microinfusion systems replacing standard intravenous nimodipine in Japanese and eastern Chinese tertiary centers simultaneously concentrates supply geography around catheterization laboratory hubs and bifurcates pricing economics between premium neuroradiology suites and cost-compressed standard wards.
Pricing Analysis
After-sales service contracts covering neuroradiologist training and catheterization laboratory technical support drive lifetime value for intra-arterial delivery system manufacturers. Three-tier pricing structure across premium catheter-directed platforms, standard intravenous formulations, and economy generic supplies dominates the market. Price differentiation hinges on cold chain certification grade and stroke center accreditation tier. Cost compression in the economy generic tier is intensifying because Indian CDSCO tenders consolidate antiplatelet procurement. Public health systems in Maharashtra and Gujarat exhibit highest price sensitivity, while Japanese tertiary stroke centers show lowest elasticity due to protocol-mandated vasospasm prophylaxis.
Supply Chain Analysis
Port congestion on the Shanghai-Singapore trade lane elevates inbound logistics costs for temperature-sensitive neurocritical injectables sourced from European sterile manufacturing hubs. Finished dose formulation capacity clusters in Japan, Australia, and India, with active pharmaceutical ingredient supply anchored in Chinese and Indian chemical synthesis networks. Raw material dependencies include nimodipine API, sterile water for injection, and specialized catheter materials. Single-source vulnerability pervades the intra-arterial delivery device segment where Japanese and German component suppliers dominate. Distribution runs through hospital pharmacy direct-to-ward dispensing tied to stroke center certification standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where catheterization laboratory infrastructure interoperability determines supplier lock-in, with protocol-integrated pharmaceutical delivery systems functioning as the ecosystem anchor.
For Market Incumbents: Fortify hospital pharmacy contract stickiness through backward integration into cold chain logistics infrastructure across Australian and South Korean stroke networks. Deepen neuroradiologist training program deployment to defend against emerging pre-hospital administration route innovators. Prioritize TGA and PMDA bioequivalence certification investments to maintain formulary position against cost-engineered generic entrants. For New Entrants and Emerging Players: Anchor in Thailand and Vietnam tertiary neurocritical unit buildouts where established formulary relationships remain absent. Target the rehabilitation center segment for secondary prevention formulary expansion as length-of-stay compression accelerates. Pursue ambulance-based nimodipine delivery system partnerships with Japanese and Australian emergency medical services as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional sterile manufacturing specialists possessing established PMDA and TGA relationships but limited catheterization laboratory partnership networks. Long-term viability over the extended window rests on capturing protocol-integrated positioning before provincial tender consolidation matures. Watch for MFDS stroke center certification mandate expansion beyond Seoul Capital Area as the inflection signal indicating addressable market widening.| Strategic Initiative | Industry Significance |
|---|---|
| Catheterization Laboratory Partnership Network | Locks in intra-arterial delivery system placement across eastern China's Jiangsu and Zhejiang tertiary hospitals. |
| Cold Chain Logistics Infrastructure Investment | Enables TGA-compliant temperature-sensitive injectable distribution throughout Australian stroke center networks. |
| Neuroradiologist Training Program Deployment | Addresses specialist scarcity limiting protocol adoption velocity in South Korean and Southeast Asian markets. |
| Pre-Hospital Administration Route Development | Extends pharmaceutical touchpoints beyond hospital pharmacy control in Japanese emergency medical services. |
| Provincial Tender Consolidation Alignment | Positions suppliers for centralized neurocritical drug procurement in China's eastern provincial health commissions. |
Research Methodology
Cross-validation between hospital pharmacy procurement records and regulatory filing databases anchors the qualitative findings in observable transaction patterns. Primary interviews with neurocritical care physicians, hospital formulary directors, sterile manufacturing plant managers, and neuroradiology department heads combined with secondary validation against PMDA approval summaries, TGA stability testing guidelines, CDSCO tender documents, and ClinicalTrials.gov enrollment data. Bottom-up demand modeling from stroke center accreditation counts and top-down market sizing from pharmaceutical trade flows establish analytical triangulation.
Sensitivity analysis around catheterization laboratory capacity expansion rates and provincial tender consolidation timelines shapes the forecast framework. Segmentation dimensions modeled include administration route, distribution channel, end-user facility type, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base growth in accredited stroke centers and protocol penetration assumptions. Forecast inputs incorporate neurointensive care specialist supply constraints and cold chain infrastructure investment trajectories.
Material uncertainties — PMDA approval pathway modifications, NMPA import licensing shifts, and pre-hospital administration route regulatory classification — sit outside the modeled envelope. Forecasts reflect documented assumptions about stroke center accreditation velocity and formulary integration timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Oral Anticoagulant Market