
 Hog Production and Pork Market | 2026-2036
Hog Production and Pork Market Size, Share, and Industry Trends Forecast 2026-2036
Hog Production and Pork Market Foresight
Genetics-as-a-service and subscription-based breeding programs is decoupling hog production from pure commodity cycles, allowing producers to monetize intellectual property independently of live animal sales. Smithfield Foods leverages vertical integration from feed milling through processing to control cost volatility across its integrated network. Muyuan Foodstuff anchors massive sow herd expansion through automated facility deployment, sustaining unit economics at scale that smaller operators cannot replicate. Wens Group differentiates through contract farming density across southern Chinese provinces, controlling farmer loyalty via guaranteed offtake pricing.
Hog production and pork encompasses the breeding, raising, slaughtering, and processing of swine into meat products with carcass yields typically ranging from 70-75% lean meat recovery after rendering and trimming. The activity spans genetic selection for feed conversion ratios, biosecurity-controlled confinement or alternative housing systems, and chilled or frozen distribution to downstream buyers. Fresh pork and processed pork categories dominate value capture, with processed pork commanding margin premiums through smoking, curing, and emulsification steps that extend shelf life and brand differentiation. Food service and retail distribution channels structure pricing power differently, as institutional buyers negotiate volume contracts while retail slots reward packaged brand recognition and cold-chain reliability.
USDA grading standards and FDA hazard analysis protocols govern product safety and labeling in the United States, while China's MEE enforces livestock waste discharge permits and manure utilization quotas that constrain facility siting. The EU Green Deal's Farm to Fork strategy pressures import access through sustainability certification requirements that non-European exporters must satisfy. Stakeholders must monitor how carbon accounting rules and antimicrobial residue limits reshape competitive access across major import jurisdictions.
Market Dynamics
China's dual carbon goals and livestock waste discharge mandates under MEE authority are forcing facility consolidation and capital-intensive environmental retrofitting across East Asian production zones.
Growth Catalysts
- Protein Consumption Surge:Vietnam and Indonesia are expanding per-capita pork intake as urban middle-class diets diversify toward animal proteins.
- Genetic Subscription Models:Artificial insemination and genomic selection platforms are decoupling breeding value from commodity hog cycles.
- EU Green Deal Certification:Sustainability import requirements are creating premium market access for compliant exporters.
Market Restraints
- Feed Cost Volatility:Soybean and corn price swings destabilize unit economics for non-integrated producers lacking captive grain sourcing.
- Supply Concentration Risk:Sow herd ownership clusters among automated mega-facilities in Henan and Sichuan provinces.
- Antimicrobial Residue Limits:FDA and EU veterinary drug standards restrict treatment protocols and lengthen withdrawal periods.
Strategic Opportunities
- Philippines Import Gap:Domestic production deficits are opening channels for chilled pork shipments from Vietnam and Thailand.
- Cellular Protein Convergence:Cultivated pork R&D is attracting venture capital alongside traditional genetics investment.
- Manure-to-Biogas Incentives:China's carbon trading scheme rewards methane capture installations at concentrated feeding operations.
Industry Challenges
- Veterinary Epidemiology Talent Scarcity:African swine fever surveillance and rapid response teams remain understaffed across provincial veterinary networks.
- Biosecurity Capex Burden:Air filtration, shower-in protocols, and all-in-all-out facility designs demand capital deployment that smaller contract farmers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hog Production and Pork Market |
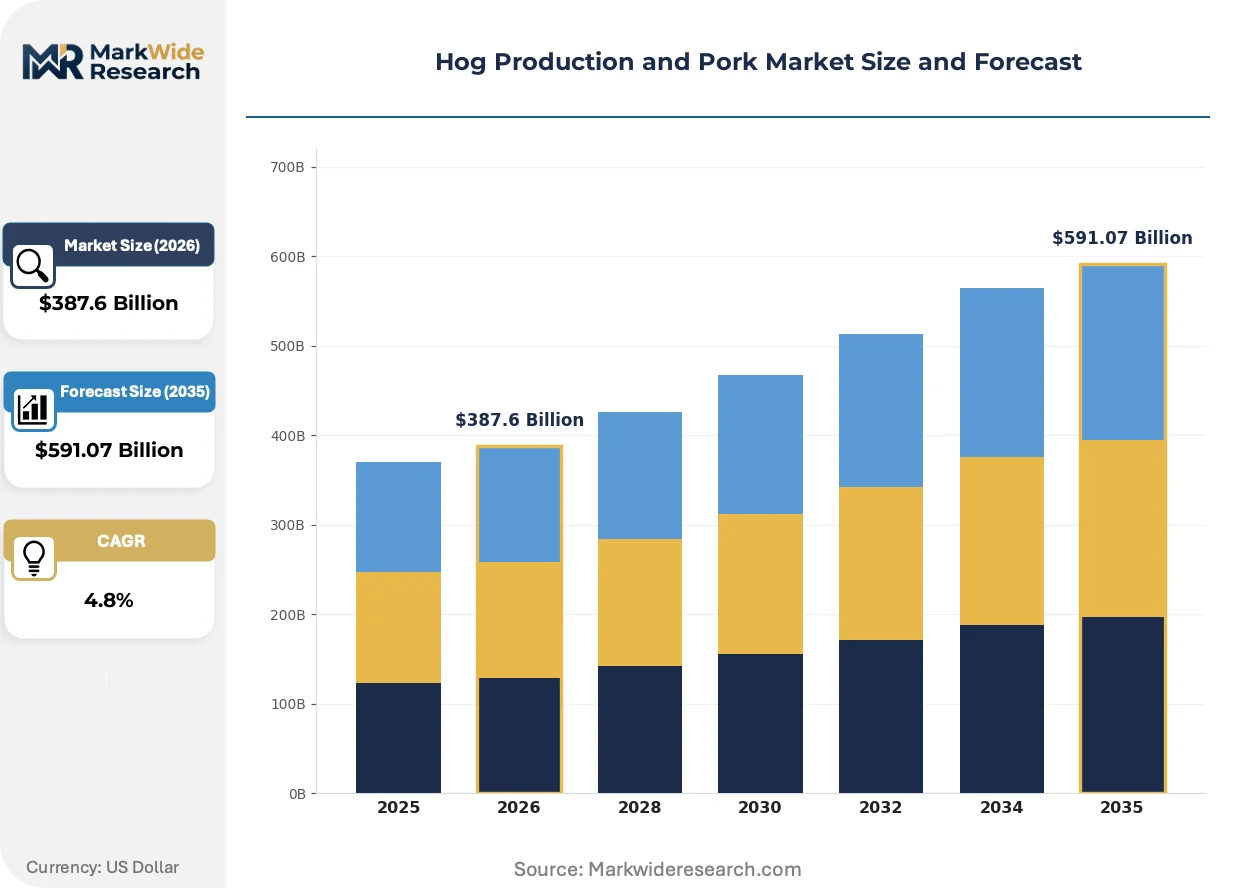
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Conventional, Organic, Free-Range, Pasture-Raised Product Type: Fresh Pork, Processed Pork, Sausages, Cured Meats Distribution Channel: Wholesale, Retail, Online, Food Service End User: Households, Restaurants, Food Manufacturers, Caterers |
| Companies Covered | Muyuan Foodstuff, Wens Group, Smithfield Foods, Zhengbang Group, New Hope Group, CP Foods, Techbank Food Co., Ltd, Triumph Foods, Iowa Select Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hog Production and Pork Market Shifts & Advancements
Automation and environmental compliance are converging to reshape facility economics, procurement relationships, and product format preferences across the value chain.
Precision livestock monitoring using computer vision and environmental sensors is automating individual animal health tracking and feed optimization. Large integrated operators in China and Vietnam are deploying these systems at sow farm scale, compressing labor requirements and mortality variance. The technology is automating early disease detection protocols that previously relied on manual pen checks.
China's MEE livestock waste discharge permits and manure utilization quotas are tightening facility siting and expansion permissions. Producers must now secure nutrient management plans and biogas infrastructure commitments before construction approval. Smallholder contract networks in Guangdong and Fujian face the steepest compliance cost escalation.
Quick-service restaurant chains are consolidating procurement through direct processor relationships, bypassing traditional wholesale market intermediaries. Yum China and regional Vietnamese operators now negotiate volume contracts specifying carcass cut specifications and cold-chain traceability. This channel compression is most advanced in tier-one Chinese cities where retail consolidation accelerates.
Hog Production and Pork Market Segmentation
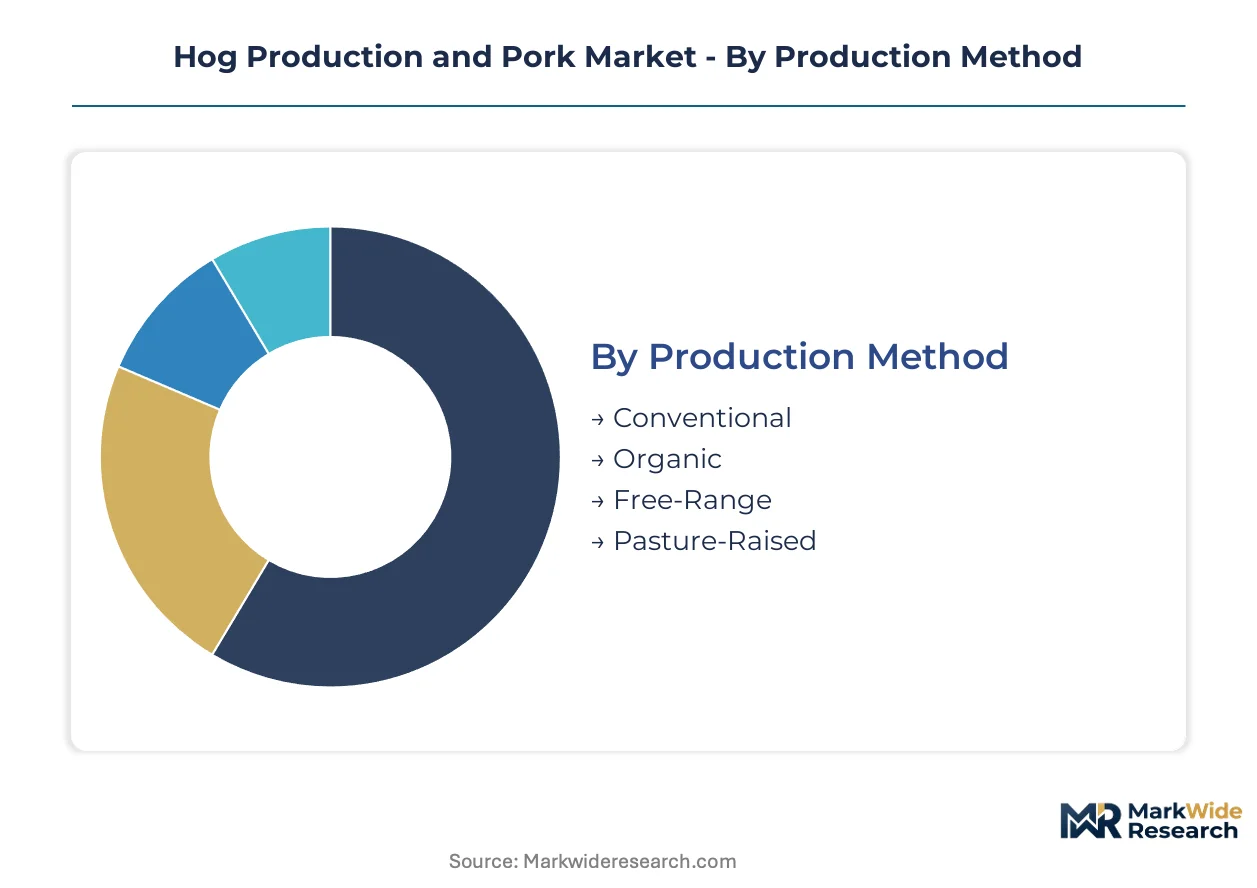
Segmentation in hog production and pork reveals how value capture splits between commodity live animal sales and differentiated processed formats. Production method and distribution channel choices determine margin architecture, biosecurity compliance burden, and geographic market access.
Production Method:
Standardization dominates at scale while niche methods command certification premiums in affluent urban markets.
- Conventional:Climate-controlled confinement systems with automated feeding and ventilation dominate sow herd economics in Henan and Sichuan provinces. China's MEE discharge permits favor these capital-intensive designs for manure-to-biogas integration. Most installed capacity flows through Conventional. Expansion is steepest in Pasture-Raised.
- Organic:Feed ration restrictions and outdoor access mandates extend finishing periods by 20-30% but unlock EU Green Deal import eligibility and domestic premium retail slots. Certification costs and land requirements limit organic conversion to established cooperatives with existing pasture access.
- Free-Range:Outdoor pen rotation with shelter access balances animal welfare marketing claims against predation and weather mortality risks. Vietnamese producers near Ho Chi Minh City deploy this method for restaurant direct-supply contracts.
- Pasture-Raised:Continuous outdoor foraging with supplemental feed meets emerging sustainability audit standards for quick-service restaurant procurement. Smaller litter sizes and slower growth rates restrict this segment to specialty butcher channels and direct-to-consumer platforms.
Conventional systems absorb the majority of capital deployment. Pasture-Raised is climbing the fastest as ESG-linked procurement policies spread.
Product Type:
Fresh formats anchor volume while processing steps multiply margin extraction opportunities.
- Fresh Pork:Chilled primal cuts and carcass quarters move through wholesale markets and processor direct contracts with minimal value-add. Cold-chain reliability determines pricing power in tier-one Chinese cities where retail consolidation accelerates.
- Processed Pork:Smoking, curing, and emulsification extend shelf life and enable brand differentiation in packaged retail. This segment captures margin premiums through recipe proprietary positioning and convenience positioning for time-constrained households.
- Sausages:Ground and emulsified products with casing or skinless formats serve both retail packaged slots and food service portion-control requirements. Regional flavor profiles dominate—Cantonese sweet varieties versus Vietnamese fermented styles.
- Cured Meats:Dry-cured hams and bacon strips require extended aging infrastructure and humidity-controlled storage. European import standards and domestic luxury positioning restrict this segment to established processors with aging facility investments.
Fresh Pork channels the largest slaughter volumes. Processed Pork is gaining share fastest as quick-service restaurants consolidate procurement through specification contracts.
Distribution Channel:
Channel compression is eliminating traditional intermediaries in tier-one urban markets.
- Wholesale:Live animal auctions and carcass markets remain dominant in provincial production zones but face margin compression from processor direct contracting. Biosecurity protocols now restrict physical market access in ASF-affected regions.
- Retail:Supermarket chilled counters and packaged meat sections reward cold-chain reliability and branded product recognition. Yum China and regional Vietnamese operators now bypass wholesale layers entirely.
- Online:E-commerce platforms and subscription meat boxes surged during mobility restrictions and retain stickiness among urban households seeking traceability claims. Same-day chilled delivery requires micro-fulfillment infrastructure investment.
- Food Service:Direct processor relationships with restaurant chains and institutional caterers specify cut specifications, portion consistency, and origin documentation. This channel compresses traditional wholesale layers most aggressively.
Wholesale retains volume dominance in production-adjacent geographies. Food Service is expanding most quickly as procurement centralization accelerates.
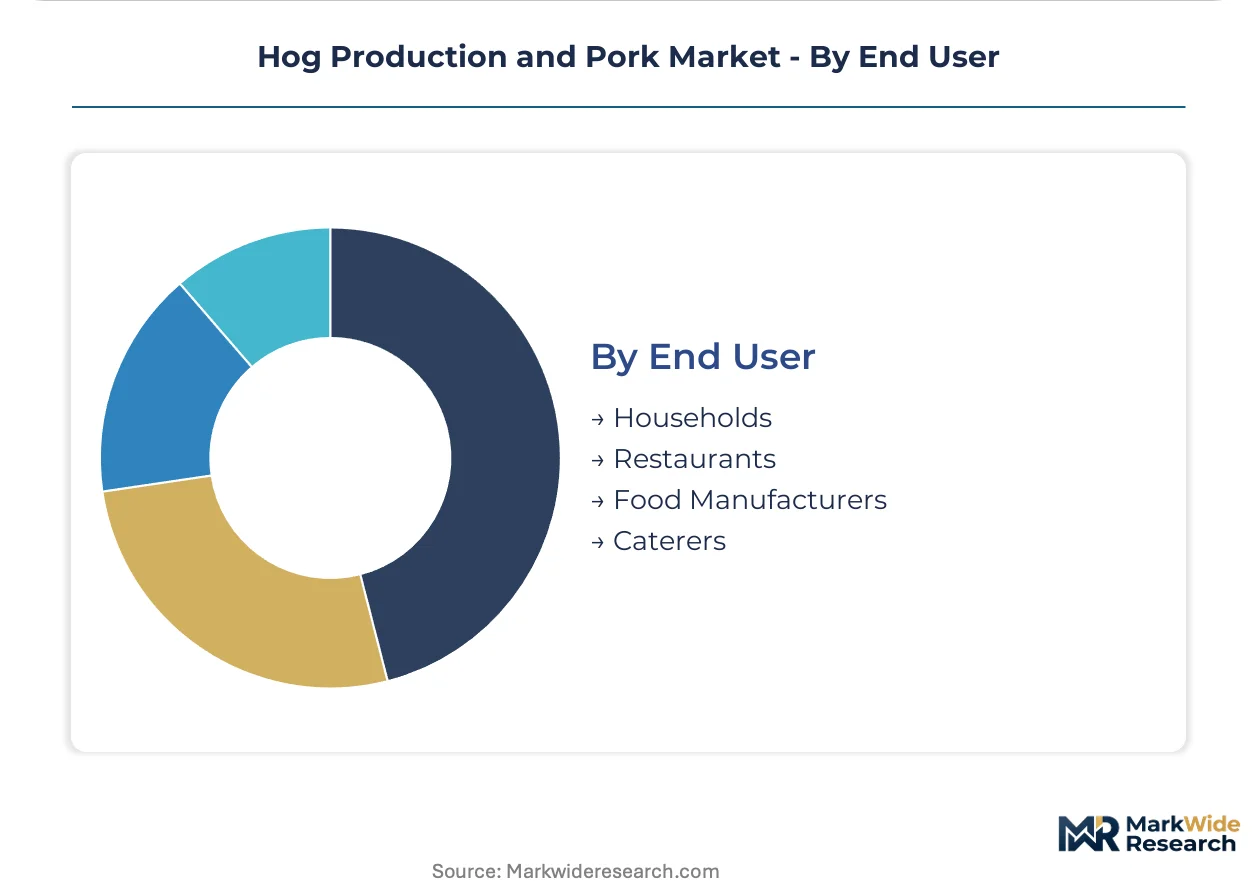
End User:
User type determines specification complexity, contract structure, and price negotiation leverage.
- Households:Retail and online purchases drive demand for convenience formats, portion sizing, and cooking instruction labeling. Urban middle-class diversification toward animal proteins sustains per-capita intake growth in Vietnam and Indonesia.
- Restaurants:Quick-service chains and independent operators negotiate volume contracts with carcass cut specifications and cold-chain traceability requirements. Direct processor relationships bypass traditional wholesale intermediaries.
- Food Manufacturers:Industrial buyers of primal cuts and trim for further processing into sausages, cured products, and ready-meal ingredients. Specifications center on lean-to-fat ratios and consistent supply scheduling.
- Caterers:Institutional feeding operations for schools, hospitals, and corporate facilities prioritize cost control through frozen product acceptance and long-term supply agreements. Volume concentration enables price negotiation leverage absent in fragmented retail.
Households consume the largest absolute volumes. Restaurants are expanding procurement fastest as chain consolidation and direct contracting spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as capital migrates toward jurisdictions with lower compliance costs or faster permitting timelines. Producers are relocating sow herds to evade stricter manure discharge quotas and carbon accounting rules.
China
Henan and Sichuan provinces concentrate automated mega-facilities serving domestic protein demand. MEE livestock waste discharge permits and manure utilization quotas constrain facility siting, forcing consolidation. Guangdong contract farmers face steepest compliance cost escalation as biogas infrastructure mandates spread.
Vietnam
Urban middle-class diet diversification drives per-capita pork intake expansion near Ho Chi Minh City. National biosecurity protocols restrict physical market access in African swine fever-affected regions. Mekong Delta producers deploy free-range methods for restaurant direct-supply contracts.
United States
USDA grading standards and FDA hazard analysis protocols govern product safety and labeling across interstate commerce. Iowa Select Farms and Triumph Foods anchor sow herd concentration in Corn Belt states with captive grain sourcing advantages. Vertical integration from feed milling through processing controls cost volatility.
Thailand
Chilled pork export capacity targets Philippines import gaps as domestic production deficits widen. National agricultural regulators enforce veterinary drug residue limits that align with EU import standards. Central Plains processing clusters specialize in quick-service restaurant specification contracts.
Brazil
São Paulo and Minas Gerais states balance pasture access against scale economics for export-oriented production. ANVISA veterinary drug standards restrict treatment protocols and lengthen withdrawal periods. Southern cooperatives pursue EU Green Deal sustainability certification for premium market access.
Hog Production and Pork Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators commanding procurement leverage and niche players capturing certification premiums. Structure tiers between automated mega-facilities and fragmented contract farming networks. Three archetypes dominate: vertical integrators controlling feed-to-retail value chains, genetics-as-a-service platforms monetizing intellectual property, and contract farming coordinators securing farmer loyalty through guaranteed offtake. Competitive moves center on facility automation deployment and backward integration into captive feed grain sourcing.
Among China-based integrated producers, Muyuan Foodstuff and Wens Group exemplify scale-driven archetypes with automated facility deployment and contract farming density respectively. Smithfield Foods anchors the North American vertical integration model. These three occupy positions that smaller operators cannot replicate due to capital intensity and biosecurity compliance burdens.
| Leading Market Players |
|---|
| Muyuan Foodstuff |
| Wens Group |
| Smithfield Foods |
| Zhengbang Group |
| New Hope Group |
| CP Foods |
| Techbank Food Co., Ltd |
| Triumph Foods |
| Iowa Select Farms |
| Others |
Supply & Pricing Matrix
Captive feed grain sourcing anchors both supply security and margin control for integrated operators across Henan and Sichuan provinces. This backward integration into corn and soybean procurement buffers unit economics against commodity volatility while concentrating pricing power among mega-facility owners.
Pricing Analysis
Direct-to-processor contracting compresses traditional wholesale margin layers as quick-service chains negotiate volume specifications with Smithfield Foods and Muyuan Foodstuff. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain reliability. Cost compression in standard-tier fresh pork intensifies because retail consolidation accelerates price transparency. Food manufacturers exhibit highest price sensitivity due to lean-to-fat ratio specifications and scheduling rigidity, while quick-service chains absorb premiums for traceability documentation.
Supply Chain Analysis
EU Green Deal sustainability certification gates market access for Brazilian and Thai exporters seeking premium positioning. Supply concentrates in China, the United States, and Vietnam, with sow herd ownership clustering around automated facilities in Henan and Iowa. Feed ration formulation draws from soybean, corn, and amino acid premix dependencies. Single-source vulnerability runs through genetic stock supply from elite nucleus herds. Distribution runs through processor-direct relationships that bypass traditional wholesale auctions in tier-one Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion rests on manure-to-biogas infrastructure deployment that converts regulatory compliance cost into carbon credit revenue. Premium-tier shift toward EU Green Deal-certified organic production captures import eligibility and domestic urban retail slots.
For Market Incumbents: Cement biosecurity protocol standardization across contract farming networks to lock in farmer loyalty against ASF recurrence threats. Deepen backward integration into captive feed milling that controls cost volatility when soybean prices spike. Expand automated facility deployment in Sichuan and Henan where MEE discharge permits favor capital-intensive designs with biogas integration. For New Entrants and Emerging Players: China's MEE livestock waste discharge mandates open a window for biogas infrastructure specialists to partner with smallholder networks facing steepest compliance cost escalation. Target Philippines import gaps through chilled pork shipment channels from Vietnam and Thailand. Pursue pasture-raised certification for quick-service restaurant ESG-linked procurement policies spreading across Ho Chi Minh City and Jakarta. For Investors and Strategic Acquirers: Consolidation pressure builds where biosecurity Capex burdens exceed contract farmer financing capacity across Guangdong and Fujian provinces. Viable acquisition targets cluster among mid-scale processors with aging facility investments and EU export certification. Watch ASF surveillance protocol standardization across provincial veterinary networks as inflection indicator for operational risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Manure-to-Biogas Infrastructure Deployment | MEE discharge permit compliance converts into carbon credit revenue under China's emissions trading scheme. |
| Genetic Subscription Platform Launch | Artificial insemination services decouple breeding value from commodity hog price cycles for recurring revenue. |
| Processor-Direct Contracting Expansion | Yum China and regional Vietnamese operators bypass wholesale layers entirely for specification control. |
| EU Green Deal Certification Investment | Southern Brazilian cooperatives unlock premium market access through sustainability audit compliance. |
| Precision Livestock Monitoring Scale-Up | Computer vision deployment at sow farm scale compresses labor requirements and mortality variance. |
Research Methodology
Multiple input streams — primary interviews with sow farm operations directors, veterinary epidemiologists, and quick-service restaurant procurement heads; secondary validation through USDA livestock reports, China MEE discharge permit databases, and EU Green Deal certification registries; plus customs trade data and SEC processor filings — were reconciled through bottom-up facility capacity modeling and top-down protein consumption trend analysis.
Data-stream reconciliation across production method, product type, distribution channel, and end user dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from facility expansion pipelines, per-capita protein intake elasticity estimates, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated ASF surveillance protocol coverage rates and biogas infrastructure deployment timelines.
Revisions become necessary when MEE discharge permit enforcement intensity shifts, ASF recurrence triggers provincial movement bans, or feed grain price volatility exceeds historical bands. Deviation in EU Green Deal certification timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Livestock Dewormers Market
Livestock Management
Poultry Health Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Layer Breeding System Market
Livestock Management
Bird Feeder Market
Livestock Management
South America Swine Feed Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Animal Identification Market
Livestock Management
China Swine Feed Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
North America Swine Feed Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Wagyu Beef Market