
 US Quantum Computing Market | 2026-2036
US Quantum Computing Market Size, Share, and Industry Trends Forecast 2026-2036
US Quantum Computing Market Insights
Superconducting qubit architectures is fragmenting across competing hardware approaches, forcing vendors to place divergent bets on error correction and scalability. IBM leverages its Quantum Network to sustain cloud access for enterprise developers. IonQ anchors its position through trapped-ion fidelity advantages in commercial deployments. Google competes on quantum supremacy demonstrations while extending its AI integration roadmap.
Quantum computing harnesses superposition and entanglement to process information using qubits operating at millikelvin temperatures in dilution refrigerators, enabling exponential speedup for specific combinatorial problems. Optimization and cryptography applications currently dominate enterprise pilot budgets, while machine learning represents the fastest-growing segment as tensor network methods mature. Cloud-based deployment leads adoption among financial services and healthcare end users seeking low-capital entry points, though on-premises systems retain priority for aerospace and defense clients with classified workloads.
NIST shapes demand through post-quantum cryptography standardization timelines, while the Department of Energy funds national quantum information science research centers. The Department of Commerce export controls under the Bureau of Industry and Security restrict certain quantum technology transfers, tightening market access for foreign component suppliers. Stakeholders must monitor which hardware modality achieves logical qubit thresholds first, as this technical milestone will determine procurement consolidation across federal and commercial buyers.
Market Dynamics
Superconducting qubit vendors face mounting pressure from trapped-ion alternatives as error-correction roadmaps diverge, fragmenting federal procurement criteria and forcing buyers to hedge across hardware modalities.
Growth Catalysts
- NIST Post-Quantum Cryptography Standards:Federal migration timelines for encryption algorithms are accelerating defense and financial sector pilot deployments. Procurement offices now embed quantum-readiness clauses into IT modernization contracts.
- Department of Energy National QIS Research Centers:Five hub facilities spanning Maryland, Colorado, and Illinois channel infrastructure investment toward fault-tolerant system development. These centers consolidate talent pipelines and shared dilution refrigerator capacity.
- Classified Aerospace Workloads:Air Force Research Laboratory and Space Force requirements for satellite-to-ground quantum key distribution are pulling on-premises ion trap systems into secure facilities.
Market Restraints
- Helium-3 Supply Concentration:Dilution refrigerator cooling dependence on Russian and Qatari helium isotopes exposes system manufacturers to export disruption and price volatility.
- Logical Qubit Threshold Uncertainty:No hardware modality has demonstrated error-corrected logical qubits at scale, leaving procurement committees without standardization benchmarks for vendor selection.
- ITAR Classification Friction:State Department export controls on quantum control electronics delay international component sourcing and complicate foreign national researcher access.
Strategic Opportunities
- Texas and Arizona Quantum Manufacturing Clusters:Underdeveloped cryogenic foundry capacity in these states offers greenfield sites for captive dilution refrigerator production and qubit fabrication integration.
- Tensor Network Machine Learning Convergence:Hybrid classical-quantum algorithms for pharmaceutical molecular simulation represent untapped commercial demand beyond optimization pilots.
- CHIPS and Science Act Quantum Provisions:Domestic semiconductor packaging incentives can subsidize control chip fabrication for trapped-ion systems, reducing import dependence.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Millikelvin system design expertise concentrates at national laboratories, constraining private sector hiring for commercial scale-up.
- Legacy Cryptography Migration Complexity:Federal agencies face decade-long hardware and software inventory overhauls to implement NIST-approved post-quantum algorithms.
- Qubit Interoperability Standards Gap:Absence of IEEE or ANSI protocols for cross-platform algorithm portability locks enterprise developers into single-vendor cloud environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Quantum Computing Market |
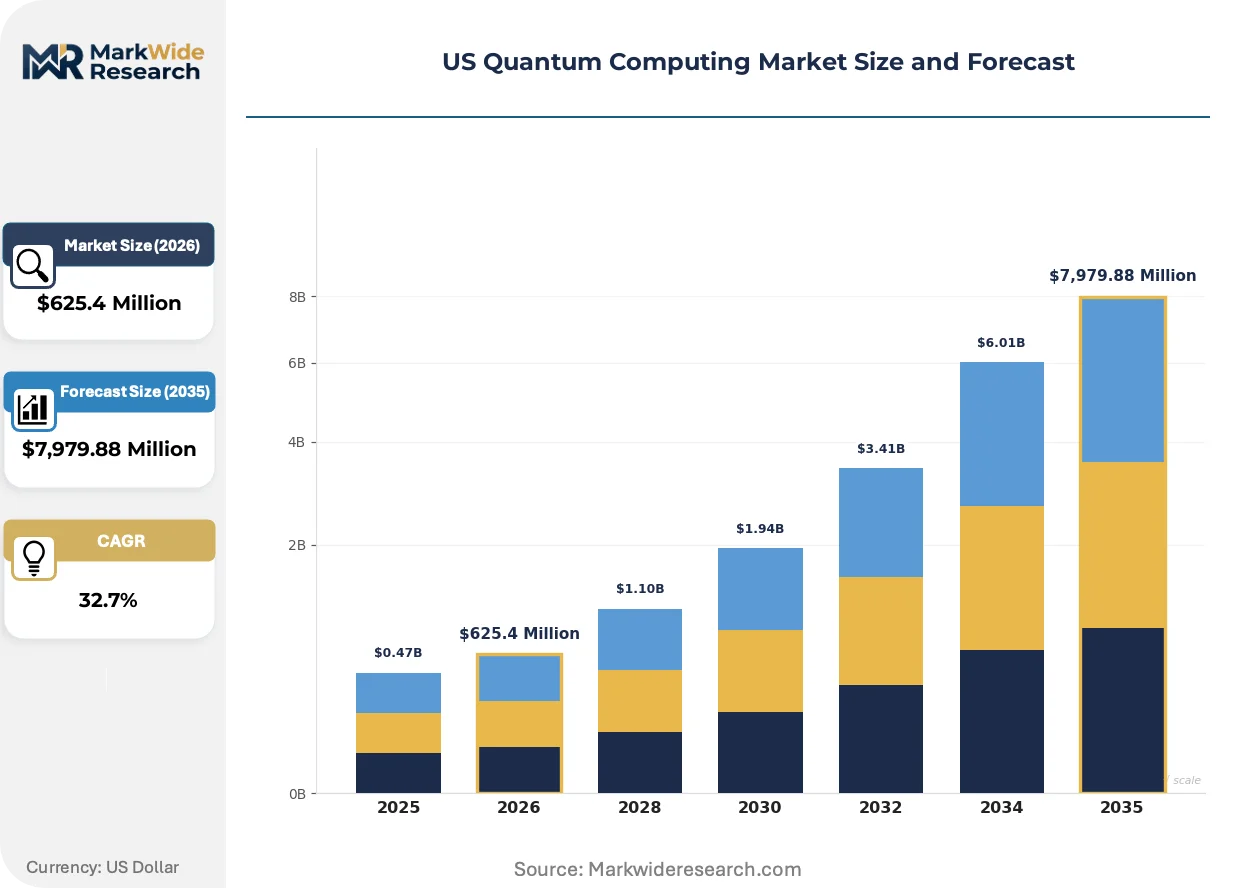
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $7,979.88 Million |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Quantum Simulation, Optimization, Cryptography, Machine Learning End User: Healthcare, Automotive, Aerospace, Financial Services Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud Technology: Superconducting Qubits, Trapped Ions, Topological Qubits, Photonic Quantum Computing |
| Companies Covered | IBM, IonQ, Google, Microsoft, Rigetti Computing, Quantinuum, D-Wave Systems, Intel, QuEra Computing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Quantum Computing Market Trends and Innovations
Hardware roadmaps are diverging faster than error-correction benchmarks can stabilize, compressing vendor consolidation timelines and forcing buyers into multi-modal hedging strategies.
Photonic interconnect architectures for modular quantum processors are rendering obsolete monolithic superconducting chip designs that dominated early cloud deployments. Defense contractors in Maryland and California are piloting photonic links between cryogenic modules to reduce control wiring density. This shift compresses vendor R&D budgets toward hybrid electro-optical systems.
NIST's 2024 post-quantum cryptography standardization timeline is mandating algorithm inventory audits across federal civilian agencies. Contractors must now certify quantum-resistant encryption in existing network hardware before new procurement approvals. Financial services firms in New York and Chicago are replicating these audit protocols ahead of anticipated SEC guidance.
Cloud access models are displacing capital-intensive on-premises installations for commercial pilot programs. Pharmaceutical and materials science teams now rent superconducting and trapped-ion capacity through hourly billing rather than facility construction. This pattern concentrates most visible in Boston and San Francisco metropolitan research corridors where real estate constraints favor outsourced infrastructure.
US Quantum Computing Market Segmentation
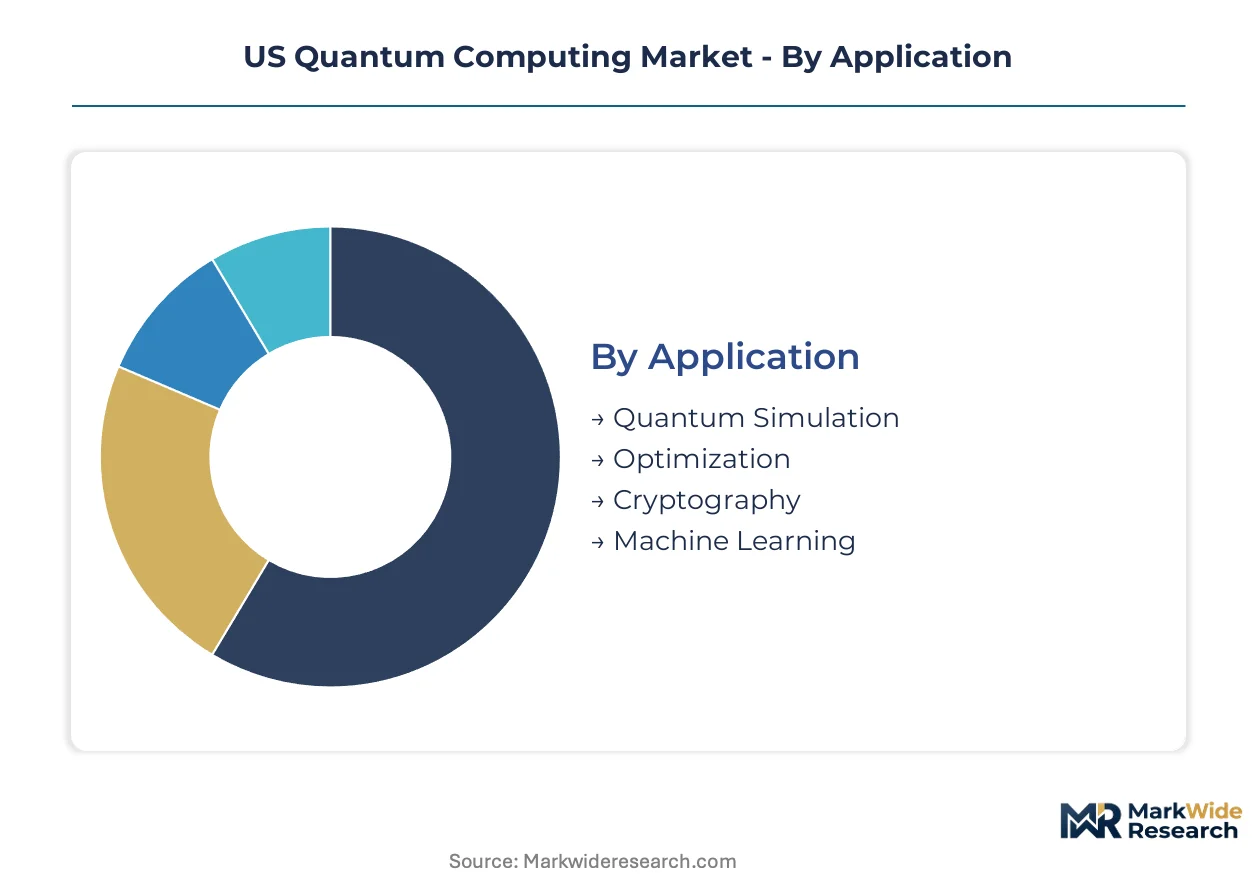
Quantum computing procurement patterns diverge sharply across application workloads and deployment constraints. Federal buyers prioritize on-premises systems for classified environments while commercial pilots favor cloud elasticity. Hardware modality selection locks customers into vendor-specific error-correction roadmaps with decade-long implications.
Application:
Mature optimization workloads anchor current revenue while emerging machine learning applications reshape vendor R&D priorities.
- Quantum Simulation:Molecular modeling for pharmaceutical discovery and materials science consumes the largest share of cloud-accessible qubit hours. National laboratories in Colorado and California operate dedicated superconducting systems for catalyst design and battery electrolyte research.
- Optimization:Financial services firms in Chicago and New York deploy hybrid algorithms for portfolio risk analysis and derivative pricing. These workloads tolerate higher error rates, making them compatible with current noisy intermediate-scale quantum hardware.
- Cryptography:NIST post-quantum migration timelines are accelerating federal demand for quantum key distribution pilots and cryptographic testing environments.
- Machine Learning:Tensor network methods for pattern recognition represent the steepest expansion trajectory among enterprise pilot budgets.
Optimization handles the majority of throughput; machine learning is the fastest mover on share.
End User:
Defense-aerospace buyers command premium pricing for air-gapped systems while healthcare and automotive sectors pursue lower-cost cloud entry points.
- Healthcare:Pharmaceutical companies in Boston and San Francisco metropolitan corridors rent trapped-ion capacity for protein folding simulation. Real estate constraints and capital avoidance drive cloud preference over facility construction.
- Automotive:Battery manufacturers and autonomous driving developers use quantum optimization for supply chain routing and sensor fusion calibration. These teams prioritize API-accessible platforms with classical integration tools.
- Aerospace:Air Force Research Laboratory and Space Force requirements for satellite-to-ground quantum communication mandate on-premises ion trap installations in secure Maryland and Colorado facilities.
- Financial Services:Banks and hedge funds in Chicago and New York dominate hourly billing for cloud-based variational algorithms. SEC anticipation of quantum-resistant disclosure rules is accelerating compliance-related procurement.
Financial services generates the highest cloud-access volume; aerospace commands the steepest per-qubit pricing premium.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from operational-expense cloud models favored by mid-market entrants.
- On-Premises:Classified defense workloads and intellectual property-sensitive pharmaceutical discovery require air-gapped dilution refrigerator facilities. These installations demand specialized cryogenic engineering talent concentrated at national laboratories.
- Cloud-Based:Hourly billing models dominate Boston and San Francisco research corridors where real estate scarcity prevents facility construction. IBM Quantum Network and competing platforms offer API access without capital commitment.
- Hybrid:Variational algorithms split computation between classical preprocessors and quantum co-processors. This architecture accommodates current hardware limitations while preserving upgrade paths.
- Private Cloud:Consortia of financial institutions and healthcare systems lease dedicated rack capacity within vendor facilities. This model satisfies data sovereignty requirements without full facility ownership.
Cloud-based deployment captures the broadest user base; private cloud is climbing the fastest among compliance-sensitive sectors.
Technology:
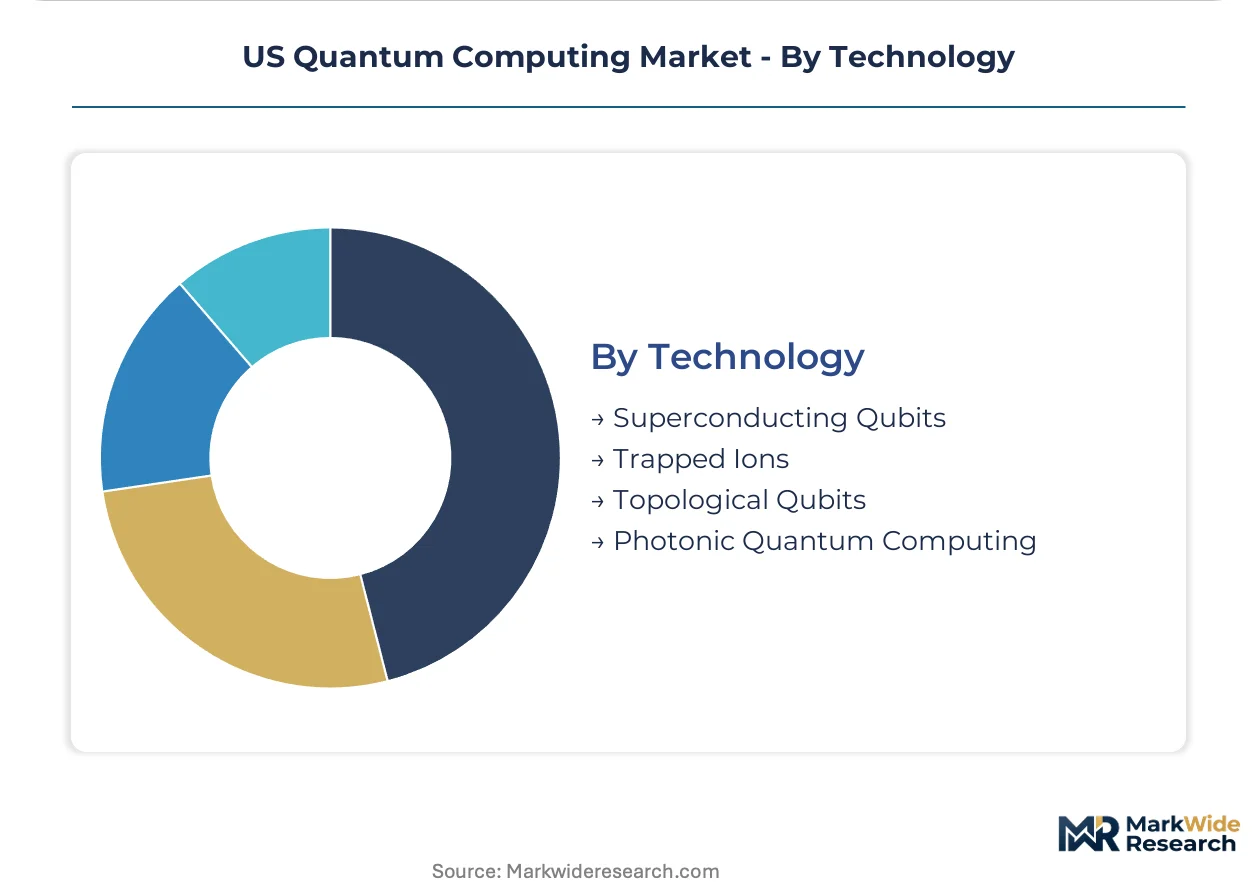
Supply concentration in superconducting modalities faces disruption from trapped-ion fidelity advantages and photonic interconnect advances.
- Superconducting Qubits:Transmon and fluxonium architectures operate in millikelvin dilution refrigerators. These systems dominate current cloud offerings through established foundry partnerships and control electronics supply chains.
- Trapped Ions:Ytterbium and calcium ion systems achieve higher gate fidelity with slower operation speeds. Maryland and Colorado defense facilities prioritize these platforms for quantum networking and cryptographic applications.
- Topological Qubits:Microsoft and affiliated researchers pursue Majorana zero-mode devices for intrinsic error protection. No commercial system has yet demonstrated scalable logical qubit operation.
- Photonic Quantum Computing:Silicon photonic interconnects enable modular processor architectures that reduce control wiring density. Defense contractors in California are piloting cryogenic optical links between superconducting modules.
Superconducting qubits handle the majority of installed capacity; photonic quantum computing is gaining share fastest among next-generation procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision cryogenic engineering components to US quantum computing facilities, establishing a critical trade corridor for dilution refrigerator manufacturing. This transatlantic supply relationship shapes regional investment patterns across American quantum hubs.
California
Defense contractors in Los Angeles and San Diego counties pilot photonic interconnects between cryogenic quantum modules. The Department of Commerce Bureau of Industry and Security export controls on quantum control electronics complicate component sourcing for these facilities. Google and affiliated research teams in Santa Barbara advance superconducting qubit architectures through cloud-accessible platforms.
Maryland
National Security Agency and Johns Hopkins Applied Physics Laboratory requirements drive classified trapped-ion system procurement. NIST post-quantum cryptography standardization timelines accelerate federal migration contracts for encryption algorithm testing. The I-270 technology corridor concentrates quantum networking research facilities serving satellite-to-ground communication programs.
Colorado
Air Force Research Laboratory and National Institute of Standards and Technology facilities anchor federal quantum information science investment. The Department of Energy funds shared dilution refrigerator capacity at the Boulder atomic physics campus. Private sector teams in Denver-Boulder metropolitan area develop error-correction software for trapped-ion hardware.
Illinois
Argonne National Laboratory quantum computing testbed attracts hybrid algorithm development for materials simulation. The Department of Energy Q-NEXT hub channels infrastructure investment toward fault-tolerant system roadmaps. Chicago metropolitan financial services firms rent cloud-based quantum capacity for portfolio optimization pilots.
Texas
Underdeveloped cryogenic foundry capacity offers greenfield manufacturing sites for captive dilution refrigerator production. The CHIPS and Science Act semiconductor packaging incentives attract control chip fabrication investment for trapped-ion systems. Austin and Dallas-Fort Worth metropolitan areas host emerging quantum software development clusters.
US Quantum Computing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware modality boundaries, creating a tiered structure where cloud platform operators and component fabricators occupy distinct strategic positions. Superconducting qubit vendors and trapped-ion specialists represent divergent archetypes with incompatible error-correction roadmaps. Consolidation pressures intensify as federal procurement committees await logical qubit threshold demonstrations. Dominant competitive moves include strategic partnerships for cryogenic engineering talent access and geographic expansion toward underdeveloped manufacturing clusters.
Within the cloud-platform archetype, IBM anchors enterprise developer access through hourly billing models, while IonQ exemplifies trapped-ion fidelity positioning for defense and cryptographic applications. Google occupies a research-intensive position emphasizing quantum supremacy demonstrations and artificial intelligence integration roadmaps. These three entities represent the primary competitive anchors shaping vendor selection criteria across federal and commercial buyer segments.
| Leading Market Players |
|---|
| IBM |
| IonQ |
| Microsoft |
| Rigetti Computing |
| Quantinuum |
| D-Wave Systems |
| Intel |
| QuEra Computing |
| Others |
Pricing and Supply Chain Analysis
German cryogenic component freight corridors into Maryland and Colorado dilution refrigerator facilities impose cost volatility that concentrates pricing power among integrated system builders while forcing downstream buyers into long-term offtake contracts indexed to helium isotope spot markets.
Pricing Analysis
Cost-plus contracts with helium-3 indexation dominate superconducting system procurement, locking aerospace buyers into decade-long agreements with price adjustment clauses tied to Qatari and Russian isotope export quotas. Three-tier pricing structure across premium classified installations, standard commercial cloud access, and economy research-tier hourly billing differentiates buyers by security clearance level and volume commitment. Cost compression in commercial cloud tiers is intensifying because IBM and IonQ compete for pharmaceutical and financial services pilot budgets. Research universities exhibit highest price sensitivity, while Space Force and NSA facilities accept steep premiums for air-gapped trapped-ion systems.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates cryogenic engineering component sourcing, threatening dilution refrigerator manufacturing timelines for Maryland and California defense contractors. Manufacturing concentrates in Germany, the United States, and Japan for precision cryogenic valves, superconducting wire, and ion trap vacuum chambers. Raw material dependencies span helium-3 isotopes, niobium-titanium superconducting filaments, and ytterbium metal for ion trapping. Single-source vulnerability in Russian helium-3 supply channels exposes system builders to export disruption. Distribution runs through national laboratory procurement offices and defense contractor prime vendor agreements rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum computing sits in early-cycle expansion as NIST post-quantum cryptography migration deadlines force federal encryption overhaul commitments across civilian agencies and defense contractors.
For Market Incumbents: Insulate trapped-ion roadmaps against photonic interconnect disruption by acquiring cryogenic optical packaging specialists in Texas and Arizona manufacturing clusters. Lock in helium-3 supply through backward integration into isotope enrichment partnerships or long-term Qatari offtake agreements. Capture NIST certification workflows for post-quantum cryptographic testing environments before competitor platforms achieve accreditation.
For New Entrants and Emerging Players: Texas cryogenic foundry underpenetration offers greenfield entry points for captive dilution refrigerator production serving trapped-ion system builders seeking import-independent supply chains. Target pharmaceutical molecular simulation workloads in Boston and San Francisco corridors where cloud rental models displace capital-intensive facility construction. Pursue API-first platform positioning with classical-quantum hybrid algorithm libraries to differentiate against incumbent closed-cloud architectures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors error-correction software specialists with demonstrated logical qubit threshold roadmaps over hardware modality bets still awaiting benchmark validation. Five-to-ten year viability hinges on which vendor achieves fault-tolerant operation first, consolidating federal procurement behind a single hardware standard. Watch for NIST logical qubit certification announcements as the inflection signal triggering vendor consolidation and acquisition premium repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Foundry Capacity Expansion | Captive dilution refrigerator production in Texas reduces helium-3 supply chain exposure for trapped-ion system builders. |
| Post-Quantum Cryptography Certification | NIST accreditation for encryption testing environments locks federal procurement into compliant vendor platforms. |
| Photonic Interconnect Development | Cryogenic optical links between superconducting modules address control wiring density limits for scalable architectures. |
| Helium-3 Supply Agreement | Long-term Qatari isotope offtake contracts stabilize input costs for millikelvin system manufacturers. |
| Tensor Network Algorithm Library | Hybrid classical-quantum machine learning tools attract pharmaceutical molecular simulation budgets beyond optimization pilots. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with quantum hardware engineers at national laboratories, federal procurement officers at NIST and Department of Energy facilities, cryogenic system architects at defense contractors, cloud platform product managers, and pharmaceutical R&D directors evaluating molecular simulation workloads. Secondary validation drew from Department of Commerce Bureau of Industry and Security export control filings, Department of Energy QIS research center funding disclosures, NIST post-quantum cryptography standardization documentation, and SEC filings from publicly traded quantum computing vendors. Bottom-up triangulation across hardware shipment estimates and top-down reconciliation against federal budget appropriations shaped market sizing.
Calibration against historical cloud access hour growth and federal procurement contract awards anchored projection modeling across the analysis window. Segmentation dimensions included hardware modality, deployment architecture, application workload, end-user industry, and geographic cluster concentration. CAGRs were derived from fitted growth curves moderated by logical qubit threshold uncertainty and helium supply volatility assumptions. Forecast inputs incorporated NIST migration timeline adherence probability and CHIPS Act semiconductor packaging incentive uptake rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by trapped-ion specialists or premature photonic interconnect commercialization would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
South America Halal Food and Beverages Market
Others
Europe Aircraft Lighting Systems Market
Others
Global ESD Protection Devices Market
Others
Dry Washer Market
Others
Palatants Market
Others
Space Power Supply Market
Others
North America 3D Printing Construction Market
Others
Language Translation Device Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Latin America Video Conferencing Hardware Market
Others
Global Crowdsourced Testing Market
Others
India 3D Printing Construction Market
Others
Smart Doorbell Market
Others
Propanil Market
Others
Electric Chainsaw Market
Others
Japan Automotive LED Lighting Market