
 Digital LUX Meter Market | 2026-2036
Digital LUX Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital LUX Meter Market Outlook
East Asian sensor manufacturers are repositioning their foundry capacity toward higher-precision photodiode arrays for digital lux instrumentation. Konica Minolta leverages its optical heritage to dominate calibration-grade segments across Japanese industrial labs. Testo SE & Co. KGaA anchors its European position through HVAC-integrated light measurement systems. Extech Instruments competes aggressively in North American distribution channels with contractor-focused portable units.
A digital lux meter quantifies illuminance in lux units using silicon photodiodes or phototransistors with spectral response correction filters, typically spanning 0.1 to 200,000 lux with cosine-corrected diffusers for angular accuracy. Portable Lux Meters sustain the largest revenue pool due to electrician and facilities-manager carry rates, while IoT Enabled Devices represent the fastest-expanding category as building management systems demand continuous luminance telemetry. Wireless Sensors capture premium positioning in research laboratories where cable-free protocols simplify experimental layouts.
The EU Green Deal and F-Gas Regulation shape European product roadmaps by mandating energy-efficient lighting verification, while OSHA workplace illumination standards enforce periodic measurement protocols across US manufacturing floors. Japan's METI enforces JIS standards that elevate sensor precision requirements for domestic suppliers. Stakeholders must monitor how converging building-automation codes recalibrate the boundary between standalone lux meters and integrated environmental sensor nodes.
Market Dynamics
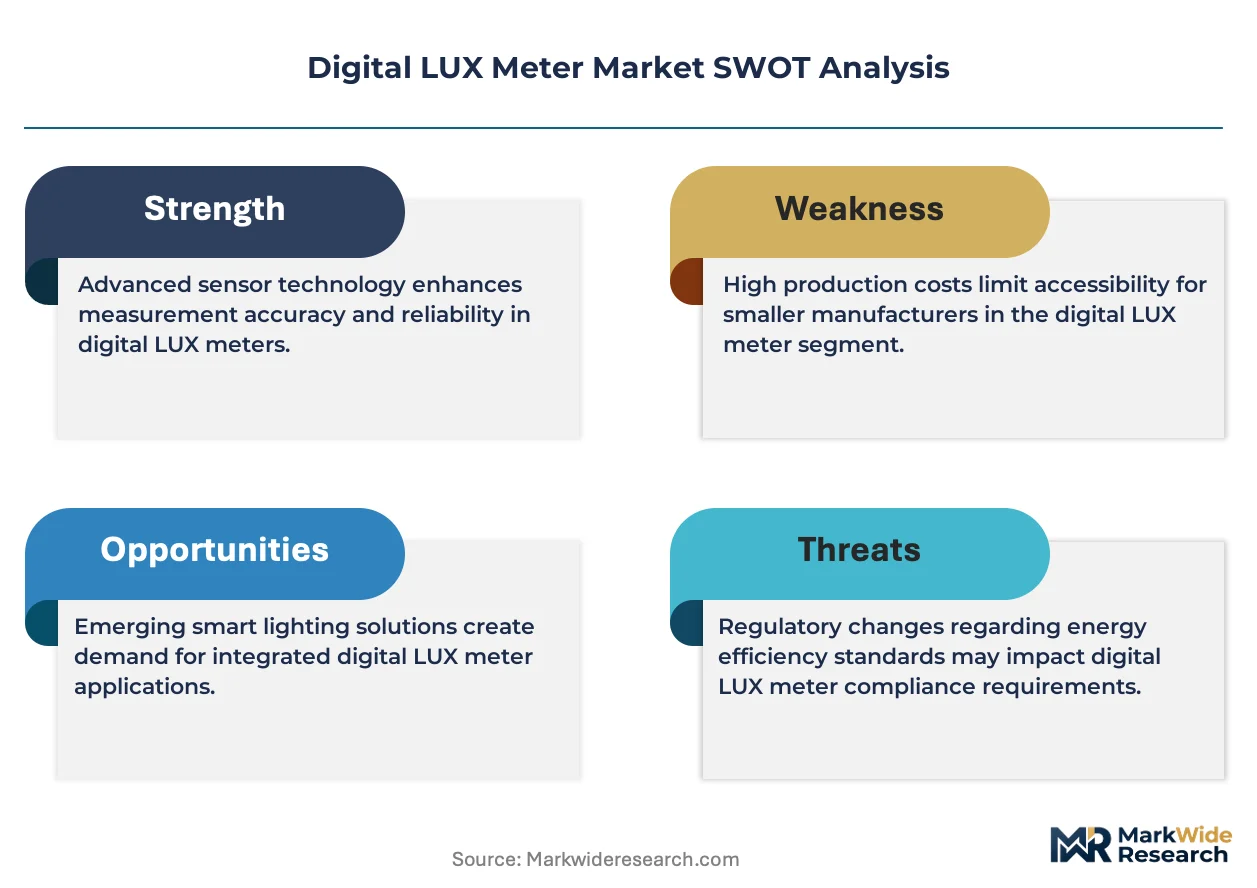
IoT-enabled building management systems are compressing the boundary between standalone lux meters and integrated environmental sensor networks, forcing vendors to reposition hardware portfolios toward continuous telemetry architectures.
Growth Catalysts
- EU Green Deal mandates:Energy-efficiency verification requirements for lighting systems are accelerating replacement cycles across commercial facilities in Germany and France.
- Workplace illumination standards:OSHA protocols enforce periodic measurement across US manufacturing floors, sustaining baseline demand for calibration-grade instrumentation.
- Silicon photodiode arrays:East Asian foundry capacity shifts toward higher-precision sensors are improving angular accuracy specifications for portable units.
Market Restraints
- Optical component concentration:Specialty diffuser and cosine-correction filter supply concentrates among Japanese and German precision optics suppliers.
- Spectral response calibration:JIS standards enforced by METI elevate domestic precision requirements, creating technical barriers for non-Japanese entrants.
- Integrated sensor substitution:Multi-parameter environmental nodes in smart buildings threaten standalone lux meter volumes in new construction.
Strategic Opportunities
- HVAC-lighting convergence:Building automation codes are creating white space for combined thermal-optical sensors in German and Dutch commercial retrofits.
- Research laboratory wireless protocols:Cable-free sensor deployments in Japanese and US academic facilities favor premium wireless lux telemetry.
- Industrial IoT platforms:Continuous luminance monitoring integration with SCADA systems opens new service revenue streams for instrumentation vendors.
Industry Challenges
- Photometric calibration expertise:Certified reference standard maintenance requires specialized technicians, constraining field service scalability.
- Legacy BMS integration:BACnet and Modbus protocol fragmentation complicates seamless data handoff to existing building management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital LUX Meter Market |
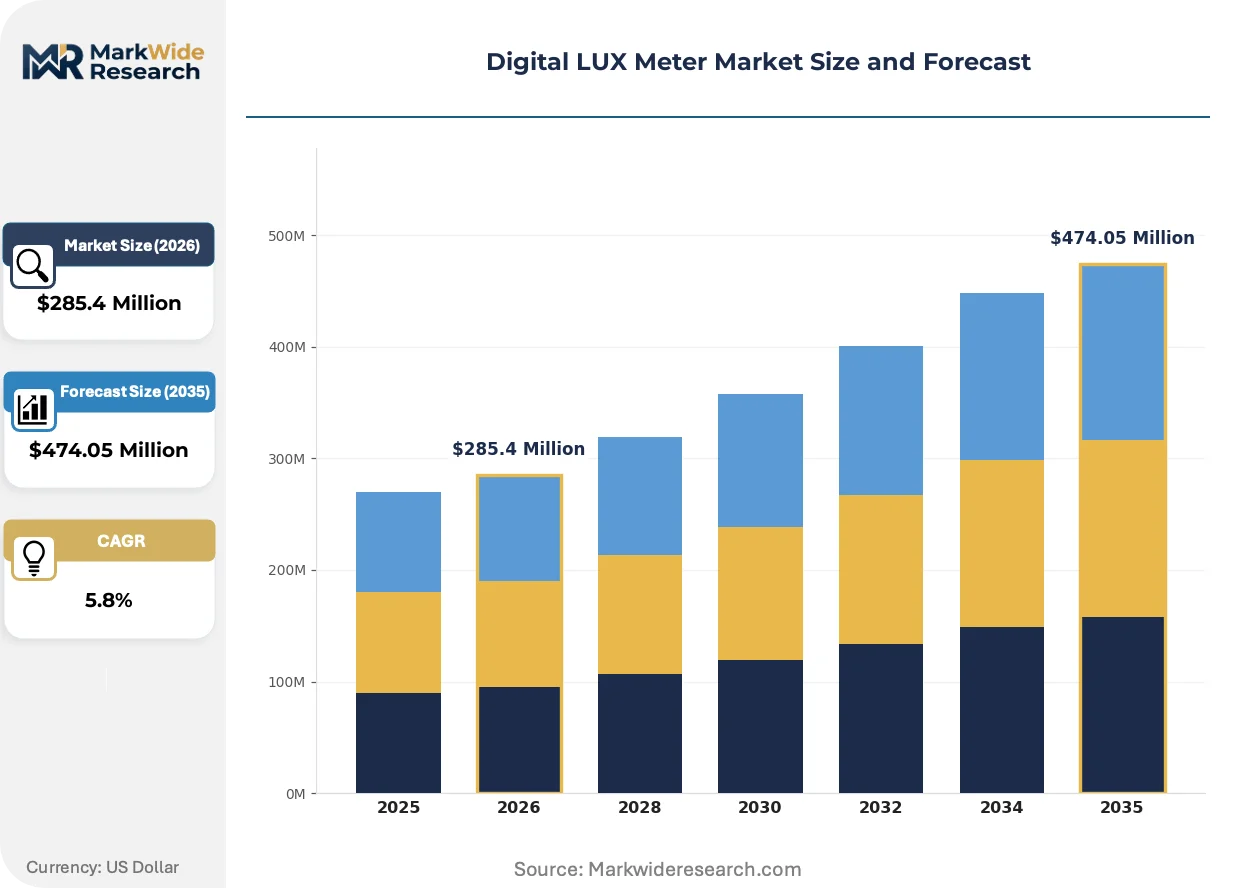
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Lux Meters, Stationary Lux Meters, Automated Lux Meters, Digital Lux Measurement Devices End User: Commercial Facilities, Educational Institutions, Research Laboratories, Residential Users Application: Lighting Design, Environmental Monitoring, Photography, Quality Control Technology: Analog Sensors, Digital Sensors, Wireless Sensors, IoT Enabled Devices |
| Companies Covered | Extech Instruments, Testo SE & Co. KGaA, Konica Minolta, Hanna Instruments, Lutron Electronic Enterprise, Sekonic Corporation, FLIR Systems, Hioki E.E. Corporation, Gossen Metrawatt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital LUX Meter Market Strategic Shifts
Edge computing architectures and spectral sensing miniaturization are redefining how illuminance data is captured, processed, and actioned within building automation workflows.
Multi-channel spectral sensors with onboard calibration algorithms are automating real-time color temperature and illuminance correction. Facility managers in US healthcare and Japanese semiconductor fabs are deploying these units at accelerating rates. The technology is automating away manual white-balance adjustments and reducing recalibration service visits.
F-Gas Regulation amendments under the EU Green Deal are tightening verification protocols for energy-efficient lighting retrofits. Commercial property operators must now document illuminance performance pre- and post-installation. German and French certification bodies are expanding accredited laboratory capacity to handle compliance testing volume.
Subscription telemetry services are displacing outright hardware purchases among multi-site retail and logistics operators. Channel partners in North America and Western Europe are bundling sensor hardware with cloud analytics platforms. This shift is most visible among US big-box retailers standardizing lighting performance across distributed footprints.
Digital LUX Meter Market Segmentation
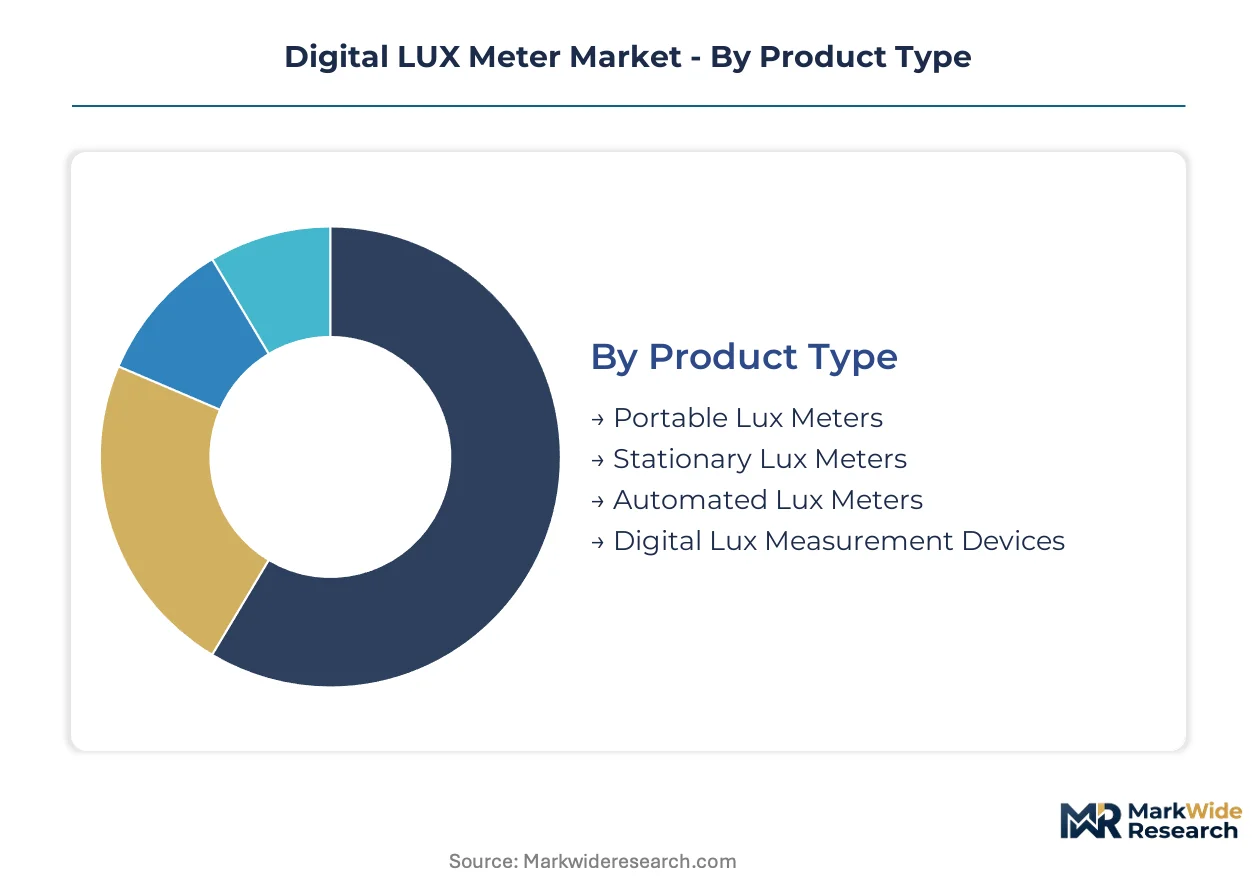
Digital lux meter segmentation reveals how hardware specialization and connectivity architectures split procurement budgets across facility types. Product form factors, end-user compliance requirements, and telemetry integration levels each create distinct competitive battlegrounds with diverging margin profiles.
Product Type:
Supply concentrates among East Asian contract manufacturers for silicon photodiode cores, while German and Japanese specialists retain captive production of cosine-correction optics and calibration-grade diffusers.
- Portable Lux Meters:Handheld units with silicon photodiode sensors and integrated cosine-corrected diffusers dominate electrician and facilities manager toolkits. Demand concentrates in US commercial retrofit markets where OSHA workplace illumination audits mandate periodic field verification.
- Stationary Lux Meters:Fixed-mount instruments with continuous logging capability anchor laboratory and manufacturing floor monitoring stations. German industrial labs and Japanese semiconductor fabs drive procurement for JIS-compliant precision variants with certified calibration chains.
- Automated Lux Meters:Robotic positioning systems with programmable measurement grids serve automotive headlamp testing and display panel quality assurance lines.
- Digital Lux Measurement Devices:Modular sensor heads with USB or Bluetooth output interfaces target integration into custom data acquisition systems.
Today's leader: Portable Lux Meters. Tomorrow's challenger: Automated Lux Meters.
End User:
Cost tier stratification separates specification-grade procurement in regulated industries from price-sensitive residential purchases.
- Commercial Facilities:Office complexes, retail chains, and logistics warehouses deploy networked lux sensors for daylight harvesting and occupancy-responsive dimming. EU Green Deal energy-efficiency verification mandates in Germany and France accelerate replacement cycles.
- Educational Institutions:Universities and K-12 districts balance budget constraints against ergonomic lighting standards for student performance. US public school districts drive volume through standardized procurement consortia.
- Research Laboratories:Photobiology and material science labs demand NIST-traceable or JIS-certified reference instruments with expanded spectral response ranges.
- Residential Users:Hobbyist photographers and home automation enthusiasts purchase entry-level smartphone-connected sensors through e-commerce channels.
Commercial Facilities command the largest hardware budgets. Research Laboratories deliver the steepest expansion trajectory for premium wireless variants.
Application:
Volume concentrates in compliance-driven measurement protocols rather than discretionary design work.
- Lighting Design:Architectural practices and theatrical consultants specify lux mapping for ambient and task illumination schemes. German commercial retrofit projects under F-Gas Regulation amendments require pre- and post-installation documentation.
- Environmental Monitoring:Building management systems integrate continuous luminance telemetry with HVAC and daylight controls. Japanese smart building deployments favor BACnet-compatible sensor nodes.
- Photography:Cinematographers and studio photographers use color-temperature-capable meters for white balance verification.
- Quality Control:Automotive tier-1 suppliers and display manufacturers automate lux uniformity testing in production lines.
Environmental Monitoring is gaining share fastest through BMS integration mandates. Lighting Design retains the deepest installed base of standalone instruments.
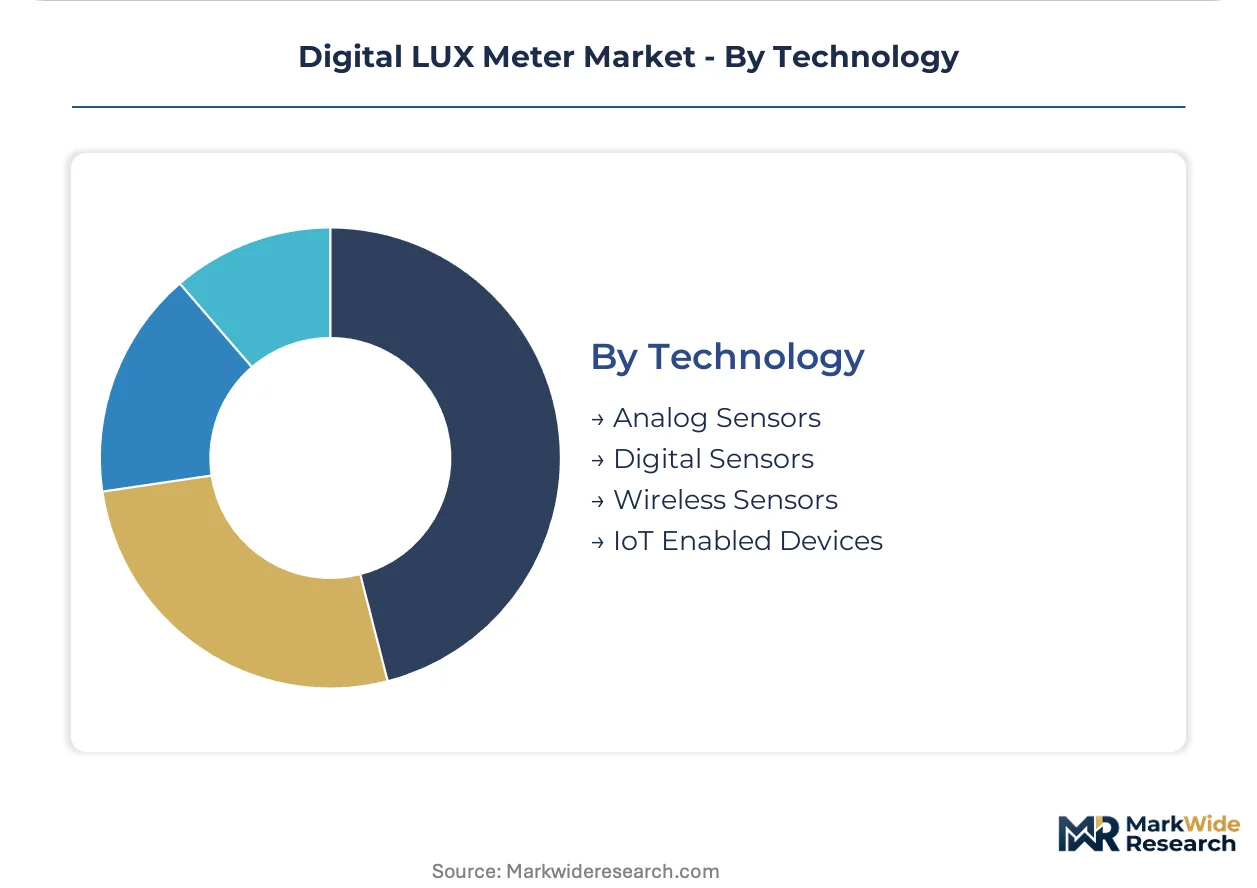
Technology:
Customer type splits between legacy analog preferences in established industrial labs and digital-native demand from IoT platform architects.
- IoT Enabled Devices:Cloud-connected sensors with edge computing capability stream continuous telemetry to building analytics platforms. US multi-site retail operators adopt subscription-bundled hardware for distributed footprint standardization.
- Wireless Sensors:Cable-free protocols simplify experimental layouts in Japanese and US academic research facilities. Premium positioning reflects reduced installation labor and reconfiguration flexibility.
- Digital Sensors:Microcontroller-based instruments with onboard ADC and display dominate mid-market portable segments.
- Analog Sensors:Galvanometer-driven meters persist in legacy industrial settings with minimal calibration infrastructure.
IoT Enabled Devices are climbing the fastest as building automation codes converge environmental sensing. Wireless Sensors capture the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of precision optical components concentrates where calibration infrastructure and photodiode foundry capacity overlap, creating compliance-cost arbitrage between Japanese sensor specialists and German optics houses versus East Asian contract manufacturers.
United States
OSHA workplace illumination audits sustain replacement demand across manufacturing floors and logistics warehouses. The Department of Energy's Better Buildings Initiative accelerates commercial retrofit specifications for networked light measurement. Industrial procurement clusters in Michigan automotive corridors and Texas petrochemical facilities favor portable verification tools.
Germany
F-Gas Regulation amendments under the EU Green Deal mandate documented illuminance performance for lighting retrofits in commercial properties. KBA and federal building codes tighten energy-efficiency verification protocols. Bavarian precision optics suppliers and North Rhine-Westphalian industrial automation integrators dominate calibration-grade instrument sourcing.
Japan
METI-enforced JIS standards elevate domestic sensor precision requirements above export-market specifications. Semiconductor fabs in Kyushu and automotive headlamp test lines in Nagoya anchor demand for automated measurement systems. Domestic photodiode foundries reposition capacity toward lux instrumentation arrays.
China
GB standards for workplace lighting and MIIT smart building directives expand procurement of IoT-enabled environmental sensors. Yangtze River Delta contract manufacturers scale silicon photodiode output for mid-market portable units. Shenzhen-based building automation integrators bundle luminance telemetry into commercial property management platforms.
South Korea
MFDS pharmaceutical manufacturing guidelines and KOSHA industrial safety standards enforce periodic illuminance verification in cleanroom environments. Seoul Capital Area biotech clusters and Busan display panel fabs drive specification-grade instrument demand. Domestic electronics conglomerates integrate light sensors into proprietary building management nodes.
Digital LUX Meter Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue wireless telemetry and cloud-analytics bundling. The vendor base stratifies across three tiers: calibration-grade specialists with captive optics production, mid-market portable manufacturers leveraging East Asian foundry supply, and IoT platform architects monetizing subscription data services. Strategic moves center on HVAC-lighting convergence partnerships and backward integration into photodiode wafer sourcing.
Among Japanese precision instrumentation houses, Konica Minolta and Sekonic Corporation exemplify the calibration-grade archetype with heritage optical capabilities. Testo SE & Co. KGaA anchors the European HVAC-integrated measurement segment. Extech Instruments occupies the North American contractor-distribution channel with portable-focused positioning. These three represent distinct geographic-specialization combinations rather than direct product rivalry.
| Leading Market Players |
|---|
| Extech Instruments |
| Testo SE & Co. KGaA |
| Konica Minolta |
| Hanna Instruments |
| Lutron Electronic Enterprise |
| Sekonic Corporation |
| FLIR Systems |
| Hioki E.E. Corporation |
| Gossen Metrawatt |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices and photodiode foundry utilization rates cascade through three distinct pricing tiers, with JIS-certified calibration-grade instruments commanding substantial premiums over contractor-grade portable units sold through North American distribution channels.
Pricing Analysis
Distributor margins of 35-45 percent in European HVAC-integrated channels sustain premium positioning for Testo SE and Gossen Metrawatt, while direct-to-OEM volume discounts compress per-unit economics for East Asian contract manufacturers supplying mid-market portable segments. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable laboratory instruments from OSHA-compliant field units and smartphone-connected hobbyist sensors. Cost compression in the mid-market portable tier is intensifying because Yangtze River Delta foundries are expanding silicon photodiode capacity. Commercial facilities managers exhibit highest price sensitivity, whereas research laboratories demonstrate minimal elasticity for certified calibration chains.
Supply Chain Analysis
Certification gating through METI-enforced JIS standards and NIST-traceable calibration protocols restricts viable supplier pools to German precision optics houses and Japanese photodiode foundries with captive diffuser production. Geographic supply concentration centers on Japan, Germany, and China, with raw material dependencies spanning silicon ingots, cosine-correction optical glass, and spectral response filter coatings. Single-source vulnerability concentrates in Bavarian specialty diffuser manufacturing, where three precision optics suppliers serve the global calibration-grade market. Distribution runs through authorized industrial instrumentation distributors in North America and Western Europe, with direct OEM relationships dominating East Asian procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital LUX Meter Market functions as a stable compounder, with regulatory mandates for workplace illumination verification and energy-efficiency documentation generating predictable replacement cycles across commercial and industrial facilities.
For Market Incumbents: Hedge against integrated sensor substitution by deepening backward integration into photodiode wafer sourcing and securing exclusive distribution partnerships with HVAC-system integrators in Germany and the Netherlands. Multi-parameter environmental nodes threaten standalone lux meter volumes in new construction, making calibration-service revenue streams and certified reference standard maintenance critical defensive moats. Capacity addition in Kyushu semiconductor fab corridors captures automated measurement system demand. For New Entrants and Emerging Players: EU Green Deal amendments in Germany and France open a window for subscription telemetry services bundled with cloud analytics platforms, displacing outright hardware purchases among multi-site retail operators. White space concentrates in US big-box retail distributed footprint standardization and Japanese academic wireless sensor deployments. A direct-to-facility-manager digital marketing approach bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with IoT platform architects monetizing continuous luminance data streams rather than hardware manufacturers facing commodity photodiode cost curves. Long-term viability favors vendors with captive optics production and established calibration infrastructure. The signal to watch is BACnet/Modbus protocol standardization progress, which would accelerate building management system integration and expand addressable market for networked sensors.| Strategic Initiative | Industry Significance |
|---|---|
| Photodiode Foundry Backward Integration | Captive silicon wafer supply secures margin control against East Asian contract manufacturer price competition. |
| HVAC-System Integrator Partnership | Testo SE's channel positioning demonstrates thermal-optical sensor convergence opportunity in German commercial retrofits. |
| Subscription Telemetry Service Launch | Cloud-analytics bundling captures recurring revenue from US multi-site retail operators standardizing lighting performance. |
| JIS Certification Investment | METI-enforced precision requirements create technical barriers protecting Japanese domestic supplier margins. |
| Wireless Protocol Certification | BACnet compatibility unlocks Japanese smart building procurement and research laboratory experimental layout flexibility. |
Study Parameters
Direct dialogue with facilities managers, calibration laboratory technicians, HVAC-system integrators, and industrial automation procurement officers grounded qualitative findings, cross-referenced against secondary sources including OSHA enforcement databases, EU F-Gas Regulation amendment texts, METI JIS standard documentation, and SEC filings from listed instrumentation manufacturers. Bottom-up unit economics triangulated with top-down construction spending and commercial retrofit activity indices.
Segment-level projections across product type, end user, application, and technology dimensions were generated through the analysis window, with CAGRs derived from regression analysis against regulatory mandate implementation timelines and smart building deployment curves. Key inputs included photodiode foundry capacity expansion announcements, accredited laboratory certification capacity in Germany and France, and building automation code convergence patterns in Japanese and US commercial construction.
Revisions become necessary when EU Green Deal enforcement intensity shifts, OSHA workplace illumination audit frequency changes, or photodiode foundry capacity reallocation accelerates beyond modeled scenarios. A model refresh is warranted upon material change in BACnet/Modbus protocol standardization progress or integrated environmental sensor node pricing trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global B2B Enterprise and Industrial Wearables Market
Others
AI in Home Automation Market
Others
Enterprise Video Content Management Market
Others
United States Cigarette Market
Others
North America Industrial Wearable Devices Market
Others
China Automotive LED Lighting Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Global Optical Comparator Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Mine Rescue Vehicle Market
Others
Crystal Growth Equipment Market
Others
Germany Smart Home Market
Others
North America Flexographic Printing Market
Others
Global Injectable Nanomedicine Market
Others
Flexographic Printing Plate Market
Others
Saudi Arabia Laser Hair Removal Market