
 Global Retail Media Networks Market | 2026-2036
Global Retail Media Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retail Media Networks Market Outlook
Retail media inventory is reconfiguring how brands access shoppers at the point of purchase. Amazon Ads leverages its first-party purchase graph to sustain closed-loop attribution for consumer packaged goods advertisers. Walmart Connect anchors its network through in-store digital displays and app-based sponsored placements. Kroger Precision Marketing differentiates by linking loyalty card data to off-site programmatic inventory across the open web.
Retail media networks are technology platforms that enable advertisers to purchase digital ad placements on retailer-owned properties, typically operating through demand-side interfaces with audience segmentation based on verified purchase history and browsing behavior. These networks process petabyte-scale transaction logs to match brand messages with shoppers demonstrating active category intent. Display ads and search ads capture the largest share of committed budgets, while video ads within retail apps represent the fastest-growing format as dwell times extend. The distribution channel structure shows online marketplaces commanding premium CPMs due to closed transaction data, whereas affiliate networks compete on reach extension with weaker attribution certainty.
The Federal Trade Commission scrutinizes data-sharing practices between retailers and brand advertisers under evolving consumer protection mandates. The European Union's GDPR and Digital Markets Act constrain cross-border audience data portability, forcing network operators to localize data processing infrastructure. Stakeholders must monitor how privacy regulation fragmentation affects the scalability of unified retail media buying platforms across operating jurisdictions.
Market Dynamics
Third-party cookie deprecation is forcing advertisers to abandon open-web tracking and consolidate spending on retailer-owned properties with verified first-party purchase data. This structural shift concentrates buying power within closed-loop ecosystems and raises barriers for independent publishers lacking transactional identity graphs.
Growth Catalysts
- GDPR enforcement:European data portability rules are pressuring brands to abandon cross-border ad tech stacks and migrate budgets toward localized retail media platforms with compliant data processing infrastructure.
- Artificial intelligence:Machine learning models for audience segmentation and predictive attribution are compressing campaign optimization cycles and improving return on ad spend for consumer packaged goods advertisers.
- Grocery sector concentration:United States supermarket chains with mature loyalty programs are capturing brand dollars previously allocated to broadcast television and social media platforms.
Market Restraints
- Data localization mandates:European Union Digital Markets Act requirements are fragmenting unified buying platforms and forcing redundant infrastructure investments across operating jurisdictions.
- Attribution opacity:Off-site programmatic inventory through affiliate networks lacks closed-loop transaction verification, creating measurement uncertainty that constrains premium pricing power.
- Technical interoperability gaps:Proprietary retailer data formats and API limitations prevent seamless cross-platform campaign management and audience deduplication.
Strategic Opportunities
- In-store digital displays:Big-box retailers are converting physical footprints into addressable advertising surfaces, creating new inventory categories for location-based brand messaging.
- India's retail digitization:Reliance Jio and Tata Neu are building first-party data ecosystems that offer early-mover advantages for network operators before market saturation.
- Video format expansion:Extended dwell times within retail apps are enabling pre-roll and shoppable video placements that command higher effective CPMs than static display units.
Industry Challenges
- Data science talent scarcity:Shortage of professionals skilled in privacy-preserving machine learning and differential privacy techniques is slowing platform development timelines.
- Legacy system integration:Enterprise resource planning and customer data platform architectures at established retailers require substantial reconfiguration to support real-time ad serving.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retail Media Networks Market |
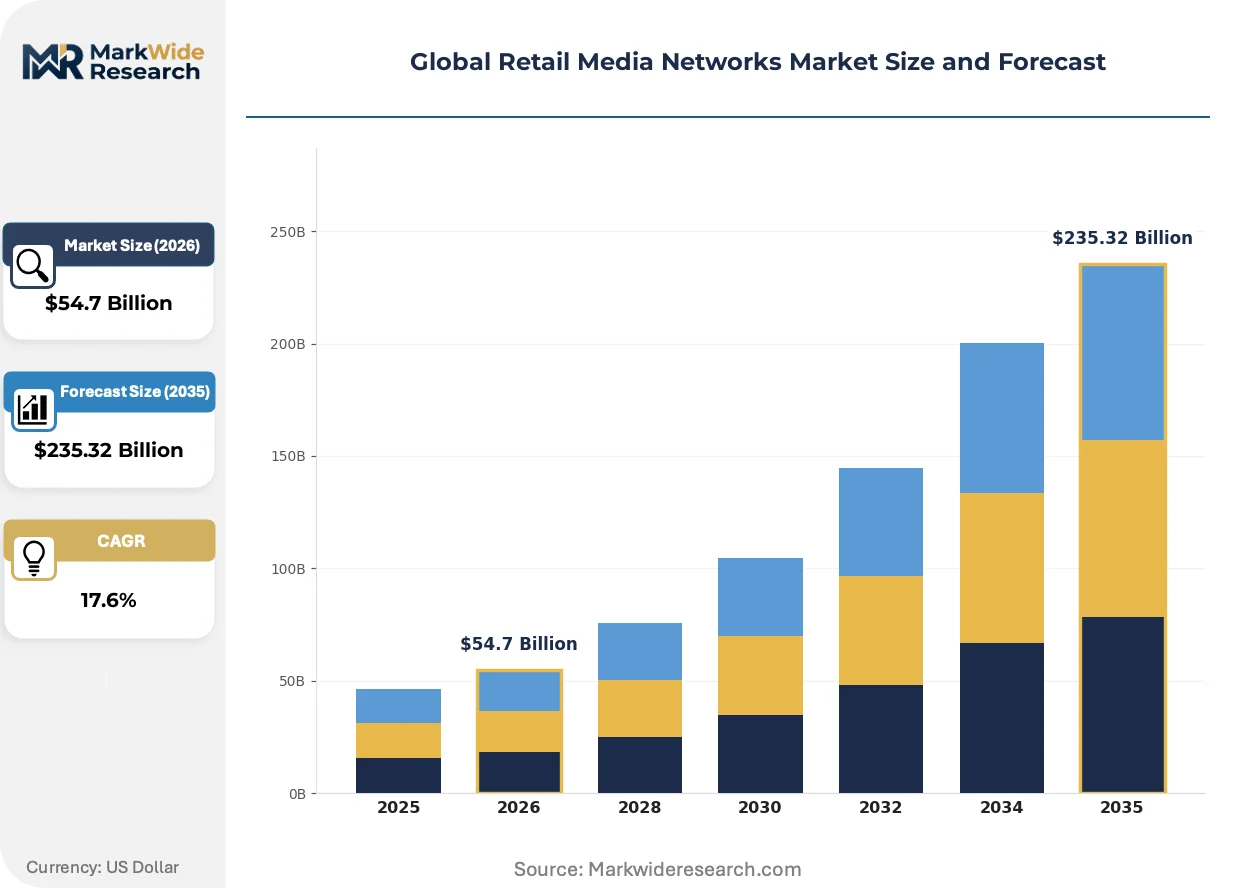
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $235.32 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Ads, Video Ads, Search Ads, Social Media Ads Distribution Channel: Online Marketplaces, E-commerce Websites, Mobile Applications, Affiliate Networks Engagement Type: Sponsored Content, Brand Partnerships, Influencer Collaborations, Loyalty Programs Customer Type: Small Businesses, Large Enterprises, Brands, Retailers |
| Companies Covered | Kroger Precision Marketing, Instacart Ads, Amazon Ads, Home Depot Orange Apron Media, Best Buy Ads, Walmart Connect, Albertsons Media Collective, Costco Connect, Target Roundel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retail Media Networks Market Strategic Shifts
Retail media infrastructure is undergoing rapid architectural transformation as artificial intelligence, privacy engineering, and connected commerce converge. These developments are redefining how advertisers access shoppers and how retailers monetize their data assets.
Clean room technology is migrating from experimental pilots to standard infrastructure for privacy-safe data collaboration. Consumer packaged goods brands and retail media networks are adopting interoperable clean room environments to combine first-party datasets without exposing raw customer records. This migration from direct data sharing to cryptographic and differential privacy techniques is enabling scaled audience matching while satisfying regulatory constraints.
The European Union's Digital Markets Act is imposing interoperability mandates on designated gatekeeper platforms that operate retail media networks. These rules require standardized advertising interfaces and data portability mechanisms that prevent walled-garden lock-in. Retailers with gatekeeper status must restructure their demand-side platforms to accommodate third-party ad tech integration, compressing their historical technology advantages.
Commerce media buying patterns are shifting from guaranteed insertion orders toward programmatic guaranteed and private marketplace transactions. Brand advertisers are demanding auction-based pricing transparency and real-time inventory access rather than annual upfront commitments. This behavioral change is most pronounced in the United States, where mature demand-side platform infrastructure enables sophisticated bidding strategies across multiple retail media networks simultaneously.
Global Retail Media Networks Market Segmentation
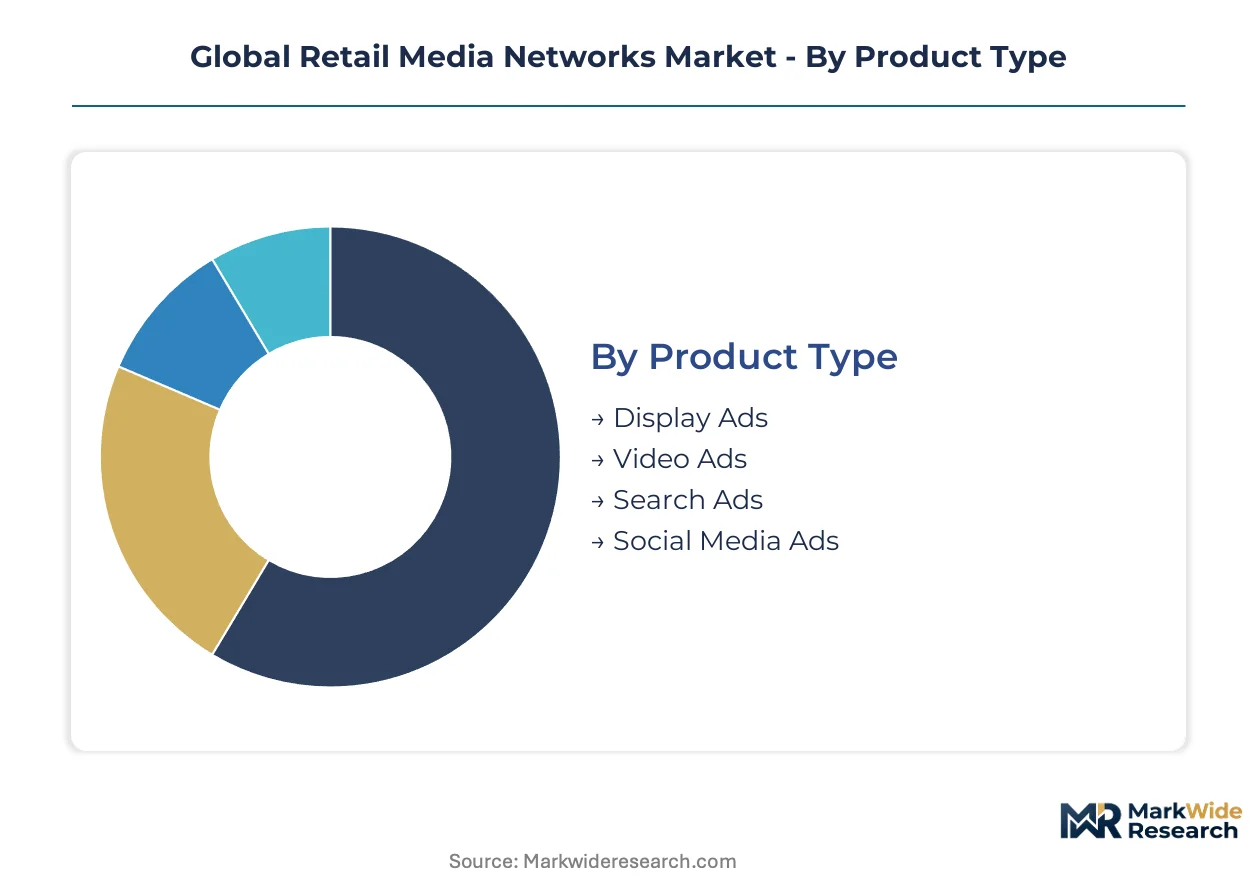
Retail media networks segment across multiple dimensions that determine campaign architecture, data integration complexity, and advertiser service requirements. Each segmentation axis reveals distinct operational models and margin structures that shape how platforms allocate engineering resources and sales capacity.
Product Type:
After-sales service intensity varies sharply across ad formats, with video and search placements demanding continuous creative optimization and attribution troubleshooting that static display units rarely require.
- Display Ads:Banner and native placements on retailer websites and apps rely on standardized IAB specifications with modest creative production overhead. Demand concentrates among consumer packaged goods brands in the United States seeking upper-funnel awareness within closed-loop measurement environments, though attribution precision lags search-based alternatives.
- Video Ads:Pre-roll and shoppable video inventory within retail apps commands premium CPMs due to extended dwell times and completion rate advantages. Growth concentrates in grocery and big-box retail apps where basket-building sessions stretch engagement windows, though creative production costs and load-time optimization demands elevate operational complexity.
- Search Ads:Sponsored product listings at point-of-purchase capture high-intent queries with direct conversion tracking.
- Social Media Ads:Retailer-integrated social placements leverage first-party data for off-platform targeting.
By volume, Display Ads leads. By growth pace, Video Ads is climbing the fastest.
Distribution Channel:
Cost tier differentiation separates premium closed-loop ecosystems from reach-extension alternatives with weaker attribution certainty and correspondingly lower platform service obligations.
- Online Marketplaces:Amazon Ads and Walmart Connect anchor this tier with verified transaction data enabling end-to-end attribution. Demand concentrates among large enterprise advertisers in the United States reallocating broadcast television budgets, though inventory scarcity and auction competition compress margin efficiency for mid-market brands.
- E-commerce Websites:Retailer-owned dot-com properties with first-party login data support behavioral targeting without marketplace transaction fees. Growth concentrates among specialty retailers in Germany and France building GDPR-compliant data infrastructures, though traffic scale constraints limit national campaign reach.
- Mobile Applications:In-app sponsored placements leverage device identifiers and geolocation for proximity-based messaging.
- Affiliate Networks:Third-party publisher relationships extend retailer data for off-site programmatic buying with probabilistic attribution.
By revenue concentration, Online Marketplaces dominates. By expansion trajectory, Mobile Applications is gaining share fastest.
Engagement Type:
Application maturity determines whether engagement formats operate as self-serve auction mechanics or high-touch managed services with dedicated account support.
- Sponsored Content:Native editorial integrations on retailer digital properties require custom creative development and placement negotiation. Demand concentrates among beauty and personal care brands in the United Kingdom seeking contextual alignment with shopping content, though production timelines and approval workflows extend campaign launch cycles.
- Brand Partnerships:Co-branded digital experiences and exclusive product launches demand deep retailer collaboration and data-sharing agreements. Growth concentrates among multinational consumer goods conglomerates with established Kroger Precision Marketing and Target Roundel relationships, though partnership scarcity limits participation to top-spending accounts.
- Influencer Collaborations:Retailer-vetted creator networks extend reach through social proof mechanisms with platform-mediated compensation.
- Loyalty Programs:Points-based promotional integrations leverage transaction history for personalized offer delivery.
By advertiser participation, Sponsored Content leads. By strategic priority, Brand Partnerships shows the steepest expansion trajectory.
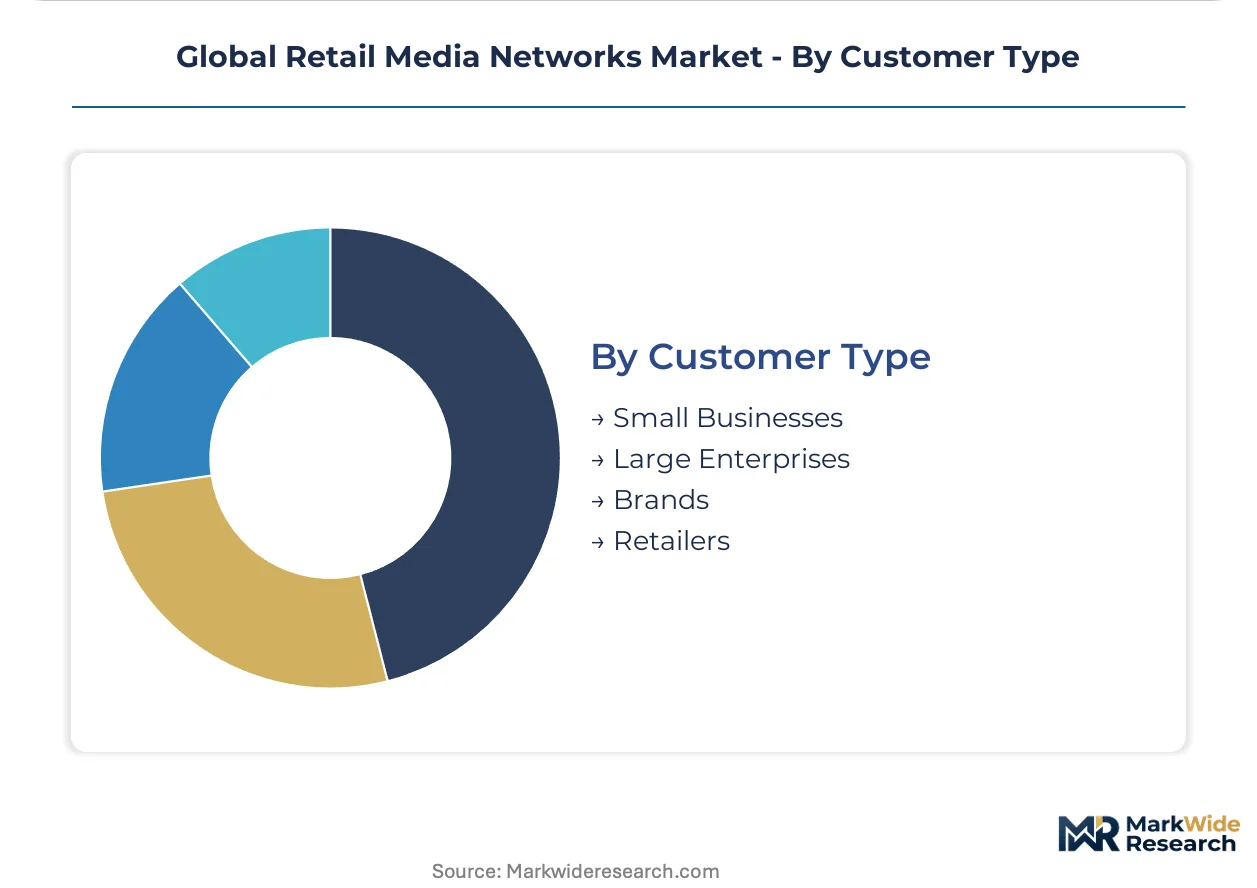
Customer Type:
Supply concentration among large enterprises with dedicated retail media agencies contrasts with fragmented small-business demand requiring automated onboarding and simplified campaign interfaces.
- Large Enterprises:Multinational brands with annual retail media budgets exceeding eight figures command dedicated platform support and beta feature access. Demand concentrates among Procter & Gamble and Unilever-scale advertisers in the United States consolidating spend across Amazon, Walmart, and Instacart, though cross-platform attribution fragmentation complicates unified measurement.
- Brands:Mid-market consumer goods companies with category-specific retail media strategies balance self-serve and managed service engagement. Growth concentrates among direct-to-consumer challengers in India accessing Reliance Jio and Tata Neu platforms, though data science talent scarcity slows optimization maturity.
- Small Businesses:Local and regional advertisers with limited technical resources rely on simplified campaign builders.
- Retailers:Retail media networks themselves as advertisers promoting private-label products and marketplace services.
By committed spend, Large Enterprises leads. By platform investment priority, Brands is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable systems linking Frankfurt to New York and London underpin Europe's data portability infrastructure for retail media operations. These digital arteries enable cross-border audience matching while GDPR enforcement pressures localized processing architectures.
United States
Grocery and big-box retailers with mature loyalty programs capture brand dollars migrating from broadcast television. The FTC scrutinizes data-sharing practices between retailers and advertisers under evolving consumer protection mandates. Retail media concentration clusters in Chicago, Bentonville, and Seattle where closed-loop attribution ecosystems command premium CPMs.
Germany
Specialty retailers build GDPR-compliant data infrastructures to attract privacy-conscious brand budgets. The Digital Markets Act imposes interoperability mandates on designated gatekeeper platforms operating retail media networks. Munich and Berlin host emerging clean room technology pilots for privacy-safe data collaboration between consumer goods brands and retail networks.
United Kingdom
Beauty and personal care brands drive demand for sponsored content integrations on retailer digital properties. The Information Commissioner's Office enforces strict guidelines on loyalty card data usage for programmatic targeting. London anchors the national retail media ecosystem with sophisticated demand-side platform infrastructure enabling cross-network bidding strategies.
India
Direct-to-consumer challengers access emerging first-party data ecosystems before market saturation. The Digital Personal Data Protection Act establishes consent frameworks for retail media audience segmentation. Mumbai and Bangalore concentrate platform development talent as Reliance Jio and Tata Neu build proprietary retail media infrastructures.
France
Mid-market consumer goods companies balance self-serve and managed service engagement models. The CNIL enforces data localization requirements that fragment unified buying platforms across operating jurisdictions. Paris hosts retail media innovation clusters focused on AI-driven audience segmentation for luxury and FMCG advertisers.
Global Retail Media Networks Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with audience data and attribution modules. The vendor base organizes around three archetypes: marketplace operators with closed transaction graphs, grocery retailers with loyalty-derived identity assets, and big-box specialists converting physical footprints into digital inventory. Consolidation pressures favor scale players with petabyte-scale data infrastructure. Dominant competitive moves include clean room technology partnerships and in-store digital display network expansion.
Within the marketplace operator tier, Amazon Ads and Walmart Connect anchor closed-loop ecosystems with verified purchase data. Kroger Precision Marketing exemplifies the grocery retail archetype, linking loyalty card data to off-site programmatic inventory. These three entities represent the dominant competitive positioning patterns shaping advertiser budget allocation across the landscape.
| Leading Market Players |
|---|
| Kroger Precision Marketing |
| Instacart Ads |
| Amazon Ads |
| Home Depot Orange Apron Media |
| Best Buy Ads |
| Walmart Connect |
| Albertsons Media Collective |
| Costco Connect |
| Target Roundel |
| Others |
Value Chain & Pricing Dynamics
GDPR enforcement as a regulatory chokepoint determines both tier spreads and supply chain architecture across retail media networks, forcing redundant infrastructure investments that compress margin efficiency for mid-market advertisers while elevating premium pricing power for compliant closed-loop ecosystems.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise commitment levels, with annual spend thresholds separating dedicated platform support from self-serve auction mechanics. Amazon Ads and Walmart Connect command premium CPMs through verified purchase graph exclusivity, while affiliate network inventory competes on reach extension with weaker attribution certainty and corresponding price softness. Cost compression in the mid-market tier is intensifying because technical interoperability gaps prevent seamless cross-platform campaign management, forcing advertisers toward bundled managed services. Small businesses exhibit highest price sensitivity due to limited technical resources and simplified campaign interface requirements, whereas multinational enterprises with eight-figure budgets demonstrate lowest sensitivity given beta feature access and dedicated account support.
Supply Chain Analysis
Upstream feedstock of first-party data assets concentrates in the United States, Germany, and the United Kingdom where mature loyalty programs and closed-loop transaction infrastructures anchor platform development. Retail media networks draw from petabyte-scale transaction logs, artificial intelligence compute clusters, and privacy-preserving machine learning frameworks as core inputs. Single-source vulnerability sits with cloud infrastructure providers hosting real-time ad serving and clean room technology deployments. Distribution runs through demand-side platform interfaces, direct sales organizations, and programmatic guaranteed channels toward consumer packaged goods advertisers and direct-to-consumer brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retail media networks market sits in a cyclical recovery phase driven by third-party cookie deprecation forcing budget consolidation toward first-party data ecosystems.
For Market Incumbents: Build data moat depth through clean room technology partnerships that lock in consumer packaged goods brand relationships before interoperability mandates erode walled-garden advantages. Kroger Precision Marketing and Target Roundel should accelerate in-store digital display network expansion to convert physical footprints into addressable inventory surfaces. Threat vectors include the European Union Digital Markets Act imposing standardized advertising interfaces that compress historical technology differentiation. Capacity addition in India through Reliance Jio and Tata Neu platform integrations represents a critical geographic lever for first-mover data asset accumulation. For New Entrants and Emerging Players: Establish a beachhead in India's retail digitization wave before Reliance Jio and Tata Neu achieve market saturation and data network effects crystallize. The most penetrable white space concentrates among specialty retailers in Germany and France building GDPR-compliant infrastructures with weaker technical talent depth than United States counterparts. A direct-to-consumer challenger go-to-market angle leveraging simplified self-serve interfaces and automated onboarding workflows addresses mid-market brand demand currently underserved by high-touch managed service models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scale players with petabyte-scale infrastructure and established clean room technology stacks. Long-term viability across the next decade hinges on artificial intelligence differentiation in audience segmentation and predictive attribution modeling. Acquisition target archetypes include grocery retailers with mature loyalty-derived identity assets and component specialists with privacy-preserving machine learning modules. The signal to watch as inflection indicator is Federal Trade Commission enforcement action on data-sharing practices between retailers and brand advertisers.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Technology Partnership | Enables privacy-safe data collaboration between Kroger Precision Marketing and Procter & Gamble-scale advertisers. |
| In-Store Digital Display Expansion | Converts Walmart and Target physical footprints into addressable advertising surfaces with location-based messaging. |
| Programmatic Guaranteed Migration | Shifts commerce media buying from insertion orders toward auction-based transparency across Amazon Ads demand-side infrastructure. |
| GDPR-Compliant Infrastructure Localization | Fragments unified buying platforms across European jurisdictions under Digital Markets Act processing mandates. |
| Artificial Intelligence Talent Acquisition | Addresses data science scarcity slowing platform development timelines for differential privacy and predictive attribution. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with retail media network executives, consumer packaged goods brand managers, demand-side platform engineers, and privacy compliance officers. Secondary validation incorporated SEC filings from marketplace operators, GDPR enforcement notices from European data protection authorities, FTC consumer protection mandate updates, and hyperscaler cloud infrastructure capex disclosures. Bottom-up triangulation across advertiser budget allocation surveys and top-down reconciliation against retail digital advertising revenue estimates anchored the analytical framework.
Calibration against historical CAGRs from adjacent digital advertising segments and retail technology infrastructure markets informed the projection framework across the analysis window. Segmentation dimensions modeled include ad format type, distribution channel structure, engagement application maturity, and customer enterprise scale tier. CAGRs were derived through regression analysis of committed budget trajectories and inventory expansion rates. Industry-specific forecast inputs encompass third-party cookie deprecation timelines and artificial intelligence compute cluster deployment velocities.
Stress conditions across regulatory enforcement intensity, cloud infrastructure cost volatility, and data science talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding privacy regulation fragmentation and interoperability mandate implementation schedules. Cross-checking against IAB digital advertising spend benchmarks and retail trade association technology investment surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hypermarket Market
Others
Mainframe Market
Others
Asia-Pacific Military 4D Printing Market
Others
Mobile Computing Devices Market
Others
Coloring Apps Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Video Conferencing Hardware Market
Others
France Smart Home Market
Others
Global Aircraft Lighting Systems Market
Others
Mini Personal Computer Market
Others
Spain Smart Home Market
Others
Latin America Fire Sprinklers Market
Others
Global Emergency Spill Response Market
Others
Blockchain in BFSI Market
Others
Safety Critical Software Testing Market
Others
Augmented Reality in Energy and Utilities Market