
 Global Fertility Tracking Apps Market | 2026-2036
Global Fertility Tracking Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fertility Tracking Apps Market Foresight
Multi-source algorithm development is shifting toward hybrid AI and sensor architectures across the fertility tracking landscape. Flo Health leverages proprietary machine learning frameworks to sustain engagement across cycle monitoring and hormonal analysis segments. Natural Cycles anchors its position through basal body temperature sensor integration and CE-marked medical device status in European markets. Clue competes by emphasizing open-data research partnerships and menstrual health analytics.
Fertility tracking apps constitute software platforms that collect physiological biomarkers—basal body temperature, cervical fluid consistency, hormone metabolite levels, and menstrual cycle timestamps—to compute ovulation windows and reproductive health insights through predictive algorithmic modeling. Their primary commercial purpose centers on enabling timed conception, identifying cycle irregularities, and supporting clinical fertility assessments through longitudinal data aggregation. Wearable integrations and AI algorithms represent the fastest-expanding solution type and technology pairing, as hardware miniaturization and edge computing reduce latency in ovulation prediction models. Mobile applications still occupy the largest value pool given minimal user friction and direct-to-consumer distribution, though cloud solutions are capturing margin from fertility clinics requiring HIPAA-compliant data architectures.
FDA software-as-medical-device oversight in the United States and the EU AI Act's high-risk system classification for fertility algorithms are tightening validation requirements for predictive accuracy claims and data governance protocols. Japan's PMDA has initiated comparable review pathways for basal body temperature sensor-linked apps, creating a tri-regional compliance benchmark that filters market access for smaller developers. Stakeholders must monitor evolving reimbursement decisions by Germany's Federal Joint Committee and comparable health technology assessment bodies, as these determinations will signal whether fertility apps transition from out-of-pocket wellness purchases to covered medical services.
Market Dynamics
Algorithmic validation requirements under the EU AI Act and FDA software-as-medical-device pathways are compressing development timelines and forcing capital reallocation toward clinical evidence generation rather than pure user acquisition.
Growth Catalysts
- Basal body temperature sensor miniaturization:Wearable manufacturers in Japan and Germany are integrating sub-millimeter thermistors into rings and patches, enabling continuous nocturnal temperature logging without user intervention.
- FDA De Novo pathway expansion:The agency's 2022 guidance clarifying fertility software classification has accelerated 510(k) submissions for algorithm-based ovulation prediction tools in the United States.
- Employer-sponsored fertility benefits:Large self-insured employers in the United States are adding digital fertility solutions to supplemental health packages, creating B2B2C distribution channels independent of traditional reimbursement.
Market Restraints
- Cloud infrastructure concentration:HIPAA-compliant hosting providers cluster in Virginia and Frankfurt, creating single-region dependency risks for data residency requirements.
- CE marking timeline under MDR:European notified body capacity constraints have extended fertility app certification cycles from 9 to 18 months, freezing product launches.
- Free-to-premium conversion friction:Consumer willingness-to-pay for subscription fertility analytics plateaus at price points below sustainable customer acquisition costs in saturated urban markets.
Strategic Opportunities
- India's CDSCO emerging framework:Draft guidance for Software as Medical Device classification creates first-mover advantage for platforms establishing local clinical validation partnerships.
- Perimenopause tracking convergence:Extending cycle prediction algorithms to irregular bleed patterns in the 40-50 demographic opens adjacent revenue pools with higher price tolerance.
- Telehealth integration APIs:Direct data feeds into electronic health records used by fertility clinics in Spain and Italy enable reimbursement coding for remote patient monitoring.
Industry Challenges
- Biostatistician talent scarcity:Validation of machine learning ovulation models requires specialists conversant in both reproductive endocrinology and FDA statistical review standards, with fewer than 200 qualified professionals globally.
- Multi-jurisdiction data governance:Simultaneous compliance with HIPAA, GDPR, and Japan's APPI forces architectural fragmentation that increases engineering headcount by 40% relative to single-market competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fertility Tracking Apps Market |
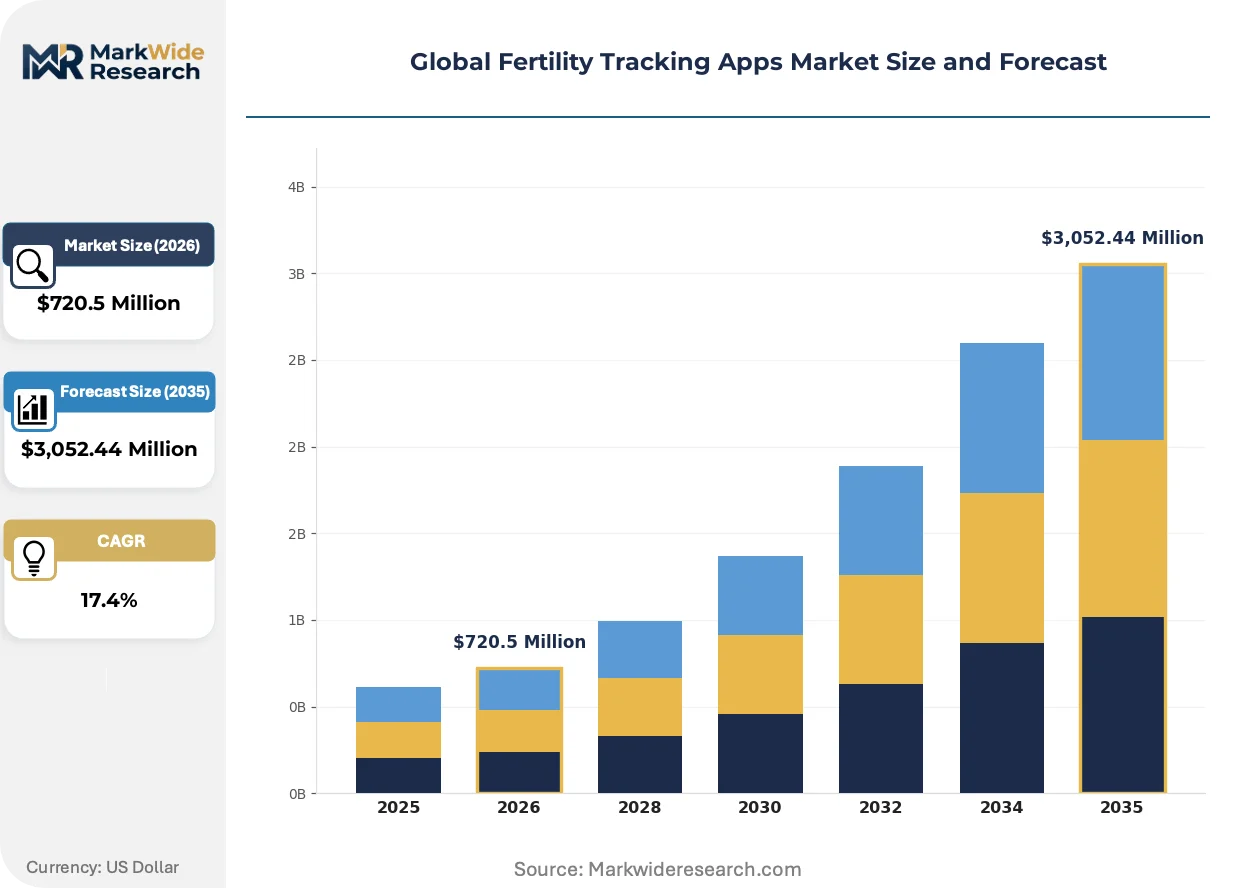
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $3,052.44 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Conception Planning, Cycle Monitoring, Pregnancy Tracking, Menstrual Health, Hormonal Analysis Solution Type: Mobile Applications, Web-Based Platforms, Wearable Integrations, SMS Services, Cloud Solutions End User: Individual Consumers, Fertility Clinics, Gynecological Centers, Wellness Coaches, Telehealth Providers Technology: AI Algorithms, Basal Body Temperature Sensors, Ovulation Prediction Models, Hormone Level Trackers, Data Analytics Tools |
| Companies Covered | Glow, Kindara, Flo Health, Bearable, Ovia Health, Natural Cycles, Samphire Neuroscience, Embody, Clue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fertility Tracking Apps Market Shifts & Advancements
Edge computing architectures and federated learning protocols are displacing centralized cloud processing for sensitive biometric data, altering competitive moats around prediction accuracy and data security simultaneously.
Multimodal sensor fusion is consolidating discrete fertility signals—basal temperature, heart rate variability, and hormonal metabolite concentrations—into single algorithmic pipelines. Fertility clinics in Denmark and the Netherlands are piloting these integrated systems for pre-IVF cycle optimization, reducing the gap between consumer-grade and clinical-grade prediction fidelity. This consolidation is compressing margins for standalone temperature-tracking hardware vendors.
The EU AI Act's high-risk system classification for fertility algorithms mandates conformity assessments through notified bodies in Germany and France. Developers must now submit technical documentation covering training data provenance, bias testing protocols, and human oversight mechanisms before CE marking. Smaller platforms without dedicated regulatory affairs functions are outsourcing compliance to specialized consultancies in Brussels, raising fixed costs and favoring scaled incumbents.
Subscription fatigue among millennial and Gen-Z users is shortening free-to-paid conversion windows from 90 to 30 days. Direct-to-consumer fertility apps in the United Kingdom and Australia are responding with usage-based pricing tied to confirmed conception outcomes rather than time-bound subscriptions. This model shifts revenue recognition risk onto developers while aligning incentives with user success metrics tracked through post-purchase surveys.
Global Fertility Tracking Apps Market Segmentation
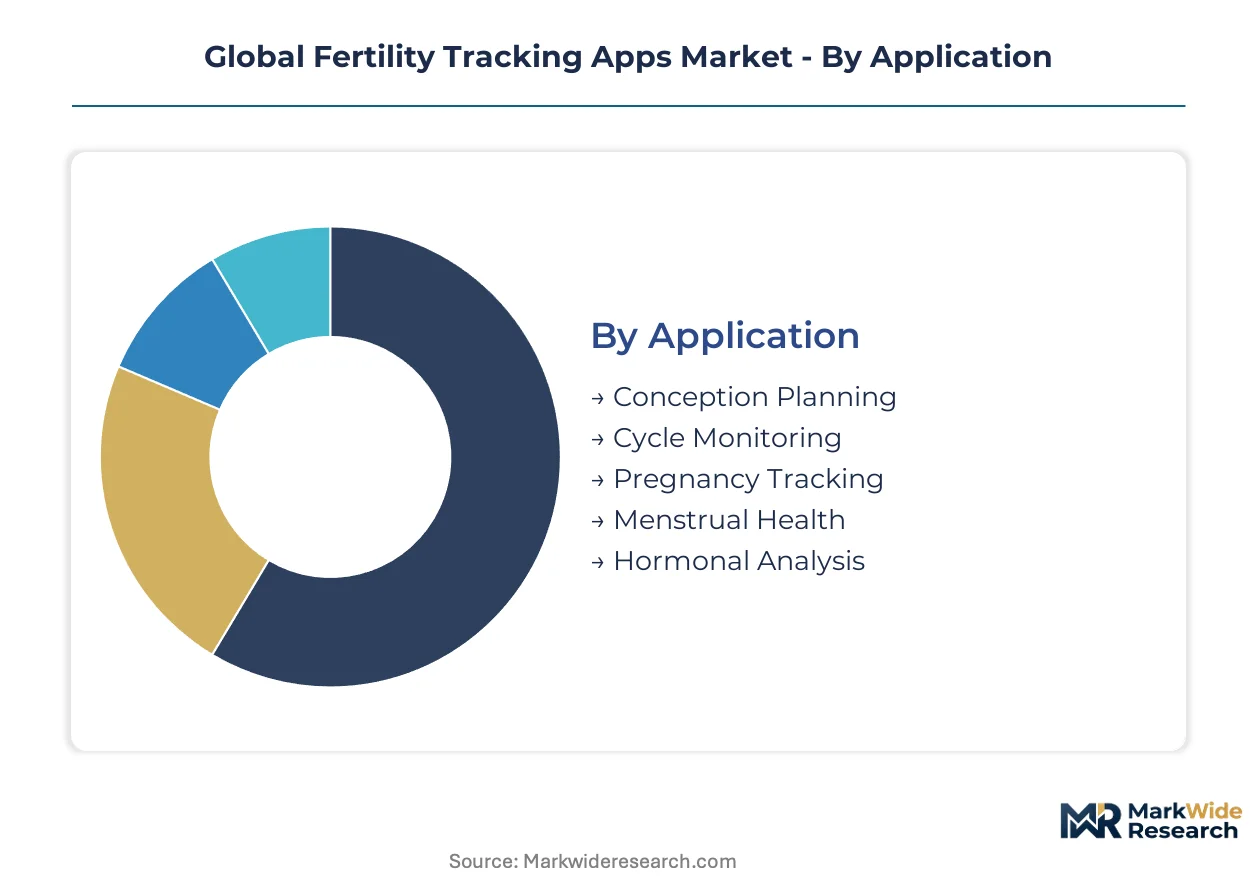
Fertility tracking apps fragment across four distinct axes that determine regulatory pathways, pricing power, and customer lifetime value. Solution architecture and technology stack choices shape compliance burdens and margin structures more acutely than in conventional health software markets.
Application:
Technology sophistication varies sharply across clinical use cases, with algorithm complexity scaling directly with diagnostic stakes.
- Conception Planning:Calendar-based ovulation window calculations represent the entry-level functionality where most users initiate engagement. Demand clusters in Germany and Japan where delayed childbearing demographics maximize the addressable population for timed intercourse tools.
- Cycle Monitoring:Longitudinal pattern recognition for irregular menstruation requires more sophisticated biomarker correlation and carries higher clinical liability. Fertility clinics in Denmark and the Netherlands deploy these modules for pre-IVF baseline assessments, driving premium pricing tolerance.
- Pregnancy Tracking:Gestational age calculators and fetal development timelines extend user retention post-conception.
- Menstrual Health:Symptom logging for endometriosis and PCOS screening attracts younger demographics with lower willingness-to-pay.
- Hormonal Analysis:Luteinizing hormone metabolite quantification through optical readers commands the highest per-test revenue in direct-to-consumer channels.
Cycle Monitoring leads on scale; Hormonal Analysis leads on momentum.
Solution Type:
Distribution economics and data residency requirements fragment competitive positioning across deployment models.
- Mobile Applications:Native iOS and Android clients dominate volume through minimal friction onboarding and direct-to-consumer app store distribution. HIPAA-compliant hosting in Virginia and Frankfurt creates geographic concentration risk for developers serving US and EU markets simultaneously.
- Wearable Integrations:Continuous nocturnal temperature logging through ring and patch form factors eliminates user compliance gaps. Japanese manufacturers anchor hardware supply, with PMDA review pathways creating certification bottlenecks for algorithm updates.
- Web-Based Platforms:Browser-based access serves enterprise fertility benefits administrators requiring SSO integration.
- SMS Services:Text-based reminders retain users in low-bandwidth markets with minimal smartphone penetration.
- Cloud Solutions:HIPAA-compliant architectures for fertility clinic data aggregation capture margin from institutional procurement.
Mobile Applications capture volume concentration; Wearable Integrations are climbing the fastest.
End User:
Procurement authority and reimbursement status create divergent customer acquisition economics across buyer types.
- Individual Consumers:Direct subscription purchases remain the revenue foundation, though free-to-premium conversion windows have compressed from 90 to 30 days. Urban saturation in London and Sydney is forcing outcome-based pricing experiments tied to confirmed conception.
- Fertility Clinics:Institutional procurement in Spain and Italy enables reimbursement coding for remote patient monitoring when data feeds integrate directly into electronic health records.
- Gynecological Centers:Specialist referrals drive higher trust conversion than digital advertising channels.
- Wellness Coaches:Affiliate distribution partnerships expand reach with revenue-sharing structures.
- Telehealth Providers:Platform licensing for virtual fertility consultations creates B2B recurring revenue streams.
Individual Consumers anchor revenue scale; Fertility Clinics show the steepest expansion trajectory.
Technology:
Algorithmic validation requirements under FDA and EU AI Act frameworks concentrate competitive advantage in technically sophisticated platforms.
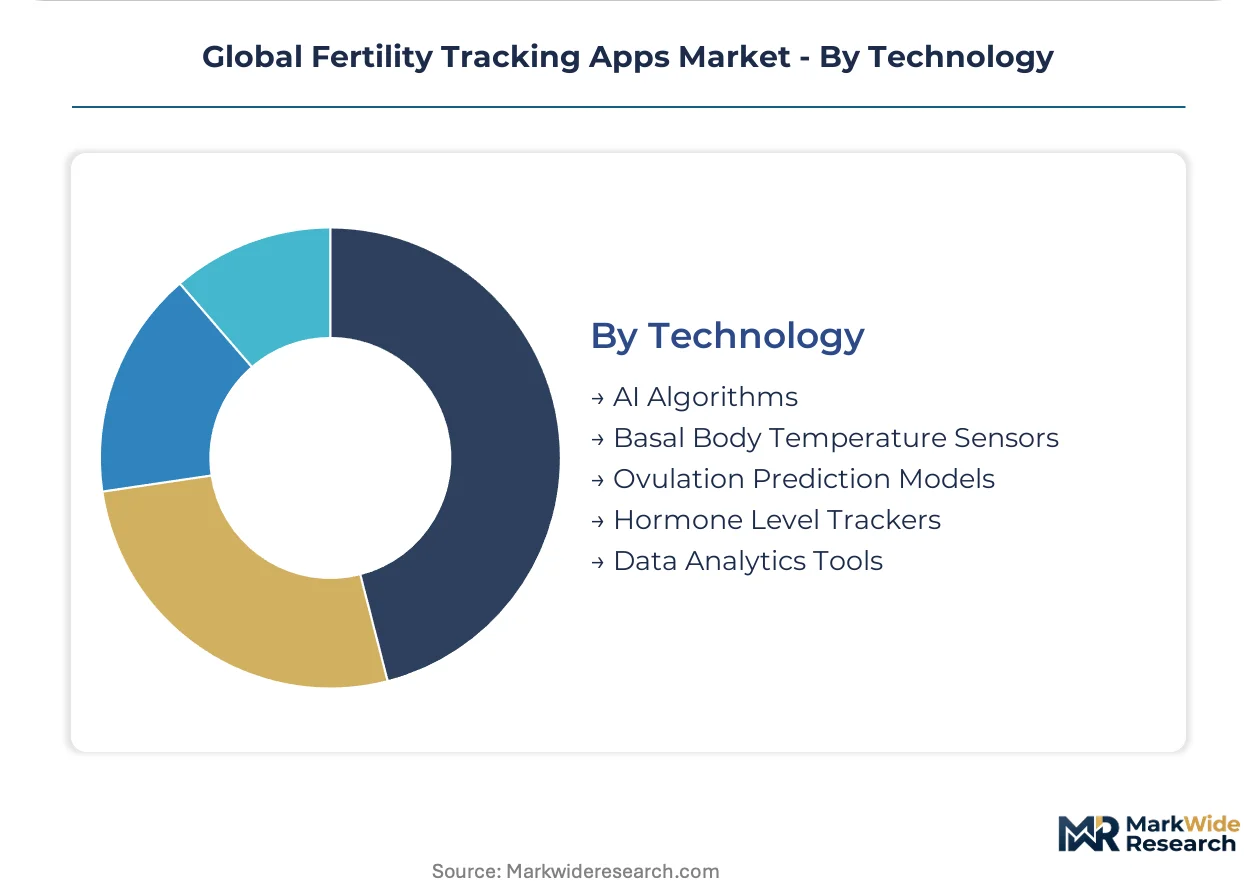
- AI Algorithms:Machine learning ovulation prediction requires biostatistician talent conversant in both reproductive endocrinology and FDA statistical review standards, with fewer than 200 qualified professionals globally. This scarcity filters market access to well-capitalized developers.
- Basal Body Temperature Sensors:Sub-millimeter thermistor integration into wearable form factors enables continuous logging without user intervention. German and Japanese hardware manufacturers dominate component supply.
- Ovulation Prediction Models:Rule-based calendar calculations face commoditization pressure from free alternatives.
- Hormone Level Trackers:Optical reader hardware for luteinizing hormone detection carries CE marking complexity under MDR.
- Data Analytics Tools:Population-level cycle pattern research attracts academic partnerships and grant funding.
AI Algorithms command margin concentration; Basal Body Temperature Sensors gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting development resources toward jurisdictions with clearer software-as-medical-device pathways. Developers are relocating algorithm validation teams from high-cost compliance zones to emerging markets where clinical trial costs compress evidence-generation timelines.
United States
Employer-sponsored fertility benefits and delayed childbearing demographics sustain consumer demand. FDA De Novo pathway expansion for fertility software classification accelerates 510(k) submissions for algorithm-based ovulation tools. Boston and San Francisco anchor venture capital concentration for digital health startups pursuing medical device status.
Germany
Federal Joint Committee reimbursement deliberations and CE marking bottlenecks under MDR create dual compliance pressures. EU AI Act high-risk system classification mandates notified body conformity assessments for fertility algorithms. Berlin and Munich host specialized regulatory consultancies serving scaled incumbents.
Japan
PMDA review pathways for basal body temperature sensor-linked apps establish certification benchmarks for hardware-software integration. Sub-millimeter thermistor manufacturers concentrate in Osaka and Nagoya industrial corridors. Tokyo-based fertility clinics pilot multimodal sensor fusion for pre-IVF cycle optimization.
India
CDSCO draft guidance for Software as Medical Device classification creates first-mover positioning for clinical validation partnerships. Bangalore and Hyderabad attract algorithm development teams seeking cost-advantaged biostatistician talent. Direct-to-consumer distribution bypasses reimbursement dependency in cash-pay wellness segments.
United Kingdom
Subscription fatigue among millennial users compresses free-to-premium conversion windows to 30 days. Outcome-based pricing experiments tied to confirmed conception emerge in London and Manchester urban markets. MHRA alignment with EU AI Act risk-tier frameworks preserves post-Brexit market access continuity.
Global Fertility Tracking Apps Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wearable hardware integration and perimenopause tracking adjacencies. The vendor base stratifies across three maturity tiers: CE-marked medical device holders, direct-to-consumer wellness platforms, and fertility clinic enterprise solutions. Strategic archetypes include algorithm-centric pure-plays, sensor-hardware hybridizers, and telehealth-integrated service bundles. Dominant competitive moves center on M&A for regulatory expertise acquisition and strategic partnerships with wearable manufacturers for continuous biometric logging.
Within the medical device tier, Natural Cycles and Flo Health exemplify divergent positioning strategies. Natural Cycles anchors European market access through CE-marked basal body temperature integration. Flo Health occupies scale-driven territory across cycle monitoring and hormonal analysis segments. Clue represents the open-data research archetype through menstrual health analytics partnerships. These three platforms collectively illustrate how regulatory compliance investment separates sustainable incumbents from attrition-vulnerable entrants.
| Leading Market Players |
|---|
| Glow |
| Kindara |
| Flo Health |
| Bearable |
| Ovia Health |
| Natural Cycles |
| Samphire Neuroscience |
| Embody |
| Clue |
| Others |
Supply & Pricing Matrix
Biostatistician scarcity in Boston and San Francisco clusters drives labor-cost differentials that widen pricing-tier spreads between FDA-validated premium platforms and unvalidated wellness apps. Cost compression in algorithm development centers on Bangalore and Hyderabad, where clinical validation partnerships reduce evidence-generation expenses.
Pricing Analysis
Direct-to-consumer app store distribution eliminates distributor margin layers entirely, compressing pricing spreads to subscription-tier differentiation alone. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked medical device holders from wellness platforms and free calendar tools. Price differentiation hinges on FDA software-as-medical-device certification and cloud hosting residency compliance. Pricing pressure stems from subscription fatigue shortening free-to-premium conversion windows. Individual consumers in saturated urban markets exhibit highest price sensitivity; fertility clinics purchasing enterprise cloud solutions show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand for basal body temperature sensor components from Japanese thermistor manufacturers in Osaka and Nagoya. Hardware-software integration feeds from German wearable designers and Indian algorithm development centers simultaneously. Component dependencies include sub-millimeter thermistors, HIPAA-compliant cloud hosting in Virginia and Frankfurt, and optical reader hardware for hormone detection. Single-source vulnerability concentrates in European notified body capacity for CE marking under MDR. Distribution runs through app store platforms for consumer segments and direct institutional sales for fertility clinic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fertility tracking apps rests on AI algorithm efficiency gains reducing cloud compute costs and premium-tier medical device certification commanding reimbursement eligibility.
For Market Incumbents: Extend regulatory certification moats through EU AI Act conformity assessments and PMDA review pathway completion before smaller competitors secure biostatistician talent. Deepen backward integration into wearable hardware partnerships with Japanese thermistor manufacturers to lock component supply. FDA De Novo pathway expansion threatens algorithm-only platforms; defend through multimodal sensor fusion investments. For New Entrants and Emerging Players: Enter via India's CDSCO emerging framework for Software as Medical Device classification, establishing clinical validation partnerships before multinational incumbents localize operations. Target perimenopause tracking for the 40-50 demographic as the most penetrable adjacent segment with higher price tolerance. Pursue telehealth integration APIs as the go-to-market angle for direct EHR data feeds into Spanish and Italian fertility clinics. For Investors and Strategic Acquirers: Large self-insured employers expanding fertility benefits packages represent the most active acquirer in this space through B2B2C platform licensing. Five-to-ten year viability favors scaled incumbents with dedicated regulatory affairs functions over outsourced compliance dependencies. Acquisition target archetype: algorithm-centric pure-plays with FDA 510(k) clearance or CE marking already secured. Watch Germany's Federal Joint Committee reimbursement deliberations as the signal for medical device tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates medical device classification for algorithm-based ovulation prediction tools in United States markets. |
| CE Marking Pathway | Unlocks European market access through notified body conformity assessments under EU AI Act high-risk system requirements. |
| Hospital System Partnership | Enables reimbursement coding for remote patient monitoring via direct EHR integration in Spanish fertility clinics. |
| Software Companion Development | Extends platform utility from conception planning into perimenopause tracking for 40-50 demographic retention. |
| Reimbursement Strategy | Positions digital fertility solutions for employer-sponsored benefits inclusion independent of traditional payer coverage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with reproductive endocrinologists, FDA regulatory affairs consultants, fertility clinic procurement managers, and digital health platform engineers with secondary validation. Primary sources included biostatisticians specializing in machine learning ovulation models, notified body assessors in Germany and France, and wearable hardware manufacturers in Japan. Secondary data drew from FDA 510(k) filings, EU AI Act technical documentation requirements, PMDA review pathway guidance, and CDSCO draft Software as Medical Device classifications. Bottom-up app revenue estimates and top-down digital health market sizing were triangulated for consistency.
Segment-weighting approaches distributed value across mobile applications, wearable integrations, and cloud solutions by procurement authority and reimbursement status. Technology stack choices, regulatory pathway complexity, and end-user price tolerance shaped the analytical framework across the projection horizon. CAGRs derived from algorithm adoption curves, sensor hardware miniaturization timelines, and reimbursement policy trajectory modeling. Fertility clinic enterprise adoption rates and employer-sponsored benefits expansion served as industry-specific forecast inputs.
Inputs from regulatory filing databases and clinical validation partnership announcements were available through the study window; gaps in private company revenue disclosures and early-stage algorithm performance metrics introduce uncertainty bands around market sizing. Forecasts reflect assumptions regarding FDA De Novo pathway processing speeds, EU notified body capacity constraints, and cloud infrastructure cost trajectories. Periodic stress-testing of base assumptions is recommended given reimbursement policy volatility and biostatistician labor market tightness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Industrial Gauges Market
Others
North America Flexographic Printing Market
Others
Global Sports and Fitness Wears Market
Others
Shisha Tobacco Market
Others
Industrial Air Pollution Control Solutions Market
Others
CAR T Cell Therapy Market
Others
Foldable Smartphone Market
Others
Solar Animal Repeller Market
Others
Cloud Advertising Market
Others
Latin America Fire Sprinklers Market
Others
Insoluble Sulfur Market
Others
Trusted Platform Module (TPM) Market
Others
Light Meter Market
Others
Pickup Truck Market
Others
Basketball Apparel Market
Others
India Home Automation Market