
 Hybrid Switchgear Market | 2026-2036
Hybrid Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Switchgear Market Intelligence
Data center operators and renewable developers are collapsing the historical procurement gap that separated utility-grade buyers from industrial purchasers. Mitsubishi Electric leverages its vacuum interrupter technology to anchor premium positions in East Asian substation retrofits. Siemens competes through modular GIS platforms that reduce footprint constraints in dense European urban corridors. Eaton differentiates via solid dielectric architectures that eliminate SF6 dependency for environmentally constrained North American utility procurement teams.
Hybrid switchgear integrates gas-insulated and air-insulated technologies within a single enclosure, typically combining SF6 or fluoronitrile gas for phase-to-ground insulation with vacuum interrupters for current breaking, achieving footprint reductions of sixty to seventy percent versus conventional AIS while maintaining outdoor accessibility for maintenance. Its primary purpose centers on medium and high-voltage power distribution where space constraints, environmental exposure, and reliability requirements converge in utility substations and industrial interconnections. Gas-insulated switchgear occupies the dominant value share due to established performance in high-voltage corridors above 145 kV, though sulfur hexafluoride free designs are accelerating as utilities face mounting regulatory pressure on greenhouse gas emissions. Renewable energy plants represent the fastest-expanding application segment, driven by offshore wind collector platforms and solar farm substations requiring compact, weather-resistant switching solutions.
The European F-Gas Regulation and EPA's proposed restrictions on SF6 emissions are forcing manufacturers toward alternative insulation chemistries and sealed-system designs that reduce leakage risk across product lifecycles. IEC 62271-203 and IEEE C37 series standards govern dielectric withstand, short-circuit ratings, and seismic performance, creating compliance barriers that favor established testing infrastructure over new market entrants. Stakeholders must monitor the pace of fluoronitrile commercialization and the evolving carbon-accounting rules that will determine whether SF6-free premiums convert into sustained procurement mandates or remain voluntary differentiation claims.
Market Dynamics
The European F-Gas Regulation and EPA's proposed SF6 emission restrictions are compressing product development cycles as manufacturers race to certify fluoronitrile and vacuum-based alternatives before procurement mandates harden into enforceable standards.
Growth Catalysts
- India's transmission expansion:State utilities are tendering for compact 145 kV hybrid installations to replace aging air-insulated substations in dense urban corridors, with CEA guidelines favoring gas-insulated designs for seismic zones.
- Offshore wind collector platforms:North Sea and East Asian developers specify weather-sealed hybrid switchgear to minimize platform footprint while maintaining 66 kV inter-array switching reliability.
- IEC 62271-203 tightening:Revised dielectric withstand and short-circuit ratings are disqualifying legacy designs, forcing replacement demand from utilities with 30-year-old AIS infrastructure.
Market Restraints
- SF6 gas supply concentration:Three chemical conglomerates control over 80% of refined sulfur hexafluoride production, exposing switchgear manufacturers to input cost volatility and allocation risk during semiconductor industry demand spikes.
- Fluorinated gas banking requirements:EU F-Gas Regulation mandates inventory tracking and leakage reporting across product lifecycles, adding compliance overhead that disadvantages smaller testing facilities.
- Air-insulated substation persistence:Rural utilities in price-sensitive markets continue specifying conventional AIS for greenfield 72 kV installations, delaying hybrid penetration in secondary distribution networks.
Strategic Opportunities
- China's ultra-high-voltage corridors:State Grid Corporation tenders for 800 kV and 1100 kV hybrid modules present premium positioning opportunities for manufacturers with seismic certification and local manufacturing partnerships.
- Data center campus substations:Hyperscale operators in Northern Virginia and Frankfurt are specifying SF6-free hybrid designs to meet internal carbon neutrality pledges ahead of regulatory mandates.
- Solid dielectric convergence:Integration of epoxy resin insulation with vacuum interrupters eliminates gas handling entirely, opening municipal utility procurement channels previously closed to fluorinated technologies.
Industry Challenges
- Seismic certification bottlenecks:IEEE 693 and IEC 62271-203 high-level testing requires specialized shake-table infrastructure concentrated in Japan, Germany, and the United States, creating 18-month approval queues for new product variants.
- Field service technician scarcity:Gas handling certification and vacuum interrupter maintenance protocols demand specialized training that utilities have deferred during decades of AIS dominance, constraining deployment velocity.
- Legacy protection relay integration:Hybrid switchgear digital control architectures require protocol translation layers to interface with electromechanical relay installations common in 1980s-era substations, complicating retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Switchgear Market |
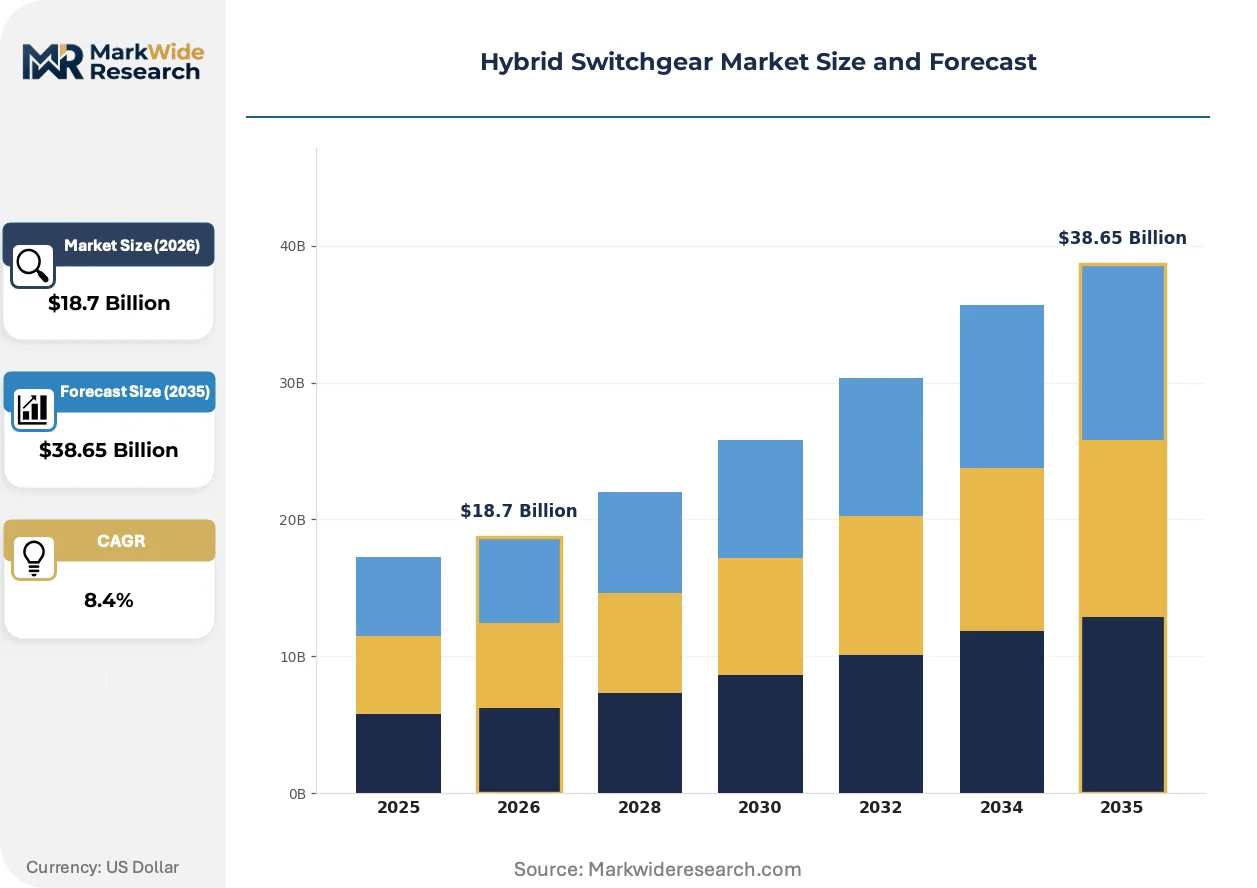
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas-Insulated Switchgear, Air-Insulated Switchgear, Vacuum Circuit Breaker, Solid Dielectric, Sulfur Hexafluoride Free Application: Power Generation, Data Centers, Renewable Energy Plants, Telecommunications, Railway Systems End User: Electric Utilities, Manufacturing Plants, Commercial Complexes, Institutional Facilities Installation Type: Indoor, Outdoor, Subsurface, Mobile, Modular |
| Companies Covered | Mitsubishi Electric, Toshiba, Hitachi Energy, Schneider Electric, Eaton, Siemens, GE Vernova, Hyundai Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Switchgear Market Strategic Shifts & Innovations
Technology substitution and regulatory compression are converging to redefine competitive advantage around sealed-system reliability and carbon-accounting transparency rather than incremental performance metrics.
Vacuum interrupter technology is displacing SF6-based current breaking in medium-voltage hybrid designs up to 145 kV, with European utilities specifying all-vacuum modules for urban distribution retrofits where footprint constraints and environmental exposure coincide. Siemens and Mitsubishi Electric have accelerated testing protocols to capture this specification shift before F-Gas Regulation Phase-Down mandates take full effect in 2030.
The EPA's proposed Significant New Use Rule for SF6 would classify switchgear emissions as reportable under greenhouse gas inventory requirements, forcing US utilities to quantify leakage rates across installed bases. Investor-owned utilities in California and New York are pre-empting this friction by writing SF6-free procurement preferences into 2025-2027 capital plans, compressing the viable commercial window for conventional gas-insulated designs.
Integrated asset performance contracts are replacing discrete equipment sales in European and North American utility procurement, with vendors assuming 15-year availability guarantees in exchange for lifecycle revenue streams. This model concentrates in offshore wind and data center interconnections where downtime costs dwarf capital expenditure premiums, rewarding manufacturers with predictive maintenance telemetry and regional service depot networks.
Hybrid Switchgear Market Segmentation
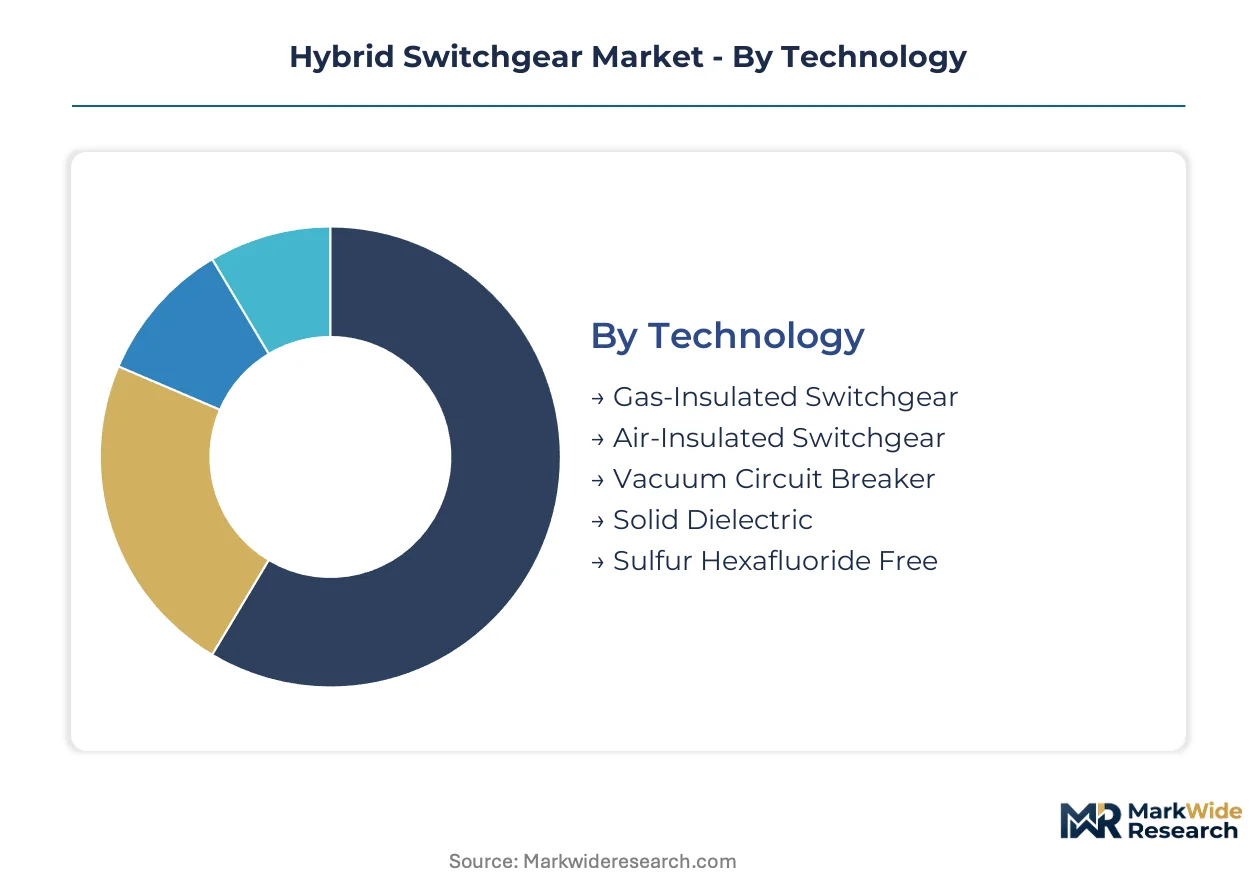
Technology choices in hybrid switchgear determine capital intensity, regulatory exposure, and service lifecycle economics. Application segmentation reveals divergent procurement patterns between carbon-constrained hyperscale operators and reliability-focused electric utilities. Understanding these splits enables targeted positioning across insulation chemistry, installation architecture, and end-user contracting models.
Technology:
Domestic production of vacuum interrupters concentrates in Japan and Germany, while fluoronitrile blending for SF6-free designs relies on Belgian and US chemical supply chains. Export-led segments face longer certification queues but capture premium pricing in regulated European markets.
- Gas-Insulated Switchgear:SF6 or fluoronitrile gas insulates phase-to-ground clearances within sealed aluminum enclosures, achieving dielectric ratings above 145 kV in footprints one-third of air-insulated equivalents. Demand clusters in China's State Grid ultra-high-voltage corridors and India's urban transmission retrofits where seismic zoning and land scarcity converge.
- Vacuum Circuit Breaker:Ceramic-enclosed vacuum interrupters extinguish arcs without gas handling, enabling maintenance intervals exceeding twenty years. European utilities specify these modules for metropolitan distribution substations facing F-Gas Regulation compliance deadlines and public opposition to fluorinated chemistries.
- Air-Insulated Switchgear:Conventional open-air bus and breaker assemblies dominate rural greenfield installations in price-sensitive markets.
- Solid Dielectric:Epoxy resin insulation eliminates gas systems entirely, attracting municipal utilities with simplified permitting.
- Sulfur Hexafluoride Free:Alternative gas blends and vacuum-only architectures address carbon accounting requirements in California and New York procurement mandates.
Gas-Insulated Switchgear holds the largest share; momentum sits with Sulfur Hexafluoride Free designs as procurement mandates harden.
Application:
Volume concentration varies sharply by project scale—offshore wind platforms demand containerized modular systems while data centers prioritize indoor walk-in configurations with integrated monitoring.
- Power Generation:Thermal and nuclear plant switchyards require seismic-qualified hybrid modules with 63 kA short-circuit withstand ratings. Japanese utilities specify these for coastal installations facing tsunami exposure and stringent METI reliability standards.
- Renewable Energy Plants:Solar farm substations and offshore wind collector platforms demand weather-sealed, compact switching with remote telemetry integration. North Sea developers in Denmark and Germany specify these for unmanned platform operations where helicopter access costs dominate lifecycle economics.
- Data Centers:Hyperscale operators in Northern Virginia and Frankfurt prioritize SF6-free indoor designs to meet internal carbon neutrality timelines.
- Telecommunications:Mobile network switching centers specify small-footprint outdoor installations for grid-edge redundancy.
- Railway Systems:Traction power substations along high-speed corridors require electromagnetic compatibility shielding and vibration resistance.
Power Generation commands the greatest installed base; Renewable Energy Plants are climbing the fastest as offshore wind capacity targets accelerate.
End User:
Contracting sophistication divides this category—electric utilities negotiate fifteen-year availability guarantees while commercial buyers prioritize capital expenditure minimization.
- Electric Utilities:Investor-owned and state-owned grid operators specify IEC 62271-203 certified equipment with integrated asset performance contracts. India's CEA guidelines and Germany's F-Gas banking requirements shape procurement documentation and lifecycle compliance obligations.
- Manufacturing Plants:Automotive and semiconductor fabs demand high-reliability indoor installations with arc-flash containment and cleanroom-compatible gas handling protocols.
- Commercial Complexes:Airport and hospital campuses specify modular outdoor designs with reduced footprint for constrained urban substations.
- Institutional Facilities:University and government campuses prioritize visible sustainability credentials in SF6-free specifications.
Electric Utilities absorb the majority of volume; Manufacturing Plants show steepest expansion trajectory as fab construction accelerates in Arizona and Saxony.
Installation Type:
Cost tier stratification is pronounced—subsurface installations command triple the engineering premium of standard outdoor designs due to waterproofing and ventilation complexity.
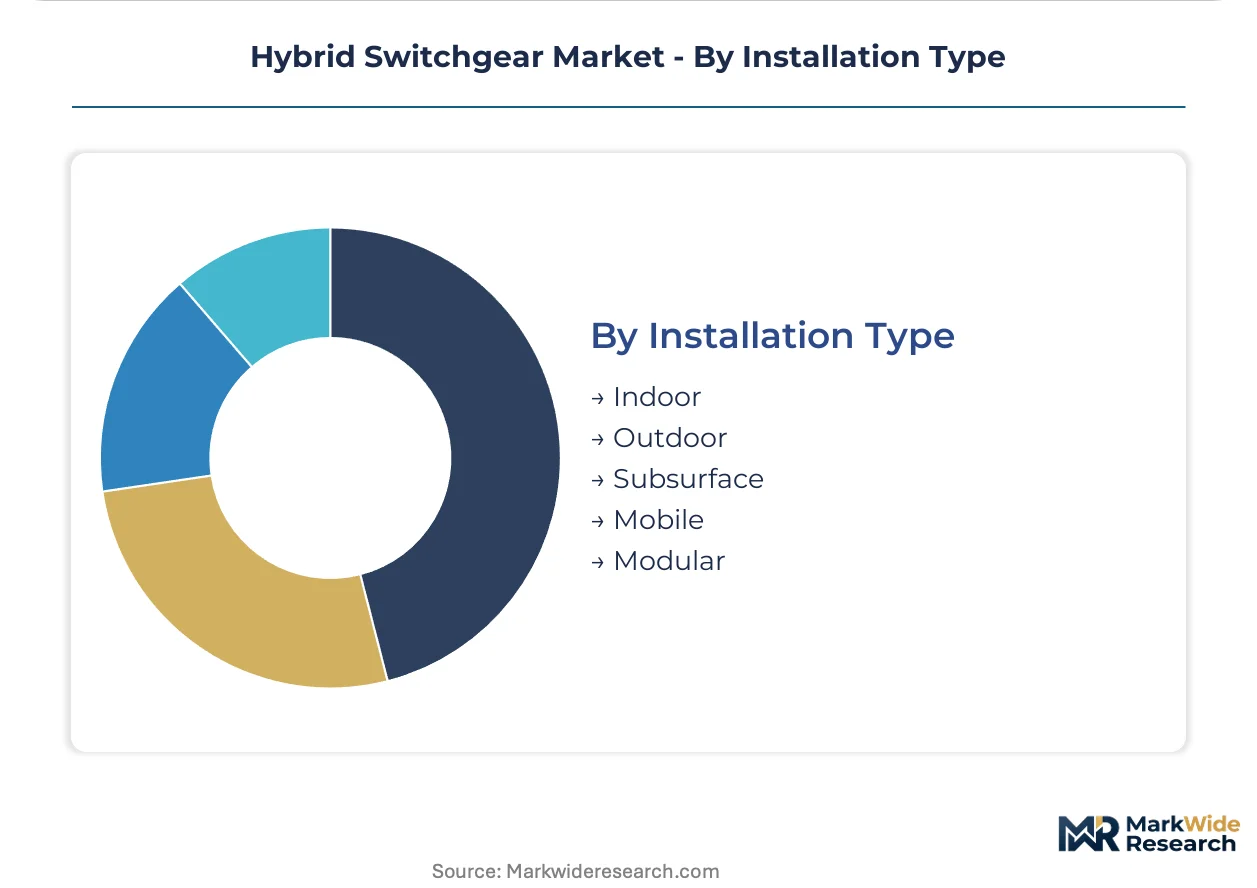
- Outdoor:Walk-in enclosures with IP54 weatherproofing dominate transmission substations and renewable interconnections. These configurations balance accessibility for maintenance against exposure to seismic and climatic loading across Japanese coastal zones and Indian monsoon regions.
- Modular:Factory-integrated skid-mounted systems compress field commissioning from months to weeks. Data center operators in Loudoun County and Frankfurt specify these for phased capacity expansion aligned with server deployment timelines.
- Indoor:Controlled-environment installations suit manufacturing and commercial settings with existing building infrastructure.
- Subsurface:Below-grade vault installations address extreme land constraints in dense Asian megacities.
- Mobile:Trailer-mounted emergency replacement units serve utility storm response and temporary construction power.
Outdoor configurations retain dominant share; Modular designs gain share fastest as speed-to-operations becomes a primary procurement criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in East Asian manufacturing clusters and European engineering centers, with demand fragmentation across transmission utilities, renewable developers, and data center operators. Three chemical conglomerates dominate refined SF6 production, creating input cost exposure for switchgear fabricators worldwide. Certification bottlenecks at specialized shake-table facilities in Japan, Germany, and the United States extend approval timelines for seismic-rated designs.
China
State Grid Corporation tenders for 800 kV and 1100 kV hybrid modules anchor ultra-high-voltage corridor expansion. MEE dual carbon goals and GB standards for SF6 emissions accelerate fluoronitrile adoption timelines. Yangtze River Delta manufacturing clusters around Shanghai supply vacuum interrupter components for domestic and export markets.
India
CEA guidelines favor gas-insulated designs for seismic zones, driving 145 kV hybrid installations in dense urban corridors. PLI scheme incentives for power transmission equipment attract foreign joint ventures. Maharashtra and Gujarat transmission utilities tender for compact substations to replace aging air-insulated infrastructure in Mumbai and Ahmedabad metropolitan zones.
Germany
EU F-Gas Regulation Phase-Down mandates compress viable commercial windows for conventional SF6 designs. ECHA registration requirements for alternative insulation chemistries favor established testing infrastructure. North Rhine-Westphalia industrial clusters around Dortmund and Essen specialize in modular GIS platforms for European urban retrofit projects.
United States
EPA Significant New Use Rule proposals classify switchgear emissions as reportable greenhouse gas inventory items. FERC interconnection standards and IEEE C37 series compliance shape procurement documentation for investor-owned utilities. Northern Virginia data center clusters in Loudoun County specify SF6-free hybrid designs to meet internal carbon neutrality timelines.
Japan
METI reliability standards and tsunami exposure requirements drive seismic-qualified hybrid module specifications for coastal installations. JIS certification protocols and specialized shake-table infrastructure create 18-month approval queues for new product variants. Kanto region utilities around Tokyo specify vacuum interrupter technology for metropolitan distribution substations facing space constraints.
Hybrid Switchgear Market Key Industry Players
Concentration sits with diversified electrical equipment conglomerates that command integrated manufacturing, testing infrastructure, and regional service networks. The vendor base spans three tiers: integrated multinationals with full voltage-range portfolios, regional specialists with country-specific certification depth, and component suppliers seeking downstream integration. Strategic archetypes include vacuum interrupter technology anchors, modular GIS platform providers, and solid dielectric pioneers eliminating gas dependency. Competitive moves center on fluoronitrile commercialization partnerships and predictive maintenance telemetry integration to capture lifecycle revenue streams.
Within the integrated multinational tier, Mitsubishi Electric, Siemens, and Eaton exemplify divergent technical positioning. Mitsubishi Electric anchors premium positions through vacuum interrupter manufacturing depth. Siemens occupies modular platform territory with footprint-optimized designs. Eaton represents solid dielectric convergence, eliminating SF6 handling for environmentally constrained procurement channels.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| Toshiba |
| Hitachi Energy |
| Schneider Electric |
| Eaton |
| Siemens |
| GE Vernova |
| Hyundai Electric |
| ABB |
| Others |
Cost & Logistics Intelligence
Eighteen-month seismic certification queues at specialized shake-table facilities in Japan, Germany, and the United States compress inventory flexibility for hybrid switchgear manufacturers, amplifying pricing power for certified suppliers while forcing buyers into longer-term contracting to secure allocation.
Pricing Analysis
EU F-Gas Regulation Phase-Down mandates dictate the pricing tier structure across the hybrid switchgear market, separating premium fluoronitrile-certified designs from standard SF6-dependent systems and economy-grade air-insulated alternatives. Price differentiation rests on seismic certification grade and integrated asset performance contracting, with utilities in California and New York showing lowest price sensitivity due to internal carbon neutrality timelines while rural Indian state utilities exhibit highest sensitivity, prioritizing capital expenditure minimization over lifecycle guarantees. Cost compression in the standard tier is intensifying as fluoronitrile commercialization accelerates and procurement mandates harden.
Supply Chain Analysis
Eighteen-month approval queues at specialized shake-table facilities concentrate supply chain risk for seismic-rated hybrid modules, with vacuum interrupter production anchored in Japan and Germany and fluoronitrile blending dependent on Belgian and US chemical supply chains. Manufacturing draws from refined sulfur hexafluoride feedstock controlled by three chemical conglomerates, ceramic vacuum interrupter enclosures, and aluminum casting for sealed enclosures. Single-source vulnerability in SF6 refining exposes switchgear fabricators to allocation risk during semiconductor industry demand spikes. Distribution runs through direct utility procurement channels, EPC contractor specifications, and regional service depot networks for integrated lifecycle contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid switchgear market sits in early-cycle expansion as F-Gas Regulation Phase-Down mandates and EPA Significant New Use Rule proposals compress the viable commercial window for conventional SF6 designs, accelerating substitution toward fluoronitrile and solid dielectric alternatives.
For Market Incumbents: Secure shake-table certification capacity at Japanese, German, and US testing facilities to defend against emerging entrants lacking seismic qualification infrastructure. Anchor backward integration into vacuum interrupter manufacturing to insulate margin pressure from ceramic enclosure supply concentration, while pre-empting fluoronitrile commercialization partnerships before procurement mandates harden into enforceable standards.
For New Entrants and Emerging Players: Predictive maintenance telemetry integration represents a service-layer gap where incumbents under-serve municipal utilities and smaller industrial offtakers lacking in-house diagnostic capabilities. Target solid dielectric architectures for North American municipal procurement channels previously closed to fluorinated technologies, entering through outcome-based availability contracts that transfer operational risk from cash-constrained buyers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because carbon-accounting rules and F-Gas banking requirements are structurally advantaging sealed-system reliability over incremental performance metrics. Acquisition focus should center on regional specialists with country-specific certification depth and established testing infrastructure, particularly those with seismic qualification in high-growth corridors. The signal to watch is the pace of fluoronitrile commercialization partnerships announced by major chemical suppliers, indicating whether SF6-free premiums convert into sustained procurement mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Certification Investment | Secures 18-month approval queue priority at Japanese and German shake-table facilities for State Grid tenders. |
| Fluorinated Gas Banking Compliance | Enables EU market access under F-Gas Regulation Phase-Down mandates with inventory tracking infrastructure. |
| Predictive Maintenance Telemetry Integration | Captures 15-year lifecycle revenue streams from offshore wind and data center availability contracts. |
| Solid Dielectric Architecture Development | Eliminates SF6 dependency for California and New York utility procurement teams facing EPA reporting requirements. |
| Regional Service Depot Expansion | Supports integrated asset performance contracts where downtime costs dwarf capital expenditure premiums. |
Research Approach
Operator-level perspectives from utility planning officers, EPC contractor project managers, substation maintenance directors, and power transmission procurement leads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across IEC 62271-203 certification databases, FERC interconnection filings, EU F-Gas Regulation compliance registries, and CEA tender documentation. Bottom-up project pipeline assessment triangulated against top-down transmission capital expenditure forecasts from national grid operators.
Sensitivity analysis across insulation chemistry adoption curves, seismic certification approval timelines, and fluoronitrile commercialization trajectories shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include technology type, application vertical, end-user contracting sophistication, and installation architecture complexity. CAGRs derived from utility capital plan trajectories, renewable interconnection queue data, and data center power demand projections, with cross-reference to substation retrofit cycle analysis and offshore wind capacity targets.
Forecasts assume regulatory continuity in EU F-Gas Regulation Phase-Down schedules and EPA Significant New Use Rule implementation; material policy acceleration or delay would require re-modeling. Substitution risk from solid dielectric convergence and vacuum-only architectures, plus raw material allocation shocks in refined sulfur hexafluoride supply, represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Animal Feed Protein Ingredients Market
Others
ASEAN Agricultural Logistics Market
Others
Global Wireless Asset Management Market
Others
Data Center CPU Market
Others
Social Media Engagement Applications Market
Others
Middle East 3D Printing Construction Market
Others
Air Separation Plant Market
Others
China Online Gambling Market
Others
Global Solder Balls Market
Others
Egg Market
Others
United States Indoor LBS Market
Others
Global Recruitment and Staffing Market
Others
Nonlinear Editing System Market
Others
Insoluble Sulfur Market
Others
Middle East Location-Based Services Market
Others
Folding Screen Mobile Phone Market