
 Next Gen Video Codecs Market | 2026-2036
Next Gen Video Codecs Market Size, Share, and Industry Trends Forecast 2026-2036
Next Gen Video Codecs Market Intelligence
Adherence to the Alliance for Open Media's AV1 specification is redrawing the competitive landscape for video compression. Intel leverages its silicon design expertise to integrate hardware decoding capabilities for this new standard. ByteDance drives adoption through its massive-scale implementation across its social media applications. Meanwhile, Cisco Systems specializes in developing low-latency codecs optimized for its enterprise video conferencing solutions.
Next-generation video codecs are advanced algorithms that compress digital video data for efficient storage and transmission. They achieve compression ratios up to 50% greater than legacy standards like H.264 while maintaining equivalent visual quality. The royalty-free AV1 codec is rapidly gaining share within the streaming application segment. In contrast, HEVC maintains a strong foothold in broadcasting and digital cinema, where established licensing structures and hardware ecosystems persist.
The market is heavily influenced by patent licensing bodies like MPEG LA and Velos Media, which govern the use of patented technologies within codecs like HEVC. Concurrently, standards organizations such as the ISO/IEC and ITU-T define the technical specifications that ensure interoperability. The critical decision for stakeholders involves balancing the cost of licensing against the performance and ecosystem maturity of competing codec technologies.
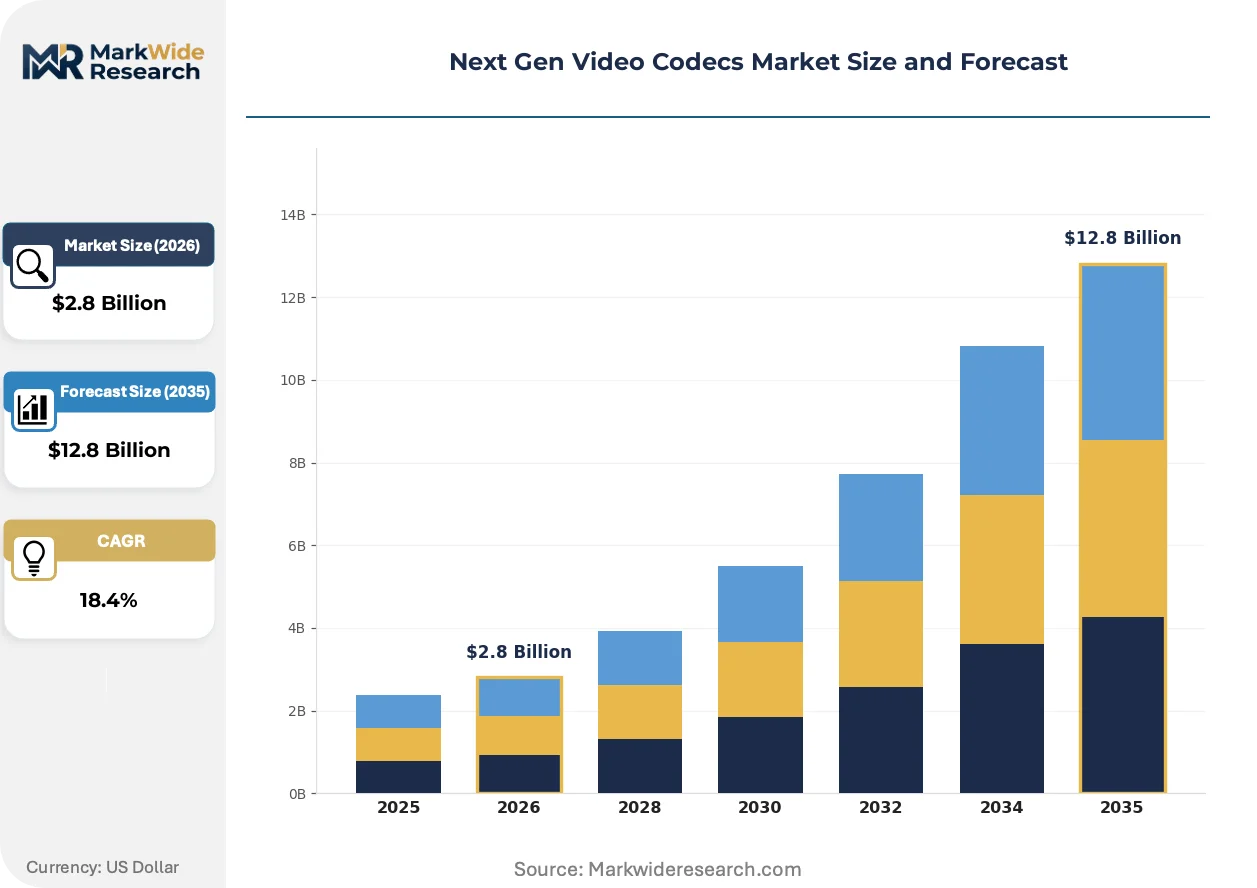
Market Dynamics
The fundamental tension between royalty-free standards like AV1 and patent-encumbered codecs such as HEVC is reshaping competitive positioning. This dynamic forces stakeholders to weigh open access and ecosystem momentum against established performance and licensing structures.
Growth Catalysts
- UHD Content Demand:The proliferation of 4K and 8K content on streaming platforms requires codecs with superior compression efficiency to manage bandwidth costs.
- Mobile-First Markets:Growth in mobile video in countries like India and China fuels demand for codecs that minimize data usage on cellular networks.
- Royalty-Free Standards:The Alliance for Open Media's AV1 specification provides a non-patented alternative, removing licensing barriers for device makers and platforms.
Market Restraints
- Complex Licensing:Patent pools like MPEG LA create significant licensing costs and legal uncertainty for implementers of codecs such as HEVC.
- High Computational Cost:Next-gen codecs demand substantial processing power for encoding, increasing operational costs for content creators and live streaming platforms.
- Legacy Hardware Inertia:The vast installed base of devices with hardware decoders for older standards like H.264 slows the market-wide transition.
Strategic Opportunities
- Low-Latency Streaming:The market for interactive applications like cloud gaming creates an opportunity for codecs optimized for minimal delay.
- AI-Enhanced Encoding:Integrating machine learning for content-aware compression improves efficiency by allocating bits intelligently based on scene complexity.
- Emerging Market Access:Expanding broadband in Southeast Asia and Africa opens markets for high-efficiency video services on data-sensitive networks.
Industry Challenges
- Patent Thicket Navigation:Implementers face significant legal risk and complexity in navigating the dense and overlapping patent claims surrounding newer standards like Versatile Video Coding (VVC).
- Backward Compatibility:Ensuring a seamless user experience during the transition requires maintaining support for multiple codecs, adding complexity to software and hardware development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Gen Video Codecs Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AV1, HEVC, VP9, MPEG-4 Application: Streaming, Broadcasting, Video Conferencing, Digital Cinema End User: Media Companies, Streaming Platforms, Telecom Providers, Enterprises Delivery Mode: Cloud-Based, On-Premises, Hybrid, SaaS |
| Companies Covered | CommScope, ByteDance, Cisco Systems, Intel, Qualcomm, Bitmovin, Harmonic, Hikvision, Motorola Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Gen Video Codecs Market Strategic Shifts & Innovations
The evolution of video compression is shifting from monolithic hardware standards toward more adaptable, software-defined, and AI-driven approaches. This transition prioritizes algorithmic flexibility and cloud-native deployment models over fixed-function silicon for specific codecs.
Hardware-accelerated codec blocks are dedicated circuits within a System-on-Chip (SoC) that offload CPU-intensive encoding and decoding tasks. SoC designers for mobile phones, smart TVs, and streaming devices are rapidly adopting these blocks for power efficiency. This core video processing logic is miniaturizing, enabling its integration into a wider array of power-constrained consumer electronics and edge computing devices.
European Union policies, such as those related to the Digital Markets Act, promote greater platform interoperability. These regulatory pressures indirectly favor the use of open, royalty-free standards to ensure seamless content exchange across different digital ecosystems. Large streaming services and device manufacturers operating within the EU are consequently increasing their investment in AV1 implementation to comply with these principles.
A notable shift involves media companies adopting consumption-based pricing for cloud encoding services over perpetual software licenses. This model disrupts on-premise hardware vendors by offering a scalable, opex-based alternative. The trend is most prominent among media startups in North America avoiding large capital investments.
Next Gen Video Codecs Market Segmentation
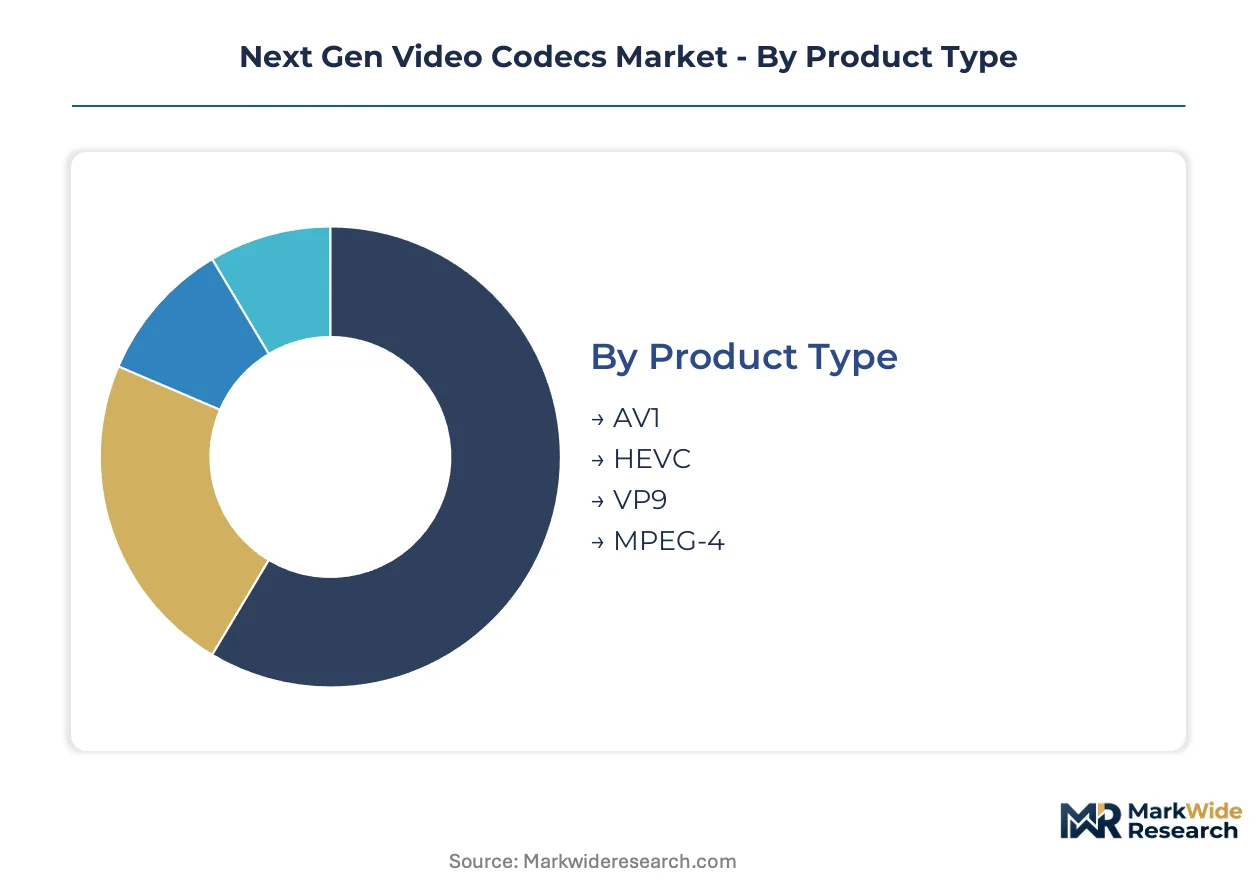
The Next Gen Video Codecs Market segmentation reveals the diverse technological approaches and application demands shaping industry evolution. Understanding these distinct segments allows for precise targeting of solutions and strategic investment in emerging areas.
Product Type:
Margin pools within this category are shifting from established, patent-encumbered codecs towards royalty-free alternatives that offer ecosystem flexibility.
- AV1:This royalty-free, open-source video coding format developed by the Alliance for Open Media delivers superior compression efficiency, often exceeding HEVC. Demand concentrates heavily within streaming platforms like YouTube and Netflix, particularly for 4K and 8K content delivery in mobile-first markets such as China.
- HEVC:High Efficiency Video Coding provides significant compression gains over H.264 but involves complex patent licensing structures. Its demand remains strong in broadcasting and digital cinema, where established hardware ecosystems and content workflows persist.
- VP9:Google developed this open and royalty-free video compression standard, primarily utilized by YouTube for its vast video content delivery.
- MPEG-4:An older, widely adopted standard, MPEG-4 remains relevant for legacy hardware compatibility and lower-resolution content streams across various devices.
HEVC holds installed capacity. AV1 is rotating up the share rankings.
Application:
Cost efficiency across various applications significantly influences codec selection, with real-time use cases prioritizing low latency and minimal processing overhead.
- Streaming:This segment involves delivering video content over IP networks, often leveraging adaptive bitrate technologies for varying network conditions. Demand for streaming codecs is intense for global platforms like Netflix and ByteDance, driven by 4K and 8K content proliferation.
- Video Conferencing:This application demands extremely low-latency codecs to ensure real-time, interactive communication without noticeable delays. Enterprises increasingly seek optimized solutions for remote collaboration tools and virtual meeting platforms.
- Broadcasting:Traditional television and radio broadcasters utilize codecs for efficient transmission of high-quality video signals to mass audiences. This segment maintains a strong preference for established, robust standards with proven reliability.
- Digital Cinema:This segment focuses on the high-fidelity encoding and distribution of feature films for theatrical exhibition and archival purposes. Codecs must support pristine visual quality and professional workflows.
Streaming continues to expand its footprint. Video Conferencing is gaining momentum.
End User:
Application complexity and scale define the volume requirements for codecs, with large content providers and platforms driving significant deployment.
- Streaming Platforms:These entities, such as Netflix and TikTok, manage vast libraries of video content and require highly efficient codecs for global delivery to diverse devices. Demand is concentrated on reducing bandwidth costs while maintaining high quality for their subscribers.
- Media Companies:This group includes content creators, production studios, and distributors that generate and manage large volumes of video assets. They require codecs for efficient archiving, editing workflows, and multi-platform distribution.
- Telecom Providers:These companies manage network infrastructure and deliver video services, necessitating codecs that optimize data usage over cellular and fixed broadband networks. Their focus is on minimizing data consumption for mobile-first markets.
- Enterprises:Businesses use video codecs for internal communications, training, and remote collaboration tools. Companies like Cisco Systems develop specialized low-latency codecs for their video conferencing solutions.
The shift towards digital content consumption is driving demand in Streaming Platforms.
Delivery Mode:
The volume of content processed dictates the preferred delivery mode, with cloud-based solutions offering scalability for dynamic workloads.
- Cloud-Based:This mode utilizes remote servers and infrastructure for encoding, decoding, and streaming video content, offering scalability and flexibility. Media startups in North America increasingly adopt this model to avoid large capital investments in hardware.
- On-Premises:This involves deploying and managing codec hardware and software directly within an organization's own data centers. Broadcasting operations often prefer this mode for greater control over data and security.
- Hybrid:This approach combines elements of both cloud-based and on-premises solutions, allowing organizations to balance scalability with control. Large organizations often use hybrid models for specific workloads.
- SaaS:Software-as-a-Service models provide video encoding and decoding capabilities as a subscription service, abstracting infrastructure management from the end-user. This model is popular for managed encoding services.
Cloud-Based is expanding its market presence due to its inherent scalability and operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global digital infrastructure underwrites the widespread adoption of next-gen video codecs. This technological shift enables efficient content delivery across diverse markets. The market dynamics vary significantly by region, influenced by local demand and regulatory frameworks.
China
China's mobile-first video consumption, particularly on platforms like ByteDance, drives immense demand for efficient codecs. The MIIT promotes digital infrastructure development, accelerating codec integration. The Yangtze River Delta region, including cities like Shanghai, spearheads codec deployment for streaming services.
United States
The United States market sees high demand from major streaming platforms like Netflix and YouTube for 4K and 8K content delivery. The FCC's focus on broadband infrastructure indirectly supports codec efficiency for data management. Silicon Valley in California remains a primary hub for advanced codec research and commercialization.
India
India's rapidly expanding mobile video market fuels demand for codecs that minimize data usage on cellular networks. The TRAI's initiatives for digital inclusion underscore the need for efficient video transmission. Bengaluru's tech ecosystem focuses on developing localized streaming solutions optimized with next-gen codecs.
Germany
Germany's broadcasting sector and enterprise video conferencing solutions require robust and efficient codecs. European Union policies like the Digital Markets Act encourage the adoption of open, royalty-free standards. Munich's media technology firms actively integrate advanced codecs for European content distribution.
South Korea
South Korea's advanced 5G networks and strong consumer demand for high-resolution content, including 8K broadcasting, necessitate sophisticated codecs. The Korea Communications Commission supports digital innovation and 5G deployment, impacting codec adoption. The Seoul Capital Area drives innovation in codec-enabled immersive media experiences.
Next Gen Video Codecs Market Key Industry Players
Listed leaders compete with private specialists across technological innovation and market reach. The market structure remains fragmented, characterized by a tiered landscape of players. Strategic archetypes include silicon designers, streaming platform integrators, and enterprise solution providers. Companies engage in strategic partnerships and technology licensing to expand their capabilities.
Within the streaming platform integrator tier, ByteDance exemplifies the massive-scale adoption of AV1 across social media applications. Cisco Systems occupies a position among enterprise solution providers, specializing in low-latency codecs for video conferencing. Intel represents a silicon design expertise archetype, integrating hardware decoding capabilities for new standards like AV1.
| Leading Market Players |
|---|
| CommScope |
| ByteDance |
| Cisco Systems |
| Intel |
| Qualcomm |
| Bitmovin |
| Harmonic |
| Hikvision |
| Motorola Solutions |
| Others |
Cost & Logistics Intelligence
Licensing agreements for proprietary codecs and consumption-based pricing for cloud encoding lock in both supply access and price visibility for next-gen video codecs. This market's structure reflects a balance between established intellectual property and emerging open standards.
Pricing Analysis
Volume-discount tiering structures characterize pricing for cloud encoding services. SaaS-tiered subscriptions and per-unit transactional models are common pricing models. Price differentiation stems from compression efficiency, specific feature sets like low latency, and the scale of content processed. Pricing pressure originates from the proliferation of royalty-free alternatives like AV1. Streaming platforms represent the most price-sensitive buyers, while digital cinema applications prioritize quality over cost.
Supply Chain Analysis
Just-in-time software development and hardware integration define the supply chain for next-gen video codecs. Core intellectual property development concentrates in the United States, China, and South Korea. Specialized hardware accelerators and cloud infrastructure form critical component dependencies. Patent thicket navigation presents a significant structural risk for implementers. Distribution runs through direct licensing agreements and cloud-based software delivery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection, driven by the shift towards open, royalty-free codecs and enhanced interoperability across digital ecosystems.
For Market Incumbents: Consolidate intellectual property by acquiring specialist codec firms. Invest heavily in hardware acceleration for emerging open standards like AV1 to counter the threat from cloud-native disruptors. Diversify revenue streams by offering managed cloud encoding services. Control distribution channels through strategic partnerships with major streaming platforms.
For New Entrants and Emerging Players: Low-latency optimization for interactive applications presents a service-layer gap. Target the rapidly growing cloud gaming and enterprise video conferencing segments. Offer AI-enhanced encoding solutions with consumption-based pricing models. Penetrate emerging markets in Southeast Asia and Africa by providing data-efficient video services.
For Investors and Strategic Acquirers: Capital is best deployed toward firms specializing in AI-enhanced encoding and royalty-free codec development. Focus on acquiring software companies with strong intellectual property in compression algorithms or hardware integration capabilities. A significant signal to watch is the widespread integration of AV1 hardware decoding across a broader range of consumer electronics over the next decade.
| Strategic Initiative | Industry Significance |
|---|---|
| AV1 Hardware Acceleration | Reduces power consumption for devices like smart TVs and mobile phones. |
| AI-Enhanced Encoding Integration | Improves video compression efficiency through content-aware algorithms. |
| Low-Latency Codec Development | Enables real-time interactive applications such as cloud gaming. |
| Cloud Encoding Platform Expansion | Offers scalable and flexible video processing solutions for media companies. |
| Open Standard Contribution | Drives ecosystem adoption and mitigates patent licensing complexities. |
Research Approach
Desk research of standards body specifications, patent databases, and regulatory filings preceded structured interviews with video codec developers, streaming platform engineers, hardware SoC designers, and media content producers. This approach combined primary insights with secondary validation. Bottom-up and top-down triangulation ensured comprehensive market sizing and trend identification.
Variance decomposition isolated key market drivers and restraints across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, and delivery mode, along with compression efficiency tiers. CAGRs were derived from historical trend analysis and future adoption curves. Forecast inputs included UHD content proliferation rates and mobile data consumption trends.
Forecasts assume regulatory continuity in key regimes like the European Union and China; material policy shifts would require re-modeling. These projections reflect assumptions regarding technological advancements and codec adoption rates. Revision becomes warranted when unexpected patent disputes or rapid shifts in open-source adoption cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Receiving Scales Market
Others
India Smart Home Market
Others
Technical Films Market
Others
South Korea Automotive LED Lighting Market
Others
Smart Badge Market
Others
Global Lavender Extracts Market
Others
AI in Home Automation Market
Others
Flexographic Printing Plate Market
Others
Rugged Tablet Market
Others
Lepidolite Market
Others
Video Paas Market
Others
ISO Cylinder Market
Others
Global Magnetic Flow Meters Market
Others
Italy 3D Printing Construction Market
Others
Smart Home Technologies Market
Others
Silicone Molding Machinery Market