
 North America Video Conferencing Hardware Market | 2026-2036
North America Video Conferencing Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
North America Video Conferencing Hardware Market Insights
Canada is narrowing its manufacturing footprint in video conferencing peripherals as supply chain localization pressures mount across North America. Cisco Systems Inc. leverages its Webex ecosystem to sustain enterprise room system dominance, while Logitech International S.A. anchors its position through USB peripheral standardization for hybrid work deployments. Poly Inc. competes on audio engineering heritage, differentiating through noise cancellation intellectual property refined over decades of enterprise headset production.
North America Video Conferencing Hardware encompasses dedicated endpoints, cameras, microphones, speakers, and displays engineered for real-time audiovisual collaboration over IP networks, typically supporting H.264/H.265 codecs with latency below 150 milliseconds for synchronous communication. Hardware cameras with 4K resolution and automatic framing algorithms now dominate premium corporate installations, while cloud-based systems displace on-premises infrastructure in mid-market accounts seeking operational flexibility. Educational Institutions represent the fastest-growing end user segment as K-12 districts and universities retrofit classrooms for hybrid instruction, though Corporates retain the largest installed base and replacement cycle volume.
FCC Part 15 emissions compliance and FDA regulatory oversight for telehealth-adjacent hardware shape product development timelines and market access requirements across the United States. NIST cybersecurity frameworks and emerging state-level biometric privacy laws in Illinois and Texas add compliance layers for facial recognition-enabled camera systems. Stakeholders must monitor interoperability certification shifts between Microsoft Teams and Zoom Video Communications platform requirements, as ecosystem allegiance increasingly dictates procurement decisions for enterprise refresh cycles.
Market Dynamics
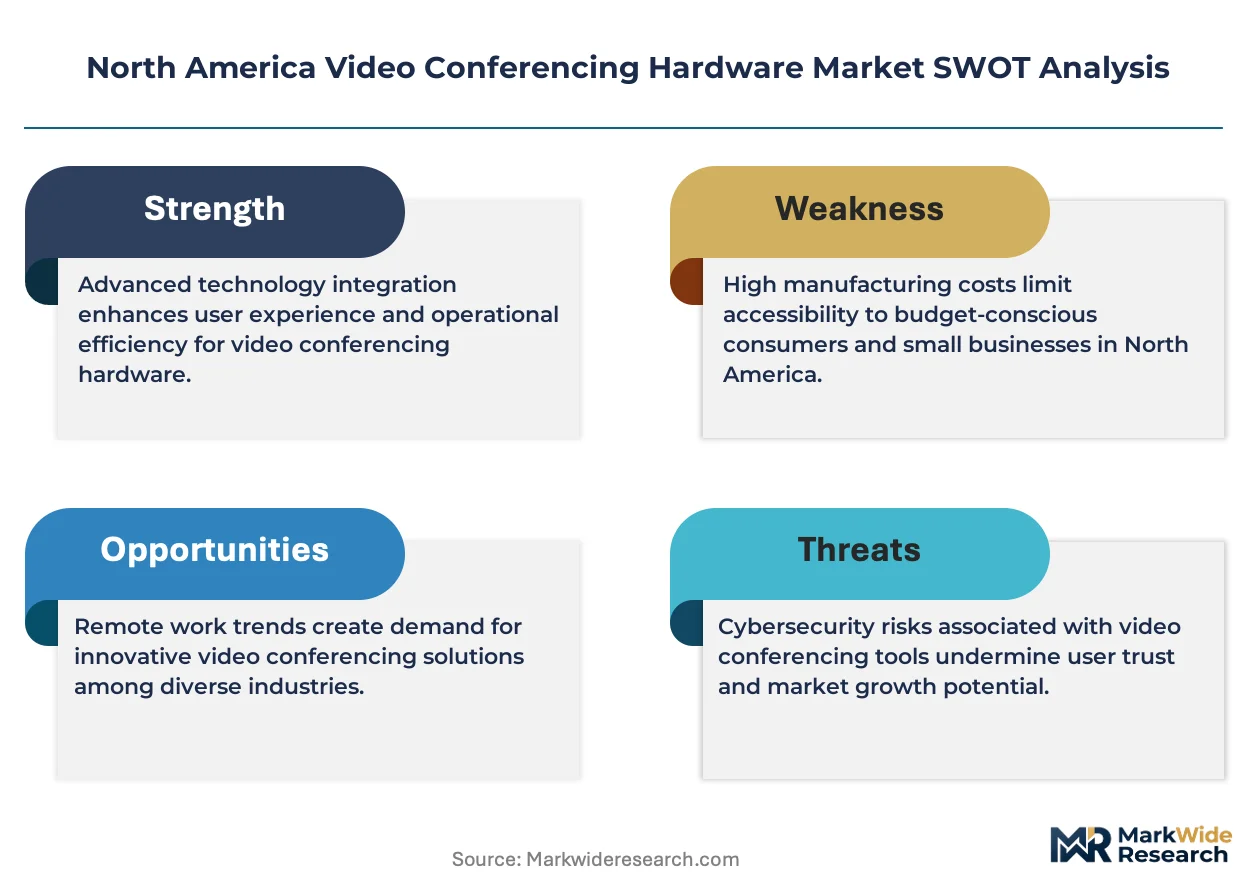
Platform ecosystem allegiance now dictates enterprise procurement cycles, with Microsoft Teams and Zoom Video Communications certification requirements forcing hardware vendors into costly interoperability investments. FCC Part 15 emissions testing and NIST cybersecurity compliance add 4-6 month certification delays, compressing product refresh windows and favoring incumbents with established regulatory pathways.
Growth Catalysts
- Telemedicine Infrastructure Mandates:Healthcare Facilities across Texas and California deploy integrated room systems for remote diagnostics. FDA oversight of telehealth-adjacent hardware accelerates clinical-grade camera adoption.
- K-12 Hybrid Instruction Retrofits:Educational Institutions represent surging demand for USB peripheral bundles and auto-framing cameras. School districts prioritize plug-and-play standardization over complex on-premises infrastructure.
- FCC Equipment Authorization Streamlining:Modular approval pathways for Wi-Fi 6E and 60GHz unlicensed bands reduce time-to-market for next-generation endpoints. Hardware vendors leverage pre-certified radio modules to bypass redundant testing.
Market Restraints
- Semiconductor Supply Concentration:Image signal processors and 4K sensor fabs concentrate in Taiwan and South Korea. Geopolitical friction threatens component allocation for North American assembly operations.
- Copper and Rare Earth Input Volatility:Magnet materials for speaker drivers and cable assemblies face price swings. Manufacturers absorb margin compression or pass costs to price-sensitive mid-market buyers.
- Smartphone Substitution Threat:Enterprise users increasingly default to mobile devices for ad-hoc video calls. Dedicated hardware must justify premium pricing through superior acoustic performance and room-scale coverage.
Strategic Opportunities
- Underpenetrated Canadian Healthcare Networks:Provincial telemedicine expansion lags US adoption curves. Vendors with Health Canada PMRA pathways capture first-mover positioning in rural clinic deployments.
- AI-Enabled Acoustic Convergence:Machine learning inference engines merge with beamforming microphone arrays. Real-time noise suppression and speaker tracking differentiate premium room systems from commodity peripherals.
- State Biometric Privacy Tailwinds:Illinois BIPA and emerging Texas facial recognition statutes create compliance consulting revenue streams. Vendors bundling privacy-by-design cameras capture legal-risk-averse enterprise accounts.
Industry Challenges
- Embedded Firmware Security Skill Scarcity:NIST SP 800-53 compliance demands specialized cybersecurity engineering talent. Hardware vendors compete with software firms for scarce penetration testing and secure-boot architecture expertise.
- Multi-Platform Certification Overhead:Simultaneous Microsoft Teams Rooms and Zoom Rooms qualification requires duplicative test matrices. Engineering teams face resource allocation trade-offs between feature development and interoperability validation.
- Legacy SIP Infrastructure Integration Friction:Enterprises with aging on-premises PBX investments demand backward-compatible endpoints. Cloud-native vendors struggle to support hybrid deployment models without engineering sprawl.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Video Conferencing Hardware Market |
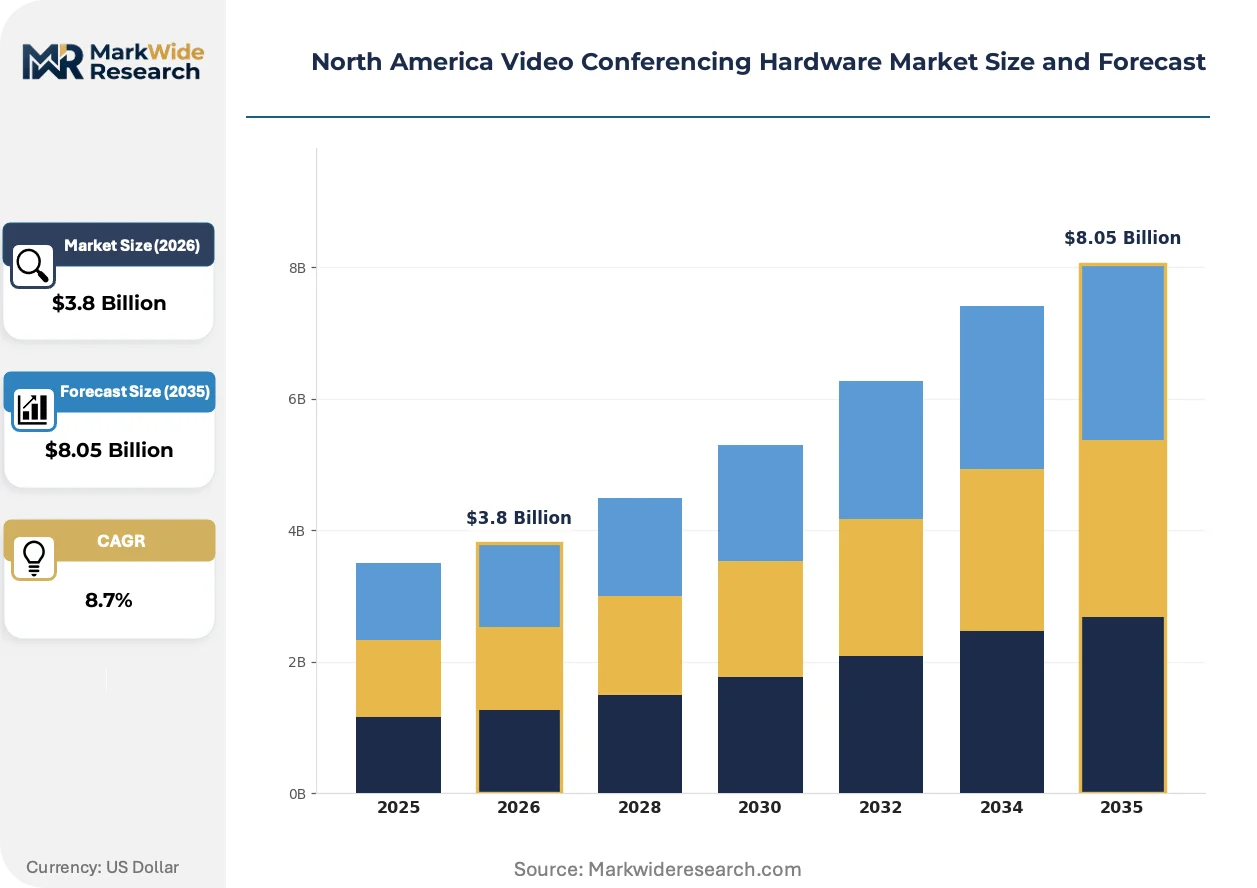
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Cameras, Microphones, Speakers, Displays End User: Corporates, Educational Institutions, Government Agencies, Healthcare Facilities Technology: HD Video, 4K Video, WebRTC, Cloud-based Systems Installation Type: On-Premises, Remote, Integrated Systems, Standalone Units |
| Companies Covered | Cisco Systems Inc., Logitech International S.A., Poly Inc., EPOS, Jabra Inc., Huawei Technologies Co., Ltd., Microsoft Corporation, Zoom Video Communications, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Video Conferencing Hardware Market Trends and Innovations
Codec optimization and edge computing architectures are compressing latency thresholds while platform-specific AI accelerators redefine performance benchmarks. Hardware vendors race to embed intelligence directly into endpoints rather than relying on cloud processing.
AV-over-IP transmission standards are hybridizing traditional HDMI-based room systems with software-defined video distribution. Corporate campuses in California's technology corridor adopt network-based switching to eliminate dedicated cable runs between cameras, displays, and control processors. This convergence enables centralized IT management of geographically dispersed meeting spaces while reducing per-room installation labor.
NIST cybersecurity frameworks and state-level biometric privacy statutes are reshaping product development roadmaps. Hardware manufacturers must implement hardware-rooted trust modules and encrypted firmware update channels to satisfy federal procurement requirements. Facial recognition-enabled cameras face heightened scrutiny under Illinois BIPA, forcing vendors to offer opt-in consent workflows and on-device processing to limit data exposure.
Enterprise buying committees now mandate platform-native certification prior to hardware evaluation, compressing vendor shortlists to pre-approved ecosystem partners. IT procurement teams in Texas energy and financial services sectors prioritize Teams-certified or Zoom-certified devices over best-of-breed alternatives. This specification tightening favors established players with dedicated certification engineering resources and disadvantages peripheral specialists lacking platform engineering partnerships.
North America Video Conferencing Hardware Market Segmentation
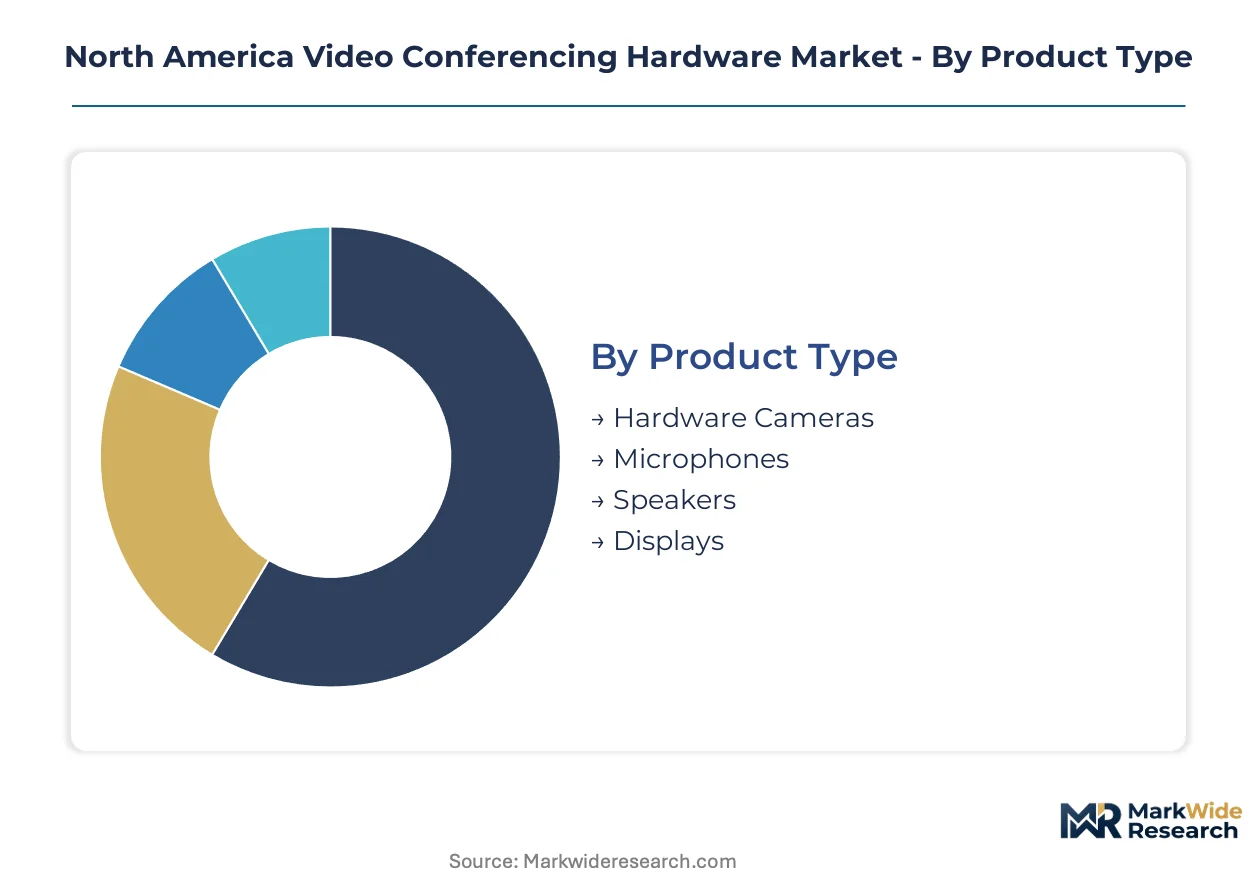
Segmentation reveals how procurement patterns diverge across technical specifications and deployment contexts in North America. Buyers prioritize platform certification compatibility over raw hardware specifications, reshaping vendor positioning across each category.
Product Type:
Mature peripheral categories face margin compression while emerging integrated systems command premium positioning.
- Hardware Cameras:4K sensors with automatic framing algorithms dominate premium corporate installations in California's technology corridor. FCC Part 15 emissions compliance adds certification overhead for Wi-Fi 6E-enabled models targeting enterprise refresh cycles.
- Microphones:Beamforming arrays with machine learning inference engines differentiate premium room systems from commodity USB peripherals. Texas enterprise hubs drive demand for acoustic convergence features that suppress HVAC noise in large conference spaces.
- Speakers:Magnet materials for drivers face copper and rare earth price volatility. Manufacturers absorb margin compression or pass costs to mid-market buyers in K-12 districts.
- Displays:AV-over-IP transmission standards displace dedicated HDMI cable runs in corporate campuses. Network-based switching enables centralized IT management of dispersed meeting spaces.
Hardware cameras retain volume leadership; integrated room systems hold the steepest expansion curve.
End User:
Customer type determines procurement complexity, with regulated sectors demanding extended compliance validation.
- Corporates:Platform ecosystem allegiance dictates refresh cycles, with Microsoft Teams and Zoom certification requirements compressing vendor shortlists. IT procurement teams in Texas energy and financial services sectors prioritize pre-approved ecosystem partners.
- Educational Institutions:K-12 districts and universities retrofit classrooms for hybrid instruction, representing surging demand for plug-and-play USB peripheral bundles. School districts prioritize standardization over complex on-premises infrastructure deployment.
- Government Agencies:NIST cybersecurity frameworks and federal procurement requirements mandate hardware-rooted trust modules. Encrypted firmware update channels become table stakes for market access.
- Healthcare Facilities:FDA oversight of telehealth-adjacent hardware accelerates clinical-grade camera adoption. Texas and California providers deploy integrated room systems for remote diagnostics and specialist consultations.
Corporates retain volume leadership; educational institutions hold the steepest expansion curve.
Technology:
Resolution tiers and architecture choices segment buyers by performance requirements and IT infrastructure maturity.
- HD Video:Legacy codec support persists in budget-constrained K-12 deployments. Price-sensitive districts delay 4K migration until refresh cycles force hardware replacement.
- 4K Video:H.265 codec optimization reduces bandwidth demands for synchronous communication below 150 milliseconds latency. Premium corporate installations in California technology corridor standardize on this resolution tier.
- WebRTC:Browser-based connectivity eliminates client software dependencies for ad-hoc meeting participation. Mid-market accounts seeking operational flexibility drive displacement of plugin-dependent architectures.
- Cloud-based Systems:Displace on-premises infrastructure in mid-market accounts. Operational flexibility outweighs capital expenditure preferences for organizations without dedicated AV engineering staff.
HD video retains volume leadership; cloud-based systems hold the steepest expansion curve.
Installation Type:
Deployment model selection reflects IT staffing levels and real estate portfolio dispersion.
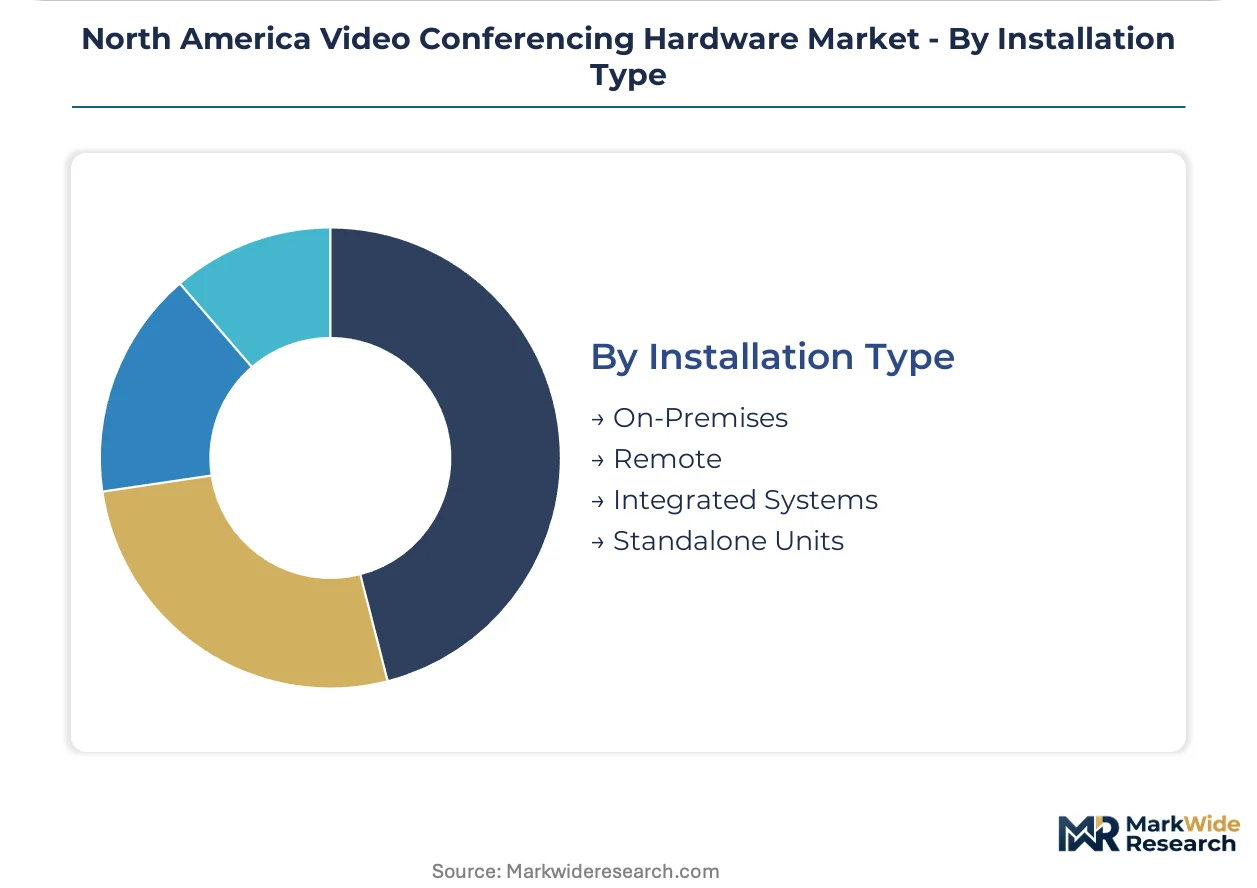
- On-Premises:Aging SIP infrastructure in legacy enterprise PBX environments demands backward-compatible endpoints. Cloud-native vendors struggle to support hybrid deployment models without engineering sprawl.
- Remote:Home office deployments concentrate in knowledge worker segments with employer-provided equipment stipends. USB peripheral standardization enables self-service installation without AV technician dispatch.
- Integrated Systems:Centralized control processors manage cameras, displays, and audio across geographically dispersed corporate campuses. California technology corridor adopters eliminate per-room installation labor through network-based switching.
- Standalone Units:All-in-one bars simplify procurement for small meeting rooms and huddle spaces. Plug-and-play positioning targets organizations without dedicated conferencing infrastructure teams.
On-premises retains volume leadership; integrated systems hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization requirements anchor demand concentration in the United States, while Health Canada PMRA pathways and provincial telemedicine programs shape adoption curves north of the border. Regulatory fragmentation across federal and state jurisdictions creates distinct certification burdens for hardware vendors serving this integrated market.
United States
California's technology corridor and Texas enterprise hubs drive integrated room system deployments for hybrid work infrastructure. FDA oversight of telehealth-adjacent hardware accelerates clinical-grade camera adoption in healthcare networks. Illinois BIPA and emerging Texas biometric privacy statutes reshape facial recognition-enabled product roadmaps.
Canada
Provincial telemedicine expansion in Ontario and British Columbia lags US adoption curves, creating first-mover positioning for vendors with established Health Canada PMRA pathways. Supply chain localization pressures narrow manufacturing footprints in video conferencing peripherals. Rural clinic deployments in Prairie Provinces represent underpenetrated demand pockets.
Mexico
Nearshoring manufacturing investments in Nuevo León and Bajío Region attract assembly operations for USB peripheral bundles serving North American distribution. Mexico City Metro enterprise corridors drive demand for cloud-based conferencing infrastructure. Regulatory alignment with FCC Part 15 emissions standards facilitates cross-border product certification.
North America Video Conferencing Hardware Market Competitive Landscape
Capability concentration sits with ecosystem-integrated tier; scale advantage sits with peripheral commoditization specialists. The vendor base stratifies across platform-certification incumbents, audio engineering heritage players, and USB standardization leaders. Three archetypes dominate: ecosystem-anchored systems integrators, acoustic IP specialists, and peripheral commoditizers. Competitive moves concentrate on multi-platform certification engineering and AI-enabled acoustic feature differentiation.
Within the ecosystem-anchored tier, Cisco Systems Inc. and Microsoft Corporation represent platform-native certification dominance, while Logitech International S.A. occupies a position as the USB peripheral standardization anchor for hybrid work deployments. Poly Inc. exemplifies the acoustic engineering heritage archetype, with EPOS and Jabra Inc. sitting within the audio specialization cluster. Huawei Technologies Co., Ltd. and Sony Corporation anchor geographic diversification vectors, while Zoom Video Communications exemplifies the platform-origin hardware extension model.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Logitech International S.A. |
| Poly Inc. |
| EPOS |
| Jabra Inc. |
| Huawei Technologies Co., Ltd. |
| Microsoft Corporation |
| Zoom Video Communications |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwanese image signal processor fabs anchor component availability for North American assembly operations, with capacity allocation decisions at TSMC and MediaTek directly transmitting into pricing power for 4K camera modules and beamforming microphone arrays. FCC Part 15 certification delays of 4-6 months compress product refresh windows, forcing vendors to absorb margin compression or accelerate premium tier positioning to recover engineering overhead.
Pricing Analysis
California technology corridor buyers pay 15-25% premiums over Texas enterprise hubs for identical hardware specifications, reflecting concentrated IT procurement sophistication and platform certification urgency. Three-tier pricing structure across premium, standard, and economy levels stratifies by Microsoft Teams Rooms and Zoom Rooms certification grade, with uncertified peripherals competing on commodity USB standardization. Pricing pressure stems from smartphone substitution in ad-hoc video use cases, eroding dedicated hardware justification. K-12 districts exhibit highest price sensitivity, prioritizing plug-and-play bundles over acoustic performance; healthcare networks show lowest sensitivity, accepting clinical-grade premiums for FDA-aligned camera systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning, with Section 301 duties on video encoder chipsets and printed circuit board assemblies forcing vendor migration to Mexican and Vietnamese contract manufacturing. Component sourcing draws from Taiwan for image signal processors, South Korea for 4K CMOS sensors, and China for rare earth magnet materials in speaker drivers. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where geopolitical friction threatens allocation priority for North American OEMs. Distribution runs through enterprise IT resellers and direct platform partnerships, with cloud-native vendors bypassing traditional AV integrators for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Video Conferencing Hardware Market sits in early-cycle expansion, with K-12 hybrid instruction retrofits and provincial Canadian telemedicine buildouts extending penetration curves beyond saturated corporate refresh cycles.
For Market Incumbents: Build certification moats through simultaneous Microsoft Teams Rooms and Zoom Rooms qualification engineering, creating switching costs that commoditize peripheral challengers. Invest in Health Canada PMRA pathway establishment to capture Ontario and British Columbia rural clinic deployments ahead of provincial telemedicine expansion. Defend against smartphone substitution by embedding AI-enabled acoustic convergence that mobile devices cannot replicate at room scale. For New Entrants and Emerging Players: Pursue underpenetrated Canadian healthcare networks where established vendors lack PMRA regulatory familiarity, offering bundled privacy-by-design cameras that preempt Illinois BIPA and Texas biometric compliance consulting. Target Prairie Provinces rural clinic deployments with simplified standalone units that eliminate AV technician dependency. Lead with USB peripheral standardization for hybrid work deployments, leveraging Logitech's category-building investments without matching their channel infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors acoustic IP specialists with machine learning inference engine integration, as noise cancellation differentiation becomes the primary non-platform purchasing criterion. Five-to-ten year viability hinges on edge computing architecture migration and firmware security engineering depth. Watch for inflection in FCC equipment authorization streamlining for Wi-Fi 6E and 60GHz unlicensed bands, which would accelerate next-generation endpoint time-to-market and reward pre-certified radio module investments.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Platform Certification Engineering | Simultaneous Teams and Zoom qualification compresses vendor shortlists to pre-approved ecosystem partners. |
| AI-Enabled Acoustic Convergence | Machine learning beamforming arrays differentiate premium room systems from commodity USB peripherals. |
| Health Canada PMRA Pathway Establishment | First-mover positioning in Ontario and British Columbia rural clinic deployments captures provincial telemedicine expansion. |
| Privacy-by-Design Camera Development | Illinois BIPA and Texas biometric statutes create compliance consulting revenue streams for legal-risk-averse enterprises. |
| Edge Computing Architecture Migration | On-device processing reduces cloud dependency latency below 150 milliseconds for synchronous communication. |
Research Methodology
A standing panel of AV integration specialists, enterprise IT procurement officers, platform certification engineers, and K-12 technology directors provided ongoing calibration across primary fieldwork. Secondary validation drew from FCC equipment authorization databases, SEC 10-K filings of publicly traded hardware vendors, NIST cybersecurity framework documentation, and Health Canada PMRA regulatory notices. Bottom-up triangulation across component bill-of-materials analysis and top-down reconciliation against enterprise refresh cycle surveys anchored volume estimates.
Scenario-bracketing framed analytical development across the projection horizon, with segmentation modeling spanning product type, end user archetype, resolution tier, and deployment architecture. CAGRs derived from fitted adoption curves incorporating platform ecosystem allegiance shifts and regulatory compliance timeline impacts. Forecast inputs included provincial telemedicine program announcements, school district bond issuance patterns for technology infrastructure, and hyperscaler capex disclosures for cloud-based conferencing infrastructure.
Macroeconomic conditions sit as an overlay; deviation in semiconductor allocation priority, copper and rare earth commodity price regimes, or federal telecommunications infrastructure spending would shift the trajectory. Forecasts reflect assumptions documented in platform certification requirement stability and regulatory pathway continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Healthcare Flexible Packaging Market
Others
Global Recruitment and Staffing Market
Others
DIY Smart Home Market
Others
Global Military Wearable Sensors Market
Others
Agitation System Market
Others
Aboveground Storage Tanks Market
Others
Mainframe Computers Market
Others
Qatar Smartphone Market
Others
Europe Refrigerated Display Cases Market
Others
Smart Home Technologies Market
Others
Calcined Petroleum Coke Market
Others
Printed Leather Market
Others
Italy 3D Printing Construction Market
Others
Rotary Dial Machine Market
Others
Global Emergency Spill Response Market
Others
Brazil Lime Market