
 Casein Peptone Market | 2026-2036
Casein Peptone Market Size, Share, and Industry Trends Forecast 2026-2036
Casein Peptone Market Outlook
Buyer concentration in the Casein Peptone Market is decoupling from traditional pharmaceutical procurement patterns as contract development and manufacturing organizations fragment demand across smaller biotech clients. Thermo Fisher Scientific Inc. leverages its vertically integrated life sciences platform to control upstream peptone supply chains. Merck KGaA anchors European demand through its high-purity media portfolio. HiMedia Laboratories Pvt. Ltd. dominates price-sensitive segments in emerging biomanufacturing hubs.
Casein peptone is a protein hydrolysate derived from enzymatic digestion of milk casein, yielding a nitrogen-rich mixture of peptides and amino acids soluble in aqueous media. Manufacturers typically employ papain or trypsin hydrolysis followed by filtration and spray-drying to achieve standardized amino acid profiles for microbial fermentation. Powder peptone leads volume due to shelf stability and freight efficiency, while liquid peptone captures premium positioning in continuous bioprocessing workflows. High purity grades command margin concentration as gene therapy and vaccine producers enforce endotoxin thresholds below established pharmacopeial limits.
The FDA enforces current Good Manufacturing Practice standards for peptone lots used in injectable drug substance production, while EMA's REACH framework governs chemical registration and occupational exposure for European manufacturers. The EU Green Deal pressures dairy-derived raw material sourcing through methane emission accounting at supplier level. Stakeholders must monitor regulatory divergence between pharmacopeial nitrogen determination methods as this directly impacts lot-release interoperability across manufacturing sites.
Market Dynamics
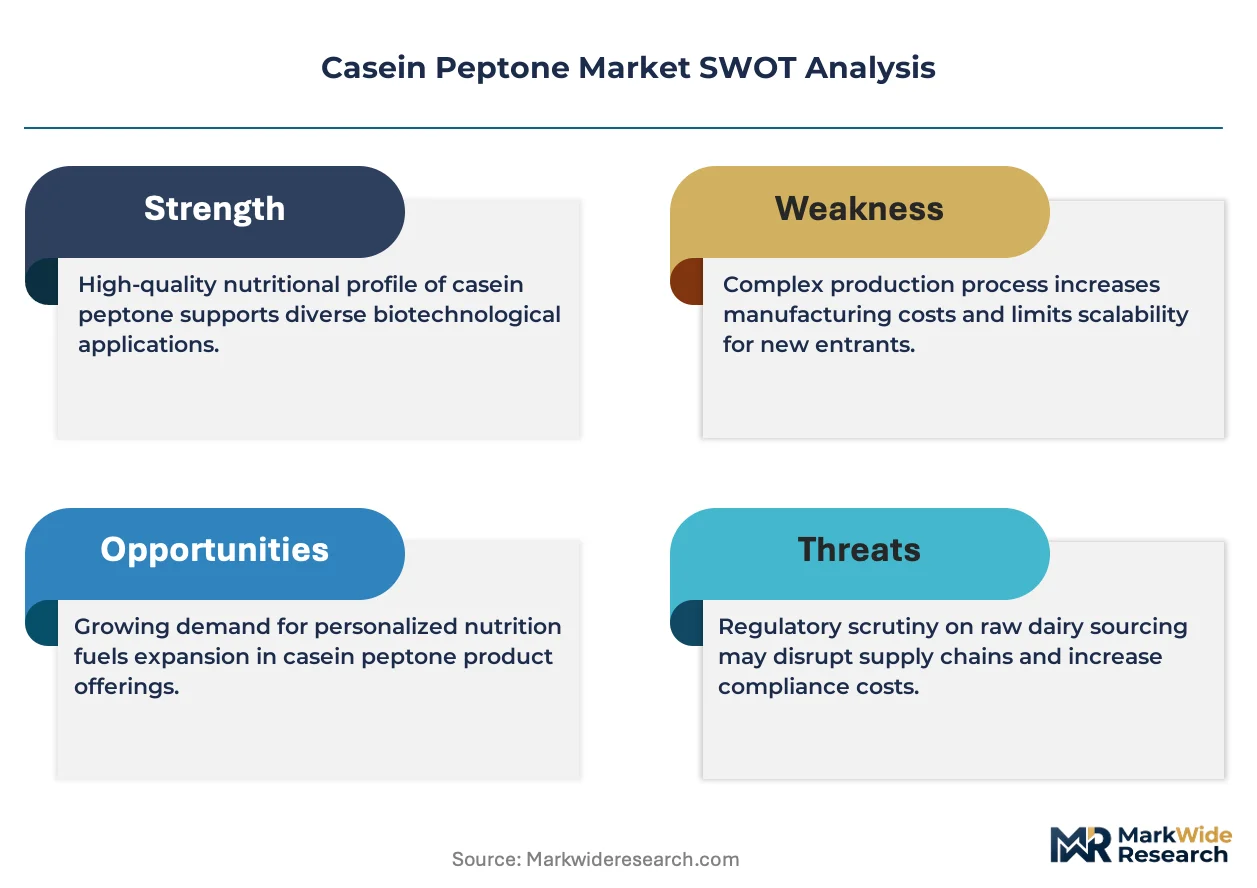
Biopharmaceutical lot-release standards are tightening nitrogen determination tolerances, forcing peptone manufacturers to harmonize testing protocols across FDA, EMA, and pharmacopeial methods or risk supply disqualification from multi-site manufacturing networks.
Growth Catalysts
- Gene therapy commercialization:Viral vector production requires endotoxin-controlled peptone grades that exceed traditional fermentation specifications, pulling high-purity casein hydrolysate into cell culture media formulations.
- EMA's REACH framework:Chemical registration mandates for enzymatic hydrolysates are accelerating supplier documentation investments, filtering out informal producers and consolidating qualified supply channels for European biomanufacturers.
- Papain hydrolysis optimization:Enzyme immobilization technologies are reducing batch-to-batch amino acid variability, enabling peptone producers to guarantee peptide profiles that match cell-line-specific nutritional requirements.
Market Restraints
- Dairy input cost volatility:Casein concentrate prices track global milk powder futures, compressing peptone margins when New Zealand and EU dairy auctions spike without corresponding media price pass-through mechanisms.
- Chinese supply concentration:A subset of enzymatic hydrolysate precursors originates from concentrated coastal dairy processing zones, creating geographic vulnerability to regional environmental enforcement actions or logistics disruptions.
- Plant-based substitution:Soy and yeast-derived peptones are capturing price-sensitive fermentation applications where nitrogen source flexibility outweighs casein's amino acid completeness.
Strategic Opportunities
- India biomanufacturing expansion:CDMO investments in Hyderabad and Bengaluru are outpacing domestic peptone production capacity, creating import substitution potential for qualified suppliers meeting CDSCO traceability requirements.
- Continuous bioprocessing:Liquid peptone formats compatible with perfusion bioreactors command formulation premiums as stainless-steel facilities convert from batch to steady-state operations.
- EU Green Deal methane accounting:Dairy suppliers with verified low-emission herds can differentiate casein peptone through carbon-labeled supply chains, accessing sustainability-premium procurement pools.
Industry Challenges
- Analytical method harmonization:Kjeldahl nitrogen determination yields diverge between USP and EP protocols, forcing manufacturers to run dual validations for lots serving transatlantic manufacturing sites.
- Endotoxin clearance validation:Gene therapy producers demand sub-pharmacopeial endotoxin thresholds that require manufacturers to revalidate filtration trains without standardized reference materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casein Peptone Market |
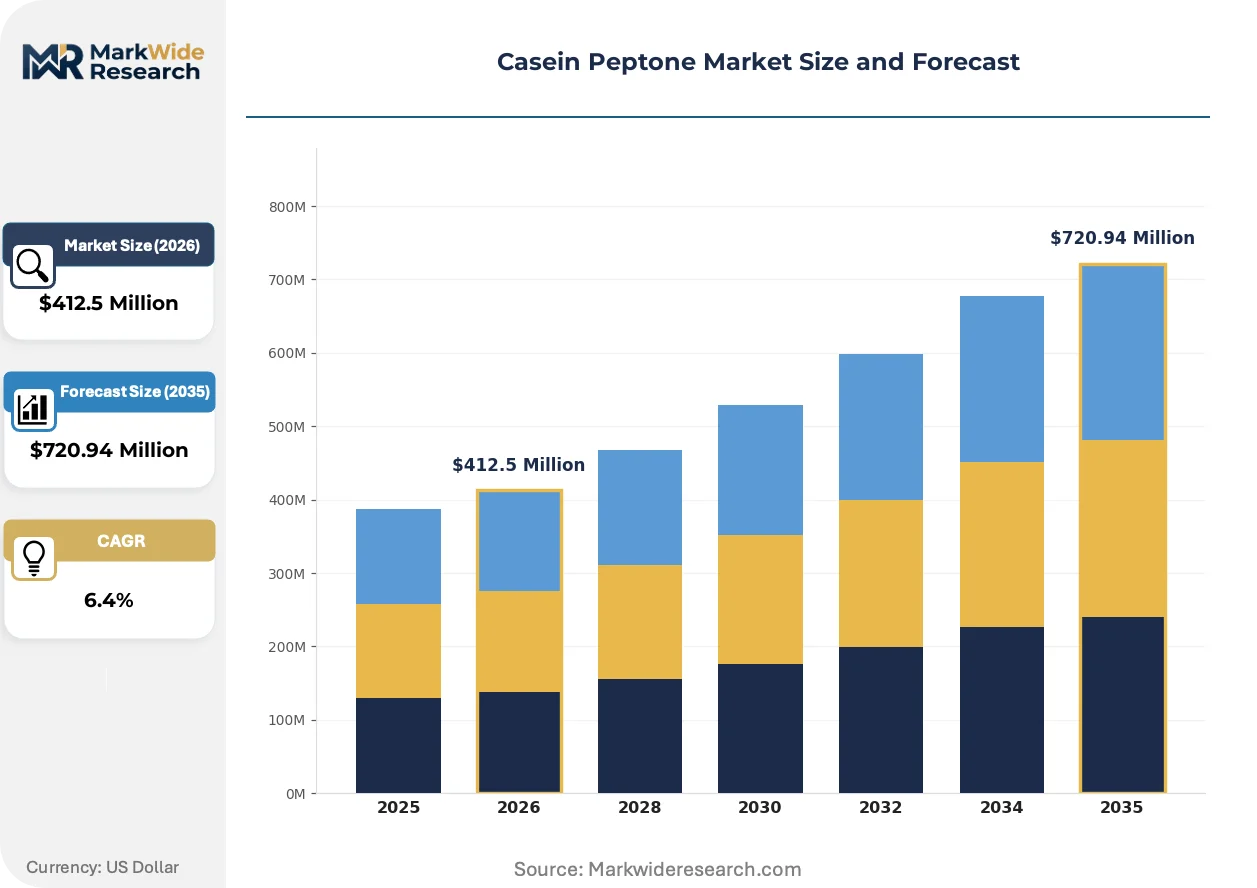
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Peptone, Powder Peptone, Granular Peptone, Hydrolyzed Peptone Application: Food Industry, Pharmaceutical Industry, Biotechnology, Laboratory Research Form: Solid, Liquid, Semi-solid, Frozen Purity: High Purity, Medium Purity, Low Purity, Others |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, HiMedia Laboratories Pvt. Ltd., Neogen Corporation, Solabia Group, Amyl Media Pty Ltd, MP Biomedicals LLC, Carl Roth GmbH & Co. KG, Azelis Americas, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casein Peptone Market Strategic Shifts
Enzymatic hydrolysis control systems and regulatory data integrity mandates are compressing the acceptable range for peptone variability, rewarding manufacturers with in-house proteomics capabilities and punishing specification-tolerant suppliers.
Precision enzyme dosing via inline spectroscopic monitoring is rewriting the economics of peptone standardization. Mid-tier biotech CDMOs are adopting these controlled-hydrolysis products to reduce cell culture failure rates. The technology is compressing the premium commanded by historical pharmacopeial-grade suppliers as consistency becomes table stakes.
REACH's updated polymer and monomer registration requirements are extending to protein hydrolysate intermediates, compelling European peptone manufacturers to submit full toxicological dossiers for enzymatic digestion byproducts. The compliance burden falls heaviest on smaller compounders lacking regulatory affairs infrastructure, accelerating consolidation toward integrated life sciences platforms with dedicated chemical registration teams.
Buyer consolidation among top-ten biopharmaceutical manufacturers is compressing supplier qualification timelines. Direct procurement relationships are displacing distributor-mediated peptone sourcing for high-volume media formulations. This concentration is most visible in the United States, where Boston and San Francisco bioclusters have centralized media procurement under platform technology agreements that specify single-source peptone qualifications.
Casein Peptone Market Segmentation
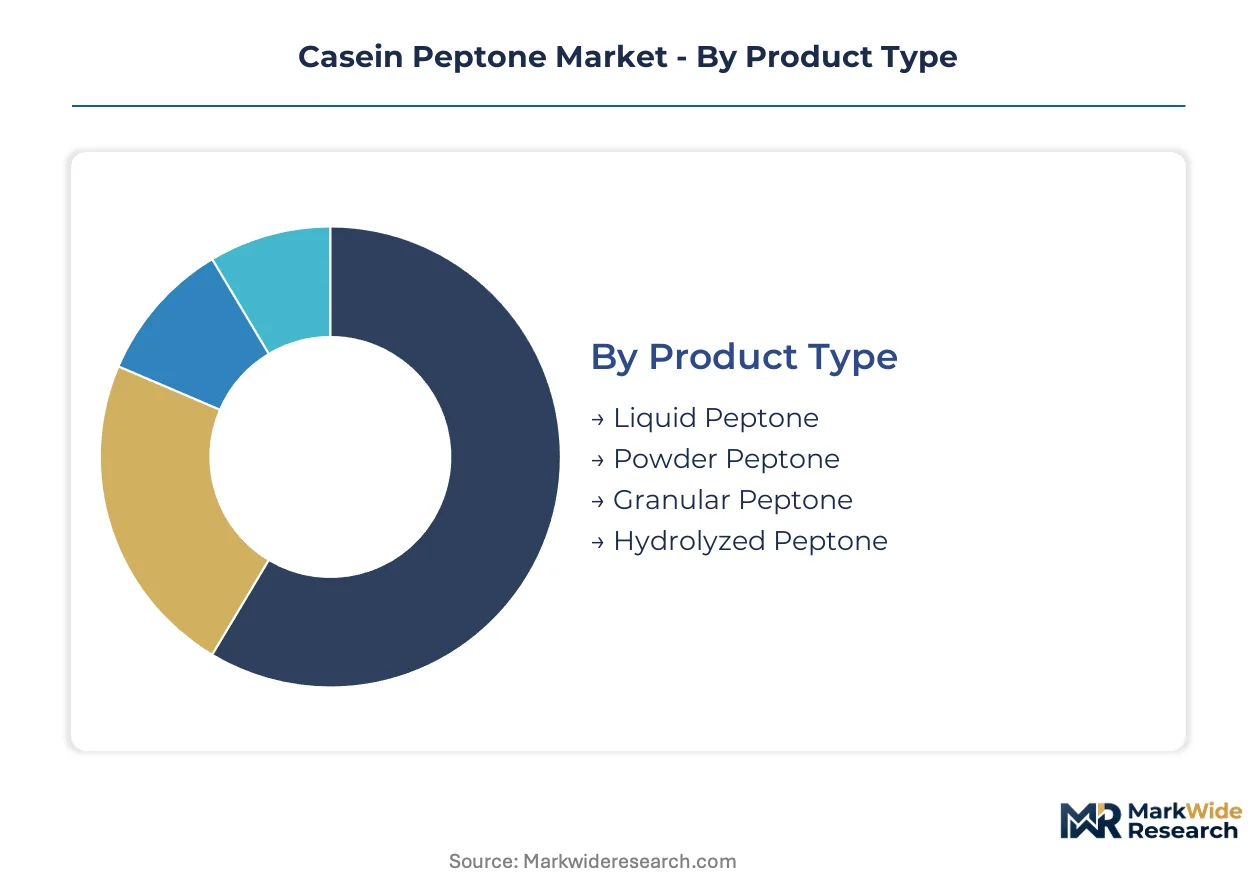
Peptone format selection determines regulatory pathway complexity and supply chain qualification burden. Manufacturers must align segment choices with end-user validation requirements and bioprocessing workflow specifications.
Product Type:
FDA and EMA impose divergent documentation loads across physical formats, with liquid preparations triggering additional stability validation protocols under ICH guidelines.
- Liquid Peptone:Aqueous solution format eliminates reconstitution steps in continuous bioprocessing. Demand concentrates in perfusion bioreactor installations across Massachusetts and California bioclusters, driven by stainless-steel facility conversions from batch to steady-state operations.
- Powder Peptone:Spray-dried format delivers shelf stability exceeding 24 months and freight efficiency for intercontinental supply. Volume leadership rests with microbial fermentation facilities in Germany and China where powder handling infrastructure dominates.
- Granular Peptone:Agglomerated particles reduce dust exposure during weighing operations. CDMOs in Hyderabad specify granular grades for occupational safety compliance under CDSCO manufacturing standards.
- Hydrolyzed Peptone:Pre-digested molecular weight fractions accelerate microbial growth curves. Niche positioning in rapid diagnostic media production.
Leading the category by volume: Powder Peptone. Growing fastest: Liquid Peptone.
Application:
End-use sector determines endotoxin threshold specifications and pharmacopeial compliance depth, with parenteral applications commanding the most rigorous lot-release protocols.
- Pharmaceutical Industry:Injectable drug substance production mandates FDA cGMP compliance with endotoxin thresholds below established pharmacopeial limits. Viral vector manufacturers in Boston and Basel drive specification tightening for gene therapy commercialization.
- Biotechnology:Cell culture media formulation requires nitrogen source traceability and amino acid profile consistency. Thermo Fisher Scientific and Merck KGaA anchor procurement concentration through platform technology agreements.
- Laboratory Research:Diagnostic media and quality control applications tolerate broader specification bands. Price-sensitive demand fragments across academic and government institutions.
- Food Industry:Fermentation starter cultures and probiotic production utilize food-grade peptone derivatives. FSSAI and EFSA frameworks govern microbiological specifications.
Dominating revenue contribution: Pharmaceutical Industry. Expanding most quickly: Biotechnology.
Form:
Physical state dictates storage infrastructure investment and cold chain dependency, with frozen formats requiring validated thaw protocols.
- Solid:Standard presentation for powder and granular peptone variants. Shelf-stable logistics minimize temperature-controlled distribution costs across multi-site manufacturing networks.
- Liquid:Ready-to-use format eliminates hydration variables. Stainless-steel bioreactor compatibility drives specification in continuous processing workflows.
- Semi-solid:Agar-based preparations for culture media plates. Regional compounding dominates with limited international trade.
- Frozen:Ultra-low temperature preservation for enzyme-sensitive peptide fractions. Gene therapy viral vector producers in San Francisco specify frozen grades for extended stability.
Highest shipment volume: Solid. Steepest expansion trajectory: Liquid.
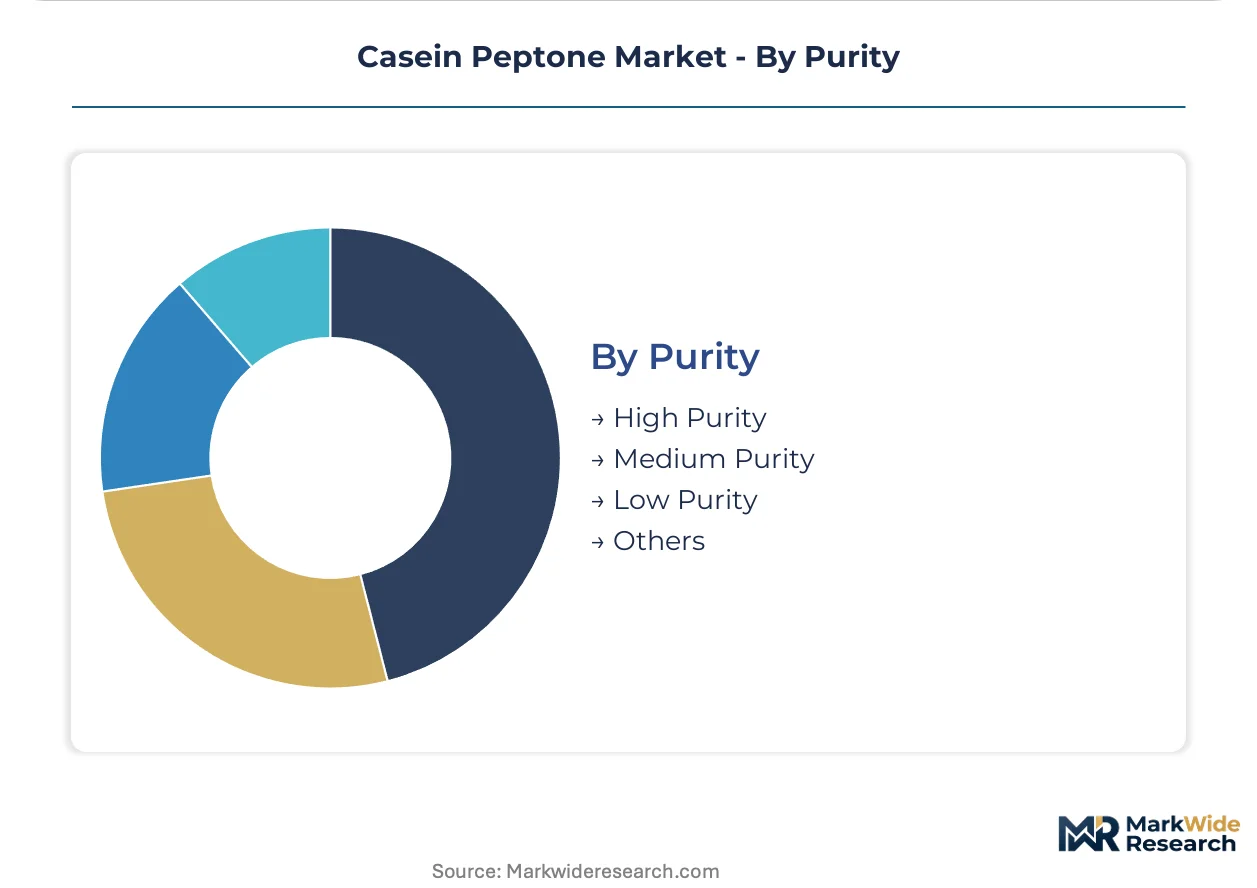
Purity:
Grade tiering separates qualified supply channels for parenteral applications from commodity fermentation inputs, with endotoxin and heavy metal specifications as primary discriminators.
- High Purity:Sub-pharmacopeial endotoxin thresholds below 0.25 EU/g with elemental impurity profiling per ICH Q3D. Gene therapy and vaccine producers enforce these specifications, consolidating demand among manufacturers with in-house proteomics capabilities.
- Medium Purity:Standard pharmacopeial compliance for oral and topical drug substance production. Balances cost and qualification burden for mid-tier CDMOs.
- Low Purity:Technical grade for industrial enzyme fermentation and agricultural applications. Price competition from soy and yeast-derived alternatives constrains margin.
- Others:Custom peptide fractionation for cell-line-specific nutritional requirements. Contract manufacturing arrangements with dedicated protease control protocols.
Commanding premium pricing: High Purity. Gaining share fastest: Medium Purity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomanufacturing demand concentrates in three national clusters where viral vector production and cell culture media formulation drive procurement. FDA, EMA, and CDSCO traceability mandates are fragmenting qualified supplier networks across these jurisdictions.
United States
Viral vector manufacturers in Greater Boston and the San Francisco Bay Area consume high-purity peptone for gene therapy commercialization. FDA cGMP enforcement for injectable drug substances mandates endotoxin thresholds below pharmacopeial limits. The Massachusetts biocluster has centralized media procurement under platform technology agreements specifying single-source qualifications.
Germany
Merck KGaA anchors European demand through its high-purity media portfolio serving contract development organizations. EMA's REACH framework requires full toxicological dossiers for enzymatic hydrolysate intermediates. The Rhine-Main region hosts concentrated stainless-steel bioreactor installations converting from batch to continuous processing workflows.
China
Coastal dairy processing zones supply enzymatic hydrolysate precursors to domestic fermentation facilities. NMPA tightening of raw material traceability rules is filtering informal producers from qualified supply channels. The Yangtze River Delta biomanufacturing corridor is outpacing domestic peptone production capacity.
India
CDMO investments in Hyderabad and Bengaluru are creating import substitution pressure for suppliers meeting CDSCO manufacturing standards. FSSAI frameworks govern microbiological specifications for food-grade peptone derivatives. Telangana's occupational safety compliance requirements are driving granular peptone specifications for dust exposure reduction.
Switzerland
Basel-based gene therapy producers enforce sub-pharmacopeial endotoxin thresholds that exceed standard fermentation specifications. Swissmedic alignment with EMA pharmacopeial methods reduces dual validation burdens for transatlantic manufacturing sites. The country's precision manufacturing heritage supports proteomics-capable suppliers guaranteeing peptide profile consistency.
Casein Peptone Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty hydrolysate fractions for cell-line-specific nutritional requirements. The vendor base stratifies across integrated life sciences platforms, regional compounders, and price-sensitive distributors. Three archetypes dominate: vertically integrated conglomerates with captive proteomics capabilities, mid-tier manufacturers with enzyme immobilization expertise, and import-dependent distributors serving emerging biomanufacturing hubs. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification timelines compress.
Among integrated life sciences platforms, Thermo Fisher Scientific Inc. exemplifies upstream supply chain control through its vertically extended media portfolio. Merck KGaA occupies a position anchoring European demand concentration through high-purity formulation capabilities. HiMedia Laboratories Pvt. Ltd. represents the emerging-market specialist archetype, serving price-sensitive segments in biomanufacturing expansion corridors.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| HiMedia Laboratories Pvt. Ltd. |
| Neogen Corporation |
| Solabia Group |
| Amyl Media Pty Ltd |
| MP Biomedicals LLC |
| Carl Roth GmbH & Co. KG |
| Azelis Americas, LLC |
| Others |
Value Chain & Pricing Dynamics
Dairy input cost volatility transmits directly from New Zealand and EU milk powder futures through to peptone manufacturer margins, with powder formats absorbing freight efficiency premiums while liquid peptone captures formulation premiums in continuous bioprocessing workflows. Buyers in Boston and Basel bioclusters enforce sub-pharmacopeial endotoxin thresholds that stratify pricing across high-purity, medium-purity, and low-purity tiers.
Pricing Analysis
Volume leadership rests with powder peptone where freight efficiency and shelf stability support standardized pricing, while liquid peptone commands margin premiums through stainless-steel bioreactor compatibility. Three-tier pricing structure across premium, standard, and economy levels separates gene therapy-grade endotoxin specifications from microbial fermentation inputs. Cost compression in the medium-purity tier is intensifying because soy and yeast-derived substitutes are capturing price-sensitive applications. Academic and government laboratory research segments exhibit highest price sensitivity, whereas viral vector manufacturers in gene therapy commercialization demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from CDMOs in Massachusetts and California mandate multi-supplier qualification for peptone lots serving transatlantic manufacturing sites. Geographic supply concentration centers on the United States, Germany, and China as these countries host the largest biomanufacturing clusters. Raw material dependencies draw from casein concentrate, papain and trypsin enzymes, and filtration membrane technologies. Single-source vulnerability emerges from concentrated coastal dairy processing zones in China subject to regional environmental enforcement actions. Distribution runs through direct procurement relationships displacing distributor-mediated sourcing for high-volume media formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision enzyme dosing via inline spectroscopic monitoring is displacing legacy batch-controlled hydrolysis, compressing the premium historically commanded by pharmacopeial-grade suppliers as consistency becomes baseline qualification.
For Market Incumbents: Acquire proteomics capabilities and in-house enzyme immobilization expertise to defend against precision hydrolysis technologies eroding specification premiums. Anchor capacity addition in Hyderabad and Bengaluru to capture CDMO import substitution demand under CDSCO traceability mandates. Consolidate backward integration into dairy sourcing with verified low-emission herd certification for EU Green Deal carbon-labeled procurement pools.
For New Entrants and Emerging Players: Enter via specialty hydrolysate fractions for cell-line-specific nutritional requirements, targeting the custom peptide fractionation segment where contract manufacturing arrangements with dedicated protease control protocols remain underpenetrated. Capture price-sensitive fermentation applications in emerging biomanufacturing hubs where HiMedia Laboratories' dominance leaves room for regional compounders with enzyme optimization expertise. Pursue go-to-market angles through CDMO partnerships rather than direct biopharmaceutical qualification timelines.
For Investors and Strategic Acquirers: REACH dossier submission completion for enzymatic hydrolysate intermediates is the leading indicator that regulatory affairs infrastructure separates acquirable mid-tier manufacturers from distressed compounders. Long-term viability across the analysis window hinges on in-house proteomics capabilities and single-source qualification status under platform technology agreements. Target acquisition archetypes include enzyme immobilization technology holders and regional compounders with pending EMA registration completeness.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Immobilization Technology Acquisition | Papain hydrolysis optimization reduces batch-to-batch amino acid variability for gene therapy producers. |
| CDSCO Traceability Certification Investment | Qualification for Hyderabad and Bengaluru CDMO procurement displaces import-dependent supply channels. |
| Low-Emission Dairy Sourcing Partnership | EU Green Deal methane accounting enables carbon-labeled peptone access to sustainability-premium pools. |
| Continuous Bioprocessing Liquid Format Expansion | Perfusion bioreactor compatibility in Massachusetts and California bioclusters commands formulation premiums. |
| Dual Pharmacopeial Validation Infrastructure | Harmonized USP and EP nitrogen determination protocols secure multi-site manufacturing network qualification. |
Study Parameters
Independent corroboration across biopharmaceutical procurement executives, regulatory affairs leads at peptone manufacturers, CDMO supply chain managers, and academic cell culture specialists underwrites the qualitative findings in this study. Secondary validation draws from FDA cGMP guidance documents, EMA REACH registration databases, CDSCO manufacturing standards, and SEC filings from integrated life sciences platforms. Bottom-up triangulation across enzymatic hydrolysis batch records and top-down demand modeling from biomanufacturing capacity announcements reconcile volume estimates.
Rate-of-change decomposition separates volume expansion from value premium capture across the projection horizon. Segmentation dimensions modeled include peptone format, application sector, physical form, and purity grade tier alongside regional regulatory cluster alignment. CAGRs derive from compound growth path analysis calibrated to biopharmaceutical lot-release standard tightening timelines and gene therapy commercialization trajectories. Forecast inputs incorporate stainless-steel facility conversion rates to continuous processing and REACH compliance investment cycles.
Revisions become necessary when FDA and EMA nitrogen determination method divergence widens, dairy input cost volatility exceeds historical bands, or Chinese environmental enforcement actions disrupt coastal hydrolysate precursor supply. Deviation in gene therapy viral vector production scale-up timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Papain Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market