
 Lupin Protein Market | 2026-2036
Lupin Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Lupin Protein Market Outlook
A capital-intensity divergence between spray-drying isolate capabilities and basic flour milling is redrawing competitive boundaries in lupin protein. Prolupin GmbH leverages its German extraction infrastructure to sustain premium isolate output for European food manufacturers. FRANK Food Products anchors its position through specialized bakery-grade concentrates. SunOpta Inc. competes via North American organic certification and scaled powder distribution networks.
Lupin protein comprises globulin and albumin fractions extracted from dehulled Lupinus angustifolius or Lupinus albus seeds, typically processed through aqueous extraction and isoelectric precipitation to achieve protein contents ranging from 40% in flour to 90% in isolate grades. Its primary commercial purpose centers on replacing soy and wheat proteins in allergen-sensitive food formulations and high-protein nutritional applications. Concentrate and isolate grades command the deepest margin pools due to downstream functional requirements in meat analogs and sports nutrition, while flour segments dominate volume through bakery and animal feed absorption. Powder form leads distribution efficiency across nutritional supplements and food manufacturing channels, with liquid formats gaining traction in beverage applications where solubility parameters prove critical.
EFSA novel food regulations shape ingredient market access timelines for European lupin protein entrants, while FDA GRAS self-affirmation governs US commercialization pathways for concentrate and isolate grades. REACH compliance and EU Green Deal agricultural subsidies further influence raw material sourcing economics and processing facility siting decisions across member states. Stakeholders must monitor evolving protein labeling thresholds and carbon accounting rules that will determine which extraction configurations retain cost-competitive supply positions.
Market Dynamics
Capital-intensity divergence between spray-drying isolate capabilities and basic flour milling is redrawing competitive boundaries in lupin protein, forcing processors to choose between premium functional grades and commodity volume positions.
Growth Catalysts
- EFSA Novel Food Streamlining:The EU's accelerated authorization pathway for non-traditional protein sources is compressing market entry timelines for isolate and concentrate grades, enabling faster commercialization of lupin-derived ingredients in meat analog formulations.
- German Plant-Based Meat Procurement:Food manufacturers in Germany are expanding lupin isolate procurement as a clean-label binder, creating concentrated demand pull for high-purity extraction output from Dutch and Belgian processing hubs.
- Aqueous Extraction Scale-Up:Advances in isoelectric precipitation and membrane filtration are improving protein recovery rates from dehulled Lupinus angustifolius seeds, reducing unit costs for isolate production.
Market Restraints
- Bitter Alkaloid Processing Costs:Removal of quinolizidine alkaloids from lupin seeds requires additional washing and debittering steps, elevating processing costs relative to soy protein extraction.
- European Raw Material Concentration:Commercial lupin cultivation clusters in France, Spain, and Germany create geographic supply risk for processors dependent on regional harvest volumes and EU Green Deal agricultural subsidy fluctuations.
- Soy Protein Substitution Threat:Established soy isolate supply chains and lower unit costs in North and South American production regions constrain lupin protein pricing power in cost-sensitive bakery and feed applications.
Strategic Opportunities
- Underpenetrated US Sports Nutrition:FDA GRAS self-affirmation pathways enable faster commercialization of lupin concentrate in protein powders and ready-to-drink beverages, where allergen-sensitive positioning commands premium shelf placement.
- Beverage Solubility Applications:Liquid format lupin protein development for high-protein beverages addresses functional gaps in current powder-dominant distribution, opening new channel access through beverage co-manufacturers.
- EU Carbon Accounting Alignment:EU Green Deal agricultural subsidies and emerging carbon labeling requirements favor domestic European protein sources over imported soy, creating structural demand tailwind for locally processed lupin ingredients.
Industry Challenges
- Specialized Extraction Engineering Talent:Scarcity of process engineers experienced in isoelectric precipitation and spray-drying optimization for legume proteins constrains facility expansion timelines and operational efficiency gains.
- EFSA Certification Timeline Variability:Novel food dossier preparation and EFSA scientific opinion timelines create revenue recognition delays for new isolate grades targeting European food manufacturing customers.
- Legacy Bakery Formulation Integration:Wheat and soy protein substitution in established industrial bakery processes requires extensive rheological testing and customer-specific reformulation support, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lupin Protein Market |
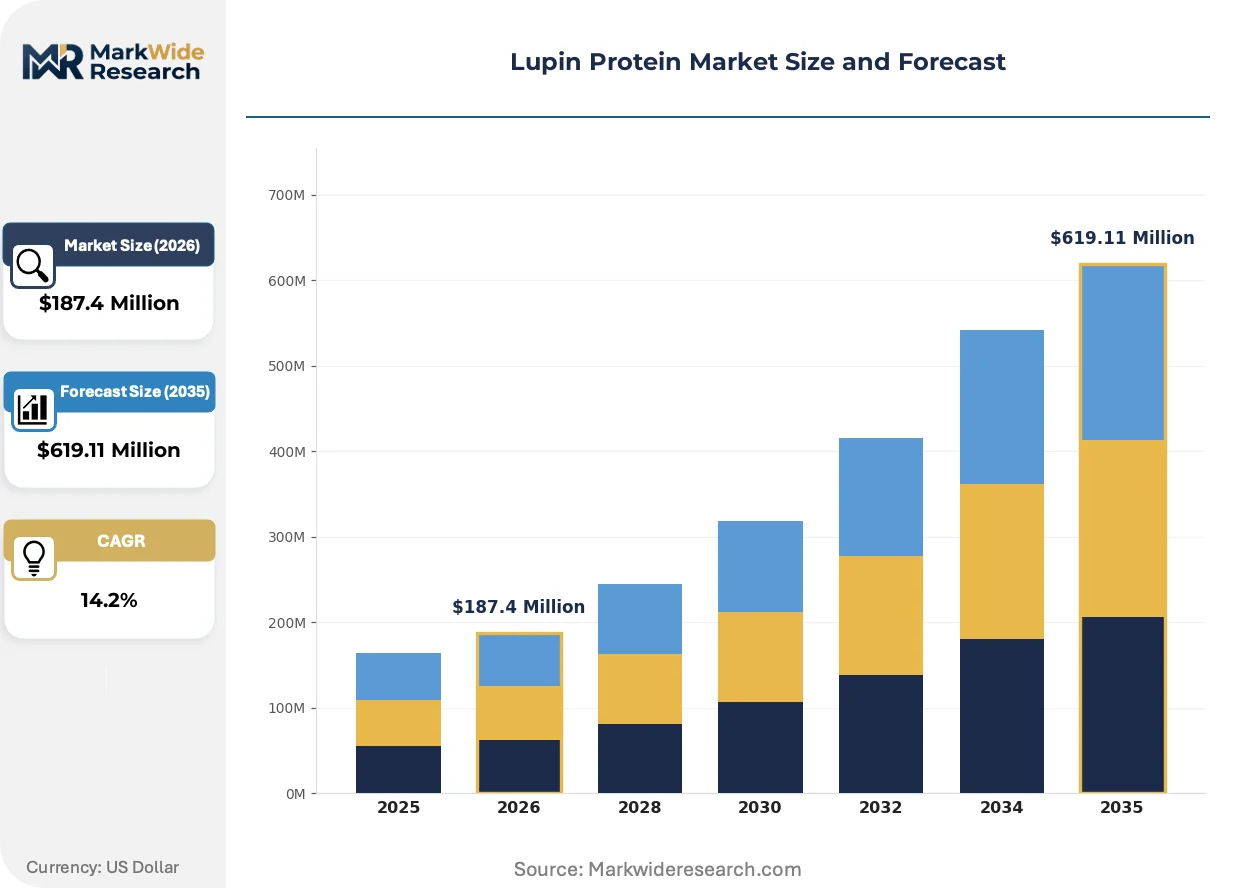
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Flour, Whole Seeds End Use: Food Products, Nutritional Supplements, Animal Feed, Bakery Form: Powder, Granules, Liquid, Whole Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Lup'ingredients, FRANK Food Products, Prolupin GmbH, The Protein Bread Company, A. Costantino & C. SpA, Aminola, Coorow Seeds, SunOpta Inc., Barentz International B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lupin Protein Market Strategic Shifts
Functional protein extraction technologies and regulatory positioning strategies are actively reshaping how lupin processors capture value across isolate, concentrate, and flour grades.
Membrane filtration systems paired with aqueous extraction methods are displacing conventional acid-wash protocols in isolate production, enabling German and Dutch processors to achieve higher protein purity with reduced water and energy inputs. Plant-based meat manufacturers are adopting these premium isolates at accelerating rates for binder applications. This technological shift is compressing margins for basic flour millers unable to fund capital-intensive extraction upgrades.
REACH compliance requirements and EU Green Deal carbon accounting rules are tightening raw material traceability standards for European protein processors. Industrial consequence includes mandatory documentation of agricultural input sourcing and processing energy footprints across supply chains. Concentrate and isolate segments face the steepest compliance burden, with Dutch ingredient hubs investing in blockchain-tracked farm-to-facility systems to maintain market access.
Bulk ingredient procurement by food manufacturers is consolidating around certified organic and non-GMO supply channels, displacing conventional commodity purchasing in premium formulation segments. Direct contracting between German plant-based meat producers and extraction facilities is replacing spot-market flour transactions. This channel restructuring is most visible in Western European food processing clusters, where clean-label positioning determines supplier selection criteria.
Lupin Protein Market Segmentation
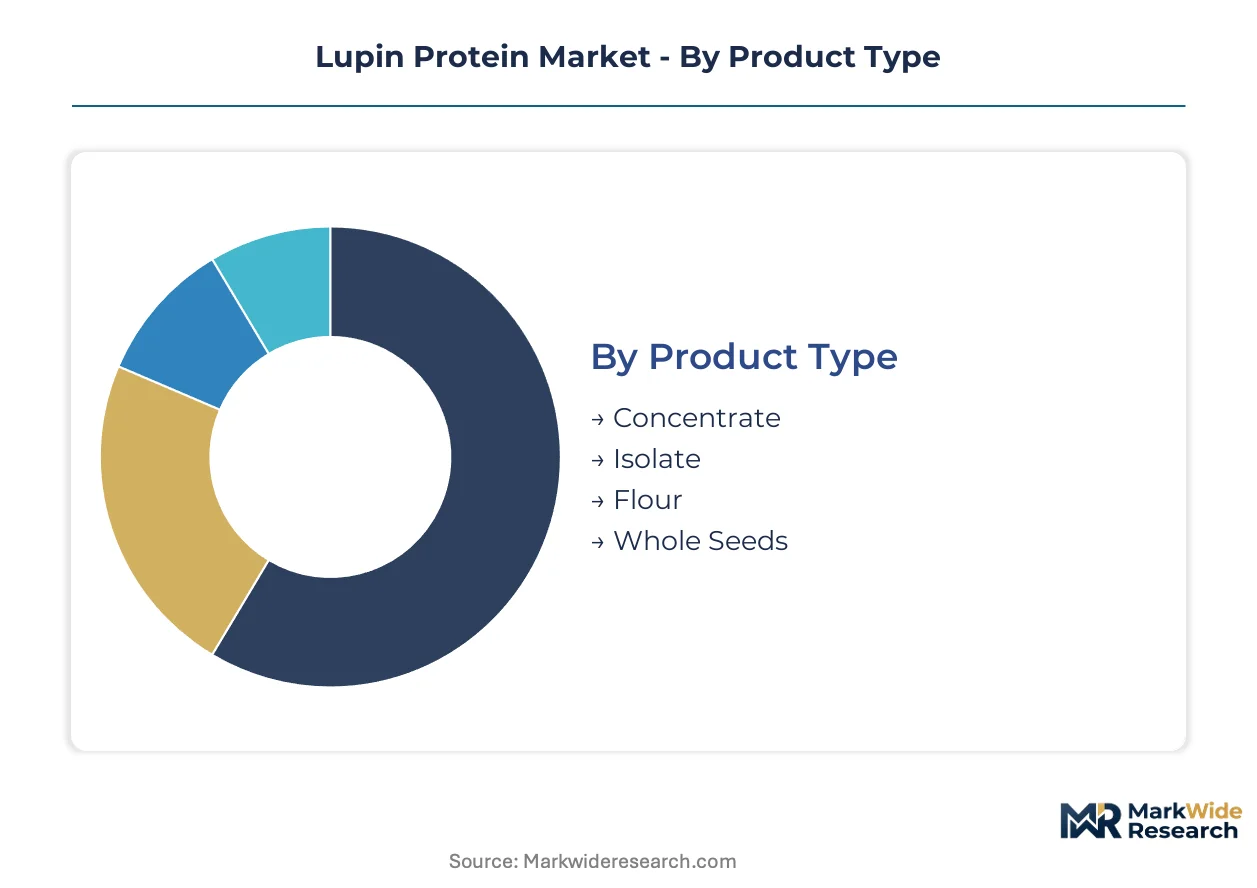
Segmentation in lupin protein reveals how extraction technology, end-use functionality, and distribution economics partition value capture across supply chain tiers. Processors must align product grade investments with specific channel and application requirements to avoid margin erosion.
Product Type:
Concentrate and isolate grades flow predominantly through export channels serving German and Dutch food manufacturers, while flour and whole seed segments serve domestic European bakery and feed compounders.
- Concentrate:Protein content ranges from 60% to 80% through aqueous extraction and partial purification. German plant-based meat manufacturers source concentrate grades for cost-sensitive clean-label formulations where isolate purity exceeds functional requirements.
- Isolate:Achieves 85% to 90% protein content via isoelectric precipitation and spray-drying. Belgian and Dutch processing hubs export isolate to premium meat analog and sports nutrition applications where allergen-free positioning commands supplier selection priority.
- Flour:Ground whole or dehulled seeds at 35% to 45% protein serve regional French and Spanish bakery and animal feed compounders with minimal processing overhead.
- Whole Seeds:Raw dehulled Lupinus angustifolius or Lupinus albus bypass protein extraction entirely for direct use in specialty feed and limited food applications.
Flour commands the established base. The steepest expansion runs through Isolate.
End Use:
Cost tier stratification separates premium-positioned nutritional supplements from commodity-absorbing animal feed, with food products and bakery occupying intermediate value bands.
- Food Products:Meat analogs, dairy alternatives, and prepared foods in Western European manufacturing clusters. EFSA novel food authorization requirements shape formulation adoption timelines for isolate-containing products.
- Nutritional Supplements:Protein powders and ready-to-drink beverages targeting allergen-sensitive consumers. FDA GRAS self-affirmation enables faster US commercialization than European regulatory pathways.
- Animal Feed:Poultry and aquaculture rations absorb lower-grade flour and processing byproducts. French and Spanish cultivation zones supply regional compounders with minimal transport cost.
- Bakery:High-protein bread and pastry formulations in German and Austrian industrial baking operations. Rheological testing requirements extend customer onboarding cycles for lupin substitution trials.
Nutritional supplements capture premium pricing. Food products are gaining share fastest.
Form:
Volume concentration favors powder formats across manufacturing channels, while liquid development addresses solubility-critical beverage applications with nascent commercial traction.
- Powder:Dominates nutritional supplements and food manufacturing distribution. Spray-dried isolates from Prolupin GmbH and Dutch processors flow through bulk ingredient procurement contracts.
- Liquid:Emerging format for high-protein beverages where solubility parameters prove critical. Beverage co-manufacturers in Germany pilot lupin protein dispersions for ready-to-drink applications.
- Granules:Intermediate moisture format for specific feed and limited food processing applications with restricted shelf stability requirements.
- Whole:Unprocessed seeds for specialty feed and select food uses bypassing extraction economics entirely.
Powder maintains supply dominance. Liquid climbs the fastest among developing formats.
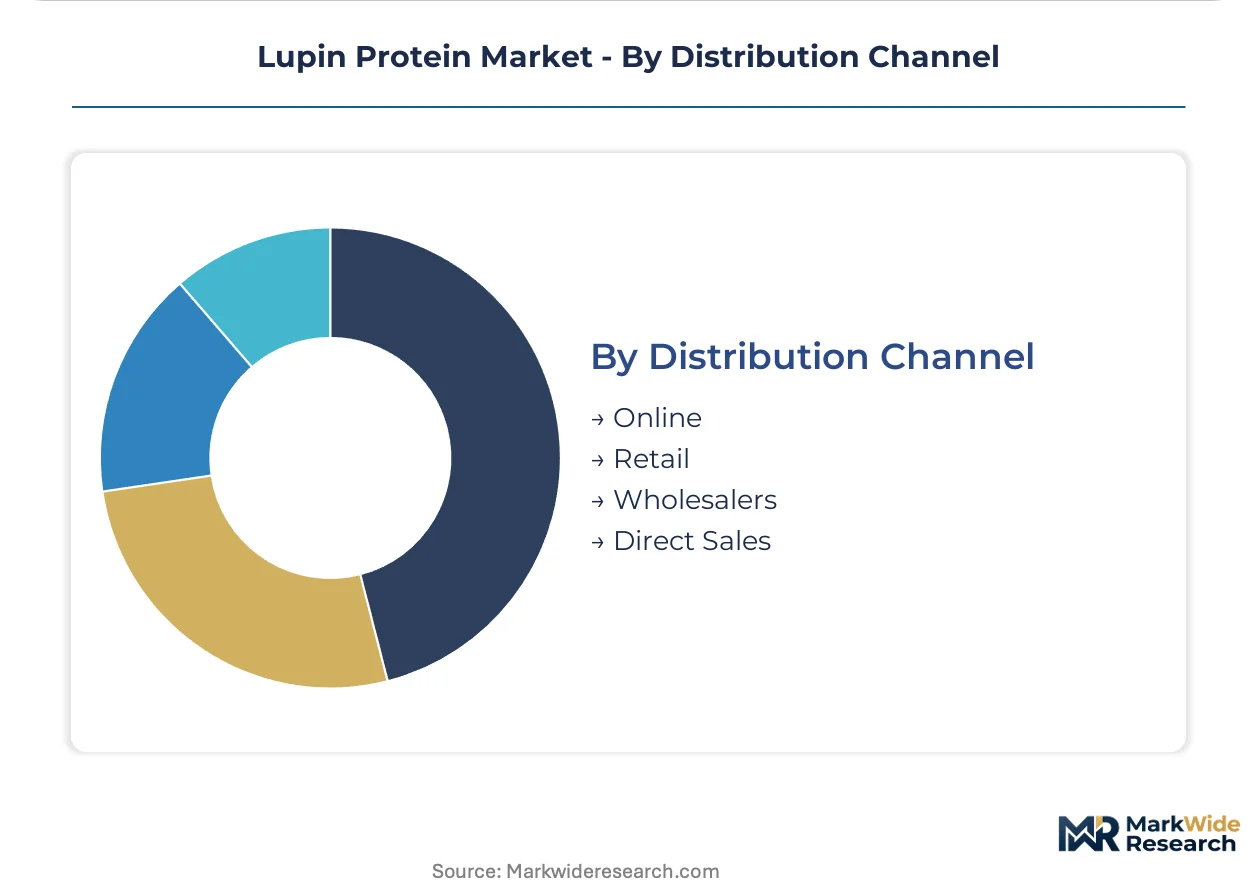
Distribution Channel:
Customer type fragmentation splits bulk procurement through direct sales and wholesalers from fragmented retail and online volumes serving small-scale formulators.
- Direct Sales:German plant-based meat producers and Dutch ingredient hubs contract directly with extraction facilities for certified organic and non-GMO isolate supply. Blockchain-tracked provenance documentation satisfies REACH compliance and EU Green Deal traceability mandates.
- Wholesalers:Regional distributors aggregate flour and concentrate volumes for French, Spanish, and Italian bakery and feed compounders with lower certification requirements.
- Online:Nutritional supplement brands and small food manufacturers source packaged isolate and concentrate through B2B platforms with minimum order thresholds.
- Retail:Limited channel for consumer-packaged lupin flour and whole seeds through health food and specialty grocery in urban European markets.
Direct sales anchor industrial volume. Online channels expand most quickly for mid-scale formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German processors commanding premium isolate margins, while French and Spanish suppliers compete on flour volume. Regulatory divergence between EFSA novel food pathways and FDA GRAS self-affirmation creates commercial timeline asymmetries. Raw material cultivation clusters in Western Europe anchor supply security calculations for downstream formulators.
Germany
Plant-based meat manufacturers in Berlin and Hamburg drive concentrated isolate procurement for clean-label binder applications. EFSA novel food authorization compresses market entry timelines for domestic extraction facilities. The Bavarian processing corridor sustains premium spray-drying capacity serving Dutch and Belgian ingredient hubs.
France
Commercial lupin cultivation in the Massif Central supplies regional flour millers serving bakery and animal feed compounders. EU Green Deal agricultural subsidies stabilize farmer planting decisions against soybean import competition. The Occitanie region anchors dehulling and basic processing infrastructure with minimal transport cost to Spanish border markets.
Netherlands
Rotterdam and Amsterdam ingredient hubs export isolate grades to German meat analog manufacturers under blockchain-tracked provenance systems. REACH compliance mandates drive investment in farm-to-facility traceability documentation. The Randstad cluster concentrates aqueous extraction expertise and membrane filtration engineering talent.
United States
FDA GRAS self-affirmation enables faster commercialization of concentrate grades in sports nutrition and ready-to-drink beverages. SunOpta Inc. leverages North American organic certification networks for premium shelf placement. California and Pacific Northwest co-manufacturers pilot liquid format development for high-protein beverage applications.
Australia
Coorow Seeds anchors domestic cultivation and basic processing for Asian export markets. The country's national food regulator maintains alignment with Codex standards for novel protein ingredient safety assessments. Western Australian growing regions supply dehulled Lupinus angustifolius to Southeast Asian feed compounders with minimal freight disadvantage.
Lupin Protein Market Competitive Environment
Concentration sits with extraction specialists possessing aqueous processing and spray-drying capabilities. The vendor base stratifies between premium isolate producers, bakery-grade concentrate suppliers, and commodity flour millers. Three archetypes dominate: German-engineered isolate specialists, North American organic-certified distributors, and Mediterranean-origin cultivation-integrated processors. Capacity expansion and direct contracting with plant-based meat manufacturers constitute the primary competitive vectors.
Among European-engineered specialists, Prolupin GmbH exemplifies the premium isolate archetype through its German extraction infrastructure. FRANK Food Products occupies a position within the bakery-grade concentrate tier, while SunOpta Inc. anchors the North American organic-certified distribution segment. These three entities represent the structural divergence between capital-intensive functional protein extraction and volume-oriented commodity milling.
| Leading Market Players |
|---|
| Lup'ingredients |
| FRANK Food Products |
| Prolupin GmbH |
| The Protein Bread Company |
| A. Costantino & C. SpA |
| Aminola |
| Coorow Seeds |
| SunOpta Inc. |
| Barentz International B.V. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German plant-based meat manufacturers and Dutch extraction facilities lock in isolate supply access while stabilizing price visibility across volatile raw material harvest cycles. These bilateral agreements concentrate procurement power among EFSA-authorized processors, compressing spot-market liquidity for uncontracted flour volumes.
Pricing Analysis
The customization-premium spread separates configured-to-order isolate grades from standard flour milling, with protein purity tiers and EFSA novel food certification status driving price differentiation. Three-tier pricing structure across premium isolate, standard concentrate, and economy flour levels reflects extraction capital intensity and regulatory compliance burdens. Cost compression in flour segments intensifies because soy protein substitution erodes pricing power in bakery applications. Animal feed compounders exhibit highest price sensitivity, while sports nutrition brands absorb premium isolate markups for allergen-free positioning.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg ports constrain isolate distribution economics to Asian export markets, favoring European over intercontinental trade lanes. Supply concentrates in France, Spain, and Germany for raw lupin cultivation, with Dutch and Belgian hubs anchoring downstream extraction capacity. Processing draws from dehulled Lupinus angustifolius seeds, aqueous extraction chemicals, and spray-drying energy inputs. Single-source vulnerability runs through EFSA-authorized isolate facilities serving German meat analog manufacturers. Distribution runs through direct sales contracts with blockchain-tracked provenance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lupin protein market sits at a platform-economics inflection where EFSA novel food authorization creates interoperability standards that concentrate value capture among certified processors. Regulatory pathway alignment between extraction facilities and downstream formulators is restructuring competitive access.
For Market Incumbents: Consolidate aqueous extraction capacity in the Randstad cluster to defend against membrane filtration technology displacement from emerging Dutch engineering specialists. Lock in backward integration into French Massif Central cultivation zones through long-term farmer contracting, securing raw material priority access before EU Green Deal subsidy fluctuations alter planting economics. For New Entrants and Emerging Players: Differentiate on liquid format solubility specifications for beverage co-manufacturers, where powder-dominant incumbents lack functional formulation expertise. Target underpenetrated US sports nutrition channels via FDA GRAS self-affirmation pathways, bypassing EFSA timeline delays that constrain European rivals. Lead with allergen-sensitive positioning and organic certification to command premium shelf placement. For Investors and Strategic Acquirers: Extraction specialists with captive spray-drying infrastructure and EFSA dossier experience represent the highest-conviction acquisition archetype for platform consolidation plays. Monitor EFSA novel food opinion publication velocity as the critical inflection signal; acceleration in authorization timelines would compress competitive moats and trigger facility valuation repricing across Western European processing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Accelerates market access timelines for isolate grades targeting German meat analog manufacturers. |
| Backward Integration into Cultivation | Secures raw material supply from French and Spanish growing regions against EU subsidy volatility. |
| Liquid Format Development Partnerships | Opens beverage channel access through German co-manufacturer solubility collaboration. |
| Blockchain Traceability Implementation | Satisfies REACH compliance and EU Green Deal documentation mandates for Dutch ingredient hubs. |
| US FDA GRAS Self-Affirmation Pathway | Enables faster commercialization in sports nutrition versus European regulatory timelines. |
Study Parameters
Desk research of EFSA novel food authorization databases, EU agricultural subsidy registries, and trade flow customs data preceded structured interviews with extraction facility plant managers, German plant-based meat procurement leads, Dutch ingredient hub technical directors, and French cultivation cooperative agronomists. Primary fieldwork with membrane filtration equipment suppliers and beverage co-manufacturer R&D heads validated secondary assumptions. Bottom-up volume modeling from named processing facilities triangulated against top-down protein ingredient demand projections.
Variance decomposition across protein grade tiers, end-use application clusters, and regional regulatory frameworks shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include isolate-concentrate-flour product grades, meat analog-sports nutrition-bakery-feed end uses, and powder-liquid form factors. CAGRs derived from facility capacity expansion announcements, EFSA authorization velocity trends, and substitution elasticity estimates for soy protein displacement. Carbon accounting rule evolution and EU Green Deal agricultural payment schedules served as scenario-weighting inputs.
The analysis sits within stated boundaries; outcomes outside EFSA regulatory pathway timelines, EU subsidy continuity, or aqueous extraction technology cost curves would require recalibration. Forecasts reflect documented assumptions regarding novel food authorization acceleration, membrane filtration adoption rates, and German meat analog procurement growth. Alkaloid processing cost breakthroughs or South American lupin cultivation scale-up would necessitate model revision. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Papain Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Zein Protein Market