
 Cultured Meat Market | 2026-2036
Cultured Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Cultured Meat Market Analysis
Scaffold-free bioprocessing is reshaping how cultured meat achieves texture fidelity at commercial scale. Aleph Farms leverages whole-muscle cultivation to anchor premium positioning in steak applications. Mosa Meat sustains R&D intensity across serum-free media development. UPSIDE Foods dominates regulatory engagement through its pre-market consultations with the FDA.
Cultured meat denotes animal protein produced through in vitro cell proliferation in bioreactors, utilizing myosatellite cells cultured in nutrient-rich media at controlled temperature and pH to generate tissue with compositional parity to conventional slaughtered meat. Its primary commercial purpose centers on decoupling protein supply from industrial animal agriculture. Burgers currently occupy the largest volume share given simpler structural requirements and established consumer familiarity, while 3D bioprinting represents the fastest-expanding technology segment as it addresses whole-cut texture complexity. Tissue engineering commands concentrated margin pools through proprietary scaffold architectures that differentiate finished product quality.
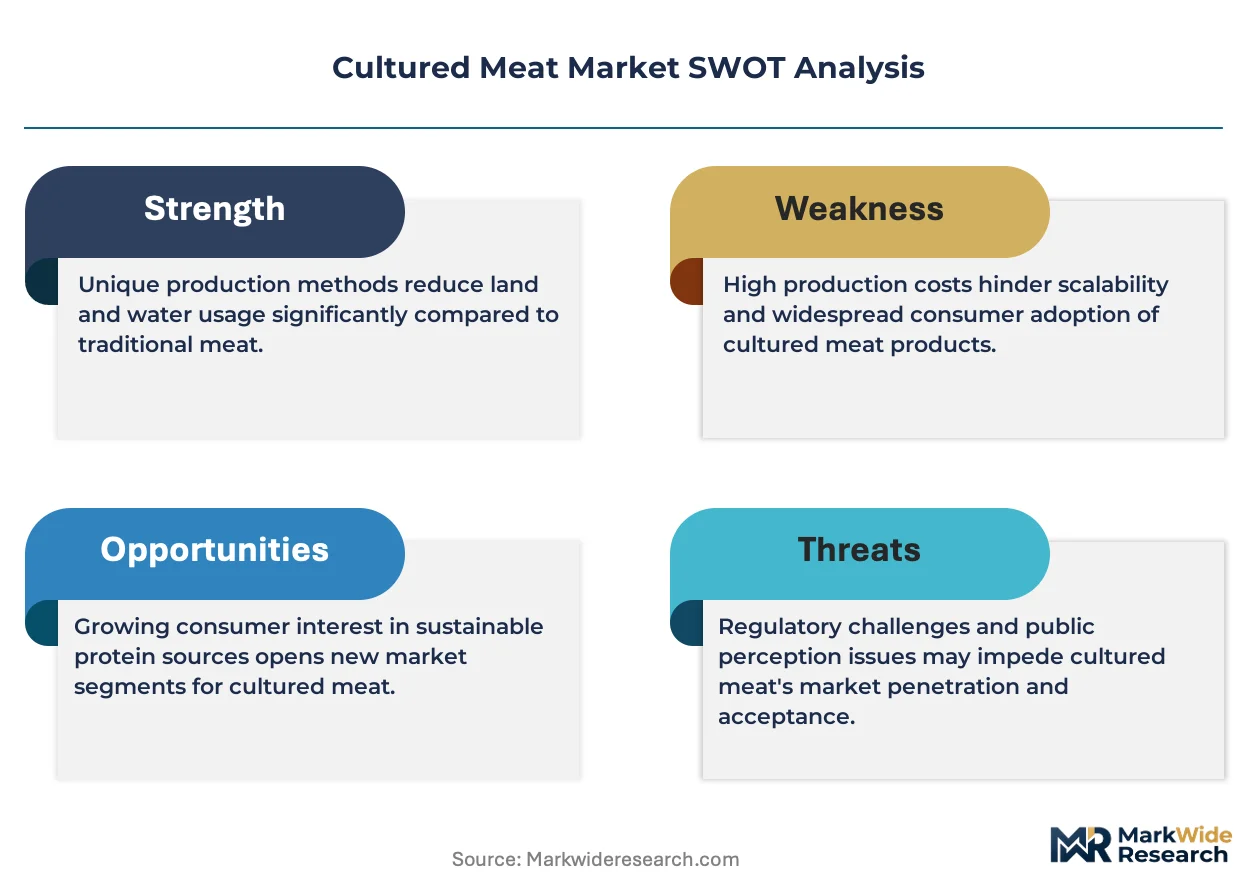
The FDA and USDA jointly oversee cultured meat safety and labeling in the United States, creating a dual-agency pathway that extends time-to-market but elevates consumer trust thresholds. Singapore's national food regulator established the first commercial approval framework, directly enabling restaurant channel access. The EU's EFSA and novel food regulation under the General Food Law will shape European market entry timelines. Stakeholders must monitor which regulatory body completes its commercial framework next, as this sequence will determine geographic priority for capacity allocation.
Market Dynamics
Serum-free media formulation is compressing production costs and enabling regulatory compliance pathways that were previously blocked by fetal bovine serum dependency.
Growth Catalysts
- Singapore's SFA commercial approval framework:The national food regulator's 2020 authorization of cultured chicken for restaurant sale established the first legally operative market entry pathway, demonstrating that novel food safety assessment protocols can function at commercial velocity.
- Scaffold-free bioprocessing:This cultivation architecture eliminates structural material costs and simplifies downstream purification, directly addressing the texture-fidelity requirements of whole-muscle applications without proprietary polymer dependencies.
- Restaurant channel concentration:Foodservice operators absorb premium pricing through menu engineering while managing consumer education through controlled tasting environments, creating demand pull that retail distribution cannot yet replicate.
Market Restraints
- Fetal bovine serum cost volatility:Traditional media formulations remain tethered to commodity slaughter byproduct markets, exposing margin structures to agricultural supply shocks that contradict the sector's decoupling thesis.
- Bioreactor manufacturing concentration:Single-use vessel and sensor supply chains cluster in German and Swiss precision engineering hubs, creating equipment procurement bottlenecks that extend facility commissioning timelines.
- Dual-agency regulatory friction:The FDA-USDA joint oversight model in the United States imposes sequential review stages that compound time-to-market without commensurate safety differentiation.
Strategic Opportunities
- Pet food application expansion:Companion animal nutrition tolerates higher price points and lower aesthetic fidelity than human consumption, creating a commercialization bridge while human-food sensory standards mature.
- EU novel food regulatory tailwind:EFSA's evolving guidance under the General Food Law promises harmonized pre-market authorization that would unlock 27-country distribution scale upon first approval.
- 3D bioprinting convergence with tissue engineering:Layered deposition technologies combined with vascularization protocols address the central technical barrier to whole-cut texture replication.
Industry Challenges
- Cell line bioprocessing talent scarcity:Industrial-scale myosatellite cultivation requires hybrid expertise across mammalian cell biology and food-grade manufacturing that existing academic and pharmaceutical pipelines do not produce.
- Cleanroom facility capex intensity:GMP-adjacent production environments demand capital deployment per square foot that exceeds conventional protein processing infrastructure by an order of magnitude.
- Labeling compliance timeline uncertainty:Disputes over "meat" nomenclature jurisdiction between agriculture departments and health agencies in multiple jurisdictions delay packaging finalization and retail channel planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultured Meat Market |
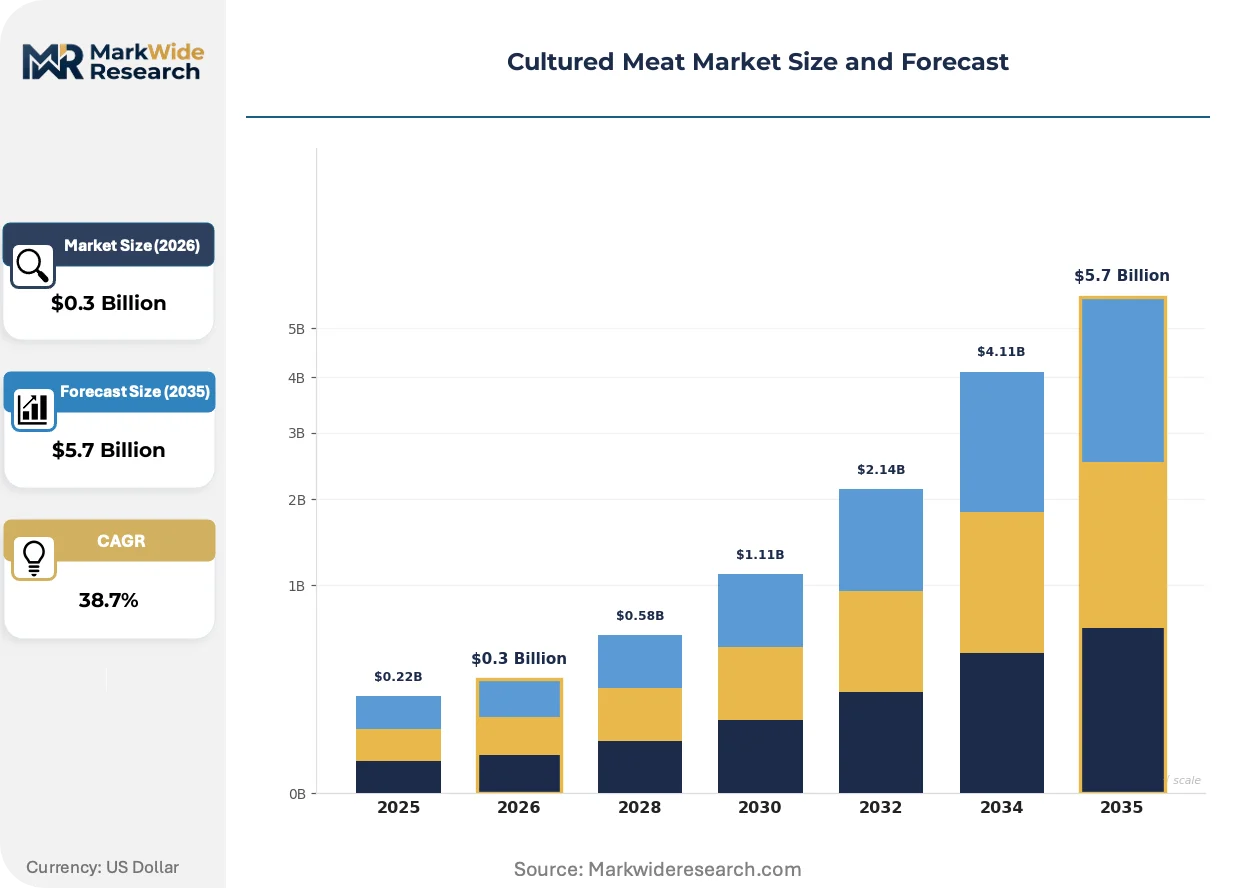
| Market Size in 2026 | $0.3 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Sausages, Nuggets, Meatballs Technology: 3D Bioprinting, Cell Culture, Tissue Engineering, Scaffold Technology Distribution Channel: Retail, Food Service, Direct-to-Consumer, Online Grocery End User: Restaurants, Supermarkets, Meal Kit Services, Catering Companies |
| Companies Covered | Aleph Farms, Mosa Meat, UPSIDE Foods, GOOD Meat, BlueNalu, Future Meat Technologies, Meatable, Finless Foods, Shiok Meats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultured Meat Market Emerging Trajectories
Bioprocess intensification is collapsing the cost curve while regulatory sequencing determines which geographies absorb initial capacity deployment.
Perfusion bioreactor operation is migrating from batch-fed cultivation toward continuous media exchange systems. Steak-focused producers adopt this mode to sustain cell density at commercial scale without nutrient depletion. The shift is compressing unit economics toward price parity benchmarks by reducing media volume per kilogram of biomass output.
EFSA's novel food guidance evolution under the EU General Food Law is reshaping European entry strategy. The regulatory body has signaled streamlined safety assessment pathways for precision fermentation and cell culture derivatives. Protein producers are redirecting pre-submission resources toward Brussels rather than pursuing fragmented national approvals.
Foodservice procurement contracts now specify provenance verification protocols that extend upstream to cell line origin documentation. Restaurant groups in Singapore and the United States require batch-level traceability that exceeds conventional meat supply chain standards. This specification pattern is visible most acutely in premium steakhouse segments where narrative transparency commands menu price premiums.
Cultured Meat Market Segmentation
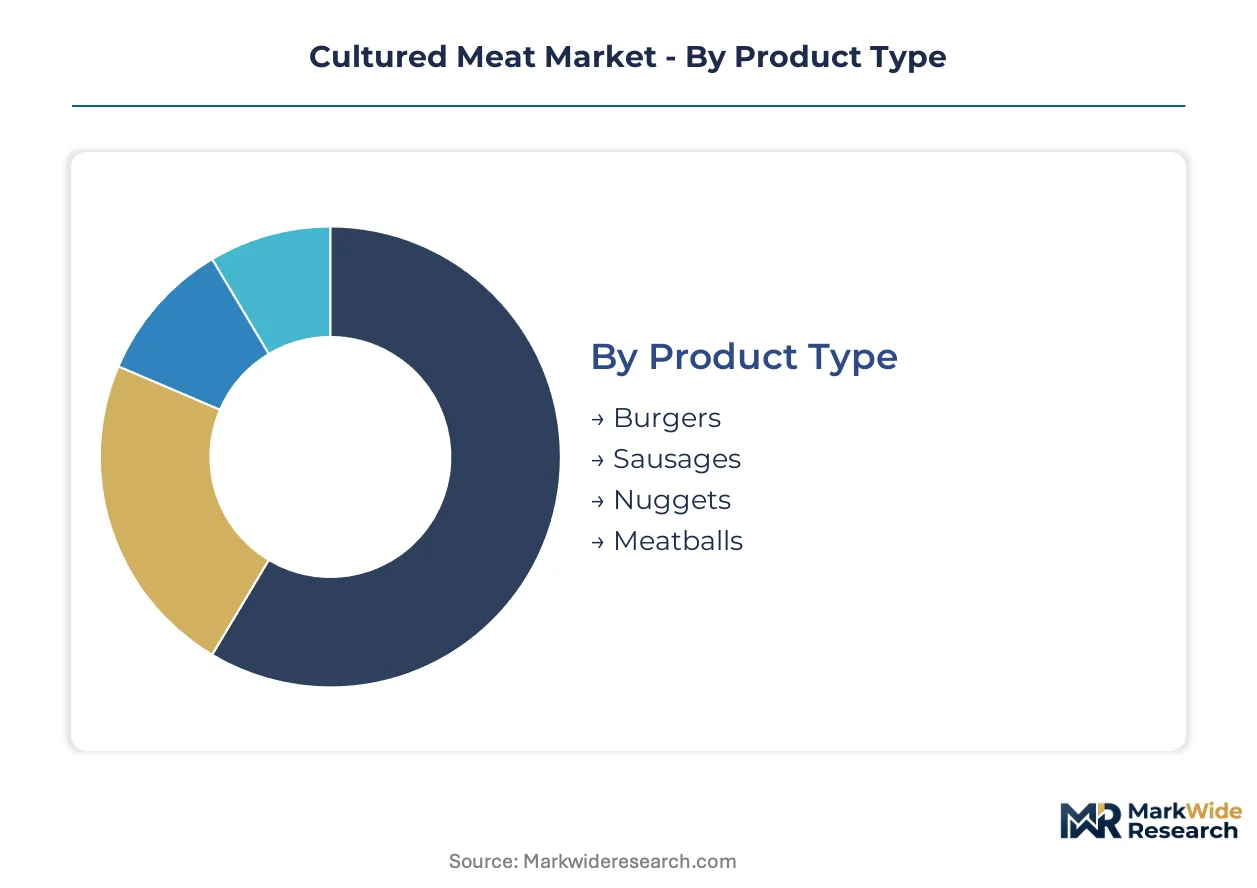
Product architecture and channel configuration determine margin capture in cultured meat. Segment boundaries shift as bioprocessing economics evolve and regulatory access unlocks new customer touchpoints.
Product Type:
Application complexity separates volume leaders from premium positioning plays in this dimension.
- Burgers:Ground tissue formats leverage simpler structural requirements and established consumer familiarity. Restaurant chains in Singapore and the United States concentrate procurement here, driven by menu integration speed and lower sensory fidelity thresholds.
- Sausages:Encased products accommodate heterogeneous cell distributions and spice masking. German and Swiss foodservice distributors prioritize this format for breakfast and casual dining applications where texture uniformity matters less than flavor delivery.
- Nuggets:Breaded coatings obscure visual and textural deviations from conventional poultry. Quick-service operators in Asia-Pacific markets specify this format for children's menu placement and price-sensitive dayparts.
- Meatballs:Comminuted structures suit sauce-based preparations and frozen retail formats. Italian and Nordic retail chains source these for ready-meal partnerships where binding agents compensate for myofibrillar protein limitations.
Burgers hold installed capacity. Sausages is rotating up the share rankings.
Technology:
Cost tier and capital intensity stratify competitive positioning across cultivation methodologies.
- 3D Bioprinting:Layered deposition systems assemble cell-laden bioinks into vascularized tissue architectures. Steak producers in Israel and Japan concentrate investment here, driven by whole-cut texture fidelity requirements that command premium pricing.
- Cell Culture:Suspension bioreactor cultivation of myosatellite cells in nutrient media represents the baseline platform. Singaporean and Dutch manufacturers scale this approach first, constrained by serum-free media formulation costs and downstream purification yields.
- Tissue Engineering:Scaffold-guided differentiation directs cell organization into aligned muscle fibers. United Kingdom and South Korean developers pursue this for premium beef applications where anisotropic texture determines consumer acceptance.
- Scaffold Technology:Edible polymer matrices provide structural templates for cell attachment and proliferation. Australian and Canadian suppliers commercialize plant-derived hydrogels that address regulatory concerns about synthetic material residues.
Cell Culture dominates current throughput. 3D Bioprinting is climbing the fastest.
Distribution Channel:
Customer type and purchase occasion shape margin structure and brand control requirements.
- Food Service:Restaurant and institutional procurement absorbs premium pricing through menu engineering. Singaporean steakhouse groups and United States fine-dining chains specify provenance documentation that exceeds conventional meat standards.
- Retail:Supermarket and specialty store placement demands packaging finalization and labeling compliance. German and French retailers pilot frozen formats pending EU novel food authorization timelines.
- Direct-to-Consumer:Subscription and brand-owned e-commerce enable narrative control and margin retention. Dutch and Israeli producers test this channel for early-adopter segmentation and sensory feedback collection.
- Online Grocery:Third-party platform distribution leverages existing cold-chain logistics. United Kingdom and South Korean delivery apps list limited SKUs where regulatory clarity permits cross-border fulfillment.
Food Service captures current revenue concentration. Direct-to-Consumer is gaining share fastest.
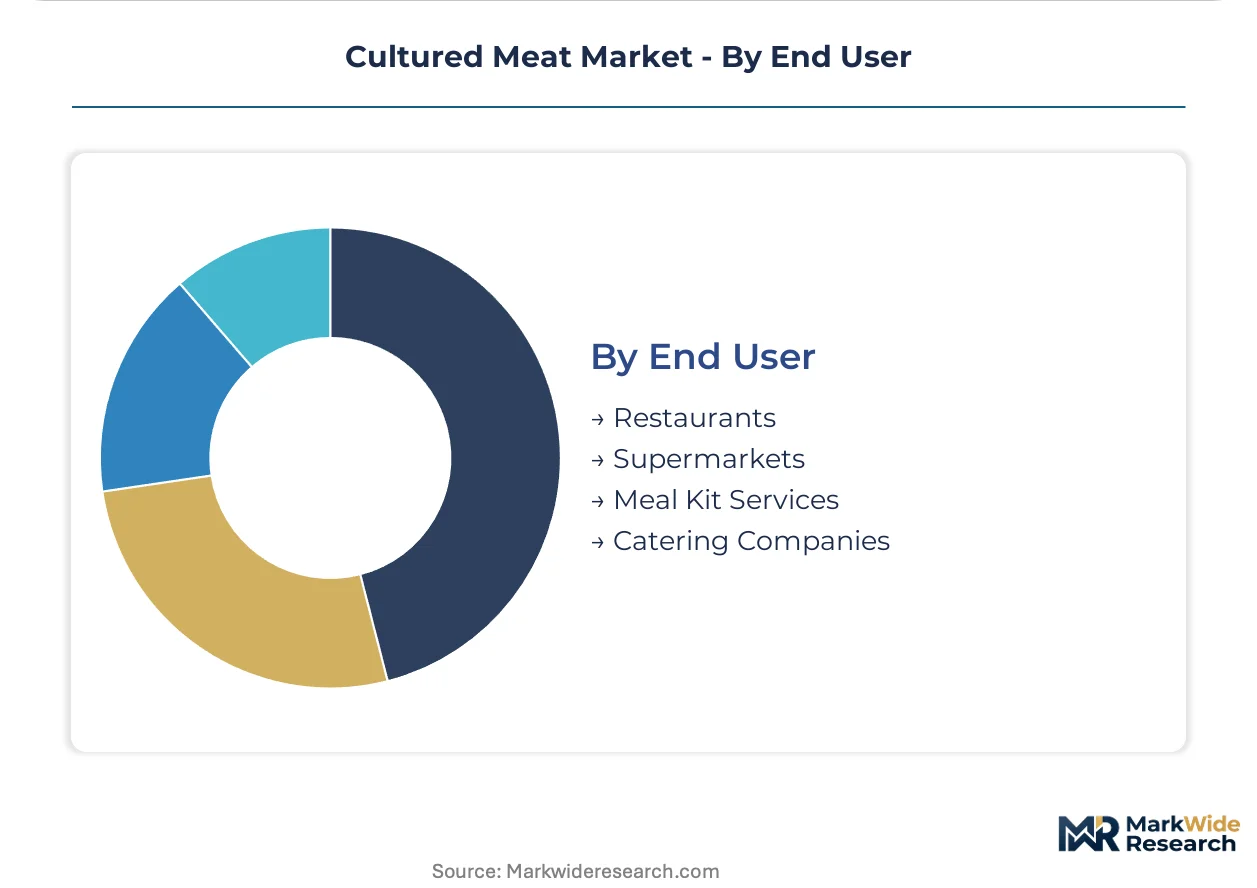
End User:
Volume scale and price sensitivity differentiate customer segments in procurement behavior.
- Restaurants:Full-service and limited-service operators manage consumer education through controlled tasting environments. Singapore's national regulator enabled this segment first, establishing batch-level traceability protocols that premium steakhouse groups now require.
- Supermarkets:Grocery retailers negotiate slotting fees and promotional support that strain nascent margin structures. German and Swiss chains await EFSA guidance before committing shelf space.
- Meal Kit Services:Portioned ingredients with recipe instructions tolerate higher per-gram pricing than retail. United States and United Kingdom subscription platforms trial cultured protein for sustainability-positioned customer cohorts.
- Catering Companies:Institutional and event feeding contracts prioritize cost predictability and supply security. Dutch and Danish catering operators evaluate long-term agreements as production scale commitments firm.
Restaurants anchor demand pull. Meal Kit Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports regulatory precedent to foodservice operators across Asia-Pacific and the Middle East, establishing the first commercial pathway that Israeli and Dutch producers now leverage for market entry.
Singapore
Restaurant groups in Marina Bay and Orchard Road absorb premium pricing through steakhouse menu engineering. The Singapore Food Agency's 2020 approval of cultured chicken established the world's first legally operative novel food framework. Tuas Biomedical Park hosts production facilities where serum-free media bioprocessing scales for regional export.
United States
Fine-dining chains in California and New York manage consumer education through controlled tasting environments. FDA and USDA joint oversight creates sequential review stages that extend time-to-market for domestic producers. San Francisco and Boston metropolitan areas concentrate venture-backed bioreactor manufacturing and pre-market consultation activity.
Netherlands
Foodservice distributors in Amsterdam and Rotterdam prioritize sausage formats for casual dining applications. EFSA novel food guidance under the EU General Food Law shapes pre-submission resource allocation toward Brussels. Eindhoven's precision engineering cluster supplies single-use bioreactor vessels to European facility developers.
Israel
Steak-focused producers command premium positioning through whole-muscle texture fidelity requirements. The national food regulator engages with developers on safety assessment protocols ahead of formal commercial frameworks. Rehovot's biotech corridor anchors cultivated protein R&D intensity alongside pharmaceutical cell culture expertise.
Japan
Quick-service operators in Tokyo and Osaka trial breaded nugget formats for children's menu placement. METI funding programs support 3D bioprinting convergence with vascularization protocols for whole-cut applications. Osaka's industrial machinery sector adapts layered deposition systems from medical tissue engineering to food-grade manufacturing.
Cultured Meat Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base clusters around three strategic archetypes: steak-focused whole-muscle cultivators, serum-free media formulators, and regulatory-first engagement specialists. Dominant competitive moves include strategic partnerships with foodservice distributors and technology licensing for scaffold-free bioprocessing architectures.
Within the steak-focused archetype, Aleph Farms and Mosa Meat exemplify premium positioning through texture fidelity differentiation. UPSIDE Foods anchors the regulatory-first vector through sustained FDA pre-market consultation activity. These three entities occupy positions that span Israeli, Dutch, and United States geographic origins respectively, reflecting the sector's distributed innovation base.
| Leading Market Players |
|---|
| Aleph Farms |
| Mosa Meat |
| UPSIDE Foods |
| GOOD Meat |
| BlueNalu |
| Future Meat Technologies |
| Meatable |
| Finless Foods |
| Shiok Meats |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Singapore maritime corridor carries German precision bioreactor components and Dutch serum-free media formulations across 8,000 nautical miles, with freight cost volatility directly compressing margin structures for Israeli steak cultivators while amplifying price premiums for Singaporean foodservice distributors who control narrative access to Asia-Pacific restaurant channels.
Pricing Analysis
Cell culture platform pricing separates sharply from 3D bioprinting and tissue engineering tiers. Three-tier pricing structure across premium steakhouse placements, mid-market casual dining, and economy-format nuggets reflects quality grade differentiation and FDA-USDA dual-agency certification status. Pricing pressure stems from serum-free media formulation costs that remain above commodity slaughter byproduct benchmarks. Quick-service operators exhibit highest price sensitivity; Marina Bay steakhouse groups absorb premiums through menu engineering.
Supply Chain Analysis
Upstream feedstock concentration centers on German and Swiss precision engineering hubs for single-use bioreactor vessels, Dutch fermentation-derived growth factor suppliers, and Singaporean serum-free media formulators. Raw material dependencies include pharmaceutical-grade glucose, recombinant protein supplements, and food-grade hydrogel polymers. Single-source vulnerability in sensor procurement creates equipment commissioning bottlenecks. Distribution runs through foodservice procurement contracts with batch-level traceability requirements exceeding conventional meat standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cultured meat sector is entering a cyclical recovery phase as regulatory approval sequencing accelerates capital deployment, with Singapore's SFA commercial framework serving as the demand-pull catalyst that resets investment timelines across Israeli, Dutch, and United States production clusters.
For Market Incumbents: Insulate margin structures through captive supply of serum-free media formulations and backward integration into precision bioreactor manufacturing. Aleph Farms and Mosa Meat demonstrate premium positioning defense through whole-muscle texture fidelity patents that emerging scaffold-free competitors cannot replicate. Channel control via exclusive foodservice distribution agreements in Singapore and California represents the critical lever against retail price erosion. For New Entrants and Emerging Players: Pet food applications in the United States and United Kingdom represent the most penetrable entry point, tolerating higher price points and lower sensory fidelity while human-food standards mature. EU novel food regulatory tailwinds position Dutch and German markets for first-mover advantage upon EFSA authorization. Direct-to-consumer subscription models enable sensory feedback collection without retail slotting fee burdens. For Investors and Strategic Acquirers: FDA pre-market consultation completion reshapes the acquisition landscape by de-risking United States market entry for portfolio companies. Five-to-ten year viability hinges on serum-free media cost curves achieving price parity with conventional protein. Target acquisition archetype: Israeli or Dutch steak-focused cultivators with scaffold-free bioprocessing IP and active regulatory engagement. Monitor EFSA novel food guidance publication as the definitive inflection signal for European capacity allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Serum-Free Media Scale-Up | FDA and USDA joint oversight pathways accelerate once fetal bovine serum dependency is eliminated from production. |
| Foodservice Distribution Partnership | Singapore steakhouse groups require provenance documentation that locks in premium pricing through controlled channel access. |
| Scaffold-Free Bioprocessing Licensing | Israeli developers monetize texture-fidelity IP while avoiding proprietary polymer regulatory scrutiny in EU markets. |
| 3D Bioprinting Convergence | Japanese METI-funded vascularization protocols address whole-cut replication barriers for premium beef applications. |
| Regulatory-First Engagement | UPSIDE Foods demonstrates that sustained FDA pre-market consultation compresses time-to-market versus sequential review stages. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA pre-market consultation filings, EFSA novel food guidance documents, Singapore Food Agency approval records, and trade data from Dutch and German precision engineering exporters. Bioprocess engineers at Tuas Biomedical Park, regulatory affairs leads at Israeli cultivators, foodservice procurement directors in Marina Bay, and venture capital specialists in San Francisco provided structured input. Bottom-up capacity buildout estimates triangulate against top-down protein substitution demand models.
Forecast inputs include cell culture platform throughput assumptions, serum-free media cost compression trajectories, and regulatory approval sequencing across the analysis window. Segmentation dimensions span product architecture, cultivation technology, distribution channel configuration, and end-user procurement behavior. CAGRs derive from facility commissioning timelines and foodservice contract ramp rates. Industry-specific inputs incorporate bioreactor manufacturing lead times and EFSA pre-submission resource allocation patterns.
Stress conditions across media formulation cost volatility, dual-agency review delays, and bioreactor equipment procurement bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory sequencing and technology maturation curves. Cross-checking against Singapore Food Agency export permit volumes and Dutch foodservice distributor procurement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Zein Protein Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Trypsin Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
North America Eubiotics Market