
 Global Motorcycle Market | 2026-2036
Global Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motorcycle Market Outlook
Modular platform strategies is recalibrating buyer choice across the Global Motorcycle Market, as manufacturers unbundle powertrain, chassis, and electronics architectures to reduce SKU complexity and accelerate regional variant launches. Honda leverages its global manufacturing footprint to sustain cost leadership across multiple engine capacity tiers. Yamaha differentiates through racing-derived technology transfer into consumer sport segments. KTM specializes in lightweight, high-performance off-road platforms that command premium positioning in European and North American markets.
A motorcycle is a two-wheeled motorized vehicle propelled by an internal combustion engine or electric motor, typically featuring a tubular steel or aluminum frame, telescopic front forks, and a chain or belt final drive, designed for individual or dual-rider transportation across paved roads and unpaved terrain. Sport and off-road product types lead volume contribution in emerging economies where terrain variability and price sensitivity shape purchase decisions. Electric fuel types represent the fastest-expanding segment as battery energy density improvements and charging infrastructure deployment reduce range anxiety. Above 600cc engine capacity brackets concentrate margin pools in developed markets where discretionary spending supports premium brand loyalty.
The EPA in the United States enforces Tier 3 emission standards that constrain petrol engine displacement strategies for manufacturers seeking market access. India's BS-VI norms, administered by the country's national automotive regulator, compel catalytic converter integration and fuel injection adoption across the 50cc-125cc segment that constitutes domestic volume majority. The EU Green Deal and F-Gas Regulation are accelerating electric motorcycle homologation timelines. Stakeholders must monitor regulatory divergence between emission-centric frameworks and battery-subsidy regimes to align platform investment with market-access requirements.
Market Dynamics
Modular platform architectures are compressing development cycles across the Global Motorcycle Market as manufacturers unbundle powertrain, chassis, and electronics systems to serve heterogeneous regional regulations without proliferating distinct vehicle lines.
Growth Catalysts
- Last-mile delivery fleet expansion:E-commerce logistics operators across Indonesia, Vietnam, and Thailand are scaling two-wheeler procurement to navigate urban congestion and reduce per-delivery operational costs.
- BS-VI emission mandates:India's national automotive regulator compels fuel injection and catalytic converter integration across the 50cc-125cc segment, accelerating technology upgrade cycles among domestic volume manufacturers.
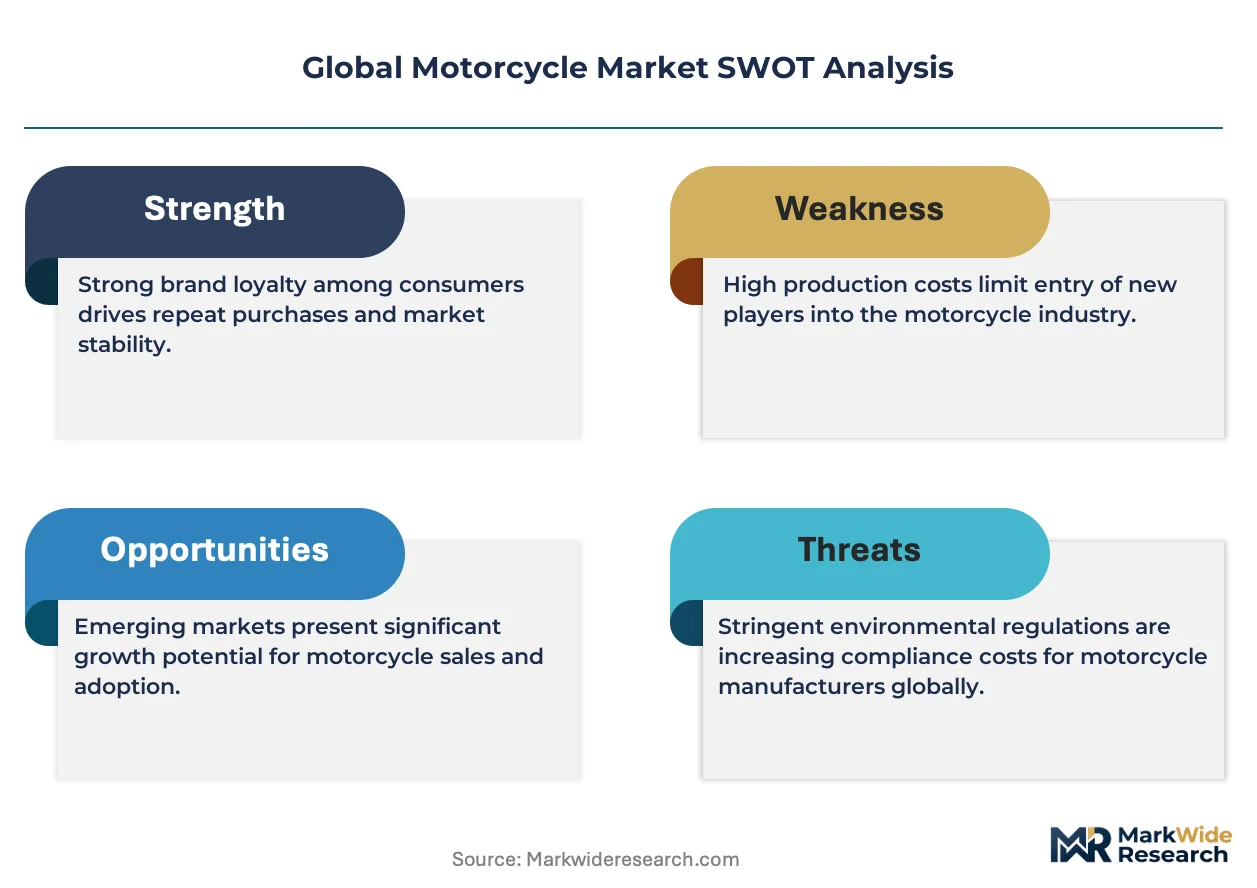
- Battery energy density improvements:Lithium-ion cell chemistry advances are extending electric motorcycle range thresholds, reducing consumer hesitation in European and North American urban commuting applications.
Market Restraints
- Raw material cost volatility:Lithium, cobalt, and rare earth price swings constrain electric powertrain cost parity timelines against internal combustion alternatives in price-sensitive emerging markets.
- Semiconductor supply concentration:Microcontroller and power electronics sourcing dependence on East Asian foundries creates vulnerability in electronic fuel injection and battery management system production.
- Charging infrastructure gaps:Inadequate fast-charging networks across Indian tier-2 cities and Southeast Asian provincial centers limit electric motorcycle adoption outside metropolitan cores.
Strategic Opportunities
- Brazilian market underpenetration:ANVISA regulatory alignment with EU emission frameworks creates pathway for European and Asian manufacturers to introduce premium electric models without duplicative homologation investments.
- Subscription-based ownership models:Battery-as-a-service and lease-to-own structures are emerging in Indian metropolitan markets, decoupling upfront acquisition cost from usage access.
- EU Green Deal subsidy pools:Member state purchase incentives and F-Gas Regulation compliance credits accelerate electric motorcycle margin recovery for manufacturers with localized assembly operations.
Industry Challenges
- Power electronics engineering scarcity:Shortage of motor control algorithm specialists and high-voltage systems engineers constrains electric platform development velocity across traditional internal combustion manufacturers.
- Dual homologation complexity:Simultaneous compliance with EPA Tier 3, EU Euro 5, and India's BS-VI frameworks fragments engineering resources and extends product launch timelines.
- Legacy dealer network reconfiguration:Transition from mechanical service dependency to software diagnostics and battery lifecycle management requires reskilling investments across established distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motorcycle Market |
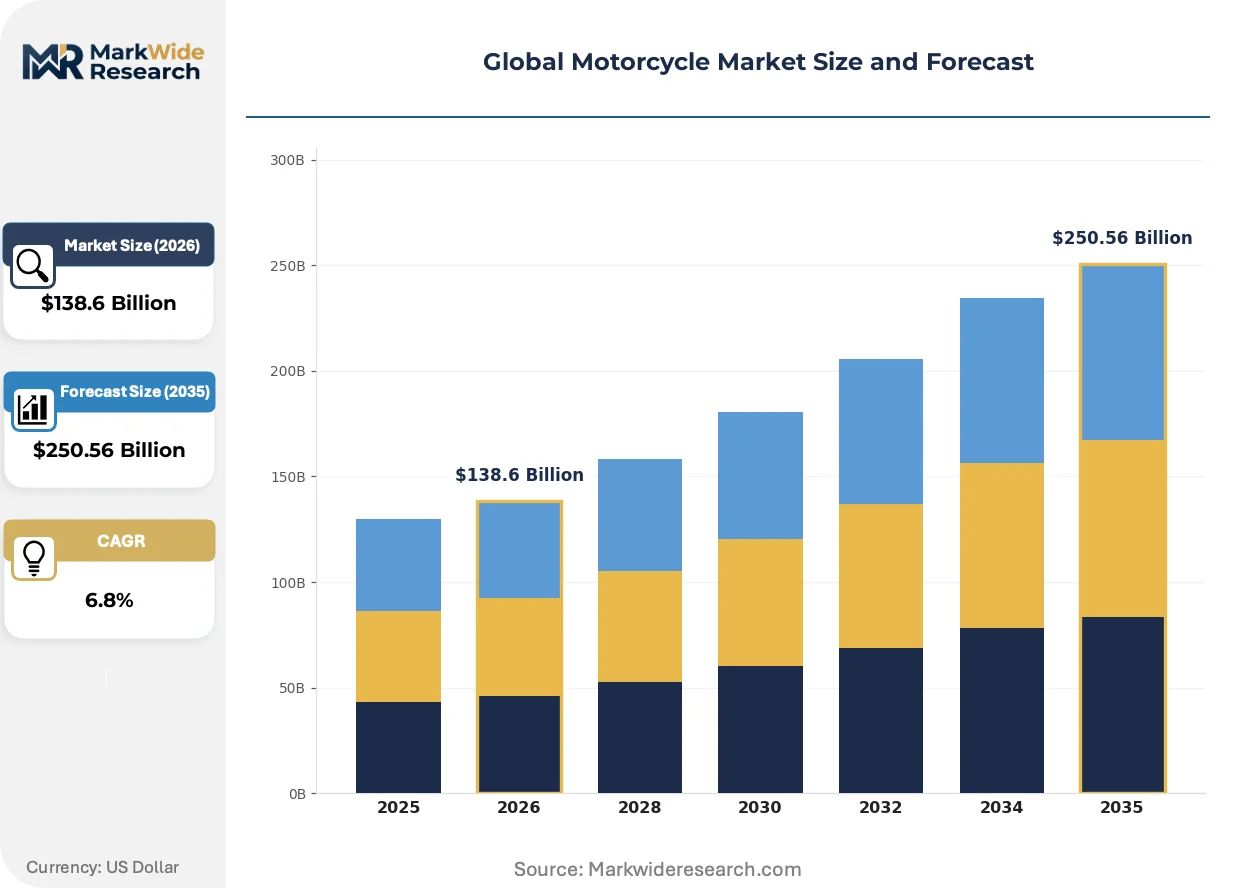
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport, Cruiser, Touring, Off-road Engine Capacity: 50cc-125cc, 126cc-250cc, 251cc-600cc, Above 600cc Fuel Type: Petrol, Electric, Diesel, Hybrid Market Channel: Direct Sales, Online Retail, Dealerships, Auctions |
| Companies Covered | TVS Motors, NIU, Honda, KTM, Yadea, Yamaha, Suzuki, Kawasaki, Bajaj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motorcycle Market Strategic Shifts
Electrification is restructuring competitive advantage around battery chemistry control and thermal management expertise rather than engine displacement optimization. Manufacturers are racing to secure cell supply agreements and develop proprietary battery management systems.
Vehicle-to-grid integration technology is automating bidirectional power flow between electric motorcycles and residential or commercial energy systems. Fleet operators in European urban centers are piloting aggregated battery storage pools that stabilize grid demand during peak hours. This capability is automating new revenue streams beyond mobility service provision, compressing total cost of ownership calculations for commercial buyers.
The EU F-Gas Regulation and accompanying battery passport requirements are mandating supply chain traceability and end-of-life recycling accountability. Manufacturers must document cobalt, lithium, and nickel sourcing through audited chain-of-custody systems to maintain market access. Premium European brands with established circular economy partnerships are capturing regulatory compliance advantages over entrants lacking reverse logistics infrastructure.
Direct-to-consumer digital sales channels are displacing traditional dealer-dependent purchase journeys among younger urban demographics. Vietnamese and Indonesian buyers increasingly configure vehicles online before limited showroom verification, reducing inventory carrying costs for distributors. This pattern concentrates in metropolitan markets where smartphone penetration and digital payment infrastructure support seamless transaction completion without physical negotiation.
Global Motorcycle Market Segmentation
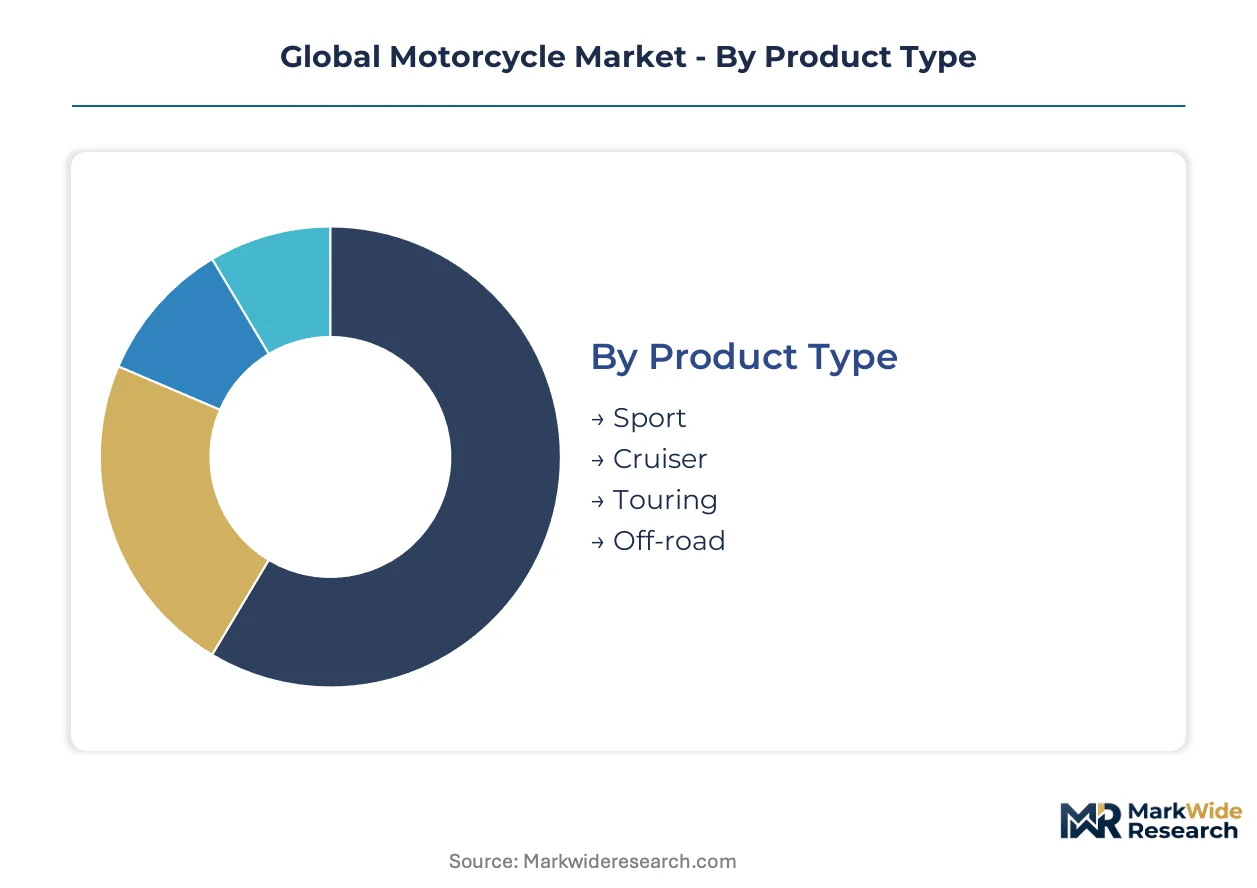
Motorcycle segmentation reveals how regulatory frameworks fragment engineering priorities across product architectures. Manufacturers must align platform investments with distinct certification burdens, emission thresholds, and channel economics that vary sharply by segment.
Product Type:
EPA Tier 3 certification governs Sport and Cruiser petrol variants entering US markets, while EU Euro 5 compliance shapes Touring and Off-road homologation timelines for European access.
- Sport:Aerodynamic fairings and high-revving engines define this category. Demand concentrates in Southeast Asian metropolitan corridors where young riders prioritize maneuverability through congested Jakarta and Bangkok traffic arteries.
- Cruiser:Low-slung ergonomics and torque-heavy V-twin configurations characterize this segment. Sales cluster in North American discretionary markets where brand heritage commands loyalty among riders above 45 years.
- Touring:Wind protection and luggage capacity specifications dominate. European long-distance commuters and rental fleet operators in the Alps region drive replacement cycles.
- Off-road:Lightweight frames and long-travel suspension systems enable terrain traversal. Australian agricultural properties and Brazilian ranching operations sustain commercial procurement.
Leading the category by volume: Off-road. Growing fastest: Sport.
Engine Capacity:
Cost tiers stratify sharply here, with 50cc-125cc units dominating emerging market unit economics while above 600cc brackets capture developed market margin pools.
- 50cc-125cc:Single-cylinder air-cooled architectures minimize production cost. India's BS-VI mandates have forced fuel injection adoption across this bracket, raising unit costs in a price-sensitive domestic majority segment.
- 126cc-250cc:Liquid-cooling and multi-valve heads improve thermal efficiency. Vietnamese urban delivery fleets and Indonesian ride-hailing operators are scaling procurement of this capacity for load-carrying versatility.
- 251cc-600cc:Parallel-twin and inline-four configurations balance performance with insurance accessibility. Japanese domestic market enthusiasts and German A2-license holders sustain niche demand.
- Above 600cc:Premium materials and electronic rider aids define specification. Italian and Austrian manufacturers command positioning here through racing-derived technology transfer.
Volume leadership sits with 50cc-125cc. Steepest expansion trajectory: 126cc-250cc.
Fuel Type:
Application requirements dictate fuel selection, with commercial operators prioritizing total cost of ownership while urban commuters weigh infrastructure availability against acquisition price.
- Petrol:Carburetor and fuel-injected variants span the full capacity range. Remains dominant in Indian tier-3 cities and Southeast Asian provincial centers where electric charging remains sparse.
- Electric:Lithium-ion battery packs and hub-mounted motors eliminate transmission complexity. European Union Green Deal subsidies and F-Gas Regulation compliance credits are accelerating homologation investments by established manufacturers.
- Diesel:Compression-ignition durability suits high-mileage commercial applications. Limited to specialized agricultural and military procurement in select markets.
- Hybrid:Series-parallel architectures combine petrol range with electric torque fill. Experimental deployments in Japanese corporate fleet trials.
Petrol retains volume dominance. Electric is gaining share fastest.
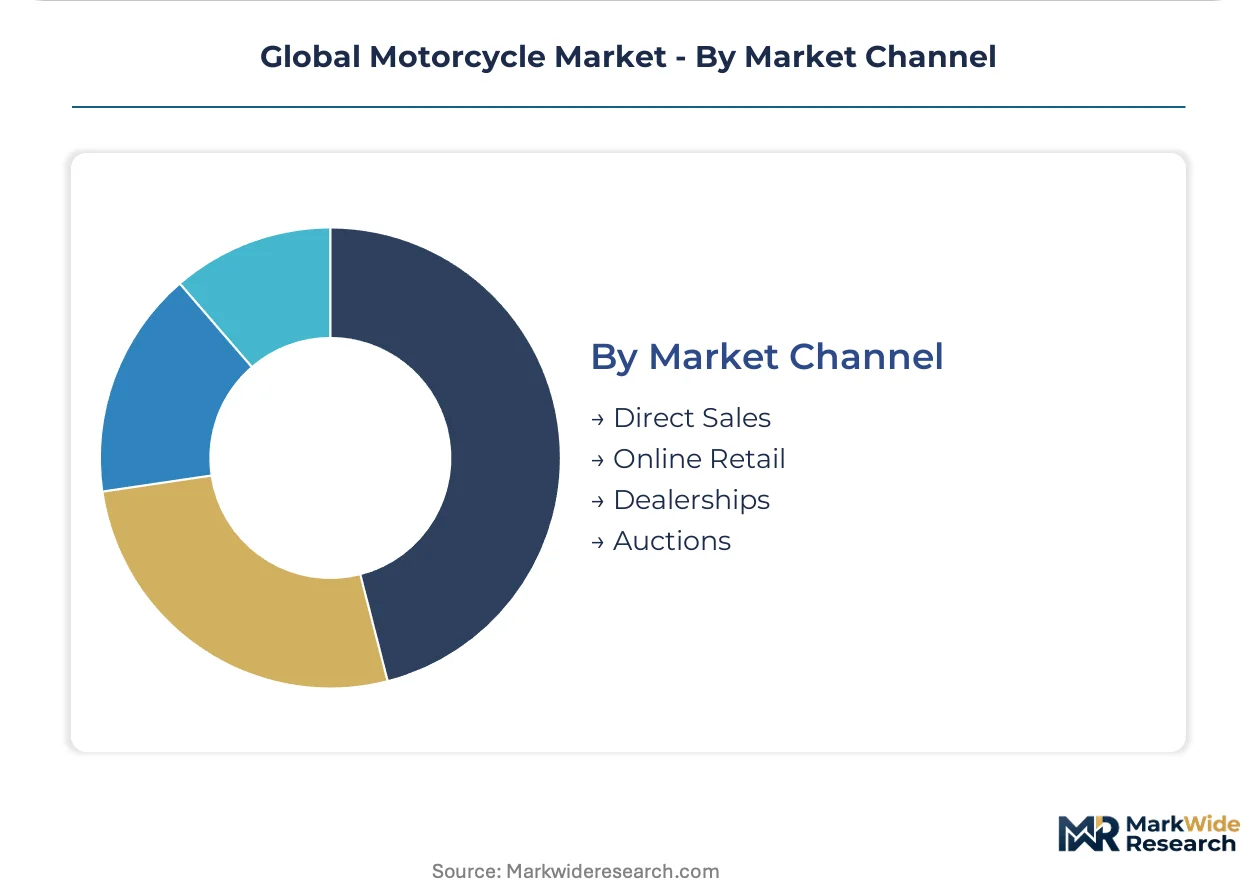
Market Channel:
Customer type and purchase urgency shape channel selection, with fleet operators demanding volume terms while individual buyers seek configuration flexibility.
- Direct Sales:Manufacturer-owned experience centers enable specification customization. Premium European brands deploy this channel in metropolitan Munich and Milan to control brand presentation.
- Online Retail:Digital configurators with doorstep delivery options reduce friction. Vietnamese and Indonesian urban buyers increasingly complete transactions through smartphone platforms before limited showroom verification.
- Dealerships:Franchise networks provide service dependency and financing access. Remains essential for petrol-powered units requiring maintenance infrastructure in Indian tier-2 cities.
- Auctions:Secondary market price discovery for fleet disposal and insurance salvage. Concentrated in Australian and North American wholesale corridors.
Dealerships lead by volume. Online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in India and Southeast Asia while consumption concentrates across divergent regulatory environments. Brazil and the European Union present contrasting compliance pathways for exporters. Tier-2 city expansion in India and Indonesian logistics corridors reshape demand geography.
India
Domestic two-wheeler volume concentrates in tier-2 and tier-3 cities where personal mobility infrastructure remains limited. The country's national automotive regulator enforces BS-VI emission standards that mandate fuel injection across the 50cc-125cc segment. Pune and Chennai industrial corridors host manufacturing clusters where domestic volume manufacturers retool for cleaner propulsion.
Indonesia
Last-mile delivery fleet operators in Jakarta and Surabaya scale motorcycle procurement to navigate chronic urban congestion. The country's energy ministry advances biofuel blending mandates that affect petrol engine calibration strategies. Jababeka and MM2100 industrial zones near Jakarta concentrate assembly operations serving domestic and export markets.
Germany
Premium above-600cc displacement brackets sustain margin pools among discretionary buyers in Bavaria and Baden-Württemberg. The EU Green Deal and F-Gas Regulation accelerate electric motorcycle homologation timelines for manufacturers seeking market access. Munich and Stuttgart metropolitan clusters host R&D facilities where racing-derived technology transfers into consumer sport segments.
Brazil
ANVISA regulatory alignment with EU emission frameworks creates pathway for premium electric model introduction without duplicative certification investments. São Paulo state agricultural properties and ranching operations sustain commercial off-road procurement. Manaus free trade zone assembly operations serve Mercosur distribution networks with reduced tariff exposure.
Vietnam
Urban delivery fleets in Ho Chi Minh City and Hanoi expand 126cc-250cc procurement for load-carrying versatility across dense street networks. The country's transport ministry pilots electric motorcycle subsidy schemes in metropolitan cores. Binh Duong and Dong Nai provinces concentrate component manufacturing feeding regional assembly operations.
Global Motorcycle Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive powertrain expertise. Volume leadership concentrates among Japanese and Indian manufacturers with established emerging market distribution density. Strategic archetypes span cost-optimized mass producers, racing-heritage premium specialists, and electric-native entrants. Consolidation pressure manifests through modular platform sharing agreements and battery supply chain partnerships rather than outright acquisition.
Among diversified industrial groups, Honda and Yamaha anchor the established tier with manufacturing footprints spanning multiple engine capacity brackets. TVS Motors and Bajaj exemplify emerging market volume specialists with domestic Indian dominance and export orientation toward Africa and Latin America. NIU and Yadea occupy positions within the electric-native archetype, leveraging lithium-ion supply chain proximity for cost structure advantage in battery-dominant segments.
| Leading Market Players |
|---|
| TVS Motors |
| NIU |
| Honda |
| KTM |
| Yadea |
| Yamaha |
| Suzuki |
| Kawasaki |
| Bajaj |
| Others |
Value Chain & Pricing Dynamics
BS-VI fuel injection mandates across India's 50cc-125cc segment are forcing domestic volume manufacturers to absorb component cost escalation while maintaining price accessibility for tier-2 and tier-3 city buyers, compressing margin structures and accelerating supplier consolidation toward fuel system specialists with scale economies.
Pricing Analysis
Margin tightening in the 50cc-125cc bracket reflects catalytic converter and fuel injection hardware absorption by domestic Indian manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates BS-VI-compliant fuel-injected units from carburetor legacy stock and electric alternatives. Pricing pressure intensifies in Southeast Asian fleet procurement as Indonesian and Vietnamese logistics operators negotiate volume terms for 126cc-250cc delivery vehicles. Tier-2 city individual buyers in India exhibit highest price sensitivity, while European above-600cc discretionary purchasers show lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Pune, Chennai, and Jakarta operate hub-and-spoke patterns feeding tier-2 city dealerships and metropolitan fleet operators. Manufacturing concentrates in India, Indonesia, and Vietnam for combustion platforms, with China, South Korea, and Taiwan anchoring lithium-ion cell and power electronics supply. Battery chemistry draws from cobalt and lithium feedstock exposed to commodity price volatility. Single-source vulnerability concentrates in semiconductor microcontroller supply for fuel injection and battery management systems. Distribution runs through franchise dealer networks for petrol units, while direct-to-consumer digital channels gain share in Vietnamese and Indonesian metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Motorcycle Market is becoming a vertical-integration race where control over battery cell supply agreements and proprietary battery management systems determines margin recovery in electric segments.
For Market Incumbents: Hedge against electric-native entrant disruption by securing long-term lithium-ion supply contracts and developing in-house power electronics engineering capabilities. Defend position in India's 50cc-125cc volume stronghold through backward integration into fuel injection component production. Prioritize certification investment for simultaneous EPA Tier 3, EU Euro 5, and BS-VI compliance to compress variant development cycles. For New Entrants and Emerging Players: Brazilian agricultural fleet operators represent an underserved buyer archetype seeking durable off-road electric alternatives with ANVISA-aligned homologation. White-space targets include EU Green Deal subsidy-captured urban commuting segments and Indian battery-as-a-service subscription markets. Penetrate through direct-to-consumer digital channels with doorstep delivery and lease-to-own structures that decouple upfront acquisition cost from usage access. For Investors and Strategic Acquirers: The window for entry favors electric-native specialists with lithium-ion supply chain proximity and established circular economy partnerships for EU F-Gas Regulation compliance. Long-term viability hinges on battery chemistry control and thermal management expertise rather than engine displacement optimization. Watch for inflection in Indian tier-2 city charging infrastructure deployment as signal for electric adoption acceleration outside metropolitan cores.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Korean or Chinese suppliers for EU electric homologation timelines. |
| Platform Standardization | Enables modular unbundling of powertrain, chassis, and electronics to serve heterogeneous regional regulations. |
| Charging Infrastructure Partnership | Addresses adoption barriers in Indian tier-2 cities and Southeast Asian provincial centers. |
| Backward Integration into Fuel Systems | Absorbs BS-VI component cost escalation across India's price-sensitive 50cc-125cc volume segment. |
| Direct-to-Consumer Digital Launch | Captures Vietnamese and Indonesian urban buyers configuring vehicles online before limited showroom verification. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers. Secondary sources included EPA Tier 3 certification databases, EU Euro 5 homologation records, India's BS-VI compliance filings, and vehicle production registration data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling deployed product type, engine capacity bracket, fuel type, and market channel dimensions at country-level resolution. CAGRs derived from segment-level volume and value trajectories incorporating battery energy density improvement curves, charging infrastructure deployment schedules, and regulatory mandate phase-in timelines. Forecast inputs included lithium and cobalt price volatility scenarios, semiconductor supply concentration risk factors, and fleet operator procurement cycle patterns.
Revisions become necessary when raw material cost volatility exceeds modeled bands, semiconductor supply disruptions extend beyond East Asian foundry concentration, or regulatory divergence between emission-centric frameworks and battery-subsidy regimes accelerates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market
Bikes and Motorcycles
Mountain Bike Suspension Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Bicycle Saddles Market